
 Australia Food Additives Market | 2026-2036
Australia Food Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Food Additives Market Outlook
Clean-label enzyme technology is reshaping how Australian food manufacturers reformulate products for reduced synthetic additive dependence. Cargill Australia Limited leverages its grain processing infrastructure to anchor supply of plant-derived texturizers across the domestic bakery sector. Kerry Group plc differentiates through integrated taste and nutrition solutions that extend from ingredient supply to finished product development. ADM Trading Australia Pty Ltd competes on oilseed and carbohydrate specialty ingredients, sustaining volume leadership in emulsifier categories.
Australia food additives comprise functional substances—preservatives, sweeteners, flavor enhancers, and colorants—incorporated at concentrations typically below one percent by weight to modify shelf stability, sensory profile, or processing behavior. These compounds serve primary industrial purposes in mass-scale food manufacturing where consistency, safety, and cost control override artisanal production methods. Preservatives occupy mature margin pools in processed foods applications, while flavor enhancers represent the fastest-growing segment as plant-based protein formulations proliferate in beverages and snacks. Colorants derived from natural sources command premium positioning over synthetic alternatives, particularly in dairy products targeting health-conscious retail channels.
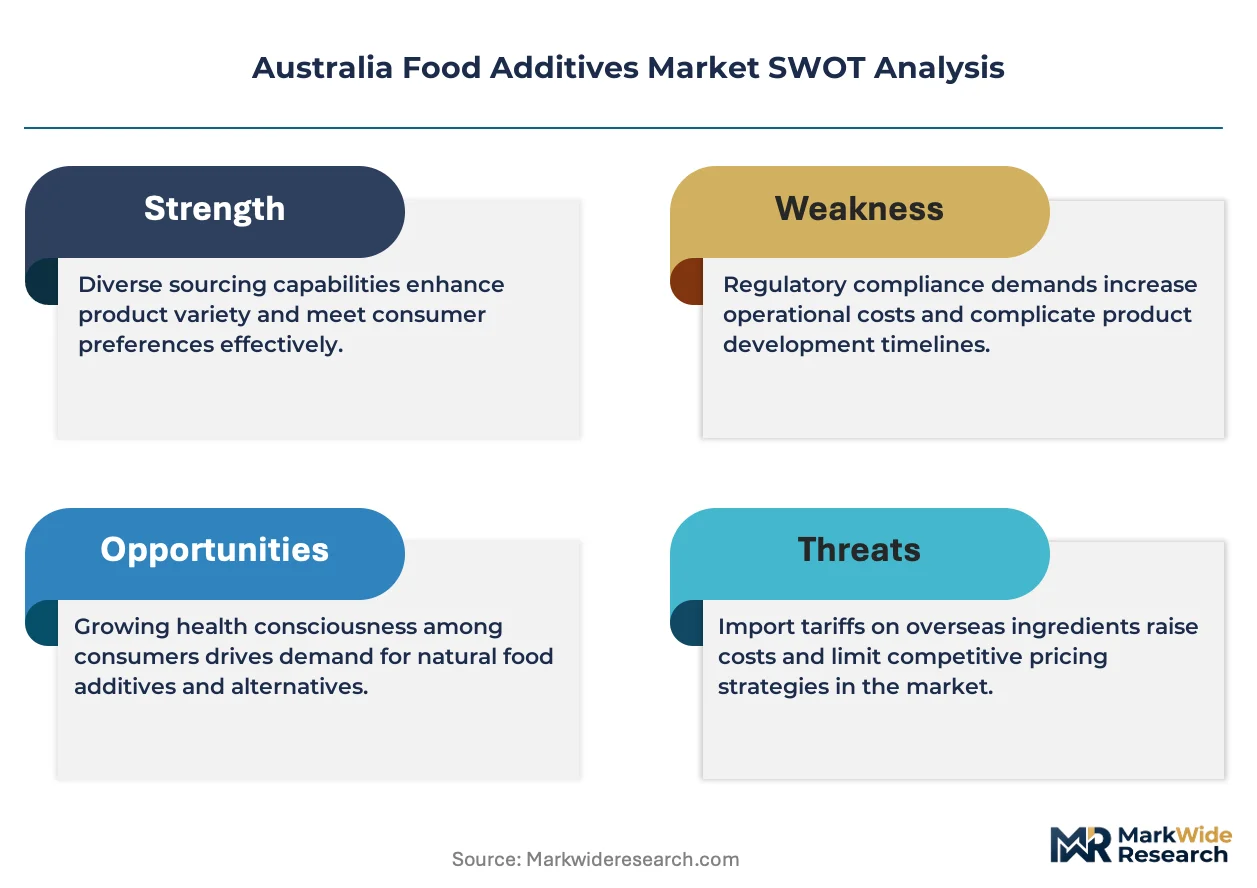
FSANZ maintains the Australia New Zealand Food Standards Code, which governs maximum permitted levels, labeling disclosures, and novel additive approvals across all jurisdictions. TGA intersects with this framework where additives carry therapeutic or probiotic claims, creating dual compliance pathways for functional ingredient suppliers. The ACCC enforces misleading representation rules that constrain how clean-label and natural-positioned products communicate additive content to consumers. Stakeholders must monitor pending FSANZ proposals on revised maximum levels for sulfites and benzoates, as these determinations will force reformulation investments or portfolio exits across affected suppliers.
Market Dynamics
FSANZ tightening of maximum permitted levels for sulfites and benzoates is forcing wholesale reformulation across Australian processed food manufacturing, compressing supplier margins while accelerating clean-label enzyme adoption.
Growth Catalysts
- Clean-label enzyme technology:Australian bakery and beverage manufacturers deploy plant-derived texturizers to eliminate synthetic additive dependence. Reformulation activity concentrates in New South Wales and Victoria processing clusters.
- FSANZ Code amendments:Pending proposals on revised maximum levels create compliance-driven demand for alternative preservation systems. Suppliers invest in natural antioxidant portfolios to preempt regulatory displacement.
- Plant-based protein proliferation:Flavor enhancer demand accelerates as meat-alternative formulations require masking and mouthfeel modification. Snack and ready-meal categories anchor procurement volumes.
Market Restraints
- Natural colorant cost premiums:Anthocyanin and carotenoid-derived alternatives command 3-5x synthetic pricing, constraining adoption in economy-tier dairy and confectionery segments.
- Grain supply concentration:Plant-derived texturizer feedstocks depend on eastern Australian wheat belt output, exposing processors to drought-induced input volatility.
- Dual compliance pathways:TGA intersection with FSANZ for probiotic-functional additives creates approval timeline uncertainty, delaying novel ingredient commercialization.
Strategic Opportunities
- Queensland and South Australia expansion:Underpenetrated food processing corridors offer first-mover positioning as regional manufacturing capacity expands beyond Sydney-Melbourne axis.
- E-commerce ingredient platforms:Direct procurement channels for mid-tier manufacturers bypass traditional distributor markups, capturing margin previously lost to intermediaries.
- ACCC clean-label enforcement:Stricter misleading representation rules create competitive advantage for suppliers with verified natural-positioning documentation and supply chain transparency.
Industry Challenges
- Reformulation technical talent scarcity:Food science expertise in enzyme stabilization and natural preservation systems concentrates with multinational ingredient houses, constraining domestic manufacturer capability building.
- Legacy equipment incompatibility:Clean-label ingredient processing often requires modified temperature and pH parameters, forcing capital expenditure in extrusion and mixing infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Food Additives Market |
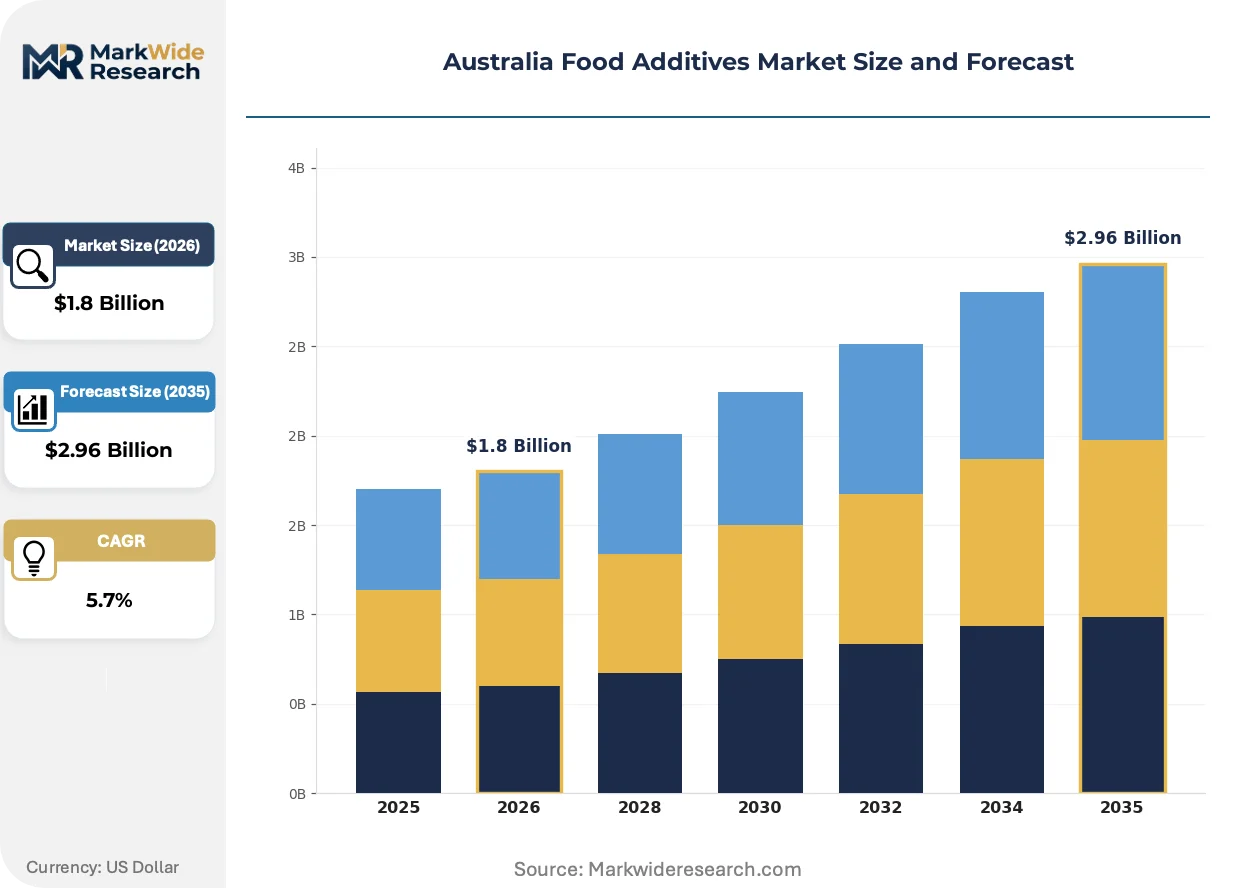
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Preservatives, Sweeteners, Flavor Enhancers, Colorants End User: Food Manufacturers, Restaurants, Retailers, Bakeries Application: Processed Foods, Beverages, Dairy Products, Snacks Packaging Type: Bottles, Bags, Bulk Containers, Jars |
| Companies Covered | ADM Trading Australia Pty Ltd, Cargill Australia Limited, Ingredion Incorporated, Kerry Group plc, Corbion NV, Tate & Lyle PLC, International Flavors & Fragrances Inc., Chr. Hansen Holding A/S, BASF SE, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Food Additives Market Strategic Shifts
Digital formulation platforms and biosynthetic production methods are compressing development cycles for Australian food additive suppliers, while regulatory transparency mandates reshape competitive disclosure requirements.
Precision fermentation for natural flavor compounds is virtualizing traditional extraction-dependent supply chains. Australian taste solution providers adopt microbial production systems to decouple from agricultural harvest volatility. This biotechnology shift is virtualizing inventory and margin structures previously tethered to seasonal raw material availability.
FSANZ mandatory allergen labeling expansions and quantitative ingredient declaration requirements tighten compliance documentation burdens. Ingredient suppliers invest in blockchain-traceability systems to satisfy downstream manufacturer audit demands. Dairy and infant nutrition categories face the steepest adaptation costs as disclosure granularity intensifies.
Consolidated procurement by supermarket private-label manufacturers concentrates additive purchasing power among three national retailers. Direct supplier-retailer partnerships displace traditional food service distributor intermediaries in contract negotiations. Victoria and New South Wales co-manufacturing facilities exhibit the most visible channel restructuring as scale requirements escalate.
Australia Food Additives Market Segmentation
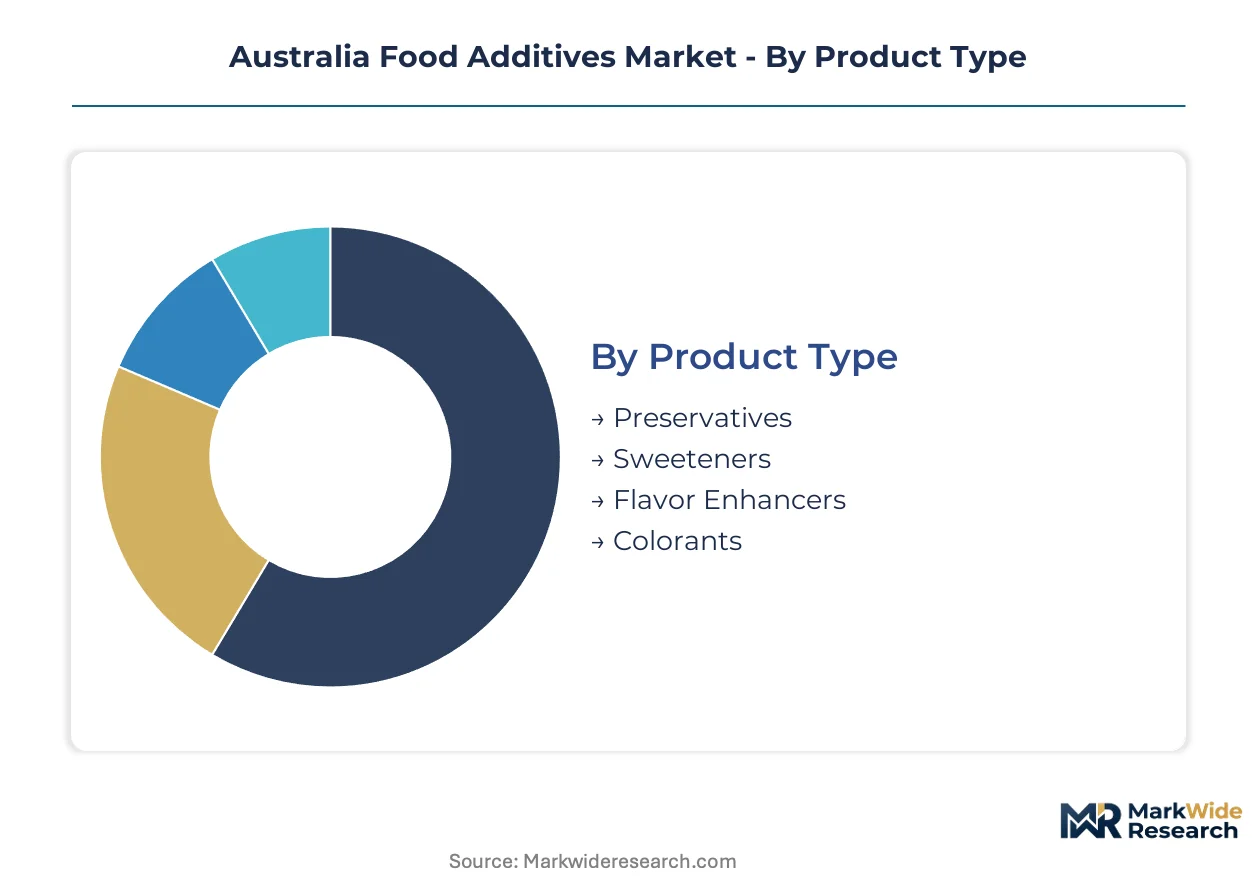
Segmentation in the Australia Food Additives Market exposes how regulatory pressure and clean-label migration reshape procurement patterns across product categories. Manufacturers align additive portfolios with FSANZ compliance tiers and end-use processing requirements to capture margin in reformulation cycles.
Product Type:
Mature preservation chemistries dominate volume throughput while enzyme-based alternatives accelerate fastest on commercial adoption curves.
- Preservatives:Sulfite and benzoate compounds face maximum permitted level reductions under pending FSANZ Code amendments. Processed food manufacturers in New South Wales and Victoria are preemptively shifting procurement toward natural antioxidant systems to avoid compliance-driven supply disruption.
- Flavor Enhancers:Yeast extracts and nucleotide blends enable mouthfeel modification in plant-based protein formulations without synthetic additive labeling. Snack and ready-meal manufacturers anchor procurement volumes as meat-alternative SKUs proliferate across Australian retail channels.
- Sweeteners:High-intensity and bulk variants serve sugar-reduction formulations in beverages and dairy.
- Colorants:Anthocyanin and carotenoid-derived alternatives command premium positioning over synthetic dyes in health-conscious retail segments.
Preservatives handle the majority of throughput; flavor enhancers are the fastest mover on share.
End User:
Procurement scale separates multinational food manufacturers from fragmented food service operators, with co-manufacturing facilities concentrating additive purchasing power.
- Food Manufacturers:National processed food and beverage producers operate direct supplier relationships bypassing traditional distributor networks. Clean-label reformulation investments concentrate in Sydney-Melbourne processing corridors where technical talent and equipment infrastructure align.
- Restaurants:Chain operators and contract food service providers procure standardized additive blends through consolidated procurement functions. Quick-service and casual dining segments drive volume for flavor enhancement and shelf-stable sauce applications.
- Retailers:Supermarket private-label manufacturers concentrate purchasing power among three national chains, displacing intermediaries in contract negotiations.
- Bakeries:Industrial and artisanal segments split between enzyme-based dough conditioners and traditional chemical leavening systems.
Food manufacturers absorb the dominant share of additive volume; retailers are expanding procurement fastest as private-label manufacturing scales.
Application:
Application segmentation tracks how clean-label migration penetrates differently across shelf-stable versus fresh-dependent categories.
- Processed Foods:Canned, frozen, and ambient-stable categories face the steepest reformulation pressure as FSANZ tightens preservative maximums. Manufacturers deploy natural preservation systems and modified atmosphere packaging to maintain shelf stability without synthetic additive dependence.
- Beverages:Sugar-reduction and flavor masking requirements in functional and plant-based drinks accelerate sweetener and flavor enhancer procurement. New South Wales beverage manufacturing clusters anchor volume for high-intensity sweetener blends.
- Dairy Products:Natural colorant premiums concentrate in yogurt and cheese targeting health-conscious retail channels.
- Snacks:Extruded and baked snack categories drive demand for flavor enhancement and texture modification systems.
Processed foods command the largest application share; beverages are climbing the fastest on reformulation activity.
Packaging Type:
Packaging segmentation reflects supply chain configuration from ingredient handling through finished goods distribution.
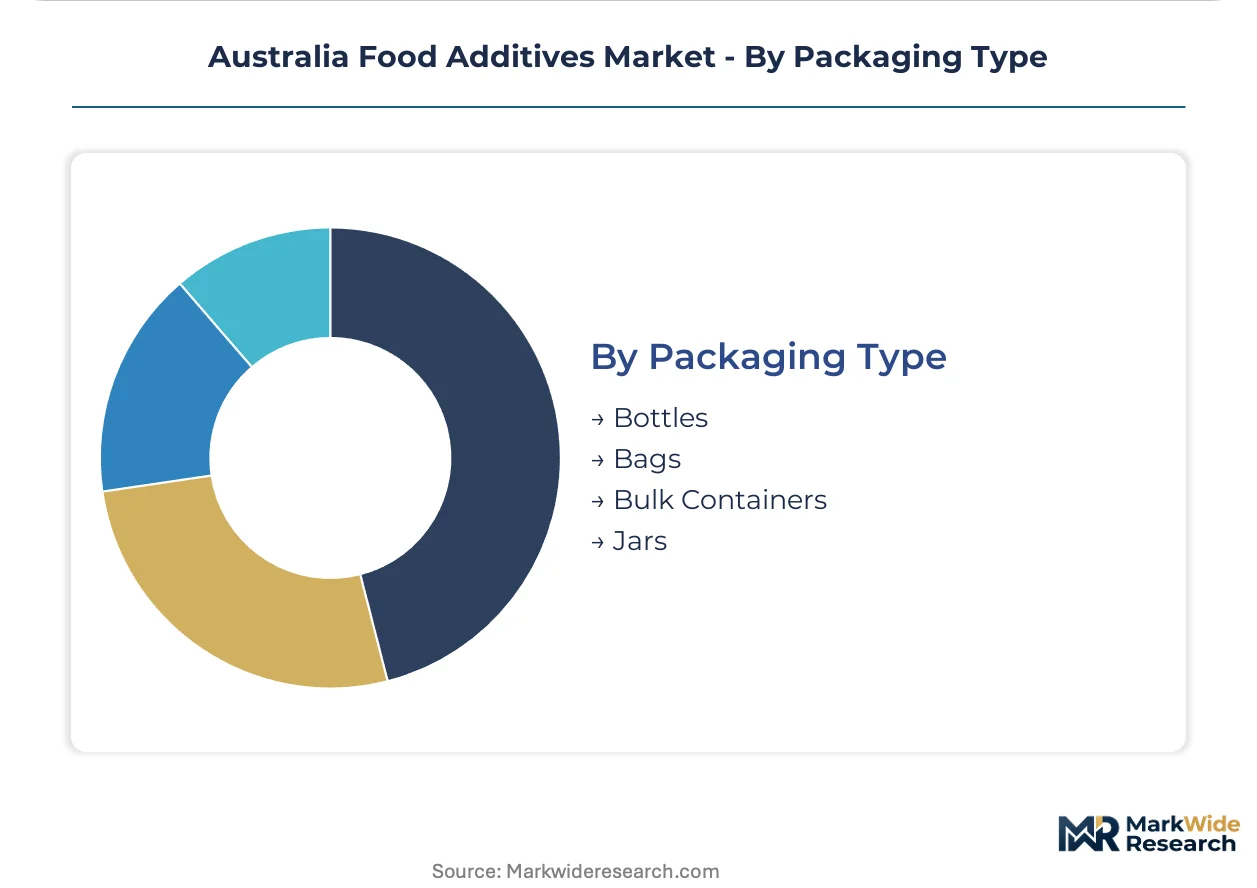
- Bulk Containers:Intermediate bulk containers and tanker deliveries serve high-volume food manufacturers with integrated formulation facilities. Direct-from-port procurement through Melbourne and Sydney anchors supply security for preservative and sweetener commodities.
- Bags:Multi-wall paper and woven polypropylene formats serve mid-tier manufacturers and distributor-stocking requirements. Powdered additive categories including texturizers and dry flavor systems standardize on bagged presentation.
- Bottles:Liquid additive concentrates including colorants and flavor solutions package in PET and glass formats for precision dosing.
- Jars:Smaller-format glass and plastic containers serve artisanal manufacturers and food service portion-control requirements.
Bulk containers move the highest additive tonnage; bags are gaining share fastest as mid-tier manufacturer procurement consolidates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ingredient supply corridors from Singapore and New Zealand feed directly into Australian east-coast manufacturing clusters, with trans-Tasman trade flows dominating preservative and enzyme imports.
New South Wales
Food manufacturers in Greater Sydney drive procurement for clean-label texturizers and natural preservation systems. FSANZ compliance audits concentrate enforcement resources on additive maximum permitted levels across Parramatta and Wetherill Park processing zones. The Sydney-Melbourne logistics corridor anchors bulk sweetener distribution through Port Botany container terminals.
Victoria
Beverage and dairy reformulation demand concentrates in Melbourne's northern suburbs manufacturing belt. State-level environmental regulations intersect with FSANZ standards for wastewater discharge from enzyme production facilities. Geelong and Laverton industrial precincts host co-manufacturing facilities serving supermarket private-label contracts.
Queensland
Expanding food processing capacity in Brisbane-Ipswich corridor creates procurement pull for flavor enhancement systems. Queensland Health coordinates with FSANZ on regional food safety incident response protocols. Gold Coast and Sunshine Coast specialty food manufacturers drive artisanal-scale demand for natural colorant portfolios.
South Australia
Grain-derived texturizer feedstock processing clusters around Port Adelaide bulk handling infrastructure. The state's grain belt drought resilience programs intersect with additive manufacturer supply security planning. Adelaide Hills wine and dairy producers anchor premium natural-positioning ingredient demand.
Western Australia
Perth-based food manufacturers rely on extended supply chains for preservative commodities given distance from eastern seaboard ports. Western Australian Department of Health administers FSANZ Code enforcement with additional state-level labeling requirements. Fremantle port infrastructure handles specialized enzyme imports for mining camp catering supply chains.
Australia Food Additives Market Competitive Environment
Channel-controlling players compete with product-specialist players across procurement tiers, with supermarket private-label concentration driving supplier consolidation. The market exhibits tiered structure between multinational ingredient houses with integrated formulation services and regional distributors serving mid-tier manufacturers. Three archetypes dominate: integrated taste-nutrition solution providers, grain-processing-anchored texturizer suppliers, and fermentation-derived specialty ingredient specialists. Capacity expansion in Queensland and strategic partnerships for clean-label enzyme technology represent the dominant competitive vectors.
Within the multinational integrated tier, Cargill Australia Limited and Kerry Group plc occupy positions as archetype anchors for supply chain control and end-to-end formulation services respectively. ADM Trading Australia Pty Ltd exemplifies the oilseed and carbohydrate specialty vector, with its corporate structure indicating trading-house rather than manufacturing-integrated positioning. These three entities collectively represent the competitive pattern visible across the supplier base, with their geographic naming conventions indicating Australian market commitment through local operating entities rather than pure export presence.
| Leading Market Players |
|---|
| ADM Trading Australia Pty Ltd |
| Cargill Australia Limited |
| Ingredion Incorporated |
| Kerry Group plc |
| Corbion NV |
| Tate & Lyle PLC |
| International Flavors & Fragrances Inc. |
| Chr. Hansen Holding A/S |
| BASF SE |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in Queensland's emerging enzyme production facilities is compressing supplier margins while elevating pricing leverage for established New South Wales and Victoria processors with secured feedstock contracts. This utilization asymmetry shapes procurement negotiations across the reformulation cycle, as manufacturers with captive supply chains extract cost advantages from competitors dependent on spot-market sourcing.
Pricing Analysis
Prior-generation synthetic preservative chemistries trade at substantial discounts to emerging enzyme-based preservation systems, with next-generation precision-fermentation flavor compounds commanding further premiums. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and FSANZ compliance documentation depth. Cost compression in synthetic preservative tiers is intensifying because pending maximum-permitted-level reductions are forcing portfolio exits. Economy-tier dairy manufacturers exhibit acute price sensitivity, while infant nutrition and premium beverage segments absorb natural-positioning premiums with minimal volume elasticity.
Supply Chain Analysis
Tariff exposure between Australia and Singapore dominates supply chain risk calculations for preservative and specialty enzyme imports transiting through Port Botany. Geographic supply concentration centers on Singapore, New Zealand, and Thailand for fermentation-derived inputs and extraction-dependent natural colorants. Raw material dependencies rest on eastern Australian wheat belt output for plant-derived texturizers, Malaysian palm derivatives for emulsifier feedstocks, and Indonesian seaweed harvests for hydrocolloid stabilizers. Single-source vulnerability characterizes the Singapore-anchored enzyme import corridor, with limited alternative port infrastructure capable of handling temperature-sensitive biotech shipments. Distribution runs through Melbourne and Sydney bulk container terminals for high-volume manufacturers, with regional distributor networks serving mid-tier Queensland and South Australia processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FSANZ regulatory entrenchment creates durable defensive moats for suppliers with established compliance documentation and pre-approved additive portfolios. Switching costs escalate as manufacturers face reformulation timelines and re-certification burdens that lock in incumbent relationships.
For Market Incumbents: Entrench market position through backward integration into grain processing infrastructure across Victoria's wheat belt, securing captive texturizer feedstock supply against drought-induced volatility. Expand clean-label enzyme production capacity in Queensland's underutilized industrial corridors ahead of competitor entry. Prioritize blockchain-traceability system deployment to satisfy supermarket private-label audit requirements and displace distributor intermediaries in direct retailer negotiations. For New Entrants and Emerging Players: Mid-tier bakery and snack manufacturers in South Australia represent the most penetrable entry point, as these segments face acute technical talent scarcity in enzyme stabilization and lack integrated formulation capabilities. Queensland's expanding beverage processing capacity offers second-mover positioning for natural preservation system suppliers. A co-manufacturing partnership model with established Sydney-Melbourne facilities provides the most viable go-to-market angle, bypassing capital-intensive equipment investments. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across precision-fermentation flavor compound production, as microbial production systems require specialized bioreactor infrastructure and extended regulatory approval timelines. Long-term viability favors suppliers with diversified feedstock sourcing and documented FSANZ pre-approval portfolios. Acquisition targets should demonstrate integrated taste-nutrition solution capabilities spanning ingredient supply through finished product development. The signal to monitor is FSANZ publication timelines for revised sulfite and benzoate maximum permitted levels, which will trigger forced reformulation cycles and portfolio consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Grain Processing | Cargill Australia's captive wheat supply secures texturizer margins against eastern belt drought volatility. |
| Clean-Label Enzyme Capacity Expansion | Queensland facility investments capture reformulation demand as FSANZ tightens synthetic preservative limits. |
| Blockchain Traceability Deployment | Verified supply chain documentation satisfies supermarket private-label audit requirements and displaces intermediaries. |
| Precision Fermentation Partnership | Microbial flavor production decouples from agricultural harvest volatility and compresses development cycles. |
| Direct Retailer Supply Agreement | Bypassing distributor networks captures margin previously lost to food service intermediaries in contract negotiations. |
Study Parameters
Cross-validation between FSANZ regulatory filing databases and Australian Bureau of Agricultural and Resource Economics trade statistics anchors the qualitative findings on supply chain configuration and reformulation investment patterns. Primary interviews with food technology directors at national processed food manufacturers, procurement leads at supermarket private-label operations, regulatory affairs specialists at ingredient houses, and technical sales managers at regional distributors combined with secondary validation from FSANZ proposal documentation, ACCC enforcement records, and Australian Customs import manifests. Bottom-up additive volume estimates triangulated against top-down food manufacturing output data across the analysis window.
Calibration against historical FSANZ amendment implementation timelines and precedent reformulation cost disclosures shaped the projection framework. Segmentation dimensions modeled include product type, end-user procurement tier, application category, and packaging format, with additional granularity on FSANZ compliance tier status. CAGRs derived from slope analysis of ingredient procurement intensity against food manufacturing value-add across the modeling period. Industry-specific forecast inputs incorporated drought probability distributions for eastern Australian wheat belt output and pending regulatory proposal publication schedules.
Macroeconomic conditions sit as an overlay; deviation in Australian dollar exchange rates against Singapore dollar and New Zealand dollar trade corridors would shift import cost trajectories and regional sourcing decisions. Forecasts reflect assumptions on FSANZ amendment adoption timelines and drought recurrence patterns that could accelerate or delay reformulation investment cycles. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Africa Anti Caking Agent Market
Food Additives and Ingredients
Australia Food Preservatives Market
Food Additives and Ingredients
South America Feed Anti-Caking Agents Market
Food Additives and Ingredients
Baking Enzymes Market
Food Additives and Ingredients
Citrus Fruit Coatings Market
Food Additives and Ingredients
Argentina Food Additives Market
Food Additives and Ingredients
Natural Solubilizers Market
Food Additives and Ingredients
Spain Food Additives Market
Food Additives and Ingredients
North America Clean Label Ingredient Market
Food Additives and Ingredients
Italy Food Enzymes Market
Food Additives and Ingredients
India Food Emulsifiers Market
Food Additives and Ingredients
North America Food Stabilizers Market
Food Additives and Ingredients
Food Protein Ingredient Market
Food Additives and Ingredients
South America Anti Caking Market
Food Additives and Ingredients
Semi-Finished Pastry Ingredients Market
Food Additives and Ingredients
Mexico Food Additives Market