
 Edible Insects Market | 2026-2036
Edible Insects Market Size, Share, and Industry Trends Forecast 2026-2036
Edible Insects Market Analysis
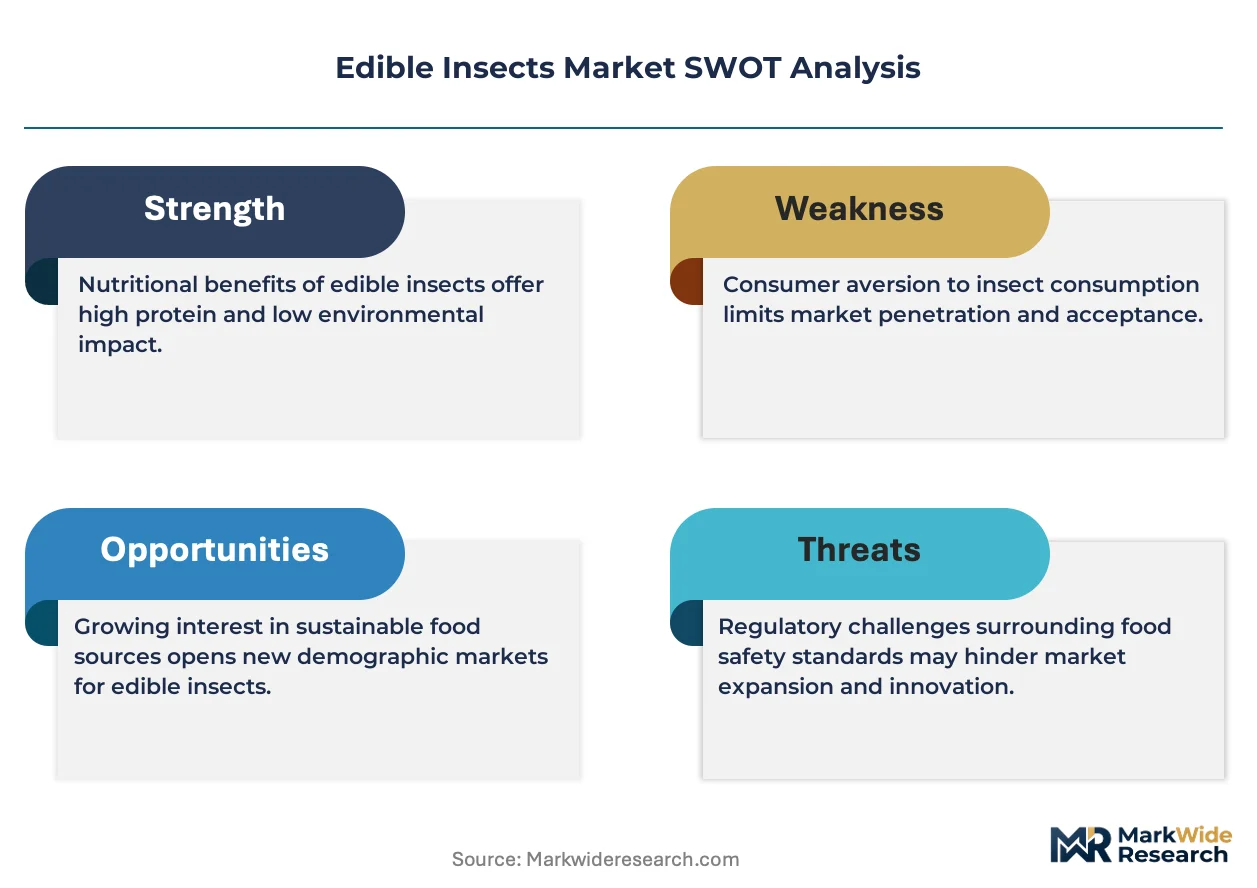
The EU Green Deal is recalibrating protein sourcing mandates across European food systems. Aspire Food Group leverages vertical integration from breeding to processing across its Thailand and Mexico operations. Ÿnsect anchors industrial-scale mealworm production through its vertical farm near Amiens, France. Innovafeed competes on pharmaceutical-grade insect protein output for aquaculture and pet nutrition clients.
Edible insects encompass whole, powdered, or extracted forms of farmed arthropods processed under controlled conditions for human or animal consumption. Cricket flour typically delivers 60-65% protein by dry weight with complete amino acid profiles, rendering it suitable for fortification of baked goods, pasta, and sports nutrition formulations. Mealworm-derived ingredients dominate the animal feed application segment where salmonid and poultry producers seek alternatives to fishmeal and soy. Snack foods represent the fastest-growing food product category as European and North American brands introduce roasted whole-insect and extruded formats to adventurous consumer segments.
EFSA novel food safety evaluations determine market access timelines for new insect species across EU member states. Thailand's national food and drug administration and the country's halal certification bodies shape export eligibility for Southeast Asian producers targeting Middle Eastern markets. FDA enforcement discretion letters and state-level incorporation into the Food, Drug, and Cosmetic Act guide US commercialization pathways. Stakeholders must monitor regulatory harmonization progress between Codex Alimentarius frameworks and national novel food regimes to anticipate cross-border trade enablement.
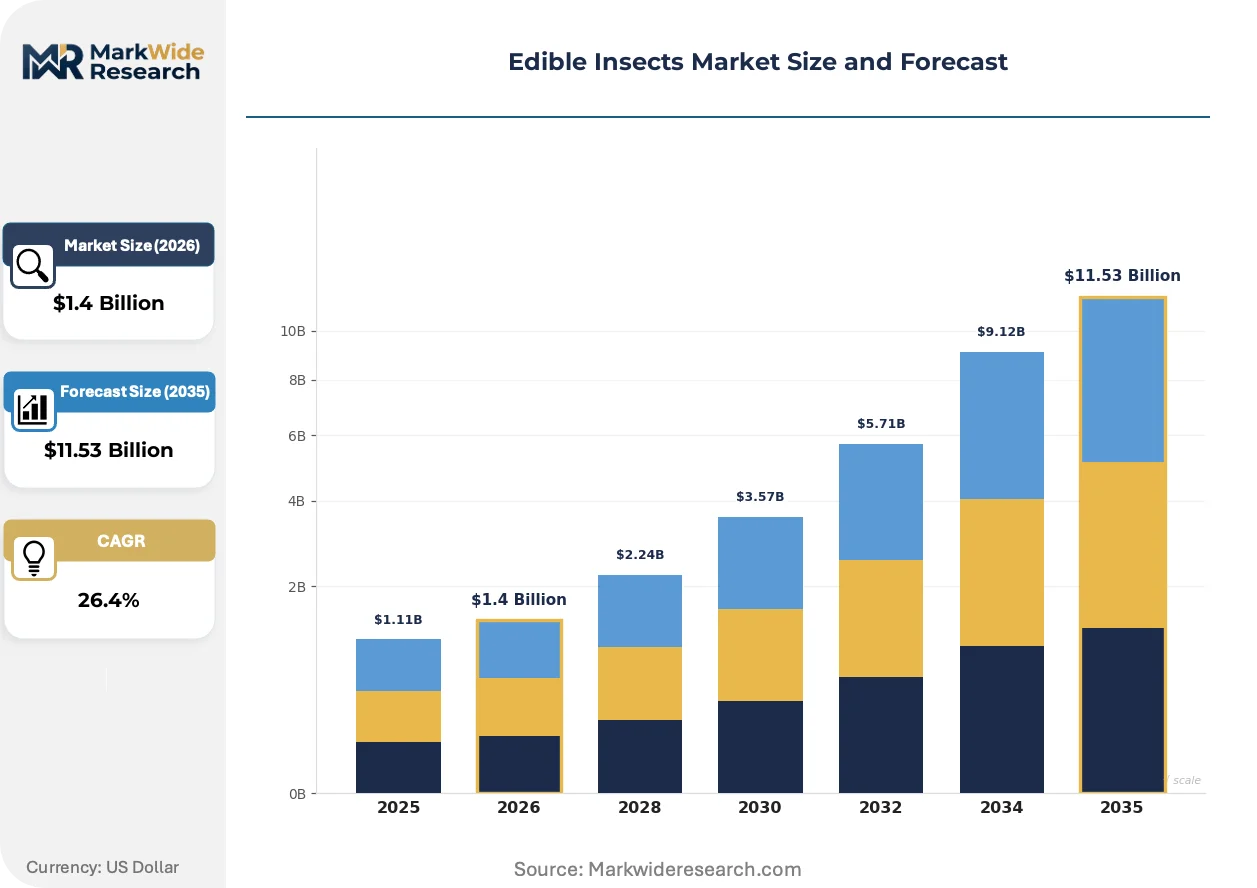
Market Dynamics
Protein diversification mandates under the EU Green Deal are forcing feed manufacturers and food brands to certify alternative ingredient streams, with insect-derived inputs now specified in procurement tenders across French and Dutch supply chains.
Growth Catalysts
- EFSA Novel Food pathways:Safety assessments for house crickets and yellow mealworms have unlocked commercialization across EU member states, enabling product launches in bakery and sports nutrition categories.
- Aquafeed formulation shifts:Salmonid producers in Norway and Scotland are substituting fishmeal with insect protein to meet marine ingredient reduction targets.
- Controlled-environment farming:Automated climate systems are reducing mortality rates in black soldier fly colonies, improving batch consistency for industrial buyers.
Market Restraints
- Input cost volatility:Organic waste substrate prices fluctuate with agricultural commodity cycles, squeezing margins for mealworm and cricket farms dependent on consistent feedstock quality.
- Regulatory fragmentation:Divergent approval timelines between EFSA, FDA enforcement discretion letters, and Thailand's FDA create multi-year lag for cross-border product registration.
- Consumer substitution:Plant-based protein isolates from pea and fava bean suppliers compete directly on price and familiarity in European retail channels.
Strategic Opportunities
- German retail penetration:Discounters and organic chains remain underdeveloped for whole-insect and powdered formats, presenting first-mover shelf space advantages.
- Pet food premiumization:Cat and dog food brands are formulating with insect protein to meet humanization trends and novel protein claims for allergy-sensitive animals.
- Bioconvergence with precision fermentation:Hybrid production models combining insect biomass with microbial protein extraction are opening pharmaceutical-grade output tiers.
Industry Challenges
- Entomology talent scarcity:Industrial-scale facilities require specialized breeding technicians and pathology experts that agricultural universities have not yet trained at sufficient scale.
- Downstream processing capex:Defatting, drying, and milling equipment for food-grade powder production demands capital commitments that exceed most farm-level financing capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Edible Insects Market |
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $11.53 Billion |
| CAGR (2026 – 2036) | 26.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Crickets, Mealworms, Grasshoppers, Ants Application: Food Products, Animal Feed, Nutritional Supplements, Snack Foods End User: Food Manufacturers, Restaurants, Retail Consumers, Feed Suppliers Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Food Service |
| Companies Covered | Aspire Food Group, Entomo Farms, Ÿnsect, Enterra Feed Corporation, Beta Hatch Inc., Protix B.V, EnviroFlight LLC, Hexafly, Innovafeed, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Edible Insects Market Emerging Trajectories
Automation and regulatory clarity are converging to transform insect farming from experimental agriculture into standardized ingredient manufacturing, with implications for unit economics and buyer qualification protocols.
Robotic harvesting systems are integrating vision-guided sorting and gentle-handling end-effectors to reduce labor costs and contamination risk in high-density cricket colonies. Dutch and French vertical farms are deploying these systems at commercial scale. The technology is integrating quality control directly into production flow, compressing post-harvest processing steps and enabling real-time grading for protein content and moisture levels.
EU Green Deal protein sourcing mandates are redirecting public procurement specifications toward certified sustainable ingredients, with insect protein now eligible for school meal programs and military rations in France and Belgium. National food safety agencies are accelerating novel food dossier reviews to meet political deadlines. Aquafeed and pet food manufacturers are responding by locking multi-year offtake agreements with domestic producers to secure supply ahead of competitor qualification.
Direct-to-brand ingredient supply contracts are displacing spot-market trading as salmonid and poultry integrators seek traceability for sustainability reporting. Buyers are consolidating supplier lists to farms with third-party organic waste chain-of-custody certification. This pattern is most visible in the Netherlands, where feed compounders now require batch-level DNA verification and carbon footprint documentation as standard contract terms.
Edible Insects Market Segmentation
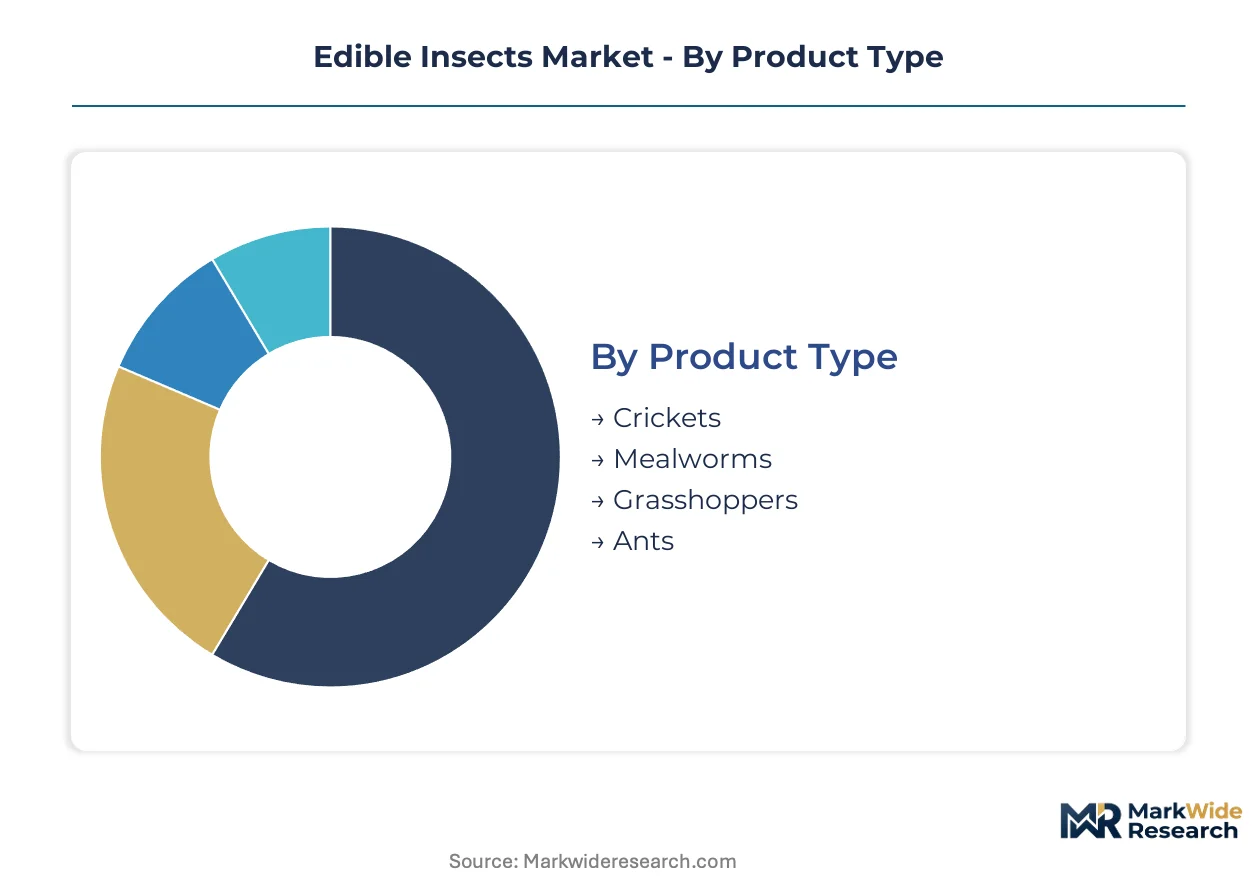
Segmentation in edible insects reflects divergent processing requirements and regulatory pathways. Product type determines substrate selection and farming infrastructure. Application and end-user splits reveal where margin pools concentrate versus where volume scales.
Product Type:
Upgrade cycles in farming automation favor species with shorter reproduction cycles and established regulatory dossiers.
- Crickets:House crickets deliver 60-65% protein by dry weight with complete amino acid profiles. French and Dutch food manufacturers specify cricket flour for bakery fortification and sports nutrition following EFSA novel food approvals.
- Mealworms:Yellow mealworms dominate industrial-scale vertical farming due to controlled-environment tolerance. Norwegian salmonid producers are locking multi-year offtake agreements for mealworm protein to meet marine ingredient reduction targets.
- Grasshoppers:Migratory locust species serve traditional consumption markets in Thailand with halal certification for Middle Eastern export eligibility.
- Ants:Weaver ant larvae and eggs occupy niche gastronomy segments in Southeast Asian fine dining with limited scalable supply.
Mealworms sit at the top of the volume ranking, with crickets climbing the fastest.
Application:
Cost tier differentiation separates commodity feed inputs from premium food-grade ingredients with divergent processing investments.
- Food Products:Powdered and whole formats for human consumption require defatting, drying, and milling to pharmaceutical-grade standards. Belgian and French school meal programs now include insect protein under EU Green Deal procurement mandates.
- Animal Feed:Salmonid and poultry integrators substitute fishmeal and soy with insect protein for sustainability reporting compliance. Dutch feed compounders require batch-level DNA verification and carbon footprint documentation as standard contract terms.
- Nutritional Supplements:Capsule and tablet formats target sports nutrition and clinical nutrition segments with higher protein concentration specifications.
- Snack Foods:Roasted whole-insect and extruded formats are gaining shelf space in German organic chains and discounters targeting adventurous consumer segments.
Animal Feed captures the largest revenue pool, while Snack Foods expands most quickly in European retail channels.
End User:
Customer type determines contract structure, with institutional buyers demanding traceability that retail channels rarely match.
- Food Manufacturers:Industrial buyers of cricket flour and mealworm powder for ingredient incorporation require third-party organic waste chain-of-custody certification.
- Restaurants:Fine dining establishments in Paris and Bangkok source whole insects for experiential menu items with volatile spot-market purchasing.
- Retail Consumers:Direct-to-consumer brands face price competition from plant-based protein isolates in European supermarkets.
- Feed Suppliers:Aquafeed and pet food compounders consolidate supplier lists to farms with vertical integration from breeding to processing.
Feed Suppliers command the steepest volume concentration, with Food Manufacturers showing the strongest margin expansion.
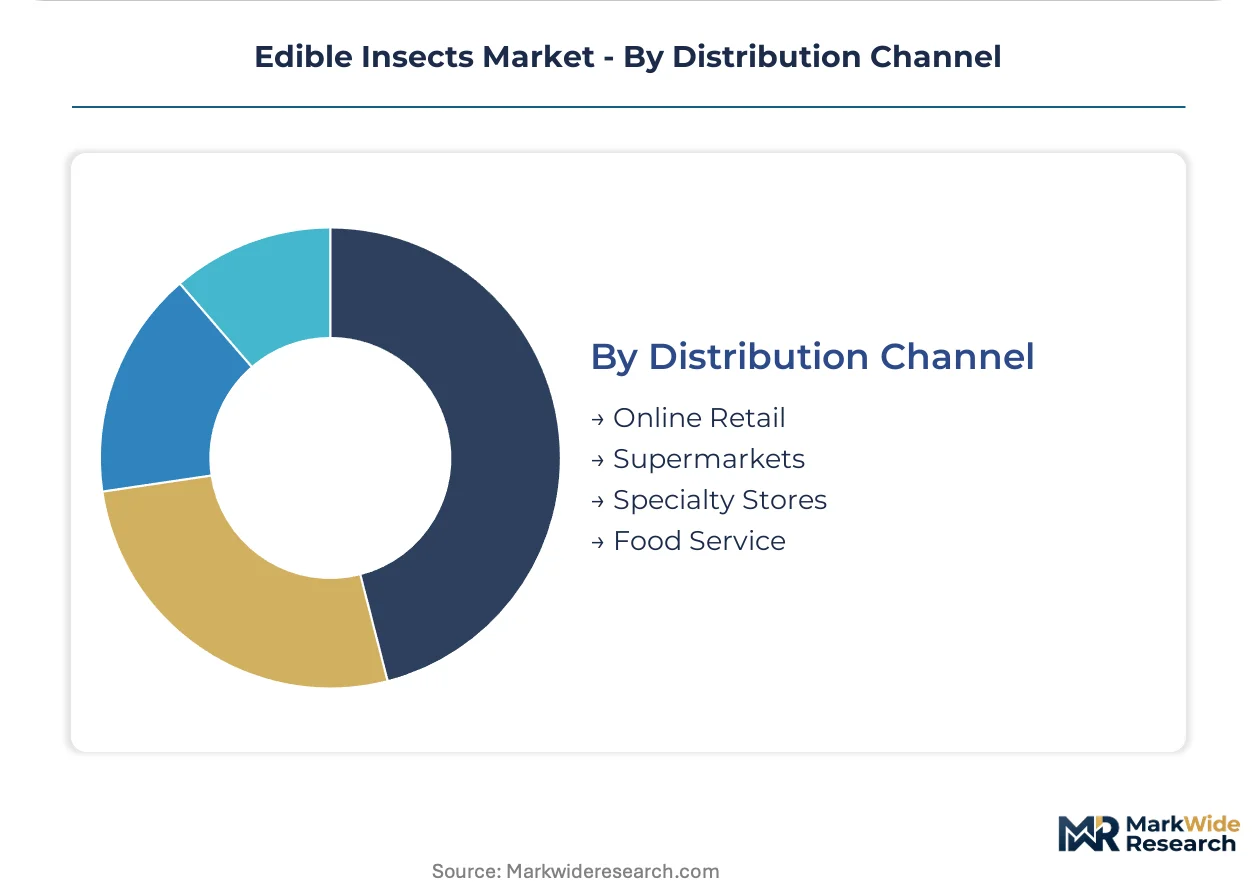
Distribution Channel:
Geography of demand shapes channel priority, with urban clusters driving online and specialty retail while rural feed markets favor direct supply contracts.
- Online Retail:Direct-to-consumer platforms bypass retail margin capture but face last-mile cold chain costs for fresh and frozen formats.
- Supermarkets:French and Belgian mass retail chains are allocating shelf space to insect-based pasta and protein bars following novel food authorization.
- Specialty Stores:Organic and gourmet retailers in Amsterdam and Copenhagen curate whole-insect assortments for early-adopter demographics.
- Food Service:Institutional catering contracts for military rations and school meals in France specify certified sustainable insect protein.
Food Service anchors the largest contract values, with Supermarkets gaining share fastest as authorization timelines compress.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Thailand pioneered commercial-scale insect farming in the 1990s, establishing breeding protocols that European and North American producers later adapted. Dutch and French clusters now dominate industrial output, while regulatory clarity in Belgium and Germany is opening new demand corridors.
France
French aquafeed manufacturers drive mealworm protein demand to satisfy marine ingredient reduction mandates in salmonid production. EFSA novel food authorizations for house crickets and yellow mealworms enable bakery fortification and sports nutrition launches. Ÿnsect's vertical farm near Amiens anchors the country's industrial-scale output, supplying compounders with pharmaceutical-grade insect meal.
Netherlands
Dutch feed compounders require batch-level DNA verification and carbon footprint documentation as standard contract terms, consolidating procurement around certified producers. The EU Green Deal redirects public procurement specifications toward sustainable ingredients, with insect protein now eligible for institutional catering. Wageningen University's research cluster advances automated climate systems for black soldier fly colony optimization.
Thailand
Traditional consumption of crickets and grasshoppers supports established supply chains serving domestic markets and Middle Eastern export destinations via halal certification. The country's food and drug administration shapes export eligibility protocols for Southeast Asian producers. Bangkok-based processing facilities supply whole-insect formats to fine dining establishments across Southeast Asia.
Belgium
Belgian school meal programs now incorporate insect protein under EU Green Deal procurement mandates, creating institutional demand anchors. The federal agency for the safety of the food chain accelerates novel food dossier reviews to meet political deadlines for sustainable protein integration. Flanders-based research institutes collaborate with compounders on aquafeed formulation trials.
Germany
German organic chains and discounters remain underdeveloped for whole-insect and powdered formats, presenting first-mover shelf space advantages for authorized suppliers. The Federal Office of Consumer Protection and Food Safety coordinates with EFSA on harmonized safety assessments. Berlin and Hamburg host emerging direct-to-consumer brands targeting adventurous urban demographics.
Edible Insects Market Vendor Landscape
Capital-heavy producers compete with asset-light ingredient designers across the edible insects sector. The market structure fragments between vertically integrated farming operations and specialized downstream processors. Three archetypes dominate: industrial-scale vertical farmers controlling breeding-to-processing pipelines, regional substrate-optimized specialists, and technology-licensing platform providers. Competitive intensity concentrates on multi-year offtake agreement capture and automated harvesting system deployment.
Within the industrial-scale tier, Ÿnsect and Innovafeed exemplify European vertical integration models, while Aspire Food Group anchors North American-African production linkages. Protix B.V. occupies a position among Dutch substrate-optimized specialists leveraging regional organic waste streams. These entities represent divergent strategic bets on species selection, automation intensity, and geographic regulatory arbitrage.
| Leading Market Players |
|---|
| Aspire Food Group |
| Entomo Farms |
| Ÿnsect |
| Enterra Feed Corporation |
| Beta Hatch Inc. |
| Protix B.V |
| EnviroFlight LLC |
| Hexafly |
| Innovafeed |
| Others |
Supply Flow & Price Mechanics
Pharmaceutical-grade certification tiers bifurcate the edible insects market into premium food-grade and commodity feed-grade streams, with EFSA novel food authorizations commanding price premiums of 40-60% over unapproved species while simultaneously requiring capital-intensive defatting and milling infrastructure that reshapes supplier consolidation patterns.
Pricing Analysis
Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade levels governs contract negotiations, with EFSA novel food status and organic waste chain-of-custody certification as primary differentiation drivers. Price erosion runs through feed-grade mealworm protein as Norwegian salmonid producers consolidate supplier lists and demand volume discounts. Food manufacturers exhibit lowest price sensitivity, prioritizing batch-level DNA verification and carbon footprint documentation over unit cost.
Supply Chain Analysis
EU Green Deal domestic-content mandates for sustainable protein procurement redirect institutional catering contracts toward French and Dutch producers, compressing import eligibility for Thai suppliers despite established halal certification networks. Raw material dependencies center on organic waste substrate streams, automated climate control systems, and pharmaceutical-grade milling equipment. Single-source vulnerability concentrates in black soldier fly colony genetics, where proprietary breeding lines lock buyers into multi-year offtake agreements. Distribution runs through direct-to-brand ingredient supply contracts displacing spot-market trading.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The edible insects market compounds steadily as EU protein diversification mandates harden into procurement specifications across French and Dutch institutional supply chains.
For Market Incumbents: Anticipate margin compression in feed-grade segments as Norwegian aquafeed integrators consolidate around certified producers with captive breeding operations. Defensive priorities center on locking multi-year offtake agreements ahead of competitor qualification and accelerating automated harvesting deployment to reduce labor cost exposure. EFSA novel food dossier expansion into additional species categories protects pricing power in food-grade tiers. For New Entrants and Emerging Players: Enter via German organic retail channels and discounters, where shelf space allocation for whole-insect and powdered formats remains underdeveloped despite rising consumer curiosity. Pet food premiumization offers the most penetrable application segment, with insect protein formulations for allergy-sensitive animals commanding formulation premiums. A direct-to-brand ingredient supply model bypasses distributor margin capture while satisfying traceability requirements. For Investors and Strategic Acquirers: Consolidation pressure builds where downstream processing capex demands exceed farm-level financing capacity, creating acquisition opportunities for entities with capital deployment capability. The 5-10 year viability window favors vertically integrated operations controlling breeding-to-processing pipelines over substrate-optimized specialists exposed to organic waste price volatility. Monitor EFSA novel food authorization timelines as the critical inflection signal for food-grade margin expansion.| Strategic Initiative | Industry Significance |
|---|---|
| EFSA Novel Food Dossier Expansion | Unlocks bakery and sports nutrition launches across EU member states. |
| Automated Harvesting System Deployment | Reduces labor costs and contamination risk in high-density cricket colonies. |
| Multi-Year Offtake Agreement Capture | Secures volume commitments from Norwegian salmonid producers ahead of competitors. |
| Backward Integration into Breeding Operations | Captures proprietary genetics and reduces colony mortality rate volatility. |
| Pet Food Formulation Partnership | Accesses premium pricing for novel protein claims in allergy-sensitive animal nutrition. |
Methodological Framework
Direct dialogue with insect farm operations managers, EFSA regulatory affairs specialists, Dutch feed compounder procurement leads, and French food manufacturer R&D directors grounded the qualitative assessment, cross-referenced with EFSA novel food dossier filings, EU Green Deal procurement specifications, customs trade data for insect protein imports, and SEC disclosures from publicly traded ingredient suppliers. Bottom-up farm capacity estimates and top-down protein substitution demand models were triangulated to anchor volume projections.
Segment-level value outputs across the projection horizon reflect modeled interactions between species type, application grade, and end-user contract structure, with CAGRs derived from regression analysis of historical novel food authorization timelines and protein substitution elasticity in aquafeed formulations. Forecast inputs incorporated black soldier fly colony mortality rates, organic waste substrate price indices, and automation capital expenditure cycles.
The model holds under stable EFSA authorization throughput and EU procurement mandate continuity; deviation in regulatory harmonization progress or feedstock commodity cycles would shift volume trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Flaxseed Based Egg Market
Alternative Food Sources
Middle East and Africa Edible Insects Market
Alternative Food Sources
Emergency Food Market
Alternative Food Sources
Low Carbs Vegan Food Market
Alternative Food Sources
Asia-Pacific Algae Protein Market
Alternative Food Sources
Plant-Based Squalene Market
Alternative Food Sources
Mycoprotein Products Market
Alternative Food Sources
Seaweed Protein Market
Alternative Food Sources
Monoprotein Market
Alternative Food Sources
Food Cultures Market
Alternative Food Sources
Vegetable Proteins Market
Alternative Food Sources
Europe Algae Protein Market
Alternative Food Sources
Spirulina Beverages Market
Alternative Food Sources
Africa Protein Market
Alternative Food Sources
Vegan Egg Substitute Market
Alternative Food Sources
Soy Leghemoglobin Market