
 Flaxseed Based Egg Replacement Market | 2026-2036
Flaxseed Based Egg Replacement Market Size, Share, and Industry Trends Forecast 2026-2036
Flaxseed Based Egg Replacement Market Analytics
Canadian flaxseed processors are pivoting toward food-grade refining capacity to serve the egg replacement segment. ADM leverages its prairie grain elevator network to secure premium oilseed supply for North American manufacturers. Cargill sustains competitive positioning through backward integration into organic flax cultivation across Saskatchewan and Manitoba. Puratos specializes in enzyme-stabilized flaxseed systems that improve emulsification in high-ratio cake formulations.
Flaxseed based egg replacement denotes a functional ingredient system derived from Linum usitatissimum seeds, typically comprising ground meal or isolated gum fractions containing 18-22% protein and 28-35% dietary fiber by weight, which replicates the binding, leavening, and moisture-retention properties of avian eggs in baked goods and prepared foods. The powdered form dominates industrial procurement due to extended shelf stability and precise dosing in automated bakery lines, while liquid formulations gain traction among restaurant chains seeking ready-to-use batters. Food manufacturers represent the deepest margin pool as they negotiate multi-year supply contracts and drive specification standards for allergen-free and vegan-certified inputs.
The FDA's Food Allergen Labeling and Consumer Protection Act shapes product positioning by elevating flaxseed as an explicitly non-allergenic alternative to eggs and soy lecithin. The USDA National Organic Program and EU Organic Regulation constrain supply pools and create certification premiums that filter through to bakery and foodservice pricing. Stakeholders must monitor evolving protein content thresholds in Codex Alimentarius draft standards, as these will determine which flaxseed fractions qualify for egg replacement claims in export markets.
Market Dynamics
Clean-label mandates from retail chains are forcing bakery manufacturers to eliminate synthetic emulsifiers and declare allergen-free status, compressing formulation cycles and elevating flaxseed gum fractions to preferred ingredient status.
Growth Catalysts
- EU Green Deal protein diversification targets:The sustainable protein framework redirects public procurement and R&D subsidies toward plant-derived binding systems in institutional foodservice across Germany, France, and the Netherlands.
- Commercial bakery automation:Powdered flaxseed meal integrates into pneumatic dosing systems without viscosity calibration, reducing line changeover time for industrial cake and muffin production.
- FDA allergen labeling pressure:The Food Allergen Labeling and Consumer Protection Act elevates flaxseed as an explicitly non-allergenic alternative in school nutrition and healthcare foodservice specifications.
Market Restraints
- Organic certification supply scarcity:USDA National Organic Program and EU Organic Regulation constraints limit eligible flax acreage, creating premium pricing tiers that filter through to mid-tier bakery margins.
- Protein content variability:Weather-dependent growing conditions in Saskatchewan and Manitoba generate batch-to-batch functional inconsistency in binding strength for high-ratio sponge formulations.
- Egg white powder price volatility:Avian influenza cycles in major producing regions periodically collapse the price gap between conventional eggs and flaxseed alternatives, freezing substitution decisions.
Strategic Opportunities
- Artisanal bakery channel penetration:Small-batch sourdough and viennoiserie producers in Italy and Spain represent unserved demand for enzyme-stabilized flaxseed systems that replicate egg wash glazing.
- Cellular agriculture convergence:Hybrid formulations combining flaxseed gum with precision-fermented proteins address texture gaps in vegan meringue and foam applications.
- Extended shelf-life frozen batters:Liquid flaxseed emulsions enable restaurant chains to deploy ready-to-use pancake and waffle mixes with 180-day frozen stability.
Industry Challenges
- Food technologist specialization gap:Formulation expertise in hydrocolloid hydration kinetics and flaxseed mucilage activation remains concentrated among legacy ingredient suppliers, constraining in-house R&D at mid-size bakeries.
- Multi-certification timeline compression:Simultaneous pursuit of vegan, organic, non-GMO, and gluten-free validations creates documentation bottlenecks that delay product launches by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Flaxseed Based Egg Replacement Market |
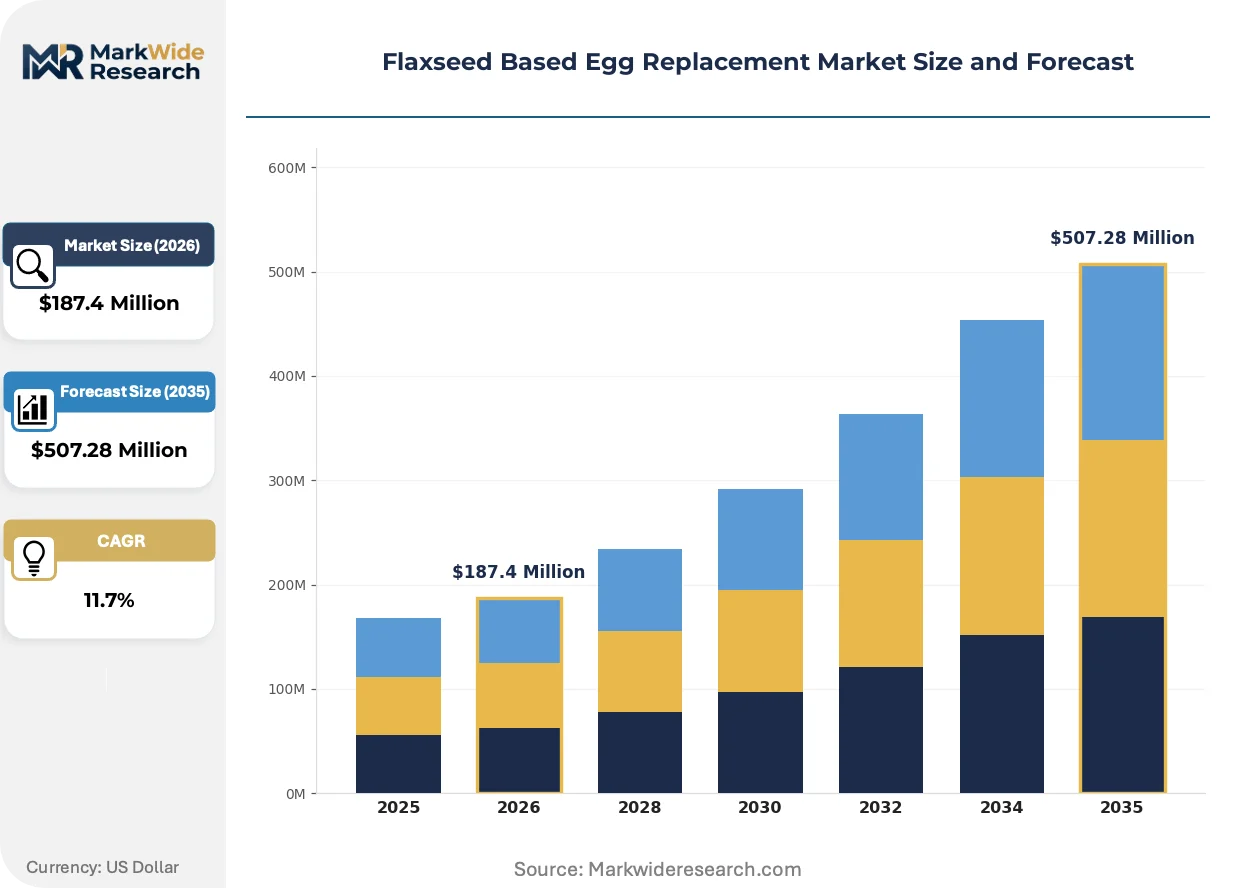
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $507.28 Million |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flaxseed Meal, Ground Flaxseed, Flaxseed Oil, Flaxseed Powder Form: Liquid, Powdered, Frozen, Dehydrated Distribution Channel: Supermarkets, Online Retail, Health Stores, Specialty Shops End User: Food Manufacturers, Bakeries, Restaurants, Home Cooks |
| Companies Covered | Archer Daniels Midland (ADM), Cargill, Puratos Group, DuPont, Glanbia, Corbion, Ingredion, Bob's Red Mill, Ener-G Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Flaxseed Based Egg Replacement Market Evolving Landscape
Enzymatic processing breakthroughs are unlocking functional performance previously restricted to egg-derived systems, while regulatory alignment on protein claims is reshaping export qualification standards across major food manufacturing jurisdictions.
Microfluidized flaxseed gum fractions are absorbing moisture-binding workloads in reduced-fat cake formulations that previously required whole egg or modified starch combinations. Industrial manufacturers in Germany and Canada are adopting these systems at pilot scale, with commercial rollout accelerating through 2026. The technology is absorbing margin pressure from volatile egg commodity markets by delivering consistent emulsification across variable ambient humidity conditions.
REACH registration requirements for novel food ingredients are tightening purity specifications for lignan content and microbial thresholds in flaxseed-derived inputs entering European Union markets. Industrial consequence includes mandatory third-party testing protocols that add 12-18% to ingredient certification costs. German and Dutch bakery ingredient distributors are responding by consolidating supplier audits and demanding pre-certified raw material streams from Canadian processors.
Direct procurement relationships between bakery chains and flaxseed processors are displacing traditional ingredient distributor intermediaries in North American foodservice. Restaurant groups with 200-plus unit footprints now negotiate volume contracts specifying protein content minimums and lot-traceability documentation. This pattern is most visible in the United States, where quick-service bakery concepts are building captive supply agreements with Saskatchewan-based processors to secure clean-label positioning for breakfast sandwich programs.
Flaxseed Based Egg Replacement Market Segmentation
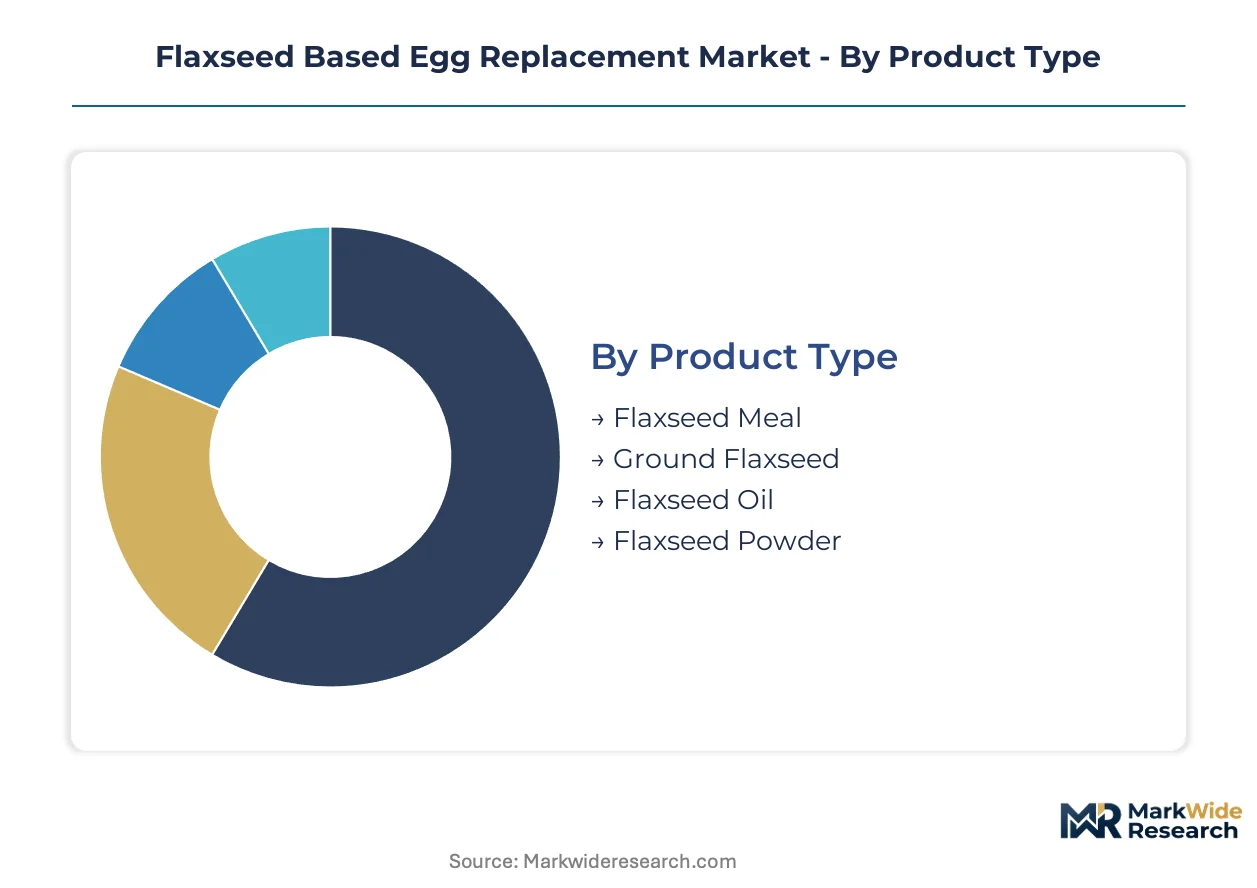
Segmentation in flaxseed-based egg replacement reveals how supply chain configuration shapes competitive access. Each dimension exposes distinct margin pools, formulation constraints, and procurement behaviors that determine supplier strategy.
Product Type:
Supply concentration in Canadian prairie processing elevates specific fractions above commodity alternatives.
- Flaxseed Meal:Coarsely milled whole seeds retain 18-22% protein and 28-35% dietary fiber, delivering binding functionality in industrial bread and muffin lines. German artisanal bakeries and North American commercial manufacturers negotiate multi-year contracts for specified particle size distributions.
- Ground Flaxseed:Finer milling increases surface area for mucilage activation, improving moisture retention in reduced-fat cake formulations. Saskatchewan processors control premium supply through backward integration into organic cultivation.
- Flaxseed Oil:Cold-pressed linseed oil serves niche emulsification applications where lipid profiles matter more than protein content.
- Flaxseed Powder:Defatted and micronized fractions integrate into pneumatic dosing systems without viscosity calibration.
Today's leader: Flaxseed Meal. Tomorrow's challenger: Ground Flaxseed.
Form:
Automation compatibility and shelf stability separate industrial procurement from foodservice purchasing patterns.
- Powdered:Extended shelf stability and precise dosing dominate automated bakery lines. Quick-service restaurant chains in the United States specify lot-traceability documentation for breakfast sandwich programs.
- Liquid:Ready-to-use emulsions gain traction among restaurant chains deploying frozen batters with 180-day stability.
- Frozen:Extended shelf-life batters enable centralized production for multi-unit bakery concepts.
- Dehydrated:Lightweight logistics suit export markets with constrained cold chain infrastructure.
Powdered commands industrial volume. Liquid gains share fastest in foodservice.
Distribution Channel:
Direct procurement relationships are displacing traditional intermediaries as scale buyers demand specification control.
- Supermarkets:Packaged consumer formats face margin compression from private-label competition.
- Online Retail:Specialty and bulk formats reach home cooks and small-batch producers without geographic constraint.
- Health Stores:Certification premiums for organic and non-GMO products filter through to pricing.
- Specialty Shops:Artisanal bakery supply channels in Italy and Spain represent unserved demand for enzyme-stabilized systems.
Supermarkets anchor volume. Specialty Shops offer steepest expansion trajectory.
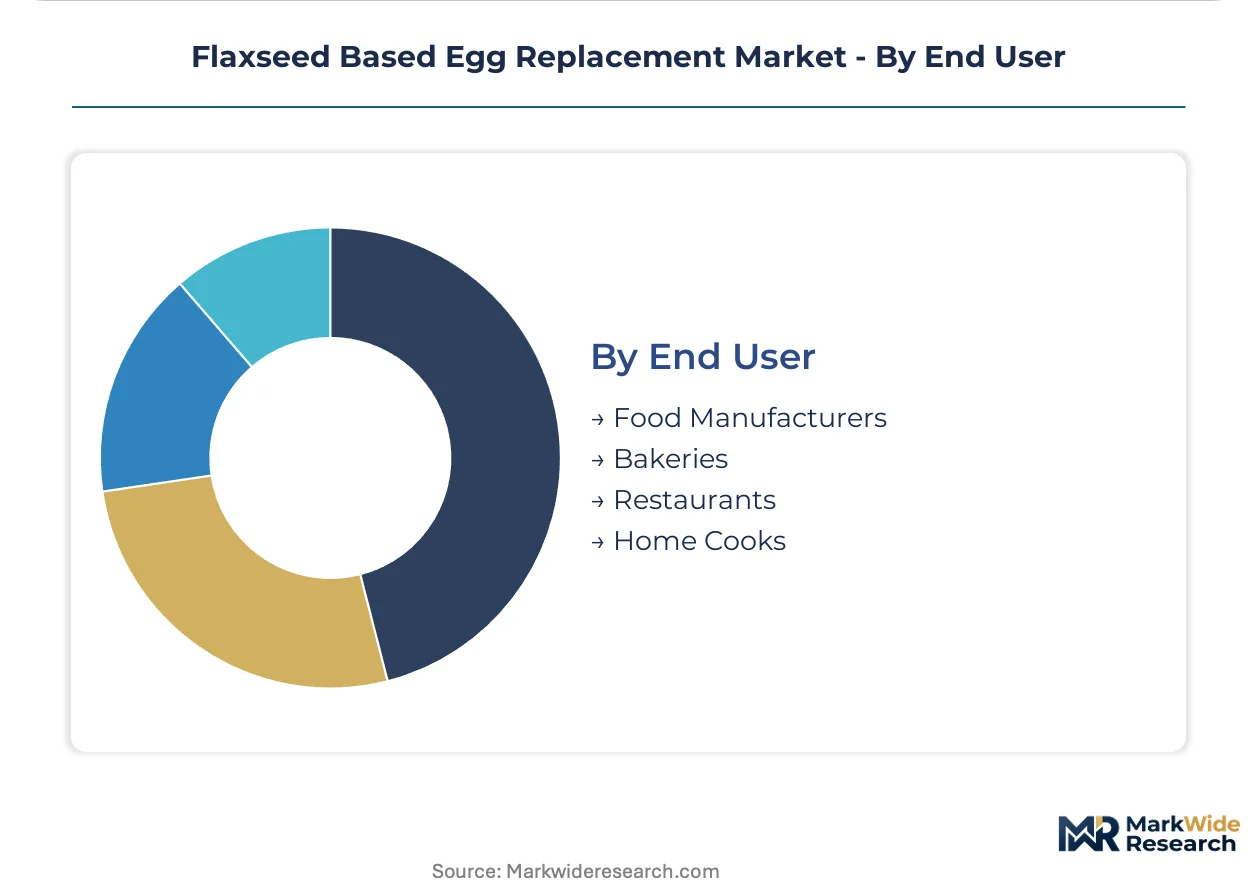
End User:
Specification authority and contract duration determine margin capture across the value chain.
- Food Manufacturers:Deep margin pools emerge from multi-year supply contracts and allergen-free certification requirements. FDA Food Allergen Labeling and Consumer Protection Act compliance elevates flaxseed in school nutrition specifications.
- Bakeries:Clean-label mandates from retail chains force elimination of synthetic emulsifiers, compressing formulation cycles.
- Restaurants:Frozen batter applications drive liquid emulsion demand with volume contract negotiation.
- Home Cooks:Package size and recipe guidance dominate purchasing decisions.
Food Manufacturers set standards. Bakeries are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's artisanal bakery reformulation surge contrasts with Canada's prairie-to-processor pipeline dominance, revealing how regulatory pressure and agricultural endowment shape divergent market architectures.
United States
Quick-service restaurant chains with 200-plus unit footprints now negotiate direct volume contracts specifying protein content minimums. The FDA Food Allergen Labeling and Consumer Protection Act elevates flaxseed in school nutrition and healthcare foodservice specifications. Minneapolis-based processors serve breakfast sandwich programs across the Midwest and Southeast.
Canada
Saskatchewan and Manitoba flax cultivation supplies premium organic and conventional oilseed to North American manufacturers. Prairie grain elevator networks secure supply continuity for multi-year industrial contracts. Winnipeg and Regina processing clusters specialize in enzyme-stabilized fractions for high-ratio cake emulsification.
Germany
Artisanal bakeries and industrial manufacturers alike reformulate traditional recipes to meet EU Green Deal protein diversification targets. REACH registration requirements tighten purity specifications for lignan content and microbial thresholds. Cologne and Munich distribution hubs consolidate supplier audits for pre-certified raw material streams.
Netherlands
Institutional foodservice procurement redirects toward plant-derived binding systems under sustainable protein framework subsidies. Dutch bakery ingredient distributors demand third-party testing protocols from Canadian processors. Rotterdam logistics clusters enable just-in-time delivery to industrial manufacturers across the Benelux.
Italy
Small-batch sourdough and viennoiserie producers represent unserved demand for enzyme-stabilized flaxseed systems replicating egg wash glazing. EU Organic Regulation constraints limit eligible supply pools, creating certification premiums. Milan and Turin specialty channels source defatted micronized fractions for premium positioning.
Flaxseed Based Egg Replacement Market Competitive Landscape
North American agribusiness conglomerates anchor one tier; European specialty ingredient specialists hold differentiated positions through enzymatic processing capabilities. The vendor base separates into three strategic archetypes: prairie-integrated oilseed processors, enzyme-technology formulators, and clean-label consumer brands. Dominant competitive moves include backward integration into organic cultivation and direct procurement relationship displacement of traditional distributor intermediaries.
Within the agribusiness tier, Archer Daniels Midland leverages its prairie grain elevator network while Cargill sustains positioning through upstream control over Saskatchewan and Manitoba organic flax cultivation. Puratos Group exemplifies the enzyme-technology specialist archetype, occupying a position in stabilized systems for industrial bakery applications.
| Leading Market Players |
|---|
| Archer Daniels Midland (ADM) |
| Cargill |
| Puratos Group |
| DuPont |
| Glanbia |
| Corbion |
| Ingredion |
| Bob's Red Mill |
| Ener-G Foods |
| Others |
Value Network & Pricing Analysis
Food technologist concentration in Winnipeg and Regina processing clusters drives labor-cost differentials that widen pricing-tier spreads between commodity flaxseed meal and enzyme-stabilized premium fractions.
Pricing Analysis
Capacity additions in Saskatchewan are reshaping price floors for organic flaxseed fractions. Three-tier pricing structure across premium, standard, and economy levels reflects protein content minimums and certification grade. Price differentiation hinges on EU Organic Regulation compliance and lot-traceability documentation. Mid-tier bakeries exhibit highest price sensitivity; quick-service chains with direct procurement contracts show lowest.
Supply Chain Analysis
Single-source vulnerability sits with Canadian prairie cultivation for premium oilseed supply. Geographic concentration centers on Saskatchewan, Manitoba, and Alberta. Raw material dependencies include Linum usitatissimum seeds, food-grade refining capacity, and enzyme processing inputs. Tariff exposure on cross-border flows to United States processors creates structural risk. Distribution runs through direct procurement relationships displacing traditional ingredient distributor intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Flaxseed-based egg replacement offers margin expansion through clean-label premium-tier shifts and automation-driven cost compression in high-volume bakery applications.
For Market Incumbents: Hedge against avian influenza-driven egg price volatility by securing multi-year organic cultivation contracts in Saskatchewan. Invest in enzyme-stabilized fraction capacity to defend against precision-fermented protein substitutes. Backward integration into prairie grain elevator networks locks supply continuity. For New Entrants and Emerging Players: Enter via artisanal bakery channels in Italy and Spain where enzyme-stabilized systems for egg wash glazing remain underserved. Target small-batch sourdough and viennoiserie producers with technical formulation support. Position through specialty distributor partnerships rather than direct industrial procurement. For Investors and Strategic Acquirers: Agribusiness conglomerates with prairie infrastructure are the most active acquirer in this space. Five-to-ten year viability rests on clean-label mandate durability and protein diversification policy continuity. Acquire enzyme-technology specialists with hydrocolloid hydration expertise. Watch FDA protein content threshold rulings as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organic Cultivation | Cargill and ADM secure Saskatchewan acreage to guarantee supply for multi-year bakery contracts. |
| Enzyme Stabilization Technology Investment | Puratos captures premium positioning in high-ratio cake emulsification for industrial manufacturers. |
| Direct Procurement Relationship Building | Quick-service chains bypass distributors to negotiate protein-content specifications with prairie processors. |
| Artisanal Channel Penetration | Specialty suppliers unlock Italian and Spanish small-batch bakery demand for egg wash alternatives. |
| Hybrid Formulation Development | Combinations with precision-fermented proteins address texture gaps in vegan meringue applications. |
Research Methodology
Bottom-up bakery and foodservice modeling reconciled against top-down oilseed processing capacity tracking forms the analytical core. Primary interviews with food technologists, procurement leads at commercial bakeries, ingredient distributor category managers, and regulatory affairs specialists combined with secondary validation. Secondary sources include USDA National Organic Program filings, EU REACH registration databases, Canadian Grain Commission trade data, and FDA Food Allergen Labeling guidance documents. Triangulation across these inputs ensures cross-verified demand and supply estimates.
Historical trendline analysis of flaxseed fraction pricing and industrial procurement volumes anchors the projection framework. Segmentation dimensions modeled include product type, form, distribution channel, and end-user specification authority across the analysis window. CAGRs derive from slope analysis of clean-label adoption curves and automation penetration rates. Industry-specific forecast inputs incorporate EU Green Deal protein diversification timelines and commercial bakery line retrofit cycles.
Inputs from prairie processor disclosures and German artisanal bakery associations were available through the study window; gaps in proprietary enzyme formulation performance data introduce uncertainty bands. Forecasts reflect documented assumptions regarding regulatory alignment on protein claims and avian influenza cycle patterns. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Precision Fermentation Market
Alternative Food Sources
Konjac Market
Alternative Food Sources
Synthetic Food Market
Alternative Food Sources
Vegan Sashimi Market
Alternative Food Sources
Fish Oil Alternatives Market
Alternative Food Sources
Mycoprotein Products Market
Alternative Food Sources
Flaxseed Based Egg Market
Alternative Food Sources
Asia-Pacific Meal Replacement Products Market
Alternative Food Sources
Plant-Based Compound Feed Market
Alternative Food Sources
Global Meal Replacement Shakes Market
Alternative Food Sources
Europe Duckweed Protein Market
Alternative Food Sources
Asia-Pacific Algae Protein Market
Alternative Food Sources
Plant-Based Squalene Market
Alternative Food Sources
Fat Replacers Market
Alternative Food Sources
Mycoprotein Market
Alternative Food Sources
Egg Replacers Market