
 North America Meat Substitutes Market | 2026-2036
North America Meat Substitutes Market Size, Share, and Industry Trends Forecast 2026-2036
North America Meat Substitutes Market Analytics
Asset-light co-manufacturing partnerships is reconfiguring competitive entry barriers for emerging brands in the North America meat substitutes sector. Beyond Meat Inc. leverages dedicated production facilities to sustain quality consistency at scale. Impossible Foods Inc. anchors its position through proprietary heme technology and deep food service relationships. Kellogg Company competes via established retail distribution networks that span thousands of grocery outlets across the United States and Canada.
Meat substitutes encompass protein-rich food products engineered to replicate the sensory properties, nutritional profiles, and culinary functionality of conventional animal meat, typically formulated from isolated plant proteins, extruded texturized vegetable proteins, or fermented mycelial biomass with moisture content ranging from fifty to seventy percent. These products serve industrial food manufacturers and commercial kitchens seeking to reduce saturated fat content while maintaining chew resistance and umami depth in finished dishes. Plant-based burgers command the largest revenue pool within product type categories, reflecting heavy investment in fat mimicry and browning chemistry. Pea protein isolates represent the fastest-expanding source segment as allergen concerns and non-GMO positioning displace soy dominance in new product development. Food service channels capture disproportionate margin attention as contract volumes with national restaurant chains lock in multi-year supply commitments.
The U.S. Food and Drug Administration and the U.S. Department of Agriculture share jurisdiction over cell-cultured meat labeling, while Health Canada oversees novel food approvals for fermented and precision-fermentation proteins entering Canadian commerce. These frameworks determine which production technologies achieve retail shelf access and how products must declare protein origin to consumers. Stakeholders must monitor evolving enforcement discretion between federal agencies as novel production methods blur traditional regulatory boundaries.
Market Dynamics
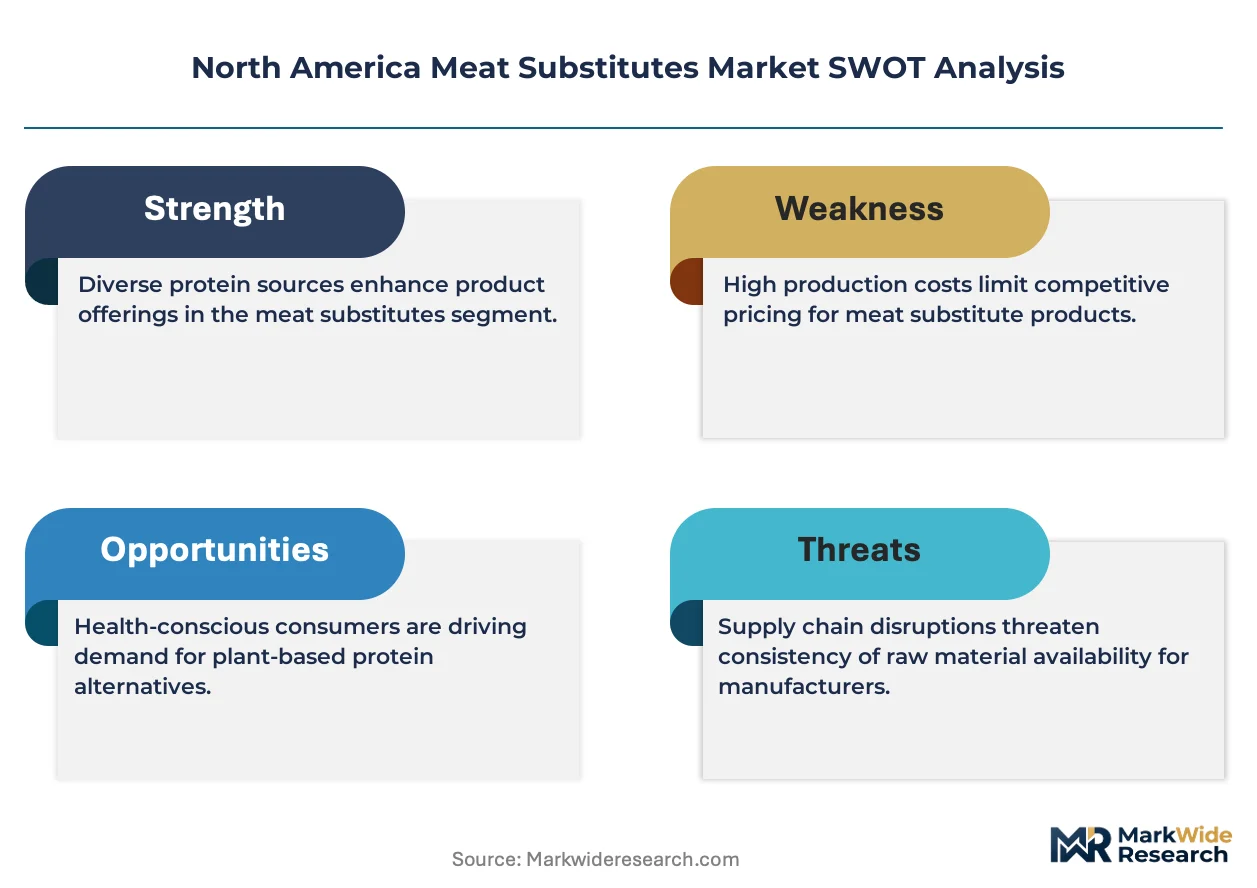
Co-manufacturing networks are redrawing capital requirements for new entrants, allowing brands to scale without owning extrusion or fermentation infrastructure while FDA-USDA jurisdictional clarity over cell-cultured products opens commercial pathways previously blocked by regulatory ambiguity.
Growth Catalysts
- Protein diversification mandates:Institutional food service contracts in California and the U.S. West Coast now require plant-forward menu rotations, creating guaranteed offtake volumes for textured protein suppliers.
- Health Canada novel food pathways:Streamlined approvals for precision-fermentation proteins accelerate Canadian market entry, reducing time-to-shelf for mycelium-based products.
- Pea protein extraction advances:Wet-fractionation improvements at Midwest processing facilities lower isolate costs and improve functional properties for high-moisture extrusion.
Market Restraints
- Input cost volatility:Yellow pea and faba bean prices fluctuate with Prairie Province crop yields, squeezing margin predictability for isolate-dependent formulations.
- Supply concentration risk:North American extrusion capacity clusters in Illinois and Minnesota, creating geographic vulnerability to regional logistics disruptions.
- Technical limitation:Current fat-mimicry chemistry fails to replicate beef tallow mouthfeel above 180°C searing temperatures, limiting culinary equivalence in high-heat applications.
Strategic Opportunities
- Underpenetrated Canadian Prairies:Saskatchewan and Manitoba institutional buyers remain underserved by national distribution networks, offering first-mover advantages for regional co-packing arrangements.
- Regulatory tailwind:U.S. FDA updated labeling guidelines for cell-cultured and plant-based meat products reduce compliance uncertainty, encouraging R&D investment in hybrid biomass formulations.
- Direct-to-food service platforms:Digital procurement portals connecting regional processors with independent restaurant chains bypass legacy distributor markups and improve margin capture.
Industry Challenges
- Specialized workforce scarcity:Food science PhDs with extrusion rheology expertise command premium compensation, constraining formulation team expansion at mid-size brands.
- Certification timeline compression:Non-GMO Project verification and organic certification require 14-18 month audit cycles, delaying product launches behind competitor windows.
- Legacy ERP integration:Batch-level traceability requirements for allergen management clash with older manufacturing execution systems, forcing costly middleware deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Meat Substitutes Market |
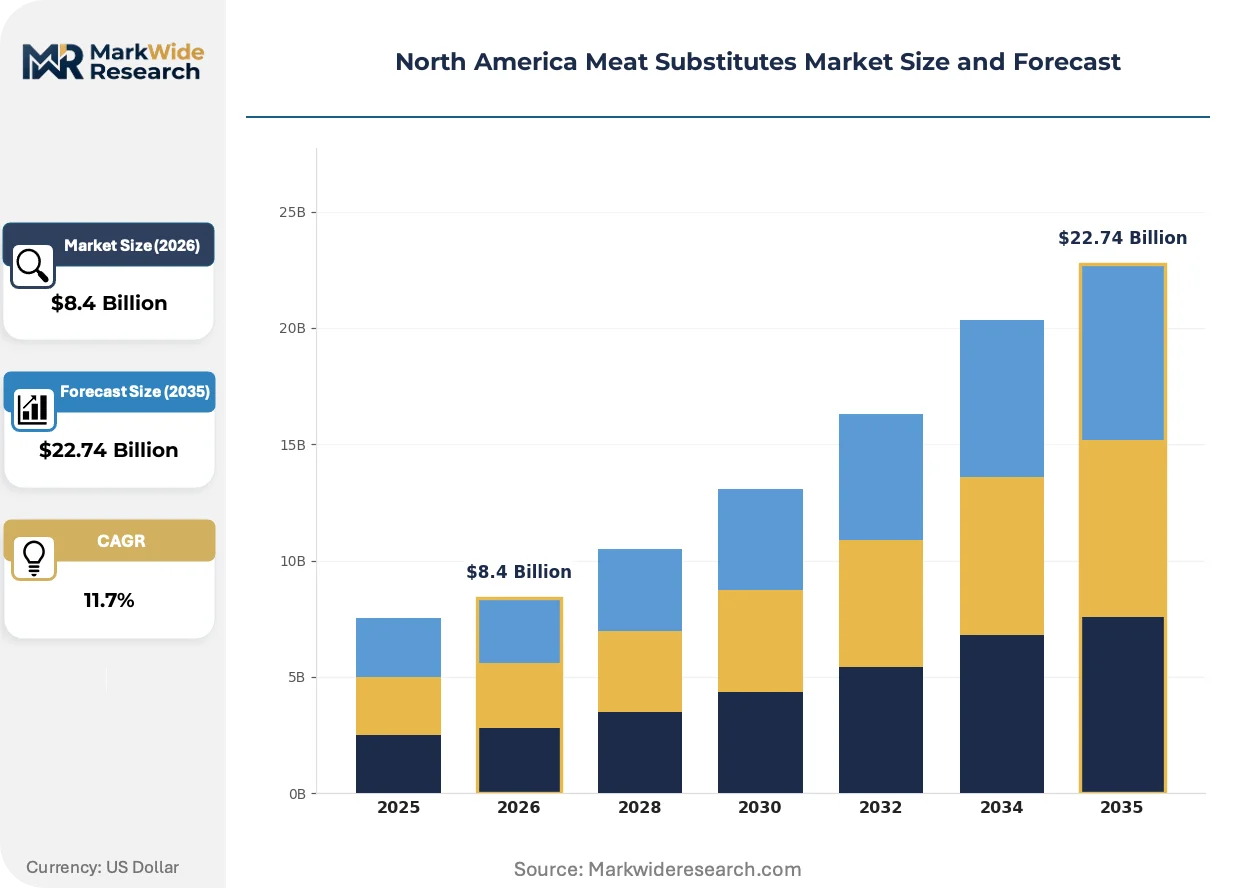
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $22.74 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Tofu, Tempeh, Seitan, Plant-Based Burgers Source: Peas, Soy, Wheat, Lentils Customer Type: Retail Consumers, Food Service, Wholesale Distributors, Nutricosmetics Application: Snacking, Cooking, Meal Replacement, Functional Foods |
| Companies Covered | Nestlé S.A., Kellogg Company, Beyond Meat Inc., Lightlife Foods, Quorn Foods, Impossible Foods Inc., Conagra Brands Inc., Amy's Kitchen Inc., Maple Leaf Foods Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Meat Substitutes Market Evolving Landscape
Product development priorities are pivoting from simple protein replacement toward complete nutritional equivalence, with R&D investment concentrating on amino acid optimization and bioavailable micronutrient fortification rather than texture alone.
High-moisture extrusion technology is migrating from European equipment suppliers to North American retrofit installations. Regional processors in Ohio and Wisconsin are adopting twin-screw systems capable of 65-70% moisture content, enabling whole-muscle analog production that previously required imported machinery. This equipment localization is compressing capital recovery timelines from seven to four years for mid-capacity lines.
The U.S. FDA and USDA finalized their joint oversight framework for cell-cultured meat labeling in late 2023, establishing which agency reviews facility inspections versus product claims. This clarity is accelerating commercialization timelines for cultivated poultry and beef startups, with the restaurant channel capturing initial volumes before retail shelf approval. Food service operators now structure supply contracts with explicit regulatory milestone clauses.
Contracting patterns among national restaurant chains are consolidating supplier relationships around fewer, larger-volume partners. Multi-year protein supply agreements with fixed-price escalators are displacing spot purchasing for plant-based menu items, particularly in the quick-service burger segment. This concentration is most visible in Texas and Florida markets where chain penetration exceeds independent restaurant density.
North America Meat Substitutes Market Segmentation
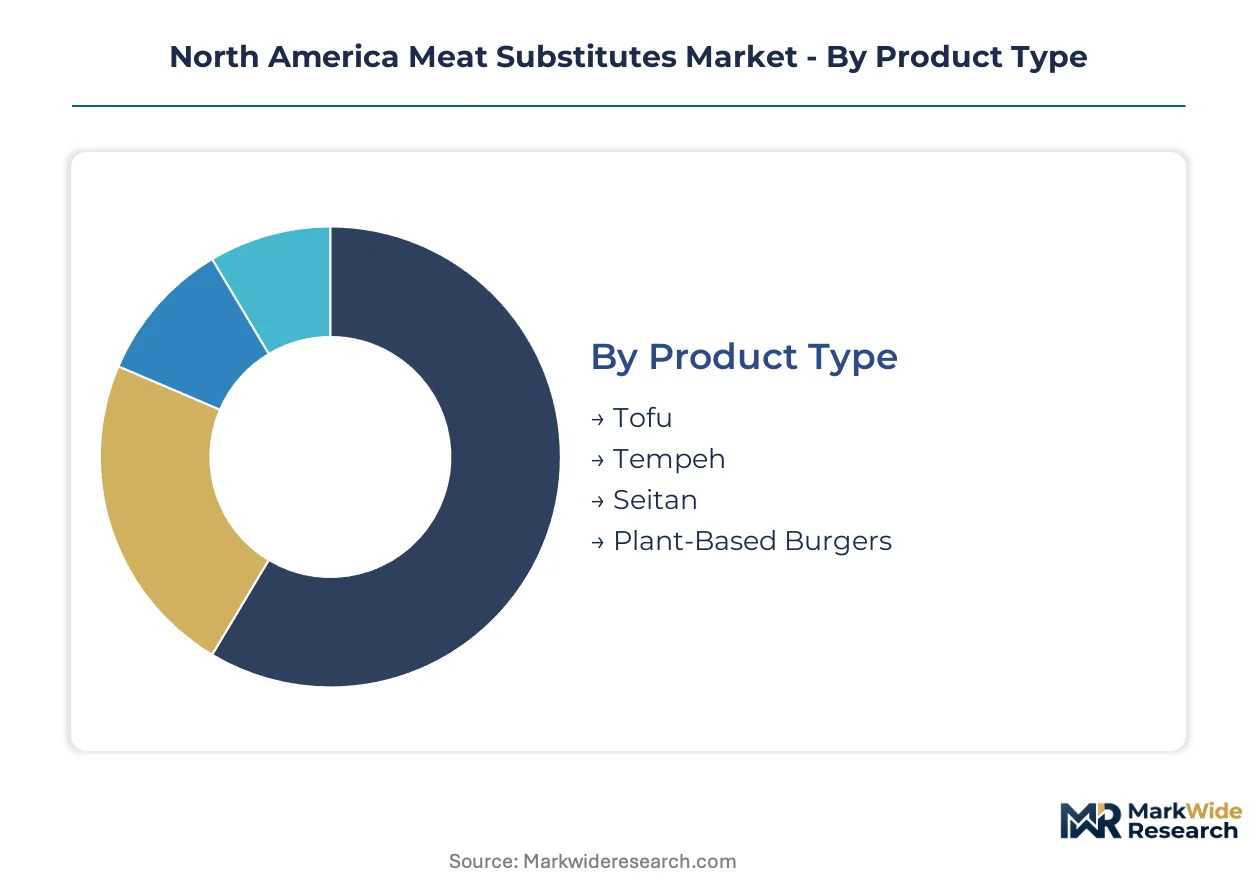
Segmentation reveals divergent technical requirements across North American meat substitute applications. Product formulation, protein sourcing, and channel economics each create distinct competitive battlegrounds with specialized margin structures.
Product Type:
Use cases span from whole-food ingredient substitutes to engineered sensory replicants with divergent capital intensity.
- Plant-Based Burgers:High-moisture extrusion and fat-mimicry chemistry replicate beef patty browning and chew. Quick-service chains in California and Texas lock in multi-year supply contracts with fixed-price escalators, concentrating demand among three national processors.
- Seitan:Vital wheat gluten hydration creates fibrous, chew-dense structures suited to Asian-American restaurant applications. Independent chains in Vancouver and Toronto drive regional demand, constrained by gluten-allergen labeling requirements that limit school and healthcare penetration.
- Tofu:Coagulated soy protein with moisture content ranging from 70-88% serves East Asian cooking traditions and vegetarian retail segments. Midwest production clusters supply bulk food service through established co-packing networks.
- Tempeh:Fermented whole-soybean cakes with bound mycelium deliver probiotic positioning and firm sliceability. Specialty retail and natural food co-ops in the U.S. Pacific Northwest and British Columbia sustain regional artisan production.
Established volume favors plant-based burgers; emerging adoption favors seitan in food service ethnic menu expansion.
Source:
Protein extraction economics and allergen risk profiles differentiate sourcing strategies across formulation types.
- Peas:Yellow pea isolate production at Prairie Province processing facilities achieves non-GMO positioning and hypoallergenic claims. Wet-fractionation advances lower functional protein costs for high-moisture extrusion applications in Ohio and Wisconsin facilities.
- Soy:Isolated soy protein maintains cost leadership in textured vegetable protein applications despite GMO and allergen headwinds. Legacy extrusion infrastructure in Illinois and Minnesota optimizes around soy concentrate feedstocks.
- Wheat:Vital gluten supplies seitan manufacturers and hybrid blend formulations with elastic protein networks. Kansas and Oklahoma milling proximity reduces inbound logistics for central U.S. production.
- Lentils:Canadian Prairie crop volumes support emerging isolate production targeting clean-label positioning and fiber-retention benefits. Small-scale processing in Saskatchewan and Alberta serves regional organic brands.
Cost leadership concentrates in soy; clean-label momentum and allergen avoidance accelerate pea expansion fastest.
Customer Type:
Channel margin structures and procurement sophistication create distinct supplier requirements.
- Food Service:National restaurant chains demand batch-level traceability, multi-year volume commitments, and culinary technical support. Contract consolidation around fewer, larger-volume partners is compressing supplier counts in Texas and Florida markets.
- Retail Consumers:Grocery placement requires Non-GMO Project verification and 14-18 month certification timelines that delay launches behind food service windows. Club store and mass merchant channels drive case-count economics.
- Wholesale Distributors:Broadline food service distributors aggregate independent restaurant and institutional demand with 15-25% markups that squeeze branded margin capture. Digital procurement portals are emerging to bypass this layer.
- Nutricosmetics:Functional food and beauty-from-within applications demand amino acid optimization and bioavailable micronutrient fortification beyond standard protein replacement. Regulatory ambiguity at FDA over structure-function claims constrains positioning.
Volume concentration favors food service; margin expansion potential favors direct-to-operator digital platforms.
Application:
Consumption occasion and preparation method determine formulation priorities and packaging formats.
- Cooking:Raw or minimally processed formats requiring heat application in home or commercial kitchens dominate volume. Texture stability across sauté, braise, and grill methods determines repeat purchase rates.
- Meal Replacement:Complete nutrition profiles with amino acid optimization target fitness and weight-management segments. Shelf-stable and refrigerated ready-to-eat formats compete with legacy frozen entrees.
- Snacking:Portable, single-serve formats with umami intensity and crisp texture target convenience channels. Jerky analogs and protein puffs drive innovation in extrusion and dehydration technologies.
- Functional Foods:Fortified positioning with probiotic, fiber, or micronutrient claims targets health-motivated purchasers. Health Canada novel food pathways accelerate precision-fermentation protein approvals for this segment.
Mainstream penetration centers on cooking applications; premium positioning and regulatory tailwinds favor functional foods expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal and state-level procurement mandates across the United States and Canada are accelerating institutional adoption of plant-based proteins. The U.S. FDA and USDA joint oversight framework for cell-cultured meat labeling has clarified commercial pathways. Health Canada novel food approval pathways reduce regulatory friction for precision-fermentation proteins entering Canadian distribution.
United States
California and the U.S. West Coast anchor demand concentration, where restaurant chains and institutional buyers normalize meat-free protein rotations. The FDA updated labeling guidelines for cell-cultured and plant-based meat products in late 2023, establishing facility inspection versus product claim jurisdiction with USDA. Ohio and Wisconsin processing clusters adopt twin-screw extrusion systems for 65-70% moisture content whole-muscle analog production.
Canada
Health Canada novel food pathways streamline approvals for precision-fermentation proteins, accelerating mycelium-based product market entry. Saskatchewan and Manitoba institutional buyers remain underserved by national distribution networks, creating first-mover opportunities for regional co-packing arrangements. Prairie Province processing facilities achieve non-GMO positioning through yellow pea isolate production with wet-fractionation cost improvements.
Mexico
Mexico City Metro quick-service chains expand plant-based menu placements following U.S. parent company procurement directives. The country's federal consumer protection agency monitors labeling claims for meat analog products entering retail channels. Northern Border States manufacturing clusters supply extruded textured protein to food service distributors serving cross-border restaurant operations.
North America Meat Substitutes Market Competitive Landscape
Channel-controlling players compete with product-specialist players across divergent margin structures. National restaurant chain procurement consolidation favors suppliers with multi-year volume commitment capacity and batch-level traceability infrastructure. Three archetypes dominate: dedicated production facility operators, proprietary technology licensors, and established retail distribution network holders. Competitive moves center on co-manufacturing partnership expansion and regulatory milestone-linked supply contract structuring.
Within the technology-licensor tier, Impossible Foods Inc. and Beyond Meat Inc. occupy positions defined by proprietary differentiation. Kellogg Company anchors the retail-network archetype through grocery outlet coverage spanning thousands of locations. Nestlé S.A. exemplifies the diversified multinational structure with portfolio breadth across protein categories.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Kellogg Company |
| Beyond Meat Inc. |
| Lightlife Foods |
| Quorn Foods |
| Impossible Foods Inc. |
| Conagra Brands Inc. |
| Amy's Kitchen Inc. |
| Maple Leaf Foods Inc. |
| Others |
Value Network & Pricing Analysis
Prairie Province yellow pea processing clusters in Saskatchewan and Manitoba anchor upstream protein isolate supply, concentrating margin capture among wet-fractionation operators while downstream branded players absorb volatile input costs through long-term contract structures.
Pricing Analysis
Certification level creates the primary spread between Non-GMO Project verified premiums and conventional commodity tiers. Three-tier pricing structure across premium, standard, and economy levels reflects brand equity, protein purity grades, and food service contract scale. Pricing pressure stems from yellow pea and faba bean crop yield volatility squeezing isolate-dependent formulations. Quick-service restaurant chains exhibit highest price sensitivity due to fixed-menu pricing constraints, while specialty retail channels absorb modest premiums for clean-label positioning.
Supply Chain Analysis
Midwest co-manufacturing networks in Illinois, Minnesota, and Ohio hold dominant extrusion and fermentation capacity for North American meat substitute production. Yellow pea isolate, vital wheat gluten, and precision-fermentation biomass constitute critical input dependencies. Single-source vulnerability concentrates in Illinois and Minnesota extrusion infrastructure exposed to regional logistics disruptions. Distribution runs through broadline food service distributors with 15-25% markups, though digital procurement portals are emerging to bypass legacy distributor layers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America meat substitutes sector represents a high-growth disruption anchored by FDA-USDA regulatory clarity over cell-cultured meat labeling, which accelerates commercialization timelines and consolidates procurement relationships around scale-capable suppliers.
For Market Incumbents: Insulate margin pools through backward integration into Prairie Province pea protein processing and captive supply of high-purity isolates. Expand Ohio and Wisconsin twin-screw extrusion capacity to capture food service contract consolidation. Defend against emerging precision-fermentation entrants by locking multi-year volume commitments with national restaurant chains before regulatory milestone clauses mature.
For New Entrants and Emerging Players: Build out regional co-packing arrangements targeting underserved Saskatchewan and Manitoba institutional buyers where national distribution networks remain thin. Penetrate the Canadian Prairies through direct-to-food service digital platforms that bypass legacy distributor markups. Anchor go-to-market positioning on Health Canada novel food pathway acceleration for mycelium-based products.
For Investors and Strategic Acquirers: Capital is best deployed toward wet-fractionation specialists with Prairie Province processing assets and established Non-GMO Project certification infrastructure. Long-term viability over the next decade hinges on securing positions upstream of pea protein isolate supply. Monitor FDA enforcement discretion between federal agencies over hybrid biomass formulations as the critical inflection signal for portfolio rebalancing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Pea Protein Processing | Captures margin pools concentrated in Saskatchewan and Manitoba wet-fractionation facilities. |
| Multi-Year Food Service Supply Agreements | Locks volume commitments with California and Texas quick-service chains ahead of competitor windows. |
| Health Canada Novel Food Pathway Navigation | Accelerates mycelium-based product approvals for Canadian market entry before USDA-FDA jurisdictional clarity. |
| Digital Procurement Platform Development | Bypasses broadline distributor markups connecting regional processors with independent restaurant chains. |
| High-Moisture Extrusion Capacity Expansion | Enables whole-muscle analog production at Ohio and Wisconsin facilities with compressed capital recovery timelines. |
Research Methodology
Cross-validation between primary interviews with food science executives, plant-based protein procurement leads at national restaurant chains, extrusion equipment specialists, and regulatory affairs directors anchors the qualitative findings. Secondary validation draws from FDA labeling guideline updates, USDA facility inspection records, Health Canada novel food approval databases, and Prairie Province agricultural yield statistics. Bottom-up segmentation modeling triangulates with top-down macroeconomic calibration across the analysis window.
Calibration against historical volume trajectories and installed capacity utilization rates informs the projection framework. Segmentation dimensions span product type, protein source, customer channel, and application occasion with regional regulatory cluster overlays. CAGRs derive from elasticity-adjusted demand curves and supply-side capacity expansion schedules. Forecast inputs incorporate wet-fractionation cost curves and twin-screw extrusion adoption rates at Midwest processing facilities.
Practitioners should monitor FDA-USDA enforcement discretion shifts, Prairie Province crop yield volatility, and food service contract renewal cycles for early signals of trajectory revision. Forecasts reflect assumptions around regulatory pathway stability and input cost normalization without guaranteed outcomes. Quarterly review of extrusion capacity utilization rates and novel food approval timelines is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Africa Potato Protein Market
Alternative Food Sources
Europe Algae Protein Market
Alternative Food Sources
Seitan Market
Alternative Food Sources
Black Soldier Fly (BSF) Market
Alternative Food Sources
Bioengineered Food Market
Alternative Food Sources
Spirulina Market
Alternative Food Sources
Plant-Based Squalene Market
Alternative Food Sources
Meal Replacement Bars Market
Alternative Food Sources
Vegan Caviar Market
Alternative Food Sources
Fat Replacers Market
Alternative Food Sources
Algae Oil Market
Alternative Food Sources
Flaxseed Based Egg Replacement Market
Alternative Food Sources
Artificial Meat Market
Alternative Food Sources
Vegan Sashimi Market
Alternative Food Sources
Insect Protein Market
Alternative Food Sources
Fungal Protein Market