
 Fishless Fillets Market | 2026-2036
Fishless Fillets Market Size, Share, and Industry Trends Forecast 2026-2036
Fishless Fillets Market Foresight
Pea protein isolate is repositioning fishless fillet formulations away from soy-dominant recipes, improving texture benchmarks and reducing allergen exposure. Beyond Meat leverages extrusion technology leadership to anchor its emerging seafood pipeline. Impossible Foods sustains heme-protein R&D intensity as it navigates plant-based fish replication. Good Catch Foods dominates algae-and-legume hybrid formulations, occupying a distinct premium tier in North American retail channels.
Fishless fillets are plant-derived or cultivated protein strips engineered to replicate the flaky texture, moisture retention, and nutritional profile of conventional finfish, typically achieving 15-20 grams of protein per 100-gram serving through extrusion or shear-cell processing. Their primary commercial purpose is to substitute wild-caught and aquaculture fish in prepared meals, reducing pressure on depleted marine stocks while satisfying flexitarian dietary migration. Soy-based and pea protein categories lead current production volume, though algae-derived formulations represent the fastest-expanding margin pool due to superior omega-3 fatty acid integration and shorter ingredient lists. The food service application channel controls the largest revenue share as institutional buyers consolidate procurement around standardized plant-based seafood SKUs.
The FDA governs novel protein safety assessments and GRAS determinations for fermented and precision-fermentation inputs entering U.S. fishless fillet supply chains. The EU EFSA evaluates algae-derived novel food applications under consolidated pre-market authorization pathways, while REACH compliance shapes additive and binder selections for European manufacturers. Stakeholders must monitor evolving nomenclature standards that distinguish cell-cultured from plant-based fillets, as regulatory classification will determine labeling privileges and retail placement access across jurisdictions.
Market Dynamics
Algae protein fermentation is redirecting capital flows away from soy-extrusion infrastructure, compressing R&D timelines and reconfiguring supplier hierarchies across alternative seafood value chains.
Growth Catalysts
- EU Green Deal protein diversification targets:The European Commission's Farm to Fork Strategy mandates 25% organic farming coverage and accelerates novel food approvals, creating procurement pull from institutional food service buyers in Germany and the Netherlands.
- Quick-service restaurant chain menu expansion:North American fast-casual operators are consolidating plant-based seafood SKUs into permanent offerings, standardizing specifications that upstream suppliers must meet.
- Shear-cell processing maturation:This extrusion alternative achieves muscle-fiber alignment without high-temperature denaturation, enabling cleaner-label formulations with shorter ingredient lists.
Market Restraints
- Pea protein input cost volatility:Yellow pea concentrate prices fluctuate with North American crop yields, squeezing margin structures for mid-tier fillet producers dependent on single-source supply contracts.
- Fermentation capacity concentration:Precision-fermentation infrastructure clusters in Denmark and Singapore, creating geographic chokepoints for algae-derived protein scaling.
- GRAS determination timelines:FDA novel protein safety assessments average 18-24 months, delaying market entry for innovators using non-traditional microbial hosts.
Strategic Opportunities
- Underpenetrated Japanese retail channels:Domestic consumers exhibit high seafood consumption frequency but limited exposure to plant-based alternatives, presenting first-mover positioning for texture-optimized formulations.
- Cell-cultured hybrid products:Convergence of plant-based scaffolding with cultivated fish fat creates premium tier differentiation, commanding shelf space in specialty grocers.
- USDA BioPreferred program procurement mandates:Federal food service contracts increasingly require biobased content verification, advantaging domestic manufacturers with certified supply chains.
Industry Challenges
- Food technologist talent scarcity:Formulation expertise spanning protein chemistry, flavor masking, and texture engineering concentrates in legacy meat-alternative companies, constraining new entrant R&D velocity.
- Dual-labeling complexity:Distinguishing plant-based from cell-cultured fillets requires navigation of evolving FDA and EFSA nomenclature standards, complicating packaging design and retail placement negotiations.
- Cold-chain reconfiguration costs:Frozen fillet distribution demands temperature-controlled infrastructure distinct from ambient plant-protein logistics, forcing capital deployment in logistics partnerships or owned distribution assets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fishless Fillets Market |
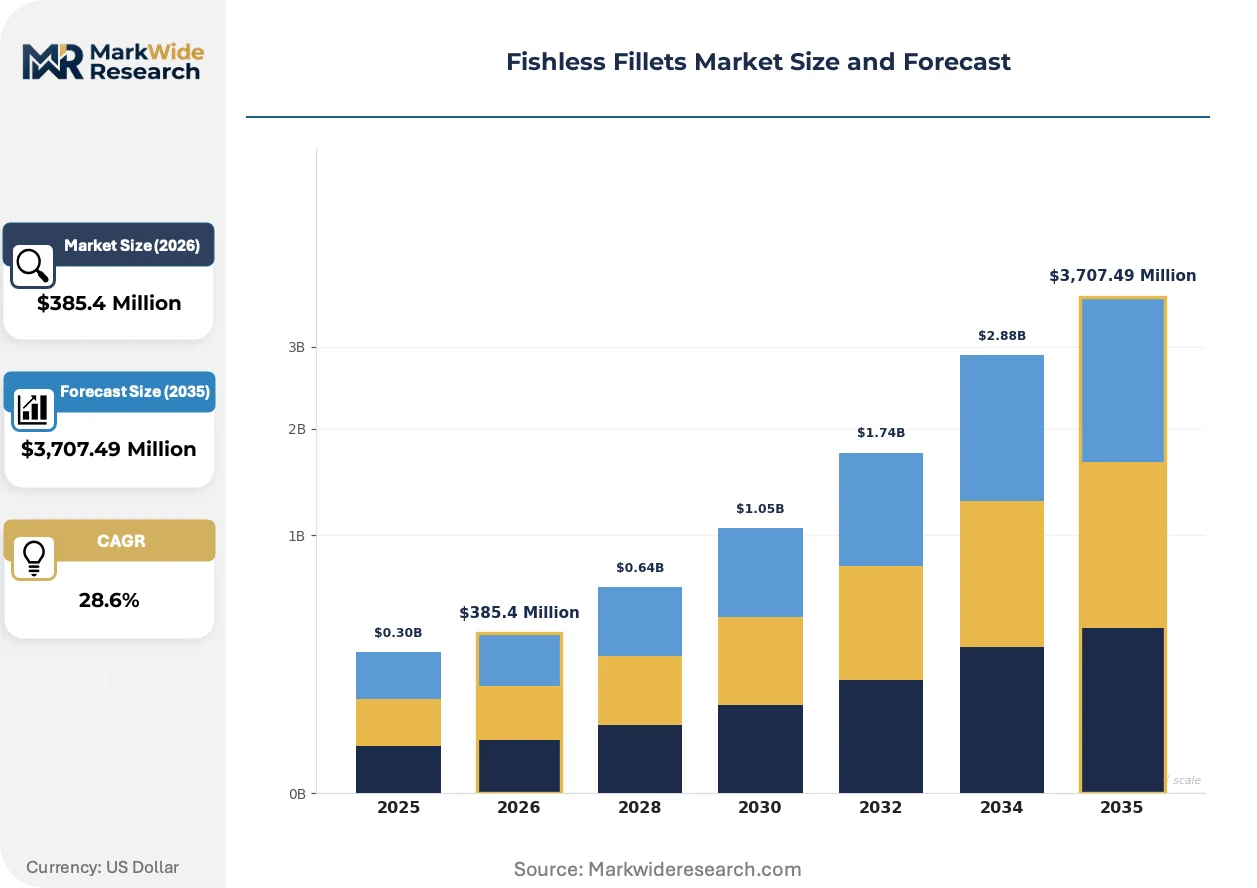
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $3,707.49 Million |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
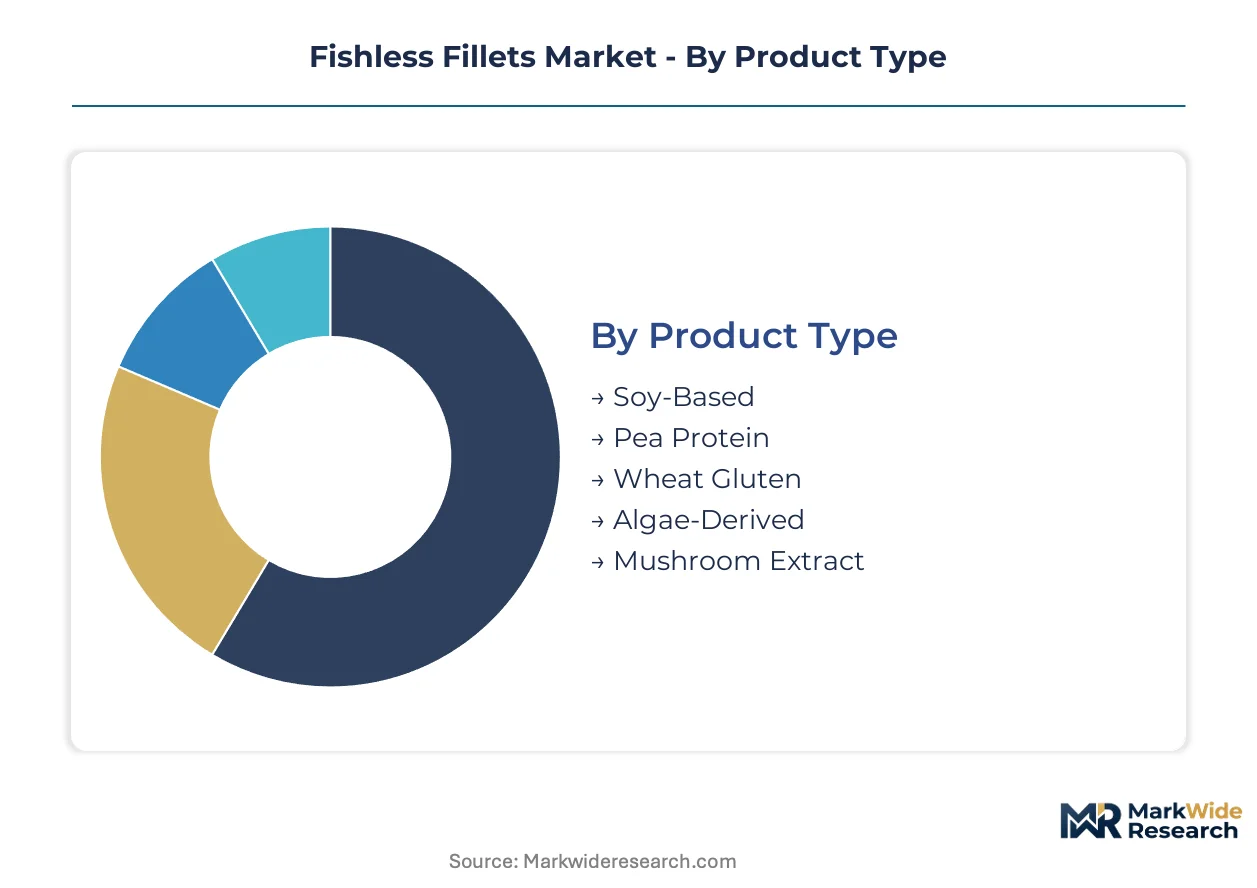
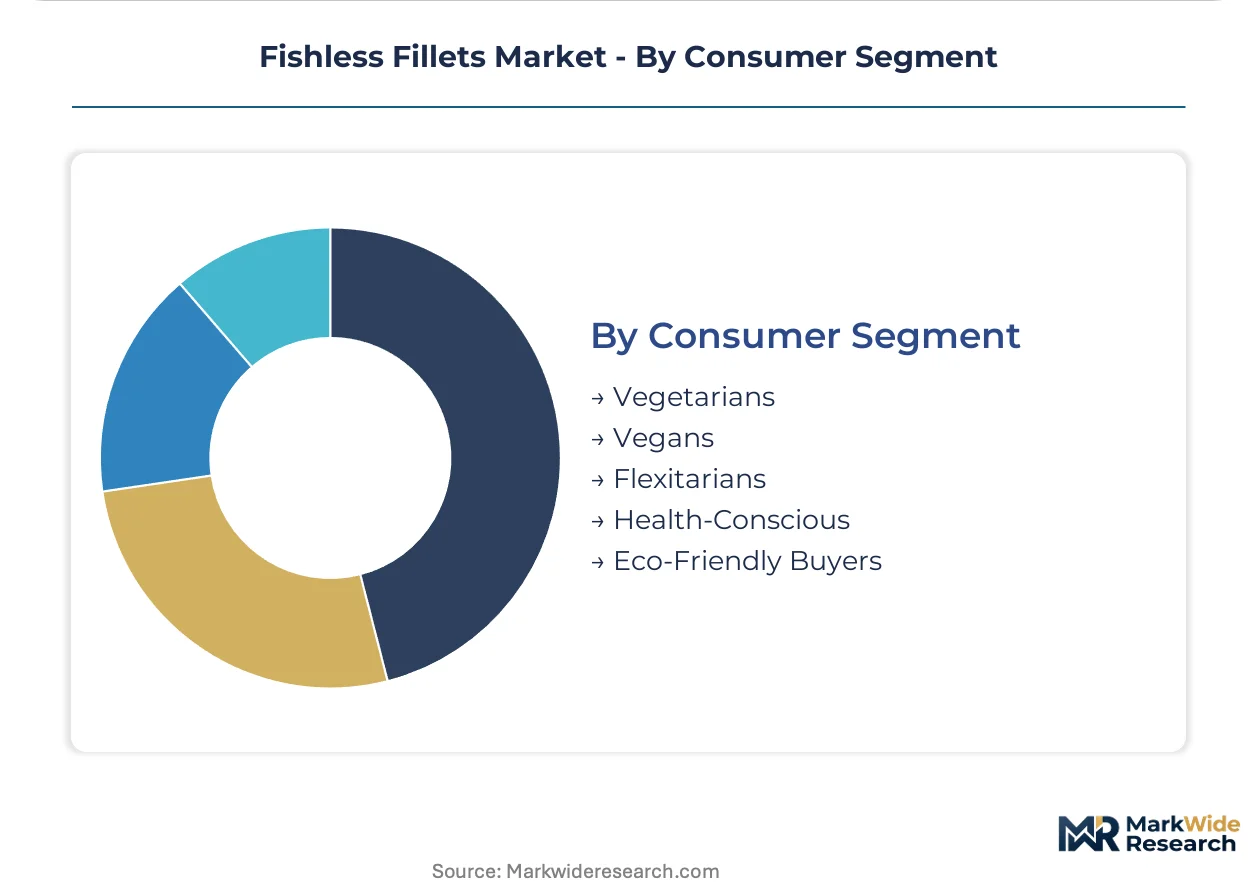
| Segmentation | Product Type: Soy-Based, Pea Protein, Wheat Gluten, Algae-Derived, Mushroom Extract Application: Food Service, Retail, Frozen Meals, Ready-to-Eat Snacks, Catering Packaging Type: Vacuum Sealed, Tray Packaging, Boxed, Bulk Packaging, Sachets Consumer Segment: Vegetarians, Vegans, Flexitarians, Health-Conscious, Eco-Friendly Buyers |
| Companies Covered | Impossible Foods, Beyond Meat, Quorn, Good Catch Foods, The Vegetarian Butcher, Gardein, MorningStar Farms, Ocean Hugger Foods, Birds Eye, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fishless Fillets Market Shifts & Advancements
Extrusion technology dominance faces disruption from biological processing methods, while regulatory classification battles and procurement centralization reshape competitive access to institutional buyers.
Algae-derived protein concentrates are overtaking soy isolate as the functional base for premium fillet formulations. North American retail buyers now specify minimum omega-3 content thresholds that only marine-sourced inputs reliably satisfy. This ingredient rotation is compressing R&D timelines for legacy suppliers anchored to legume-dominant recipes.
REACH compliance revisions for novel food contact substances are tightening binder and additive selections available to European manufacturers. EFSA pre-market authorization pathways for fermented proteins now require extended toxicology dossiers, extending product development cycles by 12-18 months. German and Dutch producers are responding by consolidating formulation expertise in-house rather than relying on external ingredient houses.
Food service procurement has consolidated around standardized SKU specifications, displacing the fragmented direct-store-delivery model that characterized early market development. Broadline distributors including Sysco and US Foods now control category placement decisions for K-12 and healthcare accounts. This channel concentration is most visible in California and New York, where institutional buyers mandate third-party sustainability certification as a contract prerequisite.
Fishless Fillets Market Segmentation
Fishless fillet producers face divergent formulation requirements across institutional buyers, retail channels, and consumer dietary profiles. Supply chain configuration and procurement specifications vary sharply between these endpoints, forcing manufacturers to maintain parallel production lines.
Product Type:
Ingredient sourcing concentrates around North American yellow pea cultivation zones and North Atlantic algae fermentation clusters, with protein extraction infrastructure determining regional production basins.
- Soy-Based:The legacy standard relies on isolated soy protein with textured vegetable protein binders. German and Dutch food service buyers specify soy-dominant formulations for cost-sensitive institutional contracts, though allergen labeling requirements compress margin structures.
- Pea Protein:Yellow pea isolate achieves superior texture benchmarks through high-moisture extrusion. California and New York retail channels specify pea-dominant recipes for cleaner-label positioning, with crop yield volatility in Canada and France creating input cost pressure.
- Wheat Gluten:Seitan-derived formulations offer chew resistance suited to battered applications. Limited commercial scale outside Japanese and Korean manufacturing.
- Algae-Derived:Fermented microalgae concentrates deliver EPA/DHA integration without marine sourcing. Danish and Singaporean bioreactor capacity constrains volume scaling.
- Mushroom Extract:Mycelium scaffolding provides fibrous texture through solid-state fermentation. Emerging production in Netherlands pilot facilities.
Soy-based formulations absorb the bulk of installed capacity; algae-derived products are expanding most quickly.
Application:
Channel requirements diverge on temperature stability, portion standardization, and sustainability certification thresholds, with institutional buyers imposing stricter compliance burdens than retail.
- Food Service:Broadline distributors consolidate procurement around frozen, individually quick-frozen fillets with specified protein content and cook-loss ratios. Sysco and US Foods mandate third-party sustainability certification for K-12 and healthcare accounts in California and New York.
- Retail:Grocery buyers prioritize refrigerated, vacuum-sealed formats with shorter ingredient lists. German and UK supermarkets specify minimum omega-3 content thresholds that algae-derived formulations satisfy.
- Frozen Meals:Prepared dish manufacturers require sauce-stable fillets resistant to freeze-thaw degradation. Limited supplier base due to specialized texture retention specifications.
- Ready-to-Eat Snacks:Shelf-stable, battered strips for convenience positioning. Emerging demand in Japanese convenience store channels.
- Catering:Bulk, cook-and-hold formats for event service. Price-sensitive segment with minimal premium positioning.
Food service commands the dominant procurement volume; retail channels are climbing the fastest.
Packaging Type:
Packaging selection tracks distribution temperature requirements and retail placement economics, with cold-chain infrastructure costs favoring certain formats in specific geographies.
- Vacuum Sealed:Modified atmosphere packaging extends refrigerated shelf life for premium retail placement. German and Dutch supermarket chains mandate recyclable film specifications.
- Tray Packaging:MAP trays with peelable film dominate frozen retail sets. Standardized dimensions for vertical freezer case efficiency.
- Boxed:Corrugated retail cases for multi-unit frozen meal kits. UK meal-kit subscription services specify FSC-certified board.
- Bulk Packaging:Food service totes for institutional procurement. California school district contracts require tamper-evident seals.
- Sachets:Single-serve portions for airline and hospitality sampling. Limited volume, high unit economics.
Vacuum sealed absorbs the bulk of installed capacity; tray packaging is expanding most quickly.
Consumer Segment:
Dietary identity shapes price tolerance and ingredient scrutiny, with flexitarian consumers representing the volume opportunity and vegan consumers driving premium tier innovation.
- Flexitarians:Occasional meat reducers seeking familiar taste at parity pricing. UK and German retail data show highest repeat purchase rates for pea-algae hybrid formulations.
- Vegans:Strict exclusion criteria demand certified animal-free supply chains. Willingness to pay premium for algae-derived omega-3 integration.
- Vegetarians:Lacto-ovo dietary framework accepts egg-white binders, expanding formulation options. Mature segment with stable demand.
- Health-Conscious:Protein-seeking consumers comparing nutrition panels to conventional fish. New York and California urban demographics.
- Eco-Friendly Buyers:Sustainability-motivated purchasers prioritizing carbon footprint claims. German market shows strongest certification responsiveness.
Flexitarian consumers absorb the bulk of addressable volume; health-conscious buyers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for fishless fillets concentrates in Germany, the United Kingdom, and the Netherlands within Europe, alongside California and New York in the United States, where institutional procurement and retail channel expansion are accelerating most rapidly.
Germany
Institutional food service buyers in Germany drive volume through EU Green Deal procurement mandates, with school districts and healthcare systems consolidating plant-based seafood SKUs. EFSA novel food authorization pathways govern algae-derived protein market entry. Berlin-Brandenburg hosts fermentation infrastructure clusters where precision-fermentation capacity is scaling for alternative protein inputs.
United Kingdom
UK retail channels specify minimum omega-3 content thresholds that favor algae-derived formulations, with supermarket chains demanding recyclable packaging specifications. REACH compliance revisions tighten binder selections for domestic manufacturers. London and the Southeast concentrate R&D activity where shear-cell processing pilot facilities are advancing texture-engineering capabilities.
Netherlands
Dutch food service buyers impose third-party sustainability certification as a contract prerequisite for institutional accounts, creating procurement pull for certified supply chains. EU Farm to Fork Strategy targets accelerate novel food approvals domestically. The Randstad region anchors solid-state fermentation pilot facilities where mycelium scaffolding production is emerging.
United States
California and New York institutional buyers mandate biobased content verification through USDA BioPreferred program requirements, advantaging domestic manufacturers with certified supply chains. FDA GRAS determinations for novel proteins average 18-24 months, delaying market entry. The Pacific Northwest concentrates extrusion technology infrastructure where high-moisture extrusion capacity serves West Coast retail distribution.
Denmark
Danish bioreactor capacity constrains volume scaling for algae-derived protein concentrates serving premium fillet formulations across Northern European markets. EFSA pre-market authorization requirements shape domestic regulatory strategy. Copenhagen anchors precision-fermentation infrastructure clusters where microbial host development is advancing for alternative seafood protein inputs.
Fishless Fillets Market Competitive Landscape
Portfolio diversification dominates the current landscape as incumbent protein houses and alternative seafood specialists reposition formulation expertise across plant-based and hybrid platforms. The vendor base stratifies between diversified conglomerates with extrusion infrastructure, pure-play alternative seafood developers with algae-fermentation capabilities, and emerging cell-cultured hybrid innovators. Three archetypes define competitive positioning: legacy meat-alternative extenders leveraging extrusion technology leadership, algae-protein specialists commanding premium omega-3 positioning, and cultivated-seafood convergents developing hybrid scaffolding systems. Capacity expansion in fermentation infrastructure and strategic partnerships with broadline distributors represent the dominant competitive moves reshaping market access.
Within the diversified protein house tier, Beyond Meat and Impossible Foods exemplify extrusion-technology anchoring as they extend platform capabilities into seafood replication, while Good Catch Foods occupies a distinct premium position representing algae-and-legume hybrid formulation specialization. These three companies illustrate the competitive spectrum from scale-driven infrastructure leverage to ingredient-innovation differentiation, with each archetype facing distinct capital requirements and regulatory pathway timelines for market expansion.
| Leading Market Players |
|---|
| Impossible Foods |
| Beyond Meat |
| Quorn |
| Good Catch Foods |
| The Vegetarian Butcher |
| Gardein |
| MorningStar Farms |
| Ocean Hugger Foods |
| Birds Eye |
| Others |
Supply & Pricing Matrix
Backward integration into algae fermentation infrastructure anchors supply positioning and pricing power for premium tier producers, while arm's-length sourcing from North American pea protein processors leaves mid-tier fillet manufacturers exposed to input cost volatility and compressed margin structures.
Pricing Analysis
Volume concentrates in economy-tier soy-based formulations serving German and Dutch institutional food service contracts, while margin pools accrue to premium algae-derived products commanding shelf space in UK and California retail channels. Price differentiation hinges on omega-3 certification thresholds and third-party sustainability credentials, with German supermarket chains mandating recyclable packaging specifications that add cost. Cost compression in the mid-tier is intensifying because yellow pea concentrate prices fluctuate with Canadian crop yields. Institutional buyers in K-12 and healthcare segments exhibit highest price sensitivity, while vegan consumers seeking certified animal-free supply chains show least elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Danish and Singaporean precision-fermentation infrastructure for algae-derived protein concentrates, constraining volume scaling for premium fillet formulations. Geographic supply concentration centers on Canada and France for yellow pea cultivation, China for textured vegetable protein binders, and the Netherlands for mycelium scaffolding pilot production. Raw material dependencies rest on marine-sourced omega-3 inputs, high-moisture extrusion equipment, and modified atmosphere packaging films. Tariff exposure on imported fermentation capacity creates supply chain risk. Distribution runs through broadline distributors including Sysco and US Foods consolidating procurement for North American institutional accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a consolidation play where fermentation capacity scarcity and extended FDA GRAS timelines will force capital-constrained formulators toward acquisition or exit.
For Market Incumbents: Cement technology leadership by acquiring Danish or Singaporean precision-fermentation assets to secure captive algae protein supply, while locking in multi-year offtake contracts with broadline distributors to defend channel access against emerging cell-cultured hybrid competitors. For New Entrants and Emerging Players: Launch via direct-to-food-service distribution targeting underpenetrated Japanese institutional buyers, where limited plant-based seafood exposure and high conventional fish consumption frequency create first-mover positioning for texture-optimized formulations. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified protein houses seeking algae-fermentation capabilities; over the projection horizon, viable acquisition targets will demonstrate EFSA pre-market authorization progress and secured bioreactor capacity. The signal to watch is FDA GRAS determination acceleration for novel microbial hosts, which would compress regulatory timelines and revalue the competitive set.| Strategic Initiative | Industry Significance |
|---|---|
| Precision-Fermentation Capacity Expansion | Danish bioreactor infrastructure secures algae protein supply for premium omega-3 positioning. |
| Shear-Cell Processing Pilot Investment | London R&D facilities advance muscle-fiber alignment without high-temperature denaturation. |
| Broadline Distributor Partnership | Sysco and US Foods consolidation mandates third-party sustainability certification for category placement. |
| EFSA Pre-Market Authorization Pathway | Extended toxicology dossiers for fermented proteins determine European market entry timing. |
| USDA BioPreferred Certification | Federal food service contracts in California and New York require biobased content verification. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with food technology R&D directors, broadline distributor category managers, institutional procurement officers at K-12 and healthcare systems, and regulatory affairs leads navigating FDA GRAS and EFSA novel food pathways. Bottom-up volume modeling triangulated against top-down protein substitution trend analysis.
Segment-level granularity modeled protein source, application channel, packaging format, and consumer dietary identity across the analysis window, with CAGRs derived from elasticity-adjusted adoption curves and input cost trajectory assumptions. Industry-specific forecast inputs incorporated EU Farm to Fork procurement mandate implementation pace and algae fermentation yield improvement curves.
The model assumes a particular technology adoption path; alternative pathways for cell-cultured hybrid scaffolding would alter the outlook if regulatory classification accelerates or consumer acceptance outpaces plant-based formulation maturation. Forecasts reflect assumptions about institutional buyer consolidation and fermentation capacity scaling that industry-specific risk factors could revise. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
South American Algae Protein Market
Alternative Food Sources
Global Algal Oil Market
Alternative Food Sources
Fish Meal Alternative Market
Alternative Food Sources
Food Cultures Market
Alternative Food Sources
Pet Food Microalgae Market
Alternative Food Sources
Teff Products Market
Alternative Food Sources
Paleo Food Market
Alternative Food Sources
Gluten Replacer Market
Alternative Food Sources
Soy Leghemoglobin Market
Alternative Food Sources
Europe Upcycled Food Products Market
Alternative Food Sources
Monoprotein Market
Alternative Food Sources
Europe Emergency Food Market
Alternative Food Sources
North America Edible Insects Market
Alternative Food Sources
Global Meal Replacement Shakes Market
Alternative Food Sources
Insect-Based Pet Food Market
Alternative Food Sources
Mushroom Protein Market