
 Electrosurgery Devices Market | 2026-2036
Electrosurgery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Electrosurgery Devices Market Intelligence
German electrosurgical instrument manufacturers are expanding production capacity for precision energy platforms. Medtronic leverages integrated energy systems to sustain leadership across open and minimally invasive procedures. Johnson & Johnson anchors its position through broad surgical portfolio breadth spanning monopolar and bipolar modalities. B. Braun Melsungen AG competes on specialized generator technology for high-frequency surgical applications.
Electrosurgery devices employ high-frequency electrical current to cut, coagulate, or desiccate tissue during surgical procedures, typically operating at frequencies between 300 kHz and 3 MHz to avoid neuromuscular stimulation while generating localized thermal energy. These systems serve as foundational tools across general surgery, gynecology, urology, and cosmetic procedures where precise tissue management reduces operative blood loss and improves recovery trajectories. Bipolar devices command premium positioning in delicate surgical environments where thermal spread must be minimized, while radiofrequency technology dominates installed base volumes due to proven reliability and lower capital requirements. Monopolar systems retain substantial share in high-volume abdominal and thoracic procedures where speed and cost efficiency outweigh precision demands.
FDA 510(k) clearance pathways and EU MDR conformity assessments impose rigorous biocompatibility and electrical safety validation requirements that extend development timelines and elevate compliance costs for manufacturers. ISO 13485 quality management standards and IEC 60601-1-2 electromagnetic compatibility directives further constrain design flexibility while ensuring patient safety across international markets. Stakeholders must monitor evolving energy delivery modalities and regulatory harmonization efforts to align R&D investments with forthcoming compliance obligations.
Market Dynamics
EU MDR compliance timelines are compressing product development cycles across electrosurgery device portfolios, forcing manufacturers to front-load biocompatibility validation and electrical safety testing before design finalization.
Growth Catalysts
- Minimally invasive procedure volume:Laparoscopic and robotic-assisted surgery expansion in tertiary hospitals drives recurring demand for disposable electrosurgical accessories and specialized handpieces.
- EU MDR Article 117:Stricter clinical evidence requirements for Class IIb and III devices accelerate replacement of legacy systems with validated next-generation platforms.
- Ambulatory surgical center buildout:United States outpatient facility construction concentrates capital equipment procurement in compact, multi-modality generator systems.
Market Restraints
- Copper and silver price volatility:Electrode and cable raw material cost swings compress gross margins for manufacturers lacking forward commodity hedging.
- Generator supply concentration:Precision high-frequency power electronics production clusters in Germany and Japan, creating geographic vulnerability to component shortages.
- Thermal spread limitations:Monopolar systems face substitution pressure from advanced bipolar and ultrasonic alternatives in delicate tissue applications.
Strategic Opportunities
- India surgical infrastructure:Government hospital modernization programs under Ayushman Bharat create first-time equipment demand in tier-2 and tier-3 cities.
- AI-integrated smoke evacuation:Convergence of computer vision and electrosurgical systems enables real-time plume detection and automatic suction activation.
- Direct-to-hospital digital procurement:Manufacturer e-commerce platforms bypass distributor markups in price-sensitive European markets.
Industry Challenges
- Biomedical engineering talent scarcity:Specialized expertise in high-frequency circuit design and thermal modeling commands premium compensation, constraining R&D team scaling.
- ISO 13485 certification timeline:Quality management system audits and technical documentation reviews extend time-to-market by 12-18 months for novel energy delivery modalities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrosurgery Devices Market |
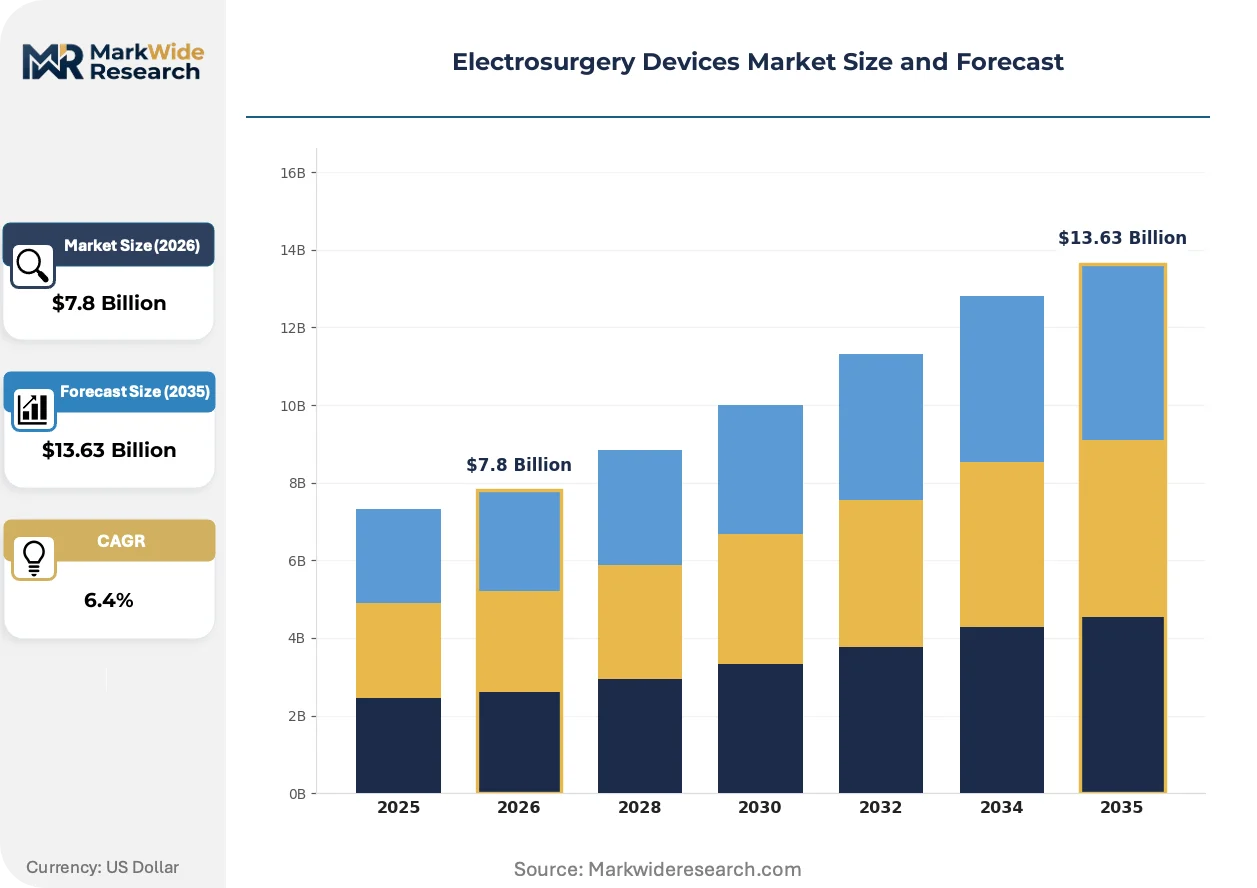
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Return Electrodes, Monopolar Devices, Bipolar Devices, Accessories End User: Hospitals, Ambulatory Surgical Centers, Clinics, Research Institutes Application: General Surgery, Gynecological Surgery, Urological Surgery, Cosmetic Surgery Technology: Radiofrequency, Microprocessor-Controlled, Laser-Assisted, Plasma-Based |
| Companies Covered | B. Braun Melsungen AG, Boston Scientific Corporation, Medtronic, BOWA-electronic GmbH & Co. KG, Erbe Elektromedizin GmbH, Johnson & Johnson, CONMED Corporation, Apyx Medical Corporation, Olympus Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrosurgery Devices Market Strategic Shifts & Innovations
Intelligent energy modulation and connected surgical platforms are redefining how tissue interaction is monitored and controlled, shifting competitive advantage toward software-enabled differentiation.
Impedance-sensing generators with real-time tissue feedback loops are automating power adjustment during cutting and coagulation cycles. Academic medical centers in the United States and Germany are piloting these systems for complex oncologic resections. This capability is automating surgeon-dependent technique variation and reducing unintended thermal injury rates.
EU MDR Annex XIV clinical evaluation requirements are mandating post-market surveillance infrastructure that manufacturers previously treated as optional. Device registries and patient follow-up obligations now consume substantial quality assurance resources. High-volume disposable electrode producers face disproportionate documentation burdens relative to capital equipment specialists.
Hospital procurement departments are consolidating vendor relationships through integrated operating room contracts that bundle electrosurgery with insufflation, irrigation, and visualization systems. Independent distributors lose access as manufacturers deploy direct sales engineers for multi-year service agreements. This concentration is most advanced in German university hospital networks and United States IDN structures.
Electrosurgery Devices Market Segmentation
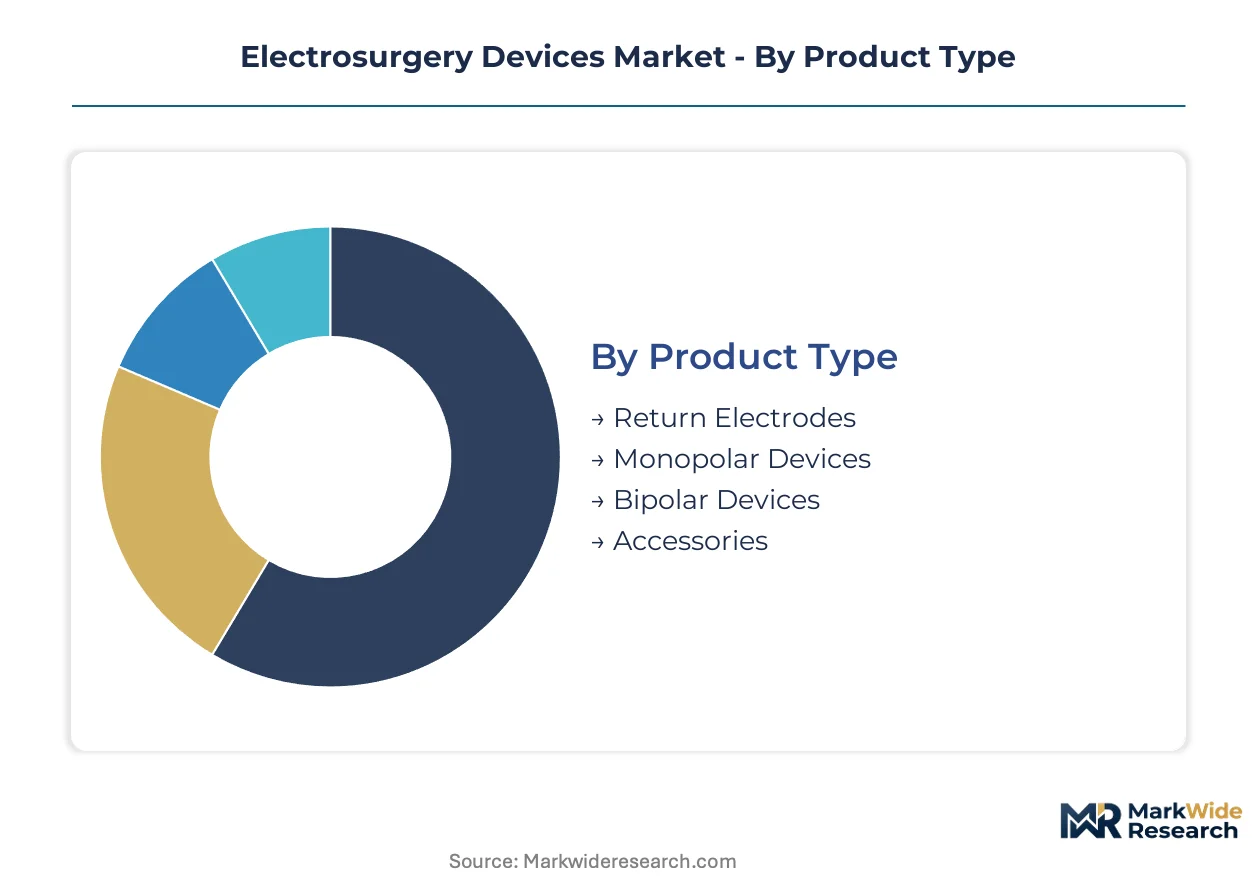
Electrosurgery device purchasing decisions pivot on surgical setting requirements, procedure complexity, and capital versus disposable economics. Segmentation reveals distinct technology preferences across acute care hospitals versus outpatient facilities, with generator modality and electrode configuration driving contract value.
Product Type:
Procurement teams prioritize capital equipment lifecycle costs against recurring disposable spend when selecting product configurations.
- Monopolar Devices:These systems utilize a single active electrode with a remote return pad, delivering high-frequency current through the patient's body to cut and coagulate tissue. United States hospitals favor monopolar platforms for high-volume abdominal procedures where speed outweighs precision requirements. Thermal spread limitations constrain adoption in delicate neurosurgical environments.
- Bipolar Devices:Current flows between two closely spaced electrodes at the instrument tip, confining thermal effect to targeted tissue. German university hospitals command premium pricing for these systems in microsurgical applications where collateral damage risks are unacceptable. EU MDR biocompatibility testing elevates entry barriers for disposable bipolar forceps manufacturers.
- Return Electrodes:Dispersive pads complete the electrical circuit in monopolar configurations, with adhesive gel technologies dominating standard procedures.
- Accessories:Footswitches, cables, and adapters generate recurring revenue streams tied to generator installed base.
Volume sits with Monopolar Devices; growth tilts toward Bipolar Devices.
End User:
Facility reimbursement structures and case volume thresholds determine equipment sophistication tiers.
- Hospitals:Tertiary medical centers in the United States and Germany anchor demand for multi-modality generators supporting both open and laparoscopic workflows. Integrated operating room contracts bundle electrosurgery with visualization and insufflation systems, consolidating vendor relationships.
- Ambulatory Surgical Centers:Outpatient facilities in the United States prioritize compact, portable generators with rapid setup protocols. Medicare reimbursement shifts toward site-neutral payments accelerate ASC capital equipment procurement.
- Clinics:Dermatology and minor procedure clinics favor lower-power radiofrequency units for limited intervention scope.
- Research Institutes:Academic laboratories in Germany and China purchase specialized generators for preclinical energy delivery studies.
Procurement concentrates in Hospitals; Ambulatory Surgical Centers are expanding most quickly.
Application:
Procedure-specific thermal requirements and tissue characteristics dictate modality selection.
- General Surgery:Abdominal wall entry, solid organ resection, and hemostasis across diverse tissue types. United States hospital networks standardize on monopolar pencils for appendectomy and cholecystectomy volume.
- Gynecological Surgery:Hysterectomy and myomectomy procedures demand precise thermal control near bowel and bladder. Bipolar vessel sealing systems command premium positioning in laparoscopic gynecology suites.
- Urological Surgery:Transurethral resection and nephrectomy applications favor plasma vaporization for reduced bleeding.
- Cosmetic Surgery:Dermatological resurfacing and minor aesthetic procedures utilize lower-power radiofrequency modalities.
General Surgery generates the highest procedure volume; Gynecological Surgery shows steepest technology upgrade rates.
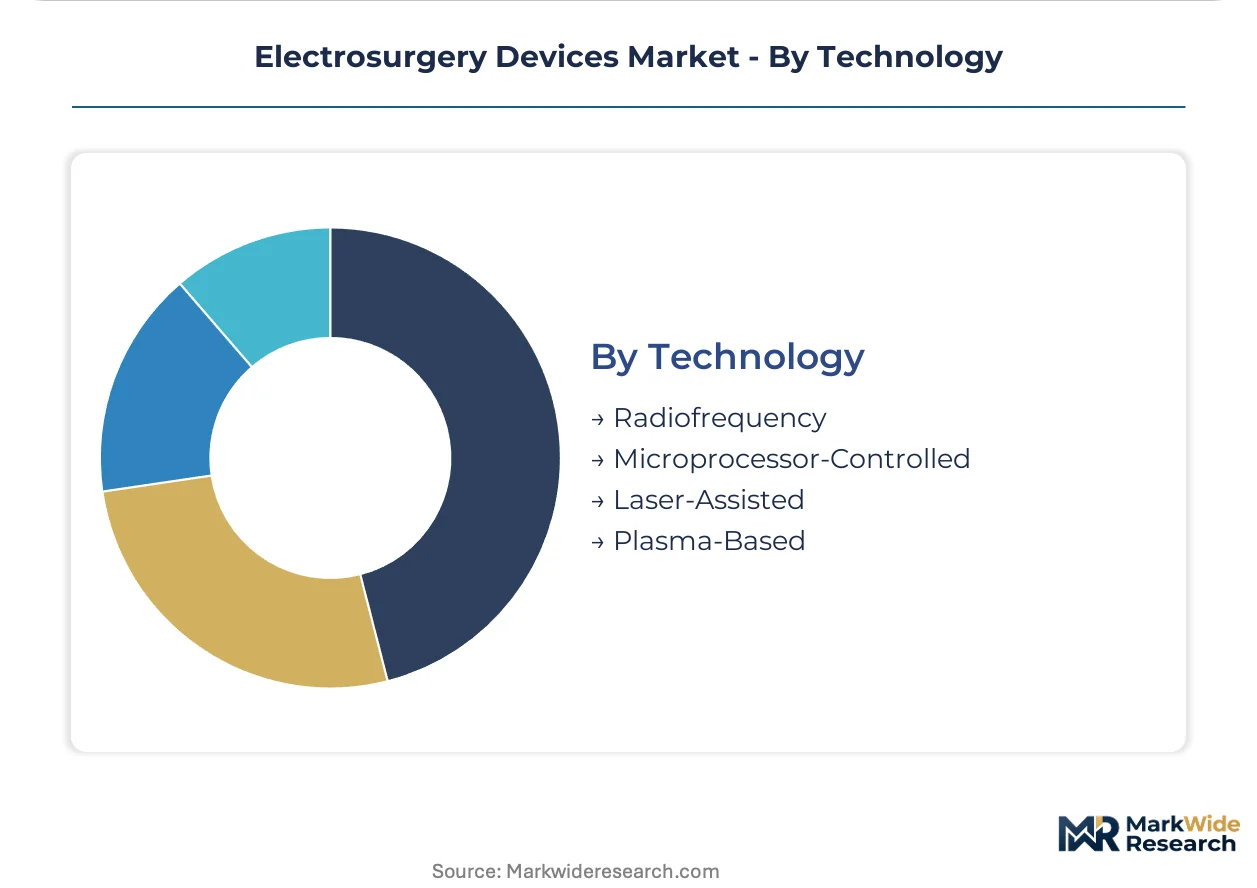
Technology:
Generator architecture sophistication separates commodity positioning from premium pricing tiers.
- Radiofrequency:Conventional fixed-frequency generators dominate installed base volumes due to proven reliability and lower capital requirements. German manufacturers maintain production concentration for precision high-frequency power electronics.
- Microprocessor-Controlled:Impedance-sensing algorithms automate power modulation based on real-time tissue feedback. Academic medical centers in the United States pilot these systems for complex oncologic resections.
- Laser-Assisted:Selective tissue ablation with minimal thermal spread for ophthalmic and dermatological applications.
- Plasma-Based:Argon beam coagulation enables non-contact hemostasis in diffuse bleeding scenarios.
Radiofrequency maintains the largest installed base; Microprocessor-Controlled platforms are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision engineering clusters supply critical high-frequency power electronics to generator manufacturers worldwide. Copper electrode fabrication concentrates in Chinese industrial zones serving cost-sensitive disposable markets. Japanese semiconductor foundries produce specialized components for impedance-sensing control systems.
United States
Tertiary hospital networks in Texas and California drive demand for multi-modality surgical platforms. FDA 510(k) clearance pathways shape product development timelines for domestic manufacturers. Minneapolis and Boston anchor medical device R&D clusters where integrated energy systems undergo clinical validation.
Germany
University hospital procurement in Bavaria and North Rhine-Westphalia commands premium pricing for precision bipolar instruments. EU MDR conformity assessments extend certification cycles for Class IIb electrosurgical devices. Tuttlingen and Melsungen host specialized manufacturing zones for high-frequency surgical generators.
China
Government hospital modernization under the 14th Five-Year Plan expands first-time equipment procurement in tier-2 cities. NMPA registration requirements for active medical devices elevate documentation burdens for imported systems. Shenzhen and Suzhou industrial parks scale production of radiofrequency electrodes for domestic consumption.
India
Ayushman Bharat health infrastructure investments create equipment demand in Maharashtra and Karnataka. CDSCO medical device rules mandate local testing for electrosurgical generators above specified power thresholds. Ahmedabad and Chennai emerge as distribution hubs for affordable monopolar accessories.
Japan
Aging demographics accelerate laparoscopic procedure volumes in Tokyo and Osaka metropolitan hospitals. PMDA quality management system inspections enforce rigorous post-market surveillance for energy delivery devices. Nagoya precision electronics suppliers manufacture control modules for next-generation impedance-sensing platforms.
Electrosurgery Devices Market Key Industry Players
Global majors compete with regional champions across regulatory compliance capabilities and service infrastructure. Market structure shows moderate consolidation with three to five integrated players commanding hospital procurement contracts, while specialized German and Japanese manufacturers occupy premium niches. Strategic archetypes span diversified conglomerates with broad surgical portfolios, pure-play energy specialists with generator expertise, and disposable electrode producers competing on manufacturing scale. Dominant competitive moves include backward integration into precision power electronics and direct-to-hospital digital procurement platforms that bypass traditional distribution.
Within the diversified conglomerate tier, Medtronic and Johnson & Johnson occupy positions exemplifying integrated surgical portfolio breadth across monopolar and bipolar modalities. Among German specialists, B. Braun Melsungen AG and Erbe Elektromedizin GmbH represent archetypes of precision generator technology and high-frequency surgical application expertise. These named entities anchor competitive dynamics without constraining the full market map, as regional champions in China and Japan plus emerging specialists in India complete the vendor landscape.
| Leading Market Players |
|---|
| B. Braun Melsungen AG |
| Boston Scientific Corporation |
| Medtronic |
| BOWA-electronic GmbH & Co. KG |
| Erbe Elektromedizin GmbH |
| Johnson & Johnson |
| CONMED Corporation |
| Apyx Medical Corporation |
| Olympus Corporation |
| Others |
Cost & Logistics Intelligence
EU MDR biocompatibility mandates gate qualified supply and premium-tier pricing access, forcing manufacturers to absorb elevated validation costs or forfeit hospital procurement contracts to certified competitors. German precision engineering clusters and Japanese semiconductor foundries anchor supply for impedance-sensing control modules, concentrating pricing power among vertically integrated generator specialists.
Pricing Analysis
Multi-year service agreements bundle generator hardware with preventive maintenance and software updates, while disposable electrodes trade on spot procurement with minimal after-sales attachment. Three-tier pricing structure across premium, standard, and economy levels separates microprocessor-controlled impedance-sensing platforms from conventional radiofrequency units and unbranded accessories. Cost compression in economy-tier disposable electrodes is intensifying because Chinese manufacturers scale copper electrode fabrication without forward commodity hedging. Ambulatory surgical centers exhibit highest price sensitivity due to Medicare site-neutral reimbursement pressures, whereas German university hospitals accept premium positioning for validated bipolar systems.
Supply Chain Analysis
India's CDSCO local-content rules for active medical devices above specified power thresholds are reshaping sourcing, compelling manufacturers to establish electrode assembly partnerships in Ahmedabad and Chennai. Precision high-frequency power electronics production clusters in Germany and Japan, while copper electrode fabrication concentrates in Chinese industrial zones serving cost-sensitive disposable markets. Generator supply chains draw from specialized semiconductor components produced in Nagoya precision electronics corridors. Single-source vulnerability in Japanese control module production creates geographic concentration risk. Distribution runs through direct-to-hospital digital procurement platforms that bypass traditional distributor markups in European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision biomedical engineering talent scarcity props pricing for validated electrosurgical platforms, as specialized high-frequency circuit design expertise commands premium compensation and constrains R&D team scaling across the competitive landscape.
For Market Incumbents: Hedge against ultrasonic and advanced bipolar substitution by accelerating impedance-sensing generator deployment in academic medical centers. Deepen backward integration into precision power electronics through captive supply agreements with Tuttlingen engineering clusters. Secure multi-year integrated operating room contracts that bundle electrosurgery with visualization systems to lock out independent distributors. For New Entrants and Emerging Players: Enter via tier-2 and tier-3 Indian cities under Ayushman Bharat hospital modernization, where first-time equipment demand outpaces established service infrastructure. Target affordable monopolar accessories for price-sensitive government procurement, leveraging Ahmedabad distribution hubs for CDSCO compliance. Pursue direct-to-hospital digital procurement platforms that bypass European distributor markups. For Investors and Strategic Acquirers: FDA 510(k) clearance for microprocessor-controlled platforms with real-time tissue feedback is the leading indicator that impedance-sensing automation is crossing from pilot to mainstream adoption. Long-term viability rests on software-enabled differentiation rather than commodity hardware scale. Acquisition targets should display specialized generator expertise with EU MDR conformity assessment completion. Watch for EU MDR Article 117 clinical evidence submission milestones as inflection signals for Class IIb device replacement cycles.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Conformity Assessment Completion | Article 117 clinical evidence requirements accelerate legacy system replacement with validated next-generation platforms. |
| Impedance-Sensing Generator Development | Real-time tissue feedback loops automate power adjustment and reduce thermal injury rates in complex oncologic resections. |
| Direct-to-Hospital Digital Procurement Platform | Manufacturer e-commerce bypasses distributor markups and captures price-sensitive European ambulatory surgical center demand. |
| Precision Power Electronics Backward Integration | Captive supply of high-frequency components from German engineering clusters insulates against Japanese semiconductor foundry concentration. |
| Hospital System Partnership for Integrated OR Contracts | Multi-year service agreements bundle electrosurgery with insufflation and visualization systems in United States IDN structures. |
Research Approach
FDA 510(k) clearance databases, EU MDR notified body conformity assessments, and hospital procurement contract registries formed the secondary backbone, supplemented by customs records tracking copper electrode trade flows and German engineering cluster production indices. Primary interviews with biomedical engineering directors, hospital purchasing committee chairs, GPO contracts managers, and electrosurgical device R&D leads validated demand assumptions and pricing dynamics. Bottom-up installed base modeling and top-down procedure volume triangulation anchored market size estimation across the analysis window.
Historical trendline analysis of radiofrequency generator shipments and disposable electrode consumption established baseline growth patterns. The projection framework modeled segmentation across product type, end user, application, and technology dimensions, with additional weighting for regulatory compliance tier and service bundling intensity. CAGRs derived from surgical procedure volume elasticity, capital equipment replacement cycles, and reimbursement policy shifts. Forecast inputs incorporated EU MDR implementation timelines and India Ayushman Bharat infrastructure investment trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under commodity price volatility in copper and silver markets, sudden EU MDR notified body capacity constraints, or geopolitical disruption to Japanese semiconductor component supply. Forecasts reflect assumptions documented in procedure volume projections and capital equipment penetration models. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Spinal Implant Market
Medical Devices
Nerve Monitoring Devices Market
Medical Devices
South Korea Aesthetic Devices Market
Medical Devices
North America Wheelchair Market
Medical Devices
Nonvascular Interventional Radiology Devices Market
Medical Devices
Global Artificial Organ and Bionic Implants Market
Medical Devices
MRI Coils Market
Medical Devices
Global Cardiopulmonary Resuscitation Device Market
Medical Devices
North America Medical Device Regulatory Affairs Outsourcing Market
Medical Devices
Saudi Arabia Artificial Organs and Bionic Implants Market
Medical Devices
Collateral Ligament Stabilizers Market
Medical Devices
Pressure Ulcer Detection Devices Market
Medical Devices
Global Cardiac Reader System Market
Medical Devices
Global Breast Surgery Retractors Market
Medical Devices
Interventional Oncology Devices Market
Medical Devices
United Arab Emirates Drug Delivery Devices Market