
 MRI Coils Market | 2026-2036
MRI Coils Market Size, Share, and Industry Trends Forecast 2026-2036
MRI Coils Market Analysis
Hospital procurement of MRI coils is shifting toward outpatient and research-oriented configurations as healthcare systems decentralize imaging services. Siemens Healthineers leverages its integrated magnet-coil-software ecosystem to sustain premium positioning across academic medical centers. GE Healthcare anchors North American replacement demand through its installed base of 1.5T and 3T systems. Philips Healthcare differentiates via multi-nuclear and digital coil architectures that compete on signal-to-noise performance.
MRI coils are radiofrequency antenna assemblies—typically wound from copper or aluminum conductors on polymer formers—that transmit excitation pulses and receive resonance signals from hydrogen nuclei in tissue, with operating frequencies scaling from approximately 64 MHz at 1.5T to 298 MHz at 7T depending on field strength. Their primary purpose is to optimize spatial coverage, sensitivity, and patient throughput across anatomically targeted imaging protocols. Head coils and spine coils command stable replacement volumes given their centrality to neuro and musculoskeletal diagnostics, while extremity coils represent a faster-growing segment as sports medicine and orthopedic outpatient volumes expand. Ultra-high-field technology above 7T occupies a narrow but high-margin niche concentrated at research institutes, whereas conventional and high-field platforms dominate hospital and diagnostic center procurement.
The FDA governs coil safety and electromagnetic compatibility through 510(k) premarket notification requirements, while the EU Medical Device Regulation mandates clinical evidence and post-market surveillance for CE-marked coils sold in Europe. ISO 13485 quality management standards shape manufacturing process controls and supplier qualification across all major production geographies. Stakeholders must monitor how evolving helium conservation regulations and superconducting magnet supply constraints influence coil-platform pairing decisions and long-term capital planning.
Market Dynamics
Helium conservation mandates and superconducting magnet supply constraints are forcing coil-platform pairing decisions toward longer capital cycles and consolidated vendor relationships across hospital procurement teams.
Growth Catalysts
- Outpatient imaging volume expansion:Diagnostic centers in the United States are adding dedicated MRI suites to capture shifted elective procedures from inpatient settings, driving coil configuration demand for high-throughput extremity and cardiac protocols.
- 510(k) clearance pathway efficiency:The FDA's streamlined premarket notification process for RF coil modifications accelerates product iteration cycles, enabling faster commercialization of anatomically specialized coil arrays.
- Ultra-high-field research infrastructure:Government-funded neuroscience institutes in Germany, Japan, and the United States are installing 7T and 9.4T systems, creating sustained demand for multi-channel transmit-receive arrays.
Market Restraints
- Copper and aluminum conductor volatility:Raw material price swings for coil winding substrates compress manufacturing margins and complicate long-term OEM contracting.
- Single-source superconducting wire dependence:Niobium-titanium filament supply concentrates among Japanese and European specialty metal producers, exposing coil-magnet system integrators to geopolitical disruption risk.
- Electromagnetic interference complexity:The EU Medical Device Regulation's tightened electromagnetic compatibility standards extend CE-marking timelines and raise compliance costs for multi-nuclear coil architectures.
Strategic Opportunities
- India diagnostic center buildout:The country's hospital procurement programs under Ayushman Bharat are funding MRI installations in tier-2 and tier-3 cities, creating first-mover advantage for coil suppliers establishing local service networks.
- Digital coil-native software integration:Convergence between AI-based image reconstruction algorithms and coil-integrated preamplifiers enables real-time adaptive signal processing that differentiates premium system offerings.
- Sports medicine clinic specialization:Dedicated orthopedic imaging centers in Australia and the United States are procuring compact extremity-dedicated coils that bypass full-body system scheduling constraints.
Industry Challenges
- RF engineer talent scarcity:Specialized expertise in high-frequency antenna design for 7T+ field strengths concentrates among academic research labs, constraining commercial R&D scaling.
- Legacy system backward compatibility:Coil manufacturers must maintain form-factor and software interface support for 10-15 year installed bases of 1.5T platforms, fragmenting engineering resources across generation-spanning product lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MRI Coils Market |
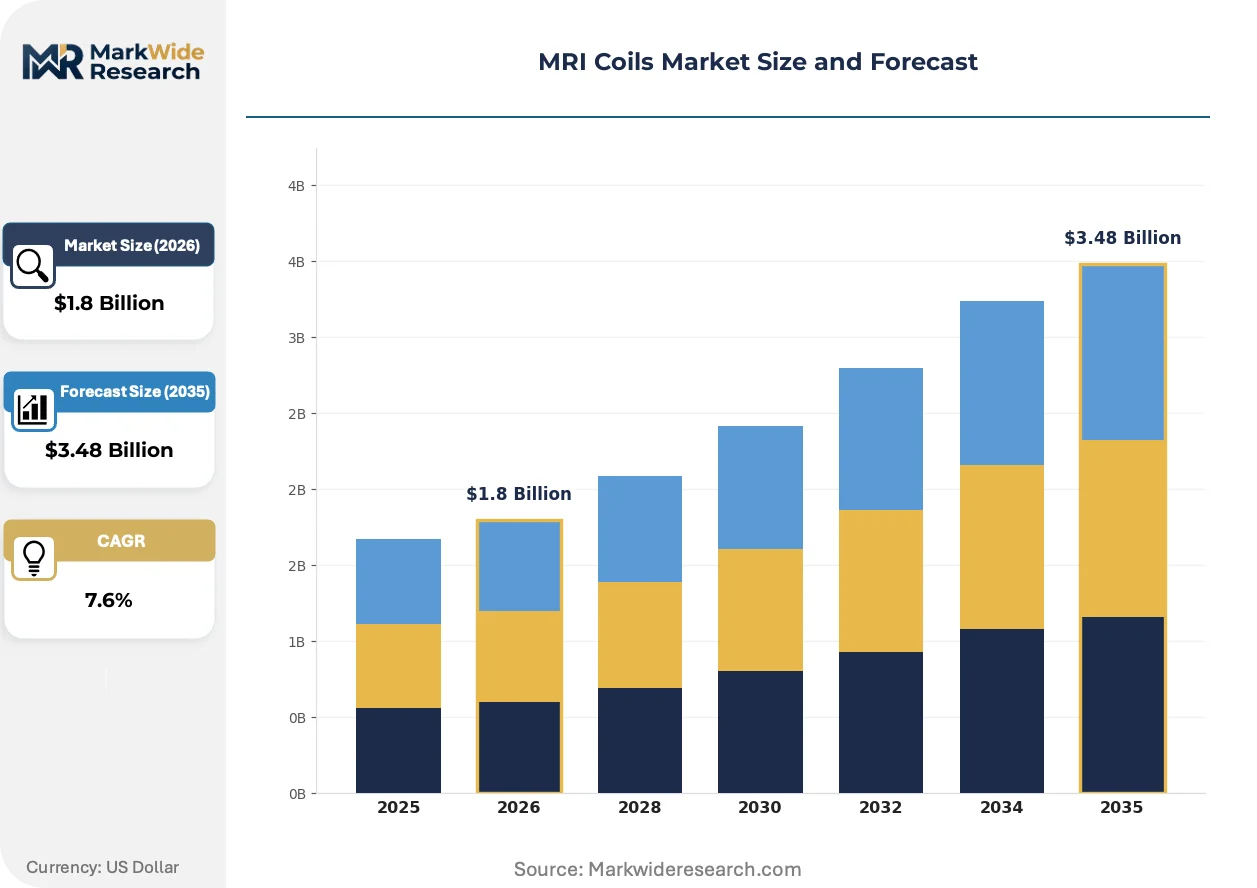
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.48 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Head Coils, Body Coils, Extremity Coils, Spine Coils Material: Silicone, Copper, Aluminum, Plastic End User: Hospitals, Diagnostic Centers, Research Institutes, Outpatient Facilities Technology: Conventional, High-Field, Ultra-High-Field, Open MRI |
| Companies Covered | Siemens Healthineers, GE Healthcare, Philips Healthcare, Canon Medical Systems, Shanghai United Imaging Healthcare, Hitachi Healthcare, Esaote SPA, ScanMed, Nova Medical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MRI Coils Market Emerging Trajectories
Digital integration between coil hardware and reconstruction software is compressing the traditional boundary between RF front-end and back-end processing, reshaping how manufacturers architect system-level value.
Digital coil arrays with embedded analog-to-digital conversion are unifying signal acquisition and preprocessing functions within the coil housing itself. Academic medical centers in the Netherlands and Switzerland are piloting these architectures for cardiac and abdominal imaging protocols. This unification eliminates analog cable transmission losses and enables flexible coil element combinations that adapt to patient anatomy in real time.
The EU Medical Device Regulation's post-market surveillance requirements are extending clinical evidence obligations to coil accessories previously exempt under the Medical Device Directive. Manufacturers must now maintain vigilance systems for coil-related adverse events across their entire installed base. High-channel-count neurovascular arrays face the steepest compliance burden, prompting some suppliers to streamline product portfolios.
Hospital procurement teams are consolidating coil purchasing decisions within centralized capital equipment committees rather than radiology department autonomy. This behavioral shift elevates total cost-of-ownership arguments over individual protocol performance metrics in vendor selection. The United States and United Kingdom exhibit the most pronounced centralization, with integrated delivery networks standardizing coil configurations across multi-site imaging fleets.
MRI Coils Market Segmentation
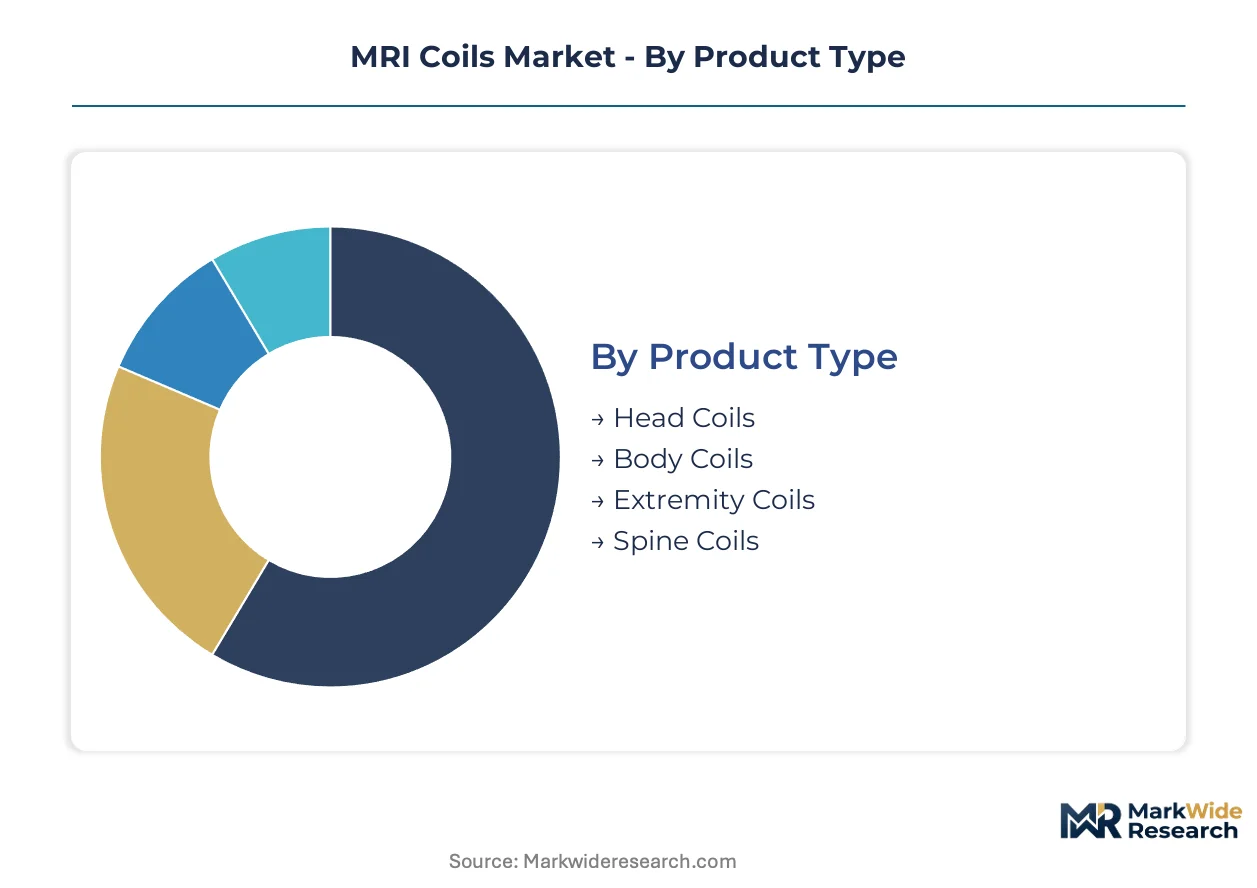
MRI coil segmentation reveals how procurement priorities diverge across clinical settings and technical specifications. Buyers prioritize anatomical coverage, field strength compatibility, and throughput economics differently depending on their patient mix and capital constraints.
Product Type:
Radiology departments select coil configurations based on exam volume distribution and reimbursement economics for specific anatomical protocols.
- Head Coils:Multi-channel phased arrays encircling the cranium optimize signal uniformity for neurovascular and functional brain imaging. Academic medical centers in Germany and the United States drive replacement demand as 7T research installations expand, though helium supply constraints lengthen procurement cycles.
- Extremity Coils:Compact dedicated arrays for knee, shoulder, wrist, and ankle imaging deliver higher spatial resolution than flexible body coils for musculoskeletal protocols. Sports medicine clinics in Australia and dedicated orthopedic centers in the United States are expanding dedicated extremity MRI suites to bypass full-body system scheduling bottlenecks.
- Body Coils:Torso-encircling arrays support abdominal, pelvic, and cardiac imaging protocols across general hospital settings.
- Spine Coils:Longitudinal arrays covering cervical through lumbar regions serve high-volume degenerative disc and trauma evaluation workflows.
Head coils lead volumes today; extremity coils are gaining share fastest.
Material:
Conductor substrate selection trades electrical performance against weight, durability, and raw material cost exposure.
- Copper:Oxygen-free high-conductivity copper windings dominate high-channel-count arrays where signal fidelity determines diagnostic utility. Japanese and European specialty metal producers concentrate niobium-titanium filament supply, exposing coil manufacturers to geopolitical disruption risk that complicates long-term OEM contracting.
- Silicone:Biocompatible elastomer housings encapsulate flexible coil elements for patient-contoured applications. Netherlands-based academic centers pilot silicone-embedded digital coil architectures that unify analog-to-digital conversion within the coil housing itself.
- Aluminum:Lighter conductor alternative for large-format body coils where weight reduction improves technologist handling.
- Plastic:Structural formers and patient contact surfaces molded from medical-grade polymers.
Copper dominates premium segment revenue; silicone is climbing the fastest as digital integration accelerates.
End User:
Procurement authority is concentrating within centralized capital committees rather than radiology department autonomy.
- Hospitals:Integrated delivery networks standardize coil configurations across multi-site imaging fleets to leverage volume purchasing and service contract consolidation. The United States and United Kingdom exhibit the most pronounced centralization, with total cost-of-ownership arguments superseding individual protocol performance metrics.
- Diagnostic Centers:Independent imaging facilities prioritize high-throughput coil configurations for extremity and cardiac protocols. United Imaging Healthcare's domestic manufacturing scale and government hospital procurement programs in China concentrate demand growth through this channel.
- Research Institutes:Neuroscience facilities in Germany, Japan, and the United States install 7T and 9.4T systems requiring multi-channel transmit-receive arrays.
- Outpatient Facilities:Ambulatory surgery centers and specialty clinics procure compact configurations for procedure-integrated imaging.
Hospitals lead installed base volume; diagnostic centers are expanding most quickly.
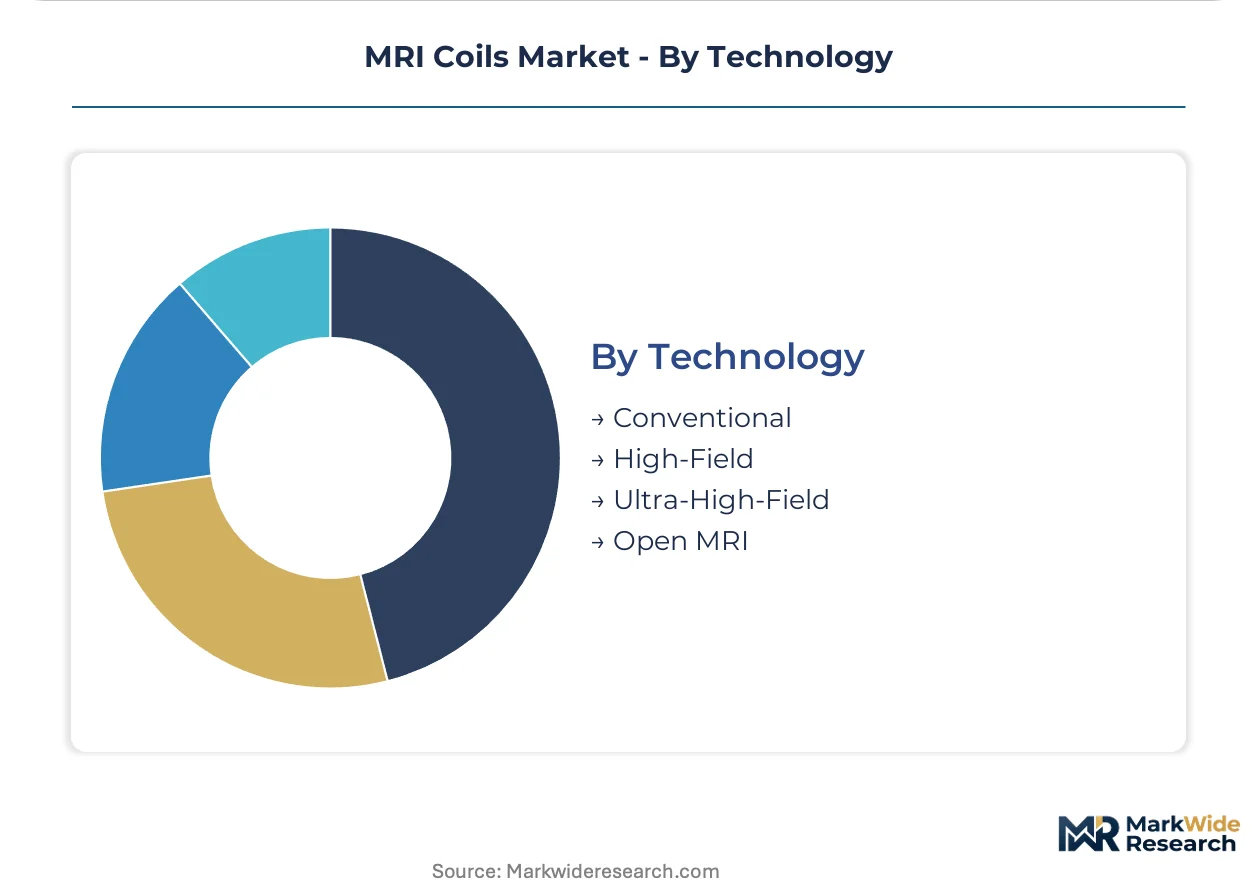
Technology:
Field strength selection determines operating frequency, magnet compatibility, and regulatory pathway complexity.
- High-Field:3T platforms balance clinical diagnostic capability with siting feasibility, commanding stable replacement demand across hospital and diagnostic center procurement. GE Healthcare anchors North American replacement demand through its installed base of 1.5T and 3T systems.
- Ultra-High-Field:7T and above systems occupy a narrow but high-margin niche concentrated at research institutes. The FDA's 510(k) clearance pathway for RF coil modifications shapes product iteration cycles for these specialized arrays in the United States.
- Conventional:1.5T platforms remain the volume workhorse for general diagnostic imaging.
- Open MRI:Permanent magnet and resistive designs accommodate claustrophobic or bariatric patients.
High-field systems lead replacement revenue; ultra-high-field shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cost-of-compliance gaps between regulatory jurisdictions are redirecting coil manufacturing investments toward markets with streamlined medical device pathways. The FDA's 510(k) efficiency in the United States contrasts with the EU MDR's extended clinical evidence requirements, creating arbitrage opportunities for suppliers optimizing regulatory sequencing.
United States
Academic medical centers in Boston and Stanford drive ultra-high-field coil demand through NIH-funded neuroscience installations. The FDA's 510(k) premarket notification pathway enables faster iteration of specialized RF arrays for 7T research systems. Minneapolis anchors replacement demand for 1.5T and 3T coils through GE Healthcare's installed base service networks.
Germany
Helmholtz Association institutes in Munich and Berlin sustain multi-channel transmit-receive array procurement for 7T and 9.4T platforms. The EU Medical Device Regulation's post-market surveillance requirements extend compliance obligations to coil accessories previously exempt under the MDD. Erlangen concentrates integrated magnet-coil-software development within Siemens Healthineers' ecosystem.
China
Government hospital procurement programs under centralized tendering systems accelerate domestic coil adoption across tier-2 and tier-3 cities. The NMPA's streamlined Class II medical device registration supports United Imaging Healthcare's manufacturing scale expansion. Shanghai anchors RF coil production clusters serving both domestic replacement and export markets.
Japan
Neuroscience institutes in Tokyo and Osaka install ultra-high-field systems requiring specialized multi-nuclear coil architectures. METI-funded quantum sensing initiatives intersect with RF engineering talent pools concentrated at University of Tokyo and Osaka University. Kyoto-based specialty metal producers concentrate niobium-titanium filament supply for superconducting magnet integration.
India
Ayushman Bharat procurement programs fund MRI installations in tier-2 cities, creating first-mover opportunities for coil suppliers establishing local service presence. The CDSCO's medical device registration pathway is streamlining import substitution for diagnostic center equipment. Bengaluru and Hyderabad concentrate diagnostic imaging demand through private hospital chain expansion.
MRI Coils Market Vendor Landscape
Strategic partnerships dominate the current landscape as coil manufacturers seek magnet-system integration and software convergence. The vendor base clusters around three tiers: integrated system OEMs with captive coil production, independent coil specialists serving multi-platform installed bases, and regional fabricators targeting price-sensitive replacement markets. Two archetypes define competitive positioning: ecosystem-integrated suppliers competing on total system performance, and modular specialists competing on backward compatibility and service responsiveness. Technology licensing and portfolio diversification represent the dominant competitive moves as vendors address legacy system support fragmentation.
Among integrated system OEMs, Siemens Healthineers AG exemplifies the ecosystem-anchored archetype through its magnet-coil-software convergence strategy. GE Healthcare Inc. occupies a parallel position in North American replacement markets. Shanghai United Imaging Healthcare Co., Ltd. represents the scale-driven regional challenger archetype, leveraging domestic manufacturing and government procurement alignment.
| Leading Market Players |
|---|
| Siemens Healthineers |
| GE Healthcare |
| Philips Healthcare |
| Canon Medical Systems |
| Shanghai United Imaging Healthcare |
| Hitachi Healthcare |
| Esaote SPA |
| ScanMed |
| Nova Medical |
| Others |
Supply Flow & Price Mechanics
Integrated delivery networks in the United States and United Kingdom anchor coil procurement through centralized capital committees, consolidating purchasing power around total cost-of-ownership contracts that bundle hardware, software interfaces, and decade-long service agreements into single-vendor relationships.
Pricing Analysis
Distributor margins for independent coil specialists compress against direct-to-OEM pricing from integrated manufacturers like Siemens Healthineers and GE Healthcare. Three-tier pricing structure across premium, standard, and economy levels separates multi-channel neurovascular arrays from refurbished 1.5T extremity coils and third-party compatible replacements. Cost compression in copper-wound premium arrays intensifies because raw material volatility and single-source superconducting wire dependence squeeze manufacturing margins. Diagnostic centers in China and India exhibit the highest price sensitivity, while academic medical centers in Germany and Japan prioritize signal-to-noise performance over unit cost.
Supply Chain Analysis
Domestic-content mandates under China's NMPA registration pathway and India's PLI scheme for medical devices are reshaping sourcing patterns toward localized RF coil production clusters in Shanghai and Bengaluru. Oxygen-free copper windings draw from Japanese and European specialty metal producers, while niobium-titanium superconducting filaments rest on Kyoto-based suppliers and German wire manufacturers. Single-source vulnerability in superconducting wire concentrates risk among two regional production hubs. Distribution runs through hospital procurement committees in consolidated markets and government tender systems in emerging economies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The MRI coils market reads as a late-cycle quality story where outpatient imaging expansion and ultra-high-field research infrastructure are tilting procurement specifications toward digital-integrated, multi-channel arrays with embedded preamplification.
For Market Incumbents: Deepen backward integration into niobium-titanium filament supply through captive partnerships with Japanese specialty metal producers, insulating against geopolitical disruption risk. Expand ISO 13485-certified manufacturing footprints in India to capture Ayushman Bharat procurement flows before local competitors consolidate service networks. Defend premium positioning by accelerating FDA 510(k) clearance cycles for AI-native coil architectures that embed real-time adaptive signal processing. For New Entrants and Emerging Players: Launch via dedicated extremity coil distribution partnerships with sports medicine clinic chains in Australia and orthopedic imaging centers in the United States, bypassing entrenched full-body system vendors. Target India's tier-2 and tier-3 diagnostic center buildout with refurbished 1.5T compatible coils priced below OEM replacement rates. Prioritize backward compatibility engineering for GE Healthcare's installed base to fragment incumbent service contract renewals. For Investors and Strategic Acquirers: Integrated system OEMs are the most active acquirer in this space, seeking digital coil-native software capabilities to unify RF front-end and reconstruction algorithm development. Long-term viability hinges on convergence between coil hardware and AI-based image reconstruction platforms over the next decade. Acquisition targets should display multi-platform backward compatibility expertise and established FDA 510(k) submission track records. The signal to monitor is NMPA registration acceleration for domestic Chinese manufacturers, which would compress pricing power for multinational suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Digital Coil-Native Software Integration | Convergence with AI reconstruction algorithms differentiates premium system offerings from commodity coil replacements. |
| Domestic Manufacturing Scale-Up | United Imaging Healthcare leverages NMPA registration efficiency to capture government hospital procurement in tier-2 Chinese cities. |
| Multi-Platform Backward Compatibility Investment | Engineering resources fragmented across 10-15 year installed bases defend replacement revenue against third-party entrants. |
| Ultra-High-Field Research Partnership | NIH-funded neuroscience institutes in Boston and Stanford sustain 7T and 9.4T coil demand through multi-channel transmit-receive arrays. |
| Helium Conservation Compliance Alignment | Regulatory pressure on superconducting magnet supply chains forces longer capital cycles and consolidated vendor relationships. |
Methodological Framework
Direct dialogue with hospital purchasing committee members, biomedical engineers at academic medical centers, GPO contracts managers, and RF coil manufacturing engineers grounded the qualitative assessment, validated against FDA 510(k) clearance databases, NMPA registration filings, EU MDR technical documentation, hospital procurement contract awards, and superconducting wire trade flow records. Bottom-up installed base modeling and top-down healthcare capital expenditure projections were cross-referenced for triangulation.
Bottom-up segment analysis tracked coil shipments by anatomical configuration, field strength compatibility, and end-user channel across the projection horizon, while top-down validation anchored on MRI system installation forecasts and replacement cycle assumptions. Segmentation dimensions included product type, conductor material, end-user setting, and technology tier. CAGRs were derived from logistic adoption curves fitted to historical replacement patterns and projected outpatient imaging volume expansion. Forecast inputs incorporated helium supply constraint scenarios and domestic-content procurement policy shifts.
Several conditions sit outside the modeled scope, including disruptive superconducting magnet cooling technologies that eliminate helium dependence, and radical coil form-factor innovations that obsolete backward compatibility requirements. Forecasts reflect documented assumptions regarding regulatory pathway efficiency and raw material price stability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Stabilometric Platform Market
Medical Devices
Novel Vaccine Delivery Systems Market
Medical Devices
Global Refractive Surgery Devices Market
Medical Devices
Europe Renal Denervation Devices Market
Medical Devices
US Clear Aligners Market
Medical Devices
Internal Neuromodulation Devices Market
Medical Devices
Light Therapy Beauty Devices Market
Medical Devices
Anti-Infective Endotracheal Tube Market
Medical Devices
EMG Biosensors Market
Medical Devices
Global Automated Dispensing Machines Market
Medical Devices
Global Ablation Technologies Market
Medical Devices
GCC Implantable Medical Devices Market
Medical Devices
US Digital Pregnancy Test Kits Market
Medical Devices
Implantable Medical Devices Market
Medical Devices
Hyperpigmentation Treatment Devices Market
Medical Devices
Global Self Care Medical Devices Market