
 Spinal Implant Market | 2026-2036
Spinal Implant Market Size, Share, and Industry Trends Forecast 2026-2036
Spinal Implant Market Analysis
Software-defined navigation and robotic-assisted planning is consolidating the value proposition around procedural outcomes rather than standalone hardware. Medtronic plc leverages its integrated surgical ecosystem to anchor premium positioning across navigation-enabled fusion systems. Johnson & Johnson (DePuy Synthes) competes through broad orthopedic scale and deep hospital contracting relationships. Stryker Corporation differentiates via Mako spine robotics and specialized instruments that tighten operative workflow control.
Spinal implants comprise metallic, polymeric, or biological devices engineered to restore vertebral alignment, decompress neural elements, or enable arthrodesis, typically manufactured from titanium alloys, PEEK, or demineralized bone matrix with pore architectures optimized for osseointegration. Their primary purpose spans stabilization of traumatic, degenerative, or deformity-related spinal pathologies in operative settings. Interbody devices and spinal fusion devices occupy the dominant revenue tiers, reflecting mature reimbursement pathways and high procedural frequency in degenerative disc disease. Artificial discs represent a faster-expanding margin pool as motion-preserving alternatives gain surgeon acceptance in select cervical and lumbar indications. Minimally invasive surgery technology reshapes competitive dynamics by reducing tissue disruption and shortening recovery intervals, compressing hospital stay economics.
FDA premarket notification and PMA pathways govern U.S. device clearance, while the EU Medical Device Regulation tightens clinical evidence requirements for implantable spinal systems. ISO 13485 quality management and ASTM F2077 mechanical testing standards further constrain design validation and post-market surveillance obligations. The EU AI Act introduces emerging compliance layers for AI-enabled surgical planning tools that interface with implant placement. Stakeholders must monitor reimbursement parity between inpatient and ambulatory settings, as site-of-service economics increasingly dictate implant selection and vendor consolidation trajectories.
Market Dynamics
CMS reimbursement parity between inpatient and ambulatory surgical settings is compressing site-of-service economics and forcing hardware vendors to reconfigure distribution models around outpatient procurement workflows.
Growth Catalysts
- EU Medical Device Regulation:The MDR's tightened clinical evidence requirements for implantable spinal systems is accelerating consolidation among manufacturers with robust post-market surveillance infrastructure, privileging scaled players.
- Titanium alloy porous architectures:Advanced additive manufacturing of trabecular-structured titanium interbody cages is improving osseointegration rates and shortening fusion timelines in degenerative disc disease procedures.
- Ambulatory surgical centers:Outpatient spine procedure volume is expanding rapidly under favorable CMS site-of-service payment differentials, redirecting hardware procurement toward ASC-focused distributors.
Market Restraints
- PEEK polymer supply concentration:Medical-grade polyetheretherketone resin production concentrates among a limited set of European and Asian chemical suppliers, exposing implant manufacturers to input cost volatility and allocation risk.
- Demineralized bone matrix sourcing:Biological implant materials depend on allograft tissue bank networks with geographic concentration in southeastern United States processing facilities, creating supply vulnerability.
- Motion-preserving device reimbursement:Artificial disc replacement procedures face inconsistent payer coverage determinations across commercial insurance plans, constraining surgeon adoption despite clinical efficacy data.
Strategic Opportunities
- AI-enabled surgical planning:The EU AI Act's emerging compliance framework for high-risk medical AI systems is creating first-mover advantage for navigation software vendors with pre-certified algorithmic placement tools.
- India's CDSCO fast-track pathway:India's streamlined medical device registration for US FDA-cleared products offers expedited market entry for spinal fusion systems targeting its expanding private hospital sector.
- Subscription-based instrument programs:Specialized access systems and disposable instrument kits are migrating toward per-procedure leasing models that reduce ASC capital burden and tighten vendor lock-in.
Industry Challenges
- Robotic surgery integration:Spine-specific robotic platforms require substantial capital deployment and specialized technician training, straining hospital capital budgets and creating adoption bottlenecks in mid-tier health systems.
- ISO 13485 audit complexity:Quality management system recertification timelines have elongated as notified bodies face capacity constraints under MDR implementation, delaying product line extensions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spinal Implant Market |
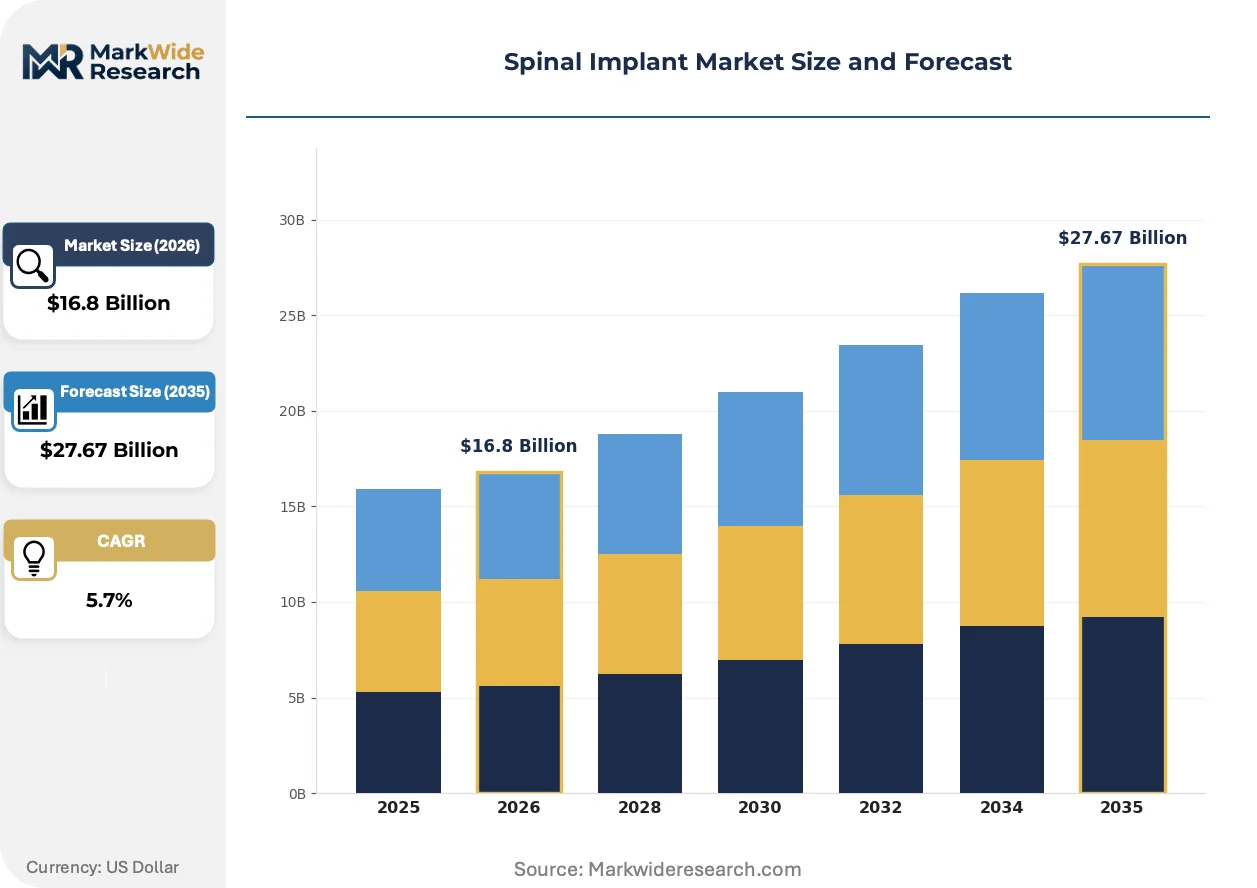
| Market Size in 2026 | $16.8 Billion |
| Market Size in 2035 | $27.67 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Interbody Devices, Spinal Fusion Devices, Artificial Discs, Bone Grafts Application: Spinal Surgery, Trauma, Degenerative Disc Disease, Scoliosis End User: Hospitals, Ambulatory Surgical Centers, Rehabilitation Clinics, Orthopedic Surgeons Technology: Minimally Invasive Surgery, Biomechanical Engineering, 3D Printing, Navigation Systems |
| Companies Covered | Medtronic plc, Johnson & Johnson (DePuy Synthes), Stryker Corporation, Zimmer Biomet Holdings, Globus Medical Inc, NuVasive Inc, B. Braun Melsungen AG, Orthofix Medical Inc, RTI Surgical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spinal Implant Market Emerging Trajectories
Navigation-enabled procedural workflows are displacing freehand implant placement as the standard of care, compressing differentiation around software integration rather than standalone hardware performance metrics.
Patient-specific 3D-printed titanium interbody cages with optimized pore geometries and integrated fixation features is overtaking off-the-shelf PEEK devices in complex deformity and revision fusion cases. Academic medical centers and high-volume spine specialty groups are adopting these implants at accelerating rates. The technology is overtaking conventional manufacturing economics by collapsing instrument set complexity and reducing operative time.
The EU AI Act's risk classification framework for medical device software is imposing new conformity assessment obligations on surgical navigation systems with autonomous planning features. Manufacturers must now compile extensive technical documentation and algorithmic transparency reports for notified body review. Spine navigation platforms with embedded machine learning are most affected, with vendors accelerating human-in-the-loop design modifications to manage compliance burden.
Hospital supply chain organizations are consolidating vendor contracts around integrated spine platforms that bundle implants, navigation, and robotics under single-source agreements. Group purchasing organizations and IDN central procurement offices are displacing individual surgeon preference contracting. This concentration is most visible in United States multi-hospital systems pursuing standardization across their ambulatory surgery networks.
Spinal Implant Market Segmentation
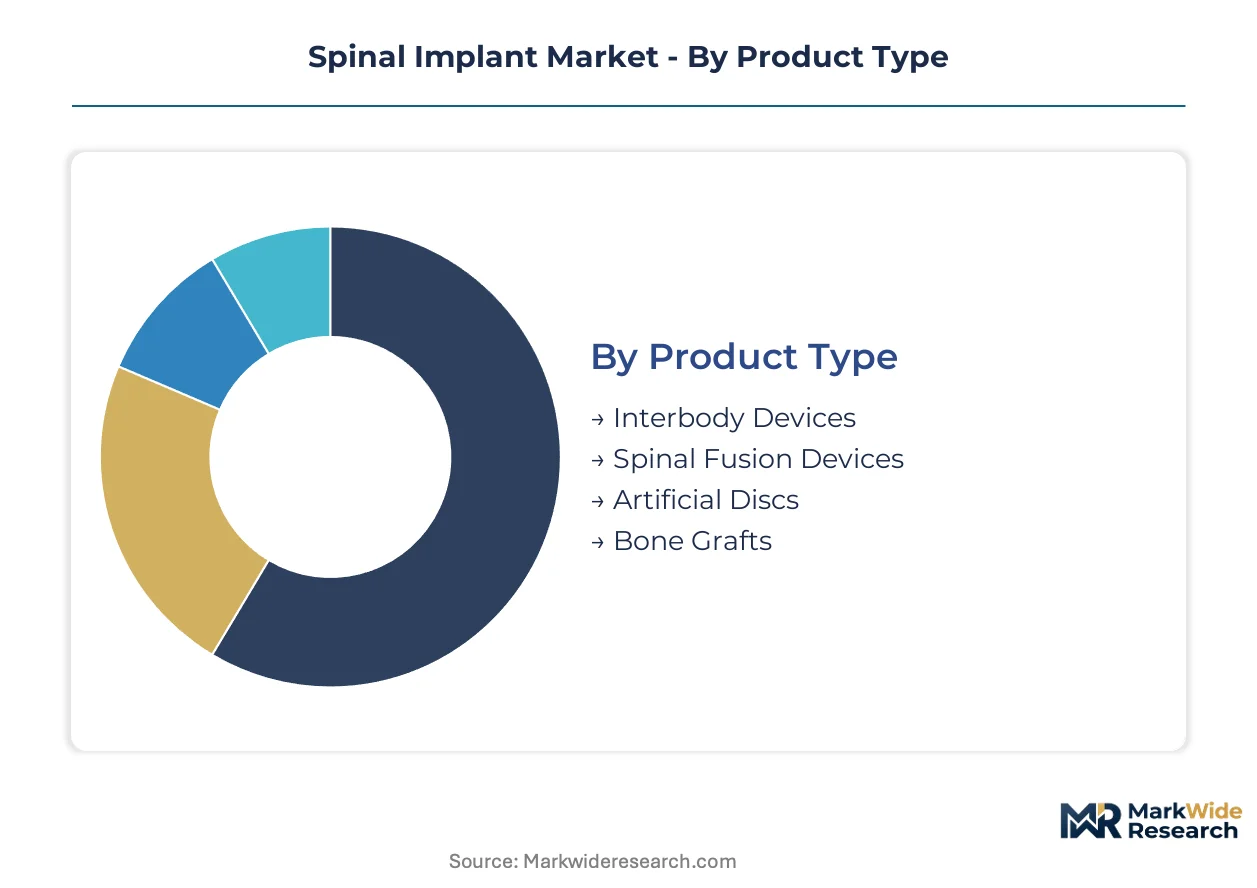
Spinal implant segmentation reveals divergent margin profiles across hardware categories, with fusion devices commanding stable reimbursement while motion-preserving alternatives reshape surgeon preference patterns. Technology-enabled segments now drive procurement consolidation as hospitals standardize around integrated platforms.
Product Type:
Volume tiers separate mature fusion hardware from emerging premium alternatives, with reimbursement parity dictating procurement concentration.
- Interbody Devices:These titanium alloy or PEEK cages occupy the procedural core of lumbar and cervical fusion, with porous titanium architectures from additive manufacturing displacing conventional machined geometries in academic medical centers. Demand clusters in United States hospital systems pursuing navigation-enabled placement workflows.
- Spinal Fusion Devices:Pedicle screw systems and rod constructs anchor the revenue base through established CPT reimbursement codes, though hardware commoditization pressures margins. United States ASC networks now drive volume as site-of-service economics favor outpatient procurement.
- Artificial Discs:Motion-preserving cervical and lumbar alternatives face uneven commercial payer coverage despite PMA pathway clearance from FDA.
- Bone Grafts:Demineralized bone matrix and synthetic ceramic scaffolds depend on southeastern United States tissue bank processing concentration.
Today's leader: Spinal Fusion Devices. Tomorrow's challenger: Artificial Discs.
Application:
Procedure complexity stratifies implant selection, with degenerative indications supporting high-volume standardized kits versus deformity cases demanding patient-specific solutions.
- Spinal Surgery:Elective decompression and stabilization procedures generate the highest hardware consumption per case, with navigation integration now standard in high-volume United States spine specialty groups. CMS reimbursement shifts toward ASC settings compress implant selection around streamlined instrument sets.
- Degenerative Disc Disease:Age-related disc pathology drives the largest addressable procedure volume globally, with interbody fusion and artificial disc replacement competing for surgeon preference in lumbar and cervical segments. United States commercial payers increasingly require prior authorization for inpatient fusion.
- Trauma:Acute fracture stabilization demands rapid implant availability through hospital emergency supply chains.
- Scoliosis:Pediatric and adult deformity correction requires complex multi-level constructs with extended operative times.
Degenerative Disc Disease captures current volume dominance. Trauma represents the most underpenetrated expansion corridor.
End User:
Capital availability and procurement autonomy separate institutional buyers, with ambulatory networks disrupting traditional hospital contracting hierarchies.
- Hospitals:Inpatient surgical departments maintain preference-based surgeon contracting, though IDN central procurement offices increasingly enforce vendor consolidation across multi-hospital systems. United States health systems now bundle navigation, robotics, and implants under single-source agreements.
- Ambulatory Surgical Centers:Outpatient spine facilities operate under constrained capital budgets, favoring per-procedure instrument leasing and disposable kit models. United States ASC volume expansion under CMS site-of-service parity redirects hardware procurement toward specialized distributors.
- Rehabilitation Clinics:Post-acute settings drive secondary demand for external fixation and bracing adjuncts.
- Orthopedic Surgeons:Individual practitioner preference historically governed implant selection, though GPO concentration erodes this autonomy.
Hospital systems retain contract leverage today. ASC networks are gaining procurement influence fastest.
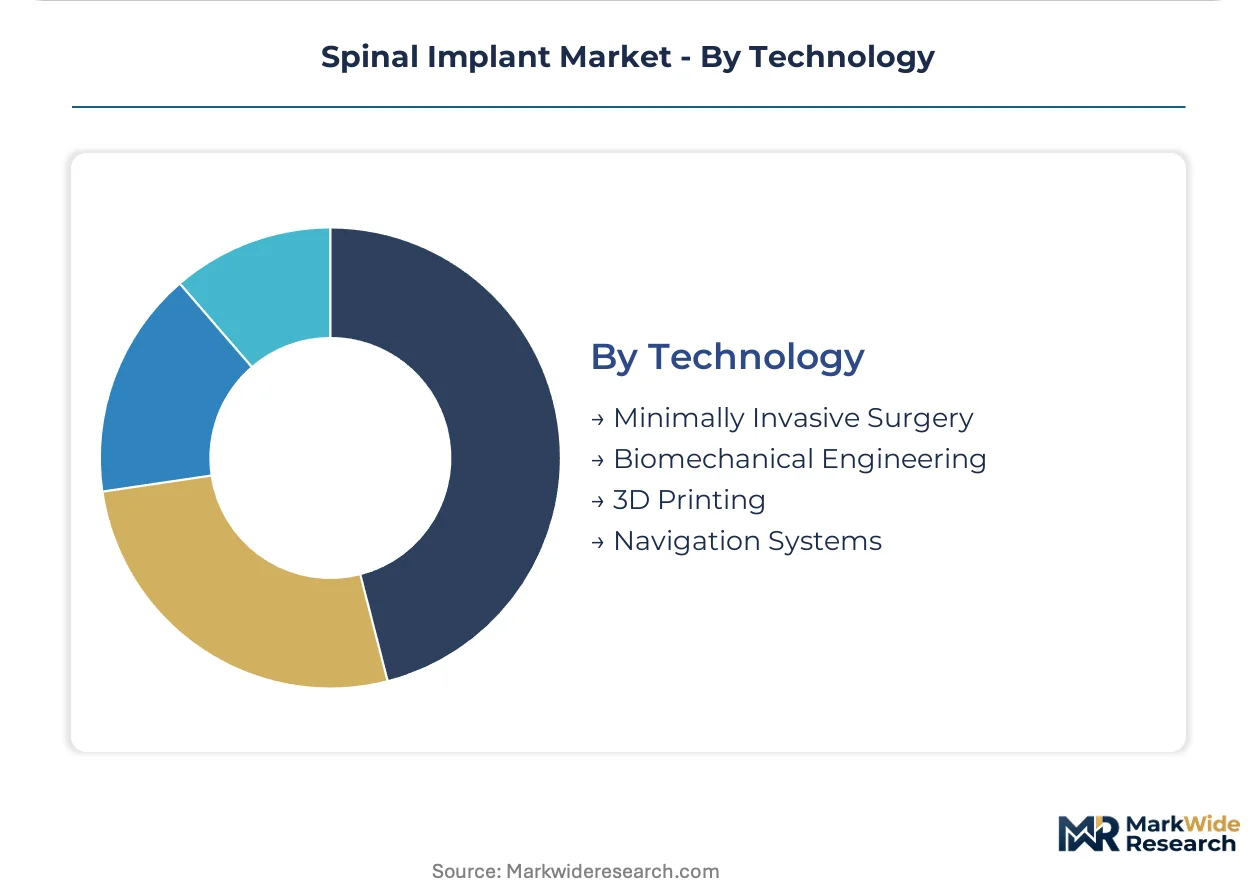
Technology:
Software integration now differentiates hardware vendors, with navigation and robotics compressing differentiation around procedural outcomes rather than standalone implant performance.
- Navigation Systems:Intraoperative image guidance and robotic-assisted planning consolidate value around placement accuracy, with FDA-cleared platforms from major orthopedic manufacturers anchoring premium positioning. EU AI Act compliance requirements for algorithmic surgical planning create first-mover advantage for pre-certified vendors.
- Minimally Invasive Surgery:Tubular retractor systems and percutaneous screw placement reduce tissue disruption and shorten recovery intervals, with United States ASC networks driving adoption for economic advantage. Technique-specific instrument sets require specialized training programs.
- 3D Printing:Patient-specific titanium interbody cages with optimized pore geometries gain traction in complex deformity cases.
- Biomechanical Engineering:Computational modeling informs implant design validation under ASTM F2077 mechanical testing standards.
Navigation Systems define current competitive positioning. 3D Printing offers the steepest technology expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting manufacturing investment toward jurisdictions with streamlined device approval pathways and lower cost-of-compliance structures. Production migration concentrates where FDA-cleared products receive accelerated local registration.
United States
Hospital systems and ASC networks anchor procurement volume as CMS site-of-service parity expands outpatient spine procedures. FDA PMA and 510(k) pathways govern device clearance with rigorous post-market surveillance requirements. Tennessee and North Carolina tissue processing clusters supply demineralized bone matrix to domestic implant manufacturers.
Germany
Academic medical centers drive adoption of navigation-enabled fusion systems and patient-specific 3D-printed titanium cages. EU MDR tightened clinical evidence requirements accelerate consolidation among manufacturers with robust quality management infrastructure. Baden-Württemberg precision engineering clusters support additive manufacturing of porous titanium interbody devices.
China
Expanding private hospital sector and aging demographics generate procedural volume growth for degenerative spine indications. NMPA medical device registration reforms streamline market entry for imported fusion systems. Jiangsu and Zhejiang manufacturing bases concentrate domestic PEEK resin processing and titanium alloy forging capacity.
India
Private hospital sector expansion in metropolitan centers creates demand for premium spinal fusion hardware. CDSCO fast-track registration for US FDA-cleared products reduces time-to-market for multinational implant vendors. Maharashtra and Karnataka medical device manufacturing zones attract contract manufacturing investment from global orthopedic suppliers.
Japan
Aging population and high surgical sophistication sustain demand for motion-preserving artificial disc technologies. PMDA regulatory frameworks emphasize long-term clinical evidence for implantable devices. Kanto region academic medical centers pioneer robotic-assisted spine surgery adoption and navigation integration.
Spinal Implant Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated platform vendors capturing hospital system contracts while component suppliers serve mid-tier distributors. The vendor base concentrates around three strategic archetypes: diversified orthopedic conglomerates with navigation-robotics ecosystems, pure-play spine specialists with deformity-focused portfolios, and biological tissue processors with allograft supply chain control. Dominant competitive moves include M&A to acquire navigation software capabilities and capacity expansion in titanium additive manufacturing.
Among diversified orthopedic conglomerates, Medtronic plc and Johnson & Johnson (DePuy Synthes) represent the integrated-platform archetype with navigation-enabled surgical ecosystems. Stryker Corporation occupies a position within the robotics-differentiated tier through specialized intraoperative workflow tools. These three anchors exemplify how scale and technology integration determine contracting leverage with IDN procurement offices.
| Leading Market Players |
|---|
| Medtronic plc |
| Johnson & Johnson (DePuy Synthes) |
| Stryker Corporation |
| Zimmer Biomet Holdings |
| Globus Medical Inc |
| NuVasive Inc |
| B. Braun Melsungen AG |
| Orthofix Medical Inc |
| RTI Surgical |
| Others |
Supply Flow & Price Mechanics
Additive manufacturing of porous titanium interbody cages is collapsing traditional cost curves while concentrating production capability among precision engineering clusters in Germany and the United States, simultaneously enabling premium pricing for patient-specific geometries and tightening supply-side control over high-margin implant categories.
Pricing Analysis
Distributor margins in the spinal implant channel typically range from 25-40 percent for specialized instrument sets, though direct-to-hospital contracting by integrated platform vendors compresses this layer through bundled navigation-implant agreements. Pricing stratifies across premium navigation-enabled systems, standard fusion hardware, and economy-tier commoditized pedicle screw constructs, with FDA PMA pathway clearance and MDR certification serving as the primary quality-grade differentiators. Cost compression in standard fusion tiers is intensifying because hospital GPOs consolidate vendor contracts around single-source platform agreements. Ambulatory surgical centers exhibit the highest price sensitivity due to constrained capital budgets, while academic medical centers prioritize placement accuracy and outcomes data over unit cost.
Supply Chain Analysis
India's PLI scheme for medical device manufacturing and China's NMPA domestic-content preferences are reshaping sourcing patterns for multinational implant vendors seeking tariff-advantaged production bases. Medical-grade titanium alloy feedstock concentrates in China, Japan, and Russia, while PEEK resin polymerization rests on European and Asian chemical suppliers. Single-source vulnerability in southeastern United States tissue bank processing for demineralized bone matrix creates geographic concentration risk for biological implant materials. Distribution runs through specialized orthopedic distributors serving hospital systems and ASC networks, with direct manufacturer-to-IDN contracting displacing traditional distributor intermediaries in high-volume accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through additive manufacturing cost-down trajectories and the shift toward subscription-based instrument programs that convert capital expenditure into recurring revenue streams.
For Market Incumbents: To counter software-defined navigation displacing standalone hardware differentiation, Medtronic plc and Stryker Corporation should deepen backward integration into titanium additive manufacturing capacity in Baden-Württemberg and Tennessee precision clusters. Securing MDR pre-certification for AI-enabled surgical planning algorithms creates compliance moats against mid-tier competitors lacking notified body relationships.
For New Entrants and Emerging Players: CDSCO's fast-track pathway in India opens a window for FDA-cleared fusion systems to capture private hospital sector growth in Maharashtra and Karnataka metropolitan centers. Targeting ASC-focused distributors with per-procedure leasing models for disposable instrument kits addresses the most penetrable procurement channel, leveraging capital-light entry against integrated platform incumbents.
For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play spine specialists lacking navigation-robotics integration, presenting acquisition targets for orthopedic conglomerates seeking deformity-focused portfolios. The signal to watch as inflection indicator is CMS site-of-service reimbursement parity expansion, which accelerates ASC volume capture and rewards outpatient-procurement-ready supply chains.
| Strategic Initiative | Industry Significance |
|---|---|
| MDR Certification Investment | EU MDR clinical evidence requirements privilege scaled manufacturers with robust post-market surveillance infrastructure. |
| Titanium Additive Manufacturing Scale-Up | Baden-Württemberg precision clusters support patient-specific cage production with optimized pore geometries for osseointegration. |
| AI-Enabled Surgical Planning Development | EU AI Act compliance for high-risk medical AI systems creates first-mover advantage for pre-certified algorithmic placement tools. |
| ASC Distribution Partnership | CMS site-of-service parity redirects hardware procurement toward specialized distributors serving outpatient spine networks. |
| Subscription Instrument Program Launch | Per-procedure leasing models reduce ASC capital burden while tightening vendor lock-in through disposable kit standardization. |
Methodological Framework
Bottom-up procedure volume modeling reconciled against top-down implant shipment tracking forms the analytical core of this study. Primary interviews with spine surgeons, hospital purchasing committee members, biomedical engineers, and GPO contracts managers combined with secondary validation against FDA 510(k) and PMA filings, CMS Medicare claims data, hospital procurement databases, and EU MDR notified body documentation. Cross-referencing manufacturer capacity disclosures with customs trade records and tissue bank processing volumes enables triangulation between demand-side utilization and supply-side production.
Historical trendline analysis of procedural volume, reimbursement code utilization, and implant shipment patterns informs the projection framework across the analysis window. Segmentation dimensions include product type, application indication, end-user facility type, and technology integration level, with CAGRs derived from regression analysis of correlated variables including aging demographic trajectories and ambulatory surgery expansion rates. Forecast inputs incorporate navigation adoption curves, additive manufacturing cost trajectories, and site-of-service reimbursement policy evolution.
Revisions become necessary when MDR implementation timelines shift, CMS site-of-service parity rules change, or AI Act enforcement interpretations alter compliance burdens for surgical planning software. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Hemoconcentrators Market
Medical Devices
South America Ultrasound Devices Market
Medical Devices
Neurosurgical Products Market
Medical Devices
Phlebotomy Equipments Market
Medical Devices
IVF Time-Lapse Imaging Devices Market
Medical Devices
Global Image Guided Surgery Devices Market
Medical Devices
Accelerometers Medical Sensors Market
Medical Devices
Orbital Tissue Expander Market
Medical Devices
India Contraceptive Devices Market
Medical Devices
Vaginal Inserts Market
Medical Devices
Global Mechanical Ventilators Market
Medical Devices
Asia-Pacific Vaginal Slings Market
Medical Devices
Middle East and Africa Electroencephalography Devices Market
Medical Devices
Global Emerging Mental Health Devices and Platforms Market
Medical Devices
Vibrating Mesh Nebulizer Market
Medical Devices
Global Blood Transfusion Devices Market