
 United Arab Emirates Drug Delivery Devices Market | 2026-2036
United Arab Emirates Drug Delivery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
United Arab Emirates Drug Delivery Devices Market Analytics
Biocompatible polymers are replacing conventional plastics in infusion pump housings, which is recalibrating unit economics across the Emirates. Becton, Dickinson and Company leverages its manufacturing scale to anchor supply contracts with Dubai Health Authority-affiliated facilities. Roche Holding AG differentiates through R&D intensity in smart delivery systems targeting diabetes management protocols. Johnson & Johnson sustains brand strength in homecare channels through specialized injector training programs.
Drug delivery devices encompass engineered systems designed to administer therapeutic agents at controlled rates, with specifications including flow precision within ±5% variance and materials meeting ISO 10993 biocompatibility standards for patient-contact surfaces. These devices serve the primary commercial purpose of improving therapeutic adherence while minimizing administration errors in clinical and non-clinical environments. Injectors occupy the dominant position among device types due to their versatility across oncology and diabetes management applications, while wearable devices represent the fastest-growing technology segment as remote patient monitoring protocols expand. Homecare settings are capturing growing margin pools as reimbursement frameworks shift toward ambulatory administration models.
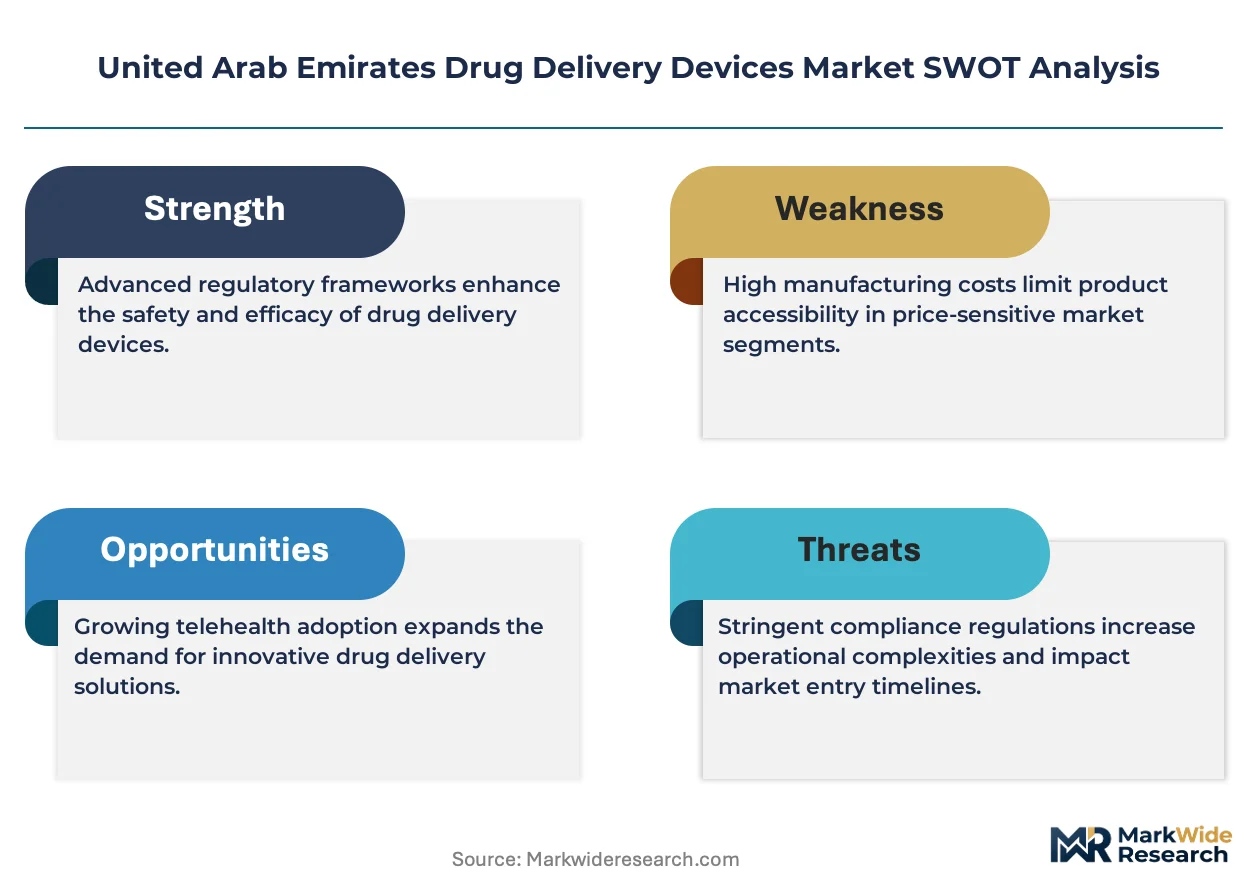
MOHAP and the UAE's medical device registration framework govern product standards, with MOHAP's mandatory conformity assessments shaping demand for ISO 13485-certified manufacturing partners seeking market access. The Emirates' alignment with GCC harmonized technical regulations further structures import and distribution pathways for multinational suppliers. Stakeholders must monitor evolving reimbursement codes for needle-free technologies and biodegradable devices as MOHAP expands its priority medical device list.
Market Dynamics
MOHAP's medical device registration reforms are compressing market access timelines for advanced delivery technologies, forcing multinational suppliers to restructure their conformity assessment workflows around ISO 13485-certified manufacturing partnerships.
Growth Catalysts
- Hospital-based administration protocols:Tertiary facilities across Dubai's healthcare corridor are expanding procurement volumes for infusion pump systems, anchoring demand for precision flow-control devices.
- Biocompatible polymer substitution:Device housings incorporating ISO 10993-compliant materials are displacing conventional plastics in patient-contact surfaces, recalibrating unit economics for domestic assemblers.
- Remote patient monitoring expansion:Wearable delivery platforms are capturing protocol adoption in diabetes management applications, with homecare settings emerging as priority deployment channels.
Market Restraints
- Import concentration risk:Supply chains for precision pump components remain concentrated among European and North American specialty manufacturers, exposing procurement to currency volatility and logistics friction.
- Technical limitation in needle-free systems:Viscosity thresholds for high-concentration biologics continue to constrain adoption of jet injector technologies in oncology protocols.
- Regulatory friction from GCC harmonization:Misalignment between MOHAP's priority device list and Saudi SFDA classification timelines creates dual-track registration burdens for suppliers targeting both markets.
Strategic Opportunities
- Underpenetrated Northern Emirates:Sharjah and Ras Al Khaimah healthcare infrastructure is expanding tertiary capacity, creating first-mover positioning for smart injector distributors.
- Technology convergence:Continuous glucose monitoring interfaces are converging with insulin pump ecosystems, enabling closed-loop delivery systems for ambulatory diabetes management.
- Distribution channel innovation:Direct-to-patient subscription models for consumable injector supplies are bypassing traditional hospital procurement committees in Abu Dhabi's private insurance networks.
Industry Challenges
- Specialized technician scarcity:Calibration and maintenance of smart infusion systems requires trained biomedical engineers, a skillset concentrated in Dubai and Abu Dhabi with limited pipeline from UAE technical institutes.
- ISO 13485 certification timelines:Manufacturing partners seeking MOHAP market access face extended audit cycles, compressing product launch windows against competitive entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Arab Emirates Drug Delivery Devices Market |
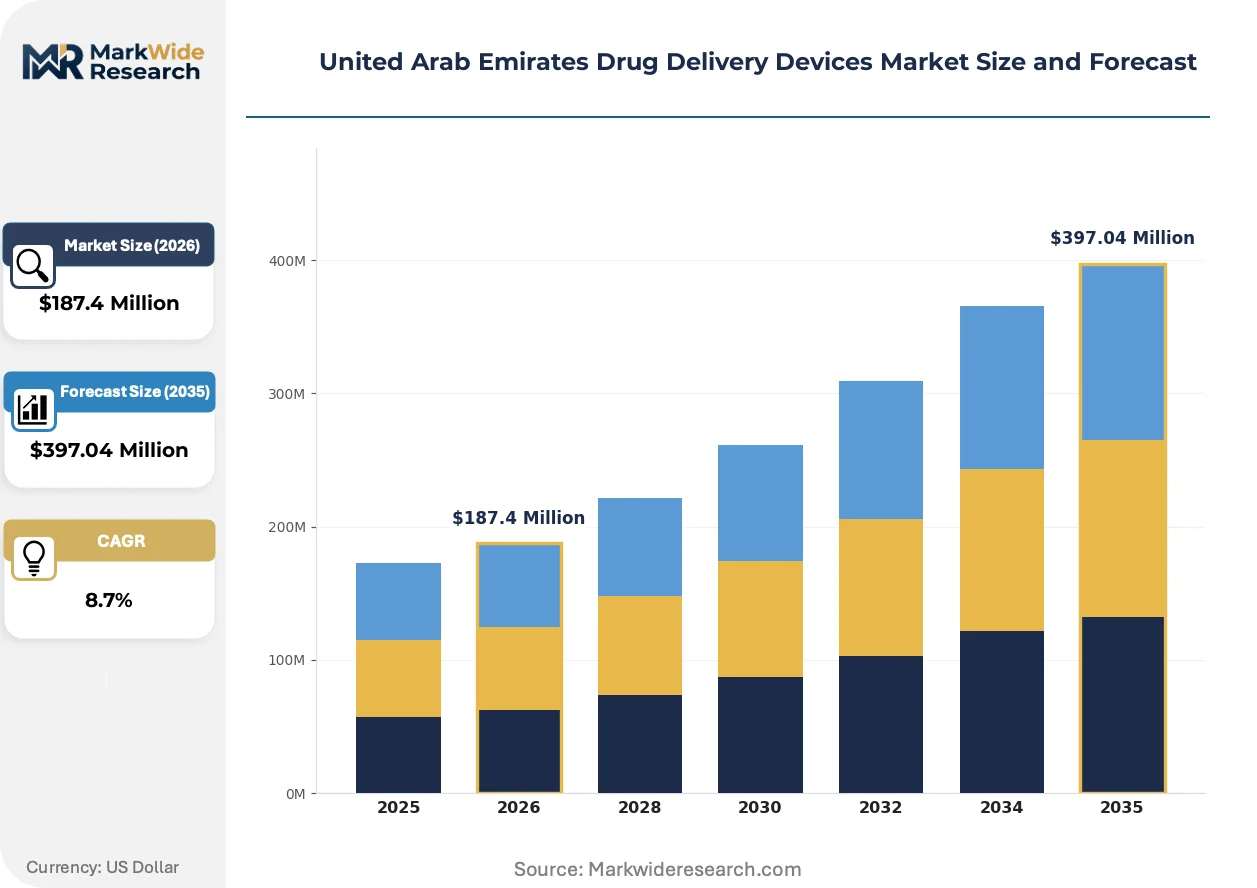
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $397.04 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Device Type: Inhalers, Injectors, Infusion Pumps, Micro-needles End User: Hospitals, Homecare Settings, Clinics, Long-term Care Facilities Technology: Smart Delivery Systems, Needle-free Technologies, Biodegradable Devices, Wearable Devices Application: Oncology, Diabetes Management, Pain Management, Cardiovascular Treatments |
| Companies Covered | AstraZeneca PLC, Bayer AG, Merck KGaA, GlaxoSmithKline PLC, Becton, Dickinson and Company, Johnson & Johnson, Pfizer Inc, Roche Holding AG, Novartis AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Arab Emirates Drug Delivery Devices Market Evolving Landscape
Three interconnected developments are restructuring competitive positioning in UAE drug delivery: materials science advancement, regulatory workflow digitization, and ambulatory care model expansion. These forces collectively favor suppliers capable of integrating hardware precision with connected health infrastructure.
Smart injector platforms incorporating Bluetooth-enabled dose tracking are converging with hospital electronic health record systems, enabling real-time adherence monitoring. Dubai Health Authority-affiliated facilities are piloting these integrations at scale, with procurement committees now specifying interoperability requirements in tender documents. This convergence is compressing competitive differentiation toward software-layer capabilities rather than hardware specifications alone.
MOHAP's implementation of blockchain-tracked device registration is streamlining conformity assessment documentation, reducing processing friction for ISO 13485-certified suppliers. The reform mandates tamper-evident supply chain records for Class II and III devices, with pilot programs operational for infusion pump imports through Dubai's Jebel Ali port. Manufacturers with pre-established digital documentation systems are capturing accelerated approval timelines relative to paper-dependent competitors.
Patient-administered therapy models are displacing clinic-based injection protocols in rheumatology and multiple sclerosis treatment plans, restructuring demand toward disposable auto-injectors with simplified user interfaces. Abu Dhabi's health insurance authority is revising reimbursement codes to favor home administration where clinical equivalence is demonstrated. This behavioral shift concentrates margin capture among suppliers offering comprehensive patient training programs alongside device delivery.
United Arab Emirates Drug Delivery Devices Market Segmentation
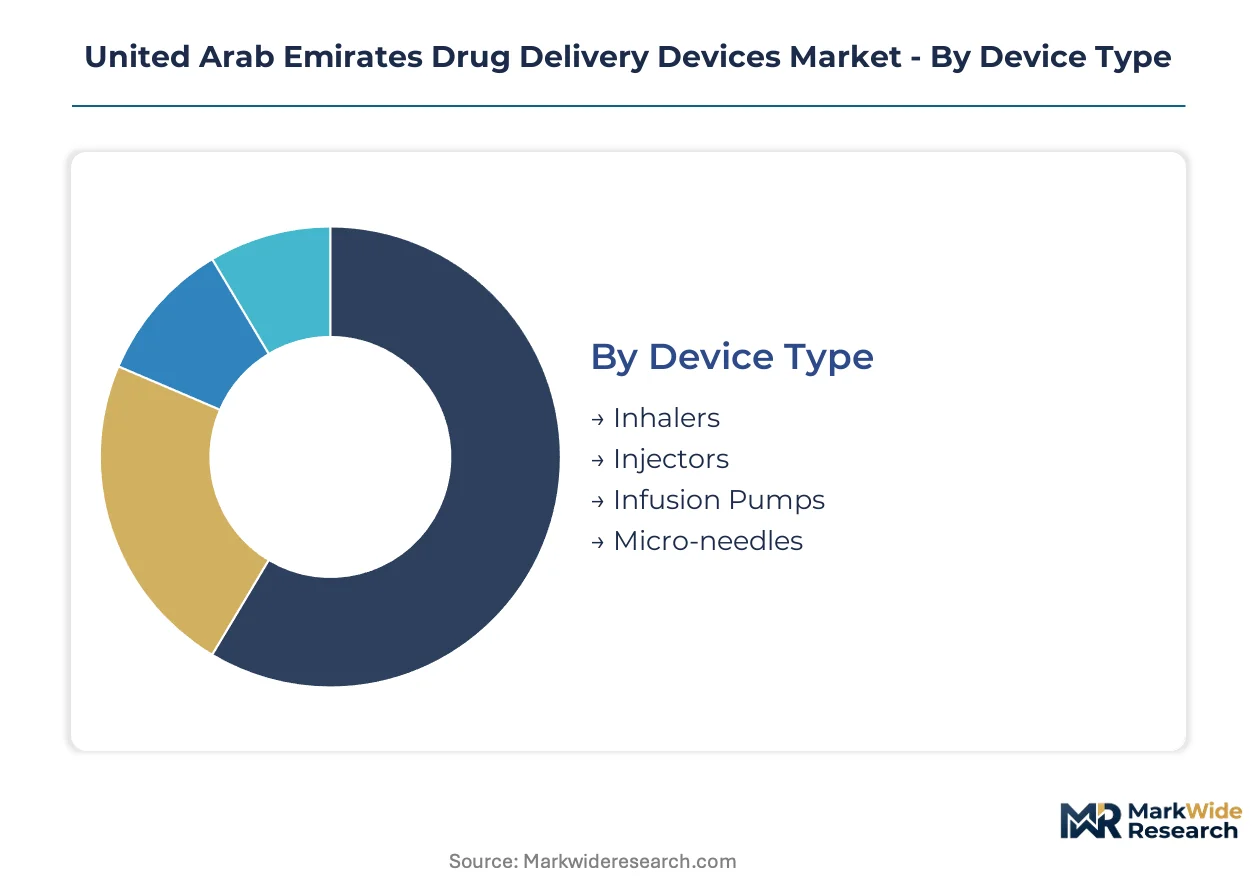
Segmentation in UAE drug delivery devices reflects divergent procurement pathways across Dubai's tertiary hospitals and Northern Emirates' emerging facilities. Device specifications, reimbursement codes, and MOHAP registration tiers fragment demand patterns across end-use channels.
Device Type:
Hospital procurement committees prioritize flow precision and ISO 10993 compliance when selecting devices for patient-contact applications.
- Injectors:These systems administer therapeutic agents through subcutaneous or intramuscular routes with dose accuracy within ±5% variance. Dubai Health Authority-affiliated facilities anchor procurement volumes for auto-injectors targeting oncology and diabetes protocols, with biocompatible polymer housings displacing conventional plastics.
- Infusion Pumps:Programmable devices deliver fluids at controlled rates through intravenous or epidural pathways. Tertiary facilities across the Emirates expand adoption for chemotherapy and pain management applications, though supply chains for precision pump components remain concentrated among European specialty manufacturers.
- Inhalers:Pressurized metered-dose devices and dry powder inhalers serve respiratory therapeutic delivery.
- Micro-needles:Arrays of micron-scale projections enable transdermal drug administration with reduced tissue trauma.
Injectors lead on scale; micro-needles lead on momentum.
End User:
Reimbursement framework evolution is redistributing margin capture across institutional and ambulatory channels.
- Hospitals:Tertiary and secondary acute care facilities administer complex therapies requiring continuous monitoring. Dubai's healthcare corridor concentrates procurement volumes for infusion pump systems, with MOHAP's medical device registration reforms compressing market access timelines for approved suppliers.
- Homecare Settings:Patient-administered therapy models demand simplified user interfaces and remote monitoring capabilities. Abu Dhabi's health insurance authority revises reimbursement codes to favor home administration where clinical equivalence is demonstrated, restructuring demand toward disposable auto-injectors.
- Clinics:Outpatient facilities deliver routine injections and infusion therapies.
- Long-term Care Facilities:Residential care centers manage chronic medication regimens for elderly populations.
Hospitals dominate current procurement volumes; homecare settings are expanding most quickly.
Technology:
Digital health infrastructure integration is becoming a mandatory tender specification for advanced delivery platforms.
- Smart Delivery Systems:Bluetooth-enabled devices with dose tracking and electronic health record interoperability. Dubai Health Authority-affiliated facilities pilot these integrations at scale, with procurement committees now specifying software-layer capabilities alongside hardware specifications.
- Wearable Devices:Ambulatory platforms enabling continuous therapeutic delivery and remote patient monitoring. These systems capture protocol adoption in diabetes management applications across the Emirates, with continuous glucose monitoring interfaces converging with insulin pump ecosystems.
- Needle-free Technologies:Jet injectors and other non-invasive administration methods.
- Biodegradable Devices:Implants and delivery systems designed for absorption or safe degradation post-administration.
Smart delivery systems command premium positioning; wearable devices gain share fastest.
Application:
Disease prevalence patterns and treatment protocol standardization shape device specification requirements across therapeutic areas.
- Diabetes Management:Insulin delivery systems and glucose monitoring interfaces dominate ambulatory care procurement. Closed-loop delivery systems are emerging as technology converges between continuous monitoring and pump ecosystems, with patient-administered models displacing clinic-based protocols.
- Oncology:Chemotherapy administration requires precision infusion with programmable flow control and tamper-evident safety features. Tertiary facilities specify these capabilities in tender documents, though viscosity thresholds for high-concentration biologics constrain adoption of needle-free alternatives.
- Pain Management:Patient-controlled analgesia and epidural delivery systems.
- Cardiovascular Treatments:Infusion therapies for acute cardiac events and chronic heart failure management.
Diabetes management leads on addressable volume; oncology leads on specification intensity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai's healthcare corridor concentrates procurement volumes for advanced infusion systems, with tertiary facilities anchoring demand across the Emirates. MOHAP's regulatory reforms are redistributing market access toward ISO 13485-certified suppliers while Northern Emirates infrastructure expansion creates new addressable channels.
Dubai
Dubai Health Authority-affiliated facilities drive procurement for smart injectors and wearable delivery platforms. MOHAP's blockchain-tracked device registration pilot at Jebel Ali port accelerates approval timelines for digitally documented suppliers. Dubai Healthcare City clusters specialist distributors serving oncology and diabetes management protocols.
Abu Dhabi
Abu Dhabi's health insurance authority revises reimbursement codes to favor home administration models for patient-administered therapies. The emirate's private insurance networks pilot direct-to-patient subscription models for consumable injector supplies. Cleveland Clinic Abu Dhabi and Sheikh Khalifa Medical City anchor tertiary procurement volumes.
Sharjah
Sharjah's expanding healthcare infrastructure creates first-mover positioning for smart injector distributors targeting underpenetrated tertiary capacity. The emirate's medical device import pathways align with GCC harmonized technical regulations, streamlining conformity assessments for multinational suppliers. University Hospital Sharjah anchors procurement for precision infusion systems.
Ras Al Khaimah
Ras Al Khaimah's emerging hospital networks generate demand for cost-optimized auto-injector platforms serving chronic disease management. The emirate's healthcare investment authority prioritizes devices with simplified user interfaces for limited technical specialist availability. Saqr Hospital anchors public sector procurement volumes.
Northern Emirates
Fujairah and Umm Al Quwain healthcare facilities rely on distributor networks radiating from Dubai and Sharjah for device procurement. MOHAP's centralized registration system enables market access without redundant conformity assessments across these smaller emirates. Clinic-based diabetes management drives ambulatory device demand.
United Arab Emirates Drug Delivery Devices Market Competitive Landscape
Global majors compete with regional champions across distribution reach and regulatory navigation capabilities. The vendor base stratifies between scale-driven pharmaceutical conglomerates with integrated device portfolios and specialized medical technology firms with ISO 13485-certified manufacturing partnerships. Three archetypes dominate: diversified healthcare conglomerates leveraging brand equity, pure-play device specialists with software-layer differentiation, and regional distributors with MOHAP relationship depth. Competitive moves concentrate on strategic partnerships with Dubai Health Authority-affiliated facilities and technology licensing for connected health interoperability.
Within the diversified healthcare conglomerate tier, Becton, Dickinson and Company and Johnson & Johnson occupy positions anchored by manufacturing scale and homecare channel strength respectively. Roche Holding AG exemplifies the R&D-intensive specialist archetype targeting diabetes management protocols. These three entities represent distinct competitive vectors: supply contract leverage, patient training program differentiation, and smart delivery system innovation.
| Leading Market Players |
|---|
| AstraZeneca PLC |
| Bayer AG |
| Merck KGaA |
| GlaxoSmithKline PLC |
| Becton, Dickinson and Company |
| Johnson & Johnson |
| Pfizer Inc |
| Roche Holding AG |
| Novartis AG |
| Others |
Value Network & Pricing Analysis
Biocompatible polymer substitution in infusion pump housings simultaneously elevates material costs and concentrates procurement leverage among ISO 10993-certified European compounders, reshaping margin structures for domestic assemblers across the Emirates. This materials transition forces device manufacturers to absorb upstream cost pass-through or cede share to vertically integrated multinational suppliers.
Pricing Analysis
Input-cost pass-through from biocompatible polymer feedstocks and precision pump components anchors pricing dynamics, with three-tier pricing structure across premium, standard, and economy levels separating Dubai Health Authority-affiliated facilities from Northern Emirates public hospitals and homecare channels. Certification grade and volume scale drive price differentiation, with ISO 13485-certified suppliers commanding premium positioning. Pricing pressure stems from reimbursement code compression for needle-free technologies as MOHAP expands its priority medical device list. Northern Emirates public hospitals exhibit highest price sensitivity; Dubai tertiary facilities demonstrate lowest.
Supply Chain Analysis
Direct-to-hospital channels handle demand from Dubai Health Authority-affiliated facilities, while distributor networks radiating from Dubai and Sharjah serve Northern Emirates and homecare segments. Supply chains for precision pump components and biocompatible polymers concentrate in Germany, Switzerland, and the United States, with specialty manufacturers anchoring upstream tiers. Raw material dependencies center on medical-grade polymers, precision-machined metals, and electronic control modules. Single-source vulnerability in European precision component supply creates structural risk. Distribution runs through authorized distributor networks with MOHAP registration requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE drug delivery devices market functions as a regulatory compounder, with MOHAP's blockchain-tracked device registration reform accelerating approval timelines and redistributing competitive advantage toward digitally documented suppliers.
For Market Incumbents: Deploy backward integration into biocompatible polymer compounding to secure input-cost stability against European supply concentration. Consolidate procurement relationships with Dubai Health Authority-affiliated facilities through software-layer differentiation and electronic health record interoperability. Threats include emerging pure-play device specialists capturing share via connected health capabilities and reimbursement code shifts favoring homecare channels. For New Entrants and Emerging Players: Bluetooth-enabled dose tracking platforms offer technology-first positioning against hardware-centric incumbents. White-space targets concentrate in Sharjah and Ras Al Khaimah tertiary capacity expansion, with simplified user interfaces addressing technician scarcity constraints. Direct-to-patient subscription models for consumable injector supplies in Abu Dhabi's private insurance networks provide the most penetrable go-to-market angle. For Investors and Strategic Acquirers: Valuations sit cheapest among regional distributors with MOHAP relationship depth and ISO 13485-certified manufacturing partnerships. Long-term viability hinges on software-layer differentiation and connected health infrastructure integration. Acquisition targets center on pure-play device specialists with closed-loop delivery system capabilities. Watch reimbursement code revisions for home administration as the inflection indicator.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 13485 Certification Investment | Accelerates MOHAP market access timelines against paper-dependent competitors. |
| Hospital System Partnership | Dubai Health Authority affiliations anchor procurement volumes for smart injectors. |
| Software Companion Development | Bluetooth-enabled dose tracking meets tender interoperability requirements. |
| Reimbursement Strategy | Alignment with Abu Dhabi home administration code revisions captures margin expansion. |
| Geographic Expansion | Sharjah and Ras Al Khaimah tertiary capacity creates first-mover positioning. |
Research Methodology
Coverage spans Dubai, Abu Dhabi, Sharjah, and Northern Emirates, with primary inputs from each emirate's healthcare infrastructure. The analysis combines structured interviews with hospital procurement managers, biomedical engineers, GPO contracts managers, and regulatory affairs specialists with secondary validation from MOHAP registration databases, Dubai Health Authority tender documents, hospital procurement records, and GCC harmonized technical regulations. Bottom-up demand modeling triangulates against top-down market sizing across device type, end user, technology, and application dimensions.
Rate-of-change decomposition separates volume growth from price evolution across the analysis window. Segmentation dimensions modeled include device type, end-user channel, technology tier, and therapeutic application, with regional regulatory cluster as an additional cross-cutting dimension. CAGRs derive from fitted growth curves applied to base-year estimates, stress-tested against MOHAP registration throughput data and hospital capital expenditure disclosures. Industry-specific inputs include infusion pump adoption rates in tertiary facilities and homecare reimbursement code evolution.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to MOHAP priority device list revisions and GCC harmonization alignment with Saudi SFDA timelines. Forecasts reflect documented assumptions regarding reimbursement framework evolution and materials science advancement trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Italy Ultrasound Devices Market
Medical Devices
Europe Nurse Call Systems Market
Medical Devices
Global Photobiostimulation Market
Medical Devices
Organ Preservation Solutions Market
Medical Devices
Scoliosis Traction Chairs Market
Medical Devices
Thoracolumbar Spine Devices Market
Medical Devices
Veterinary Radiography Flat Panel Detectors Market
Medical Devices
Elbow Fixation Systems Market
Medical Devices
Ambulatory Aids Market
Medical Devices
Left Atrial Appendage Devices Market
Medical Devices
Defibrillator Pads Market
Medical Devices
Global on-Body Injectors Market
Medical Devices
Vortex Mixer Market
Medical Devices
Global Smart Implantable Pumps Market
Medical Devices
Arteriovenous Fistula Devices Market
Medical Devices
Pocket Ventilation Systems Market