
 Global Artificial Organ and Bionic Implants Market | 2026-2036
Global Artificial Organ and Bionic Implants Market Size, Share, and Industry Trends Forecast 2026-2036
Global Artificial Organ and Bionic Implants Market Foresight
CE marking under the EU Medical Device Regulation is reorganizing competitive access for implantable device manufacturers. Medtronic plc leverages its vertically integrated cardiac rhythm portfolio to sustain manufacturing scale across European notified body jurisdictions. Boston Scientific Corporation anchors its position through specialized renal denervation systems that navigate FDA premarket approval pathways.
Artificial organs and bionic implants comprise electromechanical or biological substitutes engineered to restore physiological functions lost to disease, trauma, or congenital defects, typically incorporating biocompatible alloys, polymers, or living tissue constructs fabricated through additive manufacturing or semiconductor microfabrication. These devices serve commercial healthcare systems by reducing transplant waiting lists and enabling outpatient management of chronic organ failure. Cardiac Devices occupy the largest revenue pool given established reimbursement for ventricular assist systems, while Neural Interfaces represent the fastest-expanding segment as brain-computer interface protocols advance toward commercialization. Bioelectronics technology concentrates margin capture through proprietary signal processing architectures that differentiate premium-tier offerings from standard implantable pulse generators.
FDA premarket approval requirements and EMA MDR conformity assessments shape product development timelines and clinical evidence burdens for manufacturers seeking multi-jurisdictional market access. The EU AI Act introduces additional algorithmic transparency obligations for closed-loop bionic systems that integrate machine learning for adaptive stimulus delivery. Stakeholders must monitor evolving notified body capacity constraints in Europe and emerging CMS coverage determinations for autonomous neural implants in the United States.
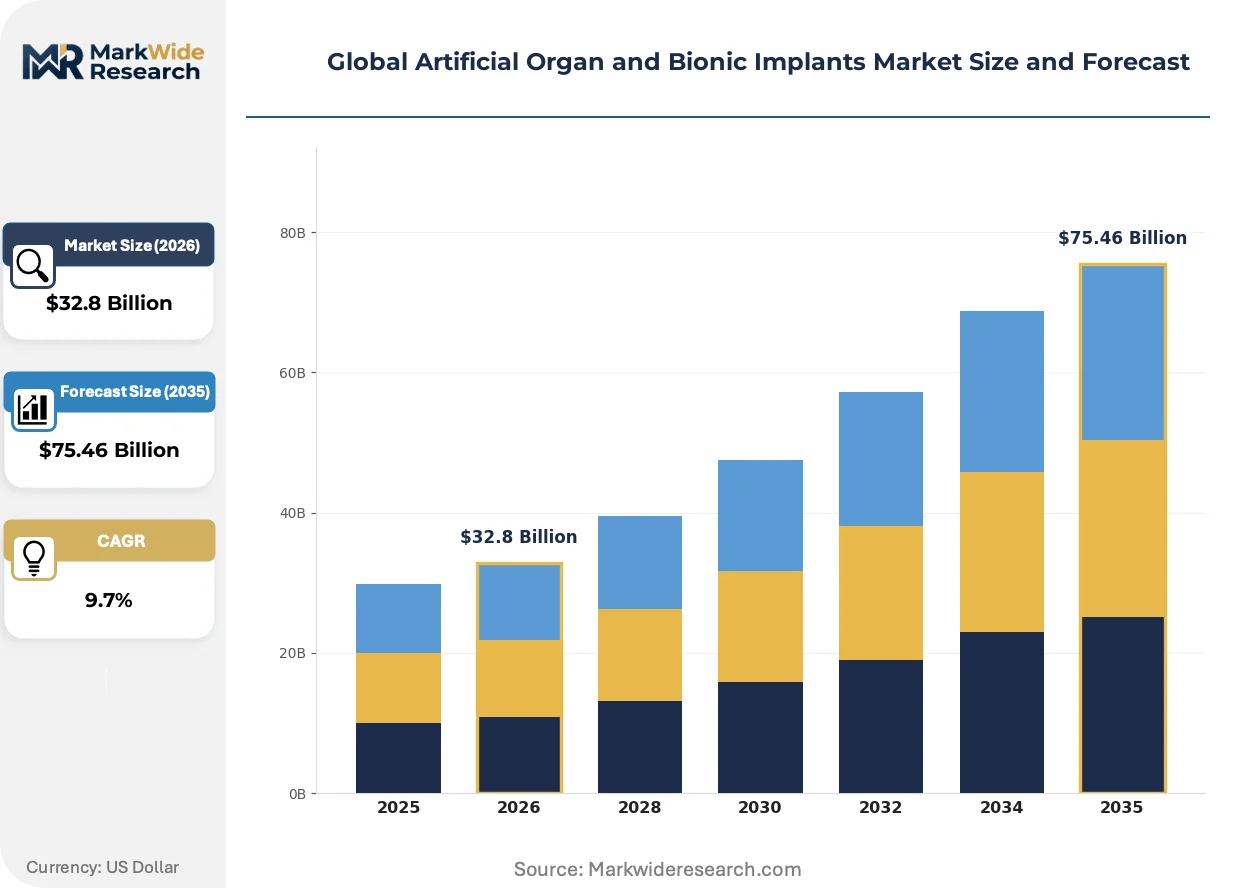
Market Dynamics
FDA and EMA regulatory convergence on biocompatibility testing is compressing product development timelines while Medicare reimbursement pathways for neural interfaces mature fastest in the United States, creating asymmetric competitive access across jurisdictions.
Growth Catalysts
- EMA MDR conformity assessments:Streamlined CE marking pathways accelerate European market entry for implantable cardiac devices, reducing notified body bottlenecks for manufacturers with established quality systems.
- Additive manufacturing of titanium lattice structures:Orthopedic bionic manufacturers leverage electron beam melting to produce patient-matched craniofacial implants with reduced lead times and improved osseointegration surfaces.
- German hospital procurement expansion:Rising patient volumes for heart failure interventions drive cardiac bionic device purchasing, particularly for ventricular assist systems and implantable cardioverter defibrillators.
Market Restraints
- Palladium and platinum price volatility:Precious metal electrode coatings in neural interfaces face input cost swings that squeeze gross margins on standard-tier implantable pulse generators.
- Notified body capacity constraints:European MDR transition has consolidated assessment resources to fewer designated bodies, creating queue bottlenecks for Class III implantable submissions.
- Biological organ transplantation:Improved immunosuppression protocols and expanded donor pools in Spain and the United States limit addressable market for total artificial heart replacements.
Strategic Opportunities
- Brain-computer interface commercialization:Adaptive stimulus delivery systems integrating machine learning for closed-loop control open premium pricing tiers in motor prosthetics and neurorehabilitation.
- CMS coverage determinations for autonomous neural implants:Emerging reimbursement codes in the United States create first-mover advantage for manufacturers with clinical evidence packages.
- Bioresorbable electronics convergence:Temporary cardiac pacing and neural monitoring applications that eliminate secondary extraction surgeries address unmet needs in pediatric and trauma populations.
Industry Challenges
- Clinical evidence generation timelines:Longitudinal safety studies for permanent implants require decade-long follow-up periods that strain R&D budgets and delay regulatory submissions.
- Algorithmic transparency obligations:EU AI Act mandates for explainable machine learning in adaptive bionic systems force architectural redesigns of proprietary signal processing architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Artificial Organ and Bionic Implants Market |
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $75.46 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cardiac Devices, Renal Implants, Cochlear Implants, Retinal Prosthetics, Neural Interfaces Application Area: Organ Failure Management, Sensory Restoration, Neurological Disorders, Musculoskeletal Repair, Endocrine Replacement End User: Specialty Hospitals, Rehabilitation Centers, Research Institutes, Outpatient Clinics, Diagnostic Laboratories Technology: Biocompatible Materials, Nanotechnology, 3D Printing, Microelectromechanical Systems, Bioelectronics |
| Companies Covered | Medtronic plc, Boston Scientific Corporation, Zimmer Biomet Holdings Inc., Edwards Lifesciences Corporation, Abiomed Inc., Cochlear Limited, Ekso Bionics Holdings Inc., Abbott Laboratories, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Artificial Organ and Bionic Implants Market Shifts & Advancements
Signal processing architectures are differentiating premium-tier neural interfaces from commodity implantable pulse generators, while regulatory frameworks for algorithmic medical devices reshape competitive positioning across Atlantic jurisdictions.
Organic electrochemical transistors are decomposing traditional rigid electrode arrays in cortical neural interfaces. Academic medical centers in Switzerland and the United States are piloting soft polymer-based recording devices for epilepsy monitoring. This materials shift is decomposing the historical barrier between diagnostic and therapeutic implantable categories, enabling single-device platforms that toggle between sensing and stimulation modes.
EU AI Act algorithmic transparency requirements are mandating explainability documentation for closed-loop bionic systems that adapt stimulus parameters through machine learning. Manufacturers must now submit technical files detailing decision-tree logic for adaptive cardiac resynchronization and deep brain stimulation devices. Neural interface developers with European market ambitions are restructuring firmware architectures to satisfy these obligations ahead of 2026 enforcement deadlines.
Hospital value analysis committees are consolidating purchasing authority for high-cost implantable devices, displacing traditional physician-directed procurement. Integrated delivery networks in the United States now mandate standardized vendor contracts across cardiac rhythm management portfolios. This concentration is most visible in Medicare Advantage–dominated markets where capitated reimbursement incentivizes volume commitments in exchange for pricing concessions.
Global Artificial Organ and Bionic Implants Market Segmentation
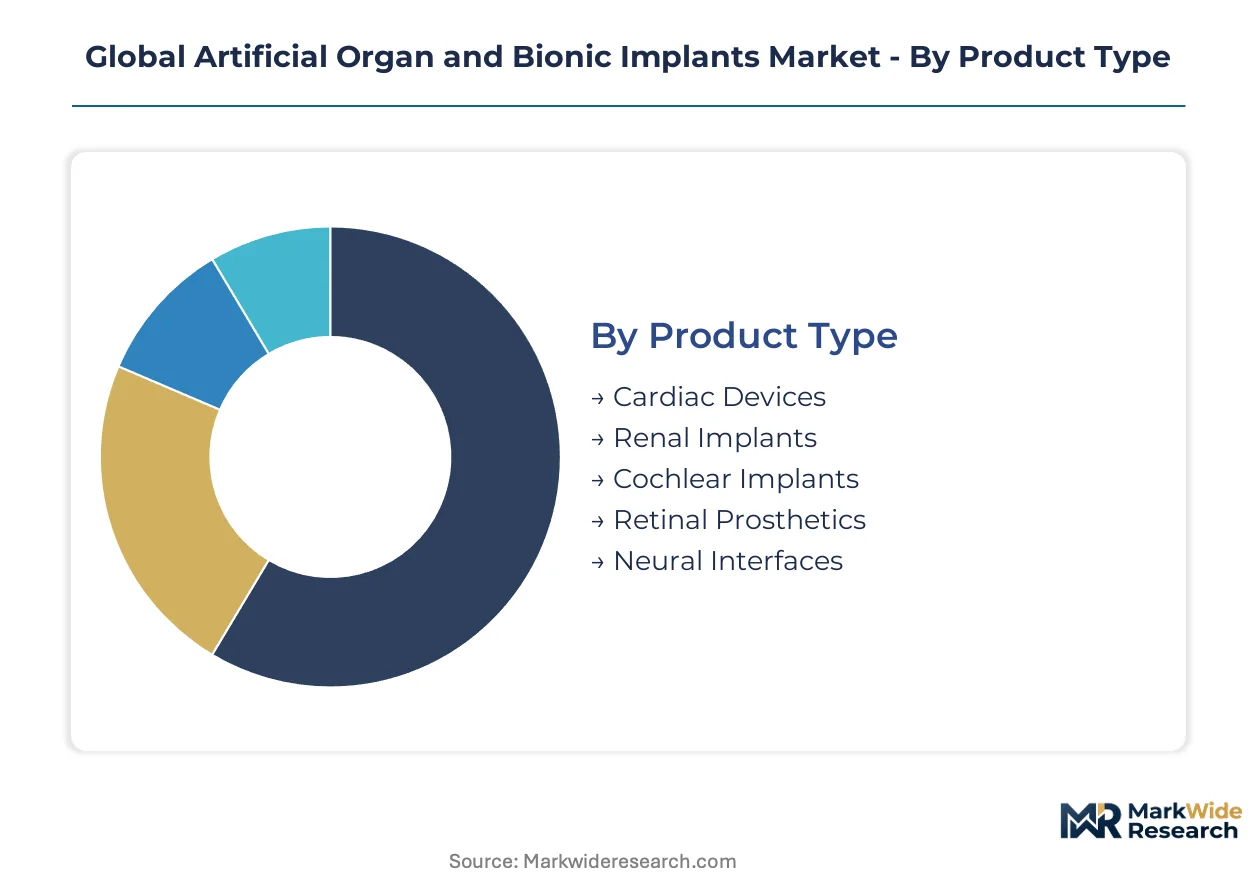
Segmentation in artificial organs and bionic implants reveals how substitution pressures from biological transplants and pharmaceutical alternatives reshape commercial viability across device categories. Product-level differentiation increasingly hinges on signal processing sophistication and materials innovation rather than mechanical function alone.
Product Type:
Cardiac Devices face the most acute substitution pressure from improved donor organ availability and mechanical circulatory support alternatives, while Neural Interfaces confront minimal biological substitute competition due to irreversible neuronal damage in target populations.
- Cardiac Devices:Electromechanical systems including ventricular assist devices and implantable cardioverter defibrillators fabricated from titanium alloys and biocompatible polymers. German hospitals are expanding procurement of these systems as heart failure patient volumes rise, though improved immunosuppression protocols in Spain and the United States constrain total addressable market for total artificial heart replacements.
- Neural Interfaces:Cortical and peripheral electrode arrays integrating semiconductor microfabrication with bioelectronic signal processing architectures. Demand is concentrating in the United States where Medicare reimbursement pathways for brain-computer interfaces mature fastest, enabling closed-loop adaptive stimulus delivery for motor prosthetics.
- Renal Implants:Hemofiltration membranes and wearable artificial kidney systems addressing end-stage renal disease.
- Cochlear Implants:Multichannel electrode arrays restoring auditory function through direct cochlear nerve stimulation.
- Retinal Prosthetics:Subretinal and epiretinal electrode systems targeting photoreceptor degeneration disorders.
Cardiac Devices anchor the volume base while Neural Interfaces gain share at the steepest rate.
Application Area:
Cost tier stratification separates acute intervention applications commanding premium pricing from chronic management categories facing reimbursement compression.
- Organ Failure Management:Cardiac, renal, and pulmonary replacement systems addressing life-threatening physiological collapse. Specialty hospitals in Germany drive procurement concentration for ventricular assist systems as bridge-to-transplant and destination therapy protocols expand.
- Neurological Disorders:Deep brain stimulation and responsive neurostimulation targeting Parkinson's disease, epilepsy, and treatment-resistant depression. The United States dominates demand concentration as FDA premarket approval pathways for autonomous neural implants advance toward commercial reimbursement codes.
- Sensory Restoration:Auditory and visual prosthetic systems restoring lost sensory modalities.
- Musculoskeletal Repair:Orthopedic bionic implants including patient-matched craniofacial reconstructions.
- Endocrine Replacement:Artificial pancreas systems and closed-loop insulin delivery devices.
Organ Failure Management generates the highest absolute expenditure while Neurological Disorders shows the steepest expansion trajectory.
End User:
Procurement authority concentration within integrated delivery networks is displacing traditional physician-directed purchasing across all facility types.
- Specialty Hospitals:Tertiary cardiac and neuroscience centers performing complex implantation procedures. These facilities concentrate demand for premium-tier devices with proprietary signal processing architectures that differentiate from standard implantable pulse generators.
- Rehabilitation Centers:Post-acute facilities managing neural interface programming and motor prosthetic training. German rehabilitation networks are expanding capacity for brain-computer interface neurorehabilitation as adaptive stimulus delivery protocols advance.
- Research Institutes:Academic medical centers conducting clinical trials for novel bionic systems.
- Outpatient Clinics:Ambulatory settings managing chronic device surveillance and battery replacement.
- Diagnostic Laboratories:Facilities performing biocompatibility testing and device explant analysis.
Specialty Hospitals command the highest device acuity while Rehabilitation Centers expand most quickly as neural interface commercialization accelerates.
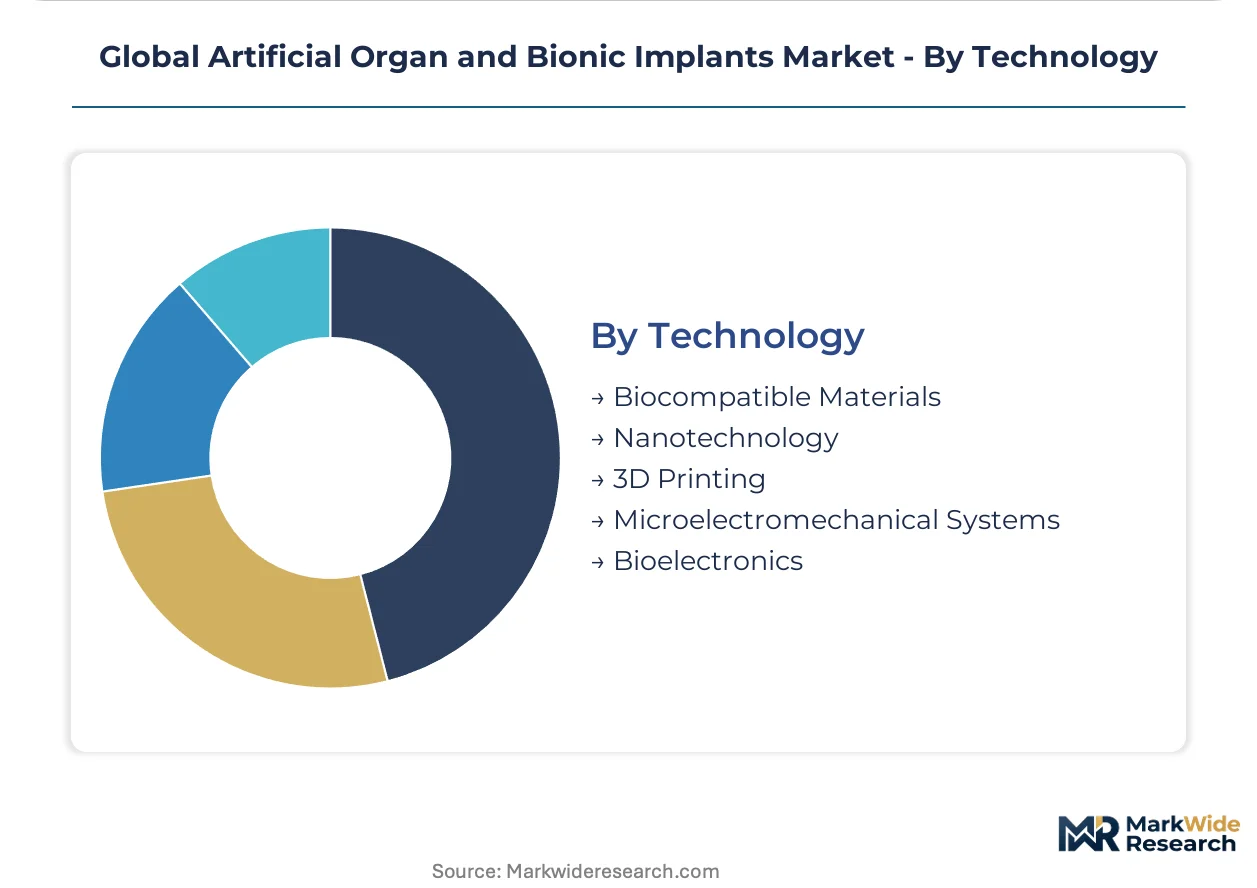
Technology:
Supply concentration in semiconductor microfabrication and additive manufacturing equipment shapes competitive access to advanced technology tiers.
- Bioelectronics:Proprietary signal processing architectures and closed-loop control systems integrating machine learning for adaptive stimulus delivery. FDA and EMA regulatory convergence on biocompatibility testing compresses development timelines for manufacturers with established quality systems, while EU AI Act algorithmic transparency obligations force firmware architectural redesigns.
- 3D Printing:Electron beam melting and selective laser sintering producing patient-matched titanium lattice structures. Orthopedic bionic manufacturers leverage these techniques for craniofacial implants with improved osseointegration surfaces.
- Biocompatible Materials:Titanium alloys, platinum-iridium electrodes, and medical-grade polymers.
- Nanotechnology:Surface modification techniques enhancing electrode-tissue interfaces.
- Microelectromechanical Systems:Miniaturized sensors and actuators for implantable diagnostic platforms.
Bioelectronics captures the highest margin tier while 3D Printing is scaling fastest through reduced lead times and personalized geometry capabilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital procurement committees in Germany, Medicare Advantage networks in the United States, and academic medical centers in Switzerland concentrate purchasing authority for high-acuity implantable devices.
United States
CMS coverage determinations for autonomous neural implants are maturing fastest here, creating first-mover advantage for manufacturers with clinical evidence packages. FDA premarket approval pathways for brain-computer interfaces compress development timelines for closed-loop adaptive systems. The Boston-Cambridge corridor anchors neurotechnology R&D concentration with specialized venture capital backing.
Germany
Specialty hospitals are expanding procurement of cardiac bionic devices as heart failure patient volumes rise, particularly for ventricular assist systems. EMA MDR conformity assessments under the EU Medical Device Regulation reorganize competitive access for implantable device manufacturers. The Rhine-Main cluster around Frankfurt concentrates notified body assessment capacity for Class III cardiac submissions.
Switzerland
Academic medical centers in Zurich and Geneva pilot soft polymer-based neural recording devices for epilepsy monitoring, decomposing traditional rigid electrode arrays. Swissmedic regulatory pathways for algorithmic medical devices align with EU AI Act transparency obligations. The Lake Geneva region hosts specialized microfabrication facilities serving cortical interface developers.
Japan
PMDA accelerated approval pathways for regenerative medical products enable faster market entry for bioresorbable cardiac pacing applications. METI funding programs support domestic development of brain-computer interface protocols for motor prosthetics. The Kansai region around Osaka maintains concentration in precision polymer processing for implantable enclosures.
United Kingdom
NHS England value-based procurement frameworks for cardiac rhythm management consolidate purchasing authority across integrated care systems. MHRA post-Brexit regulatory divergence from EMA MDR creates parallel submission requirements for multi-jurisdictional manufacturers. The Oxford-Cambridge arc concentrates neural interface translation research with specialized health technology assessment expertise.
Global Artificial Organ and Bionic Implants Market Competitive Landscape
Player mix skews toward diversified medical technology conglomerates with vertically integrated cardiac rhythm portfolios alongside specialized neurotechnology developers. Market structure exhibits tiered concentration with premium-tier signal processing architectures differentiating from standard implantable pulse generators. Strategic archetypes include scale-driven cardiac device manufacturers, adaptive neural interface specialists, and orthopedic additive manufacturing pioneers. Dominant competitive moves encompass portfolio diversification into closed-loop bioelectronics and strategic partnerships for algorithmic transparency compliance.
Within the diversified conglomerate tier, Medtronic plc and Boston Scientific Corporation exemplify scale-driven positioning across cardiac and neural verticals. Medtronic leverages vertically integrated manufacturing across European notified body jurisdictions. Boston Scientific anchors specialized positioning through renal denervation systems navigating FDA premarket approval pathways. Abbott Laboratories occupies a distinct position spanning vascular and neuromodulation portfolios with established quality systems for biocompatibility testing convergence.
| Leading Market Players |
|---|
| Medtronic plc |
| Boston Scientific Corporation |
| Zimmer Biomet Holdings Inc. |
| Edwards Lifesciences Corporation |
| Abiomed Inc. |
| Cochlear Limited |
| Ekso Bionics Holdings Inc. |
| Abbott Laboratories |
| Johnson & Johnson |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts with palladium and platinum indexation lock in electrode coating supplies for neural interface manufacturers while freezing gross margin visibility across quarterly procurement cycles. German hospital systems and United States Medicare Advantage networks exploit these structures to secure volume commitments for cardiac rhythm devices.
Pricing Analysis
Cost-plus contracts with London Metal Exchange indexation dominate raw material components, particularly platinum-iridium electrode coatings and titanium alloy feedstocks. Three-tier pricing structure across premium, standard, and economy levels separates proprietary signal processing architectures from commodity implantable pulse generators. Pricing pressure stems from palladium price volatility squeezing margins on standard-tier devices. Rehabilitation centers and outpatient clinics exhibit highest price sensitivity, while specialty hospitals prioritize performance tier over unit cost.
Supply Chain Analysis
Strait of Malacca transit underwrites precision polymer shipments from Japan to European microfabrication facilities serving neural interface developers. Semiconductor microfabrication concentrates in Taiwan, South Korea, and the United States; titanium alloy processing centers on Germany and Japan. The supply chain draws from platinum group metals, medical-grade silicone, and biocompatible polymer substrates. Single-source vulnerability in electron beam melting equipment creates procurement bottlenecks for patient-matched orthopedic implants. Distribution runs through integrated delivery networks consolidating purchasing authority across cardiac and neural device portfolios.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across reimbursement pathways and regulatory jurisdictions creates niche entry points for specialized players. Hospital value analysis committee consolidation simultaneously opens white-space opportunities in underserved geographies.
For Market Incumbents: Shield market position through captive supply of platinum-iridium electrode coatings and accelerated FDA premarket approval submissions for closed-loop neural systems. Bioresorbable electronics from specialized entrants threaten standard-tier implantable pulse generator margins. Backward integration into semiconductor microfabrication secures capacity for adaptive stimulus delivery architectures. For New Entrants and Emerging Players: Anchor in Swiss and United Kingdom academic medical centers piloting soft polymer neural recording devices for epilepsy monitoring. Brain-computer interface neurorehabilitation in German rehabilitation networks represents the most penetrable application segment. Partner with notified bodies early in EMA MDR conformity assessment pathways to compress European market entry timelines. For Investors and Strategic Acquirers: The market sits at a pre-consolidation phase that favors specialized neurotechnology developers with proprietary signal processing architectures over diversified cardiac device manufacturers. Five-to-ten year viability hinges on CMS coverage determination timing for autonomous neural implants. Watch FDA premarket approval pathway acceleration for brain-computer interfaces as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Premarket Approval Pathway | Accelerates commercialization timelines for closed-loop adaptive neural implants in United States markets. |
| CE Marking Pathway | Unlocks European market access for Class III implantable devices under EMA MDR conformity assessments. |
| Hospital System Partnership | Secures volume commitments through integrated delivery network procurement consolidation in Medicare Advantage regions. |
| Software Companion Development | Enables algorithmic transparency compliance with EU AI Act obligations for machine learning-integrated bionic systems. |
| Reimbursement Strategy | Captures first-mover advantage through CMS coverage determination navigation for autonomous neural implants. |
Research Methodology
Cross-validation between hospital procurement database analysis and FDA premarket approval filing review anchors the qualitative findings. Primary interviews with biomedical engineers, hospital purchasing committee members, GPO contracts managers, and regulatory affairs specialists at notified bodies inform demand-side and compliance dynamics. Secondary validation draws from CMS Medicare reimbursement data, EMA MDR submission records, ClinicalTrials.gov entries, and hospital procurement databases. Bottom-up device shipment modeling and top-down healthcare expenditure allocation triangulate market sizing.
Sensitivity analysis across palladium price volatility scenarios, notified body capacity constraints, and CMS coverage determination timelines tests forecast robustness. Segmentation modeling spans product type, application area, end user facility type, and technology tier across the projection horizon. CAGRs derive from longitudinal implant procedure volume trends and reimbursement pathway maturation patterns. Forecast inputs include German hospital cardiac device procurement expansion rates and United States Medicare Advantage network consolidation trajectories.
Decision-makers should treat outputs as directional under stable precious metal price and regulatory capacity assumptions; material deviation would warrant model refresh. Forecasts reflect base-case reimbursement pathway maturation and biocompatibility testing convergence between FDA and EMA. Biological organ transplantation advancement or algorithmic medical device regulatory restriction could revise projections. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Infusion Fluid Holder Market
Medical Devices
Inferior Vena Cava Filters Market
Medical Devices
Vascular Closure Device (VCD) Market
Medical Devices
Europe Single-Use Medical Device Reprocessing Market
Medical Devices
Global Acetabular Prostheses Market
Medical Devices
Surgical Loupes and Cameras Market
Medical Devices
Global Peripheral Vascular Devices and Accessories Market
Medical Devices
Global Scleral Lens Market
Medical Devices
Global Medical Composite Market
Medical Devices
Europe Smart Bed Market
Medical Devices
Infertility Treatment Devices Market
Medical Devices
Global Vascular Embolization Devices Market
Medical Devices
Neurostimulation Devices Market
Medical Devices
Syndesmosis Repair System Market
Medical Devices
3D Printing Medical Devices Market
Medical Devices
Chile Ultrasound Devices Market