
 Ultrasonic Electrosurgical Devices Market | 2026-2036
Ultrasonic Electrosurgical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Ultrasonic Electrosurgical Devices Market Intelligence
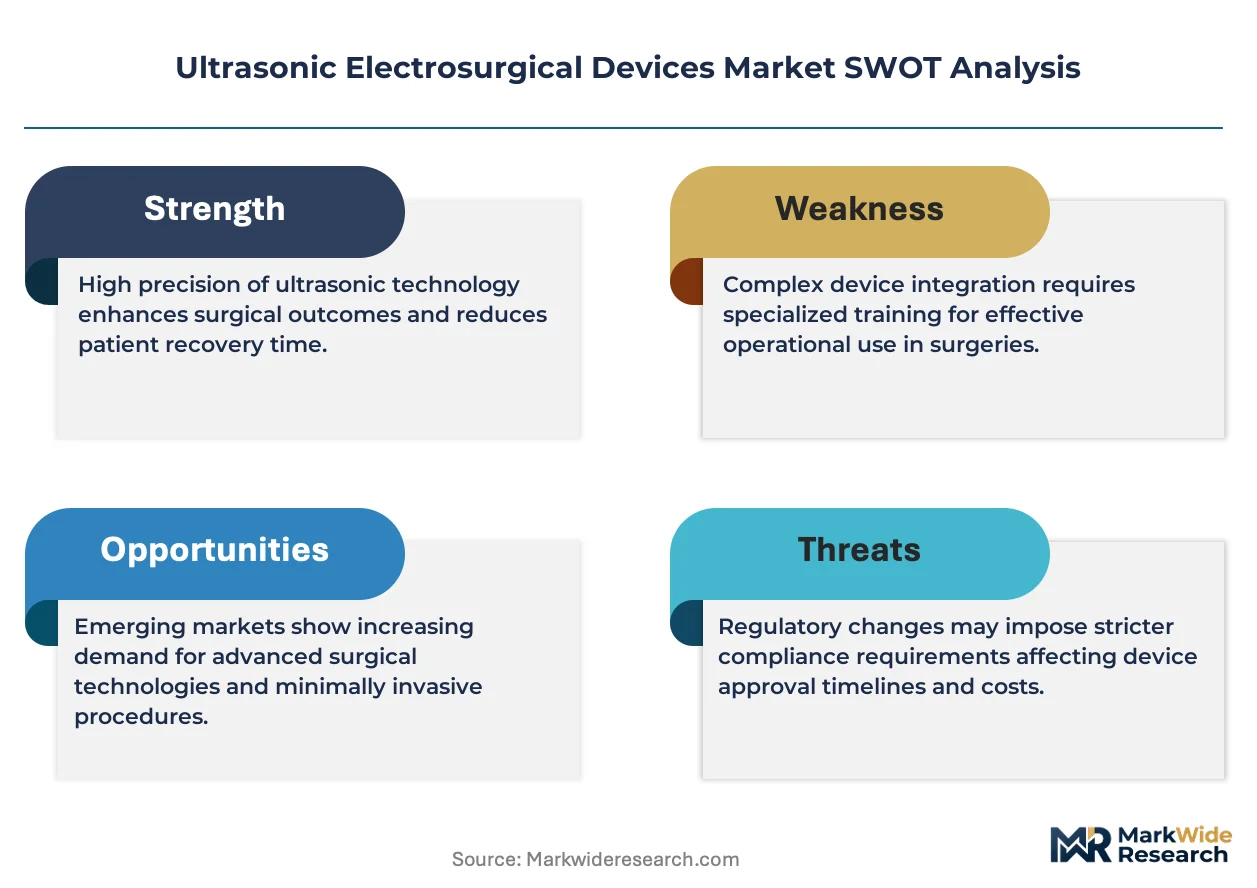
Leasing and pay-per-use financing is fragmenting competitive entry barriers in ultrasonic electrosurgical devices, allowing mid-tier hospitals to access premium systems without capital commitment. Olympus Corporation leverages its endoscopic integration expertise to bundle ultrasonic handpieces with visualization suites. Medtronic anchors its position through captive supply chains for generator electronics and disposable tips. Ethicon Endo-Surgery differentiates via proprietary blade geometries that reduce thermal spread during soft-tissue dissection.
Ultrasonic electrosurgical devices convert high-frequency electrical energy into mechanical vibrations, typically operating at 55.5 kHz, to cut and coagulate tissue through protein denaturation without electrical current passing through the patient. These systems serve minimally invasive and open procedures requiring precise hemostasis with minimal lateral thermal damage. Surgical handpieces capture the dominant margin pool due to recurring blade replacement cycles and sterilization-validated designs. General surgery applications lead volume adoption, while gynecological surgery represents the fastest-growing application segment as outpatient hysterectomy protocols expand. Advanced visualization technology increasingly fuses with ultrasonic platforms, creating integrated workflow solutions that command premium positioning.
FDA 510(k) clearance pathways govern market entry in the United States, while the EU Medical Device Regulation requires notified body certification and post-market surveillance for ultrasonic surgical equipment. ISO 13485 quality management standards and IEC 60601-1 electrical safety requirements shape manufacturing compliance across all major jurisdictions. Stakeholders must monitor evolving cybersecurity guidance for connected surgical generators and prepare for expanded clinical evidence requirements under harmonized international standards.
Market Dynamics
Leasing and pay-per-use financing is fragmenting competitive entry barriers in ultrasonic electrosurgical devices, allowing mid-tier hospitals to access premium systems without capital commitment. This structural shift is compressing traditional equipment sales cycles while expanding addressable facility bases.
Growth Catalysts
- EU Medical Device Regulation:The MDR tightens conformity requirements for ultrasonic energy platforms, accelerating replacement cycles for legacy systems that cannot meet enhanced clinical evidence standards.
- Ambulatory surgical centers:Outpatient procedure protocols are expanding across general surgery and gynecology, driving volume demand for compact, portable ultrasonic generators suited to clinic-based settings.
- Integrated visualization:Advanced imaging technology is fusing with ultrasonic platforms, creating premium workflow solutions that command higher per-procedure economics in integrated health networks.
Market Restraints
- Generator electronics supply:Captive supply chains for high-frequency power components concentrate among a limited supplier base, creating input cost volatility and allocation risk during semiconductor demand surges.
- 55.5 kHz frequency limitation:The standardized operating frequency constrains differentiation in tissue interaction profiles, compressing margin potential for hardware-only manufacturers.
- FDA 510(k) pathway:Substantial equivalence requirements for ultrasonic surgical equipment create regulatory friction for novel blade geometries and energy delivery modes.
Strategic Opportunities
- India:CDSCO regulatory harmonization with international standards is opening pathways for premium ultrasonic system entry as private hospital chains expand surgical capacity.
- Connected surgical generators:Cybersecurity-compliant device telemetry is enabling remote performance monitoring and predictive maintenance revenue streams.
- Disposable tip economics:Recurring blade replacement cycles in validated sterilization environments create annuity-like revenue pools for manufacturers with locked-in handpiece architectures.
Industry Challenges
- ISO 13485 quality management:Maintaining certified manufacturing systems across multiple jurisdictions requires sustained compliance investment as harmonized standards evolve.
- Legacy system integration:Hospital capital planning cycles delay full-platform upgrades, forcing backward compatibility engineering for mixed-generator fleets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ultrasonic Electrosurgical Devices Market |
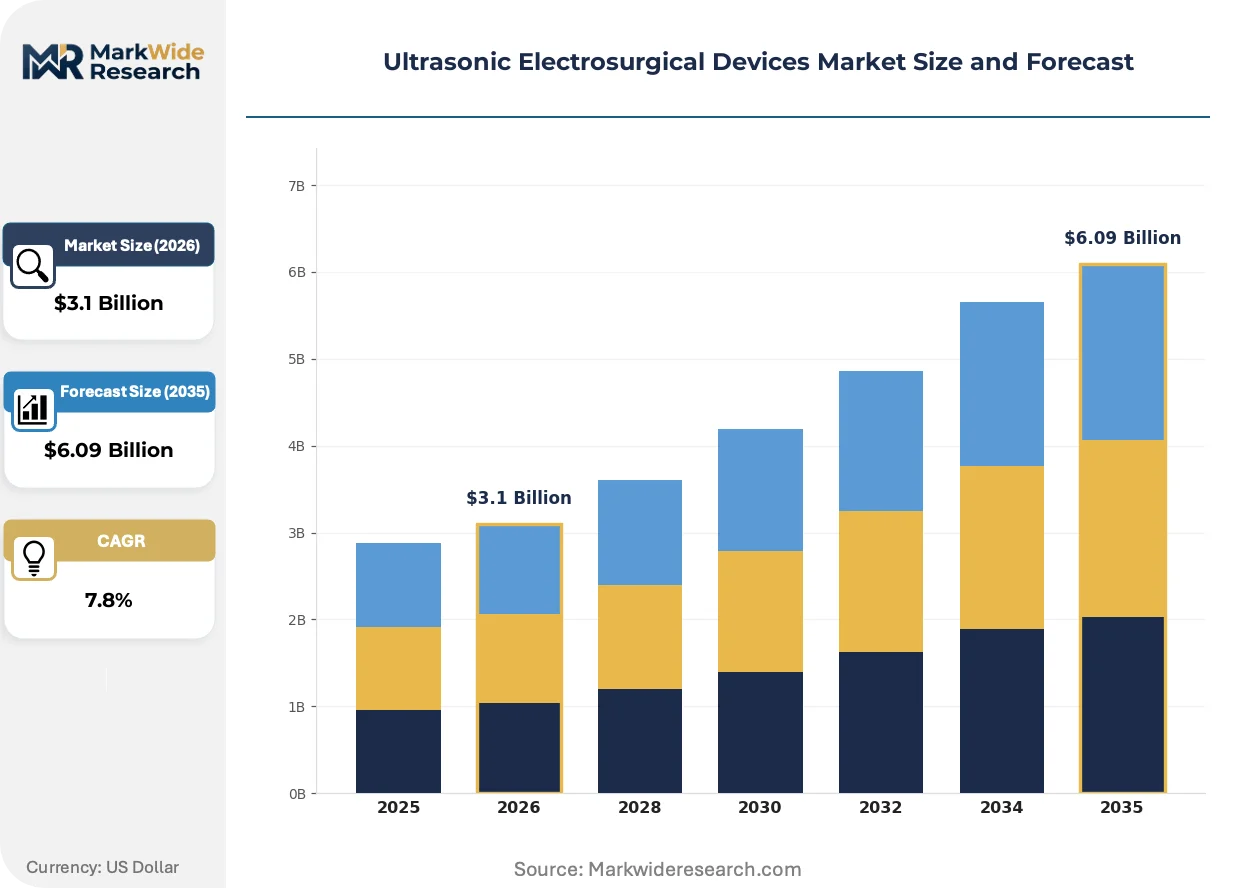
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $6.09 Billion |
| CAGR (2026 – 2036) | 7.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ultrasonic Generators, Electrode Probes, Surgical Handpieces, Accessories End User: Hospitals, Ambulatory Surgical Centers, Clinics, Research Institutions Application: General Surgery, Gynecological Surgery, Urological Surgery, Orthopedic Surgery Technology: Ultrasonic Technology, Thermal Control, Signal Processing, Advanced Visualization |
| Companies Covered | Ethicon Endo-Surgery, Olympus Corporation, Medtronic, Misonix Inc, BOWA-electronic GmbH, Söring GmbH, Advanced Instrumentations, Reach Surgical, Miconvey, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ultrasonic Electrosurgical Devices Market Strategic Shifts & Innovations
Digital workflow integration is actively reshaping competitive positioning in ultrasonic electrosurgical systems. Vendors are racing to embed intelligence into energy platforms while regulatory bodies tighten evidence requirements for connected devices.
Cloud-based surgical analytics is virtualizing post-operative outcome tracking. The technology aggregates tissue interaction data across procedure volumes. Academic medical centers in Germany and the United States are piloting these platforms for quality benchmarking. This capability is compressing the traditional service contract model toward software-subscription economics.
EU MDR post-market surveillance mandates now require systematic clinical follow-up for Class IIb surgical equipment. Manufacturers must maintain updated technical documentation and vigilance reporting across notified body jurisdictions. High-volume disposable tip suppliers face the steepest compliance cost escalation as batch traceability requirements expand.
Hospital procurement departments are unbundling after-sales service from capital equipment contracts. Third-party sterilization validation services and independent blade resupply channels are gaining share in the United States. This disintermediation is most visible in multi-hospital systems where centralized supply chain offices negotiate direct consumable agreements.
Ultrasonic Electrosurgical Devices Market Segmentation
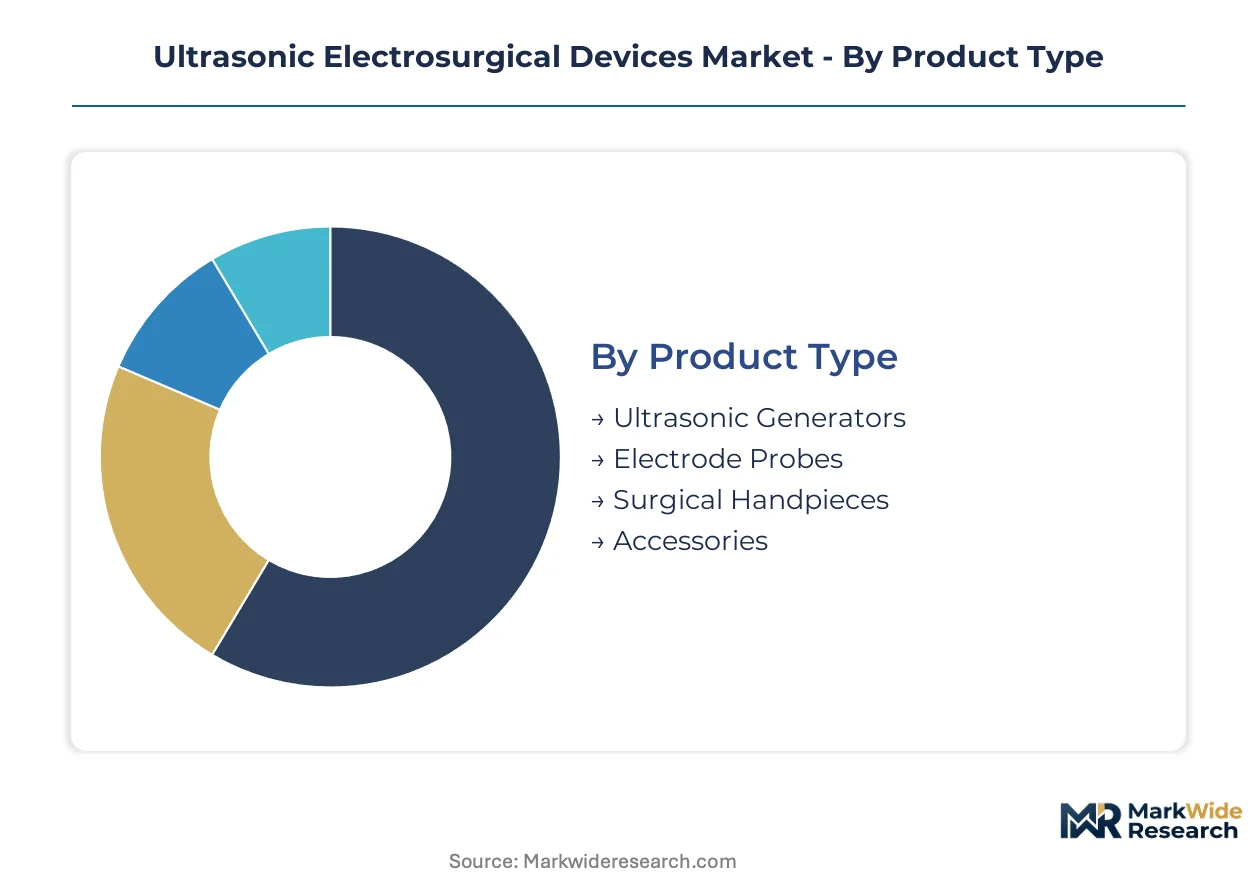
Ultrasonic electrosurgical devices fragment across four functional dimensions that determine procurement patterns and margin architecture. Product type governs capital versus consumable economics. End-user concentration shapes equipment portability requirements. Application specialization drives blade geometry differentiation. Technology integration defines premium positioning.
Product Type:
The use-case spectrum spans capital equipment with decade-long depreciation cycles to single-use consumables with recurring revenue profiles.
- Surgical Handpieces:These sterilization-validated instruments interface directly with tissue and lock hospitals into proprietary blade ecosystems. Demand concentrates in integrated US health networks where bulk sterilization contracts favor validated architectures. The recurring replacement cycle generates annuity-like revenue streams for manufacturers with captive tip designs.
- Ultrasonic Generators:High-frequency power electronics convert electrical energy to 55.5 kHz mechanical vibration. Procurement concentrates in Germany and Japan where academic medical centers prioritize advanced signal processing capabilities. Semiconductor supply constraints create allocation risk during demand surges.
- Electrode Probes:Specialized tips for tissue dissection and coagulation with application-specific geometries. Gynecological surgery protocols in France and the United Kingdom favor curved configurations for hysteroscopic access.
- Accessories:Cables, footswitches, and maintenance kits supporting system operation. Ambulatory surgical centers in Spain prioritize compact, transportable accessory bundles for multi-procedure days.
Established volume favors surgical handpieces; emerging adoption favors ultrasonic generators with embedded connectivity.
End User:
Customer type stratification reflects divergent capital commitment capabilities and procedure volume economics.
- Hospitals:Tier-one medical centers in the United States and Germany anchor demand for fully integrated visualization suites. These facilities amortize premium systems across high surgical volumes and negotiate enterprise service contracts spanning multiple campuses.
- Ambulatory Surgical Centers:Outpatient-focused facilities expanding across Texas, Florida, and California drive portable generator demand. Leasing and pay-per-use financing models reduce capital barriers for mid-tier clinic operators.
- Clinics:Specialty urology and gynecology practices in Italy and the Netherlands favor compact handpiece systems for limited-procedure schedules. CDSCO regulatory harmonization is opening private hospital chains in India to premium ultrasonic entry.
- Research Institutions:Academic centers in Massachusetts and Bavaria pilot cloud-based surgical analytics for outcome benchmarking. These facilities prioritize telemetry-enabled generators for post-market surveillance data generation.
Hospital procurement maintains volume dominance; ambulatory surgical centers are climbing the fastest in unit expansion.
Application:
Procedure specialization dictates energy delivery profiles and thermal damage tolerance thresholds.
- General Surgery:Laparoscopic cholecystectomy and colectomy protocols represent the foundational volume base. US integrated networks standardize on ultrasonic platforms for hemostasis efficiency in high-throughput abdominal procedures.
- Gynecological Surgery:Outpatient hysterectomy and myomectomy expansion is reshaping demand. French and British NHS trusts are migrating these procedures to ambulatory settings, favoring compact generators with rapid setup protocols.
- Urological Surgery:Prostate and renal procedures require extended activation periods without blade degradation. Japanese academic centers prioritize thermal control precision for nerve-sparing techniques.
- Orthopedic Surgery:Soft-tissue release and bone preparation applications demand specialized probe geometries. German trauma centers drive adoption for sports medicine procedures requiring minimal collateral tissue damage.
General surgery holds established procedure volume; gynecological surgery shows the steepest expansion trajectory.
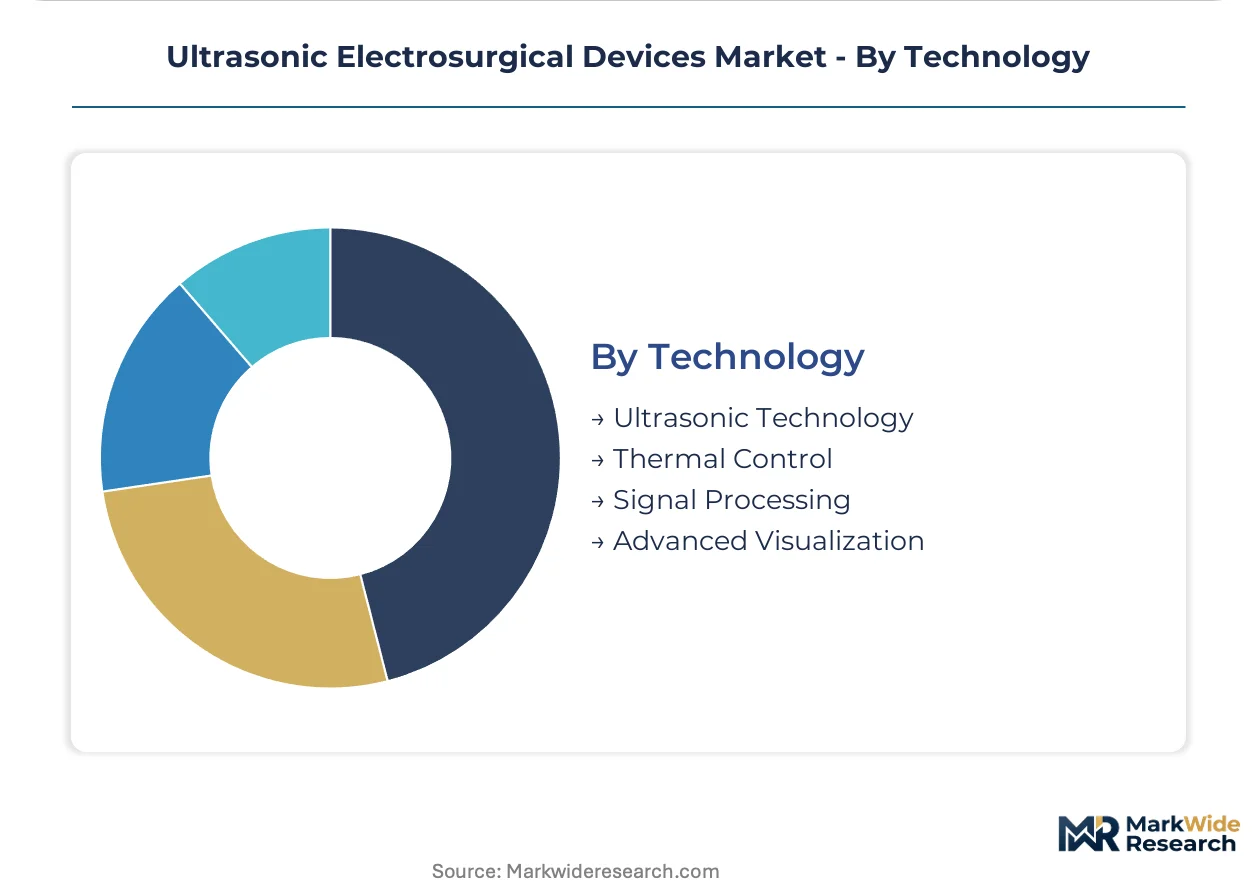
Technology:
Technology layers determine competitive differentiation and regulatory evidence requirements.
- Ultrasonic Technology:Core 55.5 kHz frequency conversion systems with piezoelectric transducer architectures. The standardized frequency constrains hardware-only differentiation, pushing margin capture toward integrated workflow solutions.
- Advanced Visualization:Fused imaging platforms combining ultrasonic energy with endoscopic guidance. Olympus leverages endoscopic integration expertise to bundle handpieces with visualization suites in Japanese and US markets.
- Thermal Control:Real-time tissue impedance monitoring to limit lateral thermal spread. Ethicon's proprietary blade geometries reduce thermal damage profiles in soft-tissue dissection applications.
- Signal Processing:Digital algorithms optimizing energy delivery based on tissue feedback. FDA cybersecurity guidance is tightening evidence requirements for connected surgical generators with telemetry capabilities.
Ultrasonic technology anchors legacy installed base; advanced visualization commands premium positioning in new procurements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated health networks in the United States concentrate procurement authority for ultrasonic electrosurgical systems, while ambulatory surgical centers in Germany and India expand addressable facility bases through leasing structures. Hospital capital planning cycles and regulatory harmonization initiatives are redistributing demand across four priority markets.
United States
Tier-one medical centers in Massachusetts and California anchor demand for fully integrated visualization suites with embedded ultrasonic generators. FDA 510(k) clearance pathways govern market entry for novel blade geometries and energy delivery modes. The Greater Boston cluster hosts academic medical centers piloting cloud-based surgical analytics for post-operative outcome tracking.
Germany
Academic hospitals in Bavaria and North Rhine-Westphalia prioritize advanced signal processing capabilities in high-frequency power electronics. EU Medical Device Regulation post-market surveillance mandates accelerate replacement cycles for legacy ultrasonic systems. The Munich-Stuttgart corridor concentrates manufacturing engineering for piezoelectric transducer architectures.
India
Private hospital chains in Maharashtra and Karnataka are expanding surgical capacity for outpatient gynecological and general surgery protocols. CDSCO regulatory harmonization with international standards opens pathways for premium ultrasonic system entry. The Mumbai-Pune corridor drives procurement of compact, portable generators suited to clinic-based settings.
Japan
Academic centers in Tokyo and Osaka prioritize thermal control precision for nerve-sparing urological techniques. PMDA regulatory frameworks align with IEC 60601-1 electrical safety requirements for connected surgical equipment. The Kanto region anchors demand for telemetry-enabled generators generating post-market surveillance data.
United Kingdom
NHS trusts in London and Manchester are migrating hysterectomy and myomectomy procedures to ambulatory settings. MHRA oversight implements EU MDR-equivalent conformity requirements for Class IIb surgical equipment. The Oxford-Cambridge arc hosts research institutions validating disposable tip economics in sterilization environments.
Ultrasonic Electrosurgical Devices Market Key Industry Players
Channel-controlling players compete with product-specialist players across three distinct tiers. The vendor base fragments between diversified medical technology conglomerates with captive supply chains and focused surgical instrument specialists with proprietary blade geometries. Two strategic archetypes dominate: visualization-integrated platform vendors and consumable-centric disposable tip suppliers. M&A activity concentrates on handpiece architecture lock-in capabilities, while strategic partnerships fuse ultrasonic energy with advanced imaging workflows.
Within the diversified conglomerate tier, Ethicon Endo-Surgery, Olympus Corporation, and Medtronic occupy positions defined by backward integration depth and endoscopic bundling power. Ethicon exemplifies the consumable-centric archetype through proprietary blade geometries. Olympus represents the visualization-integrated platform model, leveraging endoscopic expertise for workflow bundling. Medtronic anchors the captive supply chain approach, controlling generator electronics and disposable tip manufacturing in-house.
| Leading Market Players |
|---|
| Ethicon Endo-Surgery |
| Olympus Corporation |
| Medtronic |
| Misonix Inc |
| BOWA-electronic GmbH |
| Söring GmbH |
| Advanced Instrumentations |
| Reach Surgical |
| Miconvey |
| Others |
Cost & Logistics Intelligence
Single-source dependency on piezoelectric ceramic suppliers in Japan and Germany determines both three-tier pricing spreads across premium visualization-integrated, standard standalone, and economy portable systems and the captive supply chain architecture favoring backward-integrated conglomerates.
Pricing Analysis
Cost-plus contracts with semiconductor indexation govern generator electronics procurement, with pricing stratifies across premium, standard, and economy tiers based on FDA 510(k) clearance tier and bundled after-sales service depth. Cost compression in the economy portable segment is intensifying because ambulatory surgical centers negotiate direct blade resupply agreements, while integrated US health networks show least price sensitivity due to enterprise service contract consolidation.
Supply Chain Analysis
Contract manufacturing concentrates with Foxconn Medical, Jabil Healthcare, and Benchmark Electronics holding high-frequency power electronics capacity. Manufacturing draws from Japan, Germany, and Malaysia for piezoelectric transducers, ceramic substrates, and precision-machined handpiece housings. Single-source vulnerability in 55.5 kHz frequency-control chipsets creates allocation risk during semiconductor demand surges. Distribution runs through GPO contracts in the United States and direct hospital procurement in Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The ultrasonic electrosurgical market sits at a platform-economics inflection where visualization-integrated workflow bundling is displacing standalone hardware transactions, justified by cloud-based surgical analytics creating interoperability lock-in across academic medical center networks.
For Market Incumbents: Pre-empt disposable tip disintermediation by deepening backward integration into sterilization validation services and locking handpiece architectures through proprietary blade geometries. Channel control via GPO contract exclusivity represents the critical defensive lever against third-party blade resupply channels gaining share in US multi-hospital systems. For New Entrants and Emerging Players: Mid-tier ambulatory surgical centers in India and Spain represent the most penetrable entry point, where CDSCO regulatory harmonization and portable generator demand create white-space opportunity. Leasing and pay-per-use financing models offer the strongest go-to-market angle for capital-constrained clinic operators seeking premium system access without depreciation commitment. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors consumable-centric disposable tip suppliers with locked-in handpiece architectures. Long-term viability over the next decade rests on recurring revenue annuity models rather than capital equipment cyclicality. The signal to watch is unbundling velocity in US hospital procurement departments negotiating direct blade agreements.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR post-market surveillance mandates accelerate legacy system replacement cycles for Class IIb surgical equipment. |
| Hospital System Partnership | Integrated US health networks drive bulk procurement of visualization-integrated ultrasonic suites across multi-campus contracts. |
| Software Companion Development | Cloud-based surgical analytics enable remote performance monitoring and compress service contracts toward subscription economics. |
| Reimbursement Strategy | Outpatient procedure protocol expansion in gynecological surgery creates favorable coding for ambulatory ultrasonic platform adoption. |
| Backward Integration | Captive supply of generator electronics and disposable tips insulates margin pools from semiconductor allocation volatility. |
Research Approach
A spread of perspectives from hospital purchasing committee directors, biomedical engineering managers, GPO contracts specialists, and ambulatory surgical center operators converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation through FDA 510(k) clearance databases, EU MDR notified body certification records, hospital procurement contract disclosures, and piezoelectric component trade flow data. Bottom-up facility-level demand estimation triangulated against top-down manufacturer shipment analysis.
Demand-supply balance modeling across product type, end-user concentration, application specialization, and technology integration dimensions shaped the analytical framework throughout the forecast period. CAGRs derived from procedure volume elasticity, replacement cycle acceleration, and ambulatory facility expansion rates. Industry-specific inputs included semiconductor lead time volatility indices and EU MDR compliance cost escalation curves.
Practitioners should monitor regulatory harmonization progress in India, cloud-based surgical analytics pilot outcomes in Germany and Massachusetts, and unbundling velocity in US GPO negotiations for early signals of structural shift. Quarterly review of disposable tip batch traceability cost trends and ambulatory surgical center leasing penetration rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Subcutaneous Drug Delivery Devices Market
Medical Devices
Endodontic Files Market
Medical Devices
Intubation Accessories Market
Medical Devices
Japan Drug Delivery Devices Market
Medical Devices
Spain Contraceptive Devices Market
Medical Devices
Needle-Free Vaccine Injectors Market
Medical Devices
US Medical Device Outsourcing Market
Medical Devices
Liquid Oxygen Devices Market
Medical Devices
Latin America Breast Biopsy Needle Market
Medical Devices
Global Anti-Snoring Device Market
Medical Devices
Pressure Mapping Systems in Healthcare Market
Medical Devices
Breast Biopsy Marker Market
Medical Devices
Bowel Stimulators Market
Medical Devices
Global Kidney Stone Retrieval Devices Market
Medical Devices
Patient Lift Slings Market
Medical Devices
Contact Cast Systems Market