
 Global Cardiopulmonary Resuscitation Device Market | 2026-2036
Global Cardiopulmonary Resuscitation Device Market Size, Share, and Industry Trends Forecast 2026-2036
Global Cardiopulmonary Resuscitation Device Market Foresight
Project finance and leasing arrangements for emergency medical fleet upgrades is tilting procurement power toward municipal health authorities and away from direct hospital capital expenditure. Stryker Corporation leverages its emergency care portfolio breadth to bundle automated CPR devices with defibrillator contracts. ZOLL Medical Corporation anchors its position through feedback device integration with real-time perfusion monitoring. Laerdal Medical specializes in training-linked device ecosystems that sustain recurring revenue from resuscitation program certifications.
Cardiopulmonary resuscitation devices encompass manual, automated, and mechanical compression systems designed to maintain circulatory flow during cardiac arrest, typically achieving compression depths of 50-60 millimeters at rates of 100-120 per minute to preserve coronary and cerebral perfusion pressure. Automated CPR devices are capturing margin pools in hospital settings where labor costs and staff injury risks from manual compressions drive substitution. Portable deployment configurations dominate emergency medical services applications where device weight, battery autonomy, and rapid deployment mechanics determine competitive viability. Mechanical compression devices face slower uptake in clinics due to capital constraints, though ambulatory surgery centers represent an emerging installation base.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements shape product development timelines and market access costs for manufacturers seeking dual jurisdiction approval. ISO 13485 quality management systems and IEC 60601 electrical safety standards form baseline compliance thresholds that filter subscale competitors from institutional procurement channels. Stakeholders must monitor evolving AHA and ERC resuscitation guideline revisions that redefine performance benchmarks for compression depth, recoil, and duty cycle parameters.
Market Dynamics
Regulatory convergence between FDA and EU MDR on mechanical compression performance standards is accelerating product replacement cycles across hospital emergency departments and municipal EMS fleets, compressing equipment lifecycles from seven to five years.
Growth Catalysts
- Aging Demographics:Cardiac arrest incidence rises with population aging in the United States, Germany, and Japan, straining existing emergency infrastructure and forcing capital deployment into automated resuscitation systems.
- EU MDR Technical Documentation:The European Union's tightened medical device regulation mandates updated performance benchmarks for compression depth and recoil, compelling institutional buyers to replace legacy manual systems.
- Lithium-Polymer Battery Chemistry:Improved energy density in portable power systems extends device autonomy for emergency medical services applications, enabling field deployments without tethered power sources.
Market Restraints
- Capital Intensity:Automated CPR devices require upfront investment of fifteen to twenty-five thousand dollars per unit, excluding training and maintenance contracts that strain clinic and ambulatory surgery center budgets.
- Supply Concentration:Critical pneumatic compression components source from a limited German and Swiss supplier base, exposing manufacturers to lead time volatility and input cost pressure.
- Manual Compression Substitution:Trained bystander intervention and conventional CPR training programs remain entrenched in community settings, slowing automated device penetration outside institutional environments.
Strategic Opportunities
- India Emergency Infrastructure:The country's national health mission is expanding district hospital cardiac care units, creating first-mover advantage for automated CPR device vendors willing to localize service networks.
- Real-Time Perfusion Monitoring Convergence:Integration of end-tidal carbon dioxide sensors with mechanical compression feedback loops is hybridizing device categories and opening premium pricing tiers.
- Project Finance Vehicles:Municipal leasing arrangements for emergency fleet upgrades shift procurement authority from hospital capital committees to regional health authorities, consolidating buyer power and favoring multi-device contract bundling.
Industry Challenges
- Biomedical Technician Scarcity:Servicing pneumatic compression mechanisms and calibration protocols requires specialized training that outpaces supply in secondary and tertiary hospital markets.
- Dual Jurisdiction Certification:Simultaneous FDA 510(k) and EU MDR technical documentation preparation extends product development timelines by fourteen to eighteen months and consumes regulatory affairs resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Cardiopulmonary Resuscitation Device Market |
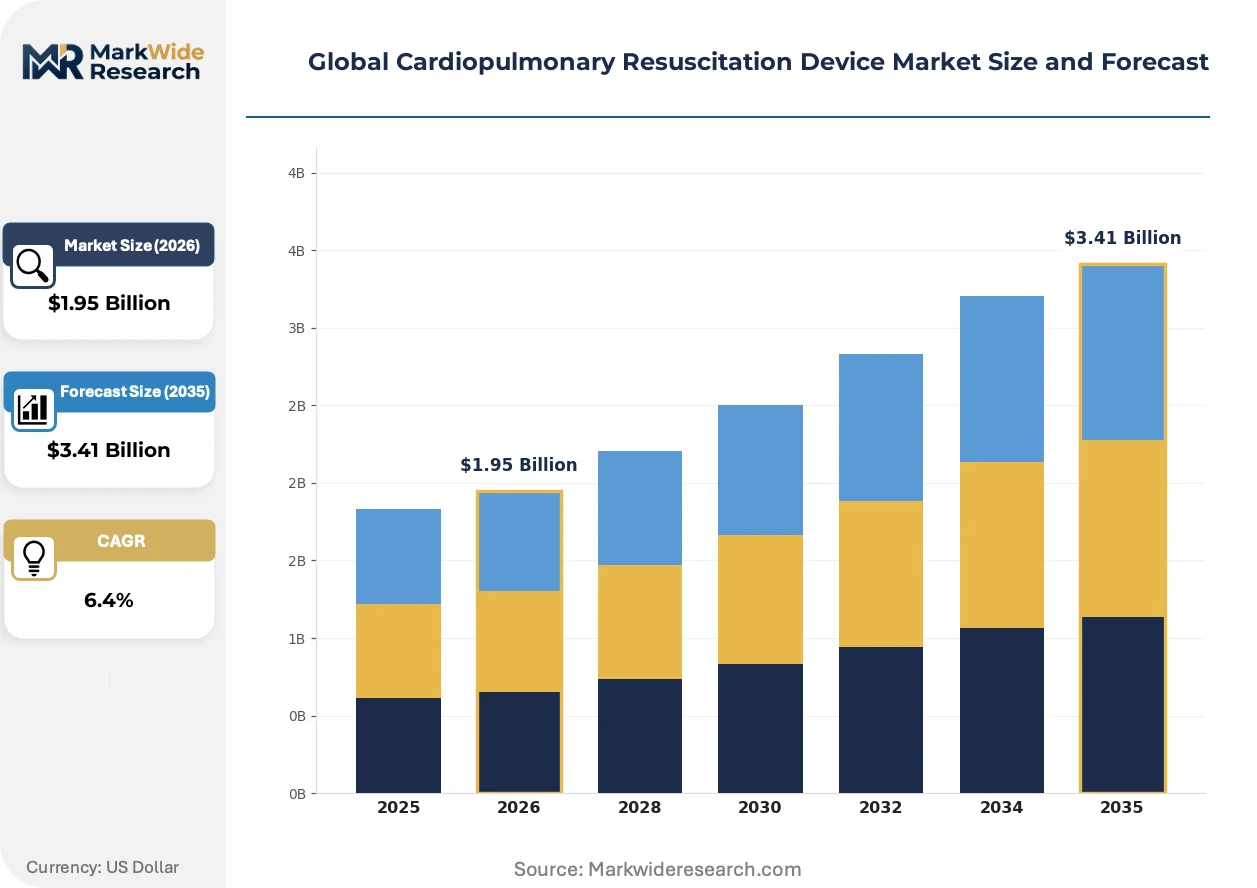
| Market Size in 2026 | $1.95 Billion |
| Market Size in 2035 | $3.41 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual CPR Devices, Automated CPR Devices, Mechanical Compression Devices, Feedback Devices Application: Emergency Medical Services, Hospitals, Clinics, Ambulatory Services, Military Medicine End User: Paramedics, Emergency Physicians, Critical Care Specialists, First Responders Deployment Type: Portable Devices, Stationary Devices, Wearable Devices, Integrated Systems |
| Companies Covered | Drägerwerk AG & Co. KGaA, Stryker Corporation, ZOLL Medical Corporation, Nihon Kohden Corporation, Laerdal Medical, Philips Healthcare, Ambu A/S, Mindray Medical International, Medtronic plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Cardiopulmonary Resuscitation Device Market Shifts & Advancements
Feedback-integrated resuscitation systems are displacing standalone mechanical compressors across high-acuity settings, compressing the competitive landscape around real-time physiological monitoring capabilities rather than compression mechanics alone.
Electromagnetic piston mechanisms are hybridizing with traditional pneumatic compression systems to reduce device weight and improve deployment speed in emergency medical services applications. EMS agencies in North America and Western Europe are piloting these hybrid configurations for rapid-response vehicle integration. The technology is compressing the performance gap between hospital-grade and field-deployable units, forcing vendors to unify their product architectures.
FDA's updated 510(k) clearance pathway for mechanical CPR devices now mandates human factors validation and simulated use testing, raising documentation burdens for manufacturers seeking US market access. The regulation compresses development timelines for smaller entrants while favoring incumbents with established quality management systems. Hospital procurement committees are responding by demanding dual-jurisdiction certification as a baseline qualification, filtering single-market vendors from institutional channels.
Equipment-as-a-service contracting is displacing capital purchase models in municipal emergency fleet management, transferring ownership risk to manufacturers and bundling maintenance, training, and device refresh cycles into per-use or annual fees. This restructuring concentrates buyer power with regional health authorities in the United States and Germany. The shift is most visible in aging metropolitan areas where budget constraints and political pressure favor operational expenditure over capital allocation.
Global Cardiopulmonary Resuscitation Device Market Segmentation
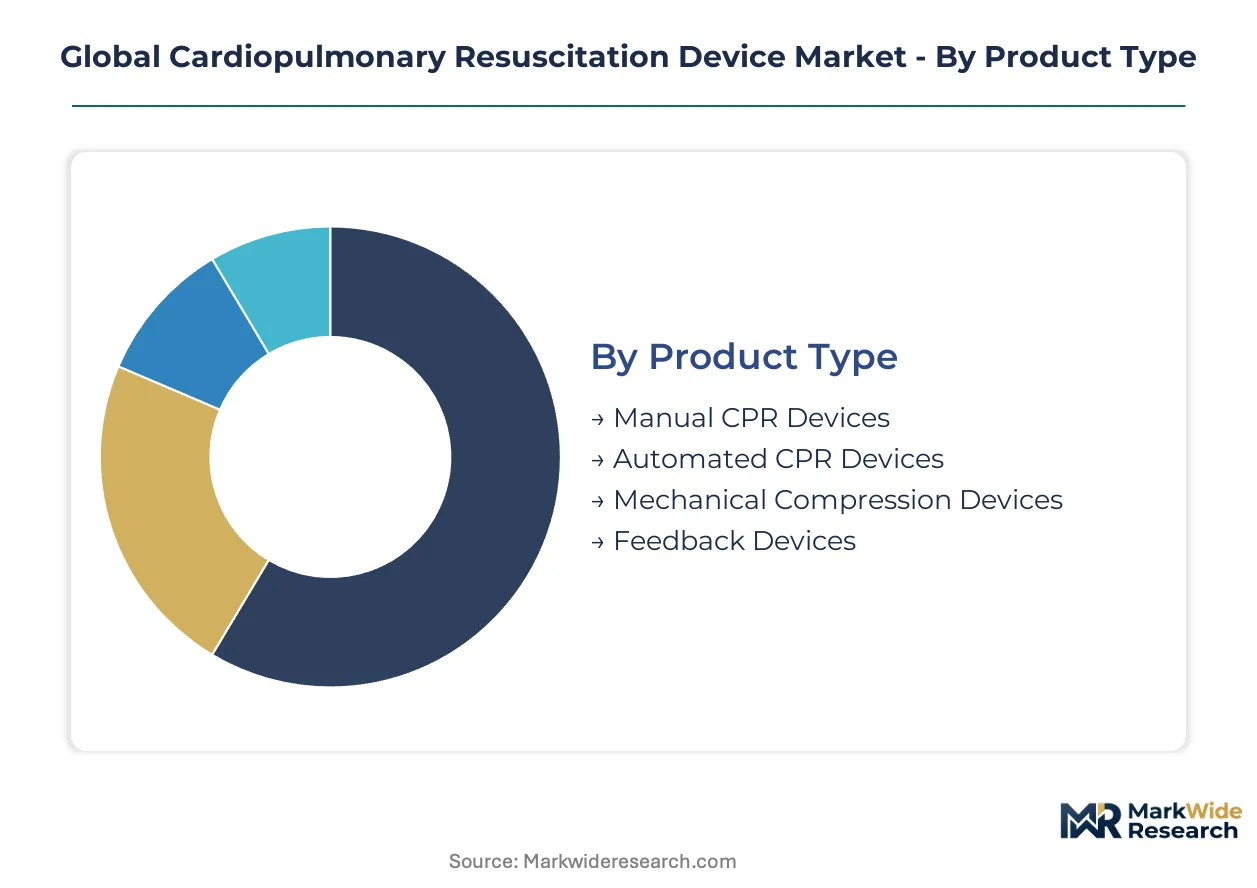
Segmentation in the cardiopulmonary resuscitation device market reveals divergent equipment lifecycles and procurement patterns across clinical settings. Compression technology maturity, regulatory certification burdens, and end-user training requirements create distinct replacement rhythms that shape vendor revenue stability.
Product Type:
Replacement cycles vary sharply across compression technologies, with automated systems turning over every five years under FDA-EU MDR convergence while manual devices persist for seven to eight years in budget-constrained settings.
- Manual CPR Devices:Hand-operated compression systems requiring trained operator technique to achieve target depth and rate parameters. Demand concentrates in developing health systems and military field medicine where capital constraints override labor cost considerations, though injury liability among hospital staff is accelerating substitution in OECD markets.
- Automated CPR Devices:Electromechanical systems delivering consistent compression depth and rate without operator fatigue. Hospital emergency departments in the United States, Germany, and Japan are expanding procurement as labor costs and staff injury claims mount, with municipal EMS fleets following as battery autonomy improves.
- Mechanical Compression Devices:Pneumatic or piston-driven systems for sustained resuscitation without human operator. Surgical suites and cath labs in tertiary hospitals favor these for prolonged procedures.
- Feedback Devices:Real-time sensors monitoring compression quality and perfusion indicators. Training centers and quality-focused hospital systems drive uptake alongside certification program requirements.
Manual CPR devices anchor the volume base while automated CPR devices gain share at the steepest rate.
Application:
Procurement authority and budget structures diverge materially across care settings, with municipal fleet managers wielding consolidated purchasing power against fragmented hospital capital committees.
- Emergency Medical Services:Field-deployable systems prioritizing weight reduction, rapid deployment mechanics, and battery endurance. EMS agencies in North America and Western Europe are piloting hybrid electromagnetic-piston configurations for rapid-response vehicle integration.
- Hospitals:High-acuity settings demanding feedback-integrated systems with real-time perfusion monitoring. Emergency departments are expanding automated device procurement under project finance and leasing arrangements that shift authority to regional health authorities.
- Clinics:Capital-constrained outpatient settings where manual compression persists due to limited cardiac arrest volume and budget restrictions.
- Ambulatory Services:Freestanding surgical and diagnostic facilities emerging as an installation base for mechanical compression devices as procedural complexity rises.
- Military Medicine:Ruggedized portable systems for battlefield and expeditionary deployment where device weight and battery autonomy determine competitive viability.
Hospitals command premium pricing tiers while emergency medical services applications expand most quickly as municipal fleet modernization accelerates.
End User:
Training requirements and liability exposure create distinct user segments with varying willingness to adopt automated assistance and real-time feedback systems.
- Paramedics:Pre-hospital providers operating in uncontrolled environments where device portability and rapid deployment mechanics outweigh hospital-grade feature sets. Municipal procurement consolidation favors vendors with service network density.
- Emergency Physicians:Hospital-based practitioners leading resuscitation teams in emergency departments where feedback-integrated systems and real-time perfusion monitoring command priority.
- Critical Care Specialists:Intensivists managing prolonged resuscitation in ICU settings where mechanical compression consistency and integration with hemodynamic monitoring systems drive selection.
- First Responders:Bystander-trained personnel and basic life support providers where manual compression training programs remain entrenched, slowing automated device penetration outside institutional environments.
Emergency physicians anchor the volume base while critical care specialists drive the steepest adoption of integrated feedback systems.
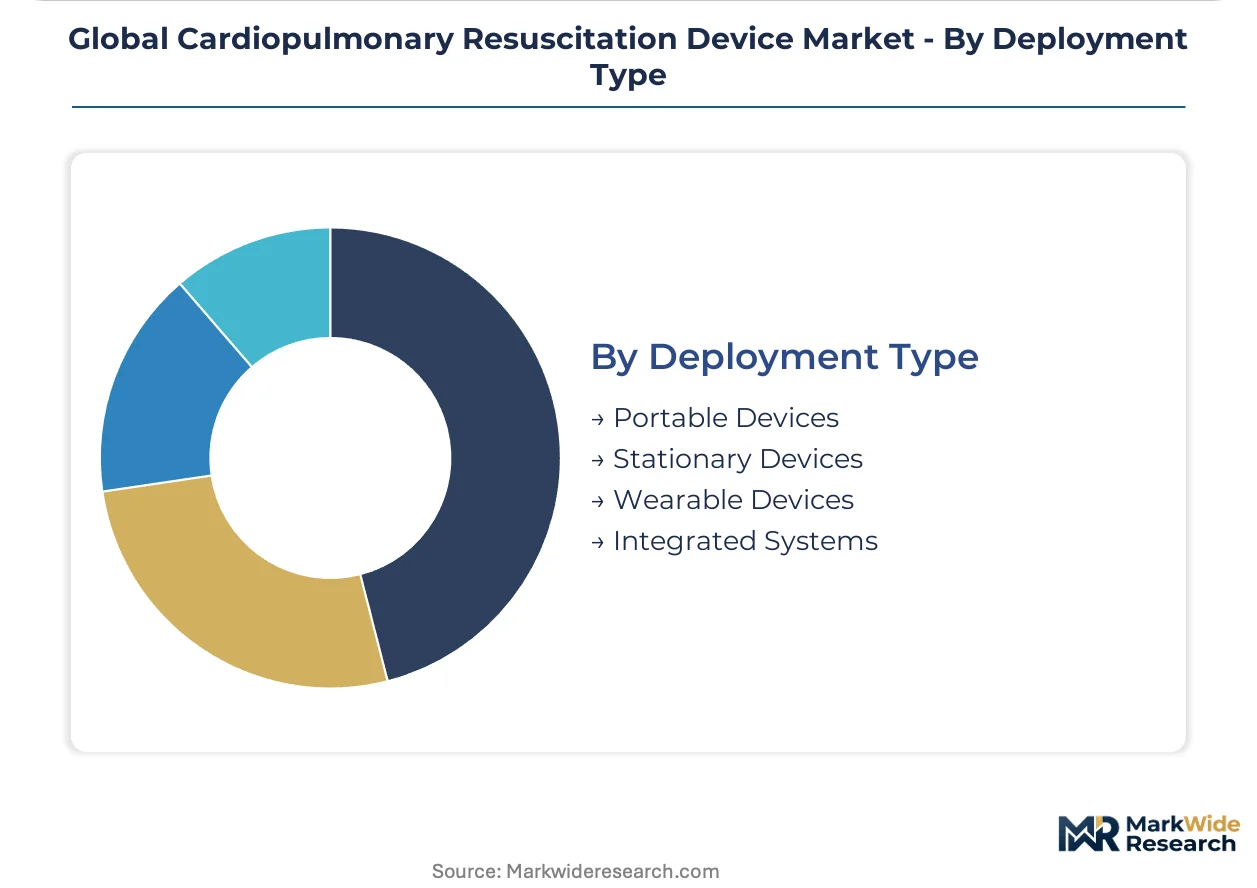
Deployment Type:
Physical configuration determines addressable market scope, with portable and stationary architectures diverging in supply chain requirements and service network economics.
- Portable Devices:Battery-powered systems under 10 kilograms for field deployment and inter-facility transport. Lithium-polymer chemistry advances are extending autonomy for emergency medical services applications.
- Stationary Devices:Hospital-installed systems with tethered power and integration with emergency department infrastructure. These command higher unit economics but face longer replacement cycles.
- Wearable Devices:Emerging vest-based compression systems for rapid application without mechanical positioning. Early pilot programs focus on cath lab and procedural sedation settings.
- Integrated Systems:Defibrillator-CPR hybrid platforms with unified feedback loops and data capture. Hospital procurement committees increasingly demand these for capital efficiency and training simplification.
Stationary devices anchor the volume base while portable configurations gain share at the steepest rate as emergency medical services fleet upgrades accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA and EU MDR regulatory convergence on mechanical compression performance standards is accelerating equipment replacement cycles across hospital emergency departments and municipal EMS fleets in major developed markets.
United States
Aging demographics in Florida, Arizona, and the Northeast corridor are straining cardiac emergency infrastructure and forcing capital deployment into automated resuscitation systems. The FDA's updated 510(k) clearance pathway now mandates human factors validation and simulated use testing for mechanical CPR devices. Hospital procurement committees in Boston and Houston are demanding dual-jurisdiction certification as a baseline qualification, filtering single-market vendors from institutional channels.
Germany
The EU MDR technical documentation requirements mandate updated performance benchmarks for compression depth and recoil, compelling institutional buyers to replace legacy manual systems. Municipal health authorities in Bavaria and North Rhine-Westphalia are consolidating procurement power through project finance and leasing arrangements for emergency fleet upgrades. Medical device clusters around Munich and Tuttlingen host pneumatic compression component suppliers that expose manufacturers to lead time volatility.
Japan
PMDA regulatory alignment with international standards is compressing product development timelines for manufacturers seeking market access. METI incentives for emergency medical infrastructure modernization are expanding automated CPR device procurement in Tokyo and Osaka metropolitan areas. Aging population concentration in rural prefectures is driving deployment of portable configurations with extended battery autonomy for inter-facility transport.
India
The national health mission is expanding district hospital cardiac care units, creating first-mover advantage for automated CPR device vendors willing to localize service networks. CDSCO medical device regulations are tightening quality management requirements for imported emergency care equipment. Industrial corridors in Maharashtra and Gujarat are emerging as assembly locations for cost-optimized portable units targeting municipal EMS fleets.
United Kingdom
NHS capital allocation shifts toward operational expenditure models are favoring equipment-as-a-service contracting for emergency fleet management. MHRA post-Brexit regulatory autonomy is maintaining alignment with EU MDR standards while streamlining approval pathways for innovative compression technologies. London and Manchester health authorities are piloting integrated defibrillator-CPR hybrid platforms with unified feedback loops.
Global Cardiopulmonary Resuscitation Device Market Competitive Landscape
On the supply side, the industry is consolidating around vendors with established quality management systems and dual-jurisdiction certification capabilities. The competitive terrain separates into three strategic tiers: diversified emergency care conglomerates bundling automated CPR devices with defibrillator contracts, specialists in feedback-integrated resuscitation systems with real-time perfusion monitoring, and training-linked device ecosystem providers sustaining recurring revenue from certification programs. Dominant competitive moves include strategic partnerships for municipal fleet modernization and portfolio diversification into hybrid electromagnetic-piston configurations.
Within the diversified emergency care tier, Stryker Corporation and ZOLL Medical Corporation exemplify vendors leveraging portfolio breadth to anchor institutional procurement relationships. Laerdal Medical occupies a position as a training-linked ecosystem specialist, while Nihon Kohden Corporation and Drägerwerk AG & Co. KGaA represent regional anchors with regulatory expertise in their respective home markets. Philips Healthcare and Medtronic plc sit within the integrated systems vector, bundling resuscitation devices with broader patient monitoring architectures.
| Leading Market Players |
|---|
| Drägerwerk AG & Co. KGaA |
| Stryker Corporation |
| ZOLL Medical Corporation |
| Nihon Kohden Corporation |
| Laerdal Medical |
| Philips Healthcare |
| Ambu A/S |
| Mindray Medical International |
| Medtronic plc |
| Others |
Supply & Pricing Matrix
Single-source dependency on German and Swiss pneumatic compression component suppliers concentrates pricing power upstream, compressing margins for device assemblers while forcing tiered certification-grade pricing spreads across hospital, EMS, and clinic buyer segments.
Pricing Analysis
Certification level creates the primary spread between premium FDA-EU MDR dual-certified units and single-market economy alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 13485 quality management maturity and after-sales service bundling. Cost compression in the standard tier is intensifying because municipal procurement consolidation favors volume discounts over feature differentiation. Clinics and ambulatory surgery centers exhibit highest price sensitivity, while tertiary hospital emergency departments prioritize perfusion monitoring integration over unit cost.
Supply Chain Analysis
Tariff exposure between Switzerland and Germany for precision pneumatic valves dominates supply chain risk architecture. Component sourcing concentrates in southern Germany around Tuttlingen and Swiss medical device clusters near Solothurn. Lithium-polymer battery cells draw from South Korean and Japanese chemical suppliers, creating secondary geographic concentration. Single-source vulnerability for electromagnetic piston mechanisms threatens hybrid configuration rollout timelines. Distribution runs through regional medical device distributors with GPO contract access in the United States and direct hospital service teams in Germany and Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
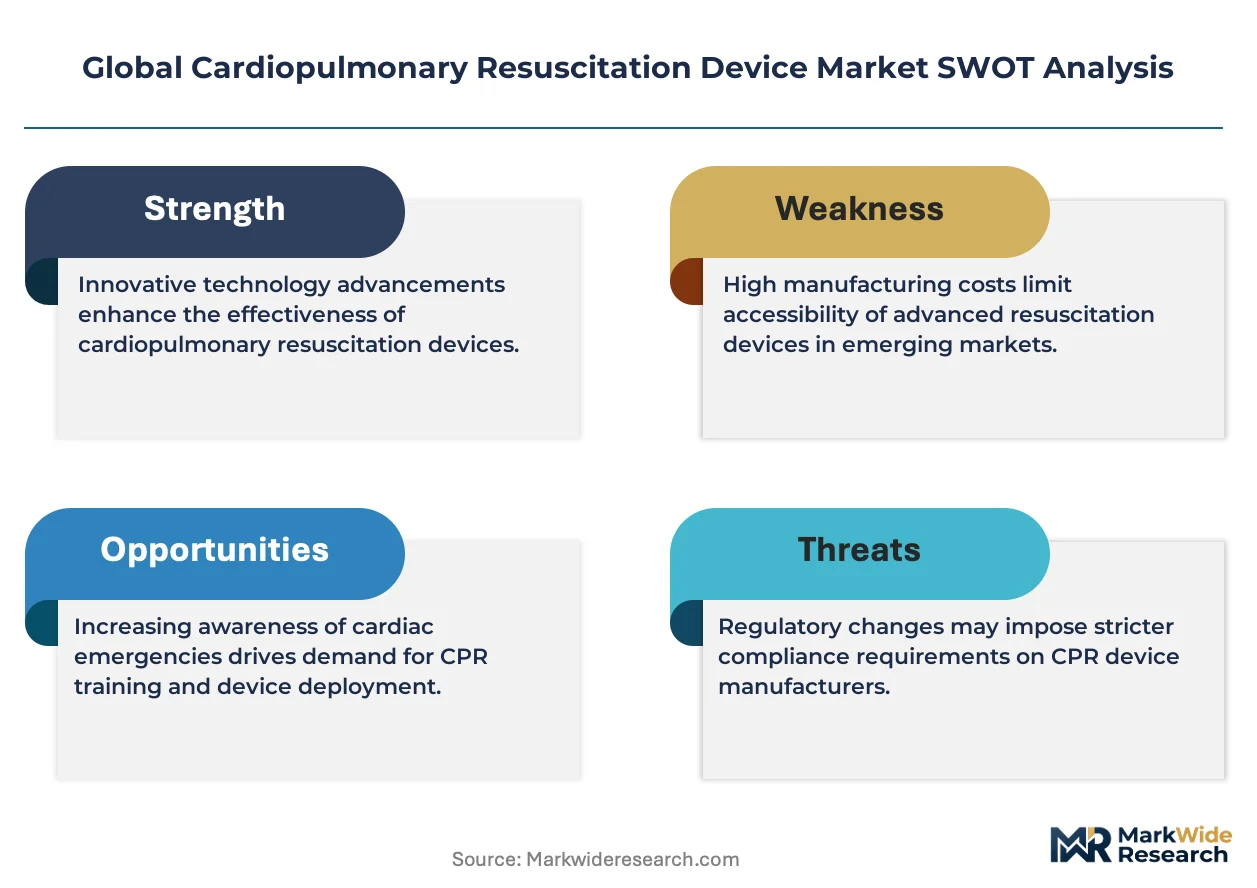
Municipal health authority procurement consolidation is shifting buyer power toward regional fleet managers and away from fragmented hospital capital committees, rewarding vendors with multi-device bundling capabilities and service network density.
For Market Incumbents: Harden quality management system investments to maintain dual-jurisdiction certification moats against emerging Asian competitors seeking FDA 510(k) entry. Deepen backward integration into pneumatic compression component supply through captive production or long-term offtake agreements with Tuttlingen-area suppliers, insulating against lead time volatility that threatens municipal contract fulfillment. For New Entrants and Emerging Players: Build out localized service networks in Maharashtra and Gujarat industrial corridors to capture India's national health mission district hospital expansion, where first-mover advantage accrues to vendors with biomedical technician training capacity. Target portable EMS configurations with simplified feedback integration as the most penetrable segment, leveraging lithium-polymer battery chemistry advances to match incumbent autonomy specifications at lower unit economics. For Investors and Strategic Acquirers: The market sits at a regulatory-convergence phase that favors diversified emergency care conglomerates with established EU MDR technical documentation capabilities and defensible hospital procurement relationships. Acquisition targets should display integrated feedback-software architectures rather than standalone mechanical compression hardware. Watch CDSCO regulatory tightening in India as the signal indicating whether cost-optimized portable entrants can sustain margin structures or face compliance-driven consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Accelerates product replacement cycles in German hospital systems by mandating updated compression performance benchmarks. |
| Hybrid Electromagnetic-Piston Configuration Development | Compresses weight and deployment speed gaps between hospital-grade and field-deployable units for EMS rapid-response integration. |
| Equipment-as-a-Service Contracting | Transfers ownership risk to manufacturers while consolidating buyer power with municipal health authorities in aging US metropolitan areas. |
| Real-Time Perfusion Monitoring Integration | Opens premium pricing tiers through end-tidal carbon dioxide sensor fusion with mechanical compression feedback loops. |
| India Service Network Localization | Captures national health mission district hospital cardiac care unit expansion through CDSCO-compliant assembly and biomedical technician training. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with emergency physicians, paramedic fleet managers, biomedical engineers, hospital purchasing committee chairs, and GPO contracts managers. Secondary validation drew from FDA 510(k) clearance databases, EU MDR technical documentation filings, hospital procurement contract repositories, and EMS fleet modernization budget disclosures. Bottom-up unit shipment estimates by compression technology and application were triangulated against top-down market value reconstructions.
Calibration against historical replacement cycle data and regulatory implementation timelines anchored growth rate derivation across the projection horizon. Segmentation modeling spanned product type, application setting, end-user specialty, and deployment configuration dimensions. Forecast inputs incorporated AHA and ERC guideline revision schedules, lithium-polymer energy density improvement curves, and municipal leasing arrangement penetration rates by metropolitan area aging demographics.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by mid-cap specialists or accelerated CDSCO regulatory harmonization would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Oxygenator Market
Medical Devices
Breast Cancer Core Needle Biopsy Market
Medical Devices
Global Mobile ECG Devices Market
Medical Devices
Transcatheter Mitral Valve Market
Medical Devices
Heat Therapy Units Market
Medical Devices
Portable Medical Ventilators Market
Medical Devices
Transcranial Doppler Ultrasounds System Market
Medical Devices
Needle-Free IV Connectors Market
Medical Devices
Augmented Bone Graft Market
Medical Devices
Global Pediatric Medical Devices Market
Medical Devices
High Pressure Contrast Media Injectors Market
Medical Devices
China Artificial Organs and Bionic Implants Market
Medical Devices
Asia-Pacific Ultrasound Devices Market
Medical Devices
Permanent Artificial Skin Market
Medical Devices
Seizure Detection Devices Market
Medical Devices
Flexible Spinal Implants Market