
 North America Medical Device Regulatory Affairs Outsourcing Market | 2026-2036
North America Medical Device Regulatory Affairs Outsourcing Market Size, Share, and Industry Trends Forecast 2026-2036
North America Medical Device Regulatory Affairs Outsourcing Market Analytics
Modular service bundling is recalibrating how device firms purchase regulatory support. PAREXEL leverages its integrated clinical and regulatory platform to anchor large-scale outsourcing relationships across the United States. ICON plc competes through specialized European-American regulatory bridge services that sustain complex multi-jurisdiction submissions. Medpace differentiates via therapeutic-area depth in cardiovascular and neurology devices, positioning its teams as embedded regulatory partners rather than transactional vendors.
North America medical device regulatory affairs outsourcing encompasses the delegation of compliance strategy, submission preparation, and post-market surveillance activities to third-party specialists, typically executed through structured quality management systems aligned with FDA 21 CFR Part 820 and ISO 13485 standards. Its primary commercial purpose is to compress time-to-market for manufacturers lacking in-house regulatory infrastructure while ensuring adherence to evolving safety and efficacy benchmarks. Clinical trial services command substantial margin pools due to the specialized expertise required for investigational device exemption pathways, while post-market surveillance represents the fastest-expanding segment as FDA intensifies real-world performance monitoring requirements. Submission management maintains mature, high-volume operations particularly for 510(k) clearances, though pre-market consulting shows accelerating growth among first-time device entrants navigating breakthrough designation pathways.
FDA's Quality System Regulation and the Medical Device Reporting framework shape baseline compliance obligations, while Health Canada's Medical Devices Bureau imposes parallel but distinct licensing requirements that expand outsourcing complexity for cross-border manufacturers. The FDA's forthcoming harmonization with international medical device regulator forum standards will reshape documentation expectations and demand recalibration of existing quality management architectures. Stakeholders must monitor how artificial intelligence-enabled device submissions alter traditional evidentiary requirements and whether regulatory consultancies can scale technical review capacity accordingly.
Market Dynamics
Mid-sized medical device manufacturers are accelerating their reliance on external regulatory partners to navigate complex FDA submission pathways, compressing time-to-market for cardiovascular and neurology devices while intensifying demand for specialized compliance expertise in software-as-a-medical-device frameworks.
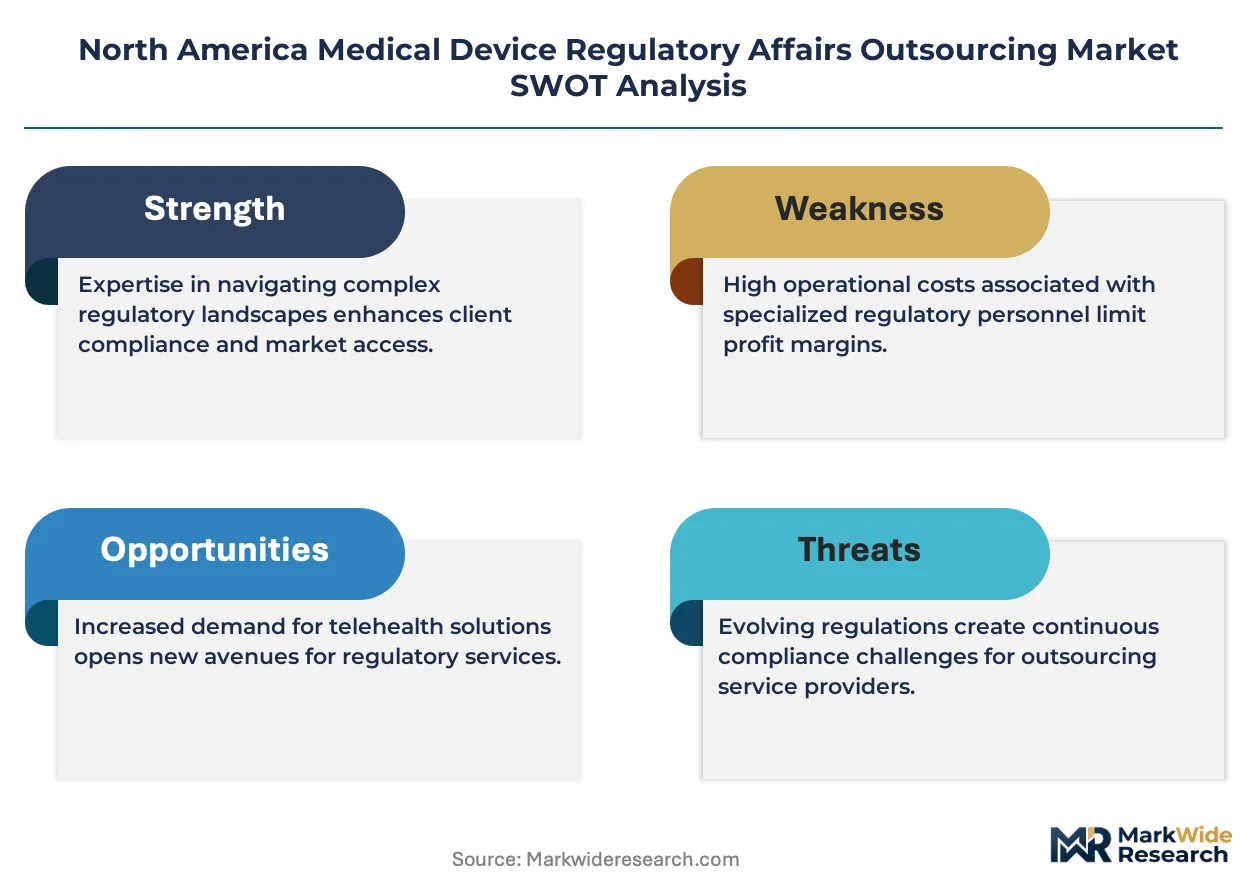
Growth Catalysts
- FDA's evolving digital health guidance:The agency's software-as-a-medical-device framework is intensifying demand for specialized compliance expertise among device manufacturers lacking in-house regulatory infrastructure.
- California's medtech corridor:Device innovation clusters in the San Francisco Bay Area and San Diego are generating concentrated outsourcing demand for 510(k) clearance support and breakthrough designation navigation.
- Artificial intelligence-enabled submissions:AI-integrated diagnostic and therapeutic devices are altering traditional evidentiary requirements, pulling manufacturers toward consultancies with scalable technical review capacity.
Market Restraints
- Cross-border regulatory friction:Health Canada's Medical Devices Bureau imposes parallel but distinct licensing requirements that expand outsourcing complexity for manufacturers seeking simultaneous US-Canada market entry.
- Quality management system recalibration costs:FDA's forthcoming harmonization with International Medical Device Regulator Forum standards demands documentation architecture overhauls that strain mid-sized manufacturer budgets.
- In-house regulatory team retention:Specialized talent scarcity in FDA 21 CFR Part 820 and ISO 13485 expertise elevates salary competition, narrowing the cost gap between captive and outsourced functions.
Strategic Opportunities
- Massachusetts device innovation cluster:Boston-Cambridge's concentration of early-stage cardiovascular and neurology ventures presents embedded partnership opportunities for regulatory consultancies willing to co-locate technical teams.
- Real-world performance monitoring services:FDA's intensified post-market surveillance mandates are expanding the fastest-growing service segment, creating recurring revenue streams beyond one-time submission support.
- Modular service bundling:Structured unbundling of clinical trial services from submission management is recalibrating purchasing patterns, allowing consultancies to anchor relationships through discrete high-value modules.
Industry Challenges
- Investigational device exemption pathway expertise:Clinical trial services command substantial margin pools due to specialized knowledge requirements, yet talent scarcity constrains consultancy scaling capacity.
- Legacy quality management system integration:Manufacturers with entrenched ISO 13485 architectures face friction embedding external regulatory partners into existing documentation workflows and audit trails.
- Multi-jurisdiction submission synchronization:Coordinated FDA-Health Canada filings demand redundant documentation sets and divergent evidentiary standards, elevating project management complexity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Medical Device Regulatory Affairs Outsourcing Market |
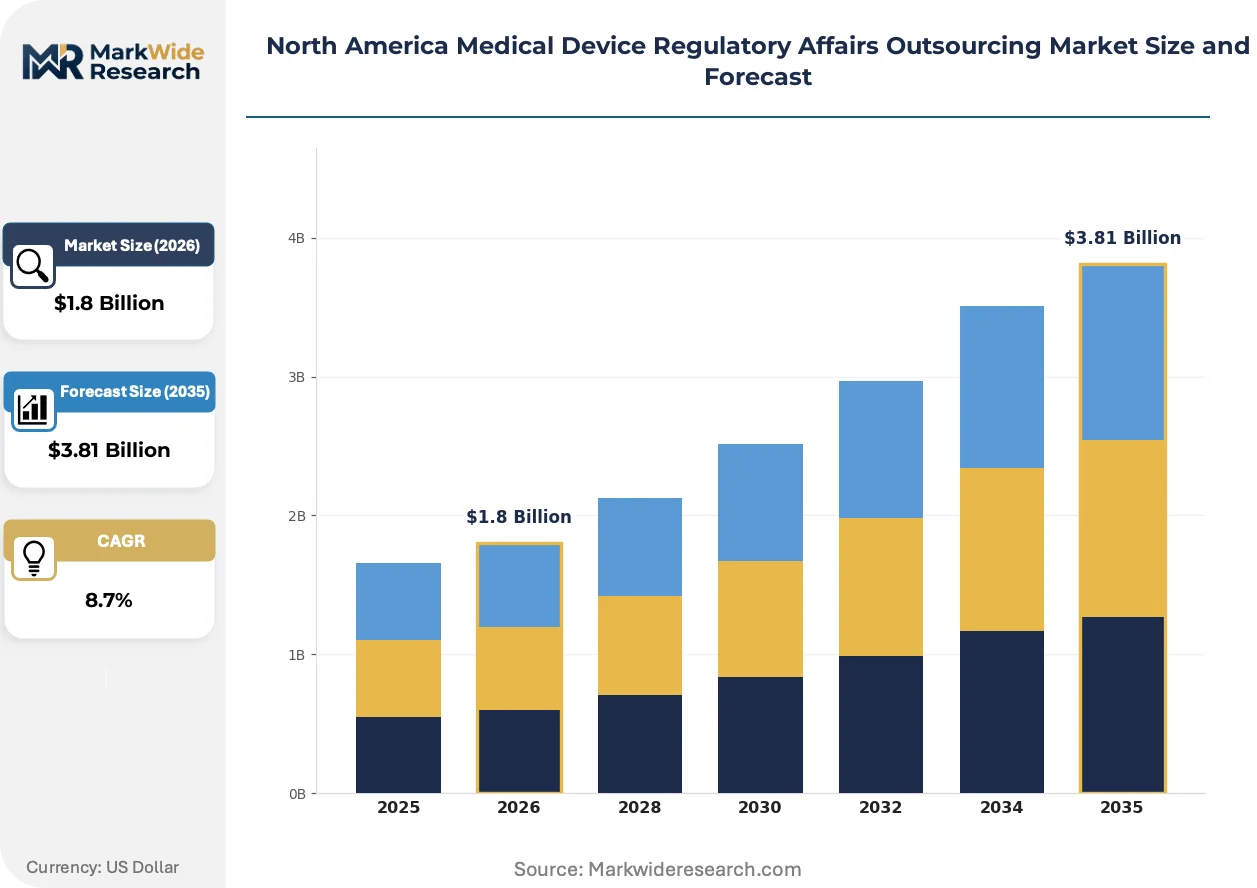
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Pre-Market Consulting, Clinical Trial Services, Submission Management, Post-Market Surveillance Industry Vertical: Diagnostic Devices, Therapeutic Devices, Surgical Equipment, Monitoring Systems End User: Medical Device Manufacturers, Biotechnology Companies, Research Institutions, Startups Solution: Regulatory Strategy Development, Compliance Consulting, Quality Management Systems, Risk Assessment |
| Companies Covered | PAREXEL (US), Medpace (US), ICON plc (IE), IQVIA, Inc., Laboratory Corporation of America Holdings, Charles River Laboratories (US), Syneos Health (US), Freyr, Emergo, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Medical Device Regulatory Affairs Outsourcing Market Evolving Landscape
Regulatory consultancies are repositioning around three converging forces: AI-enabled device submissions, modular service architectures, and embedded partnership models that displace transactional vendor relationships.
Machine learning algorithms integrated into diagnostic imaging and patient monitoring systems are electrifying the evidentiary burden for pre-market submissions. Cardiovascular device manufacturers are adopting these tools at accelerating pace to demonstrate clinical equivalence. This technology is electrifying demand for biostatisticians and clinical data scientists within regulatory consultancies, compressing traditional review timelines.
FDA's Quality System Regulation harmonization with International Medical Device Regulator Forum standards is reshaping documentation expectations for manufacturers with existing ISO 13485 certifications. The industrial consequence is mandatory recalibration of quality management architectures ahead of enforcement deadlines. Submission management services for 510(k) clearances are most affected, with consultancies pre-building compliant documentation templates to capture migrating volume.
Device manufacturers are unbundling after-sales regulatory support from upfront submission contracts, creating discrete purchasing decisions for post-market surveillance. This pattern displaces full-service retainers with modular engagements tied to specific FDA reporting obligations. California's medtech corridor exhibits the most visible adoption, where venture-backed firms prioritize variable cost structures over fixed regulatory overhead.
North America Medical Device Regulatory Affairs Outsourcing Market Segmentation
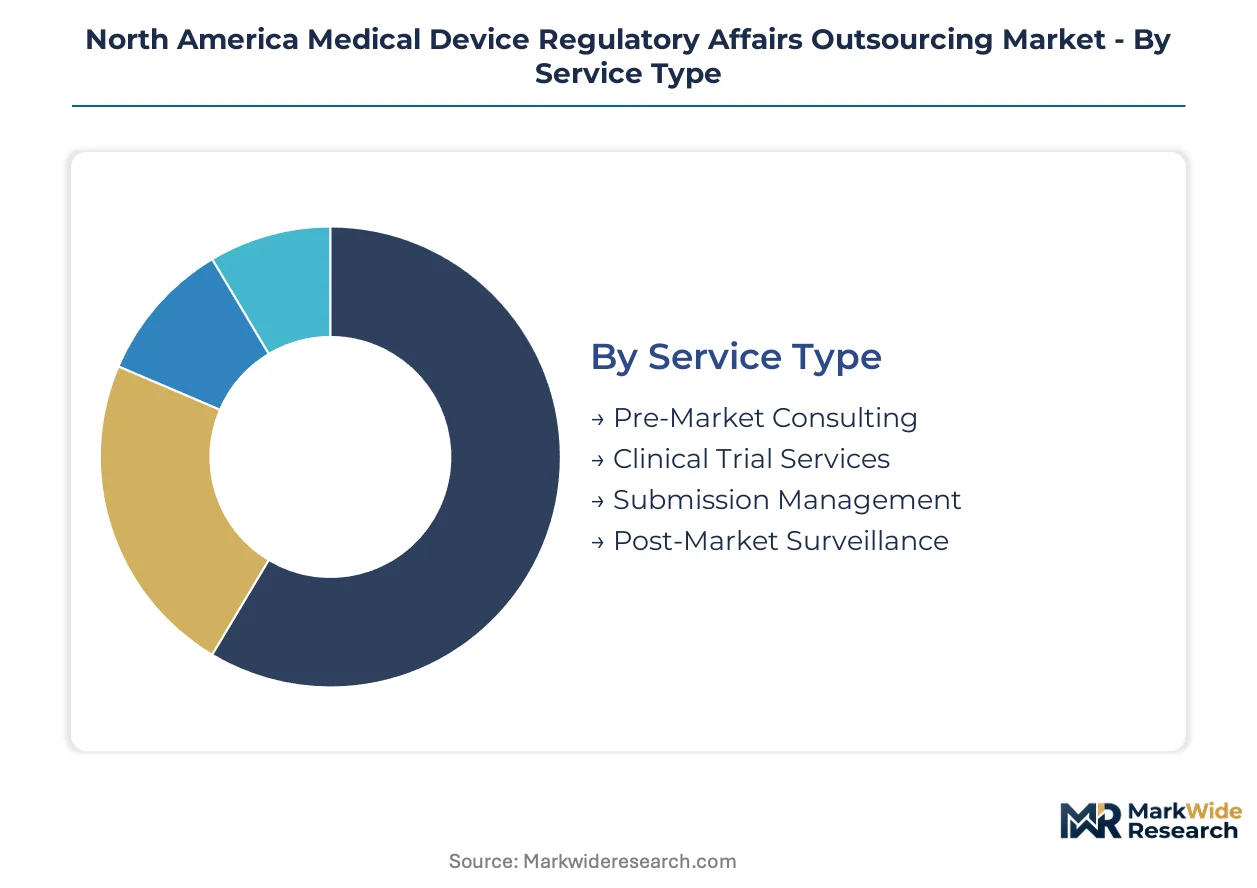
Regulatory outsourcing purchasing decisions pivot on service modularity, therapeutic specialization, and organizational scale. Manufacturers segment demand across discrete compliance functions rather than bundled retainers, with venture-backed startups and mid-sized device firms driving divergent contracting patterns.
Service Type:
Cost tier determines engagement depth, with high-complexity services commanding premium pricing and long-term relationships.
- Pre-Market Consulting:Strategic advisory spanning FDA pathway selection, breakthrough designation navigation, and predicate device analysis for first-time entrants. Massachusetts cardiovascular startups concentrate demand here as embedded technical partnerships replace transactional vendor relationships.
- Clinical Trial Services:Investigational device exemption pathway management, site qualification, and biostatistical analysis for pivotal studies. California's neurology device cluster pulls specialized expertise as AI-enabled diagnostics alter traditional evidentiary requirements.
- Submission Management:510(k) clearance documentation, pre-submission meeting preparation, and FDA correspondence handling.
- Post-Market Surveillance:Medical device reporting compliance, real-world performance monitoring, and vigilance system maintenance.
Volume sits with Submission Management; growth tilts toward Post-Market Surveillance.
Industry Vertical:
Application complexity separates pricing tiers, with software-integrated devices demanding hybrid regulatory-clinical expertise.
- Diagnostic Devices:In vitro diagnostic regulatory strategy, companion diagnostic co-development, and software-as-a-medical-device compliance. FDA's evolving digital health guidance intensifies outsourcing demand among California imaging ventures lacking in-house regulatory infrastructure.
- Therapeutic Devices:Class III device PMA pathway navigation, combination product submissions, and clinical evidence generation. Boston-Cambridge cardiovascular innovators anchor consulting relationships through therapeutic-area depth rather than generic compliance support.
- Surgical Equipment:Sterilization validation documentation, human factors engineering submissions, and 510(k) technical file preparation.
- Monitoring Systems:Remote patient monitoring compliance, cybersecurity documentation, and interoperability standards alignment.
Therapeutic Devices capture the steepest expansion trajectory as breakthrough designations proliferate.
End User:
Customer maturity dictates contract structure, with established manufacturers favoring embedded partnerships and emerging ventures preferring modular engagements.
- Medical Device Manufacturers:Established firms with captive regulatory teams purchasing discrete overflow capacity or specialized jurisdiction expertise. Mid-sized manufacturers across the United States accelerate reliance on external partners to compress time-to-market for cardiovascular submissions.
- Biotechnology Companies:Drug-device combination developers requiring cross-functional regulatory strategy spanning FDA's Center for Drug Evaluation and Research and Center for Devices and Radiological Health interfaces.
- Research Institutions:Academic medical centers navigating investigator-initiated study compliance and technology transfer regulatory requirements.
- Startups:Venture-backed early-stage firms prioritizing variable cost structures and milestone-based regulatory support over fixed overhead.
Revenue concentrates with Medical Device Manufacturers; share gains flow fastest to Startups.
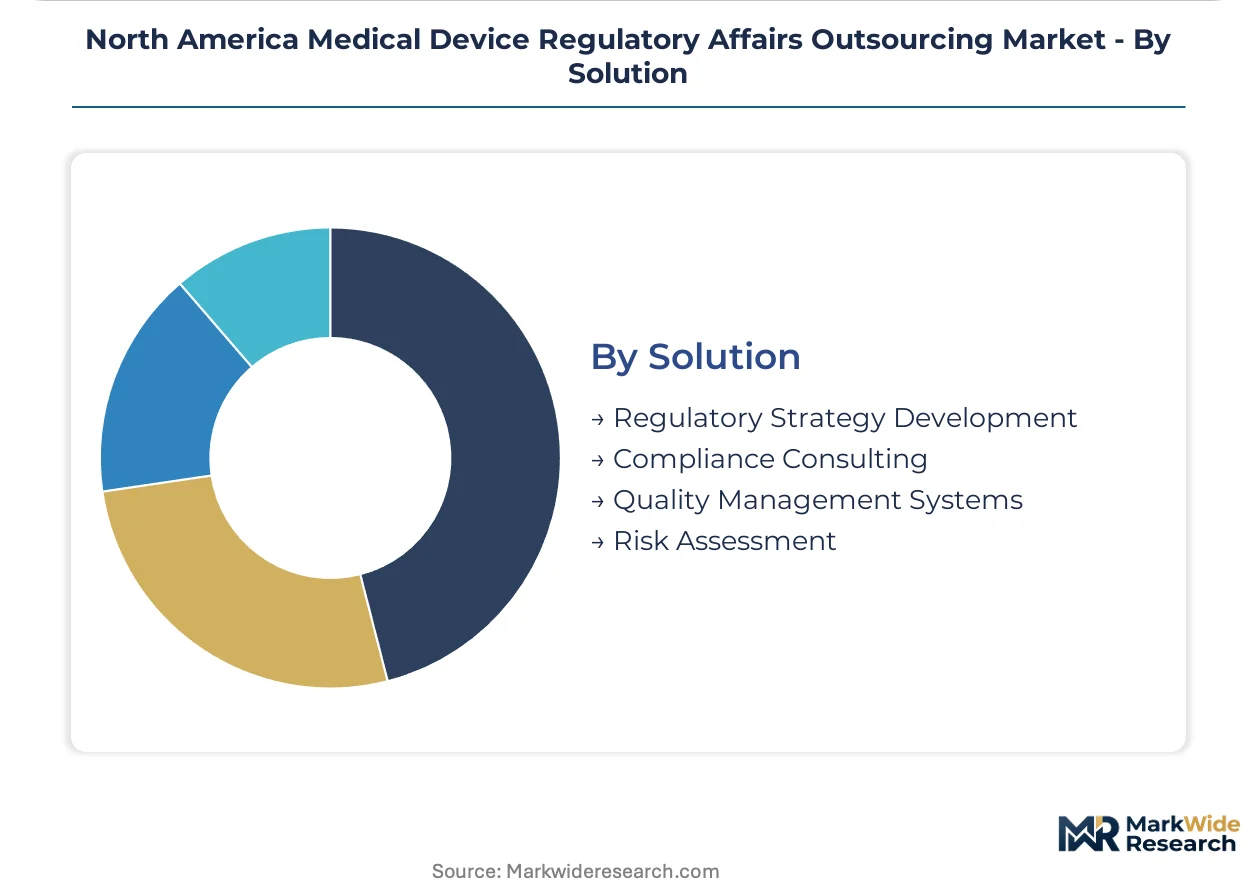
Solution:
Margin pools align with technical specialization depth, with quality system architecture commanding premium positioning.
- Regulatory Strategy Development:Market entry pathway selection, competitive regulatory intelligence, and portfolio prioritization advisory. FDA's forthcoming harmonization with International Medical Device Regulator Forum standards reshapes documentation expectations and pulls manufacturers toward consultancies with scalable technical review capacity.
- Compliance Consulting:FDA 21 CFR Part 820 gap assessments, ISO 13485 implementation, and audit preparation support. Health Canada's parallel licensing requirements expand outsourcing complexity for cross-border manufacturers seeking simultaneous US-Canada market entry.
- Quality Management Systems:Documentation architecture design, standard operating procedure development, and management review facilitation.
- Risk Assessment:ISO 14971 implementation, failure mode analysis, and post-market risk monitoring framework construction.
Quality Management Systems anchor the largest contract values; Regulatory Strategy Development expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory outsourcing demand concentrates where device innovation clusters intersect with complex FDA submission pathways. Production of regulatory expertise concentrates in established consulting hubs while consumption spreads across emerging device corridors.
United States
California's medtech corridor and Massachusetts' device innovation cluster generate the heaviest outsourcing demand for 510(k) clearance support and breakthrough designation navigation. FDA's evolving digital health guidance and software-as-a-medical-device framework pull manufacturers toward specialized compliance partners. San Francisco Bay Area and San Diego ventures prioritize modular engagements over fixed regulatory overhead.
Canada
Cross-border manufacturers seeking simultaneous US-Canada market entry expand outsourcing complexity through Health Canada's Medical Devices Bureau requirements. Ontario and Quebec device firms navigate parallel but distinct licensing standards that demand redundant documentation architectures. Toronto-Waterloo corridor shows concentrated demand for regulatory bridge services spanning FDA and Health Canada interfaces.
California
Venture-backed cardiovascular and neurology startups in the San Francisco Bay Area accelerate reliance on external regulatory partners to compress time-to-market. FDA's intensified post-market surveillance mandates expand recurring revenue opportunities beyond one-time submission support. San Diego's imaging ventures drive specialized demand for AI-enabled diagnostic compliance expertise.
Massachusetts
Boston-Cambridge's concentration of early-stage therapeutic device developers creates embedded partnership opportunities for consultancies willing to co-locate technical teams. Class III device PMA pathway navigation and combination product submissions command premium positioning among local cardiovascular innovators. Breakthrough designation proliferation sustains accelerating growth in pre-market consulting engagements.
Texas
Houston's medical center complex and Austin's emerging health tech ecosystem generate diversified demand across diagnostic and monitoring device categories. Mid-sized manufacturers lacking in-house regulatory infrastructure purchase discrete overflow capacity for ISO 13485 implementation and audit preparation. Dallas-Fort Worth surgical equipment developers concentrate 510(k) technical file preparation outsourcing.
North America Medical Device Regulatory Affairs Outsourcing Market Competitive Landscape
The competitive structure tilts toward integrated clinical-regulatory platforms rather than narrow compliance boutiques. Large-scale outsourcing relationships anchor around consultancies offering end-to-end submission management spanning investigational device exemption pathways through post-market surveillance. Three archetypes dominate: integrated CRO-regulatory hybrids, specialized FDA-Health Canada bridge services, and therapeutic-area embedded partners. Consolidation pressure intensifies as manufacturers seek single-source accountability across complex multi-jurisdiction filings.
Among integrated platform operators, PAREXEL anchors large-scale relationships through its combined clinical and regulatory infrastructure. ICON plc occupies a position exemplifying specialized transatlantic regulatory bridge capabilities. Medpace represents the therapeutic-area depth archetype, embedding teams within cardiovascular and neurology device development workflows rather than maintaining transactional vendor distance.
| Leading Market Players |
|---|
| PAREXEL (US) |
| Medpace (US) |
| ICON plc (IE) |
| IQVIA, Inc. |
| Laboratory Corporation of America Holdings |
| Charles River Laboratories (US) |
| Syneos Health (US) |
| Freyr |
| Emergo |
| Others |
Value Network & Pricing Analysis
The Bureau of Labor Statistics professional and business services employment cost index cascades through regulatory consultancy pricing tiers, compressing margins for mid-sized manufacturers while amplifying pricing power for consultancies with embedded FDA submission expertise.
Pricing Analysis
Cost-down pressure on clinical trial services accelerates because talent scarcity in biostatistics and FDA 21 CFR Part 820 expertise elevates salary competition. Project-based retainers dominate, with pricing stratifying across breakthrough designation navigation, 510(k) clearance support, and post-market surveillance modules. Certification depth—ISO 13485 implementation versus basic gap assessment—drives price differentiation. Venture-backed startups in California's medtech corridor exhibit highest price sensitivity, prioritizing milestone-based engagements over fixed overhead. Established cardiovascular manufacturers in Massachusetts show lowest sensitivity, purchasing embedded partnership models.
Supply Chain Analysis
Dual-sourcing requirements for regulatory talent mandate multi-consultancy qualification across FDA submission management, Health Canada licensing, and ISO 13485 audit support. Supply concentrates in the United States, Ireland, and Canada, with clinical data scientists and biostatisticians forming the critical talent chokepoint. Raw material dependencies include specialized regulatory software platforms, predicate device databases, and FDA correspondence archives. Single-source vulnerability sits with consultancies holding exclusive FDA pre-submission meeting relationships. Distribution runs through direct enterprise sales to device manufacturers and channel partnerships with venture capital firms sourcing regulatory support for portfolio companies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Artificial intelligence-enabled diagnostic submissions are displacing traditional evidentiary frameworks, forcing consultancies to reconstitute technical review capacity around machine learning validation protocols.
For Market Incumbents: Acquire specialized biostatistical and clinical data science teams to anchor AI-integrated diagnostic submission expertise. Consolidate position by embedding technical staff within Massachusetts cardiovascular device development workflows, countering modular unbundling from venture-backed competitors. Invest in ISO 13485 quality management system architecture ahead of FDA harmonization with International Medical Device Regulator Forum standards. For New Entrants and Emerging Players: Hospital system partnership channels offer the most penetrable entry vector, particularly for real-world performance monitoring services where FDA mandates expand recurring revenue beyond one-time submission support. Target Texas mid-sized surgical equipment manufacturers lacking in-house regulatory infrastructure for discrete overflow capacity contracts. Lead with cybersecurity documentation and interoperability standards alignment for remote patient monitoring systems. For Investors and Strategic Acquirers: Distressed-cycle entries favor therapeutic-area specialists in Massachusetts and California where breakthrough designation proliferation sustains premium positioning. Long-term viability hinges on consultancies scaling technical review capacity for software-as-a-medical-device frameworks. Watch FDA enforcement timeline for International Medical Device Regulator Forum harmonization as inflection indicator for quality management system recalibration demand.| Strategic Initiative | Industry Significance |
|---|---|
| FDA Submission | 510(k) clearance documentation anchors high-volume recurring revenue for established consultancies. |
| Hospital System Partnership | Embedded post-market surveillance contracts capture FDA intensified real-world performance monitoring mandates. |
| Software Companion Development | AI-enabled diagnostic compliance expertise differentiates consultancies in California's neurology device cluster. |
| Reimbursement Strategy | Breakthrough designation navigation commands premium pricing among Massachusetts cardiovascular innovators. |
| CE Marking Pathway | European-American regulatory bridge services sustain complex multi-jurisdiction submission relationships. |
Research Methodology
Multi-period observation of FDA submission volume trends, Health Canada licensing patterns, and regulatory consultancy hiring data anchored the trend analysis, supplemented by interviews with regulatory affairs directors, biomedical engineers, GPO contracts managers, and venture capital portfolio operations leads. Secondary validation drew from FDA 510(k) clearance databases, Health Canada Medical Device Active Licence Listing, ISO 13485 certification registries, and SEC filings from publicly traded CROs. Bottom-up service segment sizing triangulated against top-down market aggregation.
Input-output matrices modeled demand drivers across pre-market consulting, clinical trial services, submission management, and post-market surveillance segments, with therapeutic vertical and organizational scale as cross-cutting dimensions. CAGRs derived from regression analysis of historical outsourcing penetration rates and forward projection of FDA digital health guidance implementation. Forecast inputs incorporated investigational device exemption pathway complexity indices and AI-enabled device submission volume trajectories across the analysis window.
Caveats apply where FDA harmonization timeline delays, Health Canada regulatory divergence, or artificial intelligence evidentiary standard revisions could materially shift the outlook. Deviation in mid-sized manufacturer in-house regulatory team retention would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Anterior Cervical Fixation Devices Market
Medical Devices
Slit Lamps Market
Medical Devices
Global Lithotripsy Device Market
Medical Devices
Bare Metal Stents Market
Medical Devices
Saudi Arabia Anesthesia Devices Market
Medical Devices
Leadless Cardiac Pacemaker Market
Medical Devices
Tumour Ablation Devices Market
Medical Devices
Global Catheter Stabilization Devices Market
Medical Devices
Appendage Management Market
Medical Devices
Global Endovenous Ablation Devices Market
Medical Devices
Pannus Retraction Device Market
Medical Devices
At-Home Laser Hair Removal Devices Market
Medical Devices
Thermal Ablation Devices Market
Medical Devices
US Clear Aligners Market
Medical Devices
Nephrostomy Catheters Market
Medical Devices
Non-Invasive Ultrasound Stimulation Market