
 Minimally Invasive Neurosurgical Devices Market | 2026-2036
Minimally Invasive Neurosurgical Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Minimally Invasive Neurosurgical Devices Market Analysis
Neurosurgical fellowship training capacity is rotating toward robotic and navigation platforms, expanding the pool of surgeons qualified to perform image-guided procedures. Medtronic leverages its integrated surgical navigation ecosystem to anchor premium system placements across North American academic medical centers. Stryker competes through its specialized spine navigation hardware, while Penumbra differentiates with neurovascular access technologies that reduce procedural footprint.
Minimally invasive neurosurgical devices comprise precision instruments, visualization systems, and navigation platforms designed to access cranial and spinal pathologies through reduced-entry trajectories, typically operating through ports smaller than 20 millimeters with stereotactic or real-time image guidance. These systems serve to limit iatrogenic tissue disruption, shorten recovery intervals, and enable intervention in anatomically constrained regions previously requiring open craniotomy or laminectomy. Endoscopes occupy the largest product category due to their ubiquity across ventricular and skull-base procedures, while robotic-assisted technology represents the fastest-expanding segment as capital budgets shift toward systems offering sub-millimeter accuracy. Neurovascular surgery commands concentrated R&D investment because thrombectomy and aneurysm repair devices carry premium pricing and repeat-purchase consumable streams.
FDA 510(k) clearance requirements govern neurosurgical device commercialization in the United States, while the EU Medical Device Regulation imposes stricter clinical evidence standards for Class III neurological implants across European markets. Japan's PMDA maintains distinct technical documentation requirements that elongate registration timelines for foreign manufacturers of navigation-enabled instruments. Stakeholders must monitor reimbursement coding decisions for robotic-assisted neurosurgery, as category I versus category III CPT designations will determine hospital capital commitment and procedure volume trajectories.
Market Dynamics
Robotic-assisted neurosurgical platforms are compressing the traditional hierarchy between academic medical centers and community hospitals, redistributing procedural capability across facility tiers previously stratified by capital access.
Growth Catalysts
- FDA 510(k) Pathway Efficiency:Streamlined premarket notification for Class II neurosurgical instruments accelerates commercialization timelines for navigation-integrated systems in the United States.
- Neurovascular Disease Burden:Rising incidence of ischemic stroke and cerebral aneurysm across aging populations in Germany and Japan sustains procedural volume for thrombectomy and coiling devices.
- Fluorescence-Guided Resection:5-aminolevulinic acid visualization technology enables more complete tumor removal in glioma cases, expanding addressable surgical indications.
Market Restraints
- Capital Equipment Intensity:Robotic neurosurgical platforms require multimillion-dollar installation commitments that strain community hospital budgets and extend replacement cycles.
- Specialized Component Supply:High-precision optical sensors and electromagnetic tracking arrays concentrate sourcing among Japanese and German component manufacturers, creating vulnerability.
- Reimbursement Coding Uncertainty:Unresolved Category I versus Category III CPT designations for robotic-assisted intracranial procedures dampen hospital capital commitment in the United States.
Strategic Opportunities
- Ambulatory Surgical Center Penetration:Lumbar decompression and select spinal navigation cases are migrating to outpatient settings in the United States, opening new channel infrastructure.
- EU MDR Harmonization:Stricter clinical evidence requirements for Class III neurological implants create first-mover advantage for manufacturers with robust trial portfolios.
- Artificial Intelligence Fusion:Machine learning integration with intraoperative imaging is bifurcating preoperative planning from real-time decision support, enabling new software-as-service revenue streams.
Industry Challenges
- Cross-Training Bottleneck:Fellowship programs produce insufficient volumes of surgeons simultaneously qualified in both open and image-guided minimally invasive techniques.
- Interoperability Friction:Navigation platforms from competing manufacturers resist seamless data exchange with hospital PACS and EMR systems, complicating workflow integration.
- Consumable Margin Compression:Single-use neurosurgical instruments face procurement consolidation as hospital systems standardize across fewer vendor relationships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Minimally Invasive Neurosurgical Devices Market |
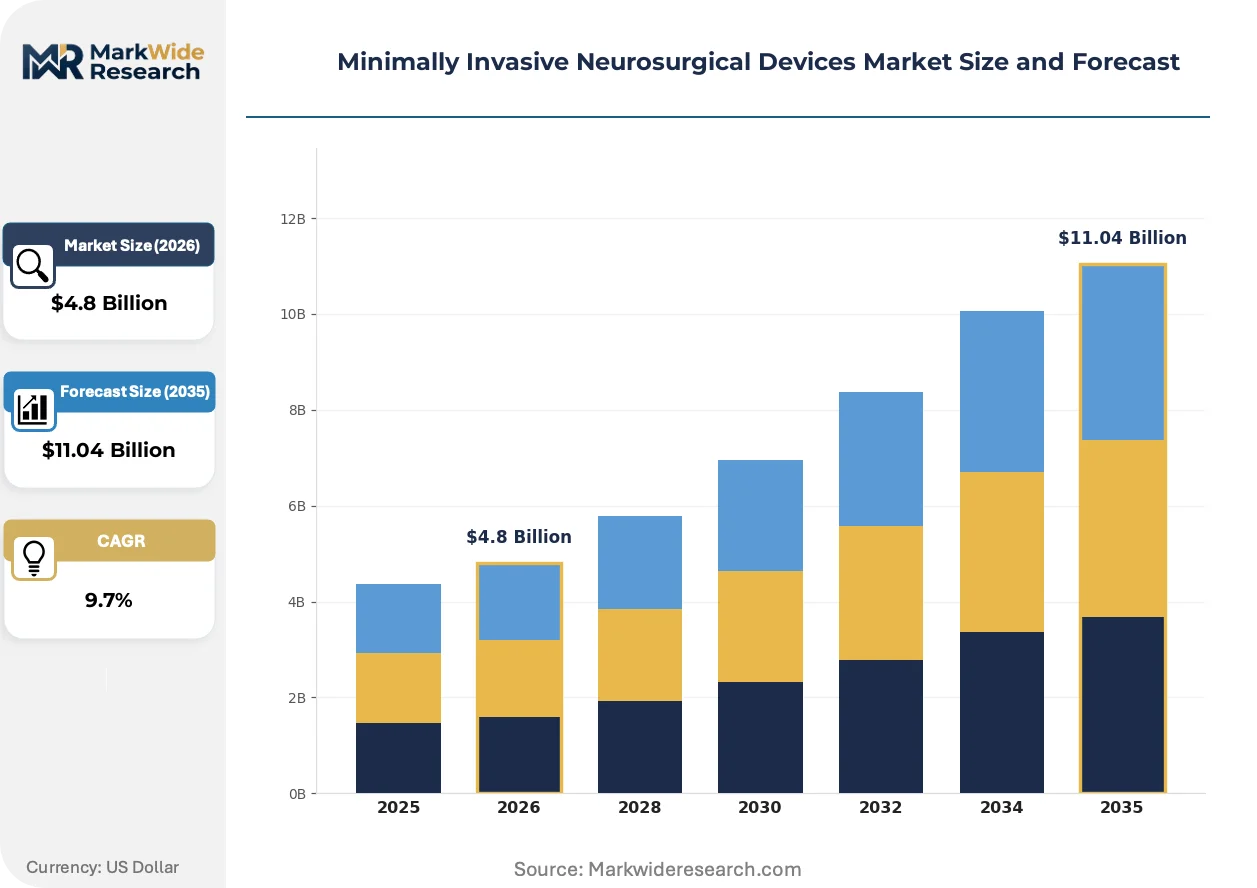
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $11.04 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Endoscopes, Laser Devices, Trocar Kits, Biopsy Needles Application: Neuro Oncology, Neurovascular Surgery, Spine Surgery, Pain Management Technology: Robotic-Assisted, Arduino-Based, Imaging Systems, Navigation Systems End User: Hospitals, Neurosurgery Clinics, Research Institutions, Diagnostic Centers |
| Companies Covered | Zimmer Biomet, Olympus Corporation, Medtronic, Integra LifeSciences, Boston Scientific Corporation, Stryker, Karl Storz, Penumbra, Johnson & Johnson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Minimally Invasive Neurosurgical Devices Market Emerging Trajectories
Digital surgery ecosystems are collapsing the boundary between preoperative planning and intraoperative execution, embedding artificial intelligence and augmented reality into previously mechanical instrument categories.
Intraoperative magnetic resonance imaging is bifurcating the neurosurgical workflow between conventional navigation and real-time anatomical verification. Academic medical centers in the United States and Germany are adopting these systems for eloquent-area tumor resections. The technology is bifurcating capital allocation between premium real-time imaging suites and conventional navigation-only installations.
Japan's PMDA has elongated technical documentation requirements for navigation-enabled instruments, extending registration timelines for foreign manufacturers. This regulatory friction is compressing competitive entry for non-domestic device makers. European and North American manufacturers are responding by establishing in-country clinical trial infrastructure and local regulatory affairs capabilities.
Hospital procurement departments are unbundling after-sales service contracts from capital equipment purchases, shifting toward performance-based maintenance agreements with penalty clauses for system downtime. Original equipment manufacturers face margin pressure as buyers in Germany and the United States demand transparent parts pricing and third-party servicing rights. This behavioral shift is most visible among university hospital consortia consolidating purchasing power across multiple facilities.
Minimally Invasive Neurosurgical Devices Market Segmentation
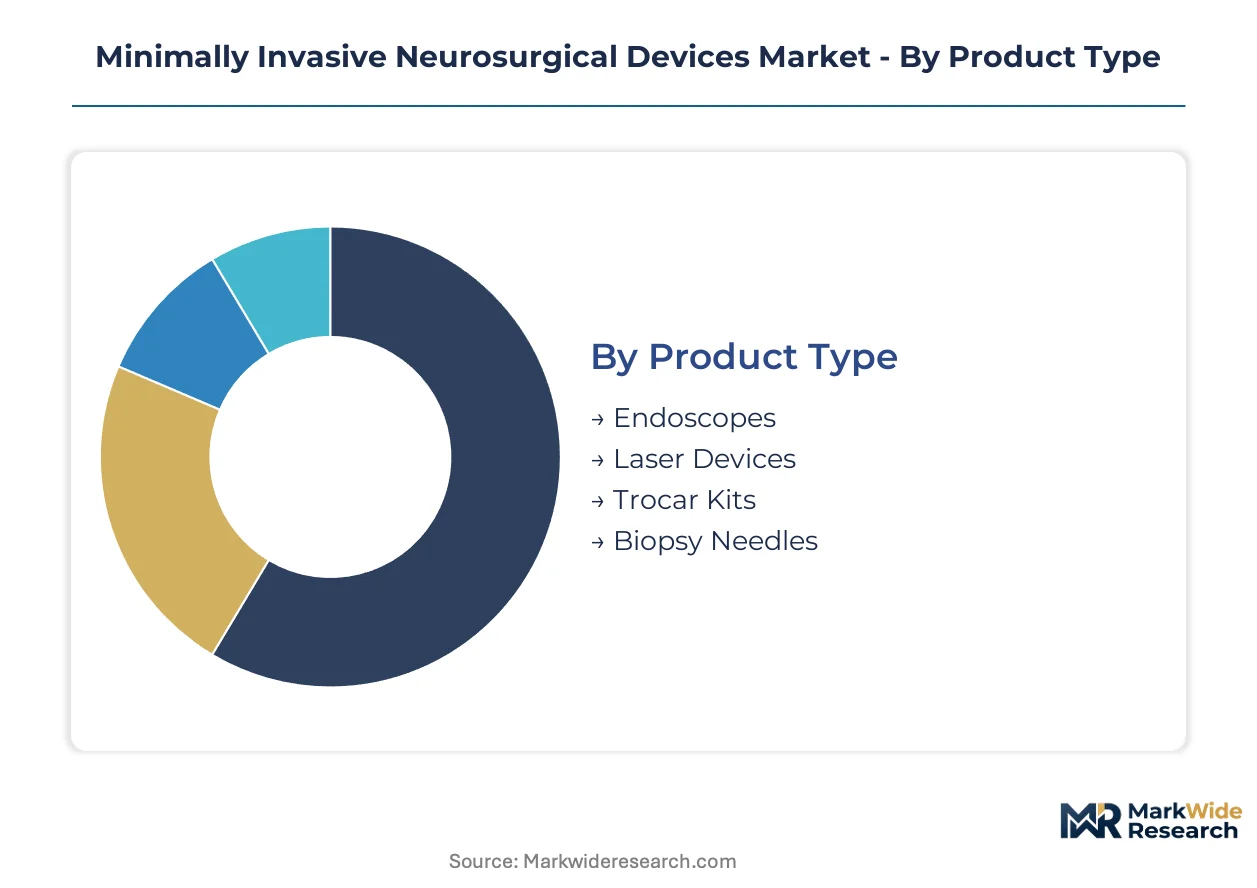
Segmentation in minimally invasive neurosurgical devices reveals how capital allocation, reimbursement pathways, and surgical training capacity distribute demand across product categories. Understanding these divides exposes where substitution pressures and margin compression concentrate most intensely.
Product Type:
Endoscopes face the strongest substitution threat from single-use variants and disposable optical systems that erode traditional capital equipment cycles.
- Endoscopes:Rigid and flexible optical systems with working channels under 4 millimeters enable ventricular and skull-base access. Demand clusters in German university hospitals validating 4K and 3D visualization protocols, constrained by sterilization throughput limits in high-volume centers.
- Laser Devices:Solid-state and fiber-delivered systems for tissue ablation and vascular coagulation operate at 1064nm and 532nm wavelengths. Adoption concentrates in United States academic medical centers pursuing fluorescence-guided resection, held back by capital budget competition with robotic platforms.
- Trocar Kits:Cannulated access systems with diameters ranging 2-12mm establish minimally invasive ports for instrument exchange.
- Biopsy Needles:Stereotactic and image-guided aspiration devices obtain tissue samples through burr-hole trajectories.
Endoscopes retain volume leadership; laser devices hold the steepest expansion curve.
Application:
Cost tier stratification separates premium-priced neurovascular interventions from commoditized pain management procedures with thinner device margins.
- Neuro Oncology:Resection and biopsy of intracranial tumors leverages fluorescence-guided visualization and intraoperative MRI compatibility. United States academic centers drive demand for 5-aminolevulinic acid-integrated workflows, constrained by limited Category I CPT reimbursement for adjunct technologies.
- Neurovascular Surgery:Thrombectomy, aneurysm coiling, and flow diversion procedures command premium device pricing with repeat-purchase consumable streams. Japanese stroke centers sustain procedural volume under PMDA-accelerated approval pathways for mechanical retrieval devices.
- Spine Surgery:Lumbar decompression and fusion navigation through tubular retractors migrates toward ambulatory settings.
- Pain Management:Radiofrequency ablation and spinal cord stimulation lead placement address chronic neuropathic conditions.
Neurovascular surgery captures the highest revenue per procedure; spine surgery is expanding most quickly into outpatient channels.
Technology:
Application maturity separates decades-old imaging modalities from emerging robotic platforms still seeking standardized training curricula.
- Robotic-Assisted:Electromechanical arms with sub-millimeter stereotactic accuracy execute planned trajectories under surgeon supervision. United States hospital systems prioritize FDA 510(k)-cleared platforms with open instrument compatibility, slowed by unresolved Category III CPT coding for intracranial applications.
- Arduino-Based:Open-source microcontroller platforms enable low-cost custom surgical tool development and prototyping. Research institutions in Germany exploit these systems for experimental navigation algorithms, constrained by clinical translation barriers and liability frameworks.
- Imaging Systems:Intraoperative MRI and CT provide real-time anatomical verification during eloquent-area resections.
- Navigation Systems:Optical and electromagnetic tracking overlays preoperative imaging onto surgical fields.
Navigation systems retain installed base dominance; robotic-assisted platforms are gaining share fastest through academic medical center adoption.
End User:
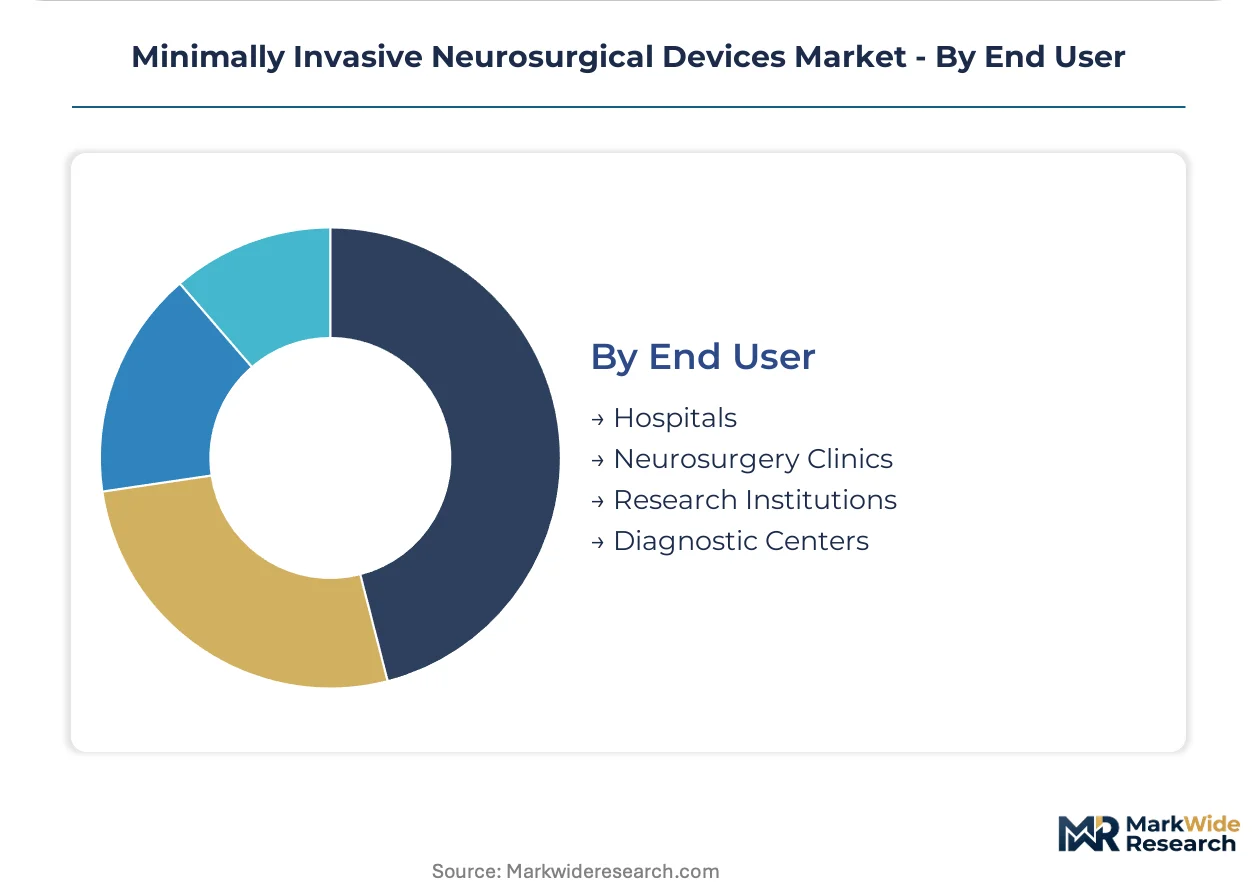
Customer procurement power concentrates in hospital systems with consolidated purchasing authority, squeezing standalone clinic margins.
- Hospitals:Tertiary and community facilities with neurosurgical service lines deploy capital-intensive robotic and navigation platforms. United States health systems with centralized value analysis committees delay adoption pending Category I CPT confirmation, while German university hospitals validate technologies through prospective trials.
- Neurosurgery Clinics:Specialized outpatient facilities perform select spine and pain procedures with lower capital requirements. These settings in the United States exploit ambulatory surgical center reimbursement differentials, constrained by limited emergency backup capacity for complications.
- Research Institutions:Academic medical centers and university hospitals conduct clinical validation and training program development.
- Diagnostic Centers:Imaging-focused facilities perform stereotactic biopsies and preoperative planning.
Hospitals retain capital expenditure leadership; neurosurgery clinics are climbing the fastest as procedure migration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA 510(k) clearance pathways anchor the United States as the dominant geography, while Japan's PMDA and Germany's BfArM impose distinct regulatory architectures that reshape competitive entry patterns across their respective markets.
United States
Academic medical centers in Boston and Baltimore drive validation of intraoperative MRI-integrated workflows, while community hospital systems delay robotic platform procurement pending Category I CPT coding resolution. FDA premarket notification requirements for Class II navigation instruments compress commercialization timelines relative to European counterparts. The Cleveland Clinic and Johns Hopkins anchor clinical trial networks for fluorescence-guided resection technologies.
Germany
University hospital consortia in Munich and Heidelberg validate navigation-integrated endoscopic systems through prospective outcome studies. BfArM oversight of Class III neurological implants under EU MDR imposes stricter clinical evidence standards than predecessor directives. The Baden-Württemberg medical technology cluster concentrates precision optical sensor manufacturing for electromagnetic tracking arrays.
Japan
Stroke centers in Tokyo and Osaka sustain procedural volume for mechanical thrombectomy devices under PMDA-accelerated approval pathways. Elongated technical documentation requirements for navigation-enabled instruments compress competitive entry for foreign manufacturers. The Kanto region anchors domestic production of high-precision surgical robotics components.
United Kingdom
NHS England's specialized commissioning frameworks concentrate neurovascular intervention capacity in London and Manchester tertiary centers. MHRA post-Brexit regulatory autonomy maintains alignment with EU MDR while streamlining recognition of FDA-cleared devices. The Oxford-Cambridge arc hosts navigation algorithm development partnerships between academic medical centers and instrumentation firms.
India
Corporate hospital chains in Mumbai and Bangalore expand minimally invasive spine surgery capacity to capture medical tourism flows. CDSCO medical device rules impose distinct registration requirements for navigation-enabled instruments that elongate market entry timelines. The Maharashtra medical device manufacturing zone hosts contract production of disposable trocar kits for export markets.
Minimally Invasive Neurosurgical Devices Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered competitive structure where premium navigation ecosystems coexist with commoditized single-use instruments. Integrated surgical platform vendors anchor the premium tier through installed base lock-in, while specialized component suppliers capture margin in optical tracking and electromagnetic sensor arrays. M&A activity concentrates among navigation software firms seeking hardware integration, and strategic partnerships between academic medical centers and device manufacturers accelerate clinical validation timelines.
Within the diversified medical technology tier, Medtronic and Stryker occupy positions exemplifying integrated platform strategies, while Karl Storz represents specialized visualization leadership. Olympus Corporation anchors the endoscopic instrument segment through rigid and flexible optical system portfolios. These three firms collectively illustrate how geographic origin—Dublin-based, Kalamazoo-based, and Tuttlingen-based respectively—correlates with distinct regulatory navigation capabilities and academic medical center relationship architectures.
| Leading Market Players |
|---|
| Zimmer Biomet |
| Olympus Corporation |
| Medtronic |
| Integra LifeSciences |
| Boston Scientific Corporation |
| Stryker |
| Karl Storz |
| Penumbra |
| Johnson & Johnson |
| Others |
Supply Flow & Price Mechanics
Ninety-day inventory buffers for high-precision optical sensors concentrate pricing power among Japanese and German component manufacturers, compressing margins for downstream device assemblers while amplifying cost pass-through to United States hospital systems. This lead-time architecture embeds supply scarcity directly into capital equipment quotations, with electromagnetic tracking arrays commanding premium positioning against commoditized disposable trocar kits.
Pricing Analysis
United States academic medical centers pay 40-60% premiums over German university hospital consortia for identical navigation-integrated robotic platforms, reflecting divergent procurement consolidation and service bundling practices. Pricing stratifies across FDA 510(k)-cleared premium tiers, CE-marked standard configurations, and economy-grade non-navigated instruments. Cost compression in consumable categories intensifies as hospital GPOs consolidate vendor relationships. Neurosurgery clinics exhibit highest price sensitivity; integrated platform vendors face lowest bargaining pressure.
Supply Chain Analysis
Just-in-time inventory strategies dominate for single-use biopsy needles and trocar kits, while strategic stockpiling persists for Japanese-sourced optical sensors and German electromagnetic tracking arrays vulnerable to extended replenishment cycles. Manufacturing concentrates in Germany for precision optics, Japan for surgical robotics components, and India for disposable access systems. Supply chains draw from high-purity fused silica, rare-earth magnetic materials, and medical-grade stainless steel. Single-source vulnerability concentrates in 1064nm laser crystal production. Distribution runs through hospital value analysis committees and GPO contract frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pool of surgeons cross-trained in both open and image-guided minimally invasive techniques remains critically shallow, constraining procedural volume expansion regardless of capital equipment availability. This capability gap defines competitive moats and acquisition premiums across the ecosystem.
For Market Incumbents: Shield installed base lock-in by embedding proprietary navigation software into hospital EMR and PACS architectures, raising switching costs for competing platforms. Deepen backward integration into optical sensor production to reduce dependency on Japanese component suppliers facing PMDA-extended lead times. Prioritize FDA 510(k) pathway efficiency for next-generation fluorescence-guided resection modules before Category I CPT coding resolves. For New Entrants and Emerging Players: Differentiate on AI-integrated intraoperative decision support, bifurcating from hardware-saturated robotic platform competition. Target ambulatory surgical center penetration for lumbar decompression navigation, the fastest-climbing channel with lower capital barriers. Pursue software-as-service revenue models decoupled from multimillion-dollar equipment sales cycles. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because navigation software firms with hospital workflow integration represent scarce acquisition targets as hardware vendors seek vertical completeness. Watch for Category I CPT coding confirmation for robotic-assisted intracranial procedures as the inflection signal triggering hospital capital commitment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Hospital System Partnership | Johns Hopkins and Cleveland Clinic networks validate fluorescence-guided resection protocols for glioma applications. |
| Reimbursement Strategy | Category I CPT designation pursuit determines United States academic medical center capital commitment timing. |
| Software Companion Development | Machine learning integration with intraoperative MRI enables new SaaS revenue streams beyond hardware sales. |
| CE Marking Pathway | EU MDR clinical evidence requirements create first-mover advantage for manufacturers with robust trial portfolios. |
| Backward Integration | In-house production of electromagnetic tracking arrays reduces exposure to German and Japanese supplier concentration. |
Methodological Framework
Initial hypotheses were tested against primary input from neurosurgical department chairs, hospital purchasing committee members, biomedical engineering directors, and GPO contracts managers and refined through secondary validation. Sources included FDA 510(k) clearance databases, EU MDR technical documentation filings, hospital procurement contract repositories, and CMS reimbursement coding decisions. Bottom-up procedure volume estimates triangulated against top-down capital equipment shipment data across the analysis window.
Variance decomposition separated volume drivers from pricing dynamics across product type, application, technology, and end user dimensions. CAGRs were derived from modeled procedure growth rates and device replacement cycles rather than macroeconomic extrapolation. Forecast inputs incorporated fellowship training program expansion trajectories and regulatory pathway efficiency differentials between FDA, BfArM, and PMDA jurisdictions.
Material uncertainties — reimbursement coding resolution timelines, supply chain disruption in precision optics, and cross-training pipeline bottlenecks — sit outside the modeled envelope. Forecasts reflect documented assumptions about hospital capital budget recovery and regulatory harmonization progress. Revision becomes warranted when Category I CPT designation for robotic-assisted intracranial procedures crosses confirmation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Blood Clot Retrieval Devices Market
Medical Devices
Global Intragastric Balloon Market
Medical Devices
Craniomaxillofacial Implants Market
Medical Devices
Global Artificial Kidney Market
Medical Devices
Surgical Helmet Systems Market
Medical Devices
Pneumatic Nebulizers Market
Medical Devices
Neurosurgical Products Market
Medical Devices
Nerve Repair and Regeneration Market
Medical Devices
Global Connected Medical Devices Market
Medical Devices
Mexico Spinal Surgery Devices Market
Medical Devices
Brachytherapy Afterloaders Market
Medical Devices
Nerve Monitoring Devices Market
Medical Devices
Pediatric Home-Use Medical Devices Market
Medical Devices
Middle East and Africa Biomedical Sensors Market
Medical Devices
Wearable Medical Robots Market
Medical Devices
Global Surgical Visualization Products Market