
 Saudi Arabia Artificial Organs and Bionic Implants Market | 2026-2036
Saudi Arabia Artificial Organs and Bionic Implants Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Artificial Organs and Bionic Implants Market Analytics
Saudi Arabia is tilting toward localized biomedical manufacturing capacity under Vision 2030 health sector transformation targets. Medtronic plc anchors its regional cardiac rhythm management supply through established distribution partnerships across the Kingdom. Edwards Lifesciences Corporation differentiates via transcatheter heart valve technologies aligned with Saudi cardiac center expansion. Boston Scientific Corporation competes in interventional cardiology and neuromodulation device segments serving Ministry of Health hospitals.
Artificial organs and bionic implants comprise engineered mechanical, electromechanical, or biological substitutes designed to replace or augment native organ function, typically incorporating biocompatible polymers, titanium alloys, or living cellular matrices fabricated through precision machining or additive manufacturing. These devices restore physiological performance in patients with end-stage organ failure, traumatic injury, or congenital defects. Heart and kidney product categories dominate current procurement volumes given the prevalence of cardiovascular and renal disease in the Saudi population. Electromechanical systems technology leads installed base metrics, while biofabrication represents the fastest-growing segment as SFDA accelerates approval frameworks for regenerative therapies. Hospitals constitute the primary end-user channel, absorbing the majority of implantable device value through centralized Ministry of Health tender processes.
SFDA medical device registration requirements shape market access timelines and clinical evidence standards for imported and locally manufactured implants. The Saudi Commission for Health Specialties coordinates practitioner certification protocols that constrain bionic implant procedure expansion to accredited tertiary centers. International Organization for Standardization (ISO) 13485 quality management benchmarks govern supplier qualification for public hospital procurement. Stakeholders must monitor SFDA regulatory science initiatives around 3D-printed patient-specific implants to anticipate competitive positioning shifts.
Market Dynamics
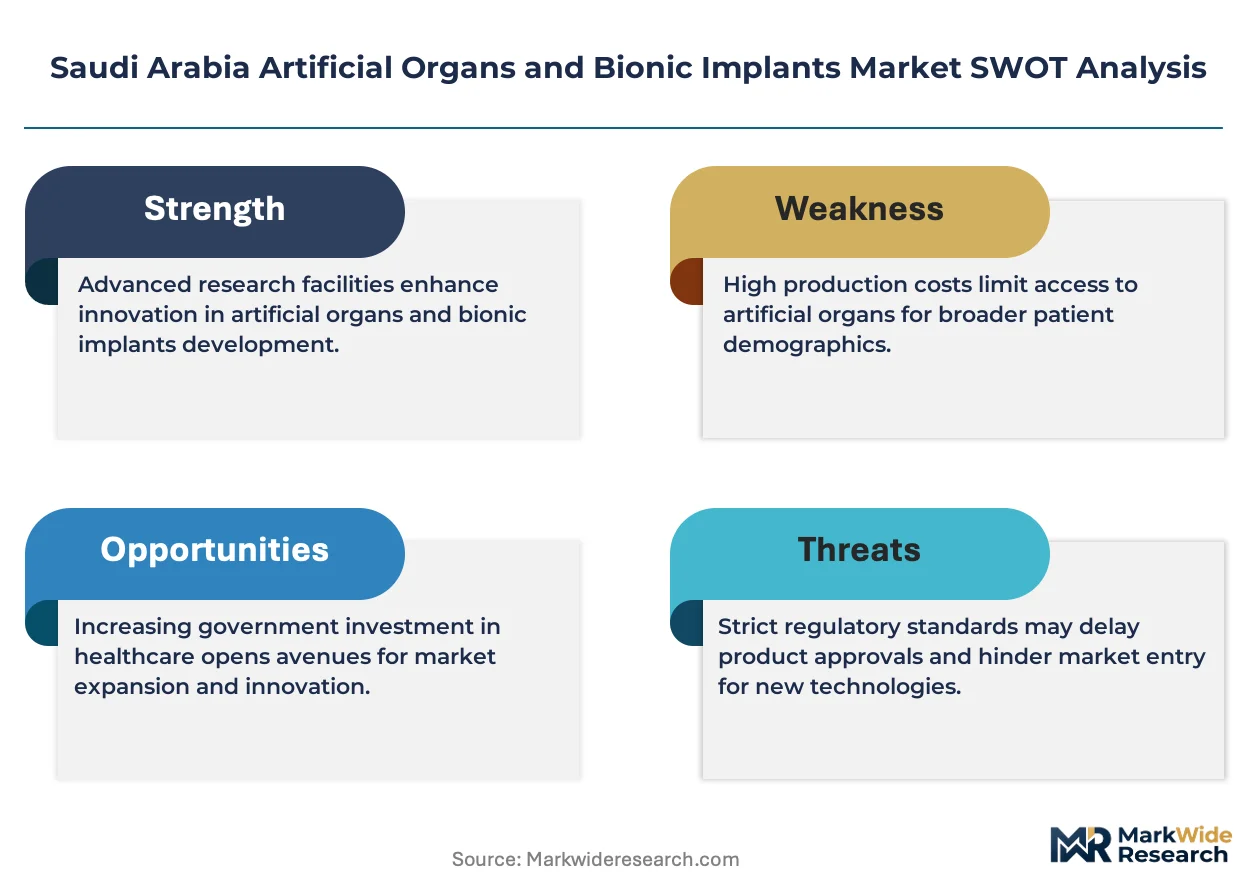
SFDA's accelerated medical device registration pathways for 3D-printed patient-specific implants are compressing approval timelines and forcing incumbent distributors to localize technical support capabilities. This regulatory momentum is redistributing competitive advantage toward manufacturers with captive biofabrication expertise.
Growth Catalysts
- Vision 2030 health sector transformation:Domestic manufacturing incentives are attracting biofabrication investment to King Abdullah Economic City industrial clusters.
- Cardiac center expansion:Ministry of Health tertiary hospital construction in Riyadh and Jeddah is expanding procedural capacity for complex implant interventions.
- Biofabrication technology maturation:Living cellular matrix printing is crossing clinical viability thresholds for patient-matched organ scaffolds.
Market Restraints
- Titanium alloy supply concentration:Import dependency on East Asian precision metal suppliers exposes procurement to shipping cost volatility and tariff uncertainty.
- SFDA clinical evidence requirements:Novel regenerative therapies face extended pre-market validation timelines that delay revenue recognition for developers.
- Biocompatible polymer substitution:Advanced ceramic composites are displacing polymer matrices in orthopedic load-bearing applications, stranding legacy material inventories.
Strategic Opportunities
- Eastern Province penetration gap:Dammam and Khobar medical infrastructure remains underserved relative to Riyadh for complex bionic implant procedures.
- SFDA regulatory science initiatives:Early engagement with the agency's 3D-printed implant framework offers first-mover positioning for localized production.
- Telemedicine-integrated follow-up:Remote monitoring protocols are opening rural patient access to tertiary center implant programs.
Industry Challenges
- Biofabrication technician scarcity:Saudi Commission for Health Specialties has not yet established certification pathways for additive manufacturing operators in clinical settings.
- Cleanroom capex intensity:ISO 13485-compliant cellular matrix production requires capital outlays that exceed mid-market manufacturer balance sheet capacity.
- Legacy device integration:Electromechanical cardiac assist systems face interoperability friction with emerging bioelectronic control architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Artificial Organs and Bionic Implants Market |
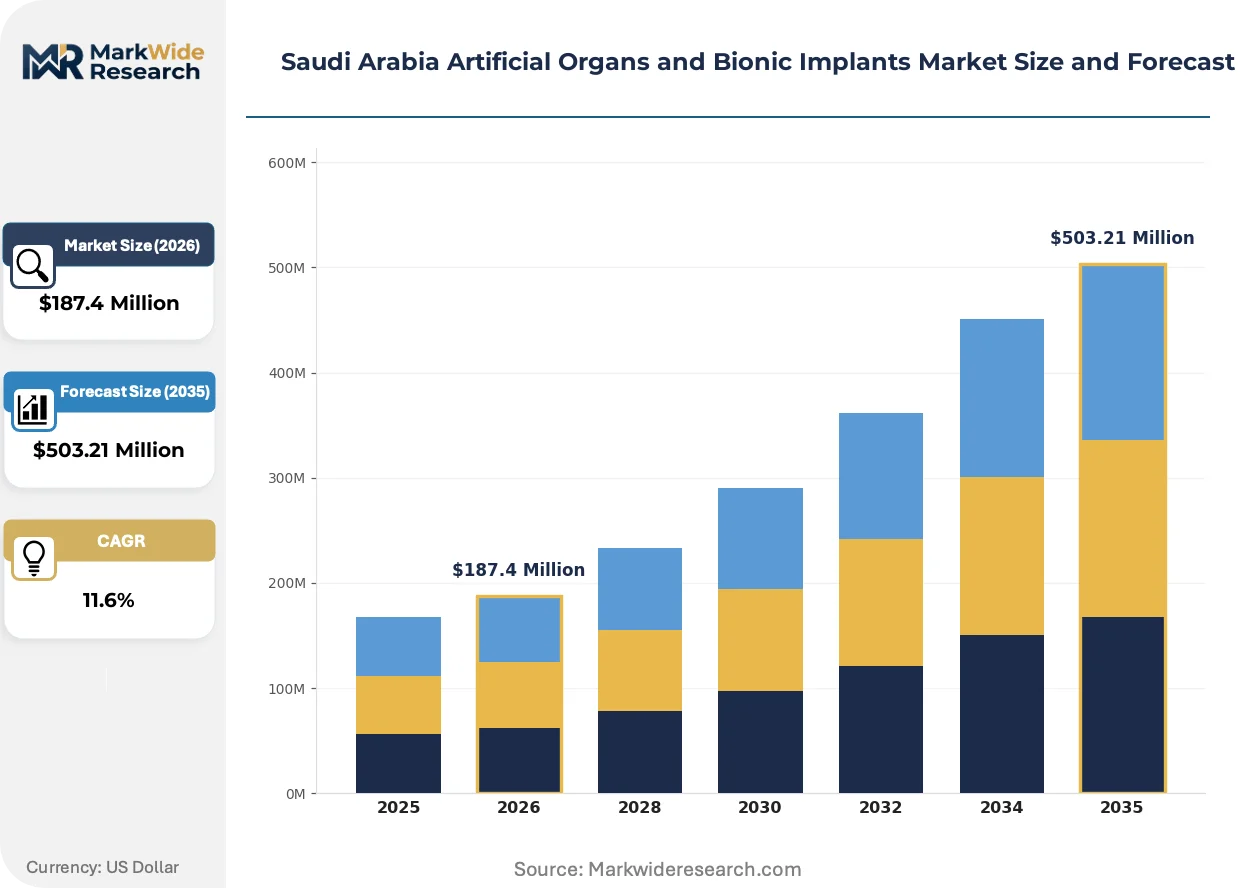
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Heart, Kidney, Liver, Pancreas End User: Hospitals, Clinics, Rehabilitation Centers, Research Institutions Technology: 3D Printing, Biofabrication, Electromechanical Systems, Cellular Technology Application: Transplantation, Organ Failure Treatment, Research, Medical Training |
| Companies Covered | Cochlear Limited, Edwards Lifesciences Corporation, Medtronic plc, Abbott Laboratories, Berlin Heart GmbH, Zimmer Biomet Holdings, Inc., Jarvik Heart, Inc., Boston Scientific Corporation, Ekso Bionics Holdings Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Artificial Organs and Bionic Implants Market Evolving Landscape
Convergence between electromechanical engineering and cellular biology is dissolving traditional boundaries between device and tissue replacement. Three distinct trajectories are restructuring how artificial organs are designed, regulated, and procured.
Bioprinting platforms incorporating vascular channel networks are hybridizing mechanical support structures with living tissue matrices. King Faisal Specialist Hospital surgical teams are piloting these hybrid constructs for complex reconstructive procedures. The technology is hybridizing the procurement categories that hospitals use to separate prosthetics from transplant services.
SFDA's 2024 medical device guidance on patient-specific implants is formalizing quality management requirements for point-of-care manufacturing. Domestic hospital networks must now establish ISO 13485-equivalent processes for in-house biofabrication. Cardiac and orthopedic centers with existing quality infrastructure are adapting fastest to these documentation burdens.
Ministry of Health tender processes are consolidating implant procurement into multi-year framework agreements with technical service bundling. Single-source contracting is displacing spot purchasing for high-value cardiac devices. This concentration is most visible in Riyadh's tertiary care cluster, where King Saud Medical City and National Guard Hospital anchor regional supply arrangements.
Saudi Arabia Artificial Organs and Bionic Implants Market Segmentation
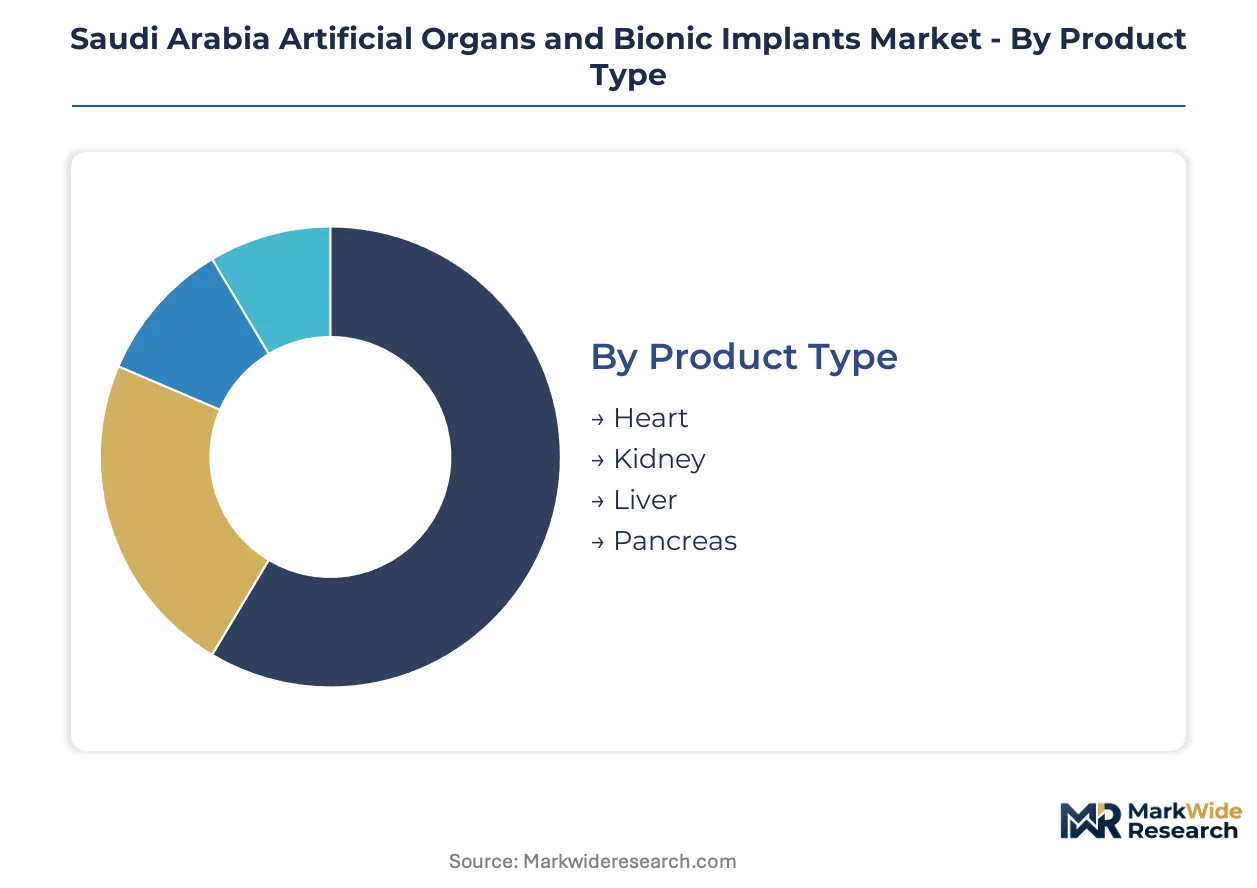
Segmentation reveals how procurement authority, technological maturity, and clinical infrastructure concentrate demand across distinct channels in Saudi Arabia. Understanding these divides exposes where SFDA regulatory pathways and Vision 2030 manufacturing incentives redirect competitive investment.
Product Type:
Volume concentration tracks disease burden patterns across the Kingdom's tertiary care network.
- Heart:Cardiac assist devices and total artificial hearts incorporate biocompatible polymers and titanium alloy housings. King Faisal Specialist Hospital anchors complex implant volumes in Riyadh, where Ministry of Health cardiac center expansion accelerates procurement timelines.
- Kidney:Wearable and implantable renal replacement systems filter blood through semipermeable membranes or bioengineered cellular matrices. Dialysis dependency rates in the Saudi population sustain demand through hospital-based procurement frameworks.
- Liver:Bioartificial liver support systems bridge patients to transplant through hepatocyte-based extracorporeal circuits.
- Pancreas:Closed-loop insulin delivery systems and islet cell encapsulation devices target diabetes management protocols.
Heart commands the established base. The steepest expansion runs through Kidney.
End User:
Customer type determines reimbursement pathways, technical service requirements, and SFDA registration complexity.
- Hospitals:Tertiary medical centers perform complex implant procedures under centralized Ministry of Health tender processes. Riyadh's care cluster absorbs the majority of high-value device procurement through multi-year framework agreements.
- Clinics:Outpatient facilities manage post-implant monitoring and device programming adjustments for cardiac rhythm management systems.
- Rehabilitation Centers:Bionic limb fitting and neuroprosthetic training programs serve trauma and congenital defect populations.
- Research Institutions:Academic medical centers pilot biofabrication protocols and patient-specific implant validation studies.
Hospitals dominate procurement value. Research Institutions are gaining share fastest as SFDA accelerates regenerative therapy frameworks.
Technology:
Maturity gradients separate proven electromechanical platforms from emerging biofabrication capabilities.
- 3D Printing:Additive manufacturing produces patient-matched orthopedic implants and surgical guides from titanium alloys and bioresorbable polymers. SFDA's 2024 guidance on point-of-care manufacturing forces hospital networks to adopt ISO 13485-equivalent quality systems.
- Biofabrication:Living cellular matrix printing constructs vascularized tissue scaffolds for organ replacement. King Abdullah Economic City industrial clusters attract domestic manufacturing investment under Vision 2030 health sector transformation targets.
- Electromechanical Systems:Mature pump and sensor technologies power ventricular assist devices and neurostimulators.
- Cellular Technology:Stem cell-derived therapies and tissue engineering approaches target functional organ restoration.
Electromechanical Systems anchor current installed capacity. Biofabrication shows the steepest capability buildout trajectory.
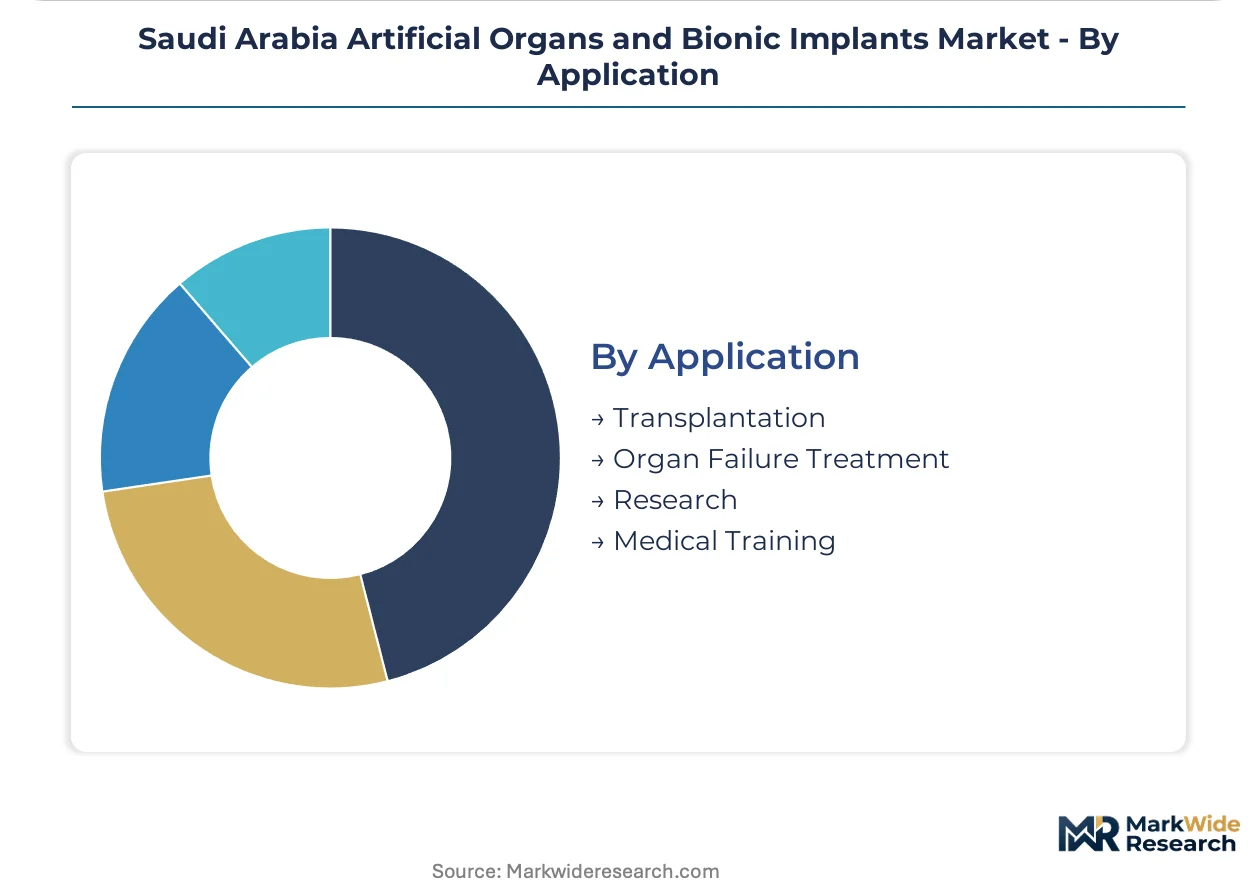
Application:
Use case differentiation separates revenue-generating clinical procedures from capability-building activities.
- Transplantation:Bridge-to-transplant and destination therapy applications deploy artificial hearts and bioartificial organs as alternatives or adjuncts to donor organ availability. SFDA organ donation registry constraints amplify demand for mechanical substitutes.
- Organ Failure Treatment:Chronic support systems sustain patients with end-stage disease through implantable or wearable platforms. Cardiovascular and renal disease prevalence in the Saudi population drives procurement concentration here.
- Research:Preclinical and clinical validation studies advance regenerative therapy platforms toward market authorization.
- Medical Training:Simulation and cadaveric training programs build surgical capability for complex implant procedures.
Organ Failure Treatment generates current revenue concentration. Transplantation applications are expanding most quickly as biofabrication crosses clinical viability thresholds.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Titanium alloy precision machining concentrates in East Asian supplier networks, exposing Saudi procurement to shipping cost volatility. Domestic biofabrication capacity is emerging through Vision 2030 industrial clustering incentives. SFDA regulatory pathways are compressing approval timelines for localized production.
Riyadh
King Faisal Specialist Hospital anchors complex cardiac implant volumes through tertiary care concentration. SFDA medical device registration pathways accelerate procurement for hospitals meeting ISO 13485 benchmarks. King Abdullah Financial District medical clusters attract biofabrication investment under health sector transformation targets.
Eastern Province
Dammam and Khobar medical infrastructure remains underserved for complex bionic implant procedures relative to Riyadh capacity. Ministry of Health cardiac center construction is expanding procedural availability. King Abdullah Economic City industrial zones host emerging domestic manufacturing capabilities for patient-specific implants.
Western Region
Jeddah tertiary hospital expansion is accelerating cardiac assist device procurement through centralized tender processes. Saudi Commission for Health Specialties coordinates practitioner certification for complex implant procedures. Red Sea coastal medical corridors integrate with telemedicine follow-up protocols for rural patient access.
NEOM Northwest
Greenfield healthcare infrastructure development is incorporating biofabrication capabilities into next-generation medical city planning. Vision 2030 health sector transformation targets prioritize localized production capacity. Regulatory sandbox frameworks are piloting accelerated SFDA pathways for 3D-printed patient-specific implants.
Saudi Arabia Artificial Organs and Bionic Implants Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying biocompatible polymers and titanium alloys. The Saudi market structures around three tiers: multinational device manufacturers with established SFDA registrations, regional distributors managing Ministry of Health tender access, and emerging domestic fabricators building point-of-care capabilities. Strategic moves concentrate on localization partnerships for technical service bundling and captive biofabrication expertise acquisition.
Within the multinational tier, Medtronic plc, Edwards Lifesciences Corporation, and Boston Scientific Corporation exemplify established SFDA registration holders. Medtronic anchors regional cardiac rhythm management supply through distribution partnerships. Edwards Lifesciences occupies a position aligned with transcatheter heart valve technologies. Boston Scientific sits within interventional cardiology and neuromodulation segments serving public hospital networks.
| Leading Market Players |
|---|
| Cochlear Limited |
| Edwards Lifesciences Corporation |
| Medtronic plc |
| Abbott Laboratories |
| Berlin Heart GmbH |
| Zimmer Biomet Holdings, Inc. |
| Jarvik Heart, Inc. |
| Boston Scientific Corporation |
| Ekso Bionics Holdings Inc. |
| Others |
Value Network & Pricing Analysis
Titanium alloy import dependency on East Asian precision metal suppliers exposes Saudi procurement to shipping cost volatility and tariff uncertainty, compressing margin structures across premium cardiac device tiers while forcing Ministry of Health tender participants to absorb freight escalation or localize fabrication. This concentration dynamic widens price spreads between ISO 13485-certified premium implants and standard-grade alternatives, reshaping how distributors structure technical service bundling.
Pricing Analysis
SFDA medical device registration requirements dictate the pricing tier structure across the Saudi market, separating premium-certified cardiac implants from economy-tier alternatives through clinical evidence burdens and quality management audits. Pricing stratifies across premium, standard, and economy tiers based on certification grade and after-sales service intensity, with tertiary hospital procurement committees showing lowest price sensitivity due to outcome-based reimbursement frameworks. Cost compression in the standard tier is intensifying because East Asian titanium suppliers are passing through freight escalation, while premium-tier margins remain defended by technical service bundling requirements in Ministry of Health framework agreements.
Supply Chain Analysis
Export control regimes on precision metalworking equipment limit technology transfer to Saudi biofabrication startups, constraining domestic capacity buildout despite Vision 2030 incentives. Supply concentrates in China, South Korea, and Japan for titanium alloy precision machining, while biocompatible polymer feedstocks draw from German and US specialty chemical producers. Single-source vulnerability runs through East Asian titanium suppliers, with distribution running through regional distributors holding SFDA registration credentials and Ministry of Health tender access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Recurring technical service revenue from implant monitoring and device programming is expanding faster than hardware sales, creating service-attach economics that favor incumbents with established clinical support infrastructure.
For Market Incumbents: Insulate installed base positions by deepening backward integration into biofabrication capabilities at King Abdullah Economic City industrial zones, countering emerging domestic competitors before SFDA point-of-care manufacturing frameworks mature. Acquire ISO 13485-certified service capabilities in the Eastern Province to preempt Dammam cardiac center expansion tenders. For New Entrants and Emerging Players: Eastern Province tertiary infrastructure gaps offer procedural capacity entry points below Riyadh's consolidated supply arrangements, particularly for remote monitoring-integrated cardiac assist programs. Target rehabilitation center bionic limb fitting networks with telemedicine-enabled follow-up protocols, bypassing capital-intensive cleanroom requirements that constrain hospital-based competitors. For Investors and Strategic Acquirers: SFDA's 2024 guidance on 3D-printed patient-specific implants reshapes the acquisition landscape toward biofabrication expertise holders with captive vascularized tissue scaffold capabilities. Five-to-ten year viability hinges on regulatory science engagement depth rather than current revenue scale; monitor SFDA approval velocity for patient-matched organ scaffolds as the inflection signal for platform valuation resets.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Registration Pathway Acceleration | Compresses market access timelines for biofabrication platforms seeking hospital procurement eligibility. |
| King Abdullah Economic City Manufacturing Scale-Up | Captures Vision 2030 incentives while reducing titanium alloy import dependency exposure. |
| Hospital System Technical Service Partnership | Locks in multi-year framework agreements through bundled device programming and remote monitoring. |
| Software Companion Development | Enables telemedicine-integrated follow-up protocols for rural patient access expansion. |
| Reimbursement Strategy Alignment | Positions biofabricated implants within Ministry of Health destination therapy coverage frameworks. |
Research Methodology
A spread of perspectives from cardiac surgeons, biomedical engineers, hospital purchasing committee members, and SFDA regulatory affairs specialists converged on the working assumptions driving segmentation and growth estimates. Primary interviews with Ministry of Health procurement officers and King Faisal Specialist Hospital surgical teams combined with secondary validation against SFDA medical device registration databases, hospital tender records, and ISO 13485 certification registries. Bottom-up demand modeling across product categories triangulated against top-down macroeconomic health expenditure projections.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon, with segmentation modeled across product type, end user channel, technology maturity tier, and application use case. CAGRs derived from procedure volume trajectories at accredited tertiary centers, SFDA approval velocity assumptions for regenerative therapies, and Vision 2030 manufacturing incentive uptake rates. Biofabrication technician pipeline constraints and cleanroom capital intensity thresholds served as industry-specific forecast inputs.
Practitioners should monitor SFDA regulatory science initiative announcements, East Asian titanium supplier tariff policy shifts, and King Abdullah Economic City industrial cluster occupancy rates for early signals of trajectory revision. Material shifts in SFDA point-of-care manufacturing enforcement timelines or Ministry of Health tender consolidation patterns would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Transradial Access Devices Market
Medical Devices
Pre-Filled Hemostasis Agents Market
Medical Devices
Pelvic Floor Electrical Stimulation Devices Market
Medical Devices
Battery-Operated Lactate Meter Market
Medical Devices
Single Lead ECG Equipment Market
Medical Devices
Global Hemorrhoid Treatment Devices Market
Medical Devices
Intravascular Temperature Management Systems Market
Medical Devices
Flexible and Semi-Rigid Ureteroscopy Market
Medical Devices
US SNF Based Dialysis Market
Medical Devices
Eye Socket Implants Market
Medical Devices
Global Hydrogel Based Drug Delivery System Market
Medical Devices
Laryngoscopes Market
Medical Devices
Australia Drug Delivery Devices Market
Medical Devices
Breast Pump Flange Market
Medical Devices
Skincare Devices Market
Medical Devices
Nonablative Laser Resurfacing Devices Market