
 North America Wheelchair Market | 2026-2036
North America Wheelchair Market Size, Share, and Industry Trends Forecast 2026-2036
North America Wheelchair Market Intelligence
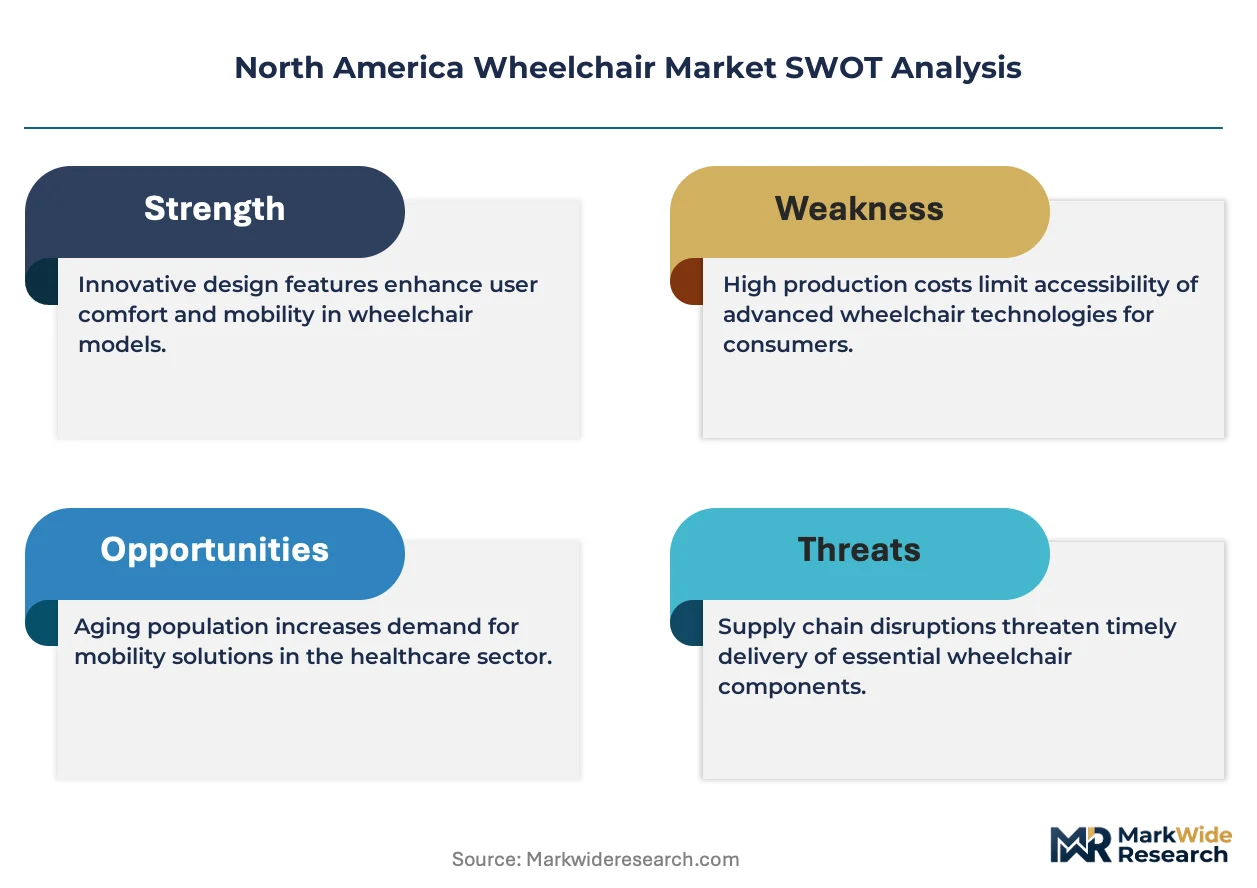
Lightweight titanium and carbon-fiber specification tiers is collapsing the traditional steel-frame cost floor, forcing manufacturers to restructure material sourcing or exit the premium segment entirely. Sunrise Medical Inc. leverages its European manufacturing footprint to sustain North American distribution density without domestic assembly overhead. Invacare Corporation anchors its position through vertical control over seating and electronics subsystems. Permobil competes on software-integrated power bases that differentiate clinical outcomes for spinal cord injury users.
A wheelchair is a mobility assistive device comprising a seating system mounted on a wheeled base, typically constructed from aluminum, steel, or composite materials, with manual propulsion via handrims or motorized drive systems powered by lithium-ion or lead-acid batteries; its primary purpose is to restore independent locomotion for individuals with impaired ambulation. Power wheelchairs now capture the dominant margin pool as reimbursement complexity and clinical documentation requirements favor prescription-driven sales over retail channels. Manual wheelchairs remain structurally mature, with lightweight material technology representing the only remaining vector for product differentiation outside commodity hospital discharges. Rehabilitation centers constitute the fastest-growing end-user channel as accountable care organizations push shorter acute stays into outpatient settings.
The FDA Center for Devices and Radiological Health classifies wheelchairs as Class II medical devices requiring 510(k) clearance, while CMS National Coverage Determinations shape reimbursement eligibility and access volume across Medicare and Medicaid programs. Health Canada and the CSA Group maintain parallel standards that create dual-compliance obligations for cross-border suppliers. State-level Medicaid prior authorization programs add fragmentation that disadvantages smaller distributors lacking dedicated reimbursement staff. Stakeholders must monitor how CMS competitive bidding expansion affects pricing power and whether FDA software-as-medical-device guidance extends to smart wheelchair navigation systems.
Market Dynamics
CMS competitive bidding expansion and FDA 510(k) documentation requirements are compressing distributor margins while concentrating procurement authority among vertically integrated manufacturers with dedicated reimbursement infrastructure.
Growth Catalysts
- Rehabilitation Infrastructure Density:Accountable care organizations in the southeastern United States are accelerating outpatient rehabilitation center construction, creating concentrated demand nodes for prescription-driven power wheelchair deployment.
- CMS National Coverage Determinations:Medicare reimbursement rule evolution is elevating clinical documentation standards that favor manufacturers with in-house seating and electronics subsystem capabilities over retail channel competitors.
- Lithium-Ion Battery Chemistry:Energy density improvements in portable power systems are extending daily range specifications for power wheelchair users, opening community mobility applications previously constrained by lead-acid performance ceilings.
Market Restraints
- Titanium and Carbon-Fiber Input Costs:Lightweight specification tiers depend on aerospace-grade material sourcing that exposes manufacturers to commodity volatility and supply rationing from priority defense and aviation contracts.
- State-Level Medicaid Fragmentation:Prior authorization program heterogeneity across fifty state jurisdictions creates compliance overhead that disadvantages smaller distributors lacking dedicated reimbursement staff.
- Manual Wheelchair Commoditization:Hospital discharge channel price compression leaves minimal margin for R&D recovery, trapping manufacturers in steel-frame cost floors that titanium and carbon-fiber alternatives are collapsing.
Strategic Opportunities
- Software-Integrated Power Bases:FDA software-as-medical-device guidance extension to smart wheelchair navigation systems would create first-mover advantage for manufacturers with embedded sensor and algorithm capabilities.
- Cross-Border Canadian Market:Health Canada and CSA Group dual-compliance obligations create barrier-to-entry protection for suppliers already certified under FDA Class II medical device standards.
- Home Healthcare Provider Consolidation:Medicare reimbursement rule tightening is driving independent durable medical equipment suppliers toward acquisition by national home health networks, creating volume concentration for preferred vendor agreements.
Industry Challenges
- Clinical Documentation Specialist Scarcity:Power wheelchair prescription fulfillment requires specialized knowledge of CMS National Coverage Determinations and state Medicaid prior authorization workflows that outpaces training pipeline capacity.
- Legacy Electronics Integration:Seating and drive control subsystem interoperability with third-party environmental control units creates firmware compatibility testing burdens that extend product development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Wheelchair Market |
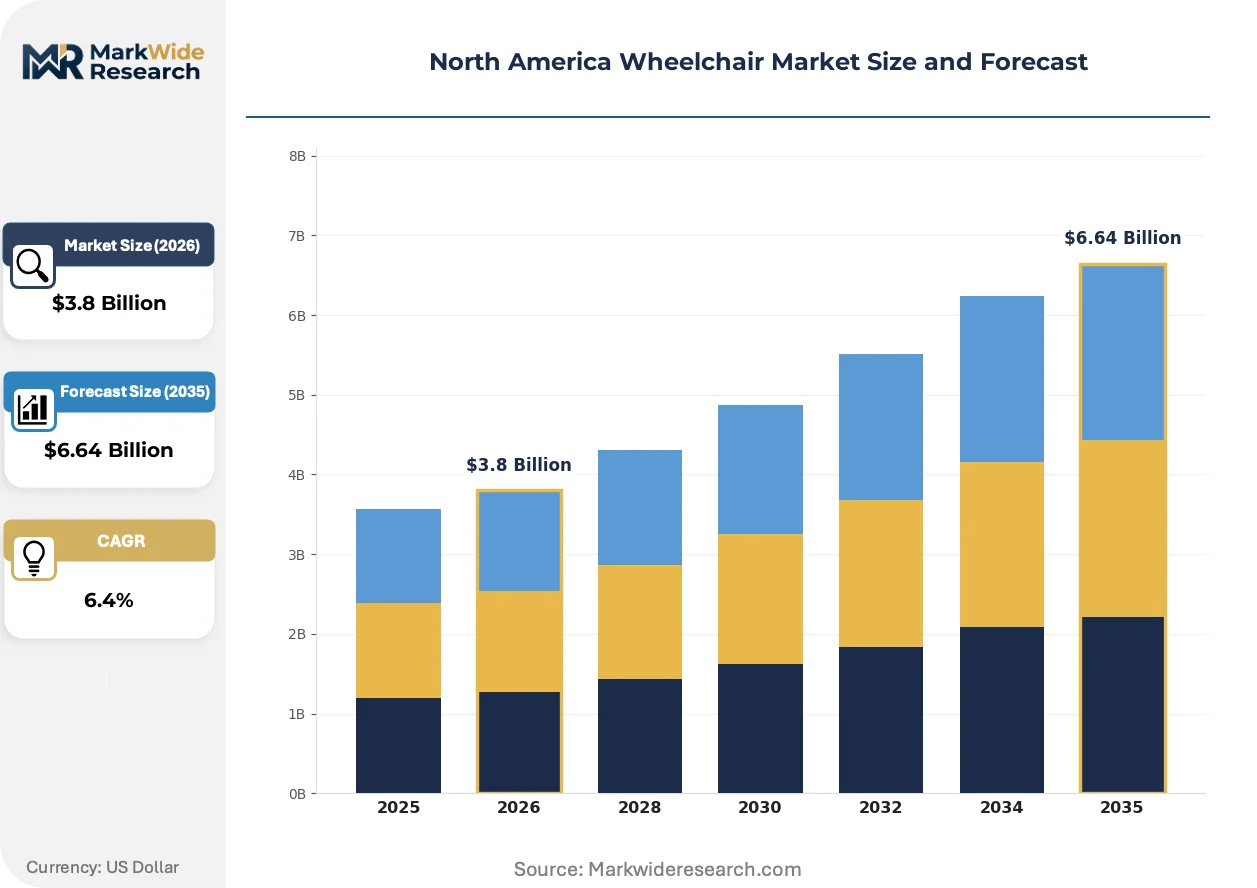
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual Wheelchairs, Power Wheelchairs, Sports Wheelchairs, Standing Wheelchairs End User: Elderly, Disabled Individuals, Hospitals, Rehabilitation Centers Technology: Smart Wheelchairs, Lightweight Materials, Adjustable Features, Customizable Designs Distribution Channel: Online Retail, Medical Supply Stores, Direct Sales, Wholesale Distributors |
| Companies Covered | Sunrise Medical Inc., Hoveround Corporation, Invacare Corporation, GF Health Products, 21st Century Scientific, Permobil, Ottobock SE & Co. KGaA, Drive DeVilbiss Healthcare, Pride Mobility Products Corp., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Wheelchair Market Strategic Shifts & Innovations
Material substitution and regulatory digitization are restructuring competitive positioning across the North American wheelchair supply base, with software-defined functionality emerging as the primary differentiation vector.
Carbon-fiber frame construction is displacing aluminum and steel specifications in the lightweight manual wheelchair segment. Rehabilitation centers and spinal cord injury clinics are prioritizing sub-ten-kilogram configurations for active-user prescriptions. This material transition is compressing margin pools for manufacturers without captive composite fabrication or European manufacturing partnerships.
FDA Center for Devices and Radiological Health software-as-medical-device guidance is elevating premarket notification requirements for power wheelchairs with embedded navigation algorithms. Manufacturers must now demonstrate clinical validation for autonomous obstacle avoidance and terrain adaptation features. The spinal cord injury user segment is most affected, with prescription patterns favoring suppliers with documented outcomes data.
Home healthcare providers are consolidating procurement authority through national group purchasing organizations that unbundle after-sales service from equipment acquisition. Independent durable medical equipment dealers are losing direct Medicare billing privileges as networks centralize documentation compliance. This channel compression is most visible in Florida and Texas, where aging demographic concentration attracts specialized home health network expansion.
North America Wheelchair Market Segmentation
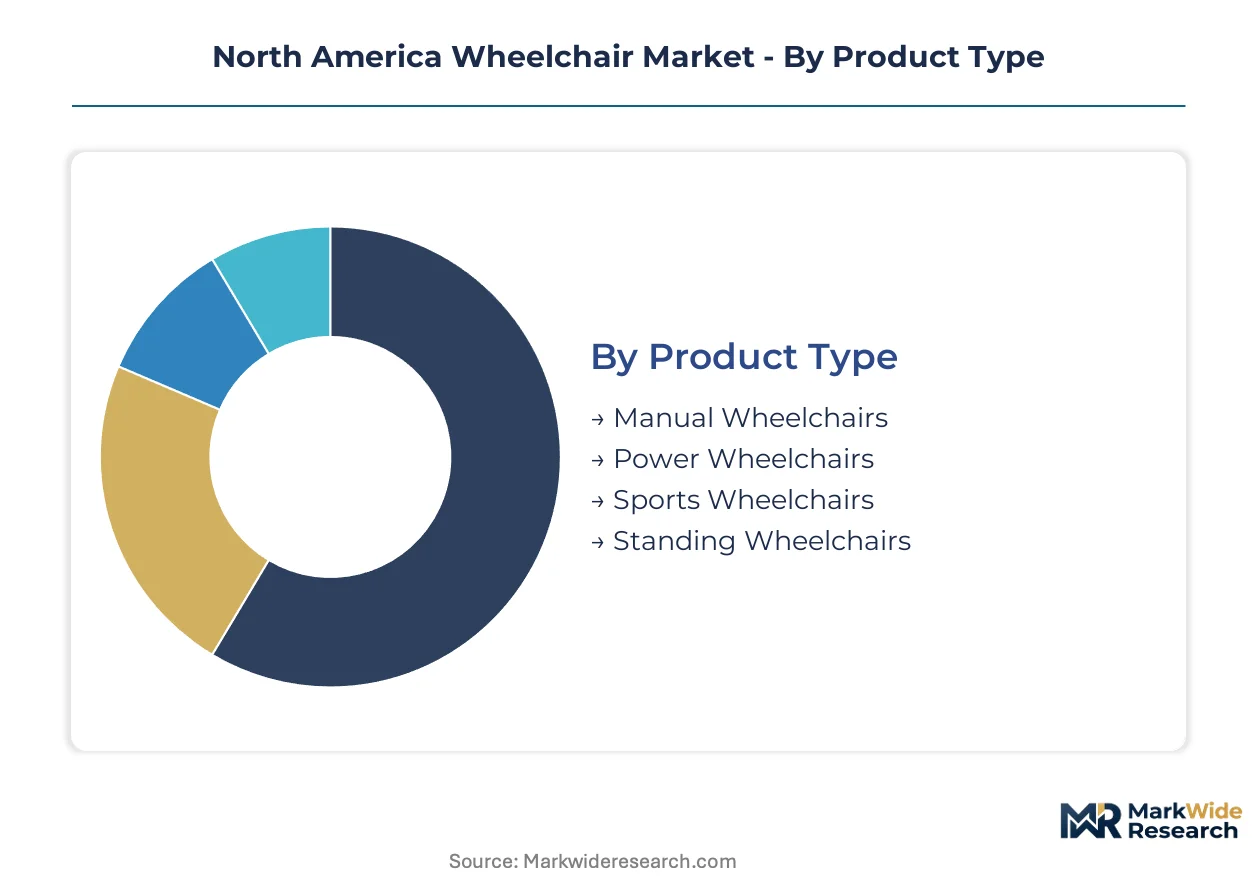
Wheelchair procurement patterns in North America diverge sharply across product specifications and care settings. Medicare reimbursement complexity and state Medicaid fragmentation create distinct demand profiles that reward targeted positioning over broad coverage.
Product Type:
Power wheelchairs face the most acute substitution pressure from smart mobility platforms, while manual wheelchair manufacturers confront titanium and carbon-fiber material substitution collapsing legacy steel-frame economics.
- Manual Wheelchairs:Constructed from aluminum, steel, or composite frames with handrim propulsion systems. Hospital discharge channels in the southeastern United States drive volume, though titanium and carbon-fiber alternatives are compressing margin pools for steel-frame suppliers.
- Power Wheelchairs:Motorized drive systems powered by lithium-ion or lead-acid batteries with programmable seating controls. Rehabilitation centers in Florida and Texas concentrate prescription-driven deployment as accountable care organizations shift patients to outpatient settings.
- Sports Wheelchairs:Specialized aluminum or titanium frames with cambered wheels for athletic activity. Veterans Affairs procurement and adaptive sports programs anchor demand in specific metropolitan clusters.
- Standing Wheelchairs:Hydraulic or electromechanical lift mechanisms enabling vertical positioning. Spinal cord injury clinics and specialized rehabilitation facilities represent the concentrated prescriber base.
Manual wheelchairs retain volume leadership across hospital discharge channels; power wheelchairs hold the steepest expansion curve driven by CMS documentation requirements favoring prescription-driven sales.
End User:
Procurement authority is shifting toward consolidated healthcare networks, with independent durable medical equipment dealers losing direct Medicare billing privileges to national home health organizations.
- Elderly:Medicare beneficiaries aged 65 and older representing the largest addressable population. Home healthcare provider consolidation in Florida and Texas is concentrating procurement through preferred vendor agreements.
- Disabled Individuals:Medicaid-eligible adults and private insurance beneficiaries with permanent mobility impairments. State-level prior authorization fragmentation creates compliance overhead that disadvantages smaller distributors.
- Hospitals:Acute care facilities managing post-surgical and trauma-related wheelchair provision. Shorter length-of-stay mandates from accountable care organizations are compressing equipment rental margins.
- Rehabilitation Centers:Outpatient facilities specializing in spinal cord injury, stroke, and amputation recovery. Construction acceleration in the southeastern United States is creating concentrated demand nodes for advanced power base configurations.
Elderly users retain volume leadership through Medicare program scale; rehabilitation centers are climbing the fastest as outpatient infrastructure expands.
Technology:
Margin capture is concentrating in segments where FDA software-as-medical-device guidance creates regulatory moats against commodity competitors.
- Smart Wheelchairs:Embedded sensor arrays and algorithmic navigation systems enabling autonomous obstacle avoidance. FDA Center for Devices and Radiological Health premarket notification requirements are elevating barriers for non-validated systems.
- Lightweight Materials:Carbon-fiber and titanium frame construction achieving sub-ten-kilogram specifications. Aerospace-grade material rationing from priority defense contracts constrains supply availability for North American fabricators.
- Adjustable Features:Modular seating systems with tool-free configuration changes. Hospital and rehabilitation center procurement specifications increasingly mandate rapid customization capabilities.
- Customizable Designs:Patient-specific anthropometric fitting with 3D-mapped pressure distribution. Spinal cord injury clinics prioritize documented clinical outcomes for pressure ulcer prevention.
Lightweight materials retain volume leadership across active-user prescriptions; smart wheelchairs are gaining share fastest pending FDA guidance finalization.
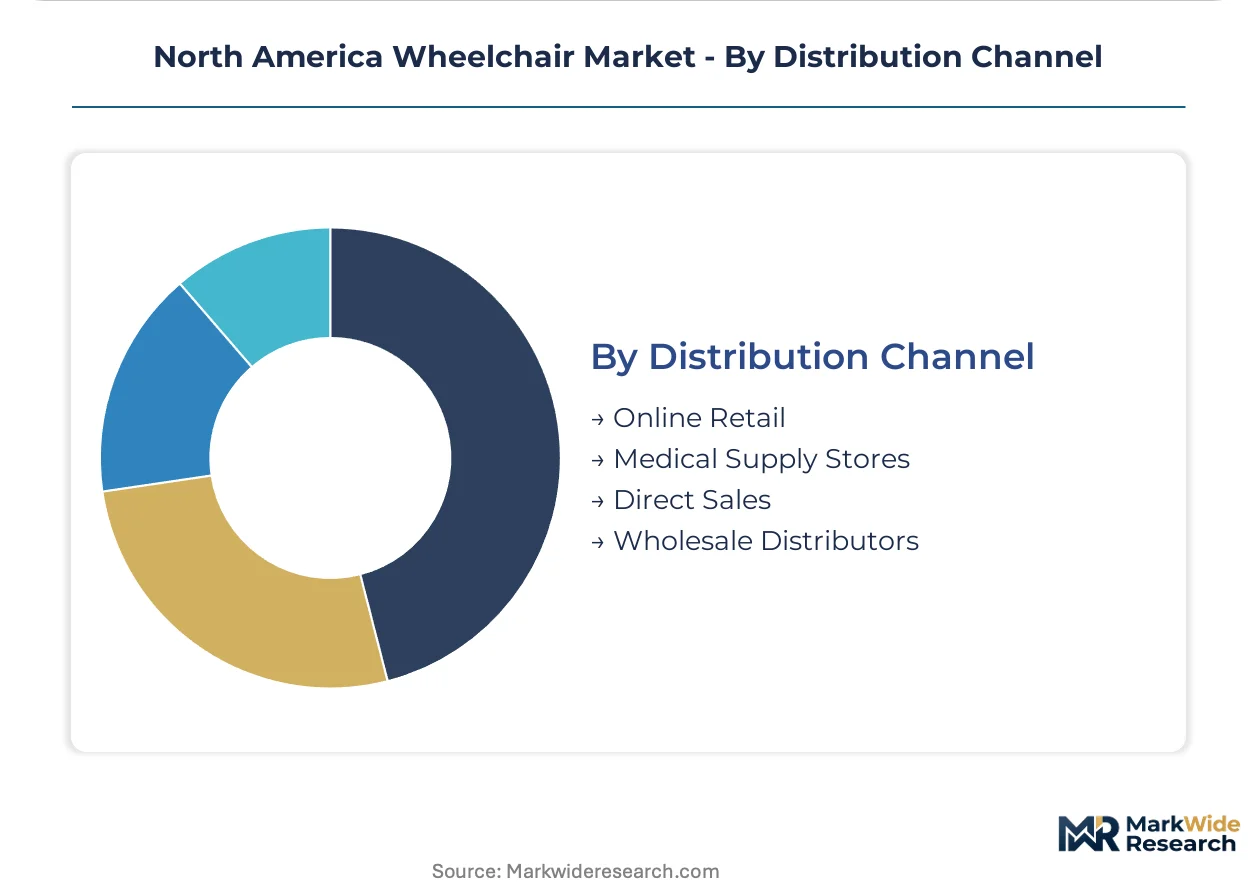
Distribution Channel:
Channel compression is eliminating independent dealer margins as national networks centralize documentation compliance and after-sales service unbundling.
- Online Retail:E-commerce platforms serving cash-pay customers and institutional purchasers with standardized specifications. Medicare reimbursement complexity limits penetration in prescription-driven power wheelchair segments.
- Medical Supply Stores:Brick-and-mortar durable medical equipment dealers with direct billing relationships. Florida and Texas markets show accelerating acquisition activity by national home health networks.
- Direct Sales:Manufacturer-employed specialists handling complex rehabilitation prescriptions. CMS National Coverage Determinations expertise requirements favor vertically integrated suppliers with captive reimbursement staff.
- Wholesale Distributors:Regional inventory aggregators serving independent dealers and smaller hospital systems. State Medicaid prior authorization heterogeneity is driving consolidation toward distributors with multi-jurisdiction compliance infrastructure.
Medical supply stores retain volume leadership in manual wheelchair distribution; direct sales are expanding most quickly as power wheelchair prescription complexity escalates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Assembly and distribution capacity clusters in the Great Lakes and southeastern United States, with Canadian certification requirements creating cross-border compliance specialization among Ontario-based suppliers.
United States
Medicare reimbursement volume and Veterans Affairs procurement anchor demand in Florida, Texas, and California rehabilitation corridors. FDA 510(k) clearance requirements and CMS National Coverage Determinations shape competitive access across fifty state Medicaid programs. The southeastern corridor from Atlanta to Miami concentrates prescription-driven power wheelchair deployment as accountable care organizations expand outpatient infrastructure.
Canada
Aging demographics in Ontario and Quebec drive provincial health program procurement of lightweight manual configurations. Health Canada and CSA Group dual-compliance obligations elevate documentation standards for cross-border suppliers seeking Health Canada Medical Device Establishment Licensing. Toronto and Vancouver serve as distribution nodes for manufacturers leveraging FDA clearance as pathway to Canadian market entry.
Mexico
Private hospital networks in Mexico City and Monterrey generate demand for imported rehabilitation equipment as domestic manufacturing concentrates on basic steel-frame hospital discharge models. COFEPRIS medical device registration creates regulatory lag for advanced power base configurations. Guadalajara medical device cluster shows nascent assembly activity for North American supply chain integration.
North America Wheelchair Market Key Industry Players
Concentration sits with vertically integrated rehabilitation specialists and diversified durable medical equipment conglomerates. The vendor base spans three tiers: premium power base manufacturers with captive electronics capabilities, mid-market manual wheelchair fabricators with European manufacturing partnerships, and commodity hospital discharge suppliers trapped in steel-frame economics. M&A activity targets independent durable medical equipment dealers in Florida and Texas, while technology licensing agreements concentrate around lithium-ion battery management systems.
Among North American rehabilitation specialists, Sunrise Medical Inc., Invacare Corporation, and Permobil exemplify distinct competitive archetypes. Sunrise Medical Inc. represents European manufacturing footprint leverage for North American distribution density. Invacare Corporation anchors vertical control over seating and electronics subsystems. Permobil occupies the software-integrated power base position targeting spinal cord injury prescription patterns.
| Leading Market Players |
|---|
| Sunrise Medical Inc. |
| Hoveround Corporation |
| Invacare Corporation |
| GF Health Products |
| 21st Century Scientific |
| Permobil |
| Ottobock SE & Co. KGaA |
| Drive DeVilbiss Healthcare |
| Pride Mobility Products Corp. |
| Others |
Cost & Logistics Intelligence
Lithium-ion battery chemistry substitution for legacy lead-acid power systems is simultaneously shifting procurement geography toward East Asian cell manufacturers and compressing margin recovery timelines for North American power wheelchair assemblers facing reimbursement rate stagnation.
Pricing Analysis
CMS National Coverage Determinations dictate the pricing tier structure across prescription-driven power wheelchair segments, separating FDA-cleared Class II medical devices with embedded seating electronics from retail-channel manual configurations. Price differentiation hinges on clinical documentation support services and state Medicaid prior authorization success rates rather than hardware specifications alone. Cost compression in the hospital discharge manual wheelchair tier is intensifying because titanium and carbon-fiber import costs expose fabricators to aerospace-grade material rationing. Home healthcare networks exhibit the lowest price sensitivity due to consolidated procurement authority, while independent durable medical equipment dealers face acute margin erosion from documentation compliance overhead.
Supply Chain Analysis
Inventory lead times for carbon-fiber composite frames and lithium-ion battery packs have extended as aerospace and electric vehicle sector demand absorbs priority supply allocations. Manufacturing concentration spans China for battery cell production, Taiwan for power management semiconductors, and Germany for precision drive control components. Raw material dependencies center on cobalt and lithium carbonate feedstocks, aerospace-grade carbon-fiber precursors, and rare-earth magnet materials for brushless motors. Tariff exposure on Chinese-sourced battery cells constitutes the primary structural risk. Distribution runs through national home healthcare networks that have displaced independent dealer channels in Florida and Texas rehabilitation corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized clinical documentation expertise represents the critical capability gap separating viable competitors from margin-compressed commodity suppliers in this reimbursement-governed market.
For Market Incumbents: Fortify vertical control over seating and electronics subsystems against software-integrated power base entrants targeting spinal cord injury prescription patterns. Expand captive reimbursement staff capacity to navigate state-level Medicaid prior authorization fragmentation. Prioritize lithium-ion battery management system R&D partnerships to secure supply priority from East Asian cell manufacturers. For New Entrants and Emerging Players: Post-acute rehabilitation center service-layer gaps in the southeastern United States present concentrated entry points where national home health networks under-serve outpatient spinal cord injury clinics. Target standing wheelchair configurations and adaptive sports program procurement channels where Veterans Affairs procurement specifications favor documented clinical outcomes over scale economies. Pursue direct sales specialist hiring from incumbent reimbursement departments as the primary go-to-market angle. For Investors and Strategic Acquirers: FDA software-as-medical-device guidance finalization reshapes the acquisition landscape by elevating premarket notification burdens for autonomous navigation capabilities. Five-to-ten-year viability favors manufacturers with embedded sensor development pipelines and existing FDA 510(k) clearance track records. Acquire independent durable medical equipment dealers in Florida and Texas exhibiting concentrated Medicare billing volume. Monitor CMS competitive bidding expansion announcements as the definitive inflection signal for pricing power erosion.| Strategic Initiative | Industry Significance |
|---|---|
| Reimbursement Infrastructure Investment | CMS National Coverage Determinations expertise creates procurement preference among home healthcare networks. |
| Software-Defined Power Base Development | FDA software-as-medical-device guidance elevates barriers for non-validated autonomous navigation systems. |
| European Manufacturing Partnership | Sunrise Medical's captive composite fabrication demonstrates cost insulation from aerospace material rationing. |
| Rehabilitation Center Direct Sales Expansion | Accountable care organization outpatient construction in Atlanta-to-Miami corridor concentrates prescription authority. |
| Lithium-Ion Battery Supply Agreement | Energy density improvements extend daily range specifications for community mobility applications. |
Research Approach
The analysis maps manual wheelchair, power wheelchair, sports wheelchair, and standing wheelchair configurations, each validated through rehabilitation clinicians, hospital purchasing committee members, home healthcare network procurement directors, and durable medical equipment reimbursement specialists. Primary interview findings were cross-referenced against FDA 510(k) clearance databases, CMS Medicare claims data, state Medicaid prior authorization program documentation, Health Canada Medical Device Establishment Licensing records, and hospital GPO contract repositories. Bottom-up demand modeling from end-user prescription patterns was reconciled with top-down market sizing from manufacturer shipment disclosures.
Consistency checks against external benchmarks confirmed analytical framework integrity across the projection horizon. Segmentation dimensions modeled include product type, end-user category, technology tier, and distribution channel structure. CAGRs were derived from longitudinal reimbursement volume trends and construction pipeline data for outpatient rehabilitation infrastructure. Forecast inputs incorporated lithium-ion battery energy density improvement curves and aerospace-grade carbon-fiber supply allocation forecasts.
Material uncertainties — CMS competitive bidding expansion timing, FDA software-as-medical-device guidance finalization, and aerospace composite material rationing severity — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding Medicare reimbursement rate stability and state Medicaid program consolidation trajectories. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Surgical Incision Closure Devices Market
Medical Devices
Global Pupillometer Market
Medical Devices
Global Female Sterilization Devices Market
Medical Devices
MRI Safe Neurostimulation Systems Market
Medical Devices
Europe Cardiac Rhythm Management Devices Market
Medical Devices
Digital Radiology Devices Market
Medical Devices
Hearing Loop Market
Medical Devices
Germany Aesthetic Devices Market
Medical Devices
Colon Hydrotherapy Units Market
Medical Devices
Laparoscopic Devices Market
Medical Devices
Tumour Ablation Devices Market
Medical Devices
Global Microelectronic Medical Implants Market
Medical Devices
Gamma Knife Market
Medical Devices
IV Poles Market
Medical Devices
Eccentric Tip Syringe Market
Medical Devices
Non-Invasive Ventilators Market