
 Patient Monitoring Accessories Market | 2026-2036
Patient Monitoring Accessories Market Size, Share, and Industry Trends Forecast 2026-2036
Patient Monitoring Accessories Market Intelligence
Hospital procurement departments are rotating toward ambulatory surgical centers as the fastest-growing buyer archetype for disposable monitoring electrodes and pulse oximetry sensors. Medtronic leverages its vertically integrated sensor manufacturing to sustain pricing power across cardiac monitoring applications. Philips Healthcare anchors its position through proprietary connector ecosystems that lock in recurring cable and electrode sales. Masimo differentiates via advanced signal processing algorithms that require matched accessories, creating captive demand for its sensor lines.
Patient monitoring accessories encompass the consumable and semi-durable peripherals—electrodes fabricated from Ag/AgCl conductive layers on flexible substrates, shielded multi-lead cables with defibrillation protection, and optical sensors employing dual-wavelength LEDs—that translate physiological signals into machine-readable data for continuous or intermittent surveillance. Electrodes and cables together constitute the largest product category by installed base, though wireless monitoring and wearable device segments are expanding fastest as health systems deploy untethered platforms for post-acute and home-based surveillance. Remote patient monitoring applications command premium pricing due to FDA-validated connectivity protocols and cloud-integration requirements, while vital signs monitoring in general wards remains a volume-driven, price-sensitive segment dominated by standard disposable configurations.
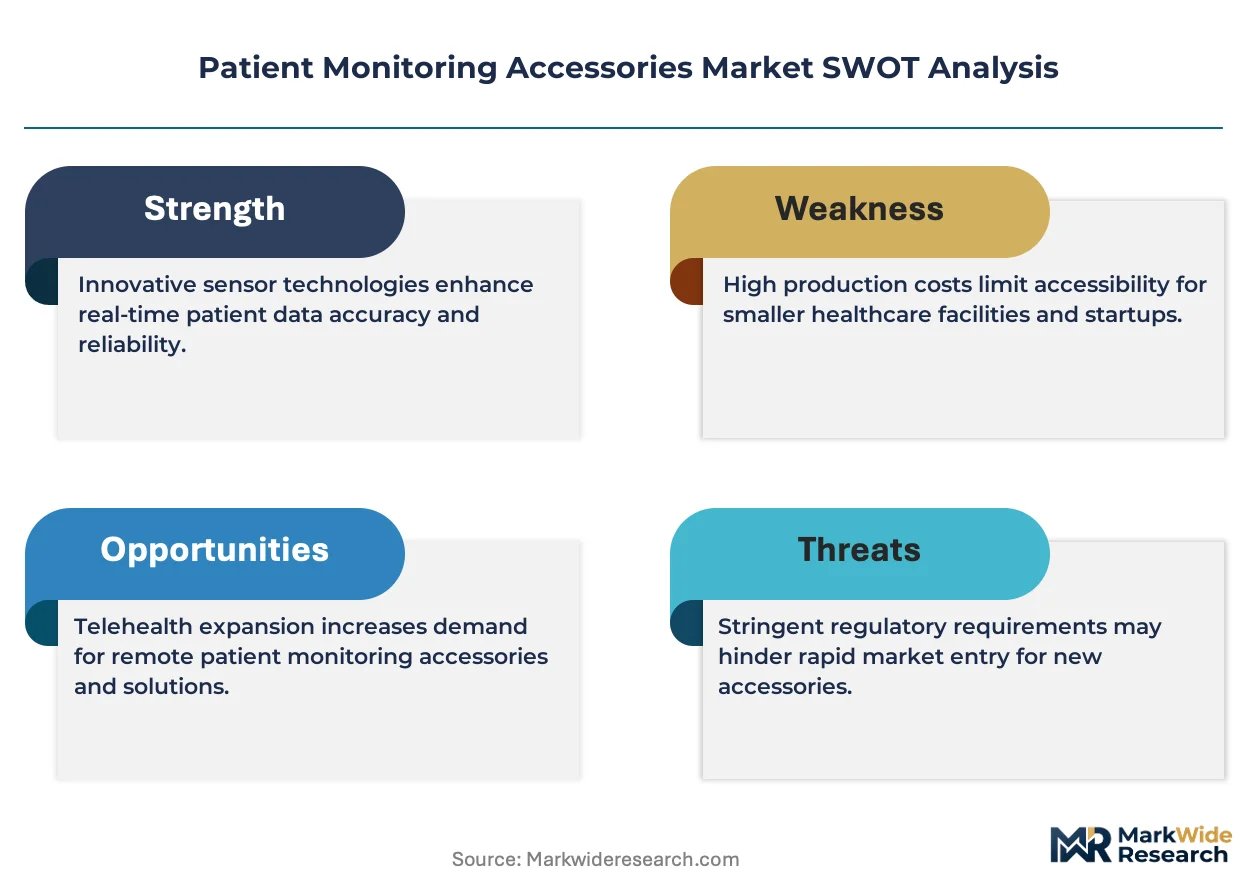
FDA 510(k) premarket notification and EU MDR technical documentation requirements enforce biocompatibility, electrical safety, and electromagnetic compatibility standards that elevate R&D barriers for new accessory entrants. ISO 10993 biological evaluation protocols and IEC 60601-1-2 electromagnetic immunity standards further constrain material selection and manufacturing processes. Stakeholders must monitor how CMS reimbursement shifts for remote therapeutic monitoring and EU IVDR companion diagnostic alignment will reshape accessory bundling strategies and compliance investment priorities.
Market Dynamics
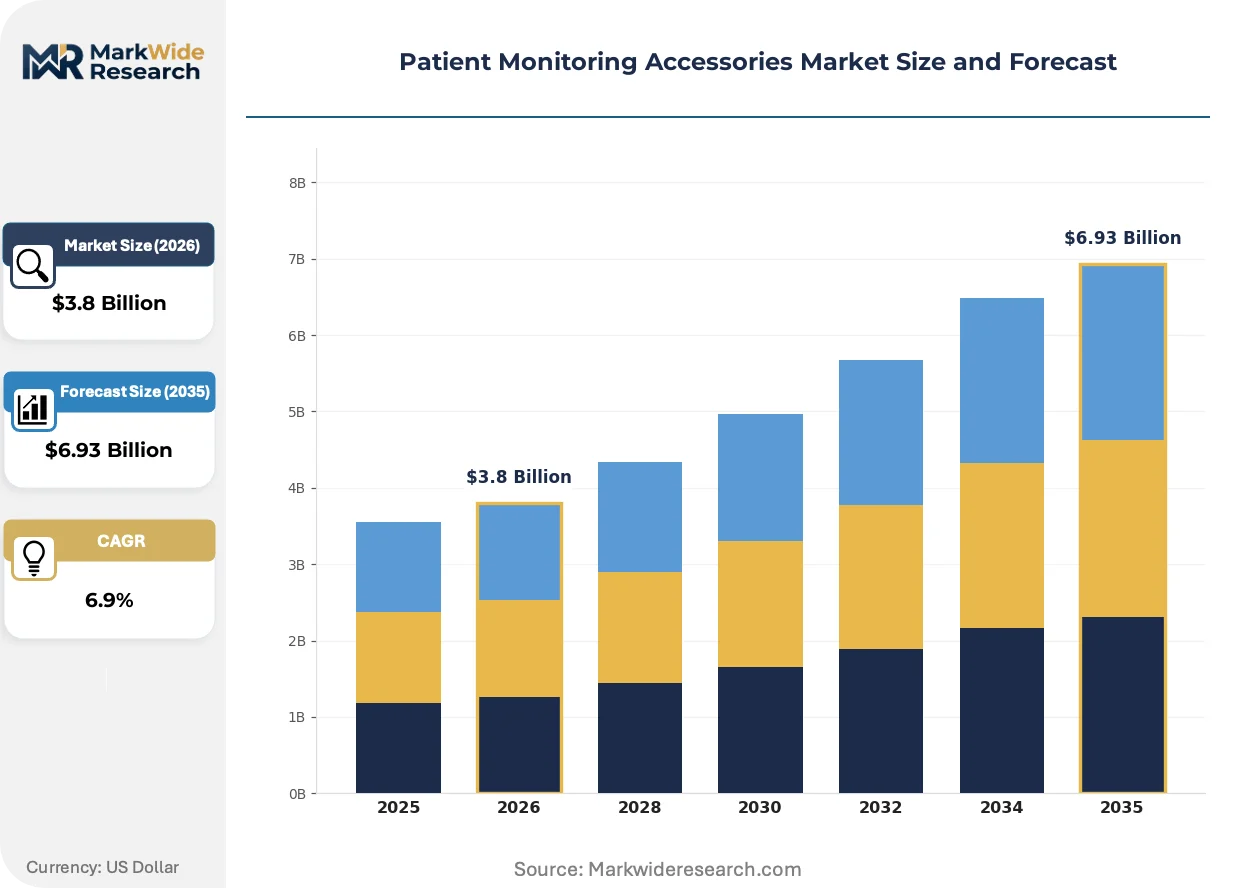
Hospital digitization programs and ambulatory surgical center expansion are compressing replacement cycles for monitoring peripherals while tightening biocompatibility requirements under FDA 510(k) and EU MDR pathways reshape material selection across the supply base.
Growth Catalysts
- EU MDR Conformity Requirements:Tightened biocompatibility standards for electrodes and lead wires are forcing manufacturers toward Ag/AgCl conductive layer innovations that command premium positioning in cardiac monitoring applications.
- Home Care Provider Procurement:Post-acute surveillance platforms are expanding procurement of reusable monitoring cables and wearable sensors as health systems deploy untethered platforms for remote patient monitoring.
- Optical Sensor Miniaturization:Dual-wavelength LED configurations in pulse oximetry sensors are enabling continuous monitoring in ambulatory settings previously restricted to intermittent spot-checks.
Market Restraints
- Silver Price Volatility:Ag/AgCl conductive layers expose electrode manufacturers to precious metal input cost swings that compress margin stability in disposable product lines.
- Connector Ecosystem Lock-in:Proprietary connector standards from dominant device manufacturers create captive demand patterns that constrain third-party accessory entrants from achieving scale.
- ISO 10993 Testing Burden:Extended biological evaluation timelines for new substrate materials delay product launches and elevate R&D overhead for electrode innovations.
Strategic Opportunities
- CMS Remote Therapeutic Monitoring Reimbursement:Expanded reimbursement codes for cloud-integrated monitoring platforms are creating premium pricing corridors for FDA-validated connectivity protocols in home-based surveillance.
- Wearable Form Factor Convergence:Integration of photoplethysmography with accelerometry in single-device configurations is opening ambulatory surgical center channels previously served by multi-component systems.
- German Hospital Digitization Programs:Federal funding for digital infrastructure is accelerating replacement cycles for monitoring peripherals in university hospitals and specialized cardiac centers.
Industry Challenges
- IEC 60601-1-2 Electromagnetic Immunity Certification:Evolving electromagnetic compatibility standards for wireless monitoring accessories require repeated testing cycles that extend time-to-market for Bluetooth-enabled sensor platforms.
- Legacy Device Integration Complexity:Health system investments in proprietary connector ecosystems create friction for accessories vendors attempting to serve mixed-vendor installed bases without adapter hardware.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Patient Monitoring Accessories Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.93 Billion |
| CAGR (2026 – 2036) | 6.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrodes, Cables, Sensors, Connectors Application: Cardiac Monitoring, Respiratory Care, Vital Signs Monitoring, Neurological Monitoring End User: Hospitals, Home Care, Long-term Care Facilities, Ambulatory Surgical Centers Technology: Wireless Monitoring, Wearable Devices, Remote Patient Monitoring, Telehealth Solutions |
| Companies Covered | Medtronic, GE Healthcare, Philips Healthcare, Nihon Kohden Corporation, Masimo, Honeywell International Inc., Welch Allyn, Mindray Medical International, Omron Healthcare, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Patient Monitoring Accessories Market Strategic Shifts & Innovations
Wireless monitoring architectures and cloud-native surveillance platforms are fragmenting traditional cable-and-electrode value chains while creating new competitive arenas around signal processing algorithms and data interoperability standards.
Photoplethysmography sensor technology is bifurcating into clinical-grade and consumer-grade performance tiers. Hospital procurement departments are adopting medical-grade optical sensors with FDA-validated accuracy specifications for general ward surveillance. This technology is bifurcating the pulse oximetry market into premium clinical segments and commoditized direct-to-consumer channels with divergent margin structures.
FDA 510(k) premarket notification pathways for wireless monitoring accessories are tightening cybersecurity documentation requirements. Manufacturers must now submit evidence of encrypted data transmission and cloud infrastructure validation. Remote patient monitoring applications face the steepest compliance burden as FDA scrutinizes end-to-end data integrity from sensor to electronic health record integration.
Ambulatory surgical centers are consolidating supplier relationships through multi-year electrode and cable bundling contracts that displace spot purchasing. German hospital procurement cooperatives are negotiating directly with sensor manufacturers to bypass traditional distribution markups. This consolidation is most visible in Bavaria and North Rhine-Westphalia where hospital digitization programs have centralized purchasing authority for monitoring peripherals.
Patient Monitoring Accessories Market Segmentation
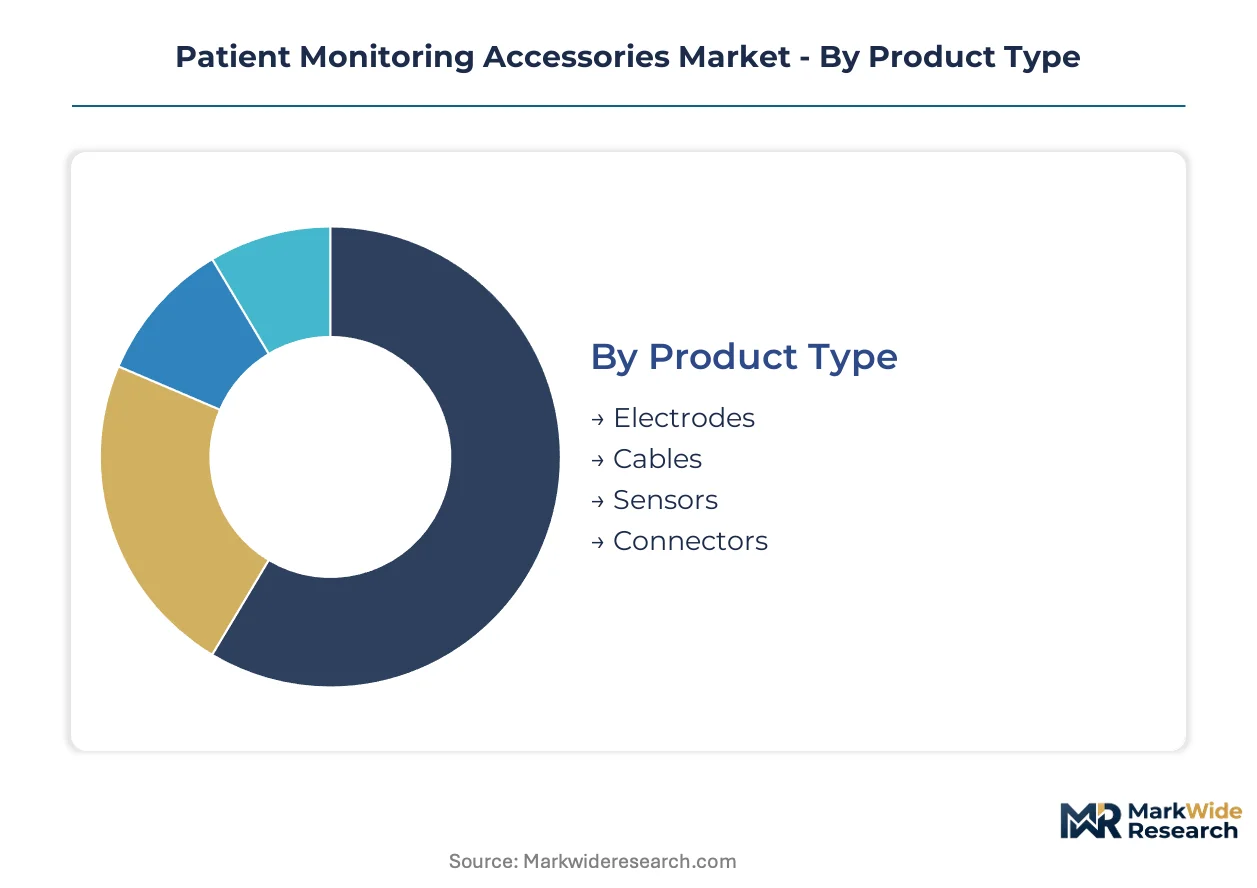
Segmentation in patient monitoring accessories reveals how procurement patterns fragment across clinical settings and connectivity architectures. Each dimension exposes different margin structures, replacement cycles, and regulatory compliance burdens that shape vendor strategy.
Product Type:
Electrodes and cables concentrate manufacturing in Germany and the United States for domestic hospital supply, while sensors and connectors flow through export-led supply chains serving Asian and Latin American markets.
- Electrodes:Ag/AgCl conductive layers on flexible polymer substrates translate ionic potentials into measurable voltages. German university hospitals and Bavarian cardiac centers drive demand for defibrillation-protected configurations under EU MDR biocompatibility mandates.
- Cables:Shielded multi-lead assemblies with molded strain reliefs protect signal integrity during patient transport. Ambulatory surgical centers in North Rhine-Westphalia are compressing replacement cycles through bundled procurement contracts.
- Sensors:Optical and pressure-transducing elements for non-invasive physiological measurement.
- Connectors:Proprietary and standardized interfaces linking peripherals to monitoring consoles.
Electrodes hold the largest share; momentum sits with sensors.
Application:
Cardiac and respiratory applications command premium pricing due to FDA-validated accuracy requirements, while vital signs and neurological segments compete on volume scale in general ward deployments.
- Cardiac Monitoring:Multi-lead ECG configurations with ST-segment analysis capability. German hospital digitization programs are accelerating electrode and cable replacement in specialized cardiac centers.
- Respiratory Care:Capnography modules and pulse oximetry sensors for ventilation management. Home care providers in the United States are expanding procurement of reusable cannulas and disposable sensors under CMS remote therapeutic monitoring reimbursement.
- Vital Signs Monitoring:Intermittent spot-check and continuous surveillance for general wards.
- Neurological Monitoring:EEG electrodes and specialized cables for seizure detection and depth-of-anesthesia assessment.
Cardiac monitoring anchors revenue concentration; vital signs monitoring is expanding most quickly across ambulatory channels.
End User:
Hospitals and ambulatory surgical centers dominate domestic procurement volume, while home care and long-term care facilities increasingly source through export-oriented distributors serving decentralized care models.
- Hospitals:Acute care settings with centralized biomedical engineering and consolidated supplier relationships. German procurement cooperatives in Bavaria and North Rhine-Westphalia negotiate directly with manufacturers to bypass distribution markups.
- Home Care:Post-acute and chronic disease management outside institutional settings. FDA 510(k) clearance for wireless monitoring accessories with encrypted data transmission is creating premium pricing corridors for cloud-integrated platforms.
- Long-term Care Facilities:Skilled nursing and assisted living environments with intermittent clinical oversight.
- Ambulatory Surgical Centers:Same-day procedure settings requiring rapid turnover of disposable peripherals.
Hospitals retain the largest share; home care demonstrates the steepest expansion trajectory.
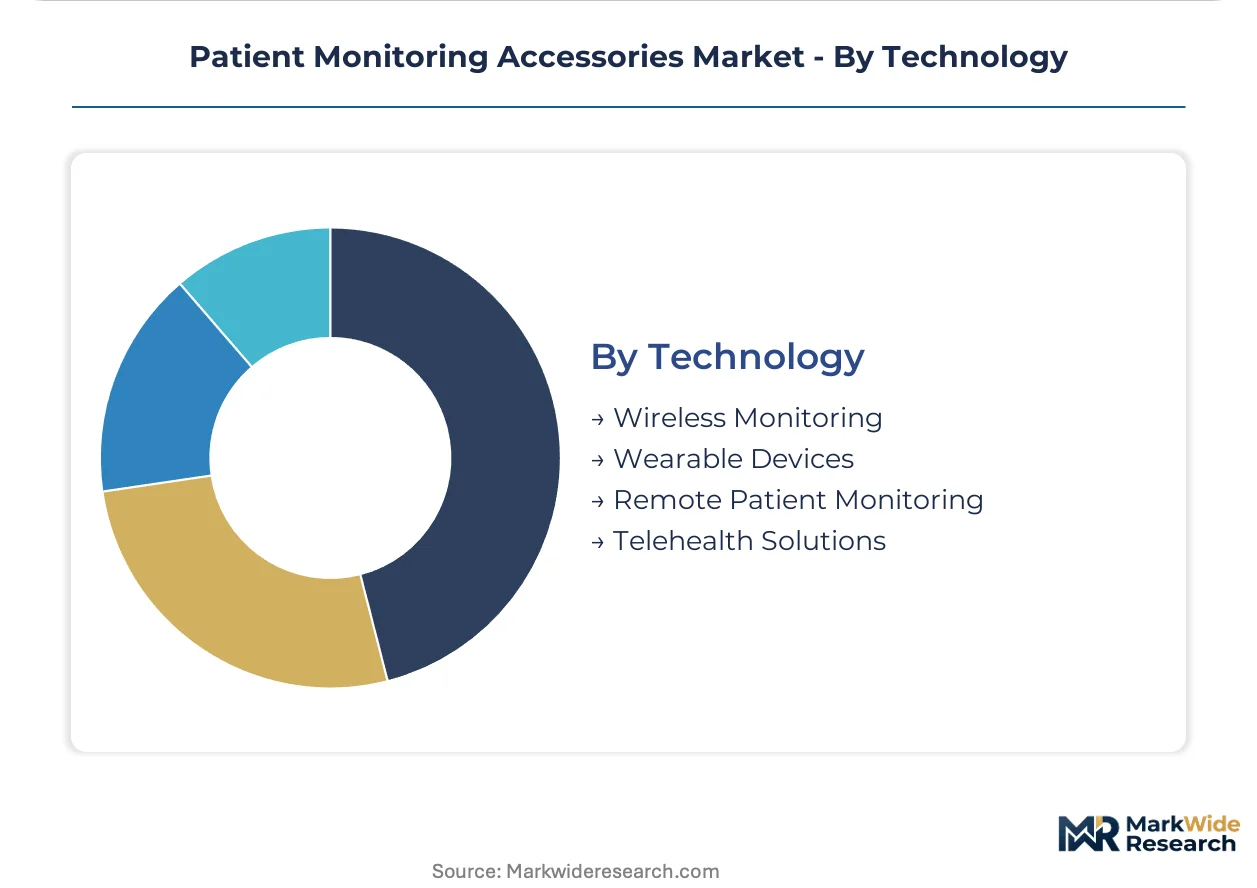
Technology:
Wearable and wireless platforms are displacing traditional tethered configurations, while remote patient monitoring and telehealth solutions require validated connectivity protocols that elevate R&D investment thresholds.
- Wireless Monitoring:Bluetooth-enabled sensors and gateway architectures for untethered surveillance. IEC 60601-1-2 electromagnetic immunity certification requirements are extending time-to-market for new platform launches.
- Wearable Devices:Photoplethysmography-integrated form factors combining accelerometry with optical sensing. Ambulatory surgical centers are adopting single-device configurations previously served by multi-component systems.
- Remote Patient Monitoring:Cloud-native platforms with FDA-validated end-to-end data integrity.
- Telehealth Solutions:Video-integrated peripherals enabling synchronous clinical consultation.
Wearable devices hold the largest emerging share; remote patient monitoring commands the highest pricing tier.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Accessory manufacturing clusters in Germany, the United States, China, Japan, and India supply distinct procurement channels with varying regulatory stringency and replacement cycle dynamics. Each concentration serves different end-user archetypes through specialized compliance pathways.
United States
FDA 510(k) clearance pathways for wireless monitoring accessories with encrypted data transmission are elevating R&D thresholds for cloud-integrated platforms. CMS expanded reimbursement codes for remote therapeutic monitoring are accelerating home care provider procurement of reusable cables and wearable sensors. Boston and Minneapolis medical device clusters anchor cardiac monitoring electrode production for domestic hospital supply.
Germany
Federal hospital digitization programs and ambulatory surgical center expansion in Bavaria and North Rhine-Westphalia are compressing replacement cycles for monitoring peripherals. EU MDR conformity requirements enforce biocompatibility standards for Ag/AgCl conductive layers that command premium positioning. Procurement cooperatives in university hospitals negotiate directly with sensor manufacturers to bypass distribution markups.
China
NMPA regulatory harmonization with IEC 60601-1-2 electromagnetic immunity standards is extending time-to-market for Bluetooth-enabled sensor platforms. Domestic health system investments in proprietary connector ecosystems create friction for third-party accessory entrants. Shanghai and Shenzhen manufacturing clusters concentrate optical sensor assembly for export-led supply chains serving Asian and Latin American markets.
Japan
PMDA validation requirements for photoplethysmography accuracy specifications are bifurcating the pulse oximetry market into clinical-grade and consumer-grade tiers. METI funding for post-acute surveillance platforms is expanding procurement of wearable devices with accelerometry integration. Tokyo and Osaka metropolitan areas anchor multi-lead cable production for domestic general ward deployment.
India
CDSCO streamlined approval pathways for vital signs monitoring accessories are attracting contract manufacturing investment from multinational device OEMs. PLI scheme incentives for medical electronics are accelerating domestic electrode substrate fabrication capacity. Bangalore and Hyderabad clusters specialize in disposable sensor assembly for price-sensitive volume segments.
Patient Monitoring Accessories Market Key Industry Players
Concentration sits with diversified medical technology conglomerates that leverage vertically integrated sensor manufacturing and proprietary connector ecosystems to sustain pricing power across cardiac monitoring applications. The vendor base stratifies into three archetypes: integrated device OEMs with captive accessory lines, specialized sensor manufacturers with FDA-validated connectivity protocols, and contract fabricators serving price-sensitive volume segments. Dominant competitive moves include strategic partnerships for cloud-native platform integration and portfolio diversification into wearable form factors.
Among integrated device OEMs, Medtronic, Philips Healthcare, and Masimo occupy distinct positioning vectors. Medtronic exemplifies the vertically integrated archetype through in-house production of Ag/AgCl conductive layers. Philips Healthcare anchors the proprietary ecosystem tier through connector standards that lock in recurring cable and electrode sales. Masimo represents the algorithm-driven differentiation model where advanced signal processing creates captive demand for matched sensor lines.
| Leading Market Players |
|---|
| Medtronic |
| GE Healthcare |
| Philips Healthcare |
| Nihon Kohden Corporation |
| Masimo |
| Honeywell International Inc. |
| Welch Allyn |
| Mindray Medical International |
| Omron Healthcare |
| Others |
Cost & Logistics Intelligence
Ag/AgCl conductive layer substitution for carbon-based electrodes simultaneously redraws manufacturing geography toward German and US specialty chemical clusters while compressing margin structures in commoditized disposable lines. This material transition elevates biocompatibility-certified production toward premium cardiac monitoring tiers while pushing price-sensitive volume manufacturing toward Asian contract fabricators.
Pricing Analysis
FDA 510(k) and EU MDR dictate the pricing tier structure across patient monitoring accessories, separating FDA-validated wireless platforms with encrypted transmission from standard disposable electrodes. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade, volume scale, and after-sales bundling intensity. Cost compression in economy electrodes is intensifying because silver price volatility exposes manufacturers to input cost swings. Home care providers demonstrate highest price sensitivity due to CMS reimbursement constraints, while German university hospitals accept premium positioning for defibrillation-protected configurations.
Supply Chain Analysis
Strategic stockpiling of Ag/AgCl substrates and shielded cable assemblies dominates inventory strategy among cardiac monitoring specialists facing ISO 10993 testing delays. Manufacturing concentrates in Germany, the United States, and China, with domestic production serving hospital digitization programs and export-led clusters supplying Asian and Latin American markets. Raw material dependencies center on silver chloride precursors, medical-grade polymer substrates, and dual-wavelength LED components. Single-source vulnerability in proprietary connector ecosystems creates structural risk for third-party accessory entrants. Distribution runs through hospital procurement cooperatives in Bavaria and North Rhine-Westphalia, GPO contracts in the United States, and export-oriented distributors serving decentralized home care channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized signal processing capabilities and validated connectivity protocols represent scarce assets that concentrate competitive advantage among algorithm-driven manufacturers. The widening capability gap between clinical-grade and consumer-grade performance tiers creates asymmetric returns for holders of FDA-cleared wireless architectures.
For Market Incumbents: Secure backward integration into Ag/AgCl conductive layer production to buffer silver price volatility and sustain margin stability in disposable electrode lines. Lock in multi-year bundling contracts with ambulatory surgical centers to preempt spot purchasing displacement. Defend against algorithm-driven entrants by accelerating proprietary connector ecosystem penetration in German hospital digitization programs. For New Entrants and Emerging Players: Differentiate on FDA-validated cybersecurity documentation for wireless monitoring accessories targeting CMS remote therapeutic monitoring reimbursement corridors. White-space opportunity concentrates in wearable form factor convergence for ambulatory surgical centers previously served by multi-component systems. Penetrate through direct negotiation with Bavarian and North Rhine-Westphalia procurement cooperatives bypassing traditional distribution markups. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed sensor manufacturers holding ISO 10993-validated substrate portfolios but lacking cloud-native platform integration. Long-term viability hinges on acquiring algorithm capabilities that create captive demand for matched accessory lines. Watch FDA 510(k) clearance velocity for Bluetooth-enabled platforms as inflection indicator for wireless monitoring segment consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission for Wireless Accessories | Clears premium pricing corridors for encrypted data transmission in home-based surveillance. |
| EU MDR Conformity Pathway Acceleration | Validates Ag/AgCl biocompatibility for defibrillation-protected cardiac monitoring configurations. |
| Hospital System Partnership for Bundled Procurement | Locks recurring cable and electrode sales through multi-year ambulatory surgical center contracts. |
| Software Companion Development for Cloud Integration | Creates captive demand via validated end-to-end data integrity from sensor to electronic health record. |
| Reimbursement Strategy Alignment with CMS Codes | Captures expanded remote therapeutic monitoring coverage for wearable sensor platforms. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted across hospital procurement committees, biomedical engineering directors, GPO contracts managers, and home care provider supply chain leads. Secondary validation drew from FDA 510(k) filings, EU MDR technical documentation databases, CMS Medicare reimbursement schedules, and hospital procurement cooperative records. Bottom-up demand modeling triangulated against top-down market sizing across product type, application, end user, and technology segmentation dimensions.
Across the analysis window, volume and value outputs reflect analytical framework segmentation by connectivity architecture, clinical setting intensity, and regional regulatory cluster. CAGRs were derived from replacement cycle compression rates in German digitization programs and ambulatory surgical center expansion trajectories. Industry-specific inputs included silver price volatility indices, ISO 10993 biological evaluation timeline distributions, and proprietary connector ecosystem penetration rates.
The analysis sits within stated boundaries; outcomes outside sustained CMS reimbursement expansion or accelerated EU MDR enforcement timelines would require recalibration. Forecasts reflect documented assumptions regarding silver input cost stability and electromagnetic immunity certification velocity. Revision becomes warranted when FDA cybersecurity documentation requirements cross thresholds that extend wireless platform time-to-market beyond competitive windows.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Patient Monitoring
Global Patient Temperature Monitoring Market
Patient Monitoring
Telemonitoring Systems Market
Patient Monitoring
Wireless Healthcare Market
Patient Monitoring
Europe Remote Patient Monitoring Systems Market
Patient Monitoring
South America Cardiac Arrhythmia Monitoring Devices Market
Patient Monitoring
Global Heart Rate Monitor Market
Patient Monitoring
Remote Patient Monitoring System Market
Patient Monitoring
Holter Monitoring Systems Market
Patient Monitoring
Global Arrhythmia Monitoring Devices Market
Patient Monitoring
Asia-Pacific Hemodynamic Monitoring Market
Patient Monitoring
Global Cardiac Monitoring and Cardiac Rhythm Management Device Market
Patient Monitoring
Patient Scales Market
Patient Monitoring
Global Consumer Healthcare Sensor Market
Patient Monitoring
South Korea Patient Monitoring Market
Patient Monitoring
Abetalipoproteinemia Monitoring Systems Market
Patient Monitoring
Asia-Pacific Fetal and Neonatal Monitoring Market