
 Interventional Oncology Devices Market | 2026-2036
Interventional Oncology Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Interventional Oncology Devices Market Outlook
A shortage of interventional radiologists trained in tumor ablation is unwinding capacity expansion at major hospital systems. Boston Scientific Corporation leverages its integrated electrophysiology and oncology portfolio to cross-sell ablation platforms. Medtronic plc anchors its position through deep catheter manufacturing scale and cath lab installed base relationships. AngioDynamics specializes in microwave and radiofrequency systems for percutaneous liver and kidney procedures.
Interventional oncology devices comprise minimally invasive instruments designed to diagnose, treat, or palliate solid tumors through percutaneous or endovascular access, typically operating at frequencies between 460-480 kHz for radiofrequency ablation and temperatures below -40°C for cryoablation. These systems serve the primary commercial purpose of reducing surgical morbidity while enabling same-day discharge for localized tumor management. Embolization devices command the largest revenue pool due to recurring consumable use in transarterial chemoembolization, while irreversible electroporation devices represent the fastest-expanding segment driven by non-thermal tissue preservation advantages near critical structures. Image-guided therapy platforms concentrate margin pools in software-hardware bundles, whereas fluoroscopy-dependent procedures retain volume dominance in cost-sensitive settings.
The FDA regulates these devices under Class II and Class III premarket pathways, with breakthrough designations compressing review timelines for novel ablation modalities. The EU MDR and CE marking requirements are reshaping clinical evidence standards for electromagnetic energy delivery systems, particularly for irreversible electroporation claims. Stakeholders must monitor reimbursement parity between percutaneous ablation and surgical resection as value-based oncology contracts restructure site-of-care economics.
Market Dynamics
Site-of-care migration toward ambulatory surgical centers is compressing capital equipment procurement cycles while elevating disposable consumable intensity across tumor ablation workflows.
Growth Catalysts
- FDA Breakthrough Device Pathway:Expedited review timelines for novel ablation modalities accelerate commercialization of irreversible electroporation and next-generation microwave systems.
- Ambulatory Surgical Center Expansion:CMS reimbursement parity for percutaneous tumor ablation in outpatient settings drives procedural volume displacement from inpatient surgical suites.
- Radiofrequency Ablation Frequency Optimization:Operating ranges between 460-480 kHz enable precise thermal lesion control with reduced collateral tissue damage in hepatic and renal applications.
Market Restraints
- Interventional Radiologist Shortage:Fellowship-trained ablation specialists remain concentrated at academic medical centers, constraining capacity expansion at community hospital systems.
- EU MDR Clinical Evidence Burden:Reshaped conformity assessment requirements for electromagnetic energy devices extend regulatory timelines and elevate documentation costs for CE marking.
- Cryoablation Gas Supply Concentration:Dependence on argon and helium sourcing creates input cost volatility and delivery reliability risks for sub-minus-40°C tissue destruction systems.
Strategic Opportunities
- Pediatric Solid Tumor Applications:Organ-sparing non-thermal modalities address unmet need in young patients with lesions adjacent to critical neurovascular structures.
- Integrated Software-Hardware Bundles:Real-time imaging fusion platforms capture margin expansion through recurring software licensing attached to capital equipment placements.
- India CDSCO Streamlined Approval:Emerging regulatory harmonization with IMDRF standards reduces time-to-market for radiofrequency and microwave ablation systems in South Asia.
Industry Challenges
- Cross-Modality Training Requirements:Operators must achieve proficiency across ultrasound, CT, and MRI guidance platforms, extending credentialing timelines and limiting workforce elasticity.
- Reimbursement Coding Fragmentation:Inconsistent Category III CPT code coverage for emerging technologies creates prior authorization friction and payment uncertainty for novel procedures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Interventional Oncology Devices Market |
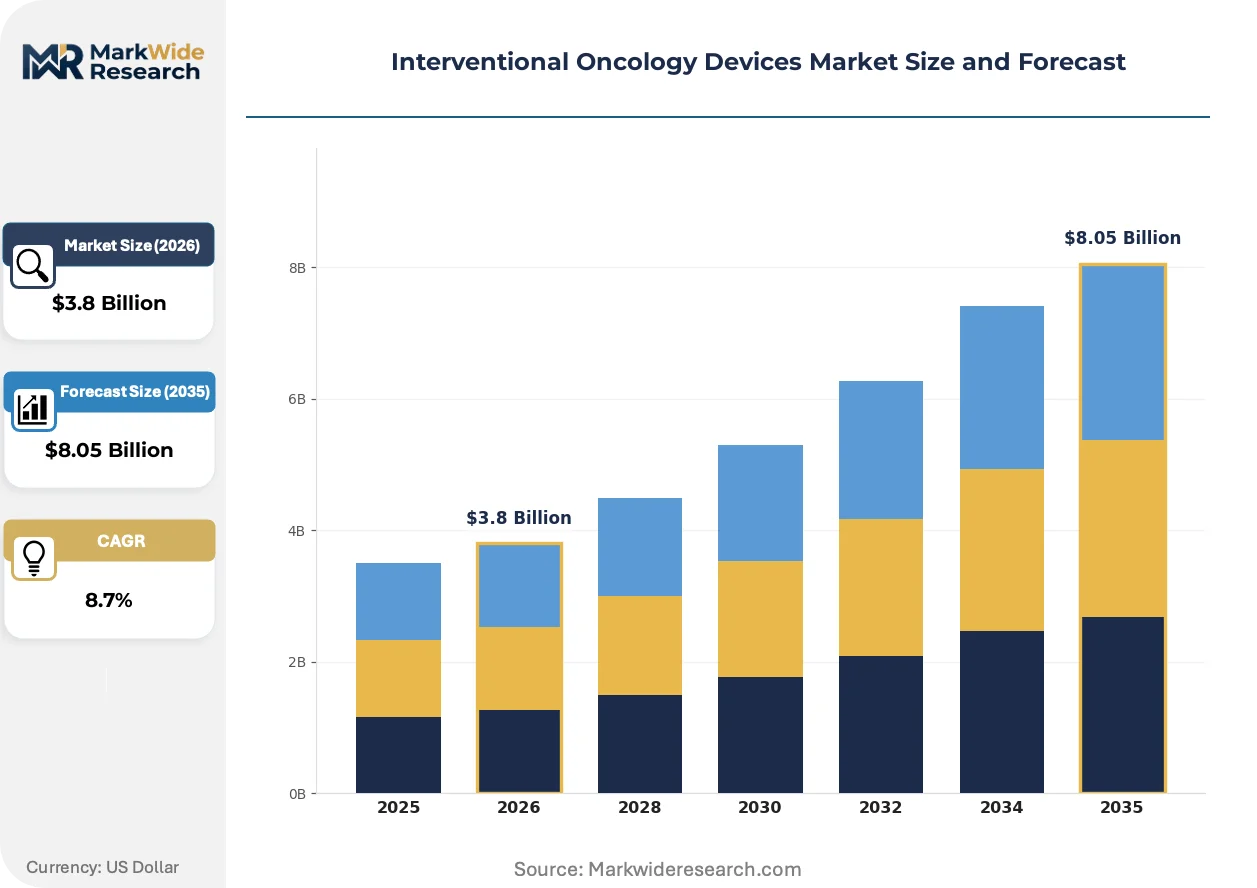
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Embolization Devices, Radiofrequency Ablation Devices, Cryoablation Devices, Irreversible Electroporation Devices Application: Liver Cancer, Kidney Cancer, Lung Cancer, Bone Cancer End User: Hospitals, Ambulatory Surgical Centers, Cancer Treatment Centers, Research Institutions Technology: Image-Guided Therapy, Fluoroscopy, CT-guided Intervention, Ultrasound-guided Procedures |
| Companies Covered | Boston Scientific Corporation, Medtronic plc, AngioDynamics, Merit Medical Systems, Cook Medical, Siemens Healthineers, Terumo Corporation, Johnson & Johnson, Stryker Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Interventional Oncology Devices Market Strategic Shifts
Device architectures are pivoting from standalone energy delivery systems toward integrated therapy platforms that bundle navigation, ablation monitoring, and outcome documentation in single-workflow solutions.
Irreversible electroporation is bifurcating the thermal ablation landscape by enabling treatment of lesions adjacent to bile ducts, ureters, and neural structures without heat-sink limitations. Academic medical centers in the United States and Germany are prioritizing IRE platform acquisition for pancreatic and prostate applications. This modality is bifurcating competitive positioning between thermal and non-thermal vendors, forcing radiofrequency and microwave specialists to defend installed base relationships through software upgrades rather than hardware displacement.
The EU MDR's enhanced clinical evidence requirements for active implantable and energy-emitting devices are extending premarket assessment timelines for novel ablation generators and applicators. Manufacturers must now generate prospective clinical data for CE marking renewals, elevating trial costs and favoring larger portfolios with amortized regulatory infrastructure. Electromagnetic ablation systems with expanded indications near vascular structures face the most stringent scrutiny under notified body interpretation of Annex XVI.
Integrated cancer networks are consolidating purchasing decisions around single-vendor image-guided therapy platforms, displacing best-of-breed device procurement. Hospital systems in the United States are negotiating enterprise-wide ablation contracts that bundle capital equipment, disposable applicators, and multi-year service agreements. This concentration is most visible at NCI-designated comprehensive cancer centers, where standardization reduces training overhead and supply chain complexity across distributed care sites.
Interventional Oncology Devices Market Segmentation
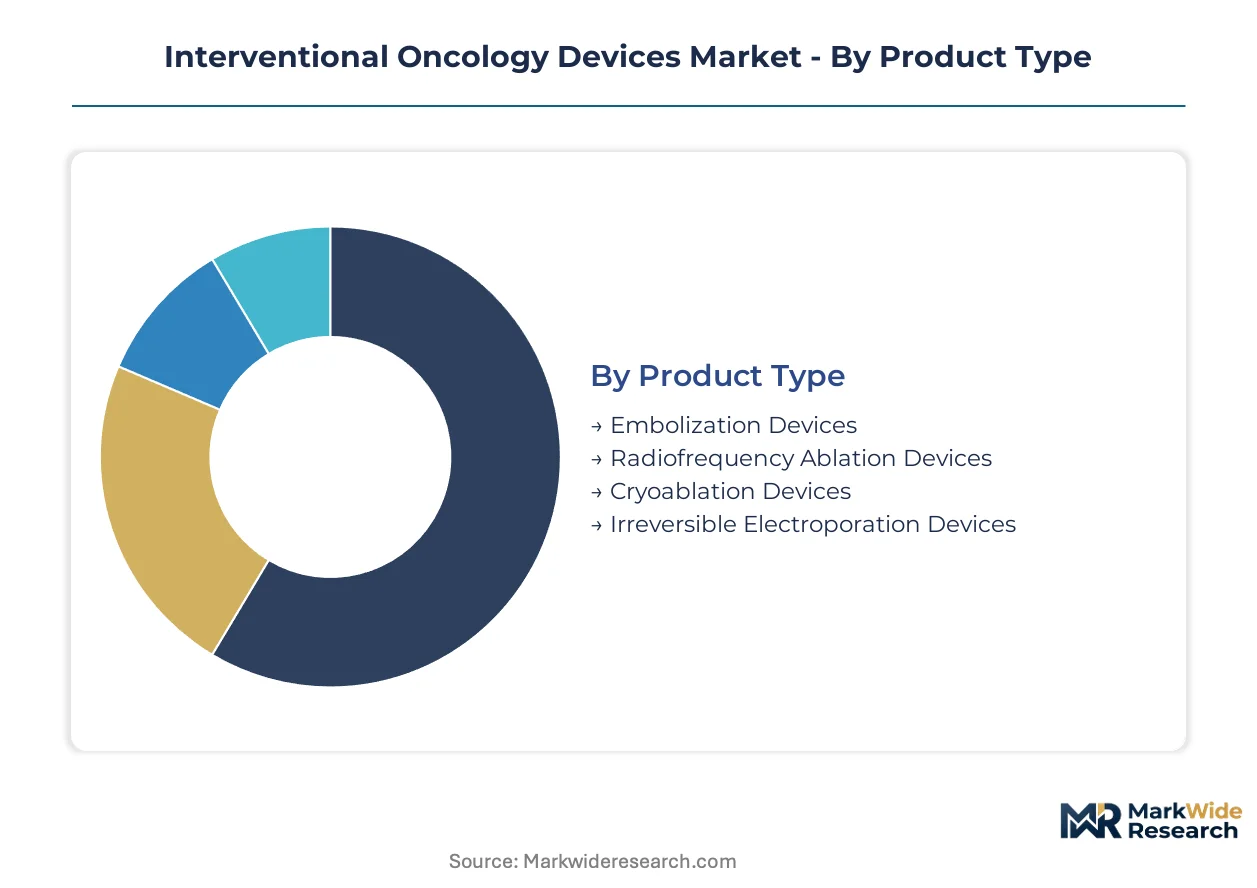
Segmentation reveals how margin pools concentrate in consumable-heavy embolization workflows versus capital-intensive imaging platforms. Understanding these divisions exposes where procurement standardization is displacing best-of-breed purchasing across integrated delivery networks.
Product Type:
Margin pools concentrate in recurring consumable use rather than one-time capital equipment sales, reshaping vendor economics toward disposable intensity.
- Embolization Devices:Transarterial chemoembolization and radioembolization systems utilize microspheres, coils, and liquid embolics in recurrent procedural workflows. Demand clusters at NCI-designated comprehensive cancer centers in the United States where transarterial therapies dominate hepatocellular carcinoma protocols, with CMS reimbursement parity for outpatient settings accelerating volume displacement from inpatient surgical suites.
- Radiofrequency Ablation Devices:Generators operating at 460-480 kHz deliver thermal energy through percutaneous applicators for hepatic and renal lesions. Adoption concentrates in community hospital systems seeking same-day discharge capabilities, though interventional radiologist shortages constrain capacity expansion outside academic medical centers.
- Cryoablation Devices:Argon-helium systems achieve sub-minus-40°C tissue destruction for renal and prostate applications.
- Irreversible Electroporation Devices:Non-thermal pulsed electric field systems enable treatment adjacent to critical structures without heat-sink limitations.
Embolization devices hold installed capacity. Irreversible electroporation devices are rotating up the share rankings.
Application:
Volume distribution tracks the prevalence of surgical unresectability and the availability of image-guided intervention expertise by tumor site.
- Liver Cancer:Transarterial chemoembolization and radiofrequency ablation serve as bridging therapies to transplant and definitive treatment for early-stage hepatocellular carcinoma. Demand concentrates in Germany and the United States where multidisciplinary tumor boards standardize ablation-first protocols for lesions under three centimeters, with EU MDR clinical evidence requirements extending regulatory timelines for expanded indication claims.
- Kidney Cancer:Cryoablation and radiofrequency ablation preserve renal function in patients with compromised contralateral kidneys or multiple comorbidities. Centers in Japan and the United States prioritize nephron-sparing approaches for T1a lesions, though reimbursement coding fragmentation for percutaneous versus laparoscopic ablation creates prior authorization friction.
- Lung Cancer:Microwave ablation addresses nonsurgical candidates with early-stage non-small cell disease or oligometastatic disease.
- Bone Cancer:Palliative ablation for painful metastases utilizes radiofrequency and cryoablation for localized tumor control.
Liver cancer applications anchor procedural volume. Kidney cancer is gaining share fastest as nephron-sparing protocols expand.
End User:
Site-of-care economics are bifurcating procurement patterns between capital-intensive hospital platforms and disposable-focused ambulatory workflows.
- Hospitals:Academic medical centers and community hospitals deploy integrated image-guided therapy platforms combining CT, MRI, and ultrasound fusion capabilities. These sites concentrate in the United States and Germany where fellowship-trained interventional radiologists maintain ablation service lines, though workforce shortages limit expansion at secondary facilities.
- Ambulatory Surgical Centers:CMS reimbursement parity for percutaneous tumor ablation enables same-day discharge workflows with reduced overhead. United States-based ASCs are displacing inpatient volumes for renal and hepatic lesions, elevating disposable consumable intensity while compressing capital equipment procurement cycles.
- Cancer Treatment Centers:Specialized oncology facilities prioritize multi-modality ablation platforms for complex lesion locations.
- Research Institutions:Academic research centers generate prospective clinical data for novel ablation modalities and expanded indications.
Hospitals retain the deepest installed base. Ambulatory surgical centers are climbing the fastest as site-of-care migration accelerates.
Technology:
Imaging modality selection determines workflow efficiency, lesion conspicuity, and the capital burden of platform deployment.
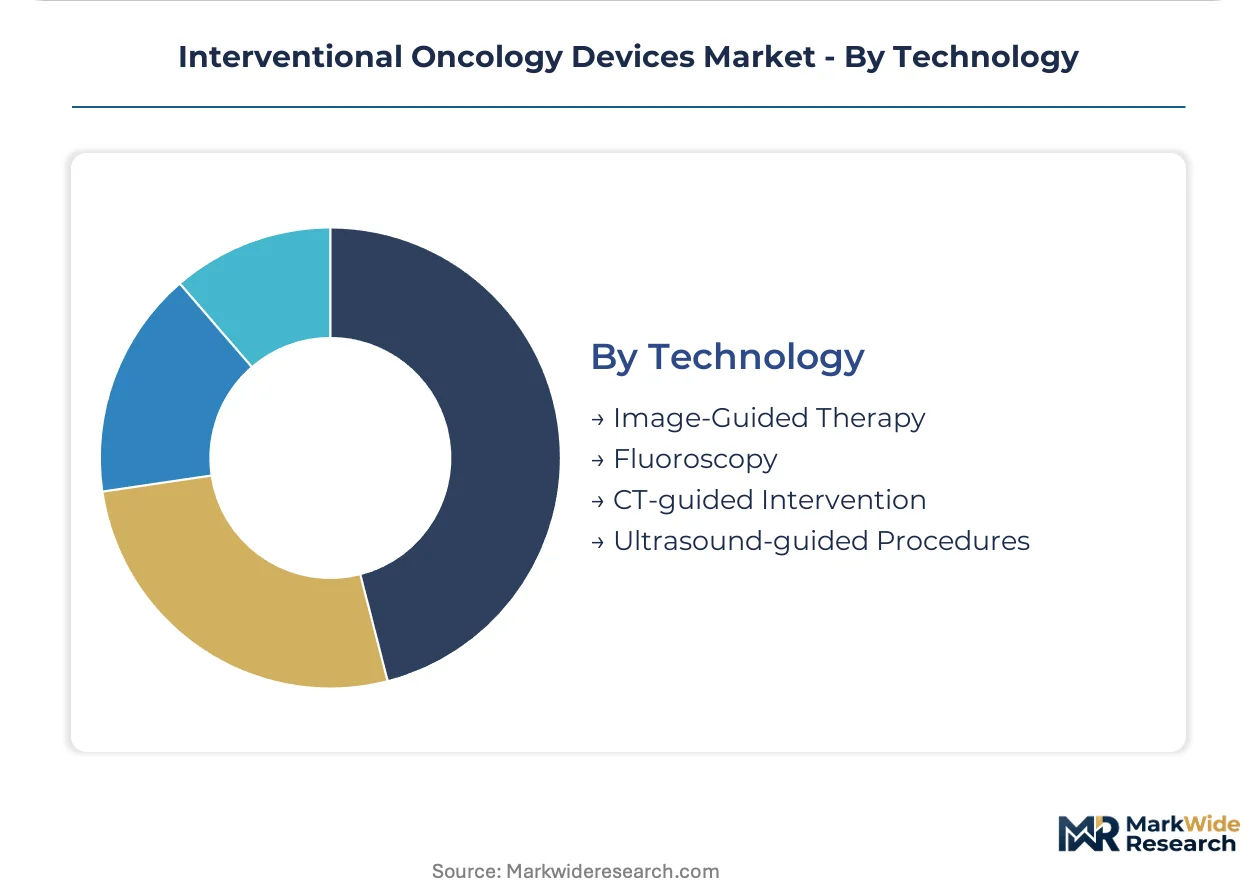
- Image-Guided Therapy:Integrated software-hardware bundles fuse real-time imaging with navigation and ablation monitoring in single-workflow solutions. These platforms command margin expansion through recurring software licensing at NCI-designated centers in the United States, where standardization across distributed sites reduces training overhead.
- Fluoroscopy:X-ray guidance retains volume dominance in cost-sensitive settings and transarterial procedures. Community hospitals in India and Brazil depend on fluoroscopy-dependent workflows for embolization, though radiation exposure concerns and image quality limitations constrain adoption for percutaneous thermal ablation.
- CT-guided Intervention:Computed tomography provides precise lesion targeting and immediate post-procedural assessment for pulmonary and hepatic applications.
- Ultrasound-guided Procedures:Real-time sonography enables continuous visualization without ionizing radiation for superficial and abdominal lesions.
Image-guided therapy platforms capture premium positioning. CT-guided intervention is expanding most quickly as lung ablation volumes rise.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply between integrated cancer networks in the United States and fragmented hospital systems in emerging economies. The United States concentrates demand in NCI-designated centers pursuing same-day discharge protocols. Germany and Japan prioritize organ-sparing modalities near critical structures. India and Brazil depend on fluoroscopy-guided workflows constrained by reimbursement limitations.
United States
Integrated cancer networks consolidate purchasing around single-vendor image-guided therapy platforms. The FDA breakthrough device designation pathway expedites commercialization timelines for novel ablation modalities. NCI-designated comprehensive cancer centers in Texas and California standardize protocols across distributed sites, reducing training overhead and supply chain complexity.
Germany
Multidisciplinary tumor boards standardize ablation-first protocols for early-stage hepatocellular carcinoma lesions under three centimeters. The EU MDR reshapes clinical evidence requirements for electromagnetic energy delivery systems, extending regulatory timelines for expanded indication claims. Academic medical centers in Bavaria and North Rhine-Westphalia prioritize irreversible electroporation platform acquisition for pancreatic applications.
Japan
Nephron-sparing approaches for T1a renal lesions drive cryoablation and radiofrequency system adoption. METI guidelines influence reimbursement parity negotiations between percutaneous ablation and surgical resection. Centers in Tokyo and Osaka concentrate fellowship-trained interventional radiologists, constraining capacity expansion at secondary facilities in rural prefectures.
India
Community hospitals depend on fluoroscopy-dependent workflows for transarterial chemoembolization procedures. CDSCO streamlined approval pathways harmonizing with IMDRF standards reduce time-to-market for radiofrequency and microwave ablation systems. Metropolitan clusters in Maharashtra and Karnataka attract capital equipment procurement despite workforce training gaps.
Brazil
Cost-sensitive settings retain volume dominance in fluoroscopy-guided embolization workflows. ANVISA regulatory requirements create documentation burdens for electromagnetic energy device manufacturers. São Paulo and Rio de Janeiro anchor demand concentration, though radiation exposure concerns constrain percutaneous thermal ablation adoption outside academic centers.
Interventional Oncology Devices Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier in interventional oncology devices. Diversified medical technology conglomerates leverage catheter manufacturing scale and cath lab installed base relationships to defend market position. Specialists in microwave and radiofrequency systems occupy differentiated niches in percutaneous liver and kidney procedures. Cross-portfolio bundling and enterprise-wide contracting represent the dominant competitive moves reshaping procurement patterns.
Among diversified conglomerates, Boston Scientific Corporation and Medtronic plc exemplify the integrated leader archetype through electrophysiology and oncology portfolio breadth. AngioDynamics occupies a specialist position within the non-thermal and thermal ablation tier. These three entities represent the competitive anchors around which procurement standardization and site-of-care migration dynamics revolve, with their respective positions reflecting divergent strategic bets on disposable intensity versus platform integration.
| Leading Market Players |
|---|
| Boston Scientific Corporation |
| Medtronic plc |
| AngioDynamics |
| Merit Medical Systems |
| Cook Medical |
| Siemens Healthineers |
| Terumo Corporation |
| Johnson & Johnson |
| Stryker Corporation |
| Others |
Value Chain & Pricing Dynamics
Helium-to-nitrogen substitution in cryoablation systems is redistributing manufacturing footprints from Gulf Coast gas processing hubs toward industrial gas production centers in China and Russia, simultaneously compressing per-procedure supply costs while introducing new tariff-exposure vulnerabilities for sub-minus-40°C tissue destruction platforms.
Pricing Analysis
Long-term enterprise service agreements dominate procurement at NCI-designated comprehensive cancer centers, locking in multi-year pricing for capital equipment bundles with attached disposable minimums. Three-tier pricing structure across premium, standard, and economy levels reflects software licensing sophistication, FDA breakthrough designation status, and field service density. Cost compression in economy-tier radiofrequency generators is intensifying because of Chinese manufacturer entry into CDSCO-streamlined approval pathways. Community hospital systems exhibit highest price sensitivity due to capital budget constraints, while integrated cancer networks prioritize total cost-of-ownership over per-unit pricing.
Supply Chain Analysis
Germany and the United States anchor precision generator manufacturing for radiofrequency and microwave ablation platforms, while China concentrates disposable applicator and catheter component production. Raw material flows draw from argon and helium extraction in Qatar and the United States, high-purity copper for electromagnetic coils in Chile, and medical-grade polymers for catheter shafts in South Korea. Single-source vulnerability concentrates in superconducting magnet wire for MRI-compatible ablation systems. Distribution runs through GPO contracts at integrated delivery networks and direct-to-hospital sales for specialized IRE platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity exists across ambulatory surgical center workflows as site-of-care migration outpaces vendor service infrastructure deployment, creating niches for disposable-focused entrants.
For Market Incumbents: Consolidate installed base relationships through software upgrade pathways that extend hardware lifecycle rather than displacement. Deepen vertical integration into argon-helium gas logistics to mitigate supply volatility for cryoablation portfolios. Cross-portfolio bundling with electrophysiology platforms at Boston Scientific and catheter manufacturing scale at Medtronic defend against microwave specialist erosion.
For New Entrants and Emerging Players: Post-procedure monitoring software and remote ablation outcome documentation represent service-layer gaps where incumbents under-serve ASC workflows. Target United States-based ambulatory surgical centers in Texas and Florida for renal and hepatic lesion volumes with disposable-only business models. Pursue CDSCO harmonized approval pathways for radiofrequency systems in Maharashtra and Karnataka metropolitan clusters.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed microwave ablation specialists lacking IRE platform breadth. Five-to-ten year viability hinges on reimbursement parity maintenance between percutaneous and surgical modalities. Watch Category III CPT code conversion timelines as inflection indicator for irreversible electroporation revenue recognition.
| Strategic Initiative | Industry Significance |
|---|---|
| FDA Breakthrough Device Pathway | Expedited review compresses commercialization timelines for novel ablation modalities at academic centers. |
| CE Marking Pathway | EU MDR clinical evidence requirements extend premarket timelines for electromagnetic energy systems in Germany. |
| Hospital System Partnership | Enterprise-wide contracts at NCI-designated centers standardize procurement across distributed care sites. |
| Software Companion Development | Real-time imaging fusion platforms capture recurring licensing revenue attached to capital placements. |
| Reimbursement Strategy | CMS parity for outpatient ablation drives volume displacement from inpatient surgical suites to ASCs. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across interventional radiologists at academic medical centers, biomedical engineers managing cath lab capital procurement, GPO contracts managers at integrated delivery networks, and regulatory affairs leads navigating FDA breakthrough and EU MDR pathways. Secondary validation drew from FDA 510(k) and PMA filings, CMS Medicare reimbursement databases, hospital procurement records at NCI-designated centers, and EU notified body guidance documents for electromagnetic energy devices. Bottom-up procedure volume estimates triangulated with top-down market sizing across product type, application, end user, and technology segments.
Across the analysis window, projections incorporated installed base replacement cycles, site-of-care migration velocity toward ambulatory settings, and reimbursement coding evolution for emerging modalities. Segmentation modeling spanned product type hierarchy, tumor site application, technology platform, and end-user facility tier. CAGRs derived from procedure volume elasticity to reimbursement parity, interventional radiologist workforce expansion constraints, and capital equipment procurement cycle compression at ASCs. Forecast inputs included helium supply contract pricing volatility and Category III CPT code conversion probability for irreversible electroporation.
Underlying assumptions cover reimbursement parity maintenance, interventional radiologist fellowship pipeline stability, and EU MDR notified body capacity, with deviation risk concentrated in cryoablation gas supply disruptions and ASC regulatory scope expansion. Forecasts reflect these conditions with explicit sensitivity to workforce shortage severity and MDR timeline extensions. Recalibration cycles align with material shifts in CMS site-of-care policy and breakthrough designation grant velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
MRI Safe Defibrillator Market
Medical Devices
Dental Implants and Prosthetics Contract Manufacturing Market
Medical Devices
Skull Deformity Implants Market
Medical Devices
Organ Care Market
Medical Devices
Specimen Retrieval Market
Medical Devices
Asia-Pacific Micro Invasive Glaucoma Surgery (MIGS) Devices Market
Medical Devices
Global Smart Biopsy Devices Market
Medical Devices
Internal Neuromodulation Devices Market
Medical Devices
GCC and UAE Diabetes Devices Market
Medical Devices
Asia-Pacific Vagus Nerve Stimulation Market
Medical Devices
Global Laparoscopic and Open Hernia Mesh Repair Surgery Market
Medical Devices
Smart Syringe Market
Medical Devices
Brain Base Knife Package Market
Medical Devices
Epistaxis Devices Market
Medical Devices
Implantable Drug Eluting Devices Market
Medical Devices
Table-Top Autorefractor Market