
 Electrosurgery Market | 2026-2036
Electrosurgery Market Size, Share, and Industry Trends Forecast 2026-2036
Electrosurgery Market Intelligence
Hospital procurement channels is rewriting how electrosurgical capital reaches operating rooms, with group purchasing organizations consolidating vendor panels and squeezing out regional distributors. Medtronic Plc leverages its broad catheter and energy platform portfolio to anchor multi-year supply contracts. Johnson & Johnson sustains channel dominance through its Ethicon surgical franchise and deep ties with integrated delivery networks. Erbe Elektromedizin GmbH specializes in precision bipolar and vessel sealing systems that compete on technical performance rather than price.
Electrosurgery employs high-frequency alternating current to cut, coagulate, or desiccate tissue during surgical procedures, with generators typically operating between 300 kHz and 3 MHz to minimize neuromuscular stimulation while achieving thermal tissue effects. The technology serves as a cornerstone of minimally invasive and open surgical workflows across general surgery, gynecology, and cardiovascular intervention. Electrosurgical generators and instruments command the largest revenue share within product categories, while radiofrequency and ultrasonic modalities represent the fastest-expanding technology segments as surgeons seek alternatives to traditional monopolar coagulation with reduced thermal spread. General surgery and gynecology applications generate the steadiest volume demand, though cardiovascular procedures offer the highest per-procedure equipment utilization rates.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements shape product development timelines and market access costs for electrosurgical device manufacturers. Japan's PMDA and China's NMPA impose additional electromagnetic compatibility and biocompatibility testing standards that fragment regulatory submission strategies. Stakeholders must monitor how FDA guidance on reusable device reprocessing and EU F-Gas Regulation constraints on sterilization gases alter total cost-of-ownership calculations for hospital buyers.
Market Dynamics
Hospital procurement consolidation through group purchasing organizations is compressing vendor margins and forcing electrosurgical manufacturers toward multi-year supply contracts anchored by platform breadth rather than standalone device sales.
Growth Catalysts
- EU MDR recertification timelines:Extended clearance cycles favor incumbent manufacturers with established technical documentation, creating barriers for new entrants and stabilizing competitive positions for compliant suppliers.
- Radiofrequency ablation modalities:These precision energy platforms are displacing traditional monopolar coagulation in oncology and cardiology procedures, expanding addressable procedure volumes.
- Japan's aging surgical infrastructure:Replacement cycles for legacy electrosurgical generators in tertiary hospitals are accelerating demand for advanced vessel sealing systems.
Market Restraints
- Copper and semiconductor input costs:Electromagnetic coil materials and power management chips face price volatility that squeezes generator manufacturing margins.
- FDA 510(k) clearance backlog:Premarket notification delays extend product launch timelines and defer revenue recognition for novel electrosurgical accessories.
- Laser and ultrasonic substitutes:These alternative energy modalities compete for soft-tissue dissection applications, particularly in laparoscopic gynecology.
Strategic Opportunities
- Outpatient ambulatory surgery centers:These facilities remain underpenetrated for advanced bipolar systems, offering volume expansion beyond traditional hospital operating rooms.
- India's PLI scheme for medical devices:Domestic manufacturing incentives reduce import dependence and create localized supply advantages for electrosurgical instrument assembly.
- AI-integrated smoke evacuation:Convergence of computer vision and electrosurgical generators enables real-time tissue recognition and automated power modulation.
Industry Challenges
- Biomedical engineering talent scarcity:Specialized expertise in high-frequency circuit design and thermal modeling remains concentrated among a limited pool of practitioners.
- EU F-Gas Regulation compliance:Sterilization gas constraints complicate reprocessing validation for reusable electrosurgical pencils and forceps.
- Legacy generator interoperability:Integration complexity with installed base units limits upgrade pathways for advanced instrument attachments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrosurgery Market |
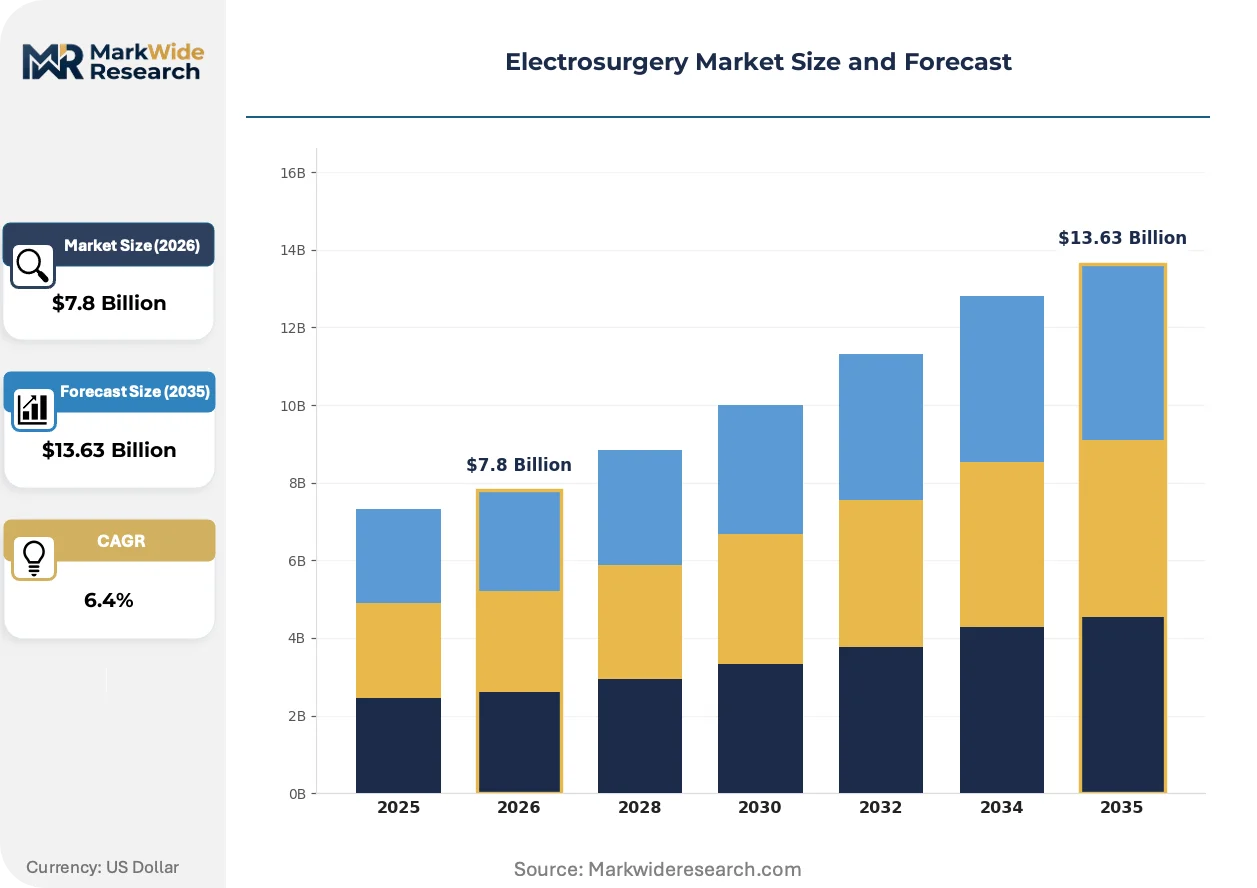
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $13.63 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrosurgical Generators, Electrosurgical Instruments, Accessories, Electrosurgical Electrodes Technology: Monopolar, Bipolar, Ultrasonic, Radiofrequency, Microwave Application: General Surgery, Gynecology, Neurosurgery, Cardiovascular Procedures, Dermatology End User: Ambulatory Surgery Centers, Specialty Clinics, Diagnostic Laboratories, Academic Research Institutes |
| Companies Covered | Medtronic Plc, Johnson & Johnson, Olympus Corporation, CONMED Corporation, Erbe Elektromedizin GmbH, B. Braun Melsungen AG, Smith & Nephew Plc, Boston Scientific Corporation, Stryker Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrosurgery Market Strategic Shifts & Innovations
Digital integration and energy platform convergence are redefining how electrosurgical systems deliver value, shifting competitive differentiation from hardware specifications toward intelligent tissue response algorithms and connected surgical workflows.
Advanced electrosurgical generators is virtualizing traditional analog power delivery through embedded sensors and machine learning models that adjust current output in real-time based on tissue impedance feedback. Academic medical centers in Germany and the United States are piloting these systems at accelerated procurement cycles. This virtualization is compressing the performance gap between premium and mid-tier generator categories, forcing manufacturers to differentiate through software subscription models rather than hardware tiering alone.
EU MDR technical documentation requirements are extending recertification timelines for legacy electrosurgical products and imposing new clinical evidence standards on reusable device families. Manufacturers must resubmit technical files for previously CE-marked instruments, diverting regulatory affairs resources from new product development. The vessel sealing instrument segment faces the steepest compliance burden, with several suppliers withdrawing older product lines rather than absorbing MDR validation costs.
Integrated delivery networks are consolidating vendor panels and unbundling after-sales service contracts from capital equipment purchases. Group purchasing organizations in the United States now specify multi-year consumable commitments as a condition of generator placement, shifting revenue concentration toward disposable electrodes and tips. This pattern is most visible in cardiovascular service lines, where procedure volume guarantees increasingly determine equipment selection criteria.
Electrosurgery Market Segmentation
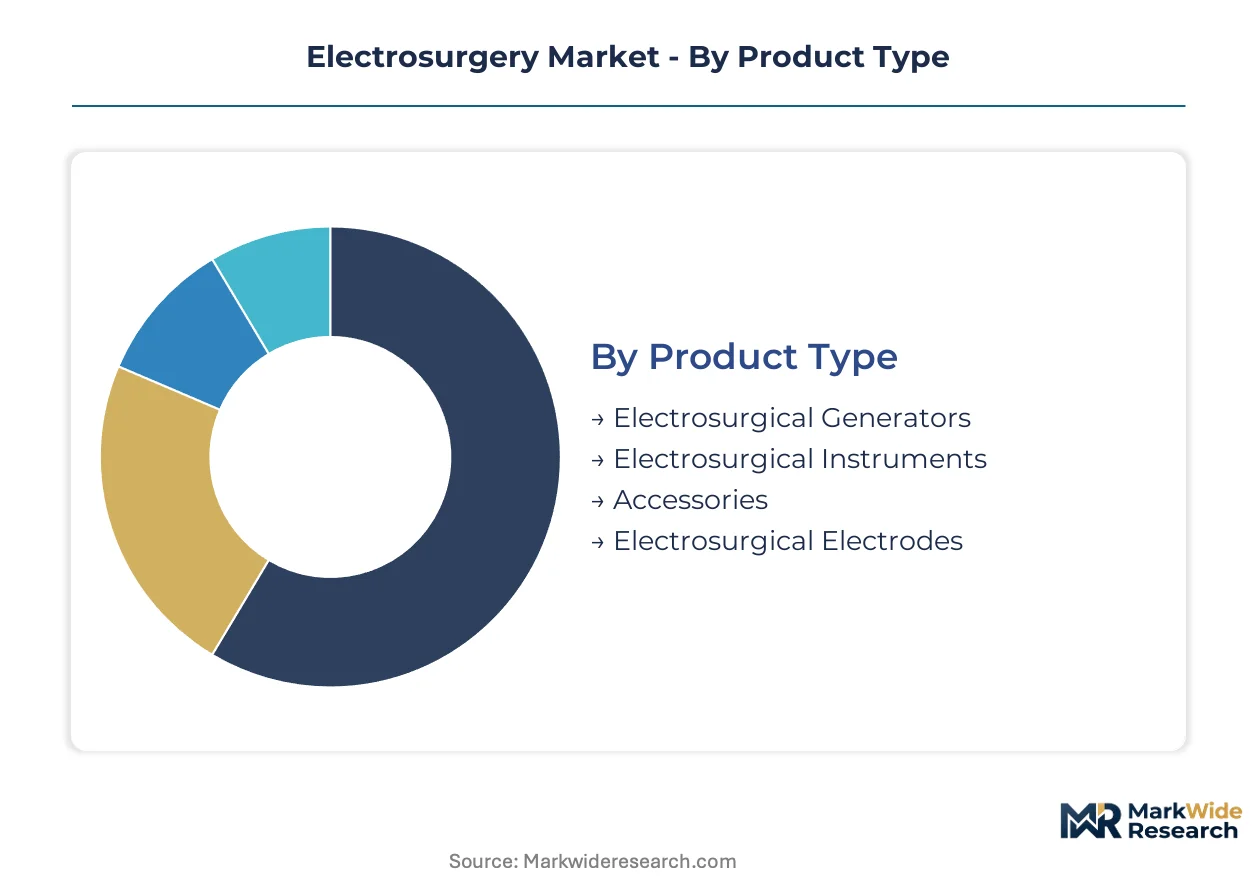
Electrosurgery segmentation reveals how capital equipment, consumable attachments, and energy modalities compete for distinct budget lines within hospital procurement. Product type and technology dimensions command the highest strategic attention due to their direct impact on per-procedure economics and vendor lock-in dynamics.
Product Type:
Cost tier separation between capital equipment and disposable attachments determines procurement cycle timing and contract negotiation leverage for hospital buyers.
- Electrosurgical Generators:These high-frequency power units (300 kHz to 3 MHz) anchor surgical suite infrastructure. Tertiary hospitals in the United States and Germany prioritize generator replacement cycles as vessel sealing capabilities displace legacy monopolar systems.
- Electrosurgical Instruments:Forceps, scissors, and dissectors with integrated energy delivery represent the highest-margin recurring revenue stream. Integrated delivery networks negotiate multi-year consumable commitments tied to generator placements.
- Accessories:Foot pedals, cables, and adapters face commodity pricing pressure from third-party reprocessors.
- Electrosurgical Electrodes:Disposable tips and pencils rotate through high-volume general surgery service lines with standardized SKUs.
Generators hold installed capacity. Instruments are rotating up the share rankings.
Technology:
Application specificity drives technology selection, with thermal spread tolerance and tissue interaction precision determining modality adoption by surgical specialty.
- Monopolar:The foundational high-frequency current architecture serves cost-sensitive procedures through single-patient-use dispersive pads. General surgery suites in India and Brazil retain monopolar dominance for open abdominal cases where thermal spread carries lower complication risk.
- Bipolar:Precision current confinement between instrument jaws enables vessel sealing with minimal lateral thermal damage. Cardiovascular and gynecology procedures in Japan's aging surgical infrastructure drive replacement demand for advanced bipolar platforms.
- Ultrasonic:Mechanical vibration cutting with simultaneous coagulation competes for laparoscopic soft-tissue dissection.
- Radiofrequency:Impedance-controlled ablation modalities expand into oncology and cardiology intervention.
- Microwave:Emerging thermal ablation technology targets hepatic and renal tumor applications.
Bipolar systems command the premium tier. Radiofrequency is climbing the fastest.
Application:
Procedure volume concentration and reimbursement intensity create divergent equipment utilization profiles across surgical specialties.
- General Surgery:Appendectomy, cholecystectomy, and hernia repair generate the steadiest instrument consumption. United States ambulatory surgery centers deploy compact bipolar systems for same-day discharge protocols.
- Cardiovascular Procedures:Highest per-case equipment utilization with vessel sealing demands. German academic medical centers pilot AI-integrated generators for real-time tissue response.
- Gynecology:Hysterectomy and myomectomy procedures favor precision energy to preserve adjacent tissue.
- Neurosurgery:Thermal spread constraints limit modality options to specialized bipolar configurations.
- Dermatology:Office-based lesion removal drives portable generator demand.
General Surgery anchors volume throughput. Cardiovascular is gaining share fastest.
End User:
Customer type differentiation separates capital-intensive hospital systems from volume-flexible outpatient facilities with divergent procurement authority structures.
- Ambulatory Surgery Centers:These facilities remain underpenetrated for advanced bipolar platforms. United States group purchasing organizations now specify procedure volume guarantees as equipment placement conditions.
- Specialty Clinics:Dermatology and gastroenterology practices favor compact radiofrequency units for in-office procedures.
- Diagnostic Laboratories:Limited electrosurgical exposure restricted to biopsy processing applications.
- Academic Research Institutes:Pilot sites for AI-integrated smoke evacuation and computer vision modulation systems.
Ambulatory Surgery Centers hold expansion capacity. Academic Research Institutes are rotating up the influence rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Germany and Japan where tertiary hospitals prioritize vessel sealing precision over procurement savings, while cost-sensitive markets in India and Brazil retain monopolar dominance for open abdominal procedures. This asymmetry shapes divergent product mix strategies across geographies.
United States
Integrated delivery networks in the United States consolidate vendor panels through group purchasing organizations, squeezing regional distributors from electrosurgical supply chains. FDA 510(k) clearance pathways extend product launch timelines for novel accessories, favoring incumbents with established technical documentation. Academic medical centers in Boston and the Research Triangle pilot AI-integrated generators with real-time tissue impedance feedback.
Germany
German academic medical centers drive replacement cycles for legacy electrosurgical generators as vessel sealing capabilities displace older monopolar systems. EU MDR recertification timelines impose new clinical evidence standards on reusable instrument families, diverting regulatory affairs resources from new product development. The Baden-Württemberg medical technology cluster hosts precision bipolar specialists competing on technical performance rather than price.
Japan
Japan's aging surgical infrastructure in tertiary hospitals accelerates demand for advanced bipolar platforms with minimal thermal spread. PMDA electromagnetic compatibility and biocompatibility testing standards fragment regulatory submission strategies for foreign manufacturers. Tokyo and Osaka metropolitan areas concentrate procurement authority for high-value cardiovascular service lines with elevated per-procedure equipment utilization.
India
India's PLI scheme for medical devices reduces import dependence and creates localized supply advantages for electrosurgical instrument assembly. Cost-sensitive general surgery suites retain monopolar dominance for open procedures where thermal spread carries lower complication risk. Manufacturing clusters in Maharashtra and Gujarat scale domestic production of disposable electrodes and standardized instrument SKUs.
Brazil
Brazilian hospital procurement channels favor established generator brands with proven interoperability against legacy installed bases. ANVISA regulatory pathways for electromagnetic compatibility testing delay market entry for novel radiofrequency modalities. São Paulo's private hospital networks anchor demand for mid-tier bipolar systems balancing performance specifications with capital constraints.
Electrosurgery Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream supplying forceps, electrodes, and cables to multi-brand installed bases. The electrosurgery market structures around three archetypes: diversified medical technology conglomerates anchoring multi-year supply contracts, precision energy specialists competing on technical performance, and regional assemblers serving price-sensitive procurement channels. Consolidation pressures intensify as group purchasing organizations unbundle after-sales service from capital equipment purchases, while EU MDR compliance costs force smaller instrument suppliers toward strategic exits or acquisition.
Among diversified platform providers, Medtronic Plc and Johnson & Johnson occupy positions anchored by broad catheter and energy portfolios that secure integrated delivery network contracts. Erbe Elektromedizin GmbH exemplifies the precision specialist archetype, with German engineering heritage supporting technical differentiation in vessel sealing systems. These three entities represent distinct competitive vectors: scale-driven platform breadth, franchise-level channel integration, and engineering-led performance positioning.
| Leading Market Players |
|---|
| Medtronic Plc |
| Johnson & Johnson |
| Olympus Corporation |
| CONMED Corporation |
| Erbe Elektromedizin GmbH |
| B. Braun Melsungen AG |
| Smith & Nephew Plc |
| Boston Scientific Corporation |
| Stryker Corporation |
| Others |
Cost & Logistics Intelligence
Copper and semiconductor price volatility determines both pricing tier spreads and supply chain shape across electrosurgical generator manufacturing, compressing margins on mid-tier units while forcing OEMs toward dual-sourcing strategies for electromagnetic coil materials and power management chips.
Pricing Analysis
Customization-premium spreads separate configured-to-order vessel sealing systems from standard monopolar generators by a factor of three to five across hospital procurement channels. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance tier, ISO 13485 certification grade, and bundled after-sales service intensity. Cost compression in mid-tier bipolar platforms is intensifying because group purchasing organizations unbundle service contracts from capital equipment purchases. Ambulatory surgery centers exhibit the highest price sensitivity, while German and Japanese tertiary hospitals prioritize technical performance over procurement savings.
Supply Chain Analysis
Contract manufacturing concentration rests with German precision engineering clusters, Malaysian electronics assembly hubs, and Chinese component foundries holding capacity for high-frequency circuit boards and disposable instrument molding. Raw material dependencies draw from Chilean copper cathode, Taiwanese semiconductor wafers, and Japanese ceramic substrates for bipolar forceps insulation. Single-source vulnerability concentrates in electromagnetic coil winding capacity, where specialized biomedical engineering expertise limits qualified supplier pools. Distribution runs through group purchasing organization vendor panels that consolidate regional distributors and anchor multi-year consumable commitments to generator placements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through integrated delivery network consolidation in the United States and group purchasing organization panel narrowing in Germany, shifting negotiation leverage toward hospital systems and away from standalone device vendors.
For Market Incumbents: Pre-empt ultrasonic and laser substitute technologies by anchoring AI-integrated generator platforms with real-time tissue impedance feedback in academic medical centers. Deepen backward integration into electromagnetic coil manufacturing to offset copper price volatility and secure supply continuity against single-source winding capacity constraints. For New Entrants and Emerging Players: Build out ambulatory surgery center penetration for compact bipolar systems, where procedure volume guarantees now determine equipment selection criteria and incumbent presence remains thin. Target India's PLI scheme for medical devices to establish localized instrument assembly and capture cost-sensitive general surgery demand with standardized SKU offerings. For Investors and Strategic Acquirers: Precision bipolar instrument specialists with EU MDR technical documentation already filed represent the most defensible acquisition archetype, as extended recertification timelines favor compliant suppliers and create barriers for new entrants. Monitor FDA 510(k) clearance backlog duration as an inflection indicator for revenue recognition timing and novel accessory launch viability.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Resubmission | Extended recertification timelines favor incumbent manufacturers with established clinical evidence portfolios. |
| AI-Integrated Generator Development | Real-time tissue impedance feedback systems differentiate premium platforms in German academic medical centers. |
| Ambulatory Surgery Center Partnership | Procedure volume guarantees as placement conditions unlock underpenetrated bipolar system demand. |
| Backward Integration into Coil Manufacturing | Captive electromagnetic coil production insulates margins from copper price volatility and supply disruption. |
| India PLI Scheme Manufacturing Footprint | Localized instrument assembly reduces import dependence and captures cost-sensitive monopolar demand. |
Research Approach
Cross-validation between primary interviews with hospital purchasing committees, biomedical engineers, GPO contracts managers, and electrosurgical device regulatory affairs leads anchors the qualitative findings against secondary validation from FDA 510(k) filings, EU MDR technical documentation databases, hospital procurement contract registries, and customs trade data for electromagnetic component imports. Bottom-up procedure volume estimates triangulate against top-down generator installed base calculations.
Calibration against historical replacement cycle patterns and vessel sealing adoption curves shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product type hierarchy, technology modality, surgical application specialty, and end-user facility tier. CAGRs derive from logistic diffusion curves fitted to bipolar platform displacement rates and radiofrequency ablation expansion trajectories. Forecast inputs incorporate copper futures pricing volatility bands and EU F-Gas Regulation compliance cost assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by diversified medical technology conglomerates or precision energy specialists would shift outcomes beyond modeled ranges. Quarterly review of FDA 510(k) clearance backlog duration, EU MDR technical file resubmission rates, and group purchasing organization vendor panel consolidation announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Surgical Instruments
Knee Surgical Impactor Market
Surgical Instruments
Laparoscopic Sutures Market
Surgical Instruments
Surgical Sutures Market
Surgical Instruments
Surgical Suction Pumps Market
Surgical Instruments
Minimally Invasive Gastrointestinal Surgical System Market
Surgical Instruments
France General Surgical Devices Market
Surgical Instruments
Americas Suture Needles Market
Surgical Instruments
Laparoscopic Needle Holder Robotic Devices Market
Surgical Instruments
Brazil General Surgical Devices Market
Surgical Instruments
Surgical Lamps Market
Surgical Instruments
Cold Disposable Biopsy Forceps Market
Surgical Instruments
Neurosurgery Surgical Power Tools Market
Surgical Instruments
Surgical Drainage Devices Market
Surgical Instruments
Articulating Paper Forceps Market
Surgical Instruments
Absorbable Surgical Suture with Needle Market
Surgical Instruments
Disposable Spinal Instruments Market