
 Collateral Ligament Stabilizers Market | 2026-2036
Collateral Ligament Stabilizers Market Size, Share, and Industry Trends Forecast 2026-2036
Collateral Ligament Stabilizers Market Outlook
REACH compliance is expanding the cost-of-entry calculus for European manufacturers of neoprene-based stabilizers. DeRoyal Industries leverages its vertically integrated domestic manufacturing to sustain pricing flexibility amid these regulatory burdens. Bauerfeind anchors its competitive position through German-engineered compression technology that dominates clinical channels across Central Europe.
Collateral ligament stabilizers are orthopedic devices designed to restrict varus or valgus stress at the knee joint through mechanical bracing, taping, or surgical fixation, typically constructed from woven nylon or molded neoprene with adjustable hinge mechanisms calibrated to 0-30 degrees of flexion. Their primary commercial purpose centers on preventing medial collateral ligament (MCL) and lateral collateral ligament (LCL) rupture during high-torque athletic movements while enabling controlled rehabilitation mobility. Braces occupy the dominant revenue position due to their reusable nature and institutional procurement contracts, whereas surgical devices command premium margins despite smaller volumes. Home care represents the fastest-growing end-user channel as post-operative protocols shift toward remote monitoring and patient-administered rehabilitation.
FDA 510(k) premarket notification requirements govern US commercialization pathways for ligament stabilizers, while the EU Medical Device Regulation (MDR) imposes stricter clinical evidence standards than its predecessor directive. Japan's PMDA maintains distinct biocompatibility testing protocols that delay entry for foreign manufacturers by twelve to eighteen months relative to domestic approvals. Stakeholders must monitor evolving MDR transition timelines and CMS reimbursement coding decisions for outpatient orthopedic bracing.
Market Dynamics
FDA 510(k) clearance pathways are compressing product development timelines while sports medicine protocols tighten injury management standards, creating dual pressure on manufacturers to accelerate clinical validation without sacrificing biomechanical precision.
Growth Catalysts
- Collegiate sports medicine infrastructure:United States universities are expanding athletic training budgets and mandating pre-injury bracing protocols for high-torque sports, institutionalizing preventive procurement.
- EU MDR clinical evidence standards:Stricter biocompatibility and performance documentation requirements are filtering out marginal competitors and consolidating demand around established manufacturers with regulatory bandwidth.
- Neoprene compression engineering:Advances in woven nylon-molded neoprene hybrids with calibrated hinge mechanisms are improving patient compliance and extending device lifecycle economics.
Market Restraints
- REACH chemical compliance costs:European manufacturers face expanded cost-of-entry calculus for neoprene-based stabilizers as ECHA substance restrictions tighten raw material sourcing.
- PMDA biocompatibility delays:Japan's distinct testing protocols extend foreign manufacturer entry timelines by twelve to eighteen months relative to domestic approvals, freezing early-mover advantages.
- Surgical fixation substitution:Arthroscopic ligament reconstruction techniques are capturing severe injury cases that previously defaulted to long-term bracing regimens.
Strategic Opportunities
- Home care rehabilitation protocols:Post-operative remote monitoring and patient-administered recovery programs are opening direct-to-consumer channels outside traditional institutional procurement.
- CMS outpatient orthopedic bracing codes:Reimbursement coding decisions under review create positioning windows for manufacturers who align evidence packages with emerging coverage criteria.
- Wearable sensor convergence:Integration of motion-tracking electronics with mechanical bracing is enabling real-time compliance monitoring and telehealth integration for remote physical therapy.
Industry Challenges
- ISO 13485 quality system maintenance:Small and mid-cap specialists struggle to sustain audit-ready documentation across multiple notified bodies simultaneously.
- Biomechanical engineering talent scarcity:The intersection of orthopedic medicine and materials science requires specialized expertise that outpaces current graduate pipeline output.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Collateral Ligament Stabilizers Market |
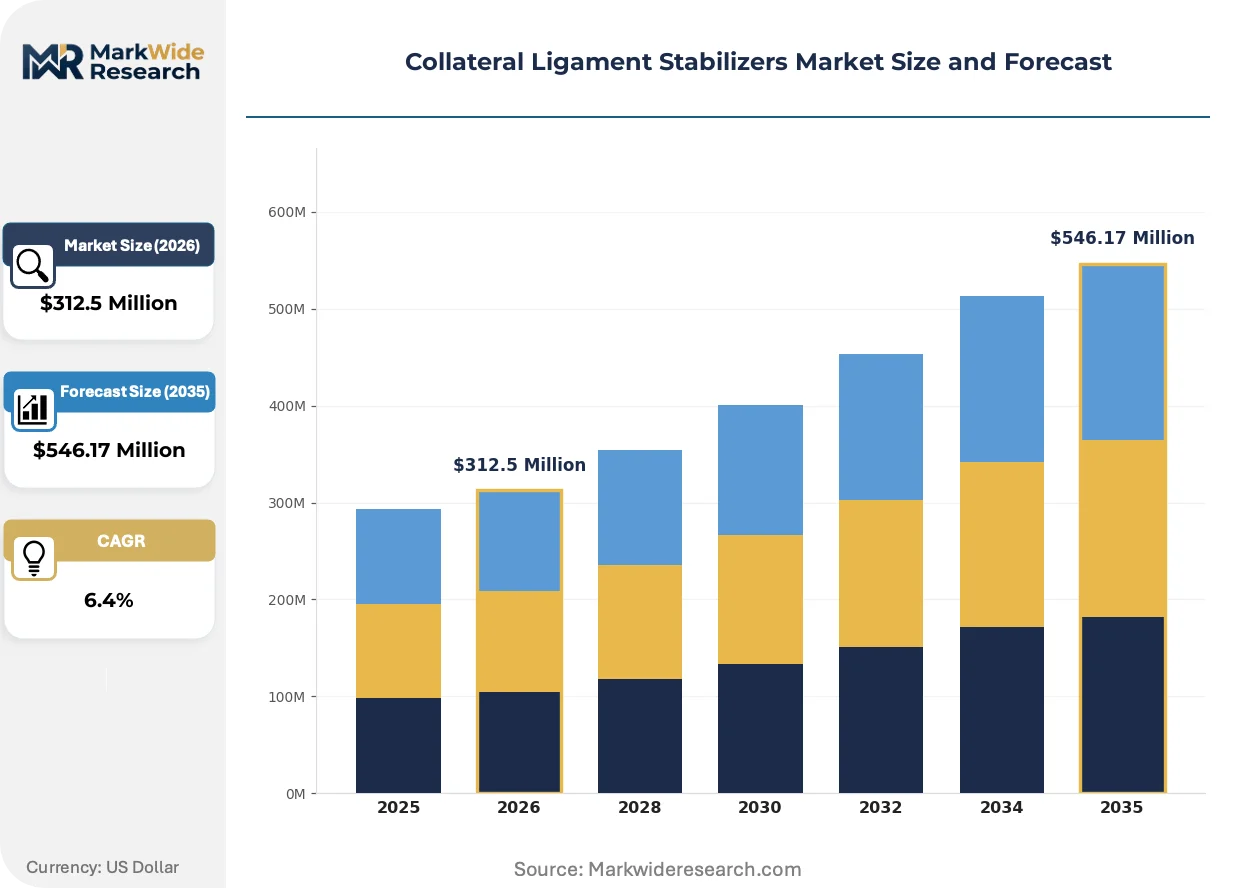
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $546.17 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Braces, Tapes, Surgical Devices, Supports Material: Nylon, Polyester, Neoprene, Cotton End User: Rehabilitation Centers, Hospitals, Sports Clinics, Home Care Distribution Channel: Online Stores, Specialty Retailers, Pharmacies, Direct Sales |
| Companies Covered | DeRoyal Industries, Inc., Arthrex, Inc., Bauerfeind, Bio Dynamic Technologies, DePuy Synthes, Ossur, Orthofix Medical, Inc., DARCO International, Inc., Enovis Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Collateral Ligament Stabilizers Market Strategic Shifts
Mechanical bracing is absorbing digital functionality while regulatory frameworks on both sides of the Atlantic force evidence-generation investments that favor capitalized incumbents over agile entrants.
Carbon fiber composite hinge mechanisms are absorbing torsional stress loads previously requiring rigid metal frames, reducing device weight by forty percent without sacrificing varus-valgus restraint calibration. Professional sports franchises and Olympic training facilities are piloting these materials for athlete return-to-play protocols. The structural consequence is absorbing premium pricing into standard institutional contracts as performance differentiation narrows between material tiers.
EU Medical Device Regulation transition timelines are forcing manufacturers to retrospectively compile clinical performance data for legacy products previously cleared under the Medical Device Directive. This regulatory burden is consuming R&D budgets that would otherwise flow to next-generation product lines. German and Swiss orthopedic device clusters are responding by pooling post-market surveillance data through industry consortia to spread compliance costs.
Athletic trainers and physical therapists are consolidating purchasing authority through group purchasing organizations that unbundle after-sales fitting services from device procurement. Hospital systems and outpatient surgery centers are displacing individual clinician preference with standardized formularies negotiated at system level. This concentration is most visible across the southeastern and midwestern United States where consolidated health networks dominate sports medicine service delivery.
Collateral Ligament Stabilizers Market Segmentation
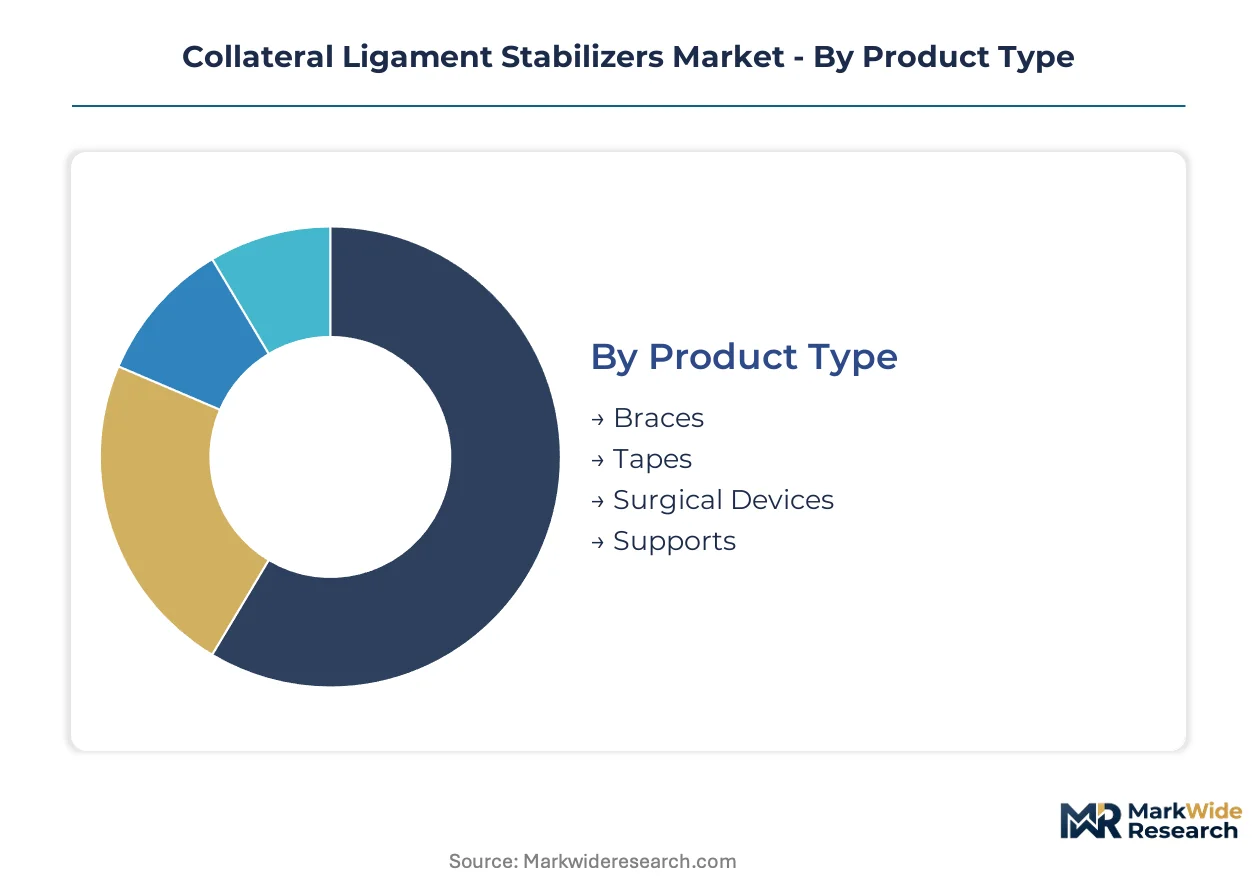
Collateral ligament stabilizers serve distinct clinical and consumer needs that fragment procurement patterns across institutional buyers and direct purchasers. Manufacturers must align product specifications with end-user technical requirements while navigating divergent distribution economics.
Product Type:
Customization intensity varies sharply across this category, from off-the-shelf adjustable braces to patient-matched surgical fixation systems.
- Braces:Mechanical devices constructed from woven nylon or molded neoprene with calibrated hinge mechanisms restricting varus-valgus stress to 0-30 degrees of flexion. Demand concentrates in United States collegiate sports medicine programs where institutional procurement contracts favor reusable devices with extended lifecycle economics.
- Surgical Devices:Internal fixation systems including interference screws and suture anchors for ligament reconstruction procedures. Growth accelerates in hospital outpatient departments as arthroscopic techniques displace long-term bracing for severe MCL and LCL ruptures.
- Tapes:Adhesive kinesiology and athletic taping systems for acute injury management and proprioceptive feedback during return-to-play protocols.
- Supports:Compression sleeves and wraparound stabilizers providing mild mechanical restraint without rigid hinge structures.
Leading the category by volume: Braces. Growing fastest: Surgical Devices.
Material:
Cost tier stratification runs from commodity synthetics to engineered composites with differentiated regulatory compliance burdens.
- Neoprene:Closed-cell synthetic rubber delivering compression, thermal retention, and moisture resistance in molded stabilizer construction. REACH chemical restrictions in Europe are forcing reformulation investments that filter marginal suppliers from EEA distribution channels.
- Nylon:High-tensile woven polymer forming the structural matrix of hinge-based braces and strap systems. Japanese PMDA biocompatibility protocols impose twelve-to-eighteen-month approval delays on foreign manufacturers utilizing nylon blends not previously cleared in domestic applications.
- Polyester:Lower-cost synthetic alternative with reduced elasticity recovery compared to nylon, common in economy-tier supports.
- Cotton:Natural fiber limited to hypoallergenic applications and markets with restricted synthetic polymer acceptance.
Neoprene commands premium positioning in clinical channels. Polyester supports are expanding most quickly in direct-to-consumer online distribution.
End User:
Customer type determines specification intensity, from protocol-driven institutional procurement to self-directed consumer selection.
- Sports Clinics:Specialized facilities serving professional and collegiate athletes with mandated pre-injury bracing protocols and return-to-play clearance requirements. United States athletic training budgets are institutionalizing preventive procurement through system-level formularies.
- Home Care:Post-operative rehabilitation settings where patients administer recovery protocols with remote physical therapy oversight. CMS outpatient orthopedic bracing reimbursement decisions are reshaping coverage criteria for this channel.
- Hospitals:Acute care and outpatient surgery centers integrating stabilizers into comprehensive orthopedic service lines.
- Rehabilitation Centers:Dedicated physical therapy facilities emphasizing graduated mobility restoration.
Sports clinics dominate institutional revenue. Home care is gaining share fastest as remote monitoring protocols expand.
Distribution Channel:
Supply concentration varies from fragmented retail networks to consolidated direct procurement relationships.
- Specialty Retailers:Orthopedic and medical supply stores providing fitting services and clinician consultation. Group purchasing organizations across southeastern and midwestern United States are unbundling after-sales fitting from device procurement, compressing margin structures.
- Online Stores:E-commerce platforms enabling direct-to-consumer access with telehealth-integrated sizing tools. Wearable sensor convergence is enabling real-time compliance monitoring through this channel.
- Pharmacies:Retail drugstore chains with limited orthopedic specialization but broad geographic coverage.
- Direct Sales:Manufacturer-to-institution contracts bypassing intermediaries for high-volume sports medicine and hospital system accounts.
Specialty retailers retain the largest transaction volume. Online stores show the steepest expansion trajectory as home care rehabilitation protocols proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States collegiate and professional sports medicine infrastructure concentrates demand for collateral ligament stabilizers, with institutional procurement contracts driving volume. Germany and Switzerland anchor European engineering standards for compression technology. Japan's distinct regulatory protocols create entry barriers that domestic manufacturers exploit.
United States
NCAA athletic training budgets and NFL team medical protocols institutionalize preventive bracing for high-torque sports. FDA 510(k) clearance pathways compress product development timelines while tightening clinical validation standards. Texas and Florida sports medicine clusters concentrate procurement authority through consolidated health network formularies.
Germany
Engineered compression technology from Baden-Württemberg and Bavaria dominates clinical channels across Central Europe. EU MDR transition timelines force retrospective clinical data compilation for legacy products. The Tübingen-Stuttgart orthopedic device corridor pools post-market surveillance through manufacturer consortia to spread compliance costs.
Switzerland
Swissmedic maintains premium-tier positioning for precision-manufactured stabilizers serving Alpine sports medicine facilities. REACH chemical restrictions on neoprene formulations filter marginal suppliers from European distribution. The Basel-Zurich medtech cluster concentrates biomechanical engineering talent scarce across broader European markets.
Japan
PMDA biocompatibility testing protocols extend foreign manufacturer entry timelines by twelve to eighteen months versus domestic approvals. METI industrial policy supports local orthopedic device champions through preferential procurement in national health insurance reimbursement. The Osaka-Nagoya manufacturing belt retains captive supply chains for nylon-woven structural components.
United Kingdom
NHS orthopedic procurement frameworks standardize stabilizer specifications across hospital trusts and outpatient surgery centers. MHRA post-Brexit regulatory autonomy creates divergence from EU MDR timelines that UK-based manufacturers must navigate. The Oxford-Cambridge medtech corridor attracts venture funding for wearable sensor integration with mechanical bracing systems.
Collateral Ligament Stabilizers Market Competitive Environment
German and Swiss producers anchor the premium engineering tier; United States specialists hold institutional procurement channels through vertically integrated domestic manufacturing. The vendor base stratifies across three archetypes: capitalized incumbents with regulatory bandwidth, mid-cap regional champions with captive production, and agile sensor-technology entrants. Consolidation pressure intensifies as EU MDR compliance costs filter marginal competitors. Dominant competitive moves include backward integration into neoprene compounding and strategic partnerships with collegiate athletic conferences for protocol-driven adoption.
Within the capitalized incumbent tier, DeRoyal Industries exemplifies vertically integrated domestic manufacturing that sustains pricing flexibility amid regulatory burdens. Bauerfeind occupies a position representing German-engineered compression technology that dominates clinical channels across Central Europe. Arthrex, Inc. sits within the surgical fixation specialist archetype, anchoring premium-margin positioning in hospital outpatient departments where arthroscopic techniques displace long-term bracing.
| Leading Market Players |
|---|
| DeRoyal Industries, Inc. |
| Arthrex, Inc. |
| Bauerfeind |
| Bio Dynamic Technologies |
| DePuy Synthes |
| Ossur |
| Orthofix Medical, Inc. |
| DARCO International, Inc. |
| Enovis Corporation |
| Others |
Value Chain & Pricing Dynamics
Neoprene feedstock indices and REACH chemical compliance costs cascade through three pricing tiers, compressing margins for European manufacturers while rewarding vertically integrated domestic producers in the United States with procurement flexibility against regulatory burdens.
Pricing Analysis
Braces generate volume at compressed margins through institutional sports medicine contracts, while surgical devices command premium positioning in hospital outpatient departments despite smaller transaction counts. Three-tier pricing structure across premium, standard, and economy levels separates German-engineered compression systems from mid-tier nylon-hinge alternatives and basic polyester supports. Price differentiation hinges on FDA 510(k) clearance tier and ISO 13485 certification status. Cost compression in the economy tier intensifies as group purchasing organizations unbundle fitting services from device procurement. Collegiate athletic programs exhibit lowest price sensitivity due to mandated preventive bracing protocols, whereas direct-to-consumer online purchasers demonstrate highest elasticity.
Supply Chain Analysis
Single-source vulnerability sits with Taiwanese woven nylon suppliers and German neoprene compounding facilities that anchor structural component production. Manufacturing draws from United States domestic molding operations, Baden-Württemberg precision engineering clusters, and Osaka-Nagoya captive supply chains for hinge mechanisms. Raw material dependencies center on petroleum-derived synthetic rubber, high-tensile polymer fibers, and medical-grade aluminum alloys. Tariff exposure on Chinese-sourced compression textiles threatens cost structures for non-vertically integrated assemblers. Distribution runs through consolidated health network formularies in the southeastern and midwestern United States, specialty orthopedic retailers, and telehealth-integrated direct-to-consumer platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR compliance costs are filtering marginal competitors from European distribution, creating consolidation pressure that favors capitalized incumbents with regulatory bandwidth and documented clinical evidence packages.
For Market Incumbents: Deploy backward integration into neoprene compounding to neutralize REACH chemical restriction impacts and sustain pricing flexibility against European competitors. Fortify hospital system formulary positioning through ISO 13485 audit-ready documentation and pooled post-market surveillance consortia. Counter surgical fixation substitution threats by integrating wearable sensor technology into brace platforms for remote compliance monitoring. For New Entrants and Emerging Players: Capture direct-to-consumer home care rehabilitation channels where telehealth-integrated sizing tools and wearable sensor convergence enable bypass of consolidated group purchasing organization procurement. Target online specialty retailers with proprioceptive feedback tape systems for acute injury management. Leverage carbon fiber composite hinge innovations to differentiate against established metal-frame incumbents in professional sports franchise pilot programs. For Investors and Strategic Acquirers: The window for entry favors mid-cap regional champions with captive production and existing FDA 510(k) clearances that can absorb EU MDR retrospective clinical data compilation costs. Acquisition focus should center on German and Swiss orthopedic device clusters with pooled surveillance infrastructure. Monitor CMS outpatient orthopedic bracing reimbursement coding decisions as the inflection signal for home care channel viability.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR transition timelines force retrospective clinical data compilation for legacy device clearances. |
| Hospital System Partnership | Consolidated health network formularies in Texas and Florida displace individual clinician preference. |
| Software Companion Development | Wearable sensor integration enables real-time compliance monitoring for remote physical therapy protocols. |
| Reimbursement Strategy | CMS coding decisions reshape coverage criteria for home care rehabilitation channel expansion. |
| Backward Integration | In-house neoprene compounding neutralizes REACH chemical restriction cost pressures on European competitors. |
Study Parameters
Multi-period observation of NCAA athletic training budget allocations, FDA 510(k) clearance timelines, and EU MDR transition compliance costs anchored the trend analysis, supplemented by interviews with orthopedic device product managers, hospital GPO contracts managers, sports medicine clinicians, and biomedical engineers. Secondary validation drew from FDA premarket notification databases, EUDAMED device registrations, CMS Medicare reimbursement coding updates, and hospital procurement contract disclosures. Bottom-up segment sizing triangulated against top-down market value estimates across product type, material, end user, and distribution channel dimensions.
Input-output matrix modeling connected neoprene raw material cost indices, REACH chemical compliance expenditure patterns, and collegiate sports medicine procurement cycle timing to volume and value outputs across the analysis window. Segmentation dimensions included brace versus surgical device versus tape product categories, neoprene-nylon-polyester material tiers, sports clinic versus home care versus hospital end-user channels, and specialty retail versus online versus direct sales distribution structures. CAGRs were derived from fitted trend extrapolation calibrated to historical FDA clearance velocity and institutional procurement contract renewal patterns. Forecast inputs incorporated PMDA biocompatibility testing protocol timelines and carbon fiber composite hinge adoption curves in professional sports facilities.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU MDR enforcement intensity, CMS reimbursement coding revisions, and arthroscopic surgical technique advancement rates. Assumptions underlying projections include sustained collegiate sports medicine budget growth, stable neoprene feedstock pricing, and gradual wearable sensor integration adoption. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Medical Loupes Market
Medical Devices
Global External Fixators Market
Medical Devices
Next Generation Infusion Pump Market
Medical Devices
South Africa Ultrasound Devices Market
Medical Devices
Speech Generating Devices Market
Medical Devices
Global Vein Illuminator Market
Medical Devices
Buccal Drug Delivery System Market
Medical Devices
Gutta Percha Obturator Market
Medical Devices
India Contraceptive Devices Market
Medical Devices
In Vitro Fertilization Monitoring System Market
Medical Devices
Global Defibrillators Market
Medical Devices
Annuloplasty Rings Market
Medical Devices
Endoprosthesis Market
Medical Devices
Brazil Artificial Organs and Bionic Implants Market
Medical Devices
Global Implantable Cardiac Monitor Market
Medical Devices
Surgical Helmet Systems Market