
 Canada Spinal Surgery Devices Market | 2026-2036
Canada Spinal Surgery Devices Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Spinal Surgery Devices Market Outlook
Equipment leasing and pay-per-procedure financing is rewriting capital deployment for mid-sized surgical centers across Canada. Medtronic PLC leverages its broad fusion portfolio to sustain hospital system contracts in Ontario and Quebec. Stryker Corporation anchors its position through specialized navigation and imaging integration for complex spinal procedures. Zimmer Biomet competes aggressively on extremity-to-spine cross-selling within integrated delivery networks.
Canada spinal surgery devices encompass implantable hardware and instrumentation systems manufactured from titanium alloys, polyetheretherketone, and cobalt-chromium substrates, designed to stabilize vertebral segments, restore disc height, or decompress neural elements following trauma or degenerative pathology. Spinal fusion devices command the largest revenue share due to established reimbursement codes and surgeon familiarity, while robotic-assisted surgery technology represents the fastest-expanding segment as Canadian teaching hospitals invest in navigation platforms. Minimally invasive surgery techniques now capture growing case volumes in ambulatory settings where reduced recovery times align with provincial cost-containment objectives.
Health Canada's Medical Devices Directorate and the Canadian Standards Association ISO 13485 certification framework govern premarket approval, post-market surveillance, and quality management for implantable spinal devices, creating compliance barriers that favor established manufacturers with dedicated regulatory affairs teams. Provincial health technology assessment bodies, notably Ontario's Health Quality Ontario and British Columbia's Health Technology Review, condition hospital purchasing decisions on clinical evidence thresholds that delay adoption of novel implant materials. Stakeholders must monitor evolving province-by-province procurement centralization and the shifting balance between academic medical center innovation access and community hospital standardization mandates.
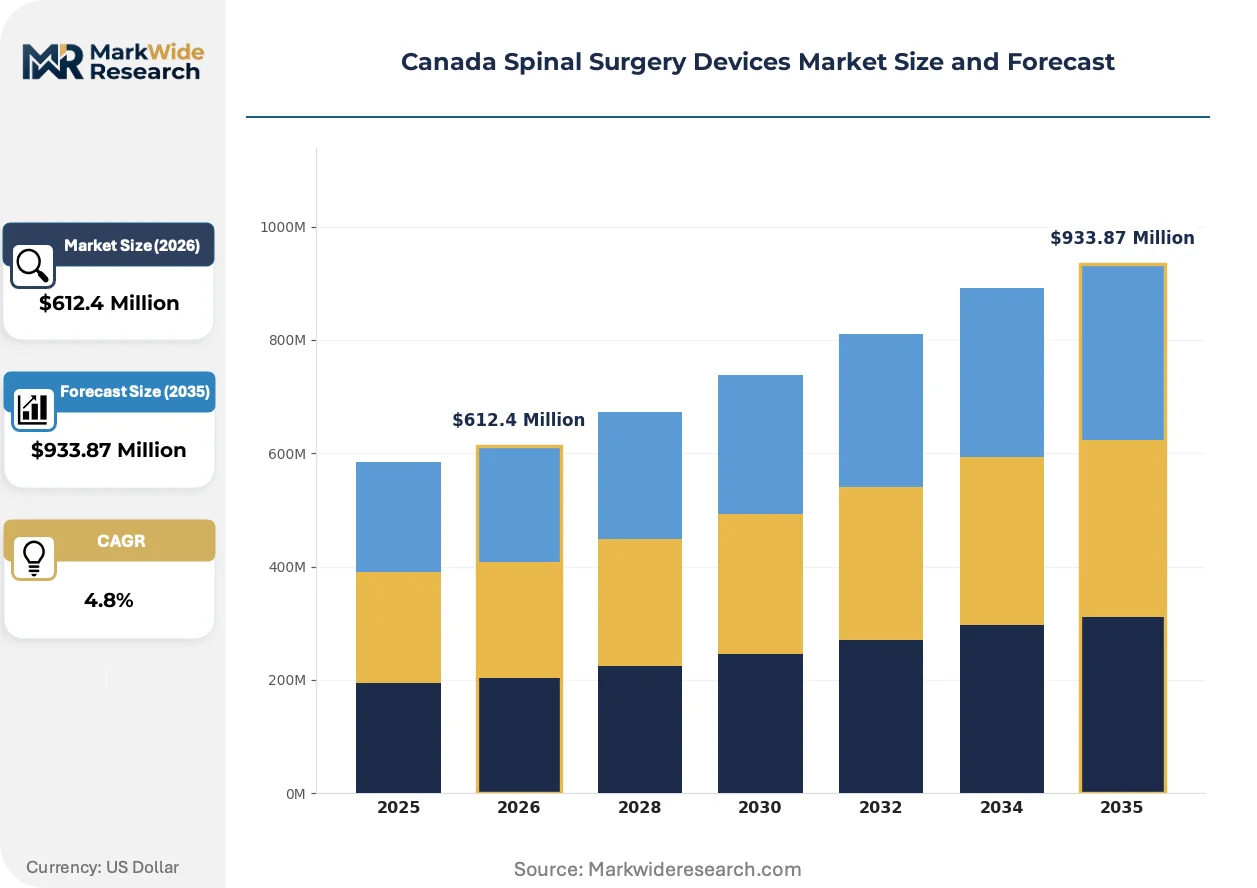
Market Dynamics
Equipment leasing and pay-per-procedure financing are rewriting capital deployment for mid-sized surgical centers across Canada, compressing upfront hardware investments into operational expenditure structures that align with provincial cost-containment mandates.
Growth Catalysts
- Ambulatory surgical center expansion:Ontario and British Columbia facilities are scaling spinal procedure volumes as provincial health authorities push same-day surgery to reduce hospital bed utilization.
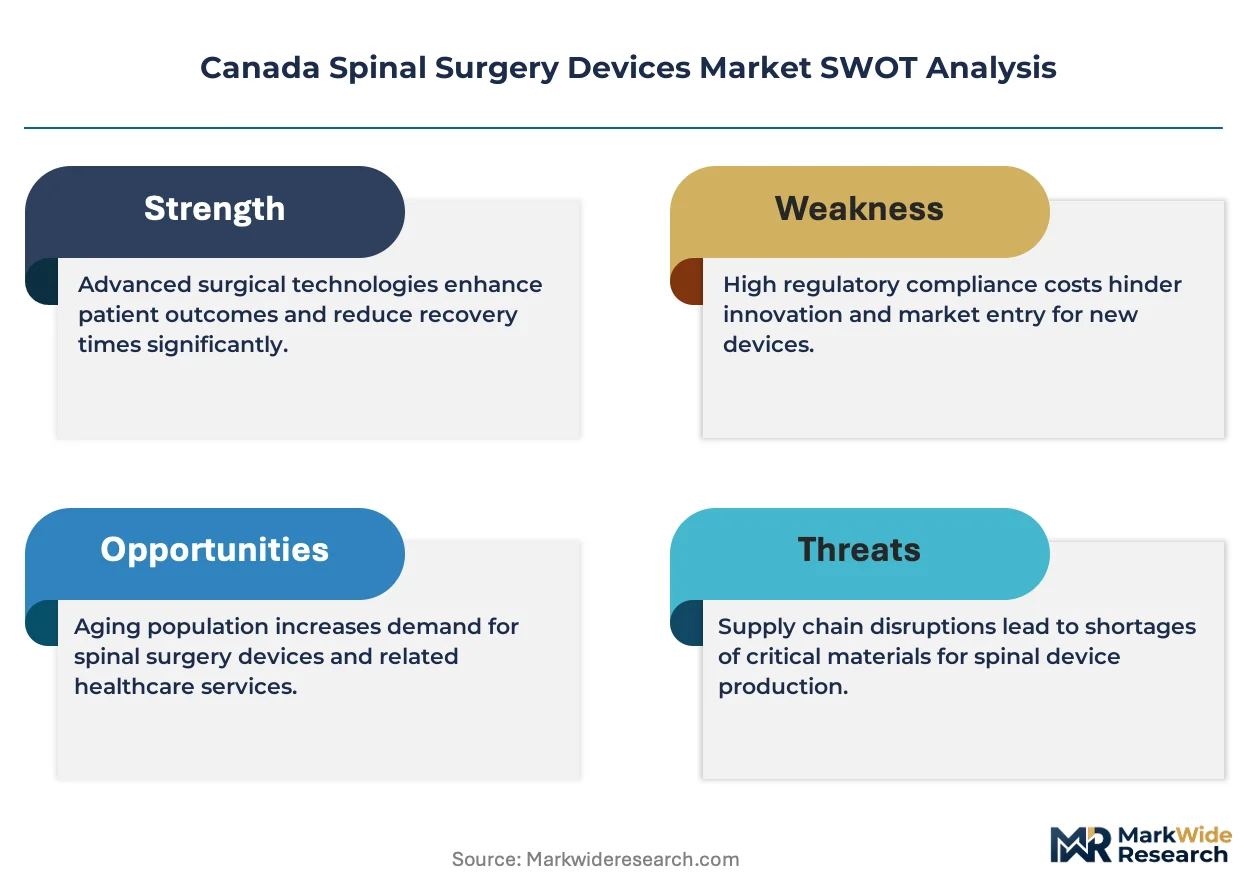
- Health Canada Class III/IV licensing:Tightening premarket validation standards for implantable devices are filtering out marginal competitors and consolidating procurement around established manufacturers with dedicated regulatory affairs infrastructure.
- Robotic navigation platforms:Canadian teaching hospitals in Toronto, Vancouver, and Montreal are investing in navigation systems that enable complex deformity corrections with reduced revision rates.
Market Restraints
- Titanium alloy input volatility:Raw material price fluctuations for implant-grade titanium alloys compress margins on fusion hardware and constrain pricing flexibility for mid-tier device suppliers.
- Health technology assessment delays:Ontario's Health Quality Ontario and British Columbia's Health Technology Review impose clinical evidence thresholds that slow adoption timelines for novel polyetheretherketone cage designs.
- Reimbursement code rigidity:Established procedural codes favor traditional open fusion techniques over minimally invasive alternatives, creating billing friction for ambulatory settings.
Strategic Opportunities
- Atlantic Canada penetration gap:Nova Scotia and New Brunswick hospital networks remain underpenetrated for advanced navigation systems, offering first-mover positioning for integrated platform vendors.
- Provincial procurement centralization:Consolidated purchasing frameworks in Quebec and Alberta create volume aggregation opportunities for manufacturers capable of meeting standardized implant specifications.
- Cross-selling from extremity reconstruction:Integrated delivery networks in Ontario are receptive to bundled orthopedic contracts spanning joint replacement and spinal stabilization hardware.
Industry Challenges
- Surgeon training pipeline constraints:Fellowship programs in complex deformity surgery produce insufficient specialists to support projected case volume growth in prairie provinces.
- ISO 13485 certification timelines:Quality management system audits for new manufacturing facilities routinely extend 18-24 months, delaying market entry for emerging implant suppliers.
- Legacy hospital information system integration:Navigation platform vendors face technical friction connecting robotic systems to entrenched electronic health record architectures in Montreal and Calgary academic centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Spinal Surgery Devices Market |
| Market Size in 2026 | $612.4 Million |
| Market Size in 2035 | $933.87 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spinal Fusion Devices, Spinal Implants, Interbody Spacers, Fixation Devices End User: Hospitals, Clinics, Ambulatory Surgical Centers, Outpatient Facilities Technology: Minimally Invasive Surgery, Robotic-Assisted Surgery, Traditional Surgery, Imaging Techniques Application: Degenerative Disc Disease, Scoliosis, Spinal Stenosis, Trauma |
| Companies Covered | Medtronic PLC, Stryker Corporation, Zimmer Biomet, Johnson & Johnson, Globus Medical, NuVasive Inc., SeaSpine Holdings Corporation, Orthofix Holdings Inc., Alphatec Spine, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Spinal Surgery Devices Market Strategic Shifts
Three intersecting developments are compressing traditional care delivery models: surgical robotics are collapsing procedure complexity thresholds, provincial regulators are tightening evidence requirements for implant approval, and purchasing consolidation is shifting bargaining power toward centralized procurement bodies.
Minimally invasive tubular retractor systems are collapsing the boundary between inpatient and ambulatory spinal fusion. Ontario community hospitals and British Columbia surgical centers are adopting these platforms at accelerating pace to capture provincial incentives for reduced length-of-stay metrics. The structural consequence is a compression of traditional open fusion volumes into lower-acuity settings that bypass academic medical center queues.
Health Canada's Medical Devices Directorate is intensifying post-market surveillance obligations for Class III spinal implants, mandating real-world evidence collection that extends beyond premarket clinical trials. Device manufacturers must now maintain active registries tracking long-term fusion outcomes, imposing data infrastructure costs that favor larger competitors with existing surveillance systems. Small and mid-cap implant suppliers face particular pressure in Quebec and Alberta markets where hospital purchasing committees prioritize vendors with demonstrated post-market surveillance capabilities.
Same-day discharge protocols are displacing traditional multi-night hospital stays for lumbar decompression and single-level fusion procedures. Ambulatory surgical centers in Toronto and Vancouver are capturing these cases from academic hospitals, with provincial funding models now reimbursing facility fees for 23-hour observation units. British Columbia's health authority has been most aggressive in redirecting elective spinal volumes to non-hospital settings, creating channel fragmentation that challenges traditional distributor relationships.
Canada Spinal Surgery Devices Market Segmentation
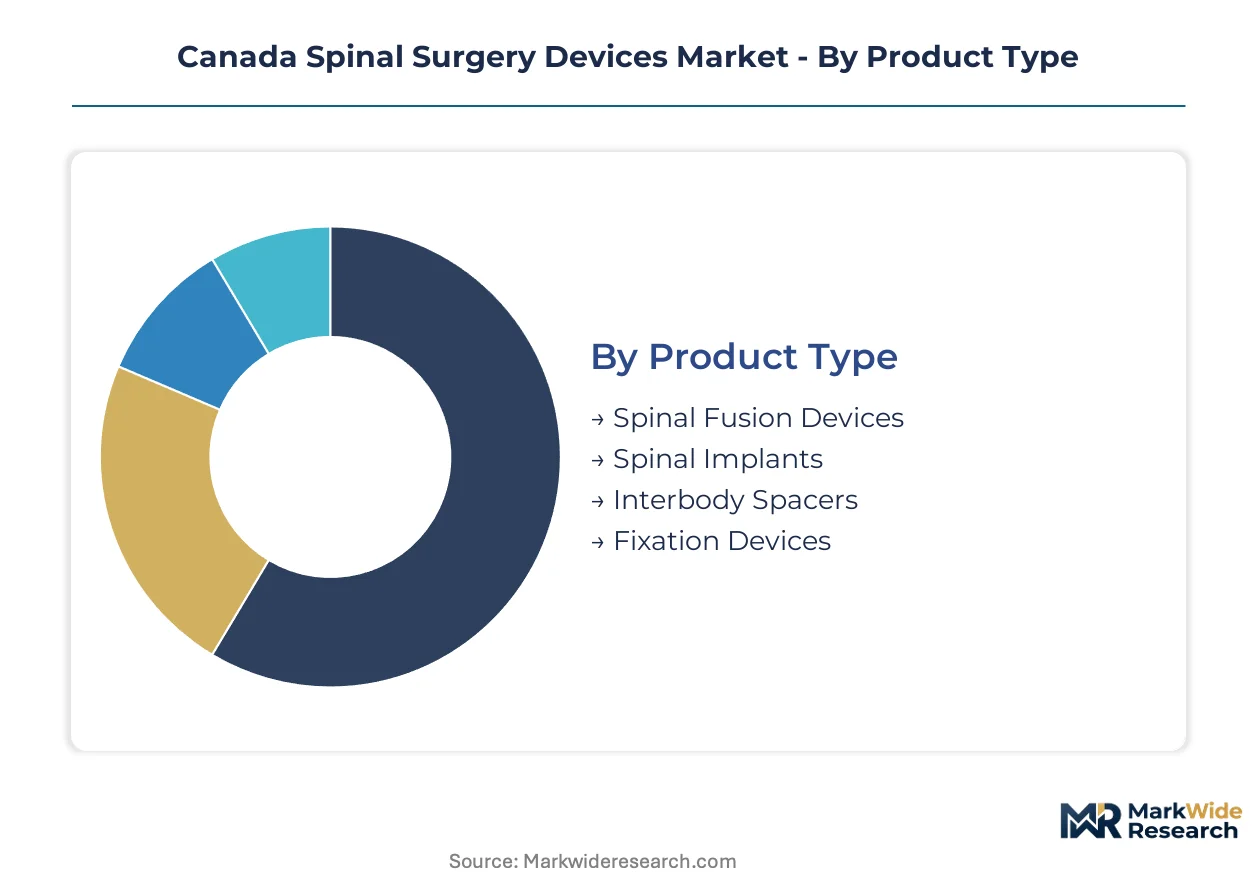
Segmentation in the Canada spinal surgery devices market reveals how procurement centralization, reimbursement pathways, and clinical evidence requirements reshape competitive positioning across product categories and care settings. Understanding these divisions exposes where Health Canada's regulatory intensity and provincial purchasing consolidation create divergent margin structures.
Product Type:
After-sales service intensity varies sharply across hardware categories, with navigation-integrated systems demanding dedicated field engineering support while commoditized implants rely on distributor logistics networks.
- Spinal Fusion Devices:Titanium alloy and polyetheretherketone constructs stabilize vertebral segments through pedicle screw-rod systems and interbody cages. Demand concentrates in Ontario's academic hospital networks where bundled procedural reimbursement incentivizes high-volume fusion programs.
- Spinal Implants:Artificial discs and dynamic stabilization systems manufactured from cobalt-chromium and ultra-high molecular weight polyethylene substrates. British Columbia's Health Technology Review applies stringent evidence thresholds that delay provincial formulary inclusion for motion-preserving alternatives.
- Interbody Spacers:PEEK and titanium mesh cages restore disc height in anterior and lateral approaches.
- Fixation Devices:Hook, wire, and screw systems for posterior spinal stabilization.
By volume, Spinal Fusion Devices leads. By growth pace, Spinal Implants is ahead.
End User:
Capital deployment models diverge across facility types, with hospitals absorbing upfront robotic platform costs while ambulatory centers favor leasing arrangements that convert hardware investments to per-procedure operational expenditures.
- Hospitals:Academic medical centers in Toronto, Vancouver, and Montreal maintain complex deformity referral networks and teaching mandates. These institutions anchor demand for navigation-integrated systems despite extended procurement cycles through centralized provincial purchasing bodies.
- Ambulatory Surgical Centers:Ontario and British Columbia facilities are scaling lumbar decompression and single-level fusion volumes as provincial authorities redirect elective cases from inpatient beds. Same-day discharge protocols compress revenue per case but accelerate capital turnover.
- Clinics:Private diagnostic and pain management facilities referring surgical candidates.
- Outpatient Facilities:Hospital-affiliated 23-hour observation units capturing redirected surgical volumes.
Hospitals dominate absolute procedure counts. Ambulatory Surgical Centers expand most quickly.
Technology:
Technology adoption curves reflect provincial reimbursement flexibility, with robotic platforms penetrating teaching hospitals faster than community settings where capital constraints favor proven minimally invasive techniques.
- Minimally Invasive Surgery:Tubular retractor and percutaneous screw systems enable reduced tissue disruption and accelerated discharge. Ontario community hospitals adopt these platforms aggressively to capture provincial length-of-stay incentives.
- Robotic-Assisted Surgery:Navigation platforms with preoperative planning and intraoperative guidance capabilities. Montreal and Calgary academic centers invest despite integration friction with legacy electronic health record architectures.
- Traditional Surgery:Open posterior approaches with direct visualization.
- Imaging Techniques:Intraoperative CT and fluoroscopy systems for real-time guidance.
Traditional Surgery retains the largest case volume. Robotic-Assisted Surgery climbs the fastest.
Application:
Procedure volume distribution tracks demographic aging patterns, with degenerative conditions dominating case pipelines while trauma and deformity cases concentrate in specialized academic referral networks.
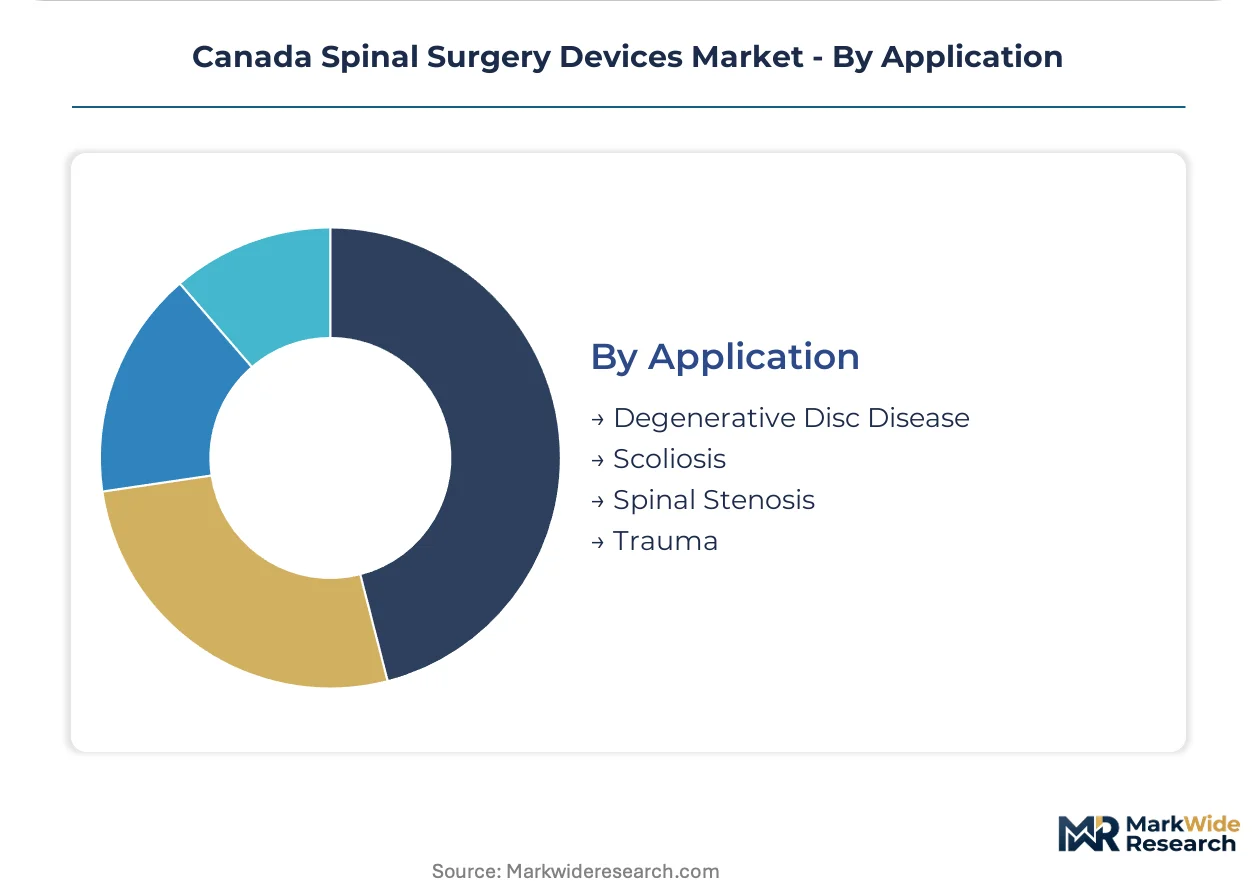
- Degenerative Disc Disease:Lumbar and cervical disc pathology requiring decompression, fusion, or arthroplasty. Demand concentrates across major urban hospital networks in Toronto, Vancouver, and Montreal where aging populations and surgical referral density align.
- Spinal Stenosis:Central and foraminal narrowing requiring laminectomy or interspinous process decompression. British Columbia's surgical centers capture growing volumes through same-day discharge protocols that align with provincial cost-containment objectives.
- Scoliosis:Adolescent and adult deformity correction procedures.
- Trauma:Fracture stabilization and spinal cord injury interventions.
Degenerative Disc Disease leads by procedure volume. Spinal Stenosis gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Canada's spinal surgery devices market depends heavily on imported implant systems and capital equipment, with domestic manufacturing concentrated in precision machining and regulatory consulting services rather than finished device production. Provincial procurement frameworks shape regional demand patterns.
Ontario
Toronto's academic hospital networks anchor complex deformity and fusion procedure volumes, with University Health Network and Sunnybrook Health Sciences Centre driving adoption of navigation-integrated platforms. Health Quality Ontario's health technology assessment protocols filter novel implant materials before provincial formulary inclusion. The Greater Toronto Area concentrates distributor logistics and surgeon training infrastructure for central Canadian markets.
Quebec
Montreal's McGill University Health Centre and CHUM sustain high-volume spinal programs with strong ties to French-language medical education networks. The province's centralized procurement through the Ministère de la Santé et des Services sociaux aggregates hospital purchasing power, favoring vendors with established regulatory affairs teams. Quebec's implant demand skews toward traditional fusion hardware over motion-preserving alternatives.
British Columbia
Vancouver Coastal Health and Fraser Health redirect elective spinal cases to ambulatory surgical centers under aggressive same-day discharge protocols. British Columbia's Health Technology Review imposes stringent evidence thresholds for novel cage designs and biologics. The Lower Mainland captures western Canadian referral volumes while Victoria's Island Health experiments with remote surgical planning for rural access.
Alberta
Calgary's Foothills Medical Centre and Edmonton's University of Alberta Hospital anchor prairie province complex spine care, with provincial procurement consolidation through Alberta Health Services creating volume aggregation opportunities. The province's oil-sector economic cycles periodically compress capital equipment budgets for robotic platform acquisition. Southern Alberta community hospitals lag in minimally invasive adoption compared to Calgary's academic centers.
Atlantic Canada
Nova Scotia's QEII Health Sciences Centre and New Brunswick's Horizon Health Network remain underpenetrated for advanced navigation systems, with surgical volumes insufficient to justify capital investment in robotic platforms. Provincial health authorities prioritize patient travel to Ontario and Quebec for complex deformity cases rather than local capacity building. Halifax anchors regional distribution while St. John's and Moncton serve secondary referral catchments.
Canada Spinal Surgery Devices Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream in the supply chain supplying precision-machined titanium and PEEK substrates to finished device assemblers. The Canadian market exhibits tiered concentration with multinational manufacturers holding hospital system contracts and mid-tier suppliers competing on price for ambulatory center volumes. Three archetypes dominate: diversified orthopedic conglomerates with cross-selling capabilities, spine-focused pure-plays with specialized navigation portfolios, and regional distributors with provincial procurement relationships. Competitive dynamics center on regulatory approval speed and Health Canada licensing maintenance rather than manufacturing scale.
Among North American-based platform vendors, Medtronic PLC, Stryker Corporation, and Zimmer Biomet occupy positions reflecting distinct strategic postures. Medtronic represents the diversified conglomerate archetype with breadth across fusion and non-fusion categories. Stryker exemplifies the navigation-integrated systems specialist with emphasis on intraoperative imaging compatibility. Zimmer Biomet sits within the cross-selling tier, leveraging extremity reconstruction relationships to access spinal procurement committees. These three anchors illustrate how scale, specialization, and portfolio breadth create distinct competitive positions within Health Canada's regulatory framework.
| Leading Market Players |
|---|
| Medtronic PLC |
| Stryker Corporation |
| Zimmer Biomet |
| Johnson & Johnson |
| Globus Medical |
| NuVasive Inc. |
| SeaSpine Holdings Corporation |
| Orthofix Holdings Inc. |
| Alphatec Spine |
| Others |
Value Chain & Pricing Dynamics
The Trans-Canada Highway freight corridor channels implant-grade titanium alloys and polyetheretherketone substrates from Vancouver port terminals to Ontario manufacturing hubs, with transport cost volatility amplifying margin compression for mid-tier suppliers while enabling price stratification between academic medical centers and ambulatory surgical centers.
Pricing Analysis
Hospital system procurement committees anchor pricing structures through multi-year bundled contracts for fusion hardware, with Health Canada Class III licensing tier and ISO 13485 certification grade driving premium-mid-economy pricing differentiation. Cost compression in standard-tier pedicle screw systems intensifies as provincial centralization aggregates purchasing volume, while ambulatory centers exhibit highest price sensitivity due to per-procedure leasing models.
Supply Chain Analysis
Health Canada's Medical Devices Directorate import restrictions on unapproved implant substrates limit raw material flows from non-certified suppliers, with supply concentration drawing from USA, Switzerland, and Ireland for precision-machined titanium components. Single-source vulnerability runs through PEEK resin suppliers serving cage manufacturers, while distribution feeds from multinational logistics hubs in Toronto and Montreal to hospital networks and surgical centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Canada's spinal surgery devices market sits in early-cycle expansion as ambulatory surgical center penetration accelerates procedure volume growth beyond traditional hospital settings.
For Market Incumbents: Build regulatory moats through expanded Health Canada post-market surveillance registry investments that smaller competitors cannot replicate. Deepen backward integration into titanium alloy sourcing to offset raw material volatility threatening fusion hardware margins. Anchor hospital system contracts in Ontario and Quebec through bundled navigation platform offerings that lock out standalone implant vendors. For New Entrants and Emerging Players: Build out Atlantic Canada distribution relationships with Nova Scotia and New Brunswick hospital networks where advanced navigation systems remain underpenetrated. Target minimally invasive tubular retractor platforms for community hospital adoption in Alberta and Manitoba, leveraging pay-per-procedure financing to bypass capital budget constraints. Pursue surgeon training partnerships with McGill and University of Toronto fellowship programs as credentialing pathway. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified orthopedic conglomerates seeking to divest non-core spine portfolios amid reimbursement code rigidity pressures. Long-term viability hinges on navigation-integrated platform capabilities rather than commodity implant manufacturing. Watch Health Canada Class IV licensing backlog clearance rates as inflection signal for regulatory capacity constraints easing market entry.| Strategic Initiative | Industry Significance |
|---|---|
| Health Canada Class III/IV Licensing Investment | Accelerated premarket approval timelines capture provincial procurement windows before competitors. |
| Surgeon Training Fellowship Partnerships | McGill and University of Toronto programs create locked-in referral networks for complex deformity cases. |
| Navigation Platform Integration | Robotic system compatibility with legacy electronic health records in Montreal and Calgary academic centers reduces sales friction. |
| Provincial GPO Contract Aggregation | Alberta Health Services and Ontario Health centralized purchasing creates volume commitments that marginalize mid-tier suppliers. |
| Ambulatory Center Leasing Model Deployment | Pay-per-procedure financing converts capital expenditure barriers into operational expenditure alignment with provincial cost-containment mandates. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of hospital procurement databases, GPO contract filings, Health Canada Medical Devices Active Licence Listing, and provincial health technology assessment publications. Interviews with spinal surgeons, biomedical engineers, hospital purchasing committee members, and distributor logistics managers informed demand-side validation. Bottom-up procedure volume estimates triangulated against top-down provincial healthcare expenditure allocations.
Forecast inputs incorporate product type segmentation across fusion devices, implants, and navigation platforms; end-user splits between hospitals and ambulatory surgical centers; technology adoption curves for minimally invasive and robotic-assisted approaches; and application demand across degenerative disc disease and spinal stenosis procedures. CAGRs derived from fitted growth curves accounting for demographic aging trajectories and provincial same-day surgery policy shifts.
Practitioners should monitor Health Canada licensing queue lengths and provincial procurement centralization timelines for early signals of competitive access shifts. Forecasts reflect assumptions regarding regulatory approval continuity and reimbursement code stability. Material shifts in titanium alloy trade flows or Health Canada post-market surveillance mandate intensity would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
South America C-Arms Market
Medical Devices
Modular Anatomic Reconstruction Market
Medical Devices
Ehealth Devices Market
Medical Devices
Japan Medical Device Regulatory Affairs Market
Medical Devices
Flow Diverters Market
Medical Devices
Digital Vision Lenses Market
Medical Devices
Contraceptive Devices Market
Medical Devices
Organoids Kits Market
Medical Devices
Global Hernia Repair Devices and Consumables Market
Medical Devices
Australia Respiratory Devices Market
Medical Devices
Global Vein Illuminator Market
Medical Devices
Portable Medical Electronic Products Market
Medical Devices
Capnography Devices Market
Medical Devices
Global Robotic Assisted Surgery Systems Market
Medical Devices
Medical Devices Vigilance Market
Medical Devices
3D Printing Medical Devices Market