
 Rapid Coagulation Testing Market | 2026-2036
Rapid Coagulation Testing Market Size, Share, and Industry Trends Forecast 2026-2036
Rapid Coagulation Testing Market Analytics
Cartridge-based reagent formats are shifting toward dry-chemistry architectures that eliminate cold-chain requirements and extend shelf life in distributed care settings. Abbott leverages its vertically integrated diagnostics pipeline to sustain cost advantages in high-throughput hospital laboratories. Sysmex Corporation anchors its position through specialized coagulation analyzer lines that dominate reference laboratory workflows in East Asia. Werfen differentiates via channel control over hemostasis testing consumables in European cardiac surgery centers.
Rapid coagulation testing encompasses diagnostic systems that measure clotting parameters—prothrombin time, activated partial thromboplastin time, international normalized ratio—within minutes using whole blood samples, typically through electrochemical or optical detection methods with sample volumes under 50 microliters. These devices serve primarily to guide anticoagulant therapy dosing, screen preoperative bleeding risk, and monitor trauma-related coagulopathy in time-critical clinical environments. Point-of-care devices capture the dominant margin pool due to premium pricing tied to waived-complexity certification under CLIA regulations, while microfluidic technology represents the fastest-expanding segment as manufacturers miniaturize multi-parameter panels onto disposable chips. Portable analyzers occupy a maturing niche in ambulance and military field settings where battery-operated operation and ruggedized housings determine procurement decisions.
FDA 510(k) premarket notification and CLIA waiver status shape competitive access in the United States, while the EU In Vitro Diagnostic Regulation enforces stricter clinical evidence requirements for coagulation self-testing devices entering European markets. ISO 15189 accreditation standards for diagnostic laboratories in multiple jurisdictions are elevating quality-system expectations that filter down to device validation protocols. Stakeholders must monitor evolving reimbursement thresholds for home-based international normalized ratio monitoring as payors recalibrate coverage between laboratory and decentralized testing modalities.
Market Dynamics
Bedside coagulation monitoring is compressing clinical decision cycles from hours to minutes, restructuring procurement priorities around waived-complexity certification and disposable cartridge economics rather than capital equipment depreciation.
Growth Catalysts
- Medicare reimbursement codes:Sustainable volume incentives in the United States reward point-of-care international normalized ratio testing, anchoring hospital emergency department adoption curves.
- Dry-chemistry architectures:Elimination of cold-chain requirements extends shelf life in distributed care settings, enabling deployment to rural clinics and military field stations.
- Anticoagulant therapy expansion:Direct oral anticoagulant prescribing growth generates parallel demand for rapid thrombin time and anti-factor Xa monitoring across cardiology and stroke units.
Market Restraints
- Reagent cost concentration:Proprietary cartridge formats lock users into single-source consumable contracts, inflating lifetime cost of ownership versus open-system laboratory analyzers.
- Clinical validation burden:FDA 510(k) pathway requires predicate device equivalence studies that compress design freedom for novel detection chemistries.
- Operator competency variance:Waived-status devices still produce erroneous results when whole blood sampling technique varies, limiting reliability in understaffed overnight shifts.
Strategic Opportunities
- Home-based international normalized ratio monitoring:Underpenetrated patient self-testing in the United States faces reimbursement recalibration that could unlock chronic warfarin management volumes.
- Microfluidic multi-parameter convergence:Integration of prothrombin time, activated partial thromboplastin time, and fibrinogen onto single disposable chips reduces sample volume requirements below 20 microliters.
- EU In Vitro Diagnostic Regulation transition:Stricter clinical evidence requirements for coagulation self-testing devices create first-mover advantage for manufacturers with pre-submitted technical documentation.
Industry Challenges
- CLIA waiver compliance timeline:FDA categorization studies for moderate-complexity reduction demand 12-18 month validation cycles that delay product launches.
- Laboratory information system integration:Point-of-care devices require bidirectional connectivity to electronic health records that fragments across Epic, Cerner, and Meditech installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rapid Coagulation Testing Market |
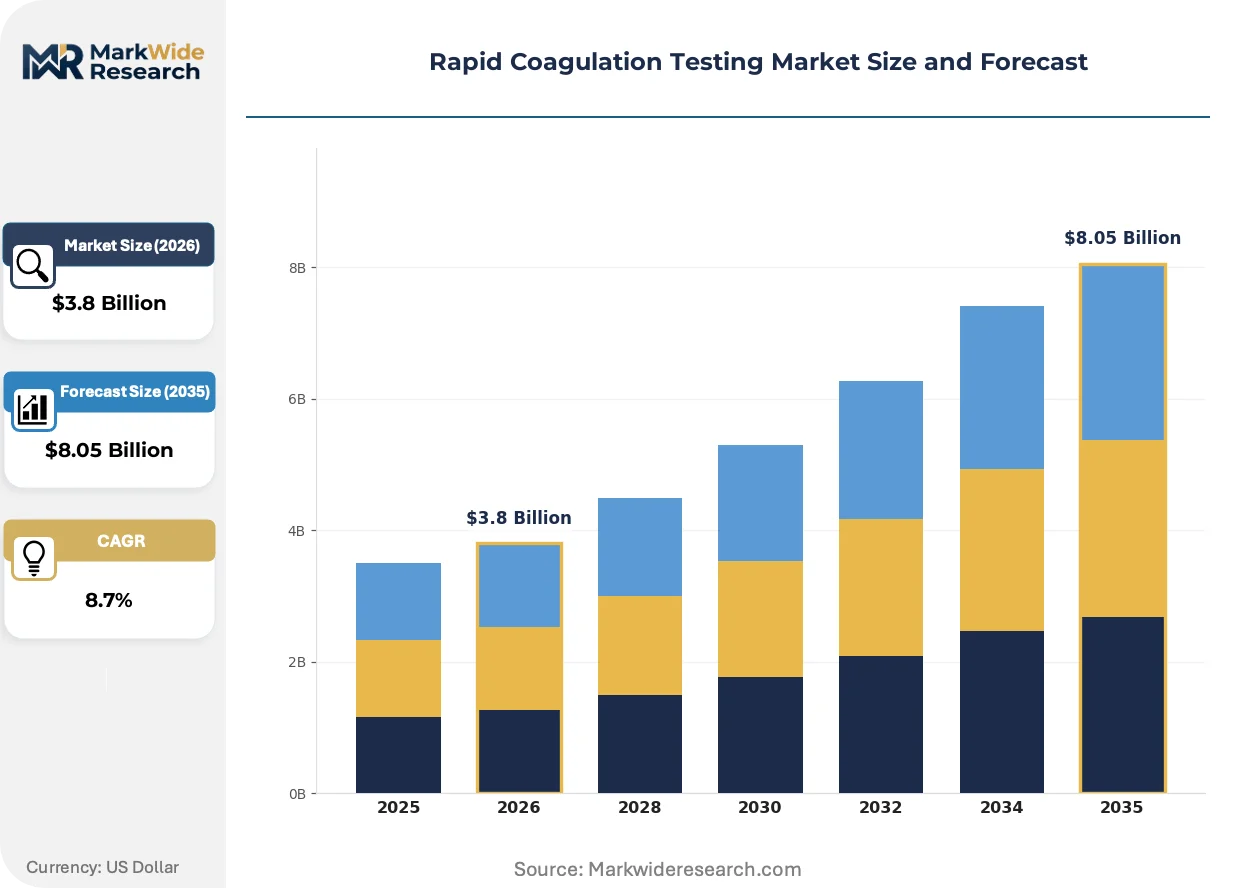
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Point-of-Care Devices, Laboratory Instruments, Portable Analyzers, Home Testing Kits Technology: Electrochemical, Optical, Mechanical, Microfluidic End User: Hospitals, Clinics, Home Care, Diagnostic Laboratories Application: Cardiology, Nephrology, Blood Transfusion, Surgery |
| Companies Covered | Abbott, F. Hoffmann-La Roche Ltd, Sysmex Corporation, Medtronic, Danaher, Thermo Fisher Scientific Inc., Helena Laboratories Corporation, Siemens Healthineers, Werfen, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rapid Coagulation Testing Market Evolving Landscape
Detection modalities are converging toward single-use electrochemical sensors that eliminate optical alignment maintenance, while regulatory frameworks on both sides of the Atlantic recalibrate evidence thresholds for decentralized testing.
Microfluidic cartridge platforms are automating sample handling, reagent metering, and waste containment within sealed disposable units. Hospital emergency departments in the United States are adopting these systems at replacement cycle compression rates of 18-24 months versus 7-year laboratory analyzer depreciation schedules. This automation is automating preanalytical error sources while collapsing the capital expenditure barrier for mid-volume sites.
The EU In Vitro Diagnostic Regulation enforces post-market surveillance and clinical performance studies for coagulation self-testing devices that exceed prior Directive 98/79/EC documentation requirements. Manufacturers must maintain periodic safety update reports and trend analysis of vigilance data. European notified bodies are extending review timelines for class C device certifications, forcing portfolio prioritization toward highest-margin configurations.
Hospital procurement committees are unbundling point-of-care coagulation testing from centralized laboratory contracts, creating standalone vendor relationships for emergency and perioperative departments. Group purchasing organizations are responding with specialty carve-outs that separate waived-device consumables from high-complexity analyzer reagent bundles. This pattern is most visible in United States health systems consolidating under regional umbrella organizations with standardized device formularies.
Rapid Coagulation Testing Market Segmentation
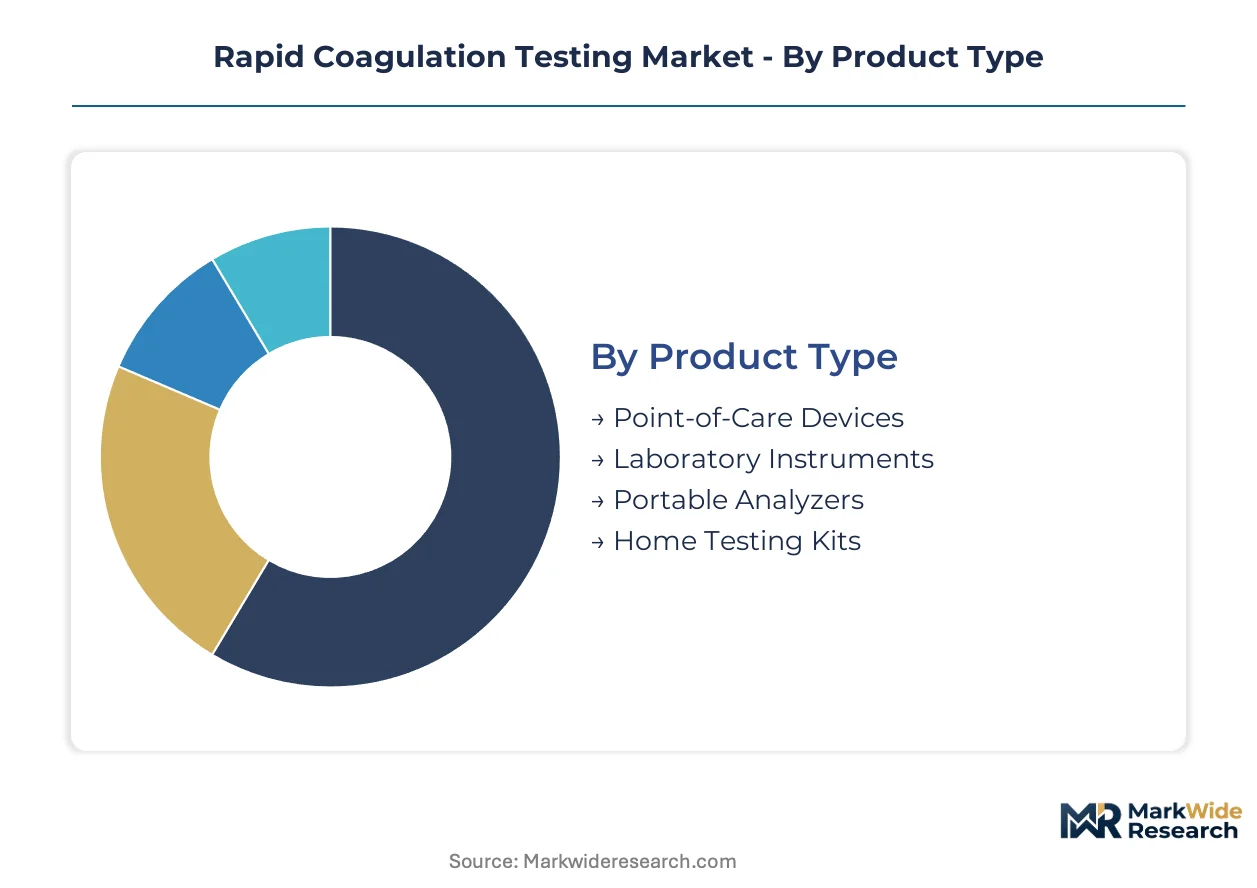
Segmentation in rapid coagulation testing reveals how regulatory pathways, reimbursement structures, and clinical workflows fragment procurement decisions across device categories. Understanding these divides exposes where margin pools concentrate and which technology transitions reshape competitive positioning.
Product Type:
FDA 510(k) clearance and CLIA waiver status create divergent commercial trajectories across product categories, with waived devices commanding premium pricing in decentralized settings while moderate-complexity systems anchor laboratory economics.
- Point-of-Care Devices:Electrochemical sensor platforms with sub-50 microliter sample requirements and waived-complexity certification dominate emergency department procurement in the United States. Medicare reimbursement codes for bedside international normalized ratio testing sustain volume incentives that compress replacement cycles to 18-24 months.
- Laboratory Instruments:High-throughput optical detection systems with multi-parameter panels serve reference laboratories requiring ISO 15189 accreditation compliance. Sysmex and Abbott anchor installed bases through reagent contract lock-in and vertically integrated consumable supply.
- Portable Analyzers:Battery-operated units with ruggedized housings address military field stations and ambulance services where cold-chain elimination determines deployment feasibility.
- Home Testing Kits:Self-monitoring devices face reimbursement recalibration pressures as payors weigh laboratory versus decentralized testing economics for chronic warfarin patients.
Point-of-Care Devices sit at the top of the volume ranking, with Home Testing Kits climbing the fastest as reimbursement frameworks evolve.
Technology:
Detection modality selection directly determines maintenance burden, sample volume minima, and the feasibility of multi-parameter integration onto single disposable platforms.
- Electrochemical:Single-use sensors eliminate optical alignment protocols and reduce calibration frequency, making them preferred for waived-status devices in understaffed overnight shifts.
- Optical:Turbidimetric and chromogenic methods dominate laboratory workflows where precision requirements exceed point-of-care tolerances.
- Mechanical:Viscoelastic testing platforms capture trauma and cardiac surgery applications requiring whole hemostasis profiling rather than isolated clotting times.
- Microfluidic:Capillary-driven flow architectures automate reagent metering and waste containment within sealed cartridges, collapsing preanalytical error rates while enabling sub-20 microliter multi-parameter panels.
Electrochemical platforms hold the broadest installed base, though Microfluidic systems gain share fastest through replacement of legacy optical systems in mid-volume hospital sites.
End User:
Procurement authority fragmentation across clinical departments creates divergent vendor relationships, with emergency and perioperative units increasingly unbundling from centralized laboratory contracts.
- Hospitals:Emergency departments drive point-of-care adoption to reduce turnaround times for trauma and stroke protocols, while perioperative units demand viscoelastic monitoring for bleeding risk assessment.
- Clinics:Rural and community sites prioritize dry-chemistry formats that eliminate cold-chain logistics and extend shelf life in distributed care settings.
- Home Care:Patient self-testing for international normalized ratio monitoring remains underpenetrated in the United States pending reimbursement clarity from Medicare and commercial payors.
- Diagnostic Laboratories:Reference sites in East Asia and Europe maintain specialized coagulation analyzer lines requiring ISO 15189 quality system validation and bidirectional laboratory information system connectivity.
Hospitals command the largest revenue pool, with Home Care expanding most quickly contingent on chronic disease management policy shifts.
Application:
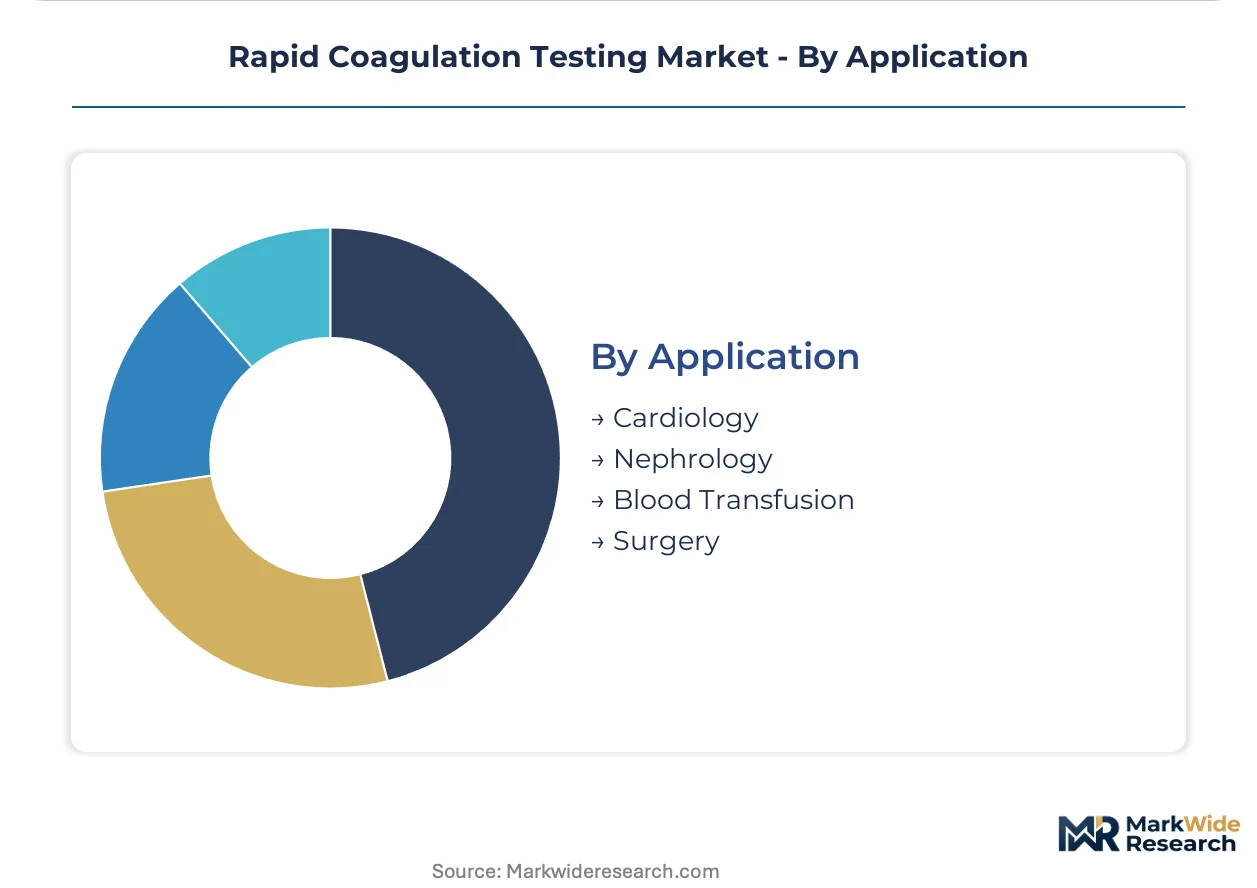
Clinical indication determines which parameter panels matter, with cardiology and surgery applications driving premium pricing for multi-test cartridges while nephrology emphasizes dialysis-related monitoring.
- Cardiology:Direct oral anticoagulant expansion generates demand for rapid thrombin time and anti-factor Xa assays alongside traditional prothrombin time monitoring in atrial fibrillation and stroke units.
- Nephrology:Dialysis centers require frequent heparin monitoring and access-related coagulopathy screening, favoring point-of-care devices with short turnaround times.
- Blood Transfusion:Massive transfusion protocols in trauma centers depend on viscoelastic or rapid point-of-care assessment to guide component therapy ratios.
- Surgery:Cardiac and orthopedic procedures drive preoperative bleeding risk screening and postoperative anticoagulation resumption decisions, with European cardiac surgery centers representing concentrated demand for specialized hemostasis testing.
Cardiology generates the highest test volume, with Surgery showing the steepest expansion trajectory as enhanced recovery protocols compress perioperative decision windows.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hospital emergency departments in the United States anchor procurement volumes for bedside coagulation monitoring, while reimbursement frameworks in Germany and Japan shape adoption curves across developed markets. Regulatory pathways in China and India determine market entry sequencing for cartridge-based platforms.
United States
Medicare reimbursement codes for point-of-care international normalized ratio testing sustain volume incentives in hospital emergency departments. FDA 510(k) clearance pathways and CLIA waiver status compress time-to-market for waived-complexity devices. The Boston-Cambridge corridor concentrates device development activity for electrochemical sensor platforms.
Germany
Reference laboratory workflows in cardiac surgery centers drive demand for specialized hemostasis testing consumables. The EU In Vitro Diagnostic Regulation enforces stricter clinical evidence requirements for coagulation self-testing devices entering European markets. The Rhine-Ruhr metropolitan region anchors centralized laboratory infrastructure serving Western European networks.
Japan
Specialized coagulation analyzer lines dominate reference laboratory workflows across East Asian markets. PMDA regulatory frameworks align with international standards while maintaining distinct quality system validation protocols. The Kanto region around Tokyo concentrates diagnostic equipment manufacturing and distribution networks.
China
Rapid hospital network expansion generates demand for point-of-care devices in tier-two and tier-three cities. NMPA regulatory pathways for in vitro diagnostic devices are converging toward international standards while retaining local clinical trial requirements. The Yangtze River Delta clusters domestic device assembly and reagent production capacity.
India
Rural clinic deployment priorities favor dry-chemistry formats that eliminate cold-chain logistics. CDSCO regulatory frameworks for medical devices are streamlining import and local manufacturing approvals. The Delhi-NCR corridor concentrates diagnostic distributor networks serving northern and central Indian states.
Rapid Coagulation Testing Market Competitive Landscape
Strategic partnerships dominate the current landscape as manufacturers seek to unbundle point-of-care coagulation testing from centralized laboratory contracts. The vendor base concentrates around three tiers: diversified diagnostics conglomerates with vertically integrated supply chains, specialized hemostasis testing firms with channel control in surgical centers, and emerging microfluidic platform developers. Competitive positioning hinges on CLIA waiver certification speed, reagent contract lock-in duration, and bidirectional electronic health record connectivity.
Among diversified diagnostics conglomerates, Abbott and Danaher exemplify scale-driven archetypes that leverage consumable supply control to sustain hospital laboratory relationships. Sysmex Corporation occupies a specialist position anchored in East Asian reference laboratory workflows. Werfen represents the channel-control archetype through concentrated presence in European cardiac surgery centers. These three entities illustrate how regulatory certification depth and geographic footprint concentration determine tier placement.
| Leading Market Players |
|---|
| Abbott |
| F. Hoffmann-La Roche Ltd |
| Sysmex Corporation |
| Medtronic |
| Danaher |
| Thermo Fisher Scientific Inc. |
| Helena Laboratories Corporation |
| Siemens Healthineers |
| Werfen |
| Others |
Value Network & Pricing Analysis
EU MDR clinical evidence mandates gate qualified supply access for premium-tier coagulation self-testing devices, compressing margins for manufacturers lacking pre-submitted technical documentation while elevating pricing power for waiver-certified platforms in decentralized care settings.
Pricing Analysis
Input-cost pass-through from proprietary electrochemical sensor substrates and precision-molded microfluidic cartridges sustains three-tier pricing structure across premium, standard, and economy levels. Price differentiation centers on CLIA waiver certification grade and after-sales service bundling with laboratory information system connectivity. Pricing pressure stems from group purchasing organization carve-outs that separate waived-device consumables from high-complexity analyzer reagent bundles. Hospital emergency departments exhibit lowest price sensitivity due to Medicare reimbursement code anchoring, while rural clinics face acute cost compression.
Supply Chain Analysis
Workforce availability constraints in precision polymer manufacturing constrain cartridge production scaling in the United States, Germany, and Japan. Raw material dependencies center on medical-grade polycarbonate substrates, dry-chemistry reagent chemistries, and electrochemical sensor membranes. Supply chain risk concentrates in single-source vulnerability for CLIA-waived device predicate equivalence studies that delay competitive entry. Distribution runs through specialized diagnostics distributors serving hospital systems and group purchasing organization networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The rapid coagulation testing market functions as a stable compounder where chronic anticoagulant therapy expansion generates recurring consumable demand with limited substitution risk from alternative monitoring modalities.
For Market Incumbents: Anchor market position through backward integration into dry-chemistry reagent manufacturing and captive supply of electrochemical sensor substrates. Defend against microfluidic platform displacement by accelerating FDA 510(k) predicate expansion for multi-parameter cartridge configurations. Prioritize certification investment in EU MDR technical documentation to sustain European cardiac surgery center access. For New Entrants and Emerging Players: Direct-to-clinic digital distribution routes bypass incumbent distributor lock-in and accelerate rural clinic penetration. Target home-based international normalized ratio monitoring as the most penetrable white space contingent on Medicare reimbursement recalibration. Pursue microfluidic multi-parameter convergence as the primary go-to-market angle for mid-volume hospital site displacement. For Investors and Strategic Acquirers: Roll-up economics work for specialized hemostasis testing firms because fragmented European cardiac surgery center channel control permits sequential consolidation with minimal customer overlap. Long-term viability rests on consumable contract duration rather than capital equipment placement. Monitor FDA CLIA waiver categorization study backlogs as the critical inflection signal for competitive entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| FDA 510(k) Submission Acceleration | Compresses time-to-market for waived-complexity devices against predicate equivalence requirements. |
| EU MDR Technical Documentation Pre-Submission | Secures first-mover advantage for coagulation self-testing devices amid notified body review delays. |
| Hospital System Partnership | Unbundles point-of-care procurement from centralized laboratory contracts through standalone vendor relationships. |
| Software Companion Development | Enables bidirectional electronic health record connectivity across Epic, Cerner, and Meditech installations. |
| Reimbursement Strategy | Aligns device formularies with Medicare code sustainability for chronic warfarin patient volumes. |
Research Methodology
Direct dialogue with hospital purchasing committee members, biomedical engineers, GPO contracts managers, and point-of-care coordinators grounded qualitative findings in procurement workflow realities. Secondary validation drew from FDA 510(k) premarket notification databases, CMS Medicare reimbursement code filings, hospital procurement contract registries, and EU MDR notified body certification records. Bottom-up and top-down triangulation reconciled device placement estimates with consumable volume projections across the analysis window.
Segment-level outputs reflect modeled trajectories for point-of-care devices, laboratory instruments, portable analyzers, and home testing kits by detection modality, end-user setting, and clinical application. CAGRs were derived from regression-weighted historical placement rates and projected replacement cycle compression in emergency departments. Forecast inputs incorporated anticoagulant therapy prescribing trends, CLIA waiver certification timelines, and reimbursement policy sensitivity scenarios.
The model assumes a particular technology adoption path; alternative pathways for microfluidic multi-parameter convergence would alter the outlook if sample volume minima fail to reach sub-20 microliter thresholds. Practitioners should monitor FDA moderate-complexity categorization study timelines and Medicare home testing reimbursement determinations for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Testing Services
Global Virology Testing Market
Testing Services
Irradiation Sterilization Services Market
Testing Services
Target-Based ADME/ Tox Assay Market
Testing Services
Pancreatic Elastase Testing Market
Testing Services
Aerospace and Life Science Testing Certification Market
Testing Services
Global Metabolic Testing Market
Testing Services
Global Nitric Oxide Test Market
Testing Services
Global Rapid Test Market
Testing Services
Global Sterility Testing Market
Testing Services
Alcohol Breathalyzer and Drug Testing Equipment Market
Testing Services
Global Biologics Safety Testing Market
Testing Services
Antibiotic Susceptibility Testing Market
Testing Services
Vials Leak Testing Market
Testing Services
Global Coagulation Testing Market
Testing Services
Influenza Home Testing Market
Testing Services
Blood Borne Testing Market