
 Global Breast Surgery Retractors Market | 2026-2036
Global Breast Surgery Retractors Market Size, Share, and Industry Trends Forecast 2026-2036
Global Breast Surgery Retractors Market Foresight
The EU Medical Device Regulation is shifting the cost-of-entry calculus for reusable breast surgery retractors by mandating enhanced clinical evidence and post-market surveillance. CooperSurgical, Inc. leverages its deep obstetric-gynecologic channel relationships to cross-sell retractor lines into breast procedures. Medtronic plc anchors its position through integrated surgical ecosystems that bundle retractors with energy and visualization platforms. Integra LifeSciences Corporation differentiates via specialization in precision-crafted titanium instruments for reconstructive microsurgery.
Breast surgery retractors are mechanical instruments designed to hold back tissue, ribs, or skin edges to expose the operative field during mastectomy, lumpectomy, or reconstruction; they typically feature ratcheted self-locking mechanisms or adjustable frame assemblies and must withstand repeated autoclave cycles without fatigue deformation. Stainless steel handheld retractors still occupy the largest volume share due to their cost efficiency and universal compatibility with existing sterilization infrastructure. Self-retaining systems are recording the fastest expansion as ambulatory surgical centers prioritize reduced staffing overhead and faster turnover between cases. Reconstructive procedures represent the most concentrated margin pool because these longer, more complex surgeries command premium instrument specifications and disposable adjunct sales.
The FDA enforces 510(k) premarket notification requirements for reusable surgical retractors, while the EU MDR imposes stricter biocompatibility and traceability standards through notified body oversight; Japan's PMDA maintains distinct quality management system certifications that delay but do not block market entry for foreign manufacturers. ISO 13485 compliance has become a non-negotiable procurement filter for hospital systems consolidating vendor lists. Stakeholders must monitor how FDA guidance on reprocessing validation evolves, as this will determine whether single-use alternatives gain accelerated traction against traditional reusable portfolios.
Market Dynamics
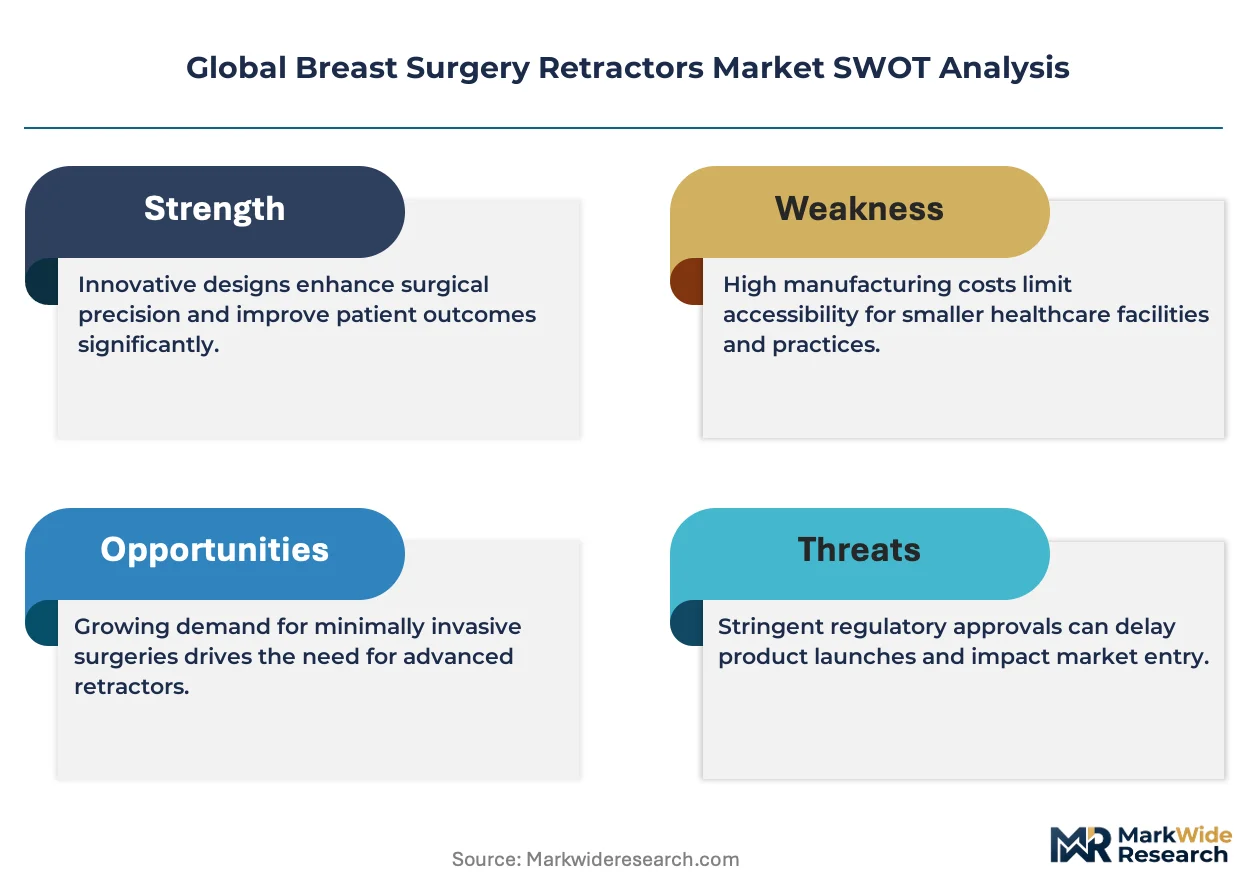
The EU MDR's elevated clinical evidence requirements are compressing vendor margins for reusable retractor portfolios while accelerating hospital consolidation of sterilization infrastructure. This regulatory pressure is forcing manufacturers to choose between absorbing compliance costs or exiting the European market entirely.
Growth Catalysts
- Japan's PMDA reimbursement expansion:Breast reconstruction procedures now qualify for enhanced coverage in tertiary oncology centers, pulling instrument procurement volumes upward.
- Self-retaining titanium frame systems:Ambulatory surgical centers in Germany are adopting these for reduced staffing overhead and faster case turnover between mastectomies.
- FDA 510(k) pathway efficiency:Streamlined premarket notification for reusable retractors with predicate devices is shortening time-to-revenue for incremental design improvements.
Market Restraints
- EU MDR notified body bottlenecks:Extended conformity assessment timelines for reusable instruments are freezing new product introductions across the 27-member bloc.
- Stainless steel input volatility:Surgical-grade 316L price swings are compressing margin predictability for high-volume handheld retractor manufacturers.
- Single-use polymer substitution:Hydrophobic thermoplastic retractors are capturing share in outpatient lumpectomy settings where reprocessing infrastructure is absent.
Strategic Opportunities
- India's CDSCO fast-track pathway:Accelerated device registration for oncology-dedicated instruments is opening access to 700+ tier-2 hospital surgical units.
- Robot-assisted mastectomy convergence:Integration of self-retaining retractors with da Vinci-compatible mounting interfaces is creating premium positioning in academic medical centers.
- Direct-to-ASC distribution:Bypassing traditional distributor markups through manufacturer-owned sterilization logistics is capturing margin in the United States ambulatory segment.
Industry Challenges
- ISO 13485 auditor scarcity:Certification backlog for quality management system renewal is delaying vendor qualification by hospital procurement committees.
- Autoclave cycle fatigue validation:Demonstrating 500+ sterilization durability for titanium alloys requires capital-intensive accelerated aging protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Breast Surgery Retractors Market |
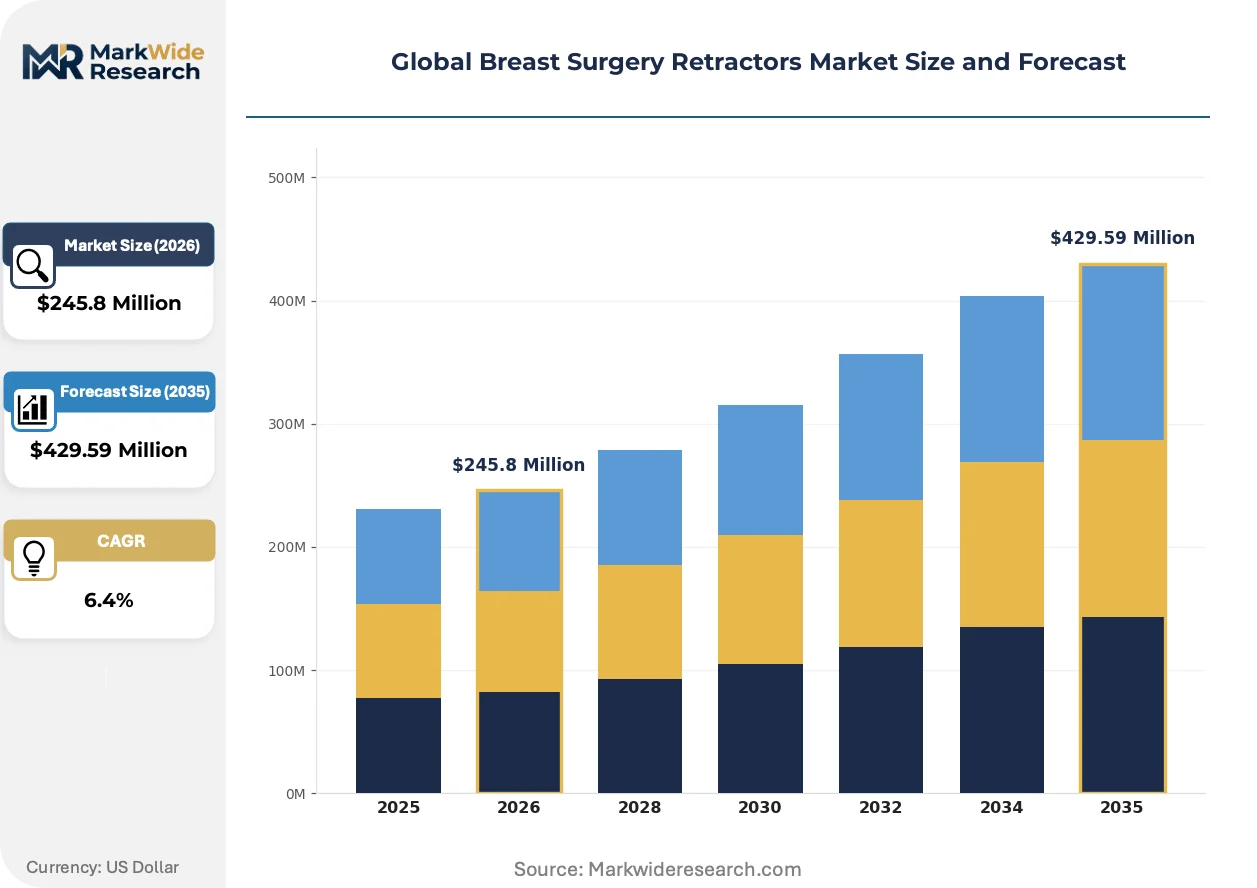
| Market Size in 2026 | $245.8 Million |
| Market Size in 2035 | $429.59 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Retaining, Handheld, Rib Spreader, Skin Hooks, Field Retractors Material: Stainless Steel, Titanium, Plastic, Carbon Steel, Alloy Steel Application: Cosmetic Surgery, Tumor Resection, Reconstructive Procedures, Biopsy Assistance End User: Specialty Clinics, Plastic Surgeons, Oncological Surgery Centers, Ambulatory Surgical Centers |
| Companies Covered | CooperSurgical, Inc., OBP Medical Corporation, Medtronic plc, Black & Black Surgical, Inc., Thompson Surgical Instruments, Integra LifeSciences Corporation, Hayden Medical, Inc., B. Braun Melsungen AG, Stryker Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Breast Surgery Retractors Market Shifts & Advancements
Electromechanical ratchet mechanisms and integrated suction channels are displacing purely mechanical designs. Regulatory convergence around biocompatibility testing is elevating R&D spend across all material categories.
Self-locking electromechanical retractor systems with torque-limited feedback are automating tissue tension management during extended reconstructive procedures. Academic medical centers in the United States are piloting these systems for complex microvascular flap surgeries. This automation is compressing operative time variability and reducing ancillary nursing labor.
The EU MDR's Unique Device Identification mandate is forcing manufacturers to embed laser-etched traceability codes on every stainless steel and titanium instrument surface. Sterilization departments must now scan and log each retractor through decontamination cycles. Reconstructive surgery suites in France and Germany are most affected, with some centers delaying procurement until full compliance infrastructure is operational.
Hospital systems are consolidating vendor lists around suppliers offering bundled instrument-reprocessing service contracts. Independent ambulatory surgery centers in Japan are shifting from capital purchase models to per-procedure leasing arrangements with sterilization included. This preference shift is most visible in Tokyo and Osaka metropolitan clusters where ASC density exceeds national averages.
Global Breast Surgery Retractors Market Segmentation
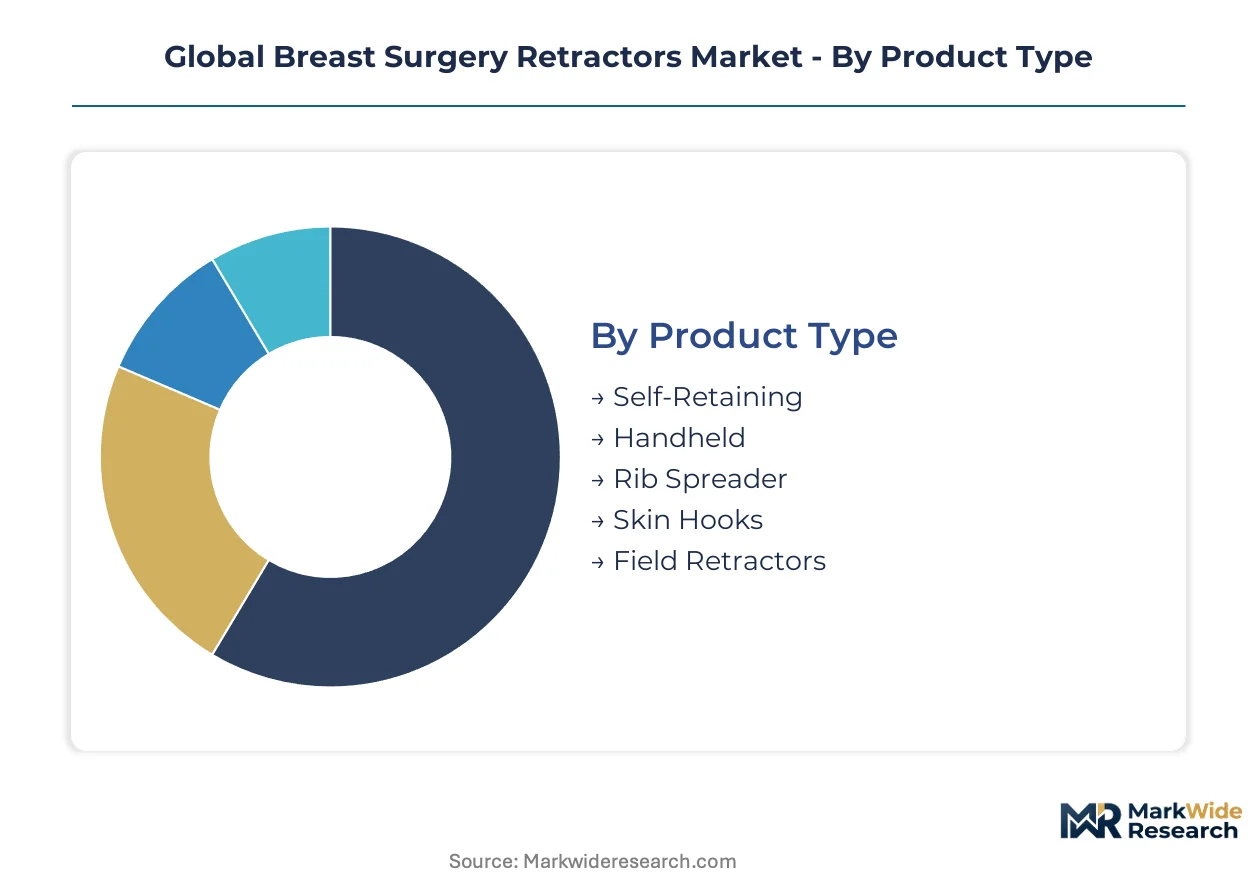
Segmentation in breast surgery retractors reveals how procurement decisions split between capital-intensive reusable systems and disposable alternatives. Material specifications and sterilization infrastructure requirements create distinct purchasing pathways across hospital systems and outpatient settings.
Product Type:
Customization ranges from fully adjustable frame assemblies to single-purpose handheld designs, with self-locking mechanisms commanding premium positioning.
- Self-Retaining:Ratcheted frame systems with torque-limited feedback automate tissue tension management during extended reconstructive procedures. Demand concentrates in German ambulatory surgical centers seeking reduced staffing overhead and faster case turnover between mastectomies.
- Handheld:Stainless steel manual retractors with universal grip compatibility dominate high-volume lumpectomy settings. United States hospital systems prioritize these for compatibility with existing sterilization infrastructure and lower per-unit capital outlay.
- Rib Spreader:Heavy-duty mechanical spreaders designed for thoracic access during radical mastectomy procedures.
- Skin Hooks:Fine-gauge instruments for delicate tissue retraction in cosmetic and reconstructive applications.
- Field Retractors:Broad-surface instruments for exposure of large operative fields in complex reconstruction cases.
Most installed capacity flows through Handheld retractors. Expansion is steepest in Self-Retaining systems.
Material:
Cost tier stratification separates aerospace-grade titanium from commodity stainless steel, with biocompatibility certification acting as the procurement gate.
- Stainless Steel:Surgical-grade 316L alloys withstand repeated autoclave cycles without fatigue deformation, making these the default for high-volume reusable portfolios. Price volatility in nickel and chromium inputs compresses margin predictability for manufacturers serving United States hospital systems.
- Titanium:Precision-crafted alloys offer superior strength-to-weight ratios and reduced thermal conductivity during microvascular flap surgeries. Academic medical centers in Japan specify these for robot-assisted mastectomy convergence where instrument weight affects robotic arm fatigue.
- Plastic:Hydrophobic thermoplastic retractors serve outpatient lumpectomy settings lacking reprocessing infrastructure.
- Carbon Steel:Lower-cost alternative for single-use or limited-reuse applications in cost-constrained markets.
- Alloy Steel:Intermediate performance tier balancing durability against capital expenditure constraints.
Stainless Steel commands the largest installed base. Titanium alloys are climbing the fastest as reconstructive procedure volumes rise.
Application:
Procedure complexity drives specification divergence, with longer surgeries justifying premium instrument investment.
- Cosmetic Surgery:Precision-focused retractors with minimal tissue trauma profiles serve aesthetic breast procedures. Specialty clinics in Tokyo metropolitan clusters favor electromechanical systems with integrated suction channels for reduced operative time variability.
- Tumor Resection:Lumpectomy and partial mastectomy retractors prioritize rapid exposure and minimal residual tissue displacement. Oncological surgery centers in Germany specify self-retaining titanium frames for reduced ancillary nursing labor during high-volume screening-detected cases.
- Reconstructive Procedures:Extended-duration surgeries command premium instrument specifications and disposable adjunct sales.
- Biopsy Assistance:Compact retractors designed for image-guided core needle biopsy procedures.
Reconstructive Procedures capture the highest margin pool. Tumor Resection generates the largest procedure volume.
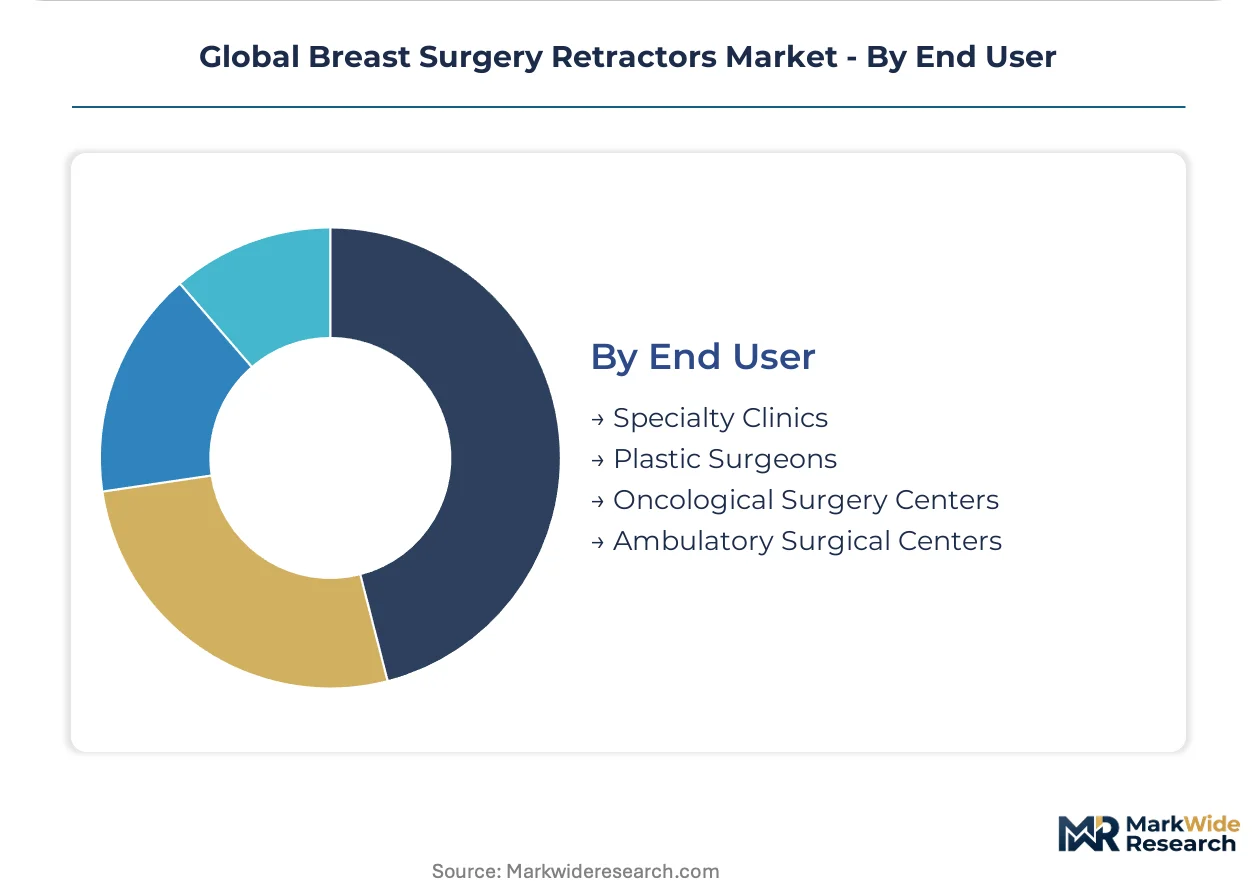
End User:
Customer type determines procurement model, from capital purchase to per-procedure leasing with sterilization bundled.
- Specialty Clinics:Focused breast surgery centers prioritize instrument specialization over breadth of portfolio. France's reconstructive surgery suites delay procurement until EU MDR Unique Device Identification compliance infrastructure is operational.
- Plastic Surgeons:Individual practitioner preferences drive specification for cosmetic and reconstructive applications. United States private practice groups are consolidating vendor lists around suppliers offering bundled instrument-reprocessing service contracts.
- Oncological Surgery Centers:High-volume cancer treatment facilities with dedicated breast surgery units.
- Ambulatory Surgical Centers:Outpatient facilities in Japan's Osaka metropolitan cluster are shifting from capital purchase models to per-procedure leasing arrangements with sterilization included.
Oncological Surgery Centers deploy the largest instrument quantities. Ambulatory Surgical Centers are gaining share fastest as case migration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Breast surgery retractor manufacturing originated in German surgical instrument workshops during the early twentieth century, with precision metalworking traditions later migrating to United States medical device clusters and Japanese orthopedic centers. Contemporary demand concentrates in tertiary oncology hubs across three continents.
United States
FDA 510(k) premarket notifications for reusable retractors with predicate devices compress regulatory timelines for incremental design improvements. Academic medical centers in Boston and Houston pilot electromechanical self-retaining systems for robot-assisted mastectomy convergence. Ambulatory surgical centers in Florida and Texas shift from capital purchase models to per-procedure leasing arrangements with bundled sterilization logistics.
Germany
EU MDR notified body bottlenecks freeze new product introductions as extended conformity assessment timelines delay reusable instrument certifications. Stuttgart and Tübingen surgical instrument clusters specialize in precision-crafted titanium alloys for microvascular flap surgeries. German ambulatory surgical centers adopt self-retaining titanium frame systems to reduce staffing overhead and accelerate case turnover between mastectomies.
Japan
PMDA reimbursement expansion for breast reconstruction in tertiary oncology centers pulls instrument procurement volumes upward. METI quality management system certifications delay but do not block market entry for foreign manufacturers. Tokyo and Osaka metropolitan clusters exhibit the fastest ASC density growth, with outpatient facilities shifting to per-procedure leasing arrangements inclusive of sterilization services.
India
CDSCO fast-track device registration for oncology-dedicated instruments opens access to tier-2 hospital surgical units in Maharashtra and Karnataka. Mumbai and Bangalore medical device manufacturing zones supply stainless steel handheld retractors for domestic lumpectomy volumes. Price-sensitive procurement in tier-3 cities sustains demand for lower-cost carbon steel alternatives despite durability trade-offs.
France
EU MDR Unique Device Identification mandates force laser-etched traceability codes onto every instrument surface, requiring sterilization departments to scan and log each retractor through decontamination cycles. Paris and Lyon reconstructive surgery suites delay procurement until full compliance infrastructure becomes operational. ANSM oversight of biocompatibility testing elevates documentation burdens for reusable portfolio entrants.
Global Breast Surgery Retractors Market Competitive Landscape
The competitive structure tilts toward diversified surgical conglomerates with cross-category sterilization service capabilities. Vendor consolidation accelerates as hospital systems narrow procurement lists around suppliers offering bundled instrument-reprocessing contracts. Three archetypes dominate: integrated surgical ecosystem providers, precision titanium specialists, and obstetric-gynecologic channel cross-sellers. Competitive moves concentrate on strategic partnerships for sterilization logistics and portfolio diversification into single-use polymer alternatives.
Among United States-based diversified manufacturers, Medtronic plc and Stryker Corporation anchor the integrated surgical ecosystem tier, bundling retractors with energy and visualization platforms. CooperSurgical, Inc. exemplifies the obstetric-gynecologic cross-sell archetype, leveraging deep channel relationships into breast procedure lines. Integra LifeSciences Corporation occupies the precision-crafted titanium specialist position for reconstructive microsurgery applications.
| Leading Market Players |
|---|
| CooperSurgical, Inc. |
| OBP Medical Corporation |
| Medtronic plc |
| Black & Black Surgical, Inc. |
| Thompson Surgical Instruments |
| Integra LifeSciences Corporation |
| Hayden Medical, Inc. |
| B. Braun Melsungen AG |
| Stryker Corporation |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap surgical instrument specialists in Germany's Tuttlingen and Sialkot clusters anchor supply-side discipline through generational ownership horizons that resist short-term pricing volatility, while their consolidated bargaining power with nickel-chromium suppliers transmits directly into stainless steel retractor pricing tiers across United States hospital systems and Japanese oncology centers.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels stratifies the market by certification grade and sterilization durability specifications. Premium titanium self-retaining systems command position through ISO 13485 audit trails and 500-cycle autoclave validation, while standard stainless steel handheld retractors compete on per-unit capital efficiency for high-volume lumpectomy settings. Cost compression in the economy tier intensifies because India's CDSCO fast-track pathway enables aggressive carbon steel alternatives. Ambulatory surgical centers in Japan exhibit the highest price sensitivity due to per-procedure leasing model adoption, whereas academic medical centers in the United States prioritize total cost-of-ownership over acquisition price.
Supply Chain Analysis
Dual-sourcing requirements mandated by United States hospital GPOs and Japan's METI quality certifications force manufacturers to qualify secondary suppliers for surgical-grade 316L stainless steel and aerospace-grade titanium alloys. Production gravity centers on Germany's precision metalworking clusters, Pakistan's Sialkot surgical instrument zone, and India's Maharashtra manufacturing belt. Raw material dependencies draw from Indonesian nickel mines, Chinese chromium processing facilities, and Ukrainian titanium sponge producers. Single-source vulnerability in titanium sponge supply creates exposure to geopolitical disruption. Distribution runs through manufacturer-owned sterilization logistics for United States ASCs and traditional distributor networks for European hospital systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The breast surgery retractors market functions as a stable compounder, with procedural volume expansion in oncological surgery centers generating predictable instrument replacement cycles regardless of macroeconomic cyclicality.
For Market Incumbents: Extend sterilization service bundling into per-procedure leasing arrangements to capture margin from Japan's ASC density growth and United States outpatient migration. Absorb EU MDR compliance costs rather than cede European market position to single-use polymer substitutes. Deepen backward integration into titanium alloy sourcing to offset surgical-grade 316L price volatility from Indonesian nickel supply constraints. For New Entrants and Emerging Players: Begin with India's tier-2 hospital surgical units, where CDSCO fast-track registration creates access to 700+ oncology-dedicated facilities underserved by incumbent sterilization infrastructure. Target robot-assisted mastectomy convergence applications in German academic medical centers, where da Vinci-compatible mounting interfaces command premium positioning without requiring full instrument portfolio breadth. Pursue direct-to-ASC distribution partnerships that bypass traditional distributor markups in United States metropolitan clusters. For Investors and Strategic Acquirers: Diversified surgical conglomerates with cross-category sterilization service capabilities are the most active acquirers in this space, seeking precision titanium specialists to fill reconstructive microsurgery gaps. The market exhibits long-term viability through replacement cycle predictability and regulatory barrier durability across a 5-10 year window. Monitor FDA guidance evolution on reprocessing validation as the critical inflection signal determining whether single-use alternatives accelerate against reusable portfolios.| Strategic Initiative | Industry Significance |
|---|---|
| CE Marking Pathway | EU MDR notified body certification unlocks access to German and French reconstructive surgery suites. |
| Hospital System Partnership | Bundled instrument-reprocessing contracts with United States GPOs consolidate vendor lists and capture recurring revenue. |
| Reimbursement Strategy | PMDA coverage expansion for breast reconstruction in Japanese tertiary oncology centers pulls procurement volumes. |
| Software Companion Development | Electromechanical ratchet systems with torque-limited feedback automate tissue tension management in complex microvascular flap surgeries. |
| Backward Integration | In-house titanium alloy production mitigates exposure to Ukrainian sponge supply disruption and nickel-chromium volatility. |
Research Methodology
Direct dialogue with hospital purchasing committees, biomedical engineers, GPO contracts managers, and sterilization department directors grounded the qualitative foundation, supplemented by FDA 510(k) filings, EU MDR notified body certification databases, Japanese PMDA reimbursement bulletins, and hospital procurement contract records. Secondary validation drew from customs trade data for surgical instrument imports, SEC 10-K disclosures from diversified medical device manufacturers, and CMS Medicare procedure volume statistics. Bottom-up and top-down triangulation cross-checked manufacturer shipment data against hospital install-base surveys.
Bottom-up modeling aggregated procedure volumes by application and end-user type across the projection horizon, while top-down analysis calibrated aggregate market size against macro healthcare expenditure trends. Segmentation dimensions included product type, material specification, application complexity, and end-user procurement model. CAGRs derived from surgical volume growth trajectories, reimbursement pathway expansions, and technology substitution elasticities. Industry-specific inputs incorporated autoclave cycle durability validation requirements and EU MDR Unique Device Identification implementation timelines.
Several conditions sit outside the modeled scope, including unannounced regulatory guidance revisions, abrupt raw material export restrictions, and disruptive single-use polymer technology breakthroughs. Deviation in FDA reprocessing validation standards would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Medical Devices
Global Brachytherapy Treatment Planning Systems Market
Medical Devices
Condylar Plate Fixation System Market
Medical Devices
Ultrasound Stimulator Market
Medical Devices
Global Anesthesia Video Laryngoscope Market
Medical Devices
Hydrogen Inhalers Market
Medical Devices
Invasive SEEG Depth Electrodes Market
Medical Devices
Global Embolization Particle Market
Medical Devices
Japan Medical Device Regulatory Affairs Market
Medical Devices
Sputum Ejection Machine Market
Medical Devices
Global Surgical/Operating Microscopes Market
Medical Devices
Transcranial Doppler Ultrasounds System Market
Medical Devices
Struts Implants Market
Medical Devices
Point-Of-Care Ultrasound (Pocus) Device Market
Medical Devices
Dual Chamber Prefilled Syringes Market
Medical Devices
Neurovascular Stent Market
Medical Devices
Germany Ultrasound Devices Market