
 Electrolyzer Market | 2026-2036
Electrolyzer Market Size, Share, and Industry Trends Forecast 2026-2036
Electrolyzer Market Analysis
Platinum is broadening its addressable role in electrolyzer stacks as manufacturers reduce iridium loading in proton exchange membrane cells. Nel Hydrogen leverages its integrated manufacturing footprint in Norway to control stack assembly and testing workflows. Siemens Energy anchors large-scale alkaline and PEM projects through its Berlin-area engineering base. Cummins Inc. competes across modular PEM systems for industrial hydrogen hubs in North America and Europe.
An electrolyzer is an electrochemical device that splits water into hydrogen and oxygen using direct current electricity, with alkaline units operating at 60-80°C using liquid potassium hydroxide electrolyte and PEM systems running at 50-80°C with solid polymer membranes and platinum-group catalysts; its primary purpose is to produce gaseous hydrogen for industrial processes, energy storage, or synthetic fuel synthesis. Alkaline electrolyzers occupy the mature cost-efficient tier for grid-scale installations, while PEM technology leads in rapid-response coupling with intermittent renewable sources. Solid oxide systems remain the emerging high-temperature segment, targeting efficiency gains through waste-heat integration with industrial facilities.
The EU Green Deal and REPowerEU framework shape European demand by mandating renewable hydrogen quotas and carbon intensity thresholds for imported fuels. In the United States, the Inflation Reduction Act's hydrogen production tax credit redirects capital toward domestic electrolyzer manufacturing and project development. China's MIIT sets efficiency benchmarks and domestic content requirements for electrolyzer deployment under national hydrogen roadmaps. Stakeholders must track how subsidy eligibility rules and carbon border adjustments restructure equipment sourcing and project finance across these jurisdictions.
Market Dynamics
The electrolyzer market is being restructured by iridium supply concentration and the race to reduce platinum-group metal loading in proton exchange membrane stacks, forcing manufacturers to re-engineer catalyst architectures and secure alternative material supply chains.
Growth Catalysts
- REPowerEU Framework:The EU's renewable hydrogen import quotas and carbon intensity thresholds are mandating electrolyzer deployment across ammonia and steel facilities in Germany, the Netherlands, and Denmark.
- Alkaline cost efficiency:Grid-scale renewable projects in China and India are selecting mature alkaline technology for 100+ MW installations where response speed is secondary to capital expenditure control.
- Steel sector decarbonization:Direct reduced iron producers in Sweden and Austria are signing long-term offtake agreements for green hydrogen, creating dedicated demand corridors for electrolyzer OEMs.
Market Restraints
- Iridium supply concentration:South African and Russian mining operations control over 80% of global iridium output, exposing PEM manufacturers to price volatility and export restriction risk.
- High-purity water infrastructure:Ultrapure water systems for PEM stacks require reverse osmosis and deionization capital that adds 15-20% to project engineering costs.
- Grid interconnection queues:Utility-scale electrolyzer projects in Germany and Texas face 24-36 month transmission access delays, compressing project returns.
Strategic Opportunities
- Solid oxide waste-heat integration:High-temperature electrolysis systems from Sunfire and Topsoe are electrifying industrial heat recovery from cement and chemical plants in Norway and the Netherlands.
- India's National Hydrogen Mission:PLI scheme subsidies for domestic electrolyzer manufacturing are attracting joint ventures between European stack suppliers and Indian engineering contractors.
- Offshore hydrogen platforms:North Sea wind-to-hydrogen projects in Denmark and the UK are testing marinized alkaline systems for direct pipeline injection without onshore grid connection.
Industry Challenges
- Electrolyzer stack assembly technician shortage:Precision welding and membrane electrode assembly skills are concentrated in Norway and Germany, constraining manufacturing scale-up.
- Multi-standard certification complexity:Projects must simultaneously satisfy ASME pressure vessel codes, IEC 61400-25 electrical safety, and local fire suppression regulations, extending commissioning timelines.
- Legacy natural gas infrastructure retrofit:Hydrogen embrittlement risks in existing pipeline networks require material testing protocols that lack harmonization across EU member states.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electrolyzer Market |
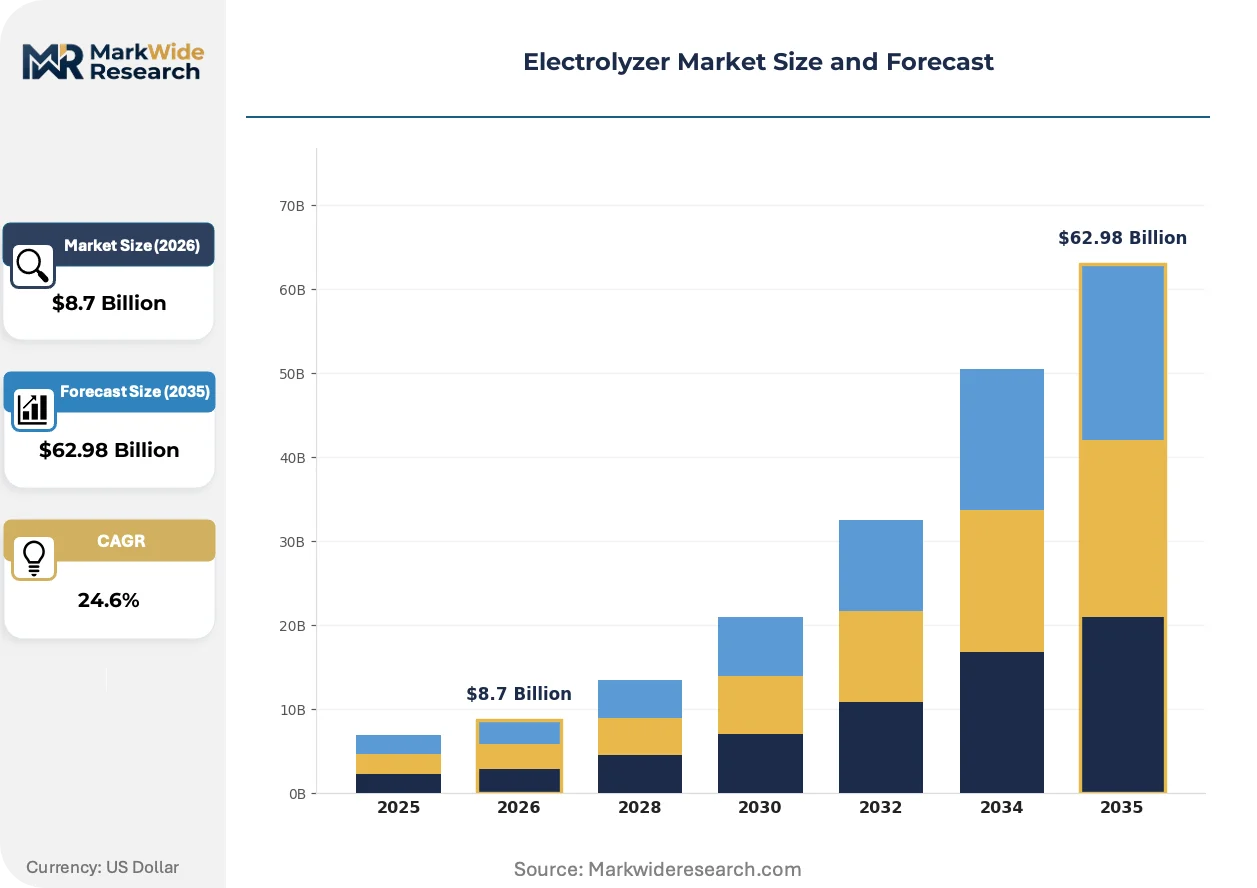
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $62.98 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alkaline, PEM, Solid Oxide, Anion Exchange Membrane Technology: Proton Exchange Membrane, High-Temperature Electrolysis, Low-Temperature Electrolysis, Bipolar Plate Technology End User: Utilities, Industrial End Users, Renewable Energy Producers, Fuel Cell Manufacturers Application: Hydrogen Production, Energy Storage, Fuel Cells, Chemical Feedstocks |
| Companies Covered | thyssenkrupp nucera, Nel Hydrogen, Siemens Energy, John Cockerill, Plug Power, Cummins Inc., ITM Power, McPhy Energy, LONGi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electrolyzer Market Emerging Trajectories
Electrolyzer technology is converging with renewable generation and industrial process heat in ways that redefine project economics and system architecture. Three developments are compressing the pathway from pilot to commercial scale.
Anion exchange membrane technology is electrifying the cost-performance gap between alkaline and PEM systems. Developers in Japan and South Korea are piloting AEM stacks that operate without platinum-group metals while achieving PEM-like current density. Steel and ammonia offtakers in Rotterdam and Hamburg are electrifying their technology evaluations to include AEM alongside established alkaline and PEM options.
The Inflation Reduction Act's hydrogen production tax credit is restructuring project finance in the United States. Developers must prove lifecycle carbon intensity below 4 kg CO2e per kg H2 to capture the full credit, forcing electrolyzer buyers to source renewable electricity through dedicated power purchase agreements rather than grid mixes. Texas and Louisiana project sponsors are electrifying their offtake negotiations to secure 10-15 year contracted electricity supply before final investment decisions.
Industrial hydrogen procurement is consolidating around integrated production hubs. Ammonia and methanol producers in the Middle East and Australia are electrifying their supplier relationships to favor electrolyzer OEMs offering 20-year service contracts with guaranteed availability clauses. This behavior is displacing equipment-only transactions and compressing margins for stack manufacturers unwilling to assume operational risk.
Electrolyzer Market Segmentation
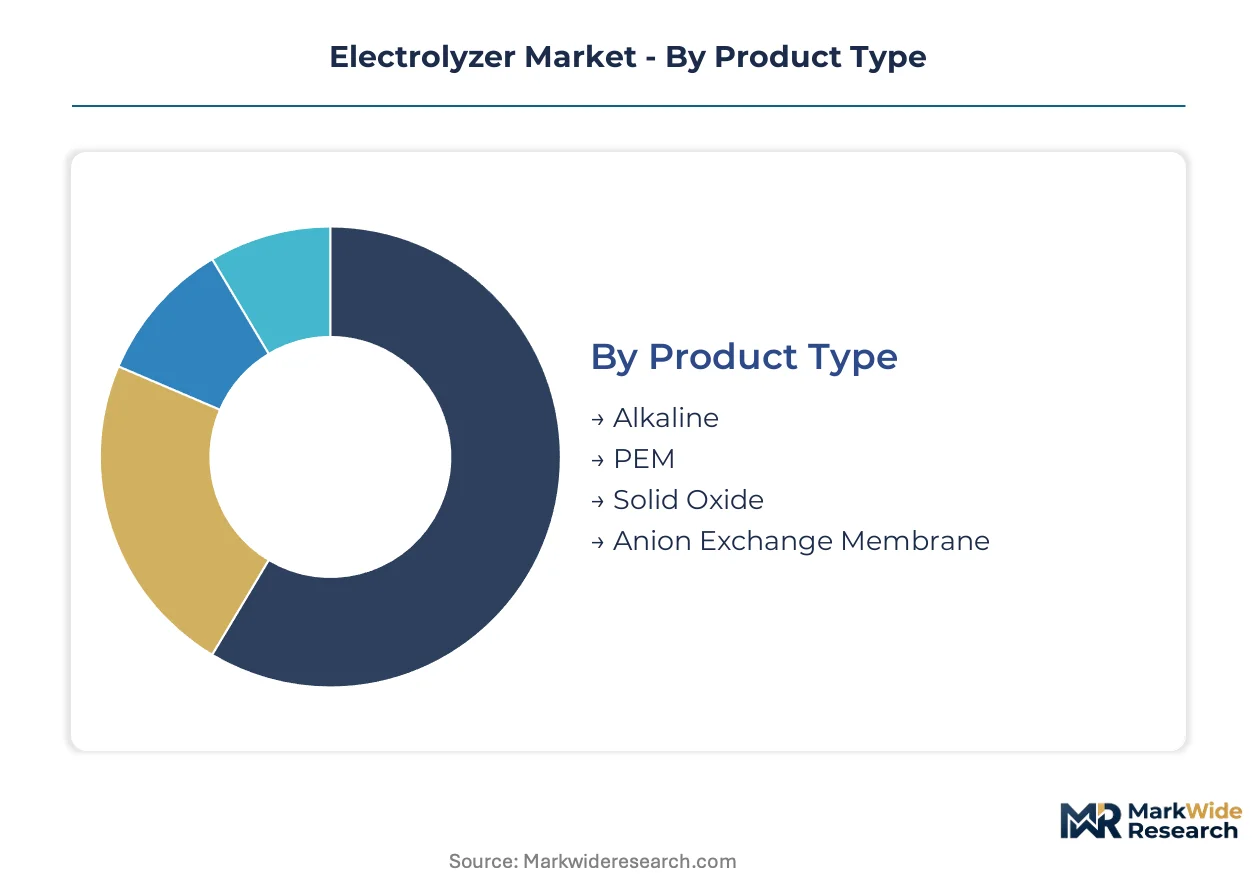
Electrolyzer procurement patterns diverge sharply across product architectures and end-use requirements. Manufacturers must align stack specifications with each buyer's carbon intensity targets, response speed needs, and existing infrastructure constraints.
Product Type:
Stack manufacturing capacity concentrates around alkaline and PEM platforms, with catalyst supply chains and membrane electrode assembly workflows determining regional production advantages.
- Alkaline:Liquid potassium hydroxide electrolyte systems operate at 60-80°C with nickel-based electrodes, avoiding platinum-group metals entirely. Chinese OEMs dominate 100+ MW project deployments where capital efficiency outweighs ramp-rate requirements.
- PEM:Solid polymer membranes with platinum-iridium catalysts enable sub-second response to renewable intermittency. German and Norwegian manufacturers anchor supply for ammonia and mobility applications requiring rapid load-following.
- Solid Oxide:Ceramic electrolyte systems at 700-800°C achieve highest electrical efficiency through industrial waste-heat integration. Sunfire and Topsoe pilot units target cement and chemical plant retrofits.
- Anion Exchange Membrane:Emerging metal-free catalyst architecture bridges alkaline cost structure with PEM current density. Japanese and South Korean developers accelerate pilot programs for steel sector offtake.
Alkaline systems absorb the bulk of installed capacity; anion exchange membrane technology is expanding most quickly.
Technology:
Process temperature and cell architecture dictate integration pathways with renewable generation and industrial heat sources.
- Proton Exchange Membrane:Perfluorinated sulfonic acid membranes require ultrapure water and precious metal catalysts. Texas and Louisiana hydrogen hubs specify PEM for direct coupling with offshore wind and solar farms.
- High-Temperature Electrolysis:Solid oxide cells reverse-operate as fuel cells, enabling bidirectional energy storage. Norwegian industrial clusters deploy these for ammonia production with geothermal heat recovery.
- Low-Temperature Electrolysis:Alkaline and PEM systems below 100°C serve distributed hydrogen refueling and grid-scale storage. Indian PLI scheme subsidies favor domestic manufacturing of these mature platforms.
- Bipolar Plate Technology:Stamped titanium or coated stainless steel plates distribute current and fluids across cell stacks. Precision stamping capacity concentrates in German and Austrian supplier networks.
Low-temperature electrolysis commands current manufacturing scale; high-temperature systems are climbing the fastest.
End User:
Procurement scale and contract duration vary dramatically between merchant hydrogen producers and captive industrial consumers.
- Utilities:Grid operators deploy electrolyzers for demand response and seasonal storage. German transmission system operators integrate 100 MW-class alkaline arrays with offshore wind curtailment management.
- Industrial End Users:Ammonia, steel, and methanol producers sign 10-20 year offtake agreements. Swedish direct reduced iron facilities in Boden and Oxelösund anchor dedicated green hydrogen supply chains.
- Renewable Energy Producers:Wind and solar developers add electrolyzers to capture otherwise curtailed generation. Danish North Sea platforms test marinized systems for direct pipeline injection.
- Fuel Cell Manufacturers:Mobility and stationary power integrators require high-purity hydrogen with guaranteed availability. California fuel cell bus fleets specify PEM-derived hydrogen meeting SAE J2719 purity standards.
Industrial end users absorb the bulk of installed capacity; renewable energy producers are gaining share fastest.
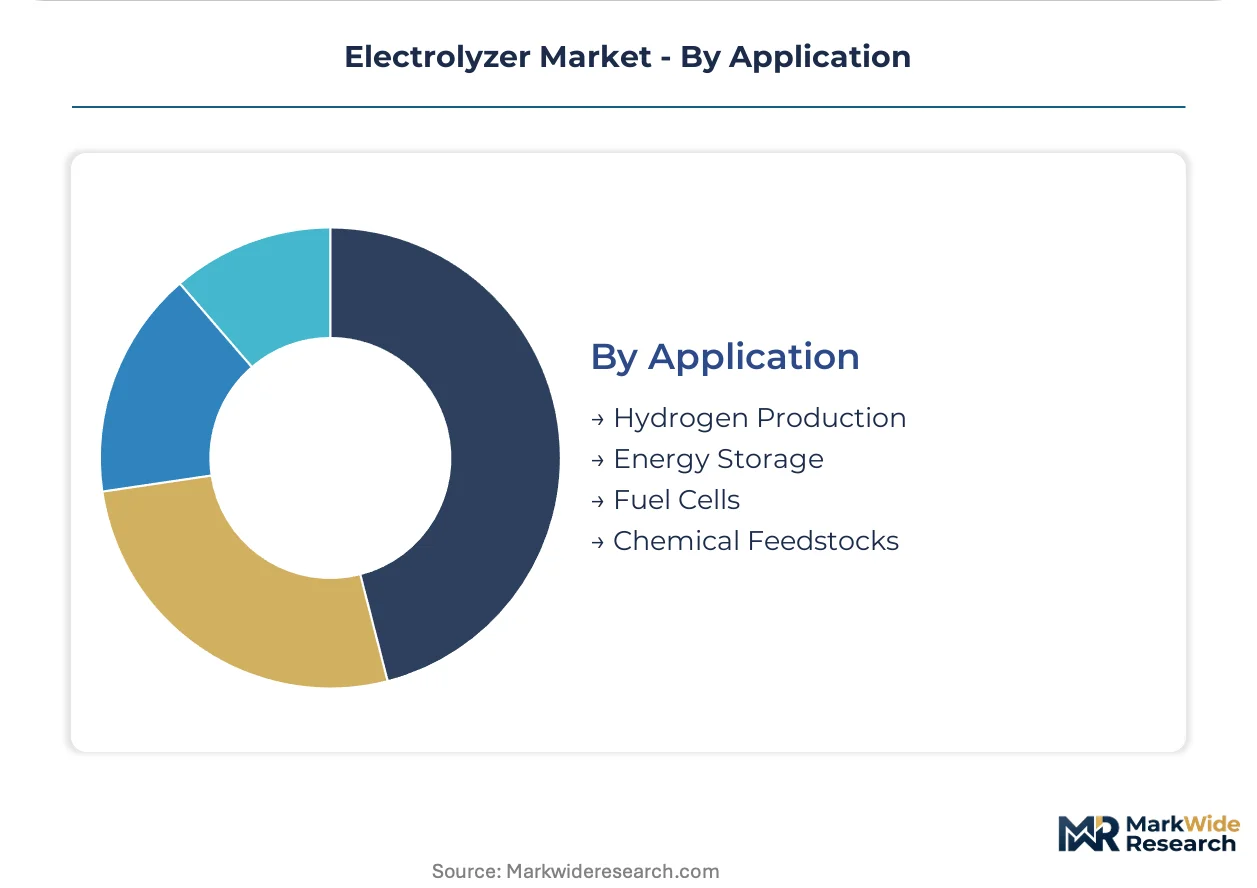
Application:
Hydrogen end-use specifications determine stack sizing, purity requirements, and compression infrastructure investments.
- Hydrogen Production:Merchant and captive production facilities supply industrial gas networks and dedicated offtakers. Rotterdam port authorities mandate renewable hydrogen quotas for imported ammonia cracking.
- Energy Storage:Power-to-gas systems convert surplus renewable electricity into storable hydrogen. German salt cavern storage projects in Lower Saxony pair alkaline electrolyzers with existing natural gas infrastructure.
- Fuel Cells:Mobility and stationary power applications require 99.97%+ purity with trace contaminant control. South Korean fuel cell electric vehicle deployment drives PEM electrolyzer demand for hydrogen refueling stations.
- Chemical Feedstocks:Synthetic fuels and ammonia synthesis consume hydrogen as process input. Australian renewable ammonia export projects in Queensland and Western Australia specify gigawatt-scale electrolyzer arrays.
Hydrogen production absorbs the bulk of installed capacity; chemical feedstock applications are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial demand for green hydrogen anchors the electrolyzer market, with ammonia and steel producers scaling procurement through auction mechanisms and dedicated manufacturing clusters.
Germany
The H2Global auction mechanism and REPowerEU hydrogen import quotas drive electrolyzer deployment across ammonia and steel facilities. German transmission system operators integrate 100 MW-class alkaline arrays with offshore wind curtailment management. Berlin-area engineering bases anchor large-scale alkaline and PEM project development.
United States
The Inflation Reduction Act's hydrogen production tax credit redirects capital toward domestic electrolyzer manufacturing and project development. FERC interconnection queues and state-level renewable mandates shape project siting decisions. Texas and Louisiana hydrogen hubs specify PEM systems for direct coupling with offshore wind and solar farms.
China
MIIT efficiency benchmarks and domestic content requirements under national hydrogen roadmaps structure equipment procurement. Grid-scale renewable projects select mature alkaline technology for 100+ MW installations where capital expenditure control outweighs response speed. Domestic OEMs dominate manufacturing scale for export and captive deployment.
India
PLI scheme subsidies for domestic electrolyzer manufacturing attract joint ventures between European stack suppliers and Indian engineering contractors. The National Hydrogen Mission mandates renewable hydrogen quotas for fertilizer and refinery operations. Gujarat and Maharashtra industrial corridors concentrate pilot project development.
Norway
Integrated manufacturing footprints control stack assembly and testing workflows for export markets. Industrial clusters deploy high-temperature electrolysis for ammonia production with geothermal heat recovery. Marinized alkaline systems for North Sea wind-to-hydrogen projects test direct pipeline injection without onshore grid connection.
Electrolyzer Market Vendor Landscape
Capacity expansion dominates the current landscape as manufacturers race to secure iridium supply chains and reduce platinum-group metal loading in proton exchange membrane stacks. The vendor base concentrates around alkaline specialists with Chinese manufacturing scale and PEM developers with European engineering heritage. Three archetypes define competitive positioning: integrated industrial conglomerates with captive energy assets, pure-play electrolyzer OEMs with dedicated stack manufacturing, and renewable energy developers backward integrating into hydrogen production. M&A activity and strategic partnerships for catalyst supply security represent the dominant competitive moves.
Among European engineering-based developers, thyssenkrupp nucera, Siemens Energy, and Nel Hydrogen exemplify the integrated industrial conglomerate archetype with captive manufacturing footprints. These entities anchor supply for ammonia and steel sector offtake agreements through long-term service contracts. Chinese manufacturers including LONGi occupy positions defined by scale-driven cost structures for grid-scale deployment. The competitive terrain rewards players securing alternative catalyst architectures and 20-year availability guarantees.
| Leading Market Players |
|---|
| thyssenkrupp nucera |
| Nel Hydrogen |
| Siemens Energy |
| John Cockerill |
| Plug Power |
| Cummins Inc. |
| ITM Power |
| McPhy Energy |
| LONGi |
| Others |
Supply Flow & Price Mechanics
Industrial ammonia and steel producers dominate electrolyzer procurement through long-term offtake contracts, anchoring a project-based pricing model where capital efficiency and guaranteed availability clauses determine contract value. German steelmakers and Rotterdam ammonia crackers bundle 20-year service agreements with equipment purchases, compressing margins for stack manufacturers unwilling to assume operational risk.
Pricing Analysis
High-volume alkaline deployments trade at thin margins against premium PEM systems capturing value from rapid-response capabilities. Price differentiation rests on platinum-group metal loading and certification tier, with ASME-coded pressure vessels commanding premiums over standard industrial grades. Cost compression in the alkaline tier intensifies as Chinese OEMs expand manufacturing scale, while PEM pricing holds firmer due to iridium supply constraints. Ammonia producers show lowest price sensitivity given carbon border exposure, whereas Indian fertilizer plants under PLI scheme subsidies exhibit acute cost consciousness.
Supply Chain Analysis
Single-source vulnerability sits with South African and Russian mining operations controlling over 80% of global iridium output, exposing PEM manufacturers to export restriction risk. Stack assembly draws from German precision stamping networks for bipolar plates and Norwegian membrane electrode assembly facilities. Supply chain risk centers on geopolitical disruption to precious metal flows. Distribution runs through EPC contractors and industrial gas majors managing project execution and long-term service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electrolyzer market is consolidating around manufacturers securing iridium supply chains and 20-year availability guarantees, with platinum-group metal concentration forcing weaker stack assemblers toward acquisition or exit.
For Market Incumbents: Lock in iridium supply through offtake agreements with South African refiners or accelerate catalyst loading reduction programs to hedge substitution risk. Expand captive membrane electrode assembly capacity in Norway or Germany to defend technician-constrained manufacturing scale against Chinese alkaline specialists. For New Entrants and Emerging Players: Digital-channel route partnerships with industrial gas distributors offer lower customer acquisition costs than direct EPC competition. Target India's National Hydrogen Mission PLI scheme corridors in Gujarat and Maharashtra, where European stack suppliers seek local engineering contractors for joint venture structures. Position anion exchange membrane pilots as metal-free alternatives for steel sector offtake evaluations in Hamburg and Rotterdam. For Investors and Strategic Acquirers: The window for entry favors pure-play AEM developers and solid oxide specialists with waste-heat integration patents ahead of industrial retrofit cycles. Prioritize targets with demonstrated Sunfire or Topsoe licensing relationships and Norwegian geothermal site access. Watch for FERC interconnection queue clearance in Texas as inflection signal for PEM demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Catalyst Supply | Secures iridium offtake from South African refiners, insulating PEM margins from export restrictions. |
| AEM Technology Licensing | Japanese and South Korean developers bridge alkaline cost structures with PEM current density for steel offtakers. |
| Long-term Service Contract Expansion | Rotterdam ammonia producers bundle 20-year availability guarantees, displacing equipment-only transactions. |
| Joint Venture with Indian Engineering Contractors | European stack suppliers leverage PLI scheme subsidies for domestic manufacturing in Gujarat corridors. |
| Marinized Alkaline System Certification | Danish North Sea wind-to-hydrogen projects test direct pipeline injection without onshore grid connection. |
Methodological Framework
Independent corroboration across electrolyzer OEM engineering directors, ammonia plant procurement leads, and EPC project managers underwrites the qualitative findings. Primary fieldwork captured stack manufacturing workflows in Norway and Germany alongside steel sector offtake negotiations in Sweden and Austria. Secondary validation drew from MIIT efficiency benchmarks, SEC manufacturing disclosures, and IEA hydrogen project databases. Bottom-up unit economics and top-down policy-driven demand curves were reconciled through iterative triangulation.
Rate-of-change decomposition across the analysis window separated alkaline cost curve improvements from PEM precious metal price volatility. The forecast framework modeled product type, end-user vertical, and regional regulatory cluster as primary segmentation dimensions. CAGRs were derived from electrolyzer manufacturing capacity buildout schedules and renewable hydrogen quota implementation timelines. Key inputs included FERC interconnection queue data and H2Global auction clearing prices.
The model holds under sustained REPowerEU import quota enforcement and IRA hydrogen production tax credit continuity; deviation in South African mining export policy or FERC transmission access timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydrogen Energy
Liquid Hydrogen Tank Market
Hydrogen Energy
Hydrogen Market
Hydrogen Energy
35MPa High Pressure Hydrogen Storage Cylinders Market
Hydrogen Energy
United States Hydrogen Generation Market
Hydrogen Energy
US Hydrogen Fueling Station Market
Hydrogen Energy
Green Energy Hydrogen Production System Market
Hydrogen Energy
Hydrogen Station Market
Hydrogen Energy
North America Liquid Hydrogen Market
Hydrogen Energy
Europe Clean Hydrogen Market
Hydrogen Energy
Asia Pacific Liquid Hydrogen Market
Hydrogen Energy
Blue Hydrogen Market
Hydrogen Energy
Hydrogen Production Electrolyser Market
Hydrogen Energy
Photovoltaic Hydrogen Production Market
Hydrogen Energy
Hydrogen Storage Technology Market
Hydrogen Energy
Hydrogen Energy Electrolyzer Market
Hydrogen Energy
Green Hydrogen Energy Storage System Market