
 Hydrogen Market | 2026-2036
Hydrogen Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogen Market Analysis
Multi-source electrolyzer procurement is decoupling from legacy steam methane reforming contracts as developers seek supply resilience. Linde plc anchors industrial hydrogen delivery through pipeline networks across the US Gulf Coast. Siemens Energy AG leverages its PEM electrolyzer technology to compete for European green hydrogen tenders. Air Products and Chemicals, Inc. sustains its position through backward integration into blue hydrogen production with carbon capture.
Hydrogen is the lightest diatomic gas, with an energy density of 120 MJ/kg by mass and a boiling point of minus 253 degrees Celsius, serving primarily as an industrial feedstock and zero-emission energy carrier. Steam methane reforming still dominates production method volumes, though electrolysis captures margin pools where renewable power purchase agreements secure cost-competitive green hydrogen. Fuel cells within the application dimension lead technology investment, while transportation and power generation segments attract policy-backed deployment capital.
The EU Green Deal and its delegated acts on renewable hydrogen define product eligibility for subsidies and import tariffs, while the US IRA production tax credits reshape project economics for domestic electrolyzer deployment. Japan's METI hydrogen roadmap and South Korea's MFDS safety standards govern equipment certification and end-use permitting in East Asian markets. Stakeholders must track how regulatory stringency on carbon intensity thresholds filters through to offtake contract structures and equipment procurement specifications.
Market Dynamics
Electrolyzer cost deflation is compressing green hydrogen production premiums against legacy steam methane reforming, while the EU Green Deal's carbon border adjustments force industrial offtakers to renegotiate long-term supply contracts.
Growth Catalysts
- EU Green Deal delegated acts:Renewable hydrogen certification rules trigger refinery offtake commitments for transport fuel blending mandates across Netherlands and Germany.
- PEM electrolyzer manufacturing:Stack production automation cuts capex per megawatt, enabling project developers to undercut alkaline electrolyzer bids in European tenders.
- Japan's METI hydrogen roadmap:Import terminal construction at Kobe and Yokohama creates guaranteed demand pools for Australian and Middle Eastern exporters.
Market Restraints
- Renewable power purchase agreement volatility:Solar and wind curtailment risks in Spain and Italy inflate levelized cost assumptions for green hydrogen project finance.
- Chinese electrolyzer supply concentration:Stack and membrane manufacturing clusters in Jiangsu and Zhejiang provinces expose developers to single-source procurement vulnerabilities.
- Liquid organic hydrogen carrier efficiency ceiling:Toluene hydrogenation and dehydrogenation energy losses limit maritime shipping applications below 5,000 kilometer routes.
Strategic Opportunities
- India's National Hydrogen Mission:Electrolyzer manufacturing-linked PLI scheme offers capital subsidies for domestic gigafactory establishment through 2030.
- Ammonia cracking for power generation:Retrofitting coal turbines in South Korea and Japan with dual-fuel ammonia injectors opens 40-gigawatt addressable capacity.
- US IRA production tax credits:Section 45V credits up to three dollars per kilogram reshape project returns for Texas and Louisiana electrolyzer deployments.
Industry Challenges
- High-pressure composite tank certification:UN ECE R134 and ISO 19881 testing timelines stretch 18-24 months, delaying fuel cell truck fleet rollouts.
- Cryogenic pump technician scarcity:Specialized maintenance skills for minus 253 degrees Celsius liquid hydrogen infrastructure concentrate in Germany and Japan.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogen Market |
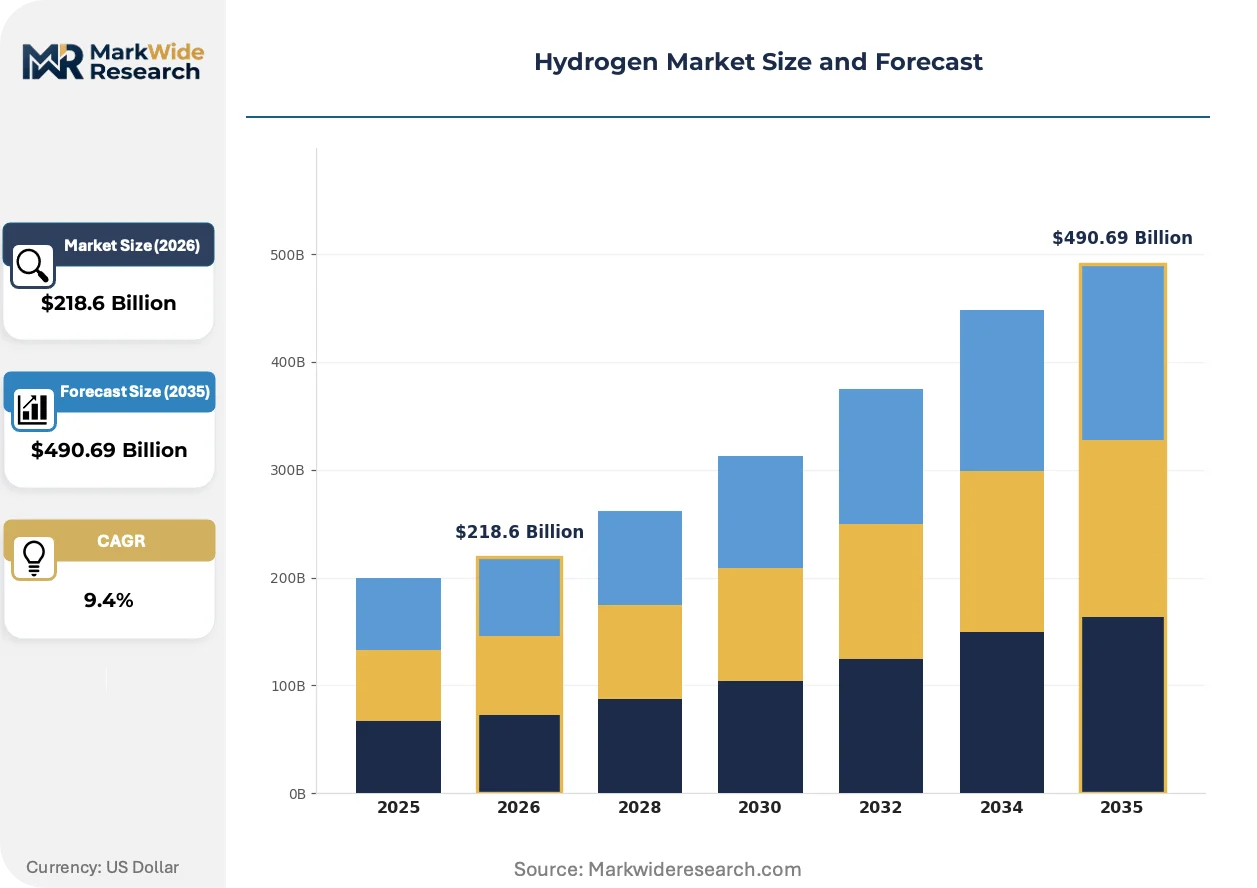
| Market Size in 2026 | $218.6 Billion |
| Market Size in 2035 | $490.69 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Production Method: Steam Methane Reforming, Electrolysis, Gasification, Biomass Application: Fuel Cells, Industrial Processes, Transportation, Power Generation End User: Automotive, Aerospace, Energy, Chemicals Distribution Channel: Pipelines, Trucks, Tanks, On-site Generation |
| Companies Covered | Linde plc, Air Liquide, Air Products and Chemicals, Inc., Siemens Energy AG, Cummins Inc., Plug Power Inc., BP, Ballard Power Systems, ENGIE SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogen Market Emerging Trajectories
Solid oxide electrolyzer technology is crossing commercial thresholds while regulatory carbon intensity accounting tightens across multiple jurisdictions simultaneously.
Proton exchange membrane stacks with iridium-coated catalyst layers are expanding into heavy-duty trucking applications as Daimler Truck and Volvo Group accelerate fuel cell powertrain roadmaps. Fleet operators in California and Germany now specify 25,000-hour stack durability guarantees. This technology is expanding into rail and maritime propulsion segments previously reserved for diesel-electric hybrids.
The EU F-Gas Regulation revision tightens fluorinated gas containment standards for hydrogen cooling systems in electrolyzer plants. Equipment vendors must redesign heat exchanger seals and compressor packings to comply with phasedown schedules. German and French electrolyzer OEMs are accelerating magnetic bearing compressor development to eliminate refrigerant leakage pathways entirely.
Industrial offtakers in chemicals and steel now contract for certified low-carbon hydrogen through mass-balance certificates rather than physical molecule tracking. Dutch and German port authorities are building shared import terminal infrastructure to aggregate supply for multiple buyers. This procurement consolidation concentrates contracting power with Rotterdam and Hamburg terminal operators.
Hydrogen Market Segmentation
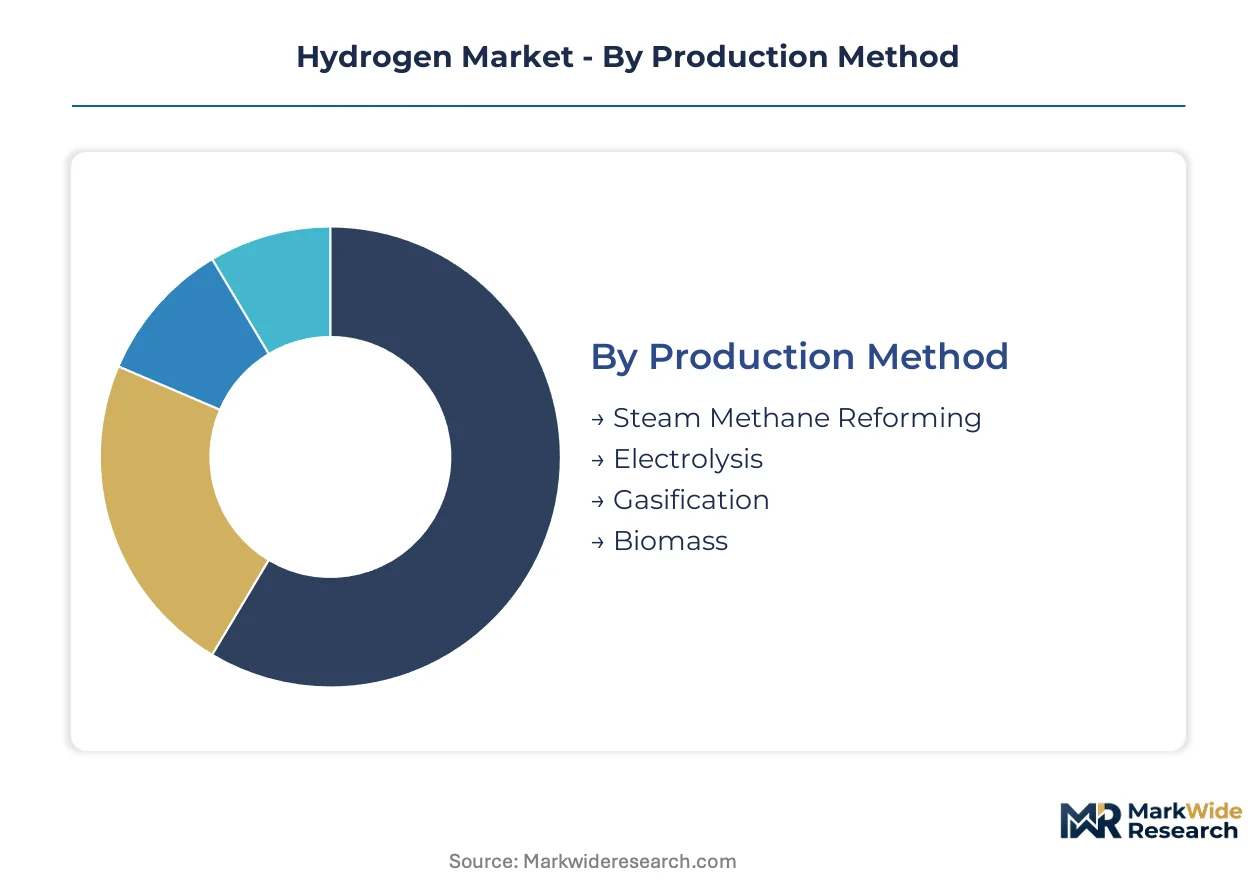
Production method and application dimensions drive divergent certification requirements across hydrogen value chains. Equipment vendors and project developers must align procurement specifications with jurisdiction-specific safety mandates and carbon intensity thresholds.
Production Method:
Steam methane reforming and electrolysis face distinct regulatory burdens under EU Green Deal carbon accounting rules and US IRA production tax credit eligibility criteria.
- Steam Methane Reforming:Natural gas feedstock conversion via high-temperature catalytic reactions produces hydrogen with carbon dioxide as byproduct. Refinery demand in Rotterdam and Houston clusters around this method due to existing pipeline infrastructure, though EU carbon border adjustments now force emission offset purchases.
- Electrolysis:Water splitting via alkaline or PEM stack technology yields hydrogen purity suitable for fuel cell applications. German and Dutch tenders increasingly specify electrolyzer-only supply for transport fuel blending mandates, with stack durability guarantees now extending to 25,000 operating hours.
- Gasification:Coal or petroleum coke partial oxidation produces syngas for hydrogen extraction, concentrated in Chinese industrial clusters where dual carbon goals are tightening emission intensity ceilings.
- Biomass:Organic feedstock gasification with carbon capture qualifies for renewable hydrogen certification under EU delegated acts, though feedstock traceability requirements complicate project finance in Nordic markets.
Steam methane reforming sits at the top of the volume ranking, with electrolysis climbing the fastest.
Application:
Application segments stratify by equipment certification complexity, from fuel cell stack testing under UN ECE R134 to industrial burner retrofit approvals.
- Fuel Cells:Electrochemical conversion devices for stationary and mobile power. California and Germany now mandate 25,000-hour stack durability for heavy-duty trucking deployments, with Daimler Truck and Volvo Group specifying iridium-coated catalyst layers for extended service life.
- Industrial Processes:Ammonia synthesis and steel direct reduction consume hydrogen as chemical feedstock. Dutch port authorities aggregate demand through Rotterdam import terminals, with mass-balance certificates replacing physical molecule tracking for carbon accounting.
- Transportation:Compressed and liquid hydrogen storage for road, rail, and maritime propulsion. High-pressure composite tank certification timelines of 18-24 months under ISO 19881 delay fleet rollouts in European markets.
- Power Generation:Gas turbine blending and fuel cell stationary installations. South Korea and Japan are retrofitting coal turbines with dual-fuel ammonia injectors, opening substantial addressable capacity for hydrogen-derived fuels.
Industrial processes command the largest current revenue pool, while transportation applications are expanding most quickly.
End User:
End user segments diverge by procurement scale and contract duration, from automotive fleet tenders to chemical offtake agreements spanning decades.
- Automotive:Fuel cell passenger and commercial vehicle manufacturers. Hyundai and Toyota anchor demand through dedicated hydrogen retail networks in California and Japan, with heavy-duty trucking pilots scaling under EU Green Deal renewable fuel mandates.
- Aerospace:Turbine combustion and fuel cell auxiliary power unit development. Airbus and Boeing research programs concentrate in Toulouse and Seattle, with liquid hydrogen handling protocols governed by FAA and EASA certification timelines.
- Energy:Utility-scale storage and grid balancing services. Texas and Louisiana project developers leverage US IRA Section 45V credits to undercut conventional peaker plant economics.
- Chemicals:Ammonia, methanol, and refinery hydrogenation processes. BASF and Linde plc negotiate long-term supply contracts with carbon intensity clauses tied to EU carbon border adjustment mechanisms.
Chemicals end users dominate contract volumes, with energy sector procurement gaining share fastest.
Distribution Channel:
Channel selection determines capital intensity and regulatory exposure, from pipeline tariff structures to cryogenic transport permitting.
- Pipelines:Dedicated hydrogen and natural gas blending infrastructure. Linde plc operates networks across the US Gulf Coast, with FERC tariff approvals required for interstate transport.
- Trucks:Tube trailer and cryogenic tanker delivery for regional supply. German and French operators face driver certification requirements for hazardous materials handling under ADR regulations.
- Tanks:Bulk liquid hydrogen storage at import terminals and industrial sites. Kobe and Yokohama terminal construction under Japan's METI roadmap creates guaranteed demand aggregation points.
- On-site Generation:Electrolyzer installation at point of consumption. Indian National Hydrogen Mission PLI subsidies incentivize domestic gigafactory establishment for captive industrial supply.
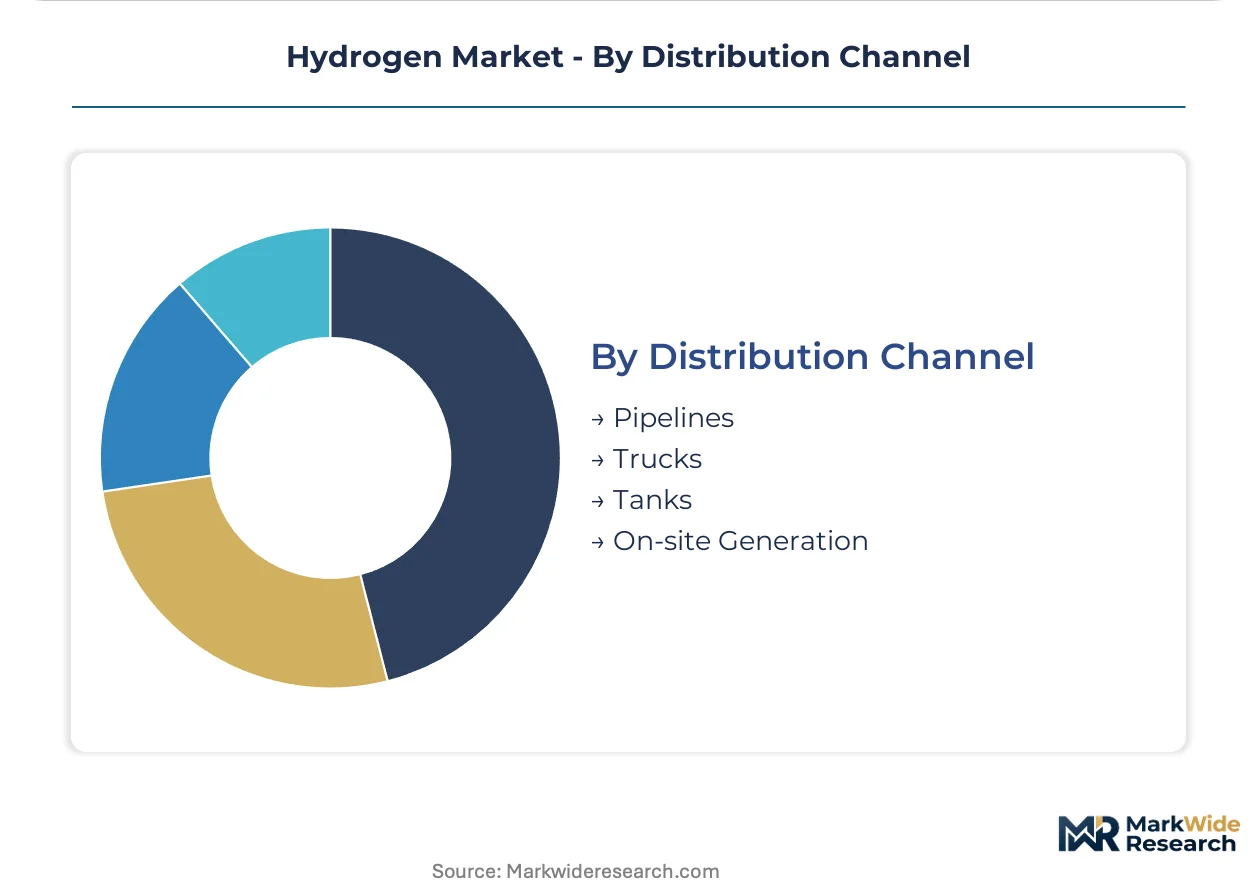
Pipelines retain the highest throughput volumes, with on-site generation showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Gulf Coast hydrogen pipeline corridor anchors global industrial hydrogen distribution, with Rotterdam and Hamburg emerging as critical import aggregation points for European green hydrogen offtake.
United States
Texas and Louisiana electrolyzer deployments leverage IRA Section 45V production tax credits to undercut conventional production economics. FERC interstate pipeline tariffs govern hydrogen transport across state lines. The Gulf Coast corridor concentrates blue hydrogen production with carbon capture infrastructure serving regional refinery demand.
Germany
Heavy transport operators scale fuel cell truck pilots under EU Green Deal renewable fuel blending mandates. The EU F-Gas Regulation revision tightens fluorinated gas containment standards for electrolyzer cooling systems. Industrial clusters in North Rhine-Westphalia and Hamburg import terminal infrastructure aggregate demand for multiple chemical offtakers.
China
Jiangsu and Zhejiang provinces dominate electrolyzer stack and membrane manufacturing scale, pulling project development toward East Asian supply chains. Dual carbon goals tighten emission intensity ceilings for coal gasification-based production. Domestic industrial clusters concentrate syngas-based hydrogen extraction for chemicals and steel applications.
Japan
METI hydrogen roadmap guarantees demand pools through Kobe and Yokohama import terminal construction for Australian and Middle Eastern exporters. JIS standards govern equipment certification and end-use permitting. The Kanto region concentrates fuel cell deployment for stationary power and early mobility applications.
India
National Hydrogen Mission PLI schemes offer capital subsidies for domestic electrolyzer gigafactory establishment through 2030. BIS certification requirements shape equipment procurement specifications for project developers. Gujarat and Maharashtra industrial corridors anchor captive on-site generation for steel and chemicals feedstock demand.
Hydrogen Market Vendor Landscape
Global majors compete with regional champions across electrolyzer technology and industrial gas distribution networks. The market structure tiers between integrated industrial gas conglomerates with pipeline infrastructure and specialized electrolyzer OEMs competing for green hydrogen tenders. Three archetypes dominate: legacy industrial gas distributors with backward integration into production, pure-play electrolyzer technology vendors, and energy majors diversifying into hydrogen supply. Competitive moves concentrate on strategic partnerships for offtake contracting and capacity expansion in electrolyzer manufacturing.
Within the integrated industrial gas tier, Linde plc, Air Liquide, and Air Products and Chemicals, Inc. represent established infrastructure players. These companies occupy positions anchored by pipeline network density and long-term refinery supply relationships. Siemens Energy AG exemplifies the technology-specialist archetype, competing for European green hydrogen tenders through PEM electrolyzer offerings. The competitive dynamic situates industrial gas incumbents with captive distribution assets against technology vendors seeking to displace steam methane reforming through electrolyzer cost deflation.
| Leading Market Players |
|---|
| Linde plc |
| Air Liquide |
| Air Products and Chemicals, Inc. |
| Siemens Energy AG |
| Cummins Inc. |
| Plug Power Inc. |
| BP |
| Ballard Power Systems |
| ENGIE SA |
| Others |
Supply Flow & Price Mechanics
Sovereign-backed producers in China and the Middle East anchor supply-side concentration, compressing electrolyzer stack pricing while European offtakers absorb carbon border adjustment premiums. This ownership pattern transmits directly into contract structures, with state-linked developers offering decade-long fixed-price offtake terms unavailable to privately financed competitors.
Pricing Analysis
Input-cost pass-through from iridium and platinum group metals governs PEM electrolyzer stack quotations, with catalyst loading specifications driving three-tier pricing structure across premium, standard, and economy certification levels. Price differentiation rests on carbon intensity certification tier and stack durability guarantee duration. Cost compression in alkaline electrolyzer segments intensifies because Chinese manufacturing scale erodes Western OEM margins. Refinery offtakers in Rotterdam and Houston exhibit highest price sensitivity, while Japanese import terminals under METI contracts show lowest.
Supply Chain Analysis
Dual-sourcing requirements from European project developers mandate qualified suppliers in China, Germany, and South Korea for membrane electrode assemblies and bipolar plates. Raw material dependencies center on iridium catalysts from South African mining operations, titanium coatings from Japanese metal processors, and perfluorinated membranes from Belgian and American chemical plants. Single-source vulnerability concentrates in Jiangsu province electrolyzer stack manufacturing clusters. Distribution runs through Rotterdam and Hamburg import terminals aggregating supply for multiple industrial offtakers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrolyzer cost deflation and carbon intensity premium capture frame this market as a margin-expansion story. Stack production automation and iridium loading reduction enable tier upgrades without proportional cost increases.
For Market Incumbents: Anchor pipeline network density through long-term refinery supply renewals in the US Gulf Coast and North Rhine-Westphalia. Defend against pure-play electrolyzer OEMs by accelerating backward integration into renewable power purchase agreements. Prioritize certification investment for EU Green Deal delegated acts compliance to lock in transport fuel blending mandates. For New Entrants and Emerging Players: Industrial gas distributors represent the most accessible channel partner type for bypassing incumbent pipeline advantages. White-space targets concentrate on India's National Hydrogen Mission PLI scheme and captive on-site generation for Gujarat steel corridors. Penetrate through modular electrolyzer skids sized for 10-50 megawatt industrial clusters rather than utility-scale competition. For Investors and Strategic Acquirers: Energy majors diversifying from upstream oil and gas are the most active acquirer in this space, seeking electrolyzer technology access and offtake contract pipelines. Long-term viability favors targets with certified low-carbon hydrogen production and mass-balance certificate infrastructure. Watch EU carbon border adjustment mechanism implementation stringency as the inflection indicator for contract repricing velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Electrolyzer Gigafactory Establishment | Indian PLI subsidies and Chinese manufacturing scale reshape cost curves for project developers. |
| Carbon Capture Integration | Blue hydrogen production with carbon capture secures IRA Section 45V credits for Gulf Coast developers. |
| Import Terminal Infrastructure | Rotterdam and Hamburg terminal aggregation concentrates contracting power with port authorities. |
| Fuel Cell Stack Durability Guarantees | 25,000-hour specifications from Daimler Truck and Volvo Group drive catalyst layer R&D investment. |
| Renewable Power Purchase Agreements | Spanish and Italian solar-wind hybrid projects anchor green hydrogen cost competitiveness for European tenders. |
Methodological Framework
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining interviews with electrolyzer OEM technical directors, refinery procurement leads, renewable project developers, and port authority infrastructure planners. Secondary validation draws from EIA hydrogen production databases, IEA hydrogen technology reports, EU delegated acts filings, and FERC interstate pipeline tariff records. Bottom-up project pipeline aggregation triangulates against top-down policy target analysis.
Rate-of-change decomposition separates electrolyzer capex deflation, renewable power price trajectories, and carbon border adjustment pass-through across the projection horizon. Segmentation dimensions include production method, application technology, end-user industry, and regional regulatory framework. CAGRs derive from installed capacity buildout curves and offtake contract pricing trends. Industry-specific inputs incorporate stack manufacturing learning rates and iridium spot price volatility assumptions.
Revisions become necessary when EU Green Deal carbon intensity thresholds tighten, Chinese export credit terms shift, or renewable power curtailment rates in Southern Europe deviate from baseline assumptions. Deviation in electrolyzer manufacturing cost curves would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydrogen Energy
Hydrogen Storage Technology Market
Hydrogen Energy
High-Pressure Hydrogen Tanks Market
Hydrogen Energy
Blue Hydrogen Market
Hydrogen Energy
Hydrogen Liquefaction Unit Market
Hydrogen Energy
USA Hydrogen Electrolyzer Market
Hydrogen Energy
Hydrogen Purifiers Market
Hydrogen Energy
Hydrogen Purification Units Market
Hydrogen Energy
Merchant Hydrogen Market
Hydrogen Energy
Hydrogen Purification Technologies Market
Hydrogen Energy
Hydrogen Composite Tanks Market
Hydrogen Energy
Green Hydrogen Market
Hydrogen Energy
Green Hydrogen Storage Technology Market
Hydrogen Energy
Liquid Organic Hydrogen Carrier (LOHC) Market
Hydrogen Energy
Europe Clean Hydrogen Market
Hydrogen Energy
Asia Pacific Liquid Hydrogen Market
Hydrogen Energy
Hydrogen Purification Market