
 Photovoltaic Hydrogen Production Market | 2026-2036
Photovoltaic Hydrogen Production Market Size, Share, and Industry Trends Forecast 2026-2036
Photovoltaic Hydrogen Production Market Insights
The direct-to-utility procurement channel is rewriting how electrolyzer vendors secure multi-year offtake contracts. Nel ASA leverages its manufacturing scale across European fabrication sites to anchor long-term supply agreements with national hydrogen programs. Siemens Energy AG competes through integrated power-to-gas architectures that bundle photovoltaic modules with proton exchange membrane stacks. Plug Power Inc. specializes in modular system designs that reduce installation complexity for distributed hydrogen hubs.
Photovoltaic hydrogen production couples solar electricity generation with water electrolysis to yield zero-carbon hydrogen, typically operating at system efficiencies between twelve and twenty-four percent depending on electrolyzer technology and solar irradiance conditions. The process serves industrial decarbonization, grid-scale energy storage, and transportation fuel supply chains. PEM electrolysis dominates current commercial deployments due to rapid response characteristics that match solar intermittency, while solid oxide electrolysis occupies a nascent position where waste heat integration can lift round-trip efficiency. Alkaline electrolysis sustains cost leadership in markets where capital expenditure sensitivity outweighs dynamic operating requirements. Photocatalytic water splitting remains confined to laboratory and pilot phases, though its potential to eliminate separate electrolyzer hardware reshapes long-term component demand projections.
The EU Green Deal and delegated acts under the Renewable Energy Directive establish product-level criteria that determine hydrogen eligibility for subsidies and import quotas. Germany's KBA and France's ANSM coordinate certification pathways for hydrogen fuel quality that affect cross-border equipment sales. The US IRA production tax credits and Japan's METI supply chain resilience programs create divergent compliance burdens for vendors serving multiple jurisdictions. Stakeholders must monitor how evolving green hydrogen definitions in Europe and North America reshape equipment specification requirements and project finance access before committing to platform standardization.
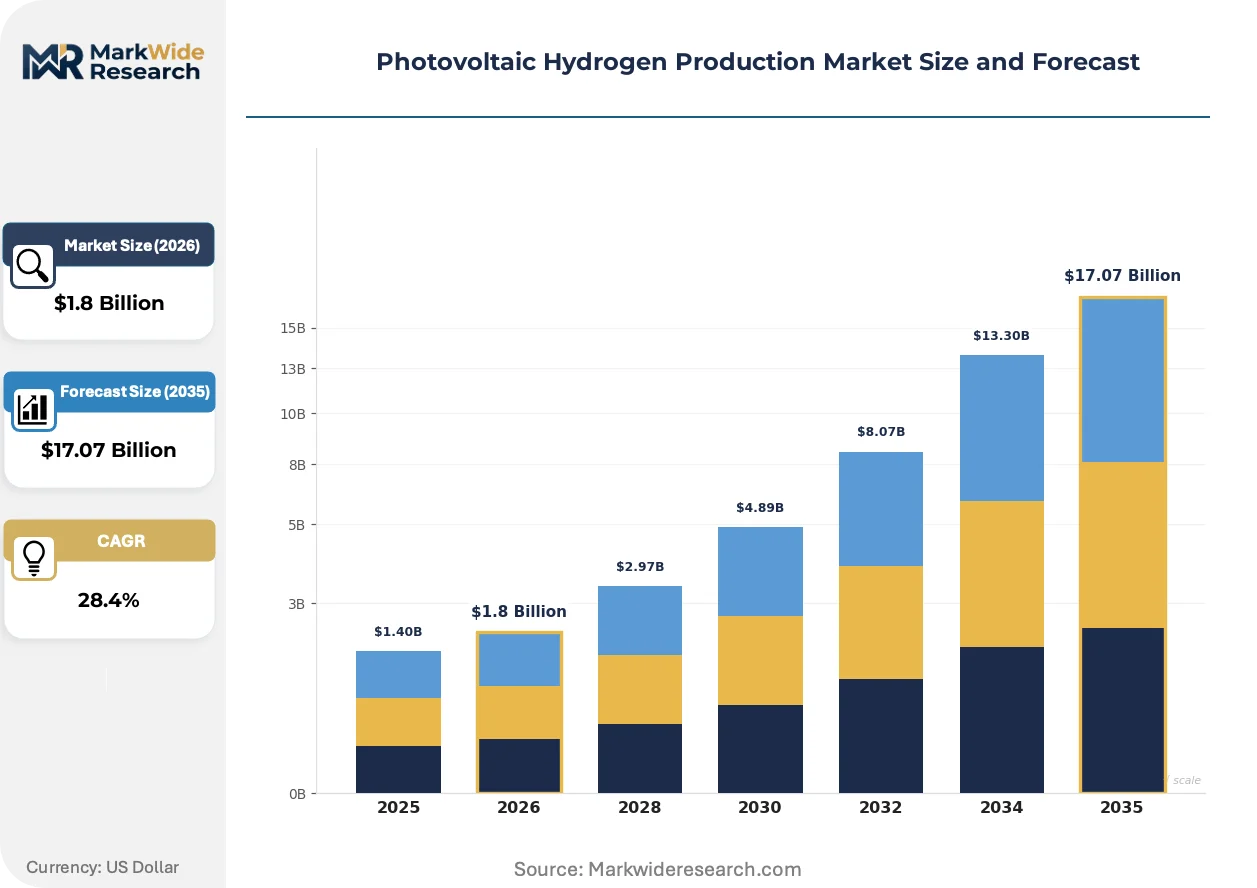
Market Dynamics
Utility-scale procurement contracts are compressing electrolyzer vendor margins while accelerating technology maturation cycles across the photovoltaic hydrogen production value chain.
Growth Catalysts
- EU Green Deal Delegated Acts:The Renewable Energy Directive's product-level criteria create subsidy eligibility thresholds that pull industrial offtake toward certified green hydrogen production pathways.
- Desert solar irradiance clusters:Concentrated deployment in Australia, Saudi Arabia, and Chile exploits capacity factors above twenty-five percent to improve electrolyzer utilization economics.
- Proton exchange membrane stacks:Rapid response characteristics match solar intermittency patterns better than alkaline alternatives, enabling dynamic operating profiles that maximize renewable energy capture.
Market Restraints
- Capital intensity of solid oxide electrolysis:High-temperature ceramic stack manufacturing requires specialized supply chains concentrated in Japan and Germany.
- Platinum group metal dependency:PEM catalyst costs tie system economics to volatile palladium and iridium spot markets with South African supply concentration.
- Grid interconnection queues:Utility-scale projects face multi-year connection delays in Germany and California that defer revenue realization.
Strategic Opportunities
- Industrial heat integration:Solid oxide electrolysis convergence with steel and cement plant waste heat streams lifts round-trip efficiency above sixty percent.
- Japan METI supply chain resilience programs:Domestic content requirements create captive demand for localized electrolyzer fabrication and photovoltaic module assembly.
- Off-grid mining operations:Remote sites in Western Australia and Chile's Atacama deploy containerized systems to displace diesel without transmission infrastructure.
Industry Challenges
- Electrolyzer stack degradation modeling:Limited operational history at solar-coupled duty cycles complicates warranty pricing and project finance due diligence.
- Cross-border certification reciprocity:Divergent hydrogen fuel quality standards between Germany's KBA and France's ANSM fragment equipment specification requirements.
- Electrochemical engineering talent scarcity:Specialized workforce for membrane electrode assembly production concentrates at a handful of European and Japanese research institutions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Photovoltaic Hydrogen Production Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $17.07 Billion |
| CAGR (2026 – 2036) | 28.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: PEM Electrolysis, Alkaline Electrolysis, Solid Oxide Electrolysis, Photocatalytic Water Splitting Application: Fuel Cells, Industrial Chemicals, Energy Storage, Power Generation Component: Electrolyzers, Photovoltaic Modules, Power Electronics, Balance of System End User: Utilities, Manufacturing, Transportation, Residential |
| Companies Covered | Nel ASA, Linde, Air Liquide S.A., Enapter, AES Corporation, Air Products and Chemicals, Inc., Plug Power Inc., SunHydrogen Inc., Siemens Energy AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Photovoltaic Hydrogen Production Market Trends and Innovations
Digital control architectures and policy-driven subsidy redesign are reconfiguring how photovoltaic hydrogen production systems integrate with industrial demand centers.
Advanced power electronics with embedded predictive algorithms are digitizing solar-to-hydrogen conversion efficiency by enabling real-time load matching between fluctuating irradiance and electrolyzer operating curves. Industrial chemical producers in the Netherlands and Texas are piloting these systems to minimize curtailment losses. The technology is digitizing project return profiles by compressing payback timelines and enabling smaller minimum viable scale deployments.
The US IRA production tax credits establish technology-neutral incentive tiers that reward higher carbon intensity reductions with larger credit values. This structure favors projects combining new-build solar with greenfield electrolysis over retrofits of existing renewable assets. Developers in Texas and Arizona are restructuring project ownership to maximize credit capture while navigating IRS guidance on prevailing wage and apprenticeship requirements.
Direct corporate offtake agreements are displacing merchant hydrogen sales as the primary revenue model for utility-scale projects. Energy-intensive manufacturers in Germany and Japan are signing fifteen-to-twenty-year contracts to lock in supply for ammonia and methanol production. This shift concentrates counterparty risk assessment in project finance structures and favors developers with investment-grade offtake partners over pure-play merchant developers.
Photovoltaic Hydrogen Production Market Segmentation
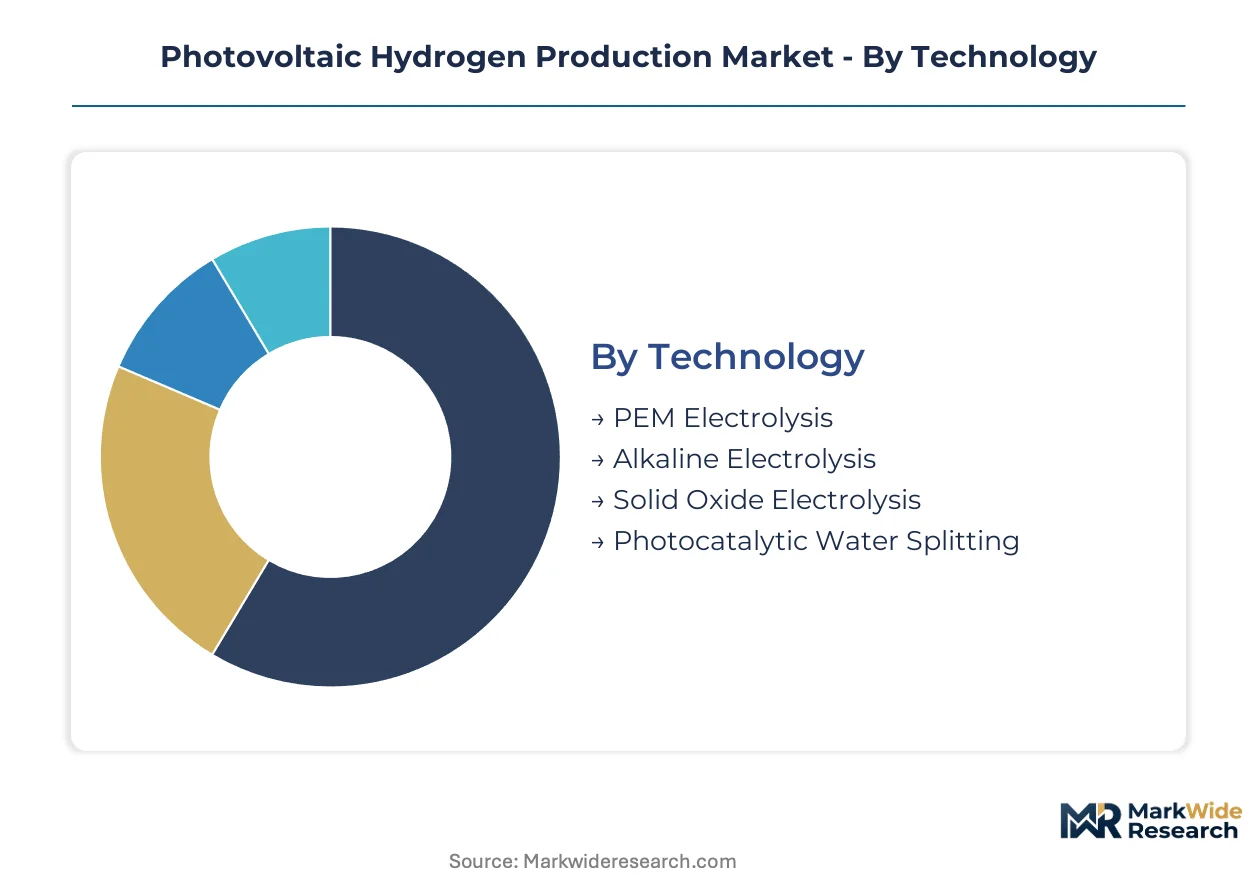
Segmentation in photovoltaic hydrogen production reveals how technology choices cascade through component procurement, application economics, and end-user contracting structures. Understanding these divides exposes where capital concentrates and where margins compress across the value chain.
Technology:
Cycle times vary dramatically across electrolyzer technologies, with stack replacement intervals spanning three years for alkaline systems to seven-plus years for emerging solid oxide platforms.
- PEM Electrolysis:Proton exchange membrane stacks utilize platinum-group catalysts and perfluorinated membranes to achieve rapid cold-start capability under ten seconds. Demand concentrates in German utility-scale deployments where EU Green Deal certification requirements favor dynamic response profiles that match solar intermittency.
- Alkaline Electrolysis:Liquid potassium hydroxide electrolyte systems operate without precious metal catalysts, trading slower ramp rates for capital cost advantages. Industrial chemical producers in India and China deploy these for baseload ammonia synthesis where steady-state operation dominates.
- Solid Oxide Electrolysis:High-temperature ceramic cells achieve superior efficiency when integrated with industrial waste heat streams. Japanese steelmakers pilot these for hydrogen injection into blast furnace operations.
- Photocatalytic Water Splitting:Direct semiconductor-mediated water splitting eliminates separate electrolyzer hardware entirely. Australian and Dutch research consortia advance tandem cell architectures toward pilot demonstration.
Alkaline electrolysis anchors the volume base while solid oxide electrolysis gains share at the steepest rate among commercial technologies.
Application:
Cost tiers separate applications by hydrogen purity requirements and delivery pressure specifications, with fuel cells commanding premium grades versus industrial chemical tolerance for lower specifications.
- Fuel Cells:Mobility and stationary power applications demand 99.97% purity hydrogen at 350-700 bar delivery pressure. Japanese transportation operators and German freight consortia procure dedicated production assets to secure supply chain control.
- Industrial Chemicals:Ammonia synthesis and methanol production consume hydrogen at massive scale with less stringent purity thresholds. Saudi Arabian and Chilean project developers target this segment for offtake contract security.
- Energy Storage:Power-to-gas systems buffer renewable curtailment through hydrogen injection into salt caverns or pipeline networks. Texas and California grid operators evaluate these for seasonal storage arbitrage.
- Power Generation:Gas turbine blending and fuel cell reconversion enable electricity output from stored hydrogen. South Korean utilities test these configurations for grid balancing services.
Industrial chemicals capture the dominant revenue share while fuel cell applications demonstrate the most rapid demand expansion trajectory.
Component:
Supply concentration varies sharply across the bill of materials, with electrolyzer stacks exhibiting tight vendor oligopoly versus fragmented photovoltaic module sourcing.
- Electrolyzers:Stack and balance-of-plant assemblies represent forty to sixty percent of system capital cost depending on technology selection. European and Japanese fabricators dominate membrane electrode assembly production.
- Photovoltaic Modules:Crystalline silicon or thin-film panels supply DC power to electrolyzer inputs. Chinese manufacturers control polysilicon refining and wafer production capacity.
- Power Electronics:DC-DC converters and inverters condition variable solar output for electrolyzer operating curves. German and American suppliers lead inverter efficiency benchmarks.
- Balance of System:Compression, storage, and dispensing equipment completes integrated installations. Local fabrication prevails for pressure vessels and piping to satisfy transport cost economics.
Photovoltaic modules constitute the largest single cost line while power electronics deliver the steepest efficiency improvement curve.
End User:
Customer type determines contracting structures, with utilities preferring long-term power purchase agreements and manufacturers seeking direct asset ownership.
- Utilities:Grid operators and renewable developers integrate solar-hydrogen assets for storage arbitrage and green certificate generation. Australian and Saudi Arabian national utilities lead procurement scale.
- Manufacturing:Steel, cement, and chemical producers deploy captive production for process heat and feedstock decarbonization. German industrial consortia aggregate demand through joint venture structures.
- Transportation:Fleet operators and fuel retailers invest in distributed hydrogen hubs for heavy-duty vehicle refueling. California and Japan subsidize station network buildout.
- Residential:Single-home electrolyzer systems paired with rooftop solar serve early adopter markets. Dutch and German pilot programs test neighborhood-scale microgrids.
Manufacturing anchors current demand volume while transportation end users expand most quickly as fuel cell vehicle deployment accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's KBA anchors the regulatory framework that shapes equipment certification pathways across the largest European demand center for solar-powered electrolysis systems.
Germany
Industrial consortia in the Rhine-Ruhr and chemical corridors along the Rhine drive captive hydrogen demand for steel and ammonia decarbonization. The EU Green Deal delegated acts under the Renewable Energy Directive compress project approval timelines and establish subsidy eligibility thresholds. Bavarian electrolyzer fabrication clusters and Hamburg port hydrogen import terminals anchor deployment infrastructure.
United States
Texas and Arizona developers restructure project ownership to maximize IRA production tax credit capture while navigating prevailing wage requirements. The IRS and FERC coordinate guidance on credit stacking and grid interconnection protocols. Permian Basin solar-electrolysis hubs and California refinery corridor deployments concentrate early commercial scale.
Japan
METI supply chain resilience programs create captive demand for localized electrolyzer fabrication and photovoltaic module assembly. The country's national hydrogen regulator coordinates with industrial consortia to establish fuel quality standards for transportation applications. Kansai and Kyushu industrial zones pilot steel mill hydrogen injection and port fueling infrastructure.
Saudi Arabia
NEOM and Red Sea coastal zones exploit capacity factors above twenty-five percent to improve electrolyzer utilization economics. The national industrial development authority channels sovereign capital toward gigawatt-scale green ammonia export projects. Jubail industrial city and Yanbu port clusters integrate solar-hydrogen with existing petrochemical infrastructure.
Australia
Western Australian mining operations deploy containerized systems to displace diesel without transmission infrastructure. The national renewable energy agency coordinates funding for pilot demonstrations in the Pilbara and Queensland hydrogen export zones. Gladstone port and Kwinana industrial precincts anchor east and west coast production corridors.
Photovoltaic Hydrogen Production Market Competitive Landscape
Integrated energy conglomerates and specialized electrolyzer fabricators split the market along technology bundling versus component purity lines. The vendor base concentrates around membrane electrode assembly supply chains in Europe and Japan, with Chinese photovoltaic module producers controlling upstream power generation inputs. Strategic archetypes include full-stack integrators bundling solar and electrolyzer hardware, pure-play stack specialists licensing core technology, and industrial gas incumbents leveraging distribution infrastructure. Capacity expansion and strategic partnerships dominate competitive moves as vendors secure multi-year offtake contracts with utility and manufacturing end users.
Among European-based fabricators, Nel ASA and Siemens Energy AG occupy positions that exemplify divergent integration strategies. Plug Power Inc. represents the modular system design archetype targeting distributed hydrogen hubs. Linde and Air Liquide S.A. anchor the industrial gas incumbent tier, leveraging existing hydrogen distribution networks and customer relationships. AES Corporation and Air Products and Chemicals, Inc. exemplify utility-scale project developers restructuring ownership to capture policy incentives.
| Leading Market Players |
|---|
| Nel ASA |
| Linde |
| Air Liquide S.A. |
| Enapter |
| AES Corporation |
| Air Products and Chemicals, Inc. |
| Plug Power Inc. |
| SunHydrogen Inc. |
| Siemens Energy AG |
| Others |
Pricing and Supply Chain Analysis
Chinese polysilicon refining and wafer production capacity concentrates upstream photovoltaic module supply, anchoring margin capture in downstream electrolyzer stack and balance-of-plant assemblies where European and Japanese fabricators maintain pricing power.
Pricing Analysis
Geographic price spreads widen between German utility-scale deployments and Australian mining-site containerized systems, reflecting divergent certification burdens and logistics costs. Three-tier pricing structure across premium PEM, standard alkaline, and emerging solid oxide levels separates buyers by response-time requirements and purity specifications. Cost compression in alkaline systems intensifies because Chinese manufacturers scale electrolyzer stack output for ammonia synthesis baseload. Industrial chemical producers exhibit highest price sensitivity, while Japanese transportation operators absorb premiums for 99.97% purity hydrogen at 700 bar delivery pressure.
Supply Chain Analysis
Upstream feedstock for proton exchange membrane stacks draws from South African platinum group metal mines and Japanese ceramic substrate fabricators, tethering system economics to volatile palladium and iridium spot markets. Chinese polysilicon refiners and German inverter suppliers anchor the photovoltaic power generation tier. Single-source vulnerability concentrates in membrane electrode assembly production at a handful of European and Japanese research institutions. Distribution runs through direct-to-utility procurement channels and long-term corporate offtake agreements with energy-intensive manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics in photovoltaic hydrogen production are shifting toward interoperability standards that determine subsidy eligibility and equipment certification reciprocity across the EU Green Deal and US IRA frameworks.
For Market Incumbents: Insulate membrane electrode assembly supply chains through backward integration into perfluorinated membrane production or captive catalyst recovery facilities. Secure long-term offtake contracts with investment-grade industrial chemical producers before emerging solid oxide electrolysis vendors achieve waste heat integration cost parity. Prioritize certification investment in EU Green Deal delegated acts compliance to maintain subsidy access.
For New Entrants and Emerging Players: Build out distributed hydrogen hub deployments in Western Australian mining corridors and Chilean Atacama off-grid sites where transmission infrastructure gaps create white-space opportunities. Target containerized system designs that reduce installation complexity for diesel displacement applications. Pursue joint venture structures with national renewable energy agencies to secure pilot demonstration funding.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed electrolyzer fabricators that scaled manufacturing capacity ahead of utility-scale procurement contract maturation. Five-to-ten year viability hinges on technology-neutral incentive tier navigation and prevailing wage requirement compliance. Monitor IRS guidance on IRA credit stacking and apprenticeship thresholds as the inflection signal for project ownership restructuring viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout | Gigawatt-scale green ammonia export projects in NEOM anchor Saudi sovereign capital deployment. |
| Backward Integration | In-house platinum group metal catalyst production reduces exposure to South African supply concentration. |
| Technology Licensing | Proton exchange membrane stack licensing to Japanese fabricators accelerates METI supply chain localization. |
| Long-term Supply Agreement | Fifteen-to-twenty-year corporate offtake contracts with German steel consortia concentrate counterparty risk assessment. |
| Green Certification Program | EU Green Deal delegated acts compliance determines hydrogen eligibility for subsidies and import quotas. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with utility planning officers, electrolyzer EPC contractors, industrial hydrogen procurement leads, and national renewable energy agency program directors. Secondary validation drew from IEA hydrogen project databases, FERC interconnection queue filings, EU delegated act regulatory texts, and SEC 10-K disclosures from integrated energy conglomerates. Bottom-up electrolyzer deployment tallies and top-down policy incentive quantification were triangulated to anchor market sizing.
Calibration against historical capacity installation rates and policy announcement timelines shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include electrolyzer technology type, application purity requirements, component cost tier, and end-user contracting structure. CAGRs were derived from fitted diffusion curves incorporating learning rate effects on stack manufacturing costs and solar module efficiency improvements. Forecast inputs included desert solar irradiance capacity factors and grid interconnection queue duration assumptions.
Sensitivities concentrate around EU Green Deal delegated act revisions, IRA guidance finalization, and platinum group metal price volatility. Cross-checking against IEA hydrogen project pipeline databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydrogen Energy
High-Pressure Hydrogen Tanks Market
Hydrogen Energy
Asia Pacific Liquid Hydrogen Market
Hydrogen Energy
Partial Oxidation Blue Hydrogen Market
Hydrogen Energy
Blue Hydrogen Market
Hydrogen Energy
35MPa High Pressure Hydrogen Storage Cylinders Market
Hydrogen Energy
Green Hydrogen Dispensing Equipment Market
Hydrogen Energy
Hydrogen-Cooled Turbine Generator Market
Hydrogen Energy
Europe Hydrogen Generation Market
Hydrogen Energy
Hydrogen Storage Technology Market
Hydrogen Energy
US Hydrogen Fueling Station Market
Hydrogen Energy
United States Hydrogen Generation Market
Hydrogen Energy
India Hydrogen Market
Hydrogen Energy
Gray Hydrogen Market
Hydrogen Energy
Global Hydrogen Electrolyzers Market
Hydrogen Energy
Hydrogen Purifiers Market
Hydrogen Energy
Asia-Pacific Clean Hydrogen Market