
 Italy Renewable Energy Market | 2026-2036
Italy Renewable Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Renewable Energy Market Outlook
Modular solar-plus-storage bundling is realigning procurement decisions across Italian commercial and utility buyers. Enel Green Power SpA leverages its integrated development platform to dominate large-scale photovoltaic deployment in Sicily and Basilicata. RWE Renewables Italia anchors its position through offshore wind pipeline advancement in the Adriatic and Tyrrhenian Seas. ERG SpA differentiates via onshore wind specialization across central and southern Italy.
Italy renewable energy encompasses electricity generation from solar, wind, biomass, and hydropower assets connected to the national grid or operating in captive configurations, with photovoltaic modules typically rated between 400-700 Wp and wind turbines scaling from 2-6 MW onshore. Its primary purpose is decarbonizing Italy's power mix while reducing dependence on imported natural gas. Solar photovoltaic leads installed capacity additions, though offshore wind represents the fastest-expanding technology segment as floating platform designs mature. Utility-scale applications command the largest share of capital deployment, while residential rooftop systems concentrate margin pools in the fragmented installer network across northern regions.
Italy's energy transition operates under EU Green Deal targets, CE marking for equipment certification, and GSE (Gestore Servizi Energetici) incentive administration, with the National Recovery and Resilience Plan channeling EU funds into grid reinforcement and renewable auctions. ARERA regulates network tariffs and connection priorities, shaping developer returns and project timelines. Stakeholders must monitor auction mechanism revisions and regional grid saturation thresholds to sequence capital commitments effectively.
Market Dynamics
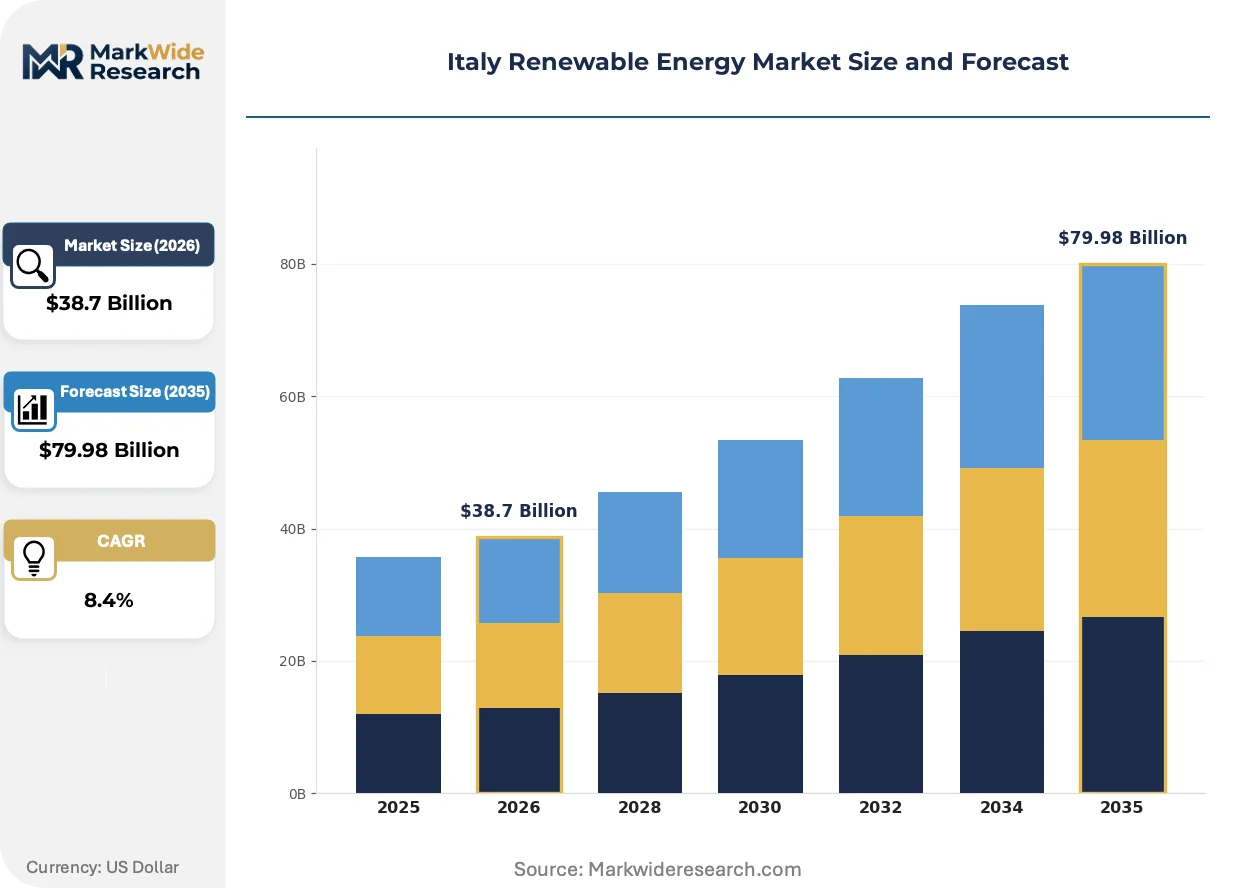
EU Green Deal mandates and Italy's National Recovery and Resilience Plan are compressing project development timelines while forcing simultaneous grid reinforcement and renewable capacity expansion. This dual-pressure environment rewards developers with pre-permitted land positions and existing grid connection agreements.
Growth Catalysts
- EU Green Deal binding targets:The framework mandates member states achieve climate neutrality by 2050, with intermediate 2030 renewables thresholds that Italy must hit through accelerated solar and wind deployment.
- Southern solar irradiance concentration:Sicily, Puglia, and Sardinia receive 1,800-2,100 equivalent peak sun hours annually, concentrating utility-scale photovoltaic development in these regions.
- Industrial PPA expansion:Manufacturing buyers from automotive, chemicals, and food processing sectors are signing 10-15 year power purchase agreements directly with renewable developers.
Market Restraints
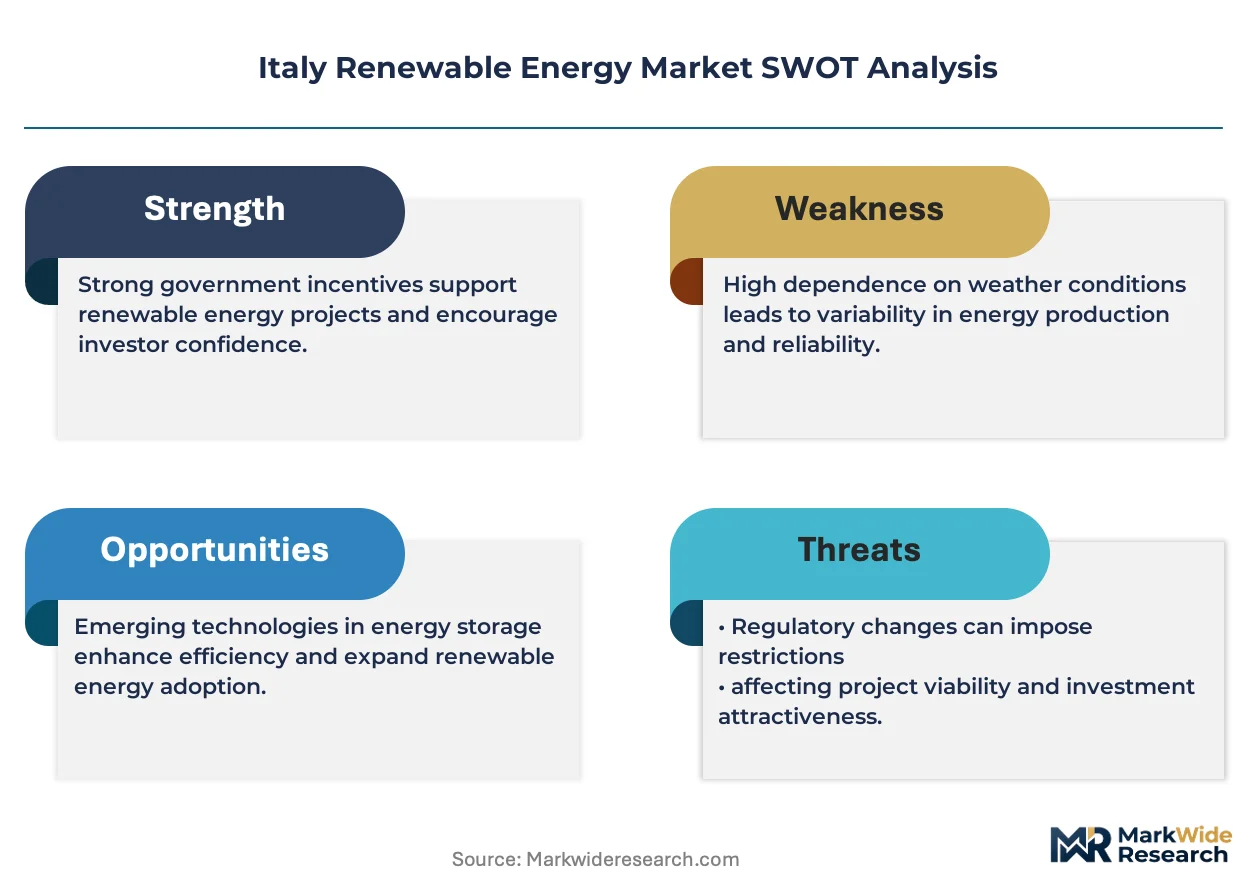
- Grid saturation in high-irradiance zones:Terna reports connection queues exceeding 100 GW in southern regions, forcing developers toward grid-constrained locations with lower resource quality.
- Domestic steel and polysilicon supply gaps:Italy lacks integrated photovoltaic manufacturing, creating import dependence on Chinese module and inverter supply chains.
- Permitting timeline volatility:Regional environmental impact assessments under Legislative Decree 104/2017 vary from 18 to 48 months depending on local authority capacity.
Strategic Opportunities
- Offshore wind licensing rounds:The Ministry of Environment has designated 12 zones in the Adriatic and Tyrrhenian Seas for floating platform development, with first-mover advantage available to bidders with marine engineering partnerships.
- Agrisolar convergence:Combining photovoltaic arrays with agricultural production is expanding into marginal farmland across Emilia-Romagna and Veneto, accessing dual revenue streams from energy and crop yields.
- Green hydrogen offtake contracts:Industrial clusters in Porto Marghera and Taranto are seeking renewable power for electrolyzer projects, creating anchor demand for otherwise merchant-exposed generation assets.
Industry Challenges
- Specialized technician shortages:Floating offshore wind installation requires marine electricians and subsea cable specialists that Italian technical institutes currently fail to produce at scale.
- Legacy grid infrastructure incompatibility:Central and northern distribution networks built for centralized thermal generation require expensive smart inverter and storage integration to accommodate distributed solar penetration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Renewable Energy Market |
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $79.98 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Solar, Wind, Biomass, Hydropower Application: Residential, Commercial, Industrial, Utility Scale Technology: Photovoltaic, Concentrated Solar Power, Offshore Wind, Geothermal End User: Households, Corporations, Governments, Energy Providers |
| Companies Covered | Plenitude (Eni Renewables), RWE Renewables Italia, Enel Green Power SpA, A2A Rinnovabili SpA, Engie Italia SpA, ERG SpA, FERA (Fri-El Green Power) SpA, EF Solare Italia SpA, Falck Renewables (Renantis) SpA, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Renewable Energy Market Strategic Shifts
Technology convergence between generation and storage assets is restructuring procurement economics for Italian utilities and large industrials. Developers now bundle photovoltaic modules with lithium-ion systems as standard offerings rather than separate transactions.
Bifacial photovoltaic modules paired with single-axis tracking systems are expanding into utility-scale projects across Basilicata and Apulia. Enel Green Power and mid-tier developers are deploying these configurations to capture 15-20% energy yield improvements over fixed-tilt monofacial alternatives. The technology is compressing levelized cost thresholds for projects competing in GSE auction rounds without subsidy support.
Italy's transposition of the EU Renewable Energy Directive II tightens sustainability criteria for biomass and biogas installations while accelerating permitting timelines for solar and wind. ARERA must now rule on connection priority disputes within 90 days, reducing developer uncertainty. The regulation most affects agricultural biogas operators in Lombardy and Veneto facing feedstock traceability requirements.
Corporate buyers are consolidating procurement through energy service companies rather than direct developer negotiations. Industrial groups in Milan-Turin-Genova triangle are outsourcing renewable sourcing to specialized intermediaries that aggregate distributed generation portfolios. This channel shift concentrates margin capture with platforms possessing grid balancing capabilities and regulatory expertise.
Italy Renewable Energy Market Segmentation
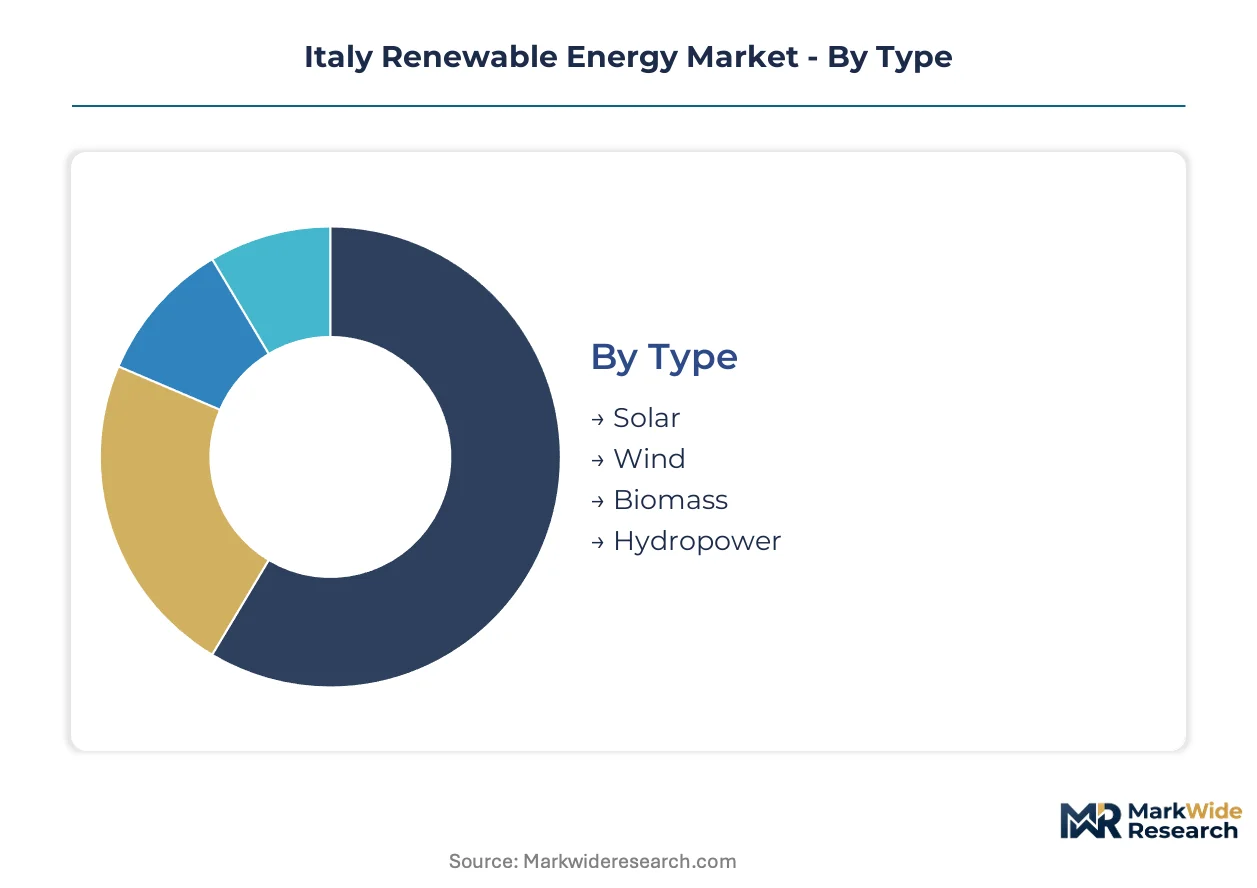
Segmentation in Italy's renewable energy market reveals how technology choices, scale economics, and buyer sophistication create distinct competitive arenas. Each dimension—type, application, technology, and end user—channels capital toward different risk-return profiles and regulatory pathways.
Type:
Standardized equipment dominates solar and wind, while biomass and hydropower require site-specific engineering that fragments procurement patterns.
- Solar:Photovoltaic modules rated 400-700 Wp form the standardized backbone of Italian deployment, with utility-scale arrays concentrating in Sicily and Puglia where GSE auction participation is highest. Southern irradiance advantages compress development timelines for projects competing without subsidy support.
- Wind:Onshore turbines scaling 2-6 MW anchor current capacity, though floating offshore platforms in the Adriatic and Tyrrhenian Seas are attracting marine engineering partnerships for licensing rounds. ERG SpA and RWE Renewables Italia dominate pipeline development across central and southern regions.
- Biomass:Agricultural biogas installations in Lombardy and Veneto face tightened EU Renewable Energy Directive II feedstock traceability requirements.
- Hydropower:Alpine run-of-river assets in northern regions provide baseload flexibility but face limited greenfield expansion due to environmental constraints.
Leading the category by volume: Solar. Expanding most quickly: Wind.
Application:
Scale determines financing structures, with residential rooftop systems fragmenting installer networks while utility-scale projects concentrate developer margins.
- Residential:Distributed rooftop photovoltaic systems concentrate margin pools across northern Italy's fragmented installer base, with households leveraging GSE net metering incentives.
- Commercial:Mid-scale solar-plus-storage bundling is restructuring procurement for Milan-Turin-Genova industrial clusters outsourcing to energy service companies.
- Industrial:Manufacturing buyers from automotive and chemicals sectors are signing 10-15 year power purchase agreements directly with Enel Green Power and mid-tier developers.
- Utility Scale:Large photovoltaic and offshore wind deployments command the largest capital commitments, with grid connection queues exceeding 100 GW in southern regions forcing developers toward constrained locations.
Utility-scale projects absorb the greatest capital deployment. Fastest growth trajectory: Industrial offtake contracts.
Technology:
Maturity gradients separate proven photovoltaic deployment from emerging floating offshore and geothermal applications requiring specialized supply chains.
- Photovoltaic:Bifacial modules paired with single-axis tracking systems are capturing 15-20% yield improvements across Basilicata and Apulia, compressing levelized cost thresholds for auction-competitive projects.
- Concentrated Solar Power:Thermal storage integration offers dispatchable renewable output, though high capital intensity limits deployment to Sicily's most irradiant zones.
- Offshore Wind:Floating platform designs are maturing for 12 designated zones in the Adriatic and Tyrrhenian Seas, with first-mover advantage available to bidders possessing marine engineering capabilities.
- Geothermal:Tuscany's Larderello field anchors existing capacity, with limited expansion potential due to geological constraints.
Photovoltaic technology leads installed capacity. Steepest expansion trajectory: Offshore wind.
End User:
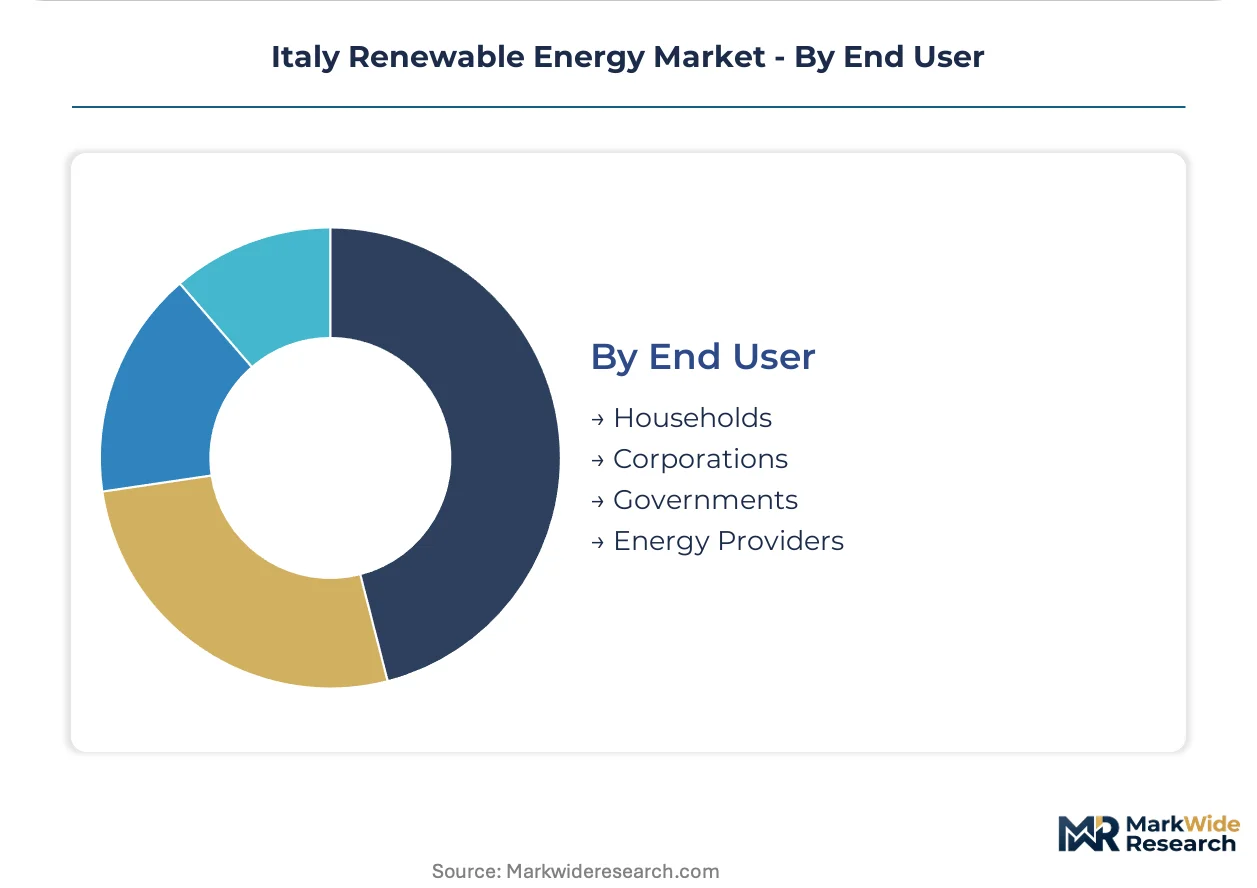
Buyer sophistication and contracting power create tiered procurement channels, from fragmented household decisions to centralized government tenders.
- Households:Northern Italian residential consumers drive distributed solar adoption through net metering, with procurement fragmented across regional installer networks.
- Corporations:Energy-intensive manufacturers are consolidating renewable sourcing through specialized intermediaries possessing grid balancing capabilities and ARERA regulatory expertise.
- Governments:Public sector procurement channels EU Recovery and Resilience Plan funds into grid reinforcement and renewable auction mechanisms administered by GSE.
- Energy Providers:Enel Green Power and integrated utilities leverage development platforms to dominate large-scale deployment, capturing margins from vertical control over permitting and grid connection.
Energy providers command the largest project pipelines. Gaining share fastest: Corporate buyers restructuring procurement through intermediaries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italy's renewable generation capacity concentrates in southern regions while industrial demand clusters in the north, creating transmission bottlenecks that shape development patterns across the peninsula.
Sicily
Sicily receives over 2,000 equivalent peak sun hours annually, attracting utility-scale photovoltaic arrays seeking unsubsidized auction competitiveness. GSE administers connection priority disputes under transposed EU Renewable Energy Directive II timelines. Catania and Agrigento provinces host bifacial tracking deployments that Enel Green Power leverages for yield optimization.
Puglia
Puglia's Murgia plateau offers flat terrain and minimal shading constraints for large solar parks competing in merchant power markets. ARERA regulates network tariffs that determine developer returns across the region's saturated grid nodes. Taranto industrial corridor anchors green hydrogen offtake demand from steel and chemical facilities seeking electrolyzer feedstock.
Sardinia
Sardinia combines high irradiance with substantial wind resources across its western coastlines, though submarine cable constraints limit export capacity to the mainland. Regional environmental impact assessments under Legislative Decree 104/2017 vary between 18 and 48 months depending on local authority staffing. Sassari and Oristano provinces concentrate onshore wind development where ERG SpA maintains specialized operational platforms.
Lombardy
Lombardy drives distributed solar adoption through residential net metering despite lower irradiance than southern counterparts. Agricultural biogas installations in the Po Valley face tightened EU Renewable Energy Directive II feedstock traceability requirements. Milan industrial triangle outsources renewable procurement to energy service companies possessing ARERA regulatory expertise and grid balancing capabilities.
Basilicata
Basilicata's sparse population density reduces land-use conflicts for utility-scale solar and onshore wind deployment. Terna reports manageable connection queues compared to saturated Sicilian and Puglian networks, accelerating project timelines. Potenza province hosts emerging agrivoltaic convergence projects combining photovoltaic arrays with marginal farmland cultivation.
Italy Renewable Energy Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across Italy's renewable energy market, creating tiered competitive dynamics where integrated utilities leverage vertical control over development pipelines. The vendor base spans multinational energy majors, domestic independent power producers, and emerging mid-tier developers with regional specialization. Three strategic archetypes dominate: integrated utilities with captive grid access, independent renewables specialists with technology focus, and oil-major spinoffs deploying balance-sheet capacity. Competitive intensity centers on pre-permitted land positions and existing grid connection agreements rather than equipment differentiation.
Among integrated utility platforms, Enel Green Power SpA exemplifies the scale-driven archetype through its dominance of large-scale Sicilian and Basilicata photovoltaic deployment. RWE Renewables Italia occupies a position within the multinational specialist tier, anchoring offshore wind pipeline advancement in Adriatic and Tyrrhenian licensing rounds. ERG SpA represents the focused pure-play model, concentrating onshore wind specialization across central and southern Italian regions where operational expertise compresses asset-level risk.
| Leading Market Players |
|---|
| Plenitude (Eni Renewables) |
| RWE Renewables Italia |
| Enel Green Power SpA |
| A2A Rinnovabili SpA |
| Engie Italia SpA |
| ERG SpA |
| FERA (Fri-El Green Power) SpA |
| EF Solare Italia SpA |
| Falck Renewables (Renantis) SpA |
| Others |
Value Chain & Pricing Dynamics
Polysilicon spot price indices from China cascade through Italian photovoltaic supply chains, compressing module procurement costs while creating tiered pricing structures that separate premium European-branded equipment from economy-tier Asian imports. This commodity-driven cost architecture feeds into project development economics where GSE auction participation thresholds determine viable pricing floors.
Pricing Analysis
Cost-down pressure on utility-scale solar EPC contracts accelerates because Chinese module manufacturers are absorbing margin compression to maintain European market share. Project-based long-term offtake agreements dominate utility procurement, while residential rooftop systems operate through transactional installer pricing. Price differentiation rests on CE certification tier and inverter brand pedigree. Industrial PPA buyers exhibit lowest price sensitivity due to carbon compliance mandates, whereas residential households in northern regions show acute sensitivity to upfront capital requirements.
Supply Chain Analysis
Direct-to-utility channels handle hyperscale developer demand while fragmented installer networks serve residential rooftop segments across Lombardy and Veneto. Manufacturing concentrates in China for polysilicon and module assembly, Germany for inverters, and South Korea for battery cell supply. Raw material dependencies include lithium carbonate, high-purity silicon, and rare earth magnets for turbine generators. Single-source vulnerability around Chinese polysilicon refining creates tariff exposure risk under EU anti-dumping enforcement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Italian renewable energy is consolidating around developers possessing pre-permitted land positions and grid connection agreements, as Terna's 100 GW southern queue forces weaker capitalized players toward resource-poor locations. Grid saturation pressures are accelerating exits among mid-tier developers lacking marine engineering partnerships for offshore wind licensing rounds.
For Market Incumbents: Hedge exposure to Chinese module supply chains through backward integration into European inverter manufacturing or captive polysilicon offtake agreements with Norwegian or German producers. Defend pipeline positions by accelerating agrivoltaic deployments in Basilicata where land-use conflicts remain minimal, insulating against southern grid saturation risks that threaten Sicilian and Puglian project viability.
For New Entrants and Emerging Players: The premium-to-economy pricing gap in floating offshore wind installation services offers entry opportunity for marine engineering specialists lacking Italian market presence. Target the Adriatic licensing zones where RWE and Enel Green Power have not yet consolidated contractor relationships. White-space exists in agrivoltaic EPC services across Emilia-Romagna marginal farmland. Go-to-market leverage rests on partnerships with agricultural cooperatives possessing land access rights.
For Investors and Strategic Acquirers: The window for entry favors developers with permitted offshore wind positions in Tyrrhenian Sea zones and operational onshore wind platforms in Sardinia. Long-term viability centers on vertical integration into grid balancing services and storage co-location capabilities. Acquisition target archetype: mid-tier developers with 500 MW+ pre-permitted solar pipelines in Basilicata. Signal to monitor: ARERA ruling timelines on connection priority disputes under 90-day mandates.
| Strategic Initiative | Industry Significance |
|---|---|
| Grid Connection Pre-Permitting | Securing Terna queue positions in southern regions compresses development timelines before saturation thresholds trigger. |
| Marine Engineering Partnership | Floating platform alliances unlock Adriatic and Tyrrhenian licensing rounds where specialized installation capabilities concentrate value capture. |
| Agrivoltaic Deployment | Dual revenue streams from energy and crop yields expand addressable land base in regions with lower irradiance competition. |
| Storage Co-Location Bundling | Lithium-ion integration with photovoltaic arrays addresses ARERA grid stability requirements while differentiating merchant power exposure. |
| Green Hydrogen Offtake Contracting | Electrolyzer feedstock agreements with Taranto and Porto Marghera industrial clusters anchor demand for otherwise merchant-exposed generation. |
Study Parameters
Document review covered GSE auction databases, Terna grid connection registries, and ARERA tariff rulings, complemented by interviews with utility planning officers, IPP project developers, EPC contractors, and grid operators across the Italian peninsula. Secondary validation drew from IEA renewable deployment trackers, EU Recovery and Resilience Plan disbursement records, and customs import data for photovoltaic equipment. Bottom-up project pipeline aggregation was cross-referenced against top-down capacity forecasts from regulatory filings.
Historical deployment trajectories were cross-referenced against panel input from project developers and equipment suppliers to establish baseline growth parameters across the projection horizon. Segmentation modeling incorporated fuel source, generation capacity tier, project scale, regulatory framework, and regional grid saturation status. CAGRs were derived through iterative reconciliation of capacity addition schedules with auction mechanism timelines and grid reinforcement investment flows. Forecast inputs included GSE incentive budget allocations and Terna transmission expansion commitments.
Inputs from developer interview programs and regulatory filing databases were available through the study window; gaps in real-time grid connection queue positioning introduce uncertainty bands around southern region deployment timelines. Forecasts reflect documented assumptions regarding ARERA ruling adherence and EU Green Deal target continuity. Periodic stress-testing of base assumptions against auction participation rates and module import price volatility is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Renewable Energy
Solar Thermal Water Heater Market
Renewable Energy
Solar Ceiling Fans Market
Renewable Energy
Peru Renewable Energy Market
Renewable Energy
Hybrid Solar Wind Diesel Market
Renewable Energy
South Africa Wind Energy Market
Renewable Energy
Finland Renewable Energy Market
Renewable Energy
Solar Lighting System Market
Renewable Energy
France Renewable Energy Market
Renewable Energy
China Solar Energy Market
Renewable Energy
Renewable Energy MRO Market
Renewable Energy
Middle East Renewable Energy Market
Renewable Energy
PV Water Heater Market
Renewable Energy
Singapore Renewable Energy Market
Renewable Energy
West Africa Renewable Energy Market
Renewable Energy
Ocean Energy Market
Renewable Energy
North America Solar Tracker Market