
 Liquid Hydrogen Tank Market | 2026-2036
Liquid Hydrogen Tank Market Size, Share, and Industry Trends Forecast 2026-2036
Liquid Hydrogen Tank Market Insights
The liquid hydrogen tank supply base is restructuring around a widening performance gap between aerospace-grade cryogenic systems and commodity industrial vessels. Chart Industries leverages in-house vacuum-insulation expertise to dominate high-specification spherical tanks for space launch applications. Linde plc anchors European demand through captive production of cylindrical tanks tied to its hydrogen refueling station deployments. Kawasaki Heavy Industries, Ltd. competes on manufacturing scale, extending its shipyard-composite capabilities into carbon-fiber pressure vessels for automotive and maritime hydrogen storage.
Liquid hydrogen tanks are double-walled, vacuum-insulated pressure vessels engineered to maintain hydrogen at minus 253 degrees Celsius with boil-off rates below 1% per day, serving as critical infrastructure for energy storage, propulsion, and industrial gas distribution. Spherical tanks command premium positioning in aerospace end-use where minimal surface-area-to-volume ratios reduce thermal ingress, while cylindrical tanks dominate automotive and industrial channels where packaging geometry aligns with vehicle chassis and facility footprints. Composite tanks, particularly carbon-fiber-reinforced polymer constructions, represent the fastest-growing material trajectory as weight reduction becomes decisive for mobile hydrogen applications.
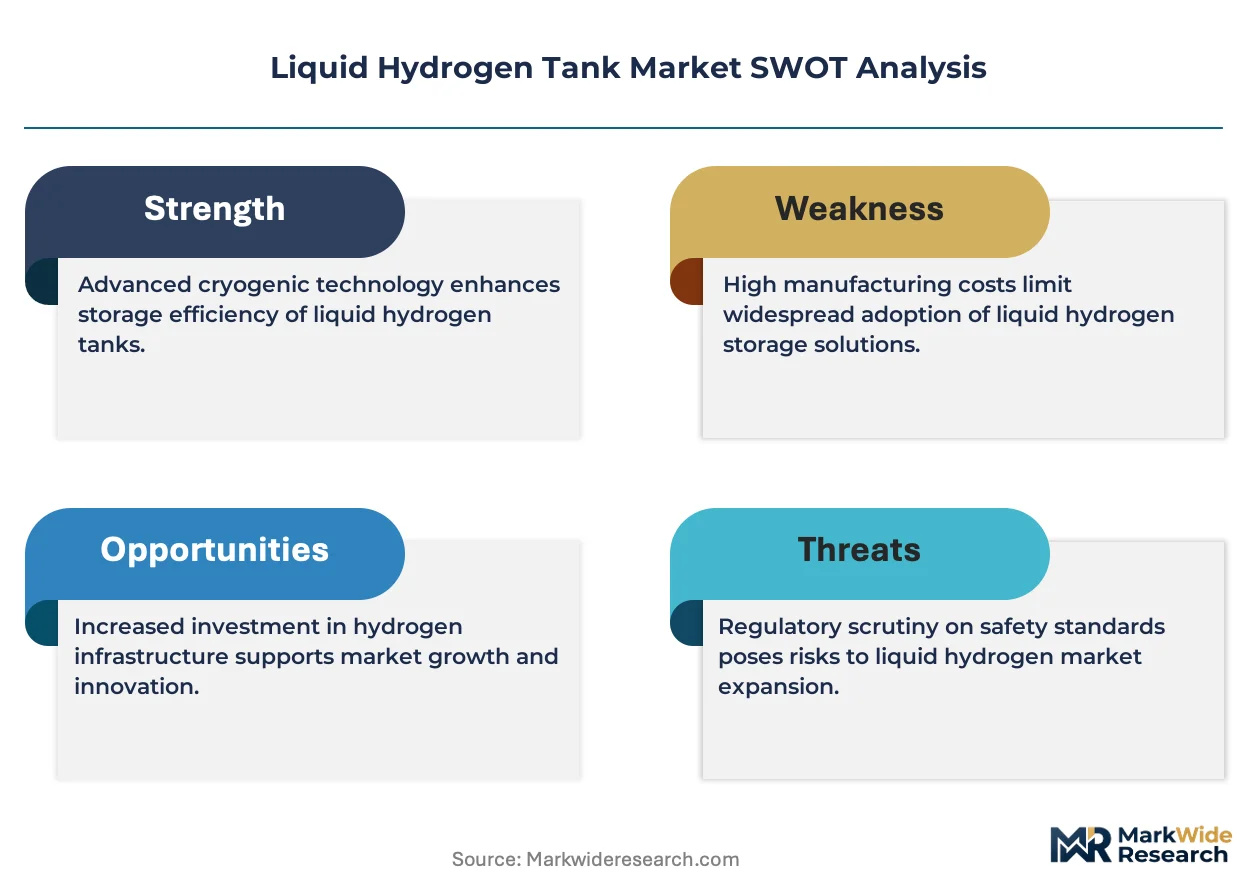
The US Department of Transportation's Pipeline and Hazardous Materials Safety Administration governs over-the-road liquid hydrogen transport vessel standards, while the European Pressure Equipment Directive mandates CE-marked conformity for tanks deployed across EU member states. Japan's Ministry of Economy, Trade and Industry enforces METI technical criteria for hydrogen fueling station storage systems, creating segmented certification pathways that fragment market access. Stakeholders must monitor evolving alignment between national hydrogen strategies and pressure equipment codes to anticipate which tank specifications will achieve cross-border portability.
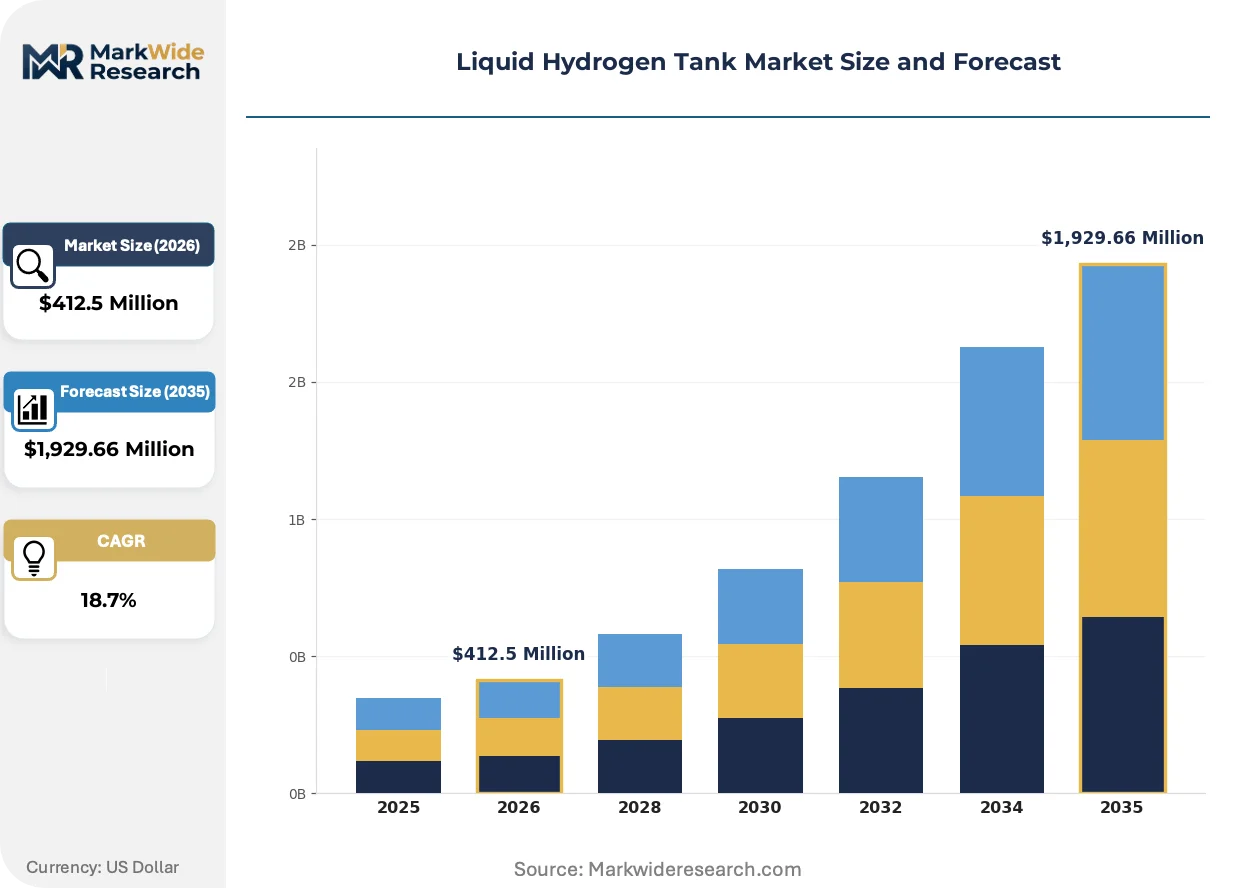
Market Dynamics
The liquid hydrogen tank market is bifurcating around a performance chasm: aerospace-grade cryogenic systems demand sub-1% boil-off rates and spherical geometries, while industrial vessels prioritize cylindrical footprints and cost-scalable manufacturing. This divergence is forcing suppliers to choose specialization lanes rather than serving both tiers.
Growth Catalysts
- Aerospace propulsion demand:Hydrogen-powered launch vehicles from SpaceX, Blue Origin, and emerging national programs are pulling spherical tank procurement with specifications that commodity industrial vessels cannot meet.
- US hydrogen hub deployment:The Department of Energy's regional clean hydrogen hubs are mandating storage infrastructure at scale, creating anchored demand for cylindrical tanks tied to refueling networks.
- ISO 19880-1 alignment:Harmonized gaseous and liquid hydrogen fueling standards are reducing certification friction for tanks crossing jurisdictional boundaries, accelerating cross-border equipment flows.
Market Restraints
- Helium supply volatility:Vacuum-insulation manufacturing depends on helium leak detection and purge cycles; price spikes in the helium spot market directly compress tank production margins.
- Stainless steel concentration:High-nickel alloy supply chains cluster around a limited set of European and Japanese metallurgical suppliers, creating input bottlenecks during aerospace procurement surges.
- Boil-off physics ceiling:Current multilayer insulation architectures approach theoretical thermal performance limits, constraining further efficiency gains without fundamental material breakthroughs.
Strategic Opportunities
- Maritime hydrogen bunkering:Port authorities in Rotterdam, Singapore, and Los Angeles are piloting liquid hydrogen fueling for deep-sea vessels, opening tank demand outside terrestrial mobility applications.
- Carbon-fiber composite scale-up:Automated fiber placement and resin transfer molding advances are collapsing the cost gap between metallic and composite pressure vessels for automotive series production.
- EU Green Deal hydrogen import corridors:Planned liquid hydrogen shipments from North Africa and the Middle East to European ports require dedicated maritime storage and regasification tank infrastructure.
Industry Challenges
- Cryogenic welding certification scarcity:Qualified technicians for orbital TIG welding of 300-series stainless steel are concentrated at a handful of aerospace suppliers, constraining production ramp rates.
- Multi-jurisdictional approval timelines:Tanks requiring simultaneous US DOT, EU PED, and Japan METI certifications face sequential rather than parallel review processes, extending time-to-revenue by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Liquid Hydrogen Tank Market |
| Market Size in 2026 | $412.5 Million |
| Market Size in 2035 | $1,929.66 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Spherical Tanks, Cylindrical Tanks, Cryogenic Tanks, Composite Tanks Material: Stainless Steel, Aluminum, Carbon Fiber, Glass Fiber End User: Aerospace, Automotive, Industrial, Research Institutions Distribution Channel: Direct Sales, Distributors, Online Sales, Others |
| Companies Covered | Chart Industries, Inc., Cryofab, Inc., Linde plc, Cryostar SAS, Taylor-Wharton International LLC, Air Liquide SA, INOXCVA, Kawasaki Heavy Industries, Ltd., Air Products and Chemicals, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Liquid Hydrogen Tank Market Trends and Innovations
Materials science advances and regulatory harmonization efforts are compressing the innovation cycle for liquid hydrogen containment. Three developments are restructuring competitive positioning across aerospace, automotive, and stationary storage applications.
Carbon-fiber-reinforced polymer (CFRP) tanks are absorbing the weight-reduction imperative for mobile hydrogen applications. Automotive OEMs and maritime vessel designers are specifying Type IV all-composite vessels at accelerating volumes. This material transition is absorbing market share from aluminum-lined hybrid designs in every segment where mass directly impacts range or payload economics.
The European Pressure Equipment Directive's 2024 recast is tightening conformity assessment procedures for cryogenic pressure vessels. Manufacturers must now demonstrate traceability through revised material certification chains. German tank fabricators serving hydrogen refueling station deployments are restructuring quality systems to maintain CE-marked access across EU member states.
Buyers are consolidating procurement around integrated storage-and-dispensing system contracts rather than discrete tank purchases. Hydrogen refueling station operators in California and Germany now specify performance guarantees covering boil-off rates, maintenance intervals, and uptime metrics. This bundling trend is most visible in the German industrial hydrogen corridor, where chemical producers negotiate total-cost-of-ownership agreements with tank suppliers.
Liquid Hydrogen Tank Market Segmentation
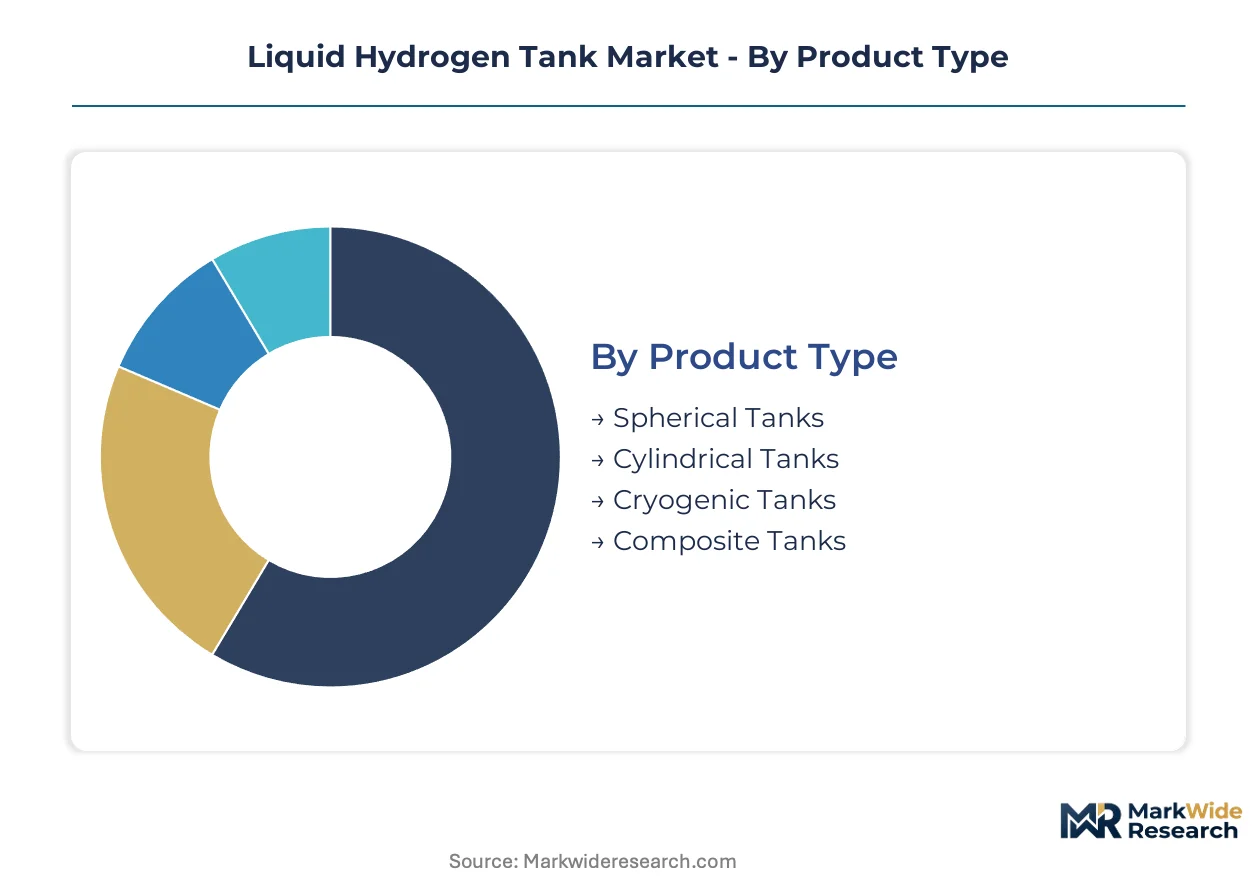
Liquid hydrogen tank procurement splits sharply between aerospace-grade spherical systems commanding premium pricing and cylindrical industrial vessels scaling through volume manufacturing. Understanding these segment boundaries reveals where margin pools concentrate versus where commoditization pressures dominate.
Product Type:
Spherical configurations absorb the aerospace premium while cylindrical geometries scale across terrestrial mobility and stationary storage applications.
- Spherical Tanks:Double-walled vacuum-insulated vessels with minimized surface-area-to-volume ratios achieve sub-1% daily boil-off rates. SpaceX and Blue Origin procurement programs anchor demand in Texas and Florida launch corridors, with specifications that exclude commodity fabricators from qualification.
- Cylindrical Tanks:Horizontal or vertical pressure vessels optimized for vehicle chassis integration and facility footprint constraints. German hydrogen refueling station deployments along the Rhine-Ruhr chemical corridor represent the densest installed base, driven by Linde plc captive production for its station network.
- Cryogenic Tanks:General-purpose vessels maintaining minus 253 degrees Celsius for industrial gas distribution.
- Composite Tanks:Carbon-fiber-reinforced polymer constructions displacing metallic alternatives in weight-sensitive mobile applications.
Mature deployment sits with cylindrical tanks in industrial corridors. Newer deployment is concentrated in spherical tanks for launch vehicle propulsion.
Material:
Metallic substrates dominate current production while fiber-reinforced polymers capture the steepest expansion trajectory in automotive and maritime applications.
- Stainless Steel:300-series austenitic alloys with high nickel content provide cryogenic toughness and weldability. Japanese and European metallurgical suppliers concentrate supply, creating procurement bottlenecks during aerospace build cycles.
- Carbon Fiber:Automated fiber placement and resin transfer molding advances are collapsing cost premiums versus aluminum-lined designs. Kawasaki Heavy Industries extends shipyard composite capabilities into automotive pressure vessel production at scale.
- Aluminum:Lighter metallic alternative for Type III hybrid tank liners.
- Glass Fiber:Lower-cost reinforcement for non-structural tank components and insulation systems.
Stainless steel commands the aerospace specification base. Carbon fiber is gaining share fastest in series-production automotive programs.
End User:
Aerospace propulsion systems extract maximum performance premiums while industrial gas users prioritize total-cost-of-ownership metrics in procurement.
- Aerospace:Launch vehicle stage tanks and satellite propulsion systems demanding orbital-qualified welding and zero-defect traceability. Chart Industries vacuum-insulation expertise positions it for spherical tank dominance in this segment.
- Industrial:Chemical producers and hydrogen hub operators negotiating performance guarantees covering boil-off rates and uptime metrics. German industrial hydrogen corridor buyers now specify integrated storage-and-dispensing contracts rather than discrete tank purchases.
- Automotive:Heavy-duty truck and bus OEMs specifying Type IV composite tanks for range extension.
- Research Institutions:National laboratories and university facilities requiring small-batch cryogenic storage for experimental programs.
Industrial end users represent the deepest installed base. Aerospace applications are absorbing the most intensive engineering development resources.
Distribution Channel:
Direct relationships dominate high-specification aerospace procurement while distributor networks penetrate fragmented industrial maintenance and replacement markets.
- Direct Sales:Engineer-to-order contracts with tank fabricators for hydrogen refueling station operators and launch vehicle prime contractors. California and German station developers specify performance guarantees through direct procurement relationships.
- Distributors:Industrial gas equipment resellers serving replacement tank demand and smaller-scale research facility procurement.
- Online Sales:Digital channels for standardized industrial tank components and spare parts.
- Others:System integrator bundling and lease-financing structures for hydrogen infrastructure projects.
Direct sales capture the aerospace and large stationary storage value. Distributor channels serve the maintenance and small-facility replacement cycle.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Rhine-Ruhr chemical corridor anchors European liquid hydrogen tank procurement, with industrial hydrogen clusters near Leverkusen and Duisburg driving cylindrical vessel demand from refueling station operators and chemical producers.
United States
SpaceX and Blue Origin procurement programs in Texas and Florida pull spherical tank demand for launch vehicle propulsion systems. The Department of Energy's regional clean hydrogen hubs mandate storage infrastructure at scale, creating anchored demand for cylindrical tanks. California station developers specify performance guarantees through direct procurement relationships with tank fabricators.
Germany
Linde plc anchors European demand through captive production of cylindrical tanks tied to its hydrogen refueling station deployments. The European Pressure Equipment Directive's 2024 recast tightens conformity assessment procedures for cryogenic pressure vessels. German tank fabricators serving hydrogen refueling station deployments are restructuring quality systems to maintain CE-marked access.
Japan
Kawasaki Heavy Industries extends shipyard-composite capabilities into carbon-fiber pressure vessels for automotive and maritime hydrogen storage. The Ministry of Economy, Trade and Industry enforces METI technical criteria for hydrogen fueling station storage systems. Port authorities in Yokohama are piloting liquid hydrogen fueling infrastructure for deep-sea vessels.
China
Industrial gas distributors are expanding cryogenic tank fleets to serve hydrogen hub deployments under the national dual carbon goals. The Ministry of Industry and Information Technology governs pressure equipment standards through GB standards certification. Manufacturing clusters in Jiangsu and Zhejiang provinces concentrate tank fabrication capacity for domestic hydrogen infrastructure buildout.
Liquid Hydrogen Tank Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification-grade specialization, with aerospace-qualified fabricators commanding structural price premiums over industrial vessel suppliers. The supply base concentrates around three strategic archetypes: integrated industrial gas majors with captive tank production, specialized cryogenic equipment fabricators with vacuum-insulation expertise, and diversified heavy industrials extending composite manufacturing into pressure vessels. Dominant competitive moves include backward integration into high-nickel alloy supply chains and strategic partnerships with hydrogen refueling station operators.
Among specialized cryogenic fabricators, Chart Industries, Inc. and Cryofab, Inc. represent the vacuum-insulation specialist archetype, while Linde plc exemplifies the integrated industrial gas major with captive cylindrical tank production. Kawasaki Heavy Industries, Ltd. anchors the diversified industrial segment, extending shipyard-scale composite manufacturing into automotive and maritime pressure vessel applications.
| Leading Market Players |
|---|
| Chart Industries, Inc. |
| Cryofab, Inc. |
| Linde plc |
| Cryostar SAS |
| Taylor-Wharton International LLC |
| Air Liquide SA |
| INOXCVA |
| Kawasaki Heavy Industries, Ltd. |
| Air Products and Chemicals, Inc. |
| Others |
Pricing and Supply Chain Analysis
High-nickel stainless steel alloys trace a path from European and Japanese metallurgical suppliers through aerospace-grade spherical tank fabricators commanding premium positioning, while commodity cylindrical vessels for industrial hydrogen hubs absorb cost-scalable manufacturing economics downstream.
Pricing Analysis
Performance-guarantee contracts now anchor value-based pricing as hydrogen refueling station operators in California and Germany negotiate total-cost-of-ownership agreements covering boil-off rates and uptime metrics. Pricing stratifies across aerospace certification tiers, with orbital-qualified welding and zero-defect traceability extracting substantial premiums over industrial vessel alternatives. Cost compression in cylindrical tank segments intensifies as Linde plc captive production and Chinese manufacturing clusters expand capacity. Industrial end users exhibit highest price sensitivity through bundled procurement, while aerospace launch vehicle prime contractors prioritize specification compliance over unit cost.
Supply Chain Analysis
Dual-sourcing requirements from SpaceX and Blue Origin procurement programs mandate multi-supplier qualification for 300-series stainless steel inputs, forcing fabricators to maintain parallel relationships with German, Japanese, and emerging Chinese metallurgical suppliers. Vacuum-insulation manufacturing draws from helium leak detection systems, multi-layer insulation materials, and cryogenic welding equipment. Single-source vulnerability concentrates in qualified orbital TIG welding technicians, where certification scarcity constrains production ramp rates. Distribution runs through direct engineer-to-order contracts for aerospace and large stationary storage, with industrial gas equipment resellers penetrating replacement tank markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The liquid hydrogen tank market sits in a material-transition phase as carbon-fiber-reinforced polymer constructions displace metallic alternatives in weight-sensitive mobile applications.
For Market Incumbents: Hedge against composite manufacturing scale-up by securing captive access to high-nickel alloy supply chains and accelerating automated fiber placement capabilities in-house. Chart Industries' vacuum-insulation expertise and Kawasaki Heavy Industries' shipyard-composite capabilities demonstrate divergent defensive postures against carbon-fiber cost convergence threatening metallic tank margins. For New Entrants and Emerging Players: Automated fiber placement technology offers a technology-first wedge into automotive Type IV tank procurement where incumbent metallurgical supply relationships carry less weight. Maritime hydrogen bunkering infrastructure at Rotterdam, Singapore, and Los Angeles ports represents the most penetrable white-space target outside terrestrial mobility saturation, with system-integrator bundling contracts offering a direct go-to-market path around established refueling station operator relationships. For Investors and Strategic Acquirers: METI technical criteria alignment with ISO 19880-1 harmonization is the leading indicator that cross-border certification portability will consolidate procurement around multi-jurisdictional qualified fabricators. Long-term viability over the next decade favors acquisition targets with demonstrated CE-marked, DOT-certified, and METI-compliant production systems, with helium supply contract restructuring serving as the critical inflection signal for margin sustainability.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into High-Nickel Alloys | Secures input supply against aerospace procurement surges and Japanese-European metallurgical bottlenecks. |
| Automated Fiber Placement Scale-Up | Collapses cost premiums for carbon-fiber tanks against aluminum-lined designs in automotive series production. |
| Multi-Jurisdictional Certification Investment | Enables simultaneous US DOT, EU PED, and Japan METI market access reducing time-to-revenue constraints. |
| Integrated Storage-and-Dispensing Contracts | Captures total-cost-of-ownership value from German chemical corridor buyers shifting from discrete tank procurement. |
| Maritime Bunkering Infrastructure Partnerships | Positions for Rotterdam, Singapore, and Los Angeles port authority pilot programs outside terrestrial mobility. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across tank fabricator engineering directors, hydrogen refueling station procurement leads, aerospace prime contractor supply chain managers, and cryogenic welding certification bodies. Bottom-up triangulation against top-down hydrogen hub deployment schedules from the US Department of Energy and EU Green Deal import corridor planning validated volume assumptions.
Data-stream reconciliation across spherical and cylindrical tank production volumes, material-grade procurement patterns, and end-use segment qualification requirements shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include tank geometry, material substrate, end-user industry, and regional regulatory cluster. CAGRs were derived from hydrogen infrastructure deployment timelines and launch vehicle procurement cycles, with boil-off rate specifications and certification approval timelines serving as industry-specific forecast inputs.
Several conditions sit outside the modeled scope, including fundamental material breakthroughs in multilayer insulation architectures, helium spot market price spikes beyond historical volatility bands, and sequential versus parallel multi-jurisdictional approval process reforms. Deviation in aerospace launch cadence or hydrogen hub funding appropriations would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydrogen Energy
Green Hydrogen Energy Storage System Market
Hydrogen Energy
Clean Hydrogen Market
Hydrogen Energy
35MPa High Pressure Hydrogen Storage Cylinders Market
Hydrogen Energy
Hydrogen Recovery Market
Hydrogen Energy
Hydrogen Production Electrolyser Market
Hydrogen Energy
Hydrogen Ejector Market
Hydrogen Energy
Green Hydrogen Dispensing Equipment Market
Hydrogen Energy
Green Energy Hydrogen Production System Market
Hydrogen Energy
Hydrogen Storage Technology Market
Hydrogen Energy
70MPa High Pressure Hydrogen Storage Cylinders Market
Hydrogen Energy
Hydrogen Tanks Market
Hydrogen Energy
United States Hydrogen Generation Market
Hydrogen Energy
Electrolyzer Market
Hydrogen Energy
Green Hydrogen Market
Hydrogen Energy
Hydrogen Energy Storage Market
Hydrogen Energy
North America Liquid Hydrogen Market