
 Global Energy Efficient Motor Market | 2026-2036
Global Energy Efficient Motor Market Size, Share, and Industry Trends Forecast 2026-2036
Global Energy Efficient Motor Market Analysis
IEC 60034-30-1 efficiency classification is reorganizing competitive eligibility across the Global Energy Efficient Motor Market, effectively filtering out suppliers unable to meet IE3 or IE4 thresholds. Siemens AG leverages its vertically integrated drive systems portfolio to anchor premium positioning in synchronous and reluctance motor categories. ABB Ltd. sustains technology leadership through deep R&D investment in electronically commutated architectures. WEG Industries dominates Latin American supply channels while extending manufacturing scale to serve North American industrial demand.
Energy efficient motors convert electrical input to mechanical output with minimized resistive, magnetic, and friction losses, typically achieving IE3 or IE4 efficiency levels with full-load efficiencies exceeding 91-96% depending on power rating and pole configuration. These machines serve primarily to reduce lifetime operating costs in continuous-duty industrial environments where motors account for substantial facility electricity consumption. AC Motors occupy the largest installed base due to their compatibility with existing variable frequency drive infrastructure and broad industrial applicability. Electronically Commutated motors represent the fastest-expanding technology segment as HVAC OEMs phase out conventional induction units in favor of precision speed-controlled alternatives. Pumps constitute a concentrated margin pool where lifecycle cost analysis favors premium-efficiency procurement in water treatment and oil and gas applications.
The US Department of Energy enforces minimum efficiency standards under 10 CFR 431, while the European Union's Ecodesign Directive and corresponding CE marking requirements mandate IE3 levels for most motor power ranges. China's GB 18613 standard, administered by SAMR, enforces IE3 minimums and incentivizes IE4 adoption through industrial energy efficiency programs. Stakeholders must monitor regulatory divergence between efficiency classification systems as compliance complexity escalates with regional certification fragmentation.
Market Dynamics
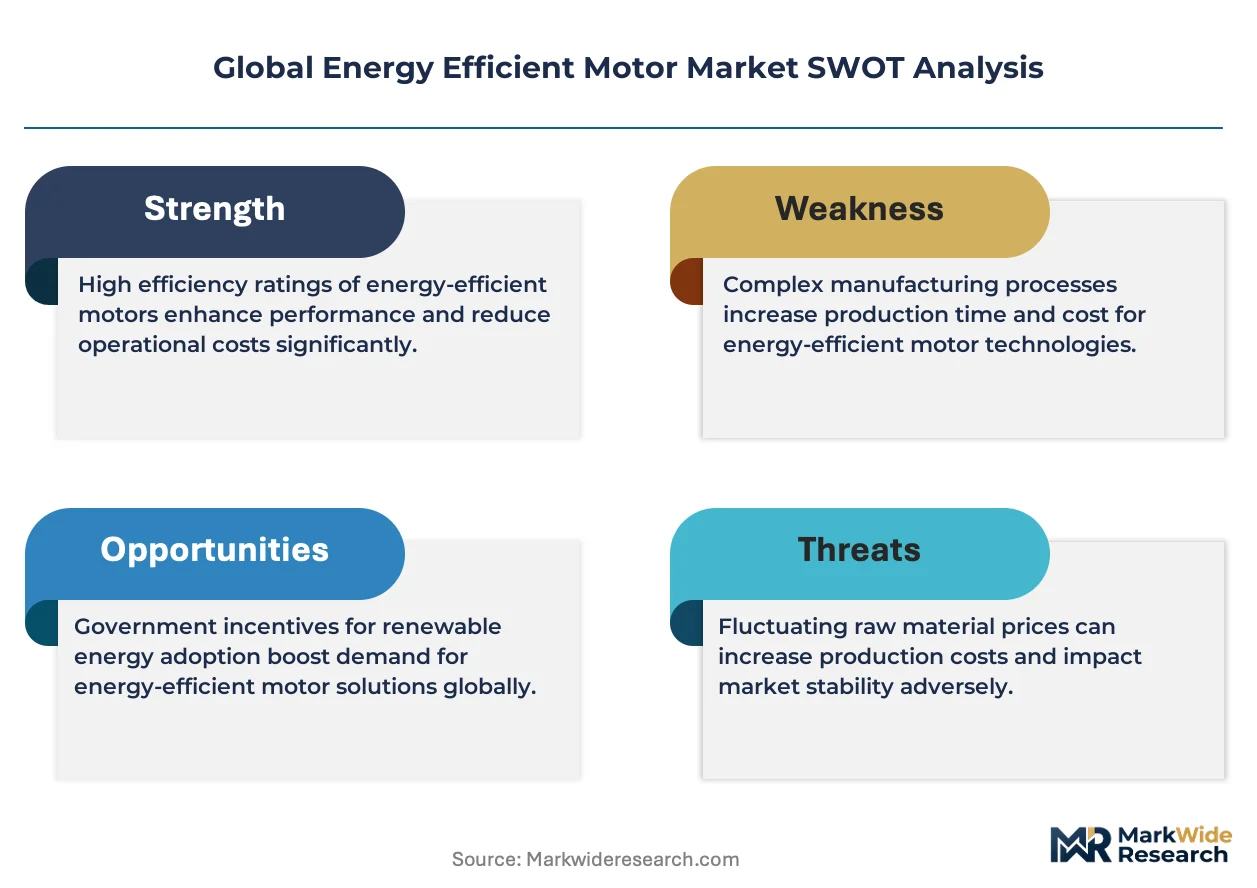
Regulatory ratcheting of minimum efficiency standards is compressing the addressable supply base while simultaneously expanding replacement demand across industrial facilities. IEC 60034-30-1's IE3 and IE4 thresholds are filtering out legacy induction motor architectures and forcing capital redeployment toward electronically commutated and synchronous reluctance platforms.
Growth Catalysts
- 10 CFR 431 Enforcement:The US Department of Energy's expanded efficiency mandates are accelerating motor replacement cycles in water treatment and HVAC infrastructure.
- Industrial Electrification Programs:China's SAMR-administered GB 18613 standard incentivizes IE4 procurement through energy efficiency rebates in steel and cement operations.
- Electronically Commutated Architectures:Precision speed control capabilities are capturing share in refrigeration compressor applications where variable load profiles dominate.
Market Restraints
- Copper and Rare Earth Price Volatility:Neodymium magnet cost swings compress margins for permanent magnet synchronous motor producers.
- Supply Concentration in China:Sintered magnet processing capacity clusters create vulnerability for European and North American motor assemblers.
- Induction Motor Inertia:Existing installed base compatibility and maintenance familiarity slow synchronous reluctance penetration in conservative process industries.
Strategic Opportunities
- India Industrial Corridor Buildout:PLI scheme incentives for manufacturing automation create untapped demand for IE3-rated pump and compressor motors.
- HVAC OEM Electrification:Heat pump deployment targets under the EU Green Deal are expanding precision motor demand in residential and commercial climate systems.
- Digital Twin Integration:Convergence of motor-drive systems with predictive analytics platforms enables outcome-based service models in critical continuous-process environments.
Industry Challenges
- Power Electronics Expertise Scarcity:Shortage of engineers proficient in variable frequency drive tuning and harmonic mitigation complicates field commissioning.
- Multi-Jurisdiction Certification Burden:Divergent efficiency testing protocols between IEC, IEEE, and GB standards extend product launch timelines.
- Legacy Control System Interfacing:Retrofit installations require custom protocol gateways to integrate modern intelligent motors with aging SCADA infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Energy Efficient Motor Market |
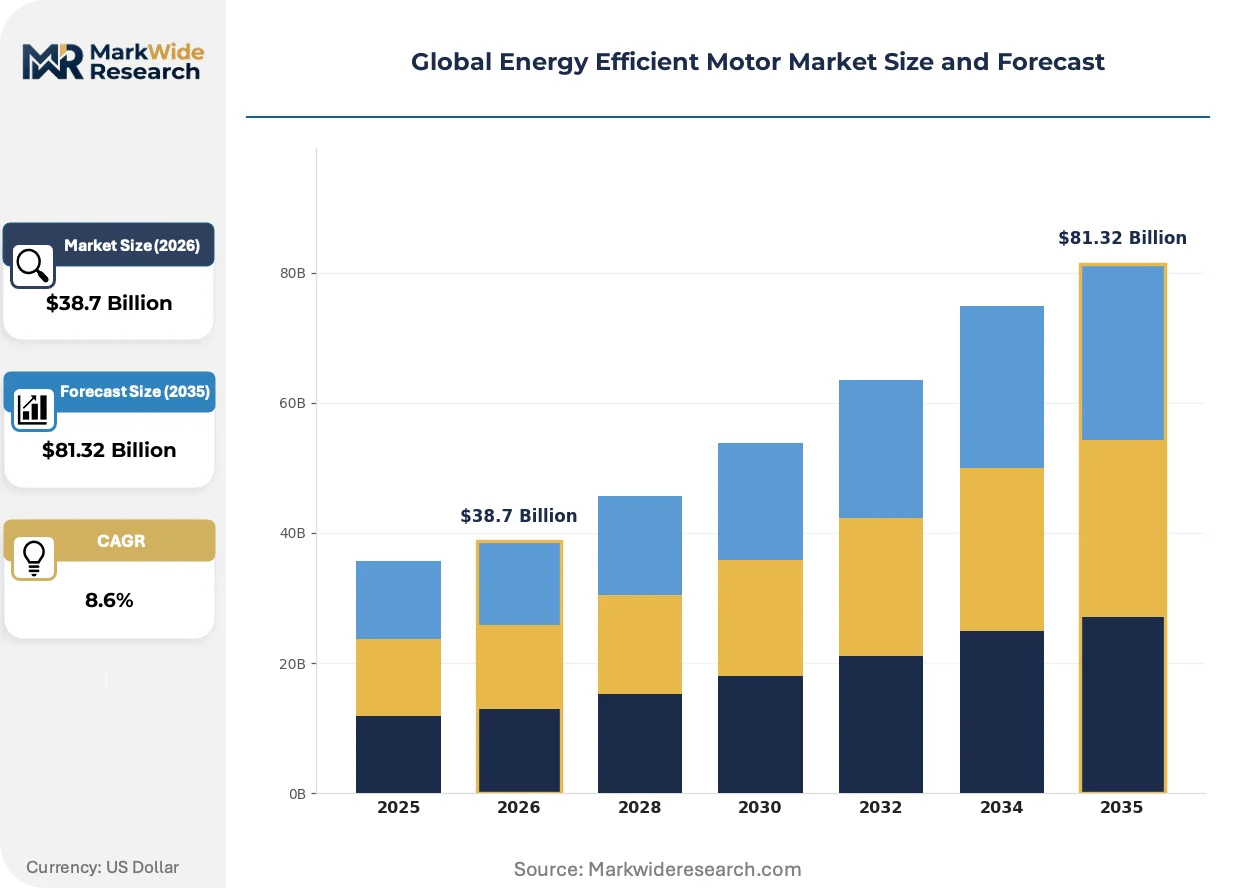
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $81.32 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: AC Motors, DC Motors, Brushless Motors, Stepper Motors Application: HVAC Systems, Industrial Machinery, Pumps, Fans End User: Manufacturing, Commercial, Residential, Transportation Technology: Electronically Commutated, Induction, Synchronous, Reluctance |
| Companies Covered | Siemens AG, ABB Ltd., Regal Rexnord Corporation, WEG Industries, General Electric Company, Nidec Corporation, Schneider Electric SE, Bosch Rexroth, Wolong Electric Group Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Energy Efficient Motor Market Emerging Trajectories
Synchronous reluctance motor architectures are capturing accelerated design-in momentum as industrial operators prioritize magnet-free efficiency solutions. Three convergent developments are compressing technology refresh cycles and redrawing competitive boundaries.
Axial flux permanent magnet configurations are supplanting conventional radial designs in torque-dense applications. Material handling and robotics OEMs are specifying these motors for compact drivetrain integration. The technology is supplanting legacy servo motor platforms in precision positioning systems where power density and thermal efficiency determine competitive specification.
The EU Ecodesign Directive's 2023 expansion to brake motors and variable speed drives is tightening compliance scope beyond baseline induction units. Industrial motor distributors are consolidating supplier portfolios to reduce certification complexity. Water treatment facilities in Germany and the Netherlands are experiencing the most acute procurement disruption as IE3 minimums extend to previously exempt power ranges.
Lifecycle cost contracting is displacing capital expenditure procurement in continuous-duty industrial environments. Energy service companies are capturing motor replacement decisions through guaranteed savings performance structures. This shift is most pronounced in North American pulp and paper operations where electricity represents the dominant operating cost category.
Global Energy Efficient Motor Market Segmentation
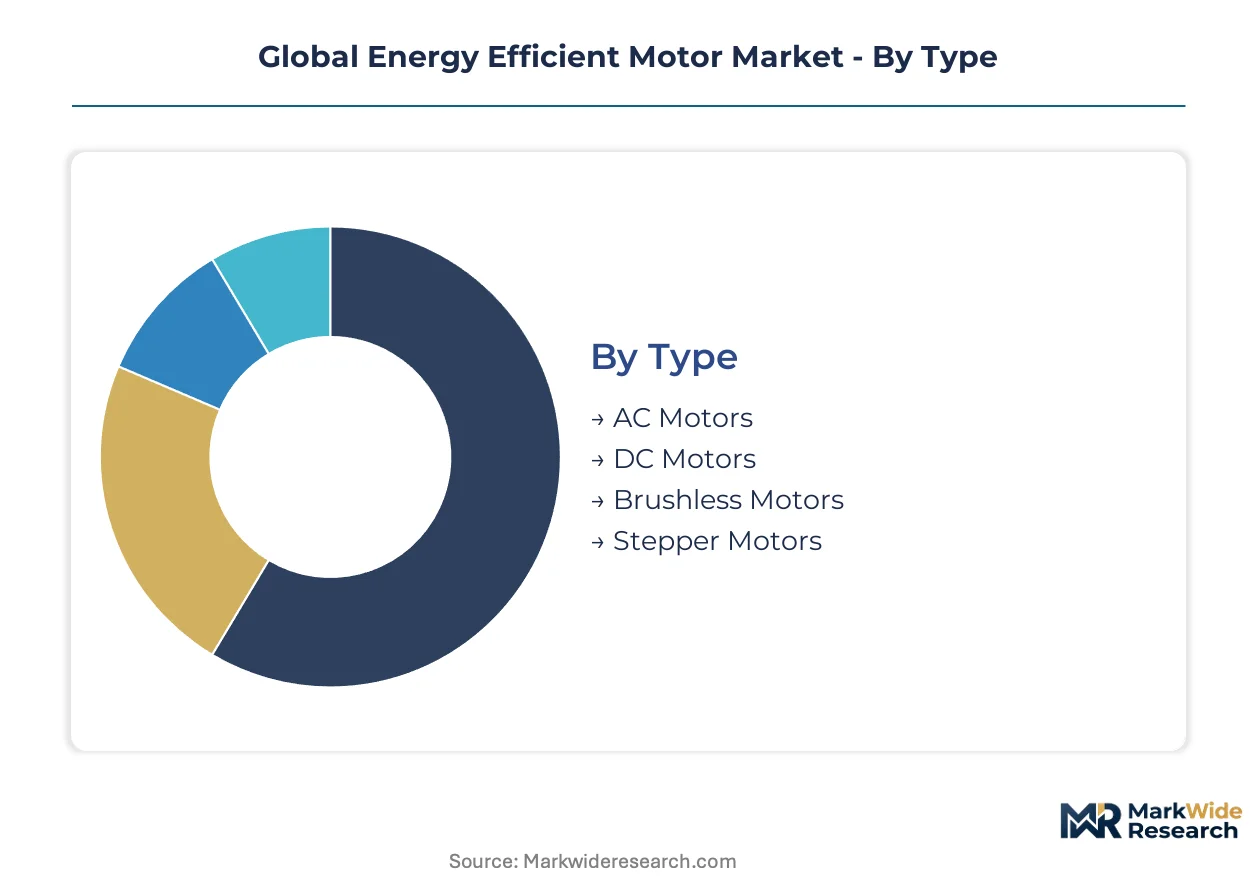
Segmentation in the Global Energy Efficient Motor Market reveals how regulatory pressure and application-specific duty cycles create divergent technology requirements across customer types. Understanding these divisions clarifies where synchronous reluctance architectures displace induction motors versus where electronically commutated platforms capture HVAC retrofit demand.
Type:
IE3 and IE4 efficiency thresholds under IEC 60034-30-1, 10 CFR 431, and China's GB 18613 are filtering motor architectures by loss characteristics and material composition.
- AC Motors:Squirrel-cage induction designs dominate continuous-duty industrial installations with compatibility across existing variable frequency drive infrastructure. Demand concentrates in German and Chinese manufacturing facilities where GB 18613 and Ecodesign Directive mandates accelerate replacement of pre-IE3 units.
- DC Motors:Wound-field and permanent magnet configurations persist in battery-electric traction and precision positioning systems requiring torque control across wide speed ranges. Transportation electrification in the United States and EU Green Deal-funded bus fleet conversions sustain procurement volume despite AC encroachment.
- Brushless Motors:Permanent magnet synchronous architectures with integrated power electronics achieve highest efficiency ratings in compact power ranges.
- Stepper Motors:Hybrid and variable reluctance designs serve open-loop positioning applications in packaging and semiconductor manufacturing equipment.
Established volume favors AC Motors; emerging adoption favors Brushless Motors.
Application:
Duty cycle intensity and operating hour economics determine which efficiency tier justifies premium procurement across water treatment, climate control, and process manufacturing.
- HVAC Systems:Refrigeration compressors and air handling units consume disproportionate facility electricity in commercial buildings. The EU F-Gas Regulation and US IRA heat pump incentives are accelerating electronically commutated motor specification in residential and commercial climate systems across Germany and the United States.
- Industrial Machinery:Conveyors, mixers, and machine tools require torque performance across variable load profiles. China's steel and cement sectors under SAMR industrial efficiency programs are prioritizing IE4-rated motor-drive packages.
- Pumps:Centrifugal and positive displacement configurations in water treatment and oil and gas applications favor lifecycle cost contracting over capital expenditure procurement.
- Fans:Axial and centrifugal designs in ventilation and combustion air supply balance efficiency against stall margin requirements.
Procurement value concentrates in Pumps; technology refresh velocity peaks in HVAC Systems.
End User:
Capital availability and electricity cost exposure create divergent payback period tolerances across facility types.
- Manufacturing:Continuous-process operations in pulp and paper, chemicals, and metals production run motors at high annual operating hours. Energy service companies are capturing replacement decisions through guaranteed savings performance structures in North American facilities.
- Commercial:Office buildings, retail, and institutional facilities prioritize reliability and acoustic performance alongside efficiency in air handling and elevator applications.
- Residential:Heat pump water heaters and furnace blowers represent concentrated motor demand in single-family and multi-family construction.
- Transportation:Rail traction, marine propulsion, and electric vehicle powertrains require specialized torque-speed envelopes and thermal management.
Operating hour intensity favors Manufacturing; electrification policy tailwinds favor Transportation.
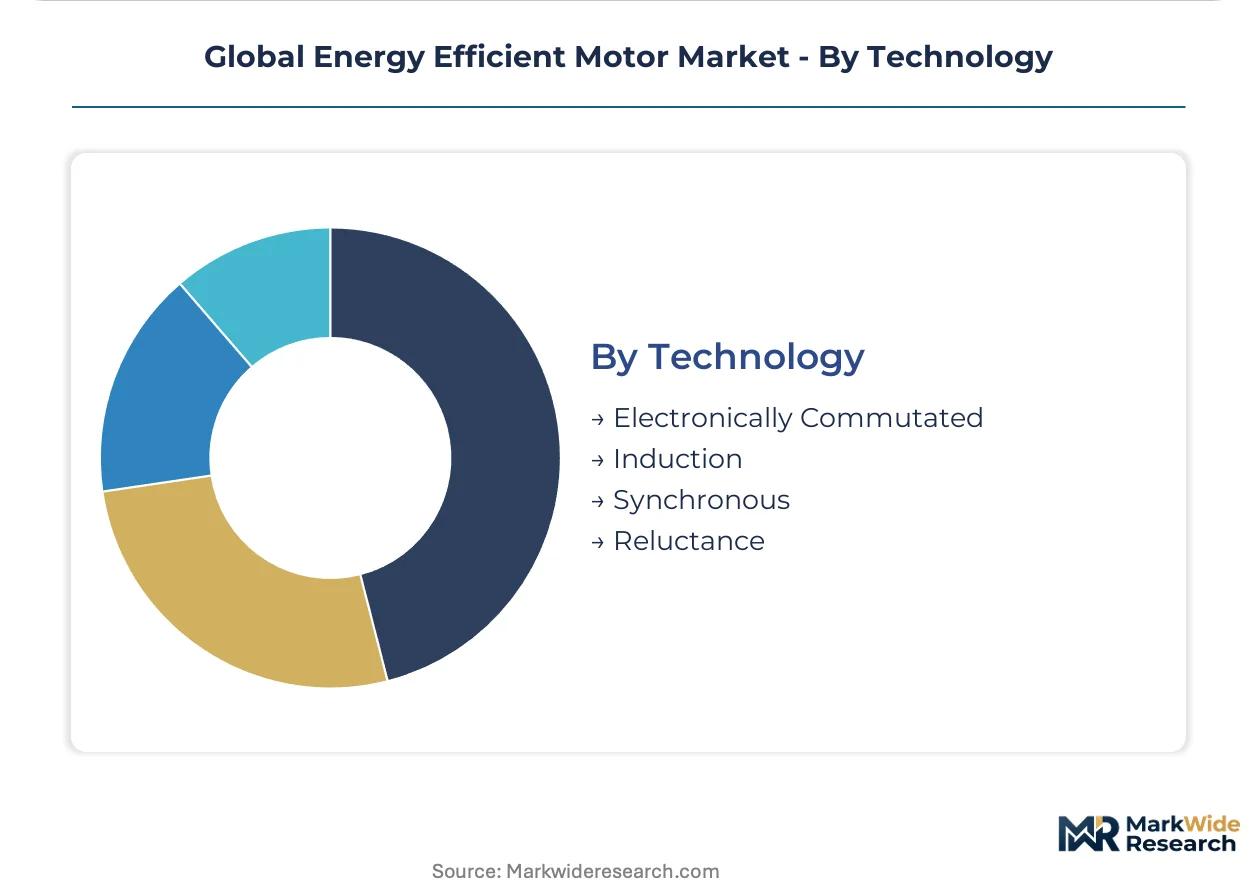
Technology:
Magnet material dependency and power electronics integration requirements are redrawing competitive boundaries between motor architectures.
- Electronically Commutated:Permanent magnet rotor designs with integrated inverter electronics achieve precise speed control without slip losses. HVAC OEMs in the Netherlands and Japan are phasing out conventional induction units in favor of these platforms for refrigeration compressor duty.
- Induction:Cage rotor designs without permanent magnets retain lowest first cost and broad maintenance familiarity. Conservative process industries in the United States slow synchronous reluctance penetration due to installed base compatibility priorities.
- Synchronous:Wound-field and permanent magnet configurations deliver power factor correction benefits in grid-intensive applications.
- Reluctance:Magnet-free rotor designs using salient pole geometry eliminate rare earth material exposure while maintaining IE4 efficiency potential.
Installed base inertia preserves Induction dominance; supply chain risk mitigation accelerates Reluctance design-in momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial electrification subsidies and carbon reduction mandates are redrawing procurement geography across the Global Energy Efficient Motor Market. SAMR-administered rebate programs in China, DOE enforcement actions in the United States, and Ecodesign Directive expansions in the European Union create divergent compliance timelines that favor localized supply chain investments.
China
Steel and cement sector modernization under the dual carbon goals is accelerating IE4 motor specification in Hebei and Shandong provinces. SAMR's GB 18613 standard mandates IE3 minimums while provincial industrial efficiency programs layer additional incentives for premium efficiency procurement. The Yangtze River Delta manufacturing cluster around Shanghai hosts concentrated motor-drive system integration capacity serving domestic OEM demand.
United States
Water treatment infrastructure replacement cycles and IRA-funded industrial decarbonization projects are expanding addressable demand for premium efficiency motors. The Department of Energy's 10 CFR 431 enforcement actions are compressing replacement timelines for pre-standard equipment in municipal pumping stations. Texas and California industrial corridors concentrate petrochemical and semiconductor manufacturing load profiles that favor continuous-duty motor specifications.
Germany
Pulp and paper sector energy service contracting models are displacing capital expenditure procurement for motor replacement in North Rhine-Westphalia. The EU Ecodesign Directive's 2023 expansion to brake motors and variable speed drives tightens compliance scope for machinery OEMs headquartered in Baden-Württemberg. The Ruhr industrial basin hosts concentrated demand for synchronous reluctance architectures in process manufacturing retrofit applications.
India
PLI scheme incentives for manufacturing automation are creating untapped demand for IE3-rated pump and compressor motors in Gujarat and Maharashtra. The Bureau of Indian Standards is harmonizing efficiency testing protocols with IEC 60034-30-1 classifications to reduce certification burden for export-oriented producers. The Delhi-Mumbai Industrial Corridor infrastructure buildout concentrates cement and steel sector motor demand in Rajasthan and Madhya Pradesh sub-regions.
Japan
HVAC OEM electrification programs under METI's building energy efficiency roadmap are expanding precision motor demand in the Kanto region. Refrigeration compressor manufacturers in Osaka prefecture are phasing out conventional induction units in favor of electronically commutated platforms. The Chubu industrial belt around Nagoya hosts automotive supplier clusters specifying compact high-efficiency motors for electric powertrain subsystems.
Global Energy Efficient Motor Market Vendor Landscape
Listed leaders compete with private specialists across capital intensity and technology integration depth. The vendor base organizes into three tiers: diversified electrical conglomerates with captive magnet supply, mid-scale motor specialists with regional channel dominance, and technology-focused innovators in electronically commutated architectures. Strategic moves concentrate on backward integration into magnet processing, capacity expansion in Southeast Asian assembly locations, and outcome-based service contracting for continuous-process industrial accounts.
Within the diversified conglomerate tier, Siemens AG and ABB Ltd. occupy positions defined by vertically integrated drive systems portfolios. WEG Industries exemplifies regional channel specialists extending manufacturing scale to serve adjacent geographies. Among Asia-Pacific producers, Wolong Electric Group Co., Ltd. represents private capital-backed consolidation plays targeting domestic replacement demand. Nidec Corporation anchors the precision motor technology vector with concentration in electronically commutated platforms for HVAC and refrigeration OEMs. These archetypes reflect divergent bets on magnet material exposure versus magnet-free reluctance architectures.
| Leading Market Players |
|---|
| Siemens AG |
| ABB Ltd. |
| Regal Rexnord Corporation |
| WEG Industries |
| General Electric Company |
| Nidec Corporation |
| Schneider Electric SE |
| Bosch Rexroth |
| Wolong Electric Group Co., Ltd. |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at sintered magnet processing facilities in China directly determines rare earth cost floors for permanent magnet synchronous motor producers, compressing margins for European and North American assemblers while elevating price floors for IE4-tier machines. This scale concentration cascades into procurement decisions as industrial buyers weigh magnet-free reluctance architectures against electronically commutated alternatives.
Pricing Analysis
Certification level under IEC 60034-30-1 creates the primary spread between IE3-compliant induction units and IE4-rated synchronous platforms. Three-tier pricing structure across premium, standard, and economy levels reflects efficiency tier, magnet material exposure, and bundled drive system integration. Cost compression in premium tiers is intensifying because neodymium price volatility forces manufacturers to absorb margin erosion or push pricing toward reluctance alternatives. Water treatment municipalities demonstrate highest price sensitivity due to capital budget constraints, while continuous-process pulp and paper operations prioritize lifecycle cost over first cost.
Supply Chain Analysis
Inventory lead times for rare earth magnets extend procurement cycles to six months or longer, forcing motor assemblers to pre-position material exposure through long-term offtake arrangements. Sintered magnet processing concentrates in China, with secondary capacity in Japan and Germany serving strategic diversification needs. Raw material dependencies center on neodymium-iron-boron alloys, electrical steel laminations, and copper winding wire. Single-source vulnerability in Chinese magnet supply creates tariff exposure risk for North American OEMs. Distribution runs through industrial motor distributors consolidating supplier portfolios to reduce certification complexity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Energy Efficient Motor Market enters a cyclical recovery phase as industrial electrification programs in China, the United States, and Germany compress replacement cycles for aging installed base. Capital redeployment toward synchronous reluctance and electronically commutated platforms accelerates as efficiency mandates tighten.
For Market Incumbents: Consolidate backward integration into electrical steel and magnet processing to defend margin position against commodity volatility. Acquire regional channel specialists in Southeast Asian assembly locations to capture proximity advantages for export-oriented production. Prioritize certification investment for IE4 and emerging IE5 thresholds under evolving IEC standards. For New Entrants and Emerging Players: Anchor in India's PLI-scheme manufacturing automation corridor where IE3-rated pump and compressor motor demand outpaces domestic supply capacity. Target synchronous reluctance architectures for process industry retrofits in Germany's Ruhr basin, where magnet-free efficiency solutions address supply chain risk aversion. Pursue outcome-based service contracting models to displace capital expenditure procurement in North American continuous-process facilities. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors electronically commutated motor specialists with HVAC OEM relationships and reluctance architecture developers with industrial retrofit traction. Long-term viability over a five-to-ten-year window hinges on magnet material exposure reduction and digital twin integration capabilities. Monitor SAMR rebate program expansions and EU Ecodesign Directive enforcement actions as inflection indicators for replacement demand velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Magnet Processing | Captive neodymium supply secures cost predictability for IE4 permanent magnet synchronous motor production. |
| Southeast Asian Assembly Expansion | Proximity to China's Yangtze River Delta component ecosystem reduces logistics exposure for export markets. |
| Digital Twin Platform Development | Predictive analytics integration enables outcome-based service contracts in continuous-process industrial accounts. |
| Synchronous Reluctance Architecture Scale-Up | Magnet-free designs eliminate rare earth dependency while maintaining IE4 efficiency ratings. |
| Lifecycle Cost Contracting Models | Guaranteed savings performance structures capture replacement decisions from energy service companies. |
Methodological Framework
Operator-level perspectives from maintenance directors, plant engineers, OEM procurement teams, and aftermarket service heads anchored the qualitative base for this study. Primary field engagement combined with secondary validation against customs and trade data, SEC filings from listed motor manufacturers, IEC standard documentation, and national regulator efficiency program disclosures. Bottom-up segmentation modeling and top-down macroeconomic triangulation ensured cross-verification of volume and value estimates.
Sensitivity analysis across copper price scenarios, rare earth cost bands, and regulatory enforcement timelines shaped the forecast framework. Segmentation dimensions modeled include efficiency class tier, motor architecture type, application duty cycle intensity, end-user capital availability, and regional regulatory cluster. CAGRs were derived through regression analysis of historical replacement cycles projected against mandated efficiency threshold adoption curves. Industry-specific inputs incorporated SAMR industrial efficiency rebate uptake rates and EU Ecodesign Directive compliance cost estimates.
Material uncertainties — commodity price volatility, regulatory enforcement timing divergence, and technology substitution rates — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding efficiency mandate adoption curves and industrial electrification program funding continuity. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Industrial Motors
Europe Induction Motor Market
Industrial Motors
North America Induction Motor Market
Industrial Motors
Smart Motors Market
Industrial Motors
Global Permanent Magnet Motor Market
Industrial Motors
Flatwire & HAIR-PIN Motor Market
Industrial Motors
Asia Pacific Safety Drives and Motors Market
Industrial Motors
Global Refrigeration Oil Market
Industrial Motors
AC Servo Motors and Drives Market
Industrial Motors
United Kingdom DC Motor Market
Industrial Motors
Japan AC Motor Market
Industrial Motors
North America Industrial Motors Market
Industrial Motors
Liquid Nitrogen Purge Systems Market
Industrial Motors
Power Stacker Market
Industrial Motors
Inverter Duty Motors Market
Industrial Motors
Electric Motors for Drones and Electric Vehicle Market
Industrial Motors
Global Brushed DC Motor Market