
 Japan Solar Energy Market | 2026-2036
Japan Solar Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Solar Energy Market Outlook
Perovskite-silicon tandem cell development is rewriting how Japanese manufacturers engineer next-generation photovoltaic modules. Sharp Corporation leverages decades of crystalline silicon expertise to anchor its position in residential rooftop systems. Panasonic Energy Co. competes through heterojunction technology leadership, while Kyocera Corporation specializes in distributed generation projects for commercial end users.
Japan solar energy encompasses photovoltaic systems that convert sunlight into electricity through semiconductor junctions, with monocrystalline and polycrystalline silicon cells achieving laboratory efficiencies exceeding 26 percent under standard test conditions. These installations serve grid-connected power generation, off-grid rural electrification, and building-integrated architectural applications. Photovoltaic panels dominate product-level revenue, while floating installations represent the fastest-growing installation type as land-scarce Japan exploits reservoir surfaces. The utilities end-user segment captures the largest volume share, though commercial adoption accelerates as corporates pursue renewable energy certificates under supply chain decarbonization mandates.
METI administers the feed-in tariff transition framework, while JIS standards govern module durability and safety certification for domestic deployment. The Renewable Energy Act revisions shape procurement timelines, and local prefectural ordinances increasingly mandate solar readiness in new construction. Stakeholders must track grid interconnection queue dynamics and storage pairing requirements as the market shifts from subsidy-dependent expansion to merchant and corporate power purchase agreement structures.
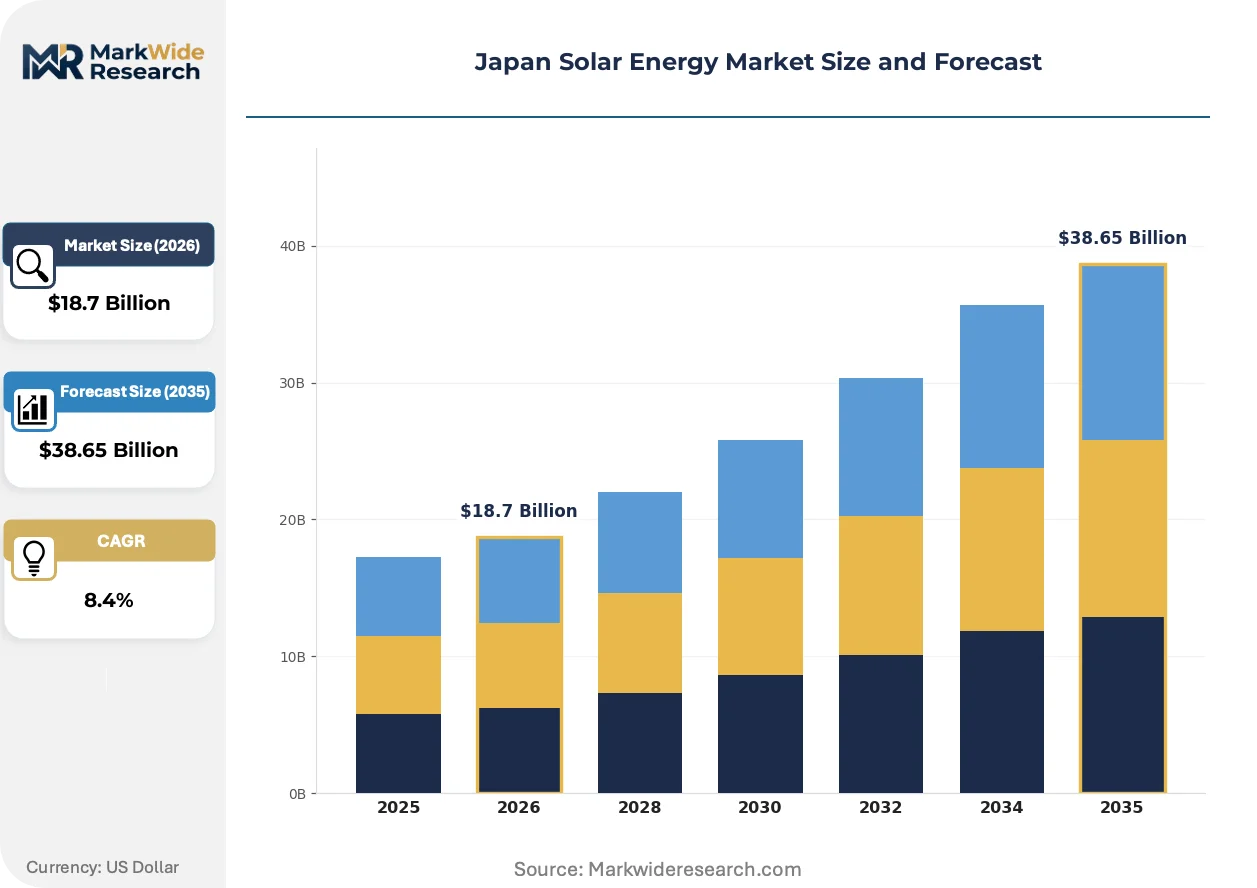
Market Dynamics
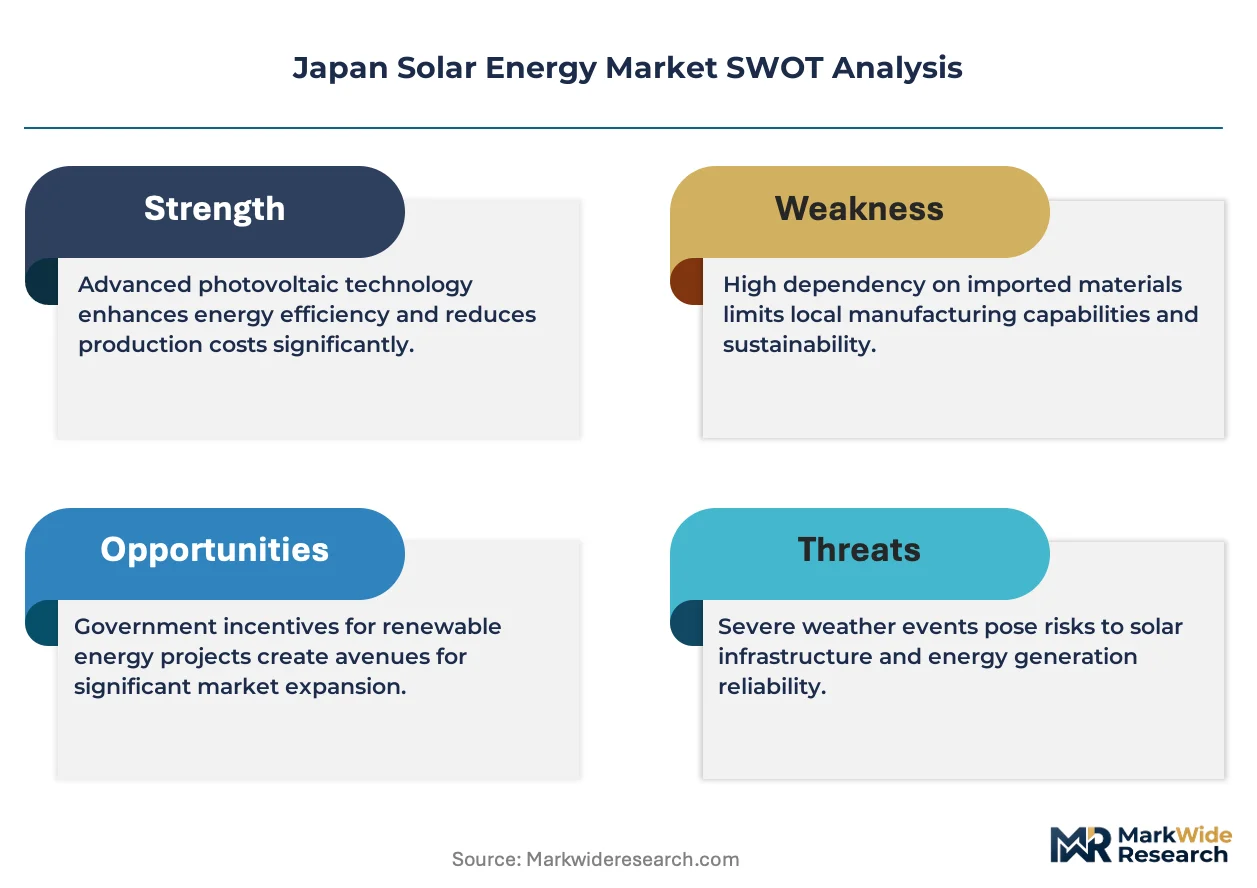
Japan's solar sector is pivoting from feed-in tariff dependence to merchant power economics as METI's auction framework forces developers to optimize for grid balancing and storage co-location rather than guaranteed pricing.
Growth Catalysts
- Feed-in Tariff Successor Auctions:METI's competitive procurement mechanism rewards projects with integrated battery storage, accelerating hybrid plant development across Kyushu and Tohoku prefectures.
- Corporate PPA Mandates:RE100 commitments from automotive and electronics manufacturers are creating direct offtake demand for utility-scale installations bypassing traditional utility intermediaries.
- Heterojunction Cell Maturation:Domestic equipment upgrades are pushing commercial module efficiencies past 24 percent, narrowing the gap with laboratory perovskite-silicon tandems.
Market Restraints
- Interconnection Queue Congestion:Regional utilities in Hokkaido and Kyushu face transformer saturation, delaying project energization by 18-36 months regardless of construction completion.
- Land Scarcity Premiums:Agricultural land conversion restrictions under the Basic Act on Food, Agriculture and Rural Areas inflate site acquisition costs for ground-mounted arrays.
- Polysilicon Supply Concentration:Japanese module assemblers remain dependent on Xinjiang-origin ingot supply chains exposed to forced labor due diligence requirements.
Strategic Opportunities
- Floating PV Expansion:Reservoir installations on irrigation dams in Chiba and Ibaraki prefectures unlock 2-3 GW of capacity without land-use conflicts.
- Building-Integrated Mandates:Tokyo Metropolitan Government's solar-ready building ordinance creates embedded demand for thin-film and translucent module architectures.
- Agrivoltaics Pilot Zones:Ministry of Agriculture, Forestry and Fisheries demonstration programs in Gifu and Aichi are validating crop-compatible elevated mounting systems.
Industry Challenges
- Grid Code Compliance Complexity:New frequency response and voltage ride-through requirements demand inverter firmware upgrades that strain O&M budgets for legacy installations.
- Skilled EPC Labor Shortage:Prefectural construction licensing bottlenecks limit certified electrical workforce availability for 150 kV+ interconnection work.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Solar Energy Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photovoltaic Panels, Inverters, Mounting Systems, Batteries Installation Type: Rooftop, Ground-Mounted, Building Integrated, Floating End User: Residential, Commercial, Industrial, Utilities Funding Source: Government Grants, Private Investment, Energy Savings, Loans |
| Companies Covered | Mitsubishi Electric Corporation, Trina Solar Co. Ltd., Sharp Corporation, LONGi Green Energy Technology Co. Ltd., JinkoSolar Holding Co. Ltd., Kyocera Corporation, Canadian Solar Inc., Hanwha Q CELLS, Panasonic Energy Co., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Solar Energy Market Strategic Shifts
Technology trajectories in Japanese solar are converging on efficiency maximization within severe spatial constraints, with manufacturing and deployment strategies increasingly optimized for rooftop and floating environments rather than utility-scale ground mount.
Perovskite-silicon tandem cell architectures are virtualizing the traditional efficiency frontier for Japanese manufacturers. Residential installers in Osaka and Nagoya prefectures are trialing early production samples ahead of IEC stability certification. This virtualization is compressing the commercialization timeline for next-generation modules from decade-scale to half-decade development cycles.
METI's 2023 Grid Connection Code revisions are mandating dynamic reactive power capability for all new installations above 50 kW. Inverter suppliers must now certify equipment for remote curtailment response within two seconds. Commercial and industrial rooftop segments are absorbing compliance costs most acutely, driving consolidation toward integrated EPC-inverter offerings.
Direct corporate procurement through virtual PPAs is displacing traditional utility-mediated green power certificates. Automotive tier-one suppliers in Aichi prefecture are contracting directly with Kyushu-based project developers for 10-15 year baseload structures. This restructuring is most visible in heavy manufacturing clusters where Scope 3 emissions accounting pressures concentrate renewable sourcing decisions.
Japan Solar Energy Market Segmentation
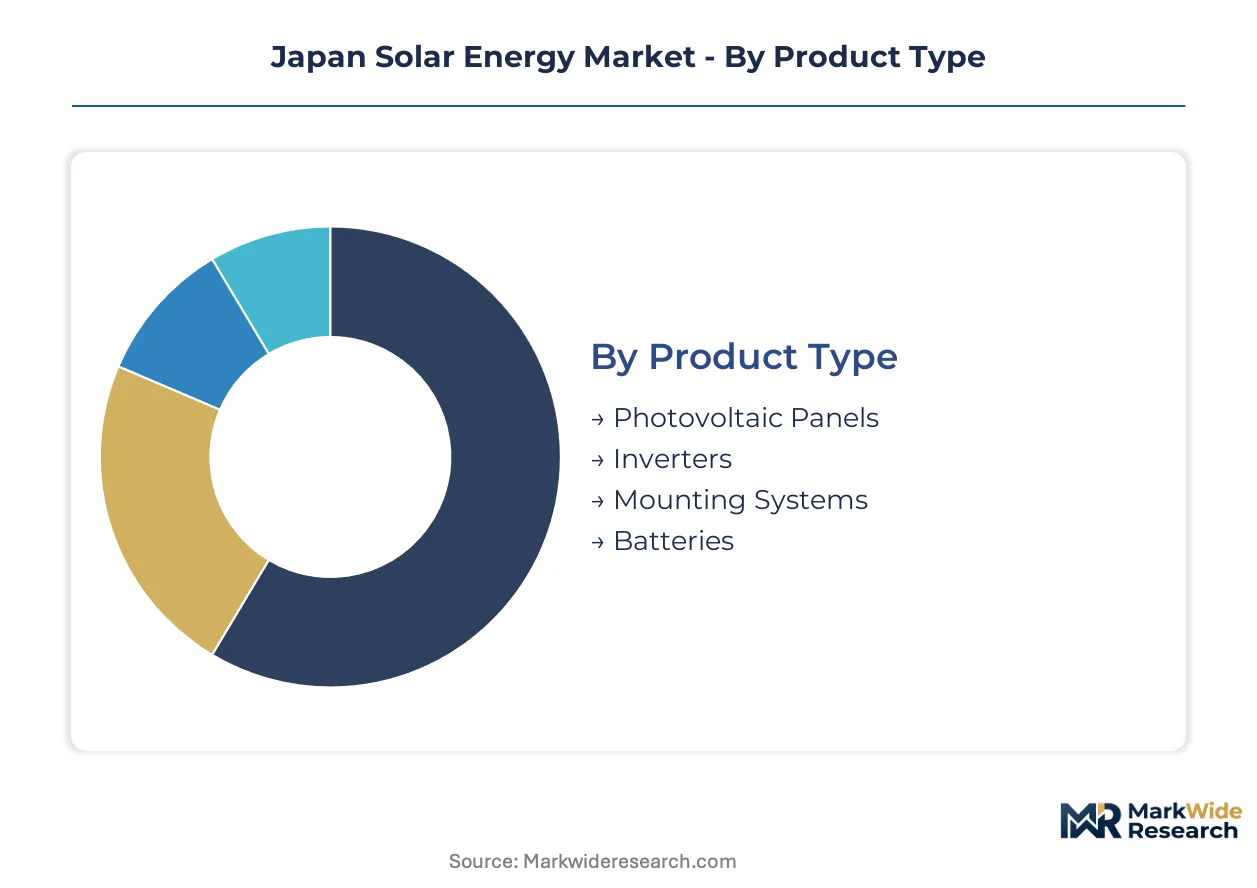
Japanese solar deployment fragments across four critical dimensions that determine procurement patterns, financing structures, and regulatory exposure. Product architecture dictates efficiency benchmarks under JIS certification. Installation topology shapes land-use constraints and grid interconnection complexity. End-user categories drive divergent contract structures from feed-in tariffs to corporate PPAs. Funding source segmentation reveals the market's transition from subsidy dependence to merchant economics.
Product Type:
Cost tier differentiation separates commodity hardware from integrated system solutions with performance guarantees.
- Photovoltaic Panels:Monocrystalline silicon cells dominate commercial deployment with heterojunction architectures pushing module efficiencies past 24 percent. Kyushu utility-scale developers specify these for space-constrained arrays where watt-per-square-meter maximization governs project returns.
- Inverters:String and central inverter configurations must now certify for two-second remote curtailment response under METI's 2023 Grid Connection Code revisions. Compliance firmware upgrades strain O&M budgets for legacy commercial and industrial rooftop installations.
- Mounting Systems:Elevated agrivoltaic racking from Gifu and Aichi demonstration programs validates crop-compatible structural designs under Ministry of Agriculture oversight.
- Batteries:Lithium-ion storage pairing accelerates under METI auction frameworks that reward hybrid plant configurations with grid-balancing capability.
Photovoltaic panels command the established base. The steepest expansion runs through batteries.
Installation Type:
Application topology determines land-use permissions, irradiance exposure, and construction labor requirements.
- Rooftop:Residential systems anchor Sharp Corporation's crystalline silicon expertise in Osaka and Nagoya prefectures. Commercial and industrial segments absorb acute compliance costs from dynamic reactive power mandates, driving consolidation toward integrated EPC-inverter offerings.
- Floating:Reservoir installations on irrigation dams in Chiba and Ibaraki prefectures unlock capacity without agricultural land conversion conflicts. This architecture gains share fastest as land-scarce Japan exploits surface water resources.
- Ground-Mounted:Agricultural land conversion restrictions under the Basic Act on Food, Agriculture and Rural Areas inflate site acquisition costs for utility-scale arrays in Kyushu.
- Building Integrated:Tokyo Metropolitan Government's solar-ready building ordinance creates embedded demand for thin-film and translucent module architectures in new construction.
Rooftop systems retain volume leadership. Floating installations are climbing the fastest.
End User:
Customer type segmentation structures contract duration, offtake pricing mechanisms, and regulatory filing obligations.
- Utilities:Regional power companies in Hokkaido and Kyushu face transformer saturation that delays project energization by 18-36 months regardless of construction completion, creating interconnection queue congestion.
- Commercial:Automotive tier-one suppliers in Aichi prefecture contract directly with Kyushu-based developers for 10-15 year baseload virtual PPAs, bypassing traditional utility-mediated green power certificates.
- Industrial:Heavy manufacturing clusters where Scope 3 emissions accounting pressures concentrate renewable sourcing decisions.
- Residential:Early production samples of perovskite-silicon tandem cells trial ahead of IEC stability certification in Osaka and Nagoya prefectures.
Utilities retain the installed base. Commercial offtake is expanding most quickly.
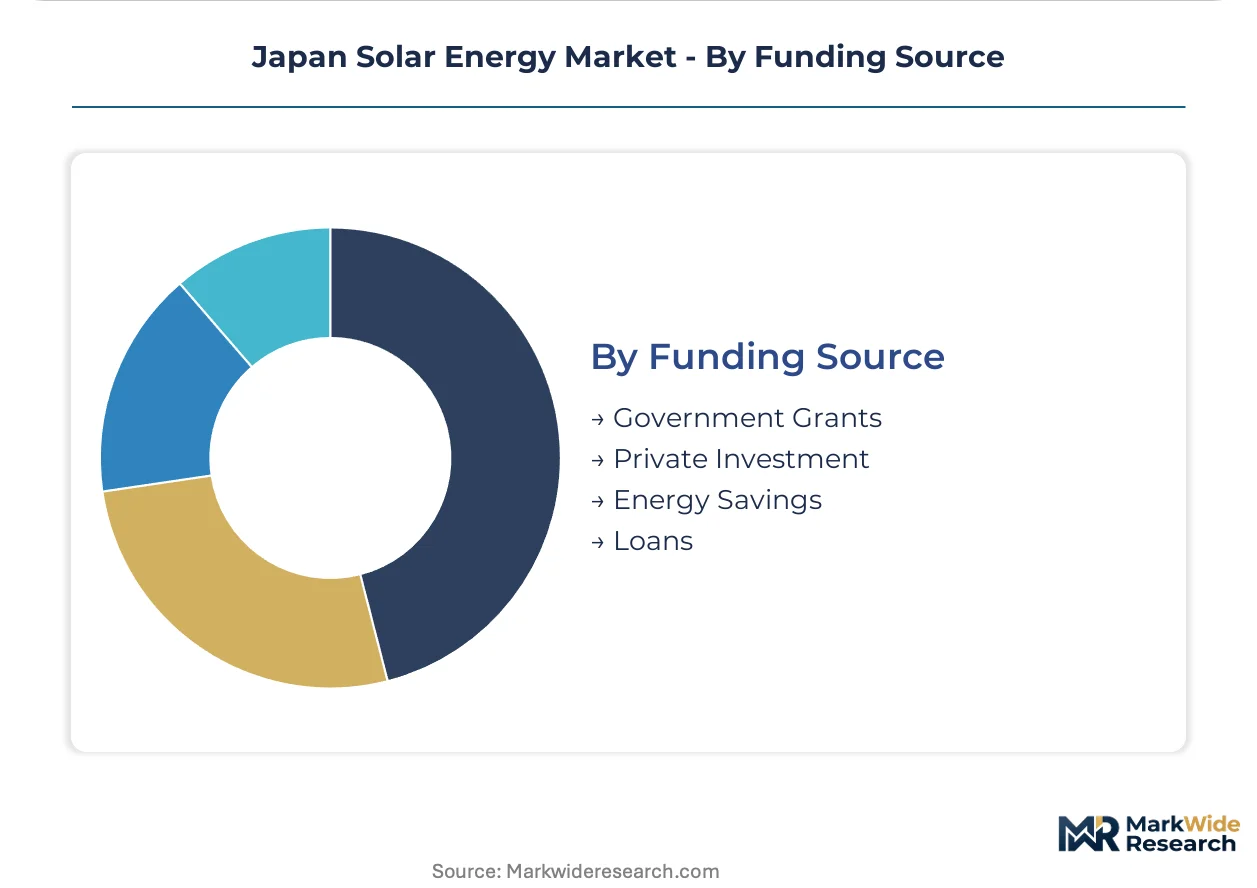
Funding Source:
Maturity of capital structures reflects the market's pivot from guaranteed returns to merchant risk exposure.
- Private Investment:Direct corporate procurement structures displace traditional utility intermediaries as RE100 commitments from automotive and electronics manufacturers create direct offtake demand.
- Government Grants:METI's feed-in tariff successor regime still anchors procurement for projects with integrated battery storage, though auction frameworks now force price discovery.
- Loans:Prefectural construction licensing bottlenecks limit certified electrical workforce availability, extending project finance timelines for 150 kV+ interconnection work.
- Energy Savings:Performance contracting structures gain traction in commercial segments with verifiable load profiles.
Government grants anchored historical deployment. Private investment is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese solar module exports flow primarily into Southeast Asian procurement networks, where Vietnamese and Thai project developers source heterojunction panels for utility-scale installations. Domestic deployment concentrates in five prefectural clusters with distinct grid interconnection profiles and land-use constraints.
Kyushu
Utility-scale developers exploit high irradiance levels and available reservoir surfaces for floating PV arrays. METI's auction framework rewards hybrid plant configurations with integrated battery storage in Kagoshima and Kumamoto prefectures. Transformer saturation at Kyushu Electric Power substations delays project energization by 18-36 months regardless of construction completion.
Kanto/Tokyo
The Tokyo Metropolitan Government's solar-ready building ordinance creates embedded demand for thin-film and translucent module architectures in new commercial construction. Corporate PPA mandates from RE100-committed automotive and electronics manufacturers concentrate direct procurement activity in Saitama and Chiba prefectures. Chiba reservoir installations on irrigation dams unlock 2-3 GW of floating capacity without agricultural land conversion conflicts.
Kansai/Osaka
Residential rooftop systems anchor crystalline silicon deployment in Osaka and Nagoya prefectures, with early production samples of perovskite-silicon tandem cells trialing ahead of IEC stability certification. Panasonic Energy Co. leverages heterojunction technology leadership to supply high-efficiency modules for space-constrained urban installations. Prefectural construction licensing bottlenecks limit certified electrical workforce availability for residential interconnection work.
Tohoku
Grid-balancing requirements under METI's 2023 Grid Connection Code revisions accelerate hybrid plant development across Aomori and Iwate prefectures. Dynamic reactive power capability mandates for installations above 50 kW drive inverter firmware upgrades and O&M budget strains for commercial and industrial segments. Regional utilities face interconnection queue congestion as auction-winning projects seek 150 kV+ grid access.
Hokkaido
Land availability attracts ground-mounted utility-scale developers despite agricultural land conversion restrictions under the Basic Act on Food, Agriculture and Rural Areas. Hokkaido Electric Power Network faces transformer saturation comparable to Kyushu, creating parallel interconnection delays. Cold-climate performance optimization for heterojunction modules distinguishes procurement specifications from southern prefectures.
Japan Solar Energy Market Competitive Environment
On the supply side, the industry is bifurcated between domestic manufacturers with crystalline silicon heritage and Chinese-scale producers competing on cost-position. Tiered differentiation separates premium heterojunction specialists from commodity module assemblers. Three archetypes dominate: technology-integrated domestic champions, volume-exporting Chinese fabricators, and regional EPC-integrated specialists. Competitive moves concentrate on strategic partnerships for grid-storage hybrid development and technology licensing for perovskite-silicon tandem commercialization.
Among domestic technology-integrated manufacturers, Sharp Corporation, Panasonic Energy Co., and Kyocera Corporation exemplify the premium-tier archetype anchored in residential and commercial distributed generation. Chinese-scale exporters including LONGi Green Energy Technology Co. Ltd., JinkoSolar Holding Co. Ltd., and Trina Solar Co. Ltd. occupy the volume-driven position serving utility-scale procurement. Mitsubishi Electric Corporation represents the industrial-electronics conglomerate model with cross-sector energy infrastructure capabilities. Canadian Solar Inc. and Hanwha Q CELLS sit within the international specialist tier competing for corporate PPA offtake structures.
| Leading Market Players |
|---|
| Mitsubishi Electric Corporation |
| Trina Solar Co. Ltd. |
| Sharp Corporation |
| LONGi Green Energy Technology Co. Ltd. |
| JinkoSolar Holding Co. Ltd. |
| Kyocera Corporation |
| Canadian Solar Inc. |
| Hanwha Q CELLS |
| Panasonic Energy Co. |
| Others |
Value Chain & Pricing Dynamics
Kyushu-based heterojunction module fabrication clusters anchor Japan's solar supply base, with concentrated domestic capacity in Kagoshima and Kumamoto prefectures translating into pricing leverage for premium-efficiency products. METI's auction framework compresses margins for commodity-tier assemblers while rewarding integrated storage configurations with tariff premiums.
Pricing Analysis
Heterojunction cell premiums over conventional monocrystalline silicon create a three-tier pricing structure across premium, standard, and economy levels. Sharp Corporation and Panasonic Energy Co. command brand premiums for residential rooftop systems certified under JIS durability standards. Cost compression in utility-scale procurement intensifies as Chinese-scale exporters compete on module pricing for Kyushu ground-mounted arrays. Commercial and industrial segments exhibit highest price sensitivity due to dynamic reactive power compliance burdens, while floating PV developers absorb premium pricing for corrosion-resistant mounting architectures.
Supply Chain Analysis
Contract manufacturing concentration rests with domestic equipment fabricators in Osaka and Nagoya prefectures, supplemented by Taiwanese and South Korean ingot suppliers. Polysilicon feedstock draws from Xinjiang-origin supply chains exposed to forced labor due diligence requirements. Single-source vulnerability concentrates in high-purity silicon refining capacity. Distribution runs through regional EPC-integrated specialists serving prefectural utility interconnection queues.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's solar sector is navigating a cyclical recovery as METI's feed-in tariff successor regime forces price discovery and merchant risk absorption. The auction framework's storage co-location mandates create differentiated recovery trajectories across hybrid and standalone project archetypes.
For Market Incumbents: Entrench heterojunction technology leadership through backward integration into cell manufacturing equipment. Panasonic Energy Co. and Sharp Corporation should deepen captive wafer supply to defend margin position against Chinese-scale cost pressure. Accelerate perovskite-silicon tandem commercialization timelines to preempt next-generation efficiency competition.
For New Entrants and Emerging Players: Build out floating PV EPC capabilities targeting Chiba and Ibaraki reservoir installations, where land-scarce constraints create protected niche demand. Agrivoltaic demonstration zones in Gifu and Aichi offer white-space penetration with Ministry of Agriculture pilot program alignment. Pursue direct corporate PPA origination with automotive tier-one suppliers in Aichi prefecture.
For Investors and Strategic Acquirers: Long-term, this sits as a grid-balancing infrastructure play because hybrid solar-storage assets capture auction premiums and merchant arbitrage value. Acquisition targets should prioritize EPC-integrated developers with certified 150 kV+ interconnection capabilities. Watch transformer saturation resolution timelines at Kyushu Electric Power and Hokkaido Electric Power Network as inflection signals for project energization velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Plant Capacity Buildout | METI auction premiums reward integrated battery storage configurations in Kagoshima and Kumamoto. |
| Perovskite-Silicon Technology Licensing | Sharp Corporation's crystalline silicon heritage accelerates tandem cell commercialization timelines. |
| Floating PV Project Development | Chiba reservoir installations unlock capacity without agricultural land conversion restrictions. |
| Corporate PPA Origination | RE100-committed automotive manufacturers in Aichi create direct offtake demand bypassing utilities. |
| Grid Code Compliance Certification | Two-second remote curtailment firmware upgrades strain O&M budgets for legacy commercial rooftops. |
Study Parameters
A standing panel of utility planning officers, IPP project developers, EPC contractors, and grid operators provided ongoing calibration across the analysis window. Primary fieldwork combined structured interviews with secondary validation against METI procurement databases, JIS certification registries, and regional utility interconnection filings. Bottom-up project pipeline triangulation against top-down auction award aggregation anchored volume estimates.
Scenario-bracketing framed low, base, and high cases across the projection horizon. Segmentation dimensions modeled include installation topology, end-user category, funding source maturity, and prefectural regulatory cluster. CAGRs derived from fitted growth curves applied to auction pipeline conversion rates and corporate PPA origination velocity. Forecast inputs incorporated heterojunction cell efficiency trajectories and floating PV cost learning curves.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese-scale exporters or accelerated perovskite commercialization by domestic manufacturers would shift outcomes. Quarterly review of transformer saturation resolution at Kyushu Electric Power and METI auction clearing prices is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Cell Busbar Market
Solar Power Systems
Middle-East and Africa Distributed Solar Power Generation Market
Solar Power Systems
Optical Solar Reflectors Market
Solar Power Systems
PV Array Combiner Box Sales Market
Solar Power Systems
Floating Solar Panels Market
Solar Power Systems
North America Rooftop Solar Market
Solar Power Systems
US Solar PV Market
Solar Power Systems
Trinidad and Tobago Solar Energy Market
Solar Power Systems
Solar Cullet Market
Solar Power Systems
South Korea Solar Energy Market
Solar Power Systems
Global Solar Module for Electric Vehicle Market
Solar Power Systems
Asia-Pacific Solar Photovoltaic (PV) Market
Solar Power Systems
Czech Republic Solar Energy Market
Solar Power Systems
Solar Microgrid Market
Solar Power Systems
Solar-Powered EV Charging Stations Market
Solar Power Systems
South America Rooftop Solar Market