
 Blue Hydrogen Market | 2026-2036
Blue Hydrogen Market Size, Share, and Industry Trends Forecast 2026-2036
Blue Hydrogen Market Analysis
The EU Green Deal's hydrogen backbone initiative is broadening offtake visibility for low-carbon fuel suppliers. Shell plc leverages its integrated gas and CCS project pipeline to anchor early-mover positions across Northwest Europe. Linde plc sustains engineering leadership through its proprietary cryogenic carbon capture designs for large-scale reformers. Air Products and Chemicals, Inc. dominates the North American project roster with announced blue hydrogen facilities tied to ammonia export terminals.
Blue hydrogen denotes hydrogen produced from natural gas feedstocks with integrated carbon capture and storage, typically achieving CO2 capture rates exceeding ninety percent through amine-based absorption or pressure swing adsorption systems. The output serves primarily as a decarbonized industrial feedstock and power plant fuel, bridging the gap between fossil hydrogen and green electrolysis economics. Steam methane reforming commands the production method landscape due to its mature catalyst technology and established equipment supply chains, while autothermal reforming gains traction for projects targeting higher capture efficiencies at integrated refinery complexes. Chemical feedstock applications attract the deepest margin pools given ammonia and methanol producers' willingness to contract long-term offtake, though transportation sector demand accelerates fastest as heavy-duty fuel cell truck pilots expand.
The US EPA tailors greenhouse gas performance standards for hydrogen production facilities under evolving Clean Air Act frameworks, while the EU F-Gas Regulation and REACH compliance shape equipment material specifications for European project developers. Japan's METI hydrogen roadmap influences technology licensing terms for export-oriented producers targeting Asian offtake agreements. Stakeholders must monitor CCS storage site permitting velocity and pipeline interconnection rulings, as these infrastructure decisions will determine which project clusters achieve commercial operation before cost-competitive green hydrogen scales.
Market Dynamics
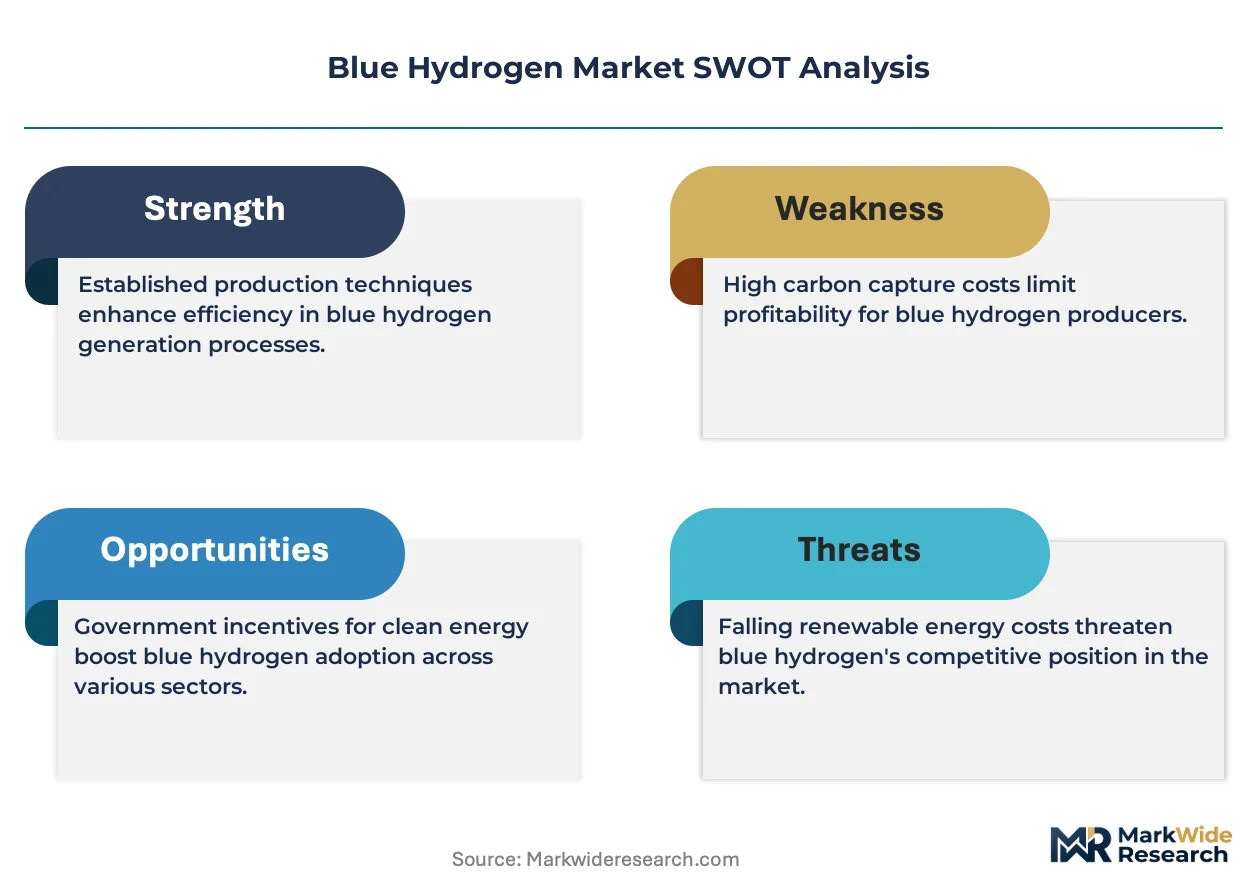
EU ETS compliance deadlines are compressing refinery procurement cycles, forcing operators to contract blue hydrogen offtake before carbon capture infrastructure reaches scale parity with conventional reforming.
Growth Catalysts
- EU Green Deal hydrogen backbone:The initiative mandates cross-border pipeline corridors, creating guaranteed offtake visibility for low-carbon fuel suppliers in Northwest Europe.
- Steam methane reforming maturity:Established catalyst technology and equipment supply chains reduce execution risk for first-mover projects targeting industrial feedstock contracts.
- Louisiana hydrogen hub designation:Federal funding concentration accelerates CCS storage site permitting and pipeline interconnection rulings along the US Gulf Coast corridor.
Market Restraints
- Natural gas feedstock volatility:Input cost swings compress project IRRs for developers locked into long-term offtake contracts at fixed pricing.
- CCS storage site scarcity:Permitting velocity for saline aquifer injection limits project clustering in regions without depleted oil and gas fields.
- Green electrolysis cost curve:Declining renewable power and electrolyzer capex threaten blue hydrogen's bridging window before grid-scale green production achieves parity.
Strategic Opportunities
- Heavy-duty fuel cell trucking:Pilot fleet expansions in California and Germany create demand for distributed hydrogen fueling infrastructure.
- Japan METI import roadmap:Technology licensing terms for export-oriented producers open Asian offtake agreements tied to ammonia co-firing power targets.
- Amine-based absorption advancement:Convergence with pressure swing adsorption systems enables capture rate improvements above ninety percent for autothermal reforming units.
Industry Challenges
- CCS engineer scarcity:Specialized geoscientists and injection well designers command premium compensation, stretching project staffing timelines.
- Pipeline reconfiguration friction:Legacy natural gas infrastructure requires material retrofits for hydrogen service, complicating interconnection with capture facilities.
- F-Gas material compliance:EU equipment specifications for seals and valves extend procurement lead times for European project developers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Blue Hydrogen Market |
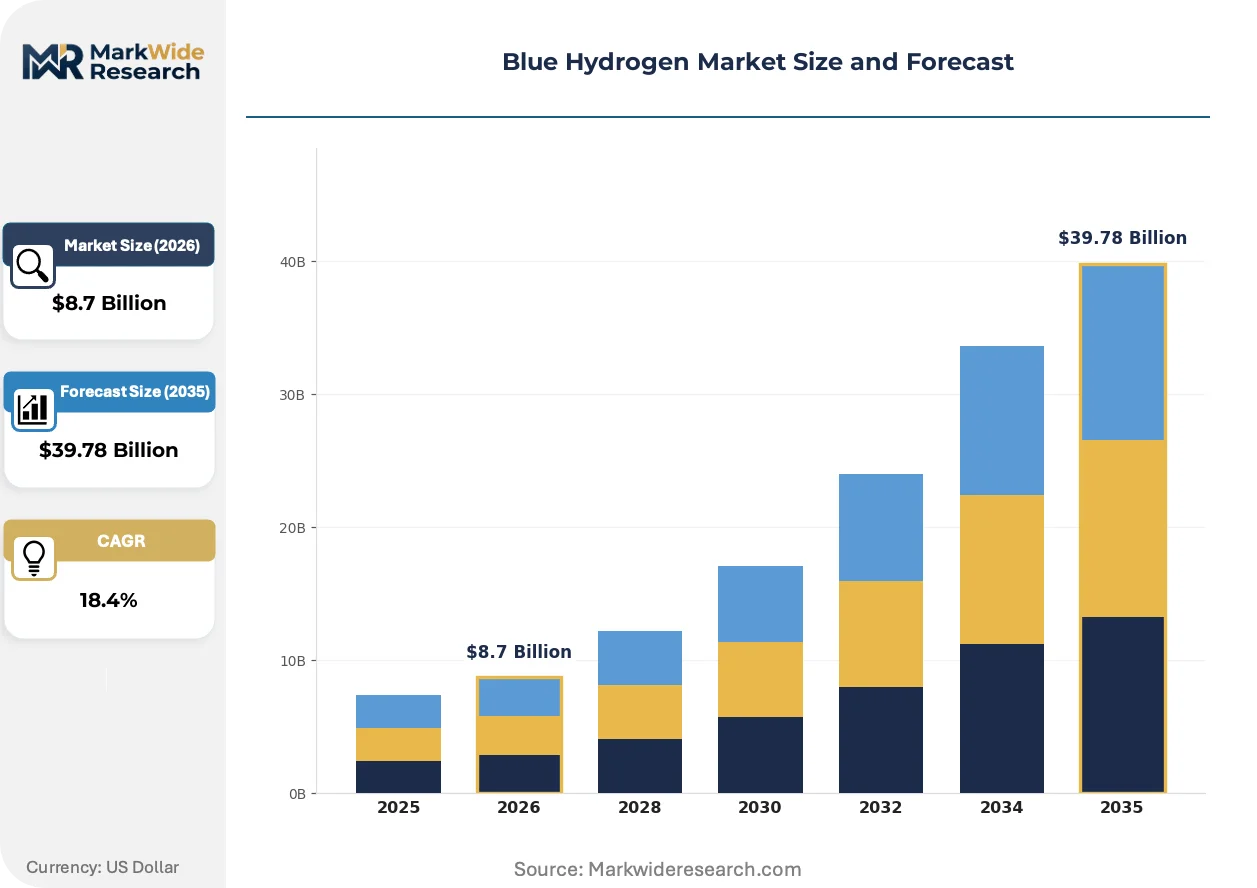
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Production Method: Steam Methane Reforming, Gasification, Partial Oxidation, Autothermal Reforming Application: Power Generation, Transportation, Industrial Processes, Chemical Feedstock End User: Utilities, Manufacturing, Oil & Gas, Automotive Distribution Channel: Pipelines, Trucking, Shipping, On-site Generation |
| Companies Covered | Shell plc, Linde plc, Air Products and Chemicals, Inc., Air Liquide, ExxonMobil Corporation, BP p.l.c., Equinor ASA, Engie, Technip Energies N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Blue Hydrogen Market Emerging Trajectories
Carbon capture integration is shifting from bolt-on retrofit to front-of-mind engineering discipline, with reformer designs now optimizing for capture efficiency rather than treating it as secondary equipment.
Cryogenic carbon capture systems are absorbing residual CO2 from reformer flue gas streams at temperatures below minus eighty degrees Celsius. Ammonia producers in the US Gulf Coast are piloting these units for integration with existing steam methane reforming trains. The technology is absorbing project risk premiums previously assigned to amine solvent degradation and regeneration energy penalties.
EPA greenhouse gas performance standards under evolving Clean Air Act frameworks are tightening emission intensity thresholds for hydrogen production facilities. Industrial consequence includes mandatory monitoring and reporting protocols for methane leakage across the natural gas supply chain. Refinery operators in Texas and Louisiana are responding by contracting certified low-leakage gas supplies and installing continuous emissions monitoring systems.
Long-term offtake contracting is displacing spot market procurement for industrial hydrogen buyers. Ammonia and methanol producers are locking in ten to fifteen year supply agreements to secure financing for their own decarbonization investments. This pattern is most visible in Germany and the Netherlands, where EU ETS carbon price exposure creates urgency for feedstock switching.
Blue Hydrogen Market Segmentation
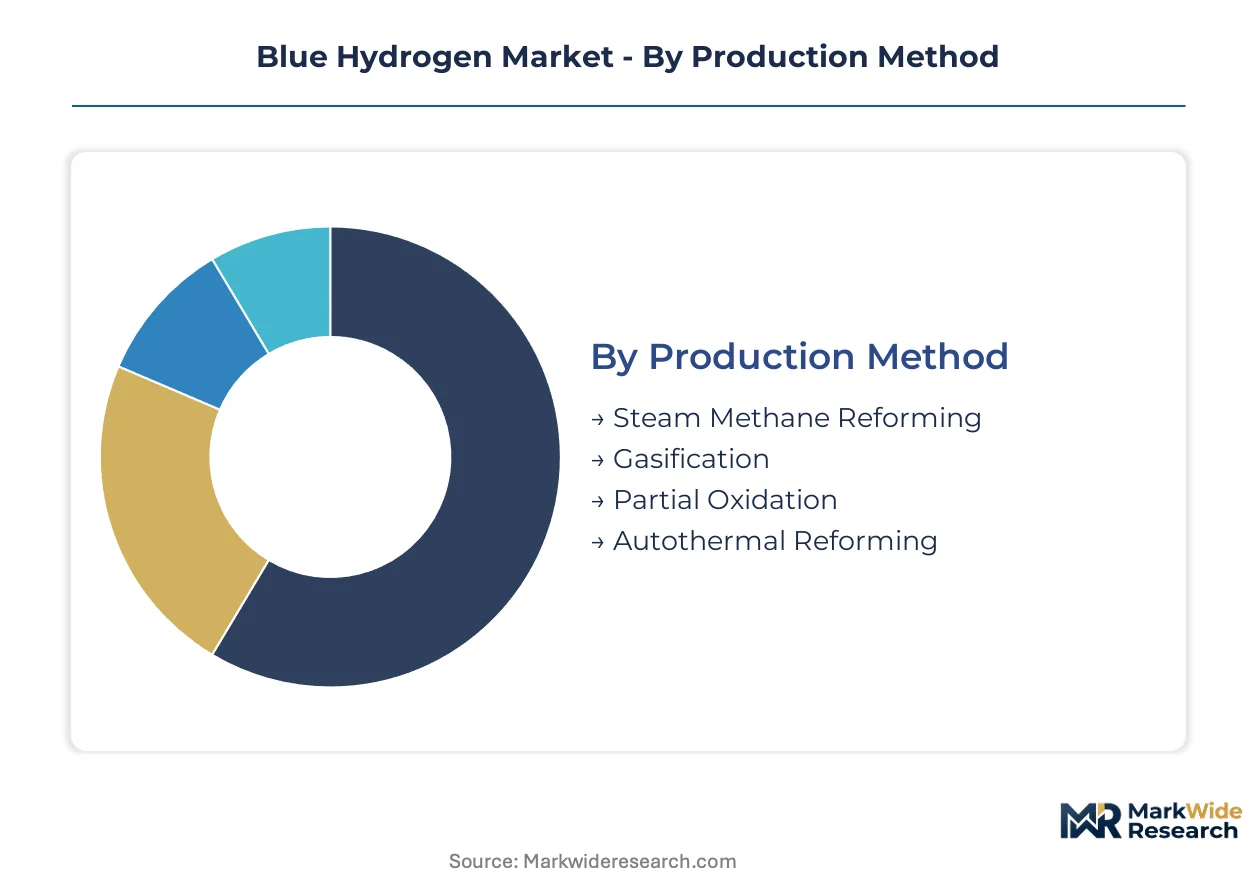
Segmentation reveals how blue hydrogen value pools concentrate around production technology maturity and offtake contract duration. Developers align project configurations with specific end-use carbon intensity requirements and infrastructure availability.
Production Method:
Technology selection determines capture efficiency thresholds and equipment supply chain access.
- Steam Methane Reforming:Mature catalyst systems and standardized reactor vessels dominate current capacity installations. Refinery operators in Germany and the Netherlands contract SMR-based supply for EU ETS compliance deadlines, leveraging established maintenance protocols and spare parts networks.
- Autothermal Reforming:Oxygen-blown reforming achieves higher CO2 concentrations in syngas output, reducing capture energy penalties. Louisiana hydrogen hub developers favor ATR configurations for greenfield ammonia export terminals targeting Asian offtake agreements.
- Gasification:Coal or biomass feedstock conversion enables carbon-negative pathways with biomass sourcing. Project feasibility concentrates in regions with stranded coal assets and CCS storage site proximity.
- Partial Oxidation:Heavy hydrocarbon feedstock processing serves refinery integration where residual oil upgrading coincides with hydrogen demand. Applications cluster at integrated petrochemical complexes with existing syngas infrastructure.
Mature deployment sits with Steam Methane Reforming. Newer deployment is concentrated in Autothermal Reforming.
Application:
End-use carbon intensity requirements and offtake contract structures shape demand segmentation.
- Chemical Feedstock:Ammonia and methanol producers lock ten to fifteen year supply agreements to secure project financing. US Gulf Coast corridor facilities anchor this segment through export terminal integration.
- Industrial Processes:Steel and cement decarbonization pilots create spot demand for high-purity hydrogen. German refinery operators scale procurement under EU ETS compliance timelines.
- Transportation:Heavy-duty fuel cell truck pilots in California and Germany expand distributed fueling infrastructure. This application climbs the fastest as fleet operators test total cost of ownership against diesel baselines.
- Power Generation:Gas turbine co-firing trials in Japan and South Korea establish ammonia combustion specifications. METI roadmap targets influence technology licensing terms for export-oriented producers.
Contract security concentrates in Chemical Feedstock. Operational trial activity clusters in Transportation.
End User:
Procurement scale and carbon accounting sophistication differentiate buyer segments.
- Oil & Gas:Integrated majors leverage CCS project pipelines and storage site portfolios for captive hydrogen production. Shell plc anchors early-mover positions across Northwest Europe through this vertical integration.
- Utilities:Power sector buyers pilot ammonia co-firing for grid-scale generation decarbonization. Japanese utilities drive technology licensing negotiations under METI import roadmap frameworks.
- Manufacturing:Steel, cement, and chemicals producers contract blue hydrogen for process heat and feedstock switching. EU ETS carbon price exposure accelerates procurement urgency in Germany and the Netherlands.
- Automotive:Fuel cell vehicle manufacturers sponsor distributed production pilots to secure supply chain visibility. California fleet operators anchor demand for heavy-duty trucking applications.
Integrated supply control dominates Oil & Gas. Merchant procurement expansion centers on Manufacturing.
Distribution Channel:
Logistics configuration determines project siting economics and customer reach.
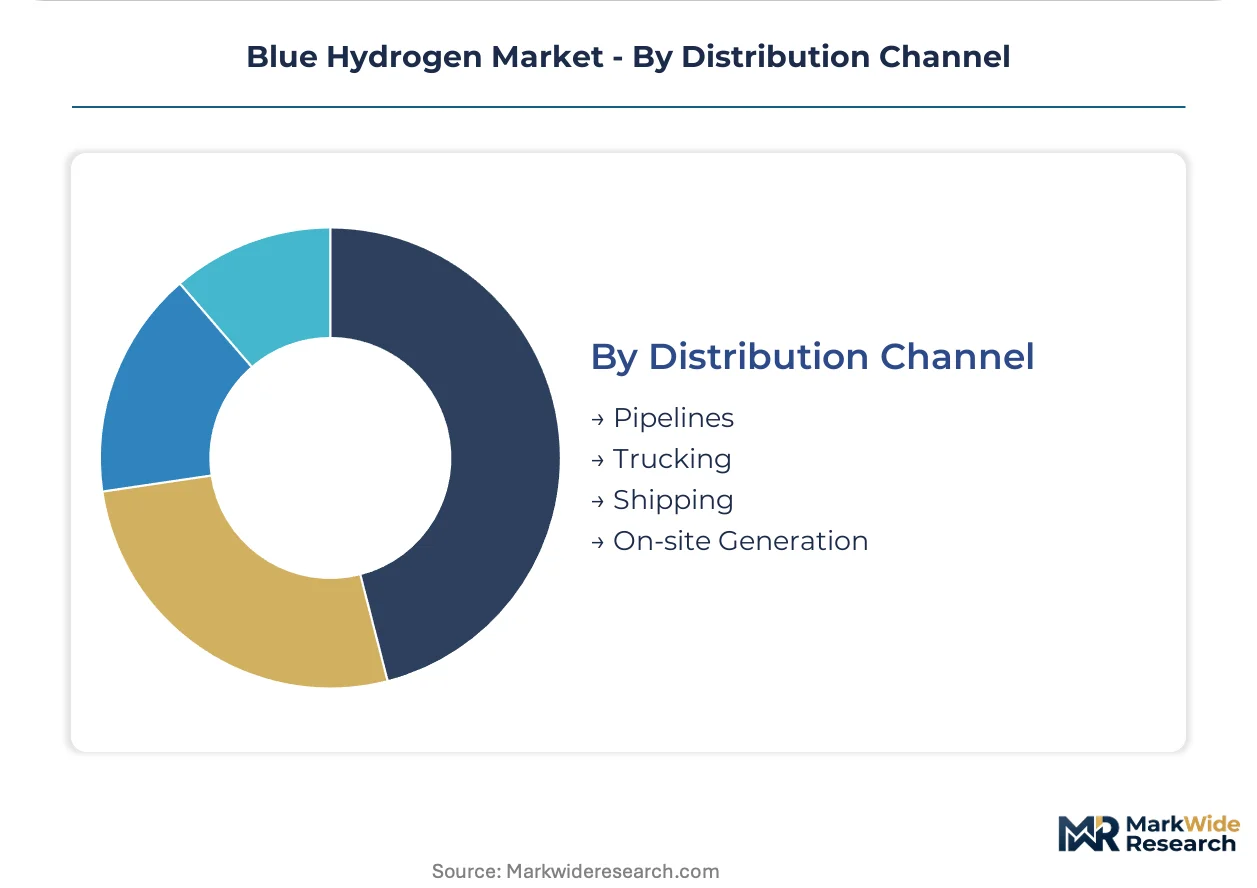
- Pipelines:Dedicated hydrogen pipelines and repurposed natural gas infrastructure serve clustered industrial demand. Louisiana and Texas hydrogen hub designations accelerate CCS storage site permitting and interconnection rulings.
- On-site Generation:Captive production at refineries and ammonia plants eliminates transport costs and leakage risks. This channel gains share fastest as developers optimize for capture efficiency rather than merchant market access.
- Trucking:Tube trailer delivery serves distributed fueling stations and small-scale industrial offtake. California heavy-duty fleet pilots expand this channel for transportation sector demand.
- Shipping:Ammonia carrier transport enables intercontinental hydrogen trade to Asian offtake markets. Japanese and South Korean import targets shape liquefaction and terminal investment timelines.
Capital deployment concentrates in Pipelines. Emerging capacity expansion targets On-site Generation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The US Gulf Coast corridor anchored by Louisiana and Texas hydrogen hub designations concentrates the most visible project development velocity for carbon capture-enabled hydrogen production.
United States
Louisiana and Texas hydrogen hub designations accelerate CCS storage site permitting and pipeline interconnection rulings along the Gulf Coast corridor. EPA greenhouse gas performance standards under evolving Clean Air Act frameworks tighten emission intensity thresholds for production facilities. Refinery operators in Texas contract certified low-leakage gas supplies and install continuous emissions monitoring systems.
Germany
Refinery operators scale blue hydrogen procurement under EU ETS compliance timelines forcing feedstock switching decisions. EU Green Deal hydrogen backbone mandates cross-border pipeline corridors creating guaranteed offtake visibility for low-carbon fuel suppliers. Industrial clusters in North Rhine-Westphalia anchor project feasibility studies for carbon capture retrofit mandates.
Netherlands
Port of Rotterdam infrastructure positions the country as a Northwest European hydrogen import and distribution gateway. EU F-Gas Regulation and REACH compliance shape equipment material specifications extending procurement lead times for project developers. Shell plc leverages integrated gas and CCS project pipelines to anchor early-mover positions.
Japan
METI hydrogen roadmap influences technology licensing terms for export-oriented producers targeting Asian offtake agreements. Gas turbine co-firing trials establish ammonia combustion specifications for power generation decarbonization. Utilities drive technology licensing negotiations under import roadmap frameworks.
Saudi Arabia
Stranded gas assets and favorable geology for saline aquifer injection create project clustering advantages for carbon capture development. The country's national energy regulator shapes domestic hydrogen export certification standards. Industrial zones in the Eastern Province concentrate feasibility studies for integrated reforming and CCS facilities.
Blue Hydrogen Market Vendor Landscape
Premium-margin players sit above commodity-margin players across capture efficiency and offtake contract duration dimensions. The market structure consolidates around integrated energy majors with captive CCS storage portfolios and specialized industrial gas suppliers with proprietary capture technology. Two strategic archetypes dominate: vertically integrated oil and gas majors leveraging upstream gas and storage assets, and engineering-focused gas specialists monetizing cryogenic and amine-based absorption designs. Capacity expansion and strategic partnerships represent the dominant competitive moves as developers race to secure pipeline interconnection rulings before green electrolysis achieves cost parity.
Within the integrated major tier, Shell plc and ExxonMobil Corporation exemplify archetypes combining natural gas production with carbon capture infrastructure control. Linde plc occupies a position among engineering-specialist gas suppliers, representing the premium-capture-technology vector. Air Products and Chemicals, Inc. anchors the North American project development cluster, sitting within the ammonia-export-integrated developer archetype.
| Leading Market Players |
|---|
| Shell plc |
| Linde plc |
| Air Products and Chemicals, Inc. |
| Air Liquide |
| ExxonMobil Corporation |
| BP p.l.c. |
| Equinor ASA |
| Engie |
| Technip Energies N.V. |
| Others |
Supply Flow & Price Mechanics
CCS geoscientist scarcity in the US Gulf Coast corridor widens labor-cost differentials between premium capture-technology deployments and standard amine-based installations, compressing margin spreads for projects unable to secure specialized injection well designers.
Pricing Analysis
Value-based pricing anchored to carbon intensity outcomes dominates contract structures, with ammonia producers paying premiums for certified sub-kilogram CO2 per kilogram hydrogen performance. Price differentiation stems from capture efficiency certification tiers and long-term offtake duration, with ten-year contracts commanding standard rates and fifteen-year agreements securing discount floors. Pricing pressure stems from green electrolysis cost compression threatening blue hydrogen's bridging economics before scale. Merchant buyers in industrial processes exhibit highest price sensitivity, while integrated oil and gas majors with captive storage portfolios show lowest.
Supply Chain Analysis
REACH and F-Gas Regulation qualification requirements for seals, valves, and pressure vessels extend procurement lead times for European developers, gating equipment access. Manufacturing concentrates in Germany, the Netherlands, and the US Gulf Coast, with specialized reformer vessels drawing from established catalyst supply chains in Belgium and Japan. Nickel-based catalysts, amine solvents, and cryogenic separation units constitute critical input dependencies. Single-source vulnerability sits with CCS injection well casing suppliers. Distribution runs through dedicated hydrogen pipelines and repurposed natural gas infrastructure serving clustered industrial demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Players are pursuing upstream control over carbon capture storage site portfolios to lock in offtake pricing power before pipeline interconnection rulings finalize.
For Market Incumbents: Hedge against green electrolysis cost parity by accelerating autothermal reforming deployments with capture rates above ninety percent. Secure depleted oil and gas field storage leases in Louisiana and Texas before saline aquifer permitting bottlenecks intensify. Reinforce engineering talent pipelines through partnerships with geoscience programs at Gulf Coast universities.
For New Entrants and Emerging Players: Engineering procurement construction contractors represent the critical channel partner type for market access without captive storage assets. Target distributed heavy-duty fuel cell trucking infrastructure in California where fleet operators test total cost of ownership against diesel baselines. White-space exists in cryogenic carbon capture retrofits for existing steam methane reforming trains. Pursue technology licensing arrangements with Japanese utilities under METI roadmap frameworks.
For Investors and Strategic Acquirers: Re-rating potential sits with engineering-specialist gas suppliers given proprietary cryogenic capture designs and ammonia export terminal integration. Long-term viability hinges on five-to-ten year contracting windows before green hydrogen achieves grid-scale parity. Acquisition targets should display integrated CCS storage site control or exclusive pipeline interconnection agreements. Monitor EPA greenhouse gas performance standard threshold tightening as inflection indicator for accelerated refinery procurement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into CCS Storage | Captive saline aquifer or depleted field access secures offtake pricing power against merchant competitors. |
| Long-term Supply Agreement | Ten to fifteen year ammonia producer contracts enable project financing for Louisiana hydrogen hub developments. |
| Technology Licensing | METI roadmap compliance opens Japanese utility offtake negotiations for export-oriented producers. |
| Joint Venture | Shell plc partnerships with pipeline operators accelerate Northwest Europe hydrogen backbone interconnection. |
| Green Certification Program | EU ETS compliance certification differentiates supply for German refinery procurement under carbon price exposure. |
Methodological Framework
EPA enforcement guidance documents, FERC pipeline interconnection filings, and EU ETS carbon price auction records formed the secondary backbone. Primary interviews with CCS project developers, refinery procurement officers, ammonia plant engineering directors, and hydrogen hub program administrators validated demand assumptions. Bottom-up capacity installation tracking across Louisiana, Texas, and Rotterdam clusters was triangulated against top-down hydrogen demand modeling for ammonia and methanol feedstock switching.
Bottom-up project-level economics were stress-tested against top-down sectoral demand projections across the analysis window. Segmentation dimensions modeled include production method maturity, offtake contract duration, and regional regulatory framework stringency. CAGRs were derived from installation velocity curves weighted by capture technology deployment share. Forecast inputs incorporated natural gas feedstock price volatility scenarios and green electrolysis capital cost decline trajectories.
Caveats apply where EPA performance standard threshold revisions or EU ETS carbon price spikes could materially shift the outlook. Forecasts reflect assumptions about CCS storage site permitting velocity and pipeline reconfiguration timelines. A model refresh is warranted upon material change in green electrolysis cost parity achievement.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydrogen Energy
Gray Hydrogen Market
Hydrogen Energy
Asia-Pacific Clean Hydrogen Market
Hydrogen Energy
Green Hydrogen Market
Hydrogen Energy
35MPa High Pressure Hydrogen Storage Cylinders Market
Hydrogen Energy
Liquid Hydrogen Tank Market
Hydrogen Energy
Hydrogen Composite Tanks Market
Hydrogen Energy
India Hydrogen Market
Hydrogen Energy
Hydrogen Purification Technologies Market
Hydrogen Energy
Hydrogen Gas Generator Market
Hydrogen Energy
Hydrogen Purifiers Market
Hydrogen Energy
PEM Water Electrolytic Hydrogen Production System Market
Hydrogen Energy
Hydrogen-Cooled Turbine Generator Market
Hydrogen Energy
Hydrogen Liquefaction Unit Market
Hydrogen Energy
High-Pressure Hydrogen Tanks Market
Hydrogen Energy
Hydrogen ICE Ignition System Platforms Market
Hydrogen Energy
Hydrogen Market