
 North America Liquid Hydrogen Market | 2026-2036
North America Liquid Hydrogen Market Size, Share, and Industry Trends Forecast 2026-2036
North America Liquid Hydrogen Market Insights
Heavy-duty fleet operators are unwinding decades of diesel dependency as hydrogen fuel cell economics improve for long-haul routes. Air Products and Chemicals, Inc. anchors North American production capacity through its Gulf Coast network and megaproject pipeline. Linde plc leverages its industrial gas infrastructure to control hydrogen liquefaction and distribution nodes across the United States and Canada. Plug Power competes aggressively in material handling and on-road mobility segments with integrated green hydrogen systems.
Liquid hydrogen denotes hydrogen gas cooled to minus 253 degrees Celsius, achieving a density of 70.8 kilograms per cubic meter for efficient long-distance transport and high-purity industrial use. Cryogenic liquefaction requires multi-stage compression and expansion cycles, making energy efficiency a critical cost parameter for commercial viability. Aerospace applications currently lead offtake volumes given established space launch demand from NASA and commercial operators, while energy storage represents the fastest-growing segment as grid-scale hydrogen installations multiply. The turboexpander technology category sustains premium margins due to limited supplier bases and exacting performance specifications for large-scale plants.
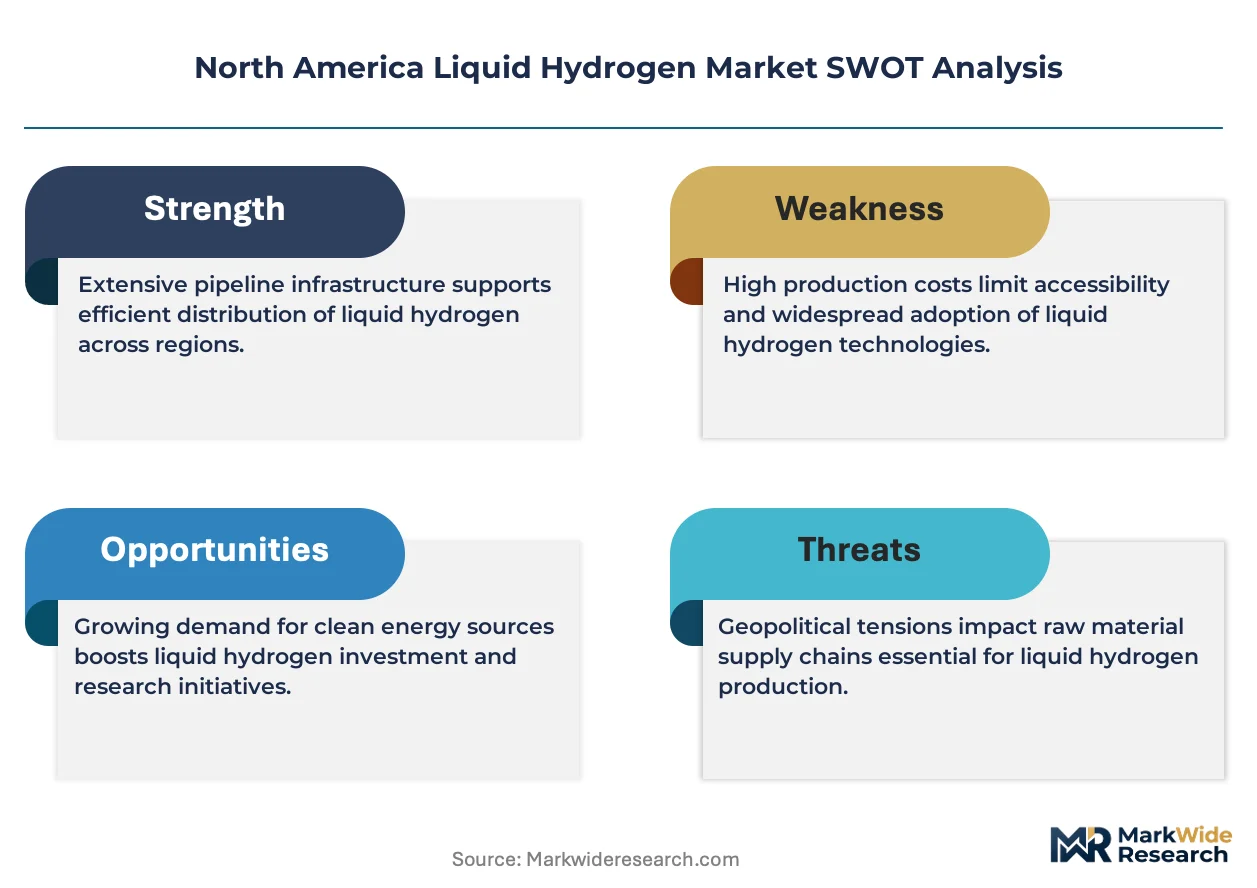
The U.S. Department of Energy hydrogen hub program and Canada's Clean Fuel Regulations jointly shape investment timelines and offtake commitments across the value chain. OSHA process safety management standards and DOT hazardous materials regulations govern liquefaction facility design, truck transport, and terminal operations, creating compliance barriers for new entrants. Stakeholders must monitor final Treasury Department guidance on IRA hydrogen tax credit implementation, as additionality and wage requirements will determine project returns and regional competitive positioning.
Market Dynamics
The U.S. Inflation Reduction Act hydrogen production tax credits are restructuring project economics across the Gulf Coast corridor. Domestic liquefaction capacity decisions now hinge on Treasury Department guidance around additionality and prevailing wage requirements.
Growth Catalysts
- IRA Production Tax Credits:The 45V credit tier structure rewards clean hydrogen output with up to three dollars per kilogram, accelerating developer commitment timelines for Texas and Louisiana megaprojects.
- Heavy-Duty Fleet Electrification Limits:Battery weight and charging duration constraints on long-haul trucking routes are pushing fleet operators toward hydrogen fuel cell alternatives for 500-plus mile corridors.
- Gulf Coast Infrastructure Clustering:Existing petrochemical hydrogen pipelines, salt cavern storage, and deepwater port access concentrate development in Texas and Louisiana, reducing greenfield capital requirements.
Market Restraints
- Cryogenic Energy Penalty:Liquefaction consumes 30-40 percent of hydrogen's energy content, compressing delivered cost competitiveness against compressed gas and on-site electrolysis alternatives.
- Turboexpander Supply Concentration:Large-scale liquefaction plant rotating equipment depends on a limited supplier base in Germany and Japan, creating procurement bottlenecks for North American project schedules.
- DOT Hazardous Materials Friction:49 CFR Part 173 cryogenic liquid transport regulations impose route restrictions, vehicle specifications, and driver certification requirements that constrain distribution network expansion.
Strategic Opportunities
- Canadian Clean Fuel Regulations:Federal carbon intensity reduction mandates for liquid fuels create guaranteed offtake premiums for low-carbon hydrogen in British Columbia and Alberta refining corridors.
- Grid-Scale Energy Storage:Seasonal renewable curtailment in Texas and California is opening utility procurement for hydrogen-based long-duration storage systems with multi-day discharge capability.
- Electrolyzer-Liquefaction Co-location:Integrated green hydrogen production and liquefaction facilities on the Texas Gulf Coast are capturing IRA stackable credits while eliminating intermediate transport costs.
Industry Challenges
- Cryogenic Systems Engineering Talent:Specialized expertise in large-scale hydrogen liquefaction thermodynamics and vacuum insulation systems remains concentrated among a narrow cohort of practitioners with aerospace or industrial gas backgrounds.
- OSHA Process Safety Management:29 CFR 1910.119 compliance for flammable cryogenic facilities demands extensive hazard analysis documentation, mechanical integrity programs, and management of change procedures that extend commissioning timelines.
- Legacy Industrial Gas Contract Structures:Long-term take-or-pay agreements with incumbent suppliers create switching friction for petrochemical and refining customers evaluating new low-carbon hydrogen sources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Liquid Hydrogen Market |
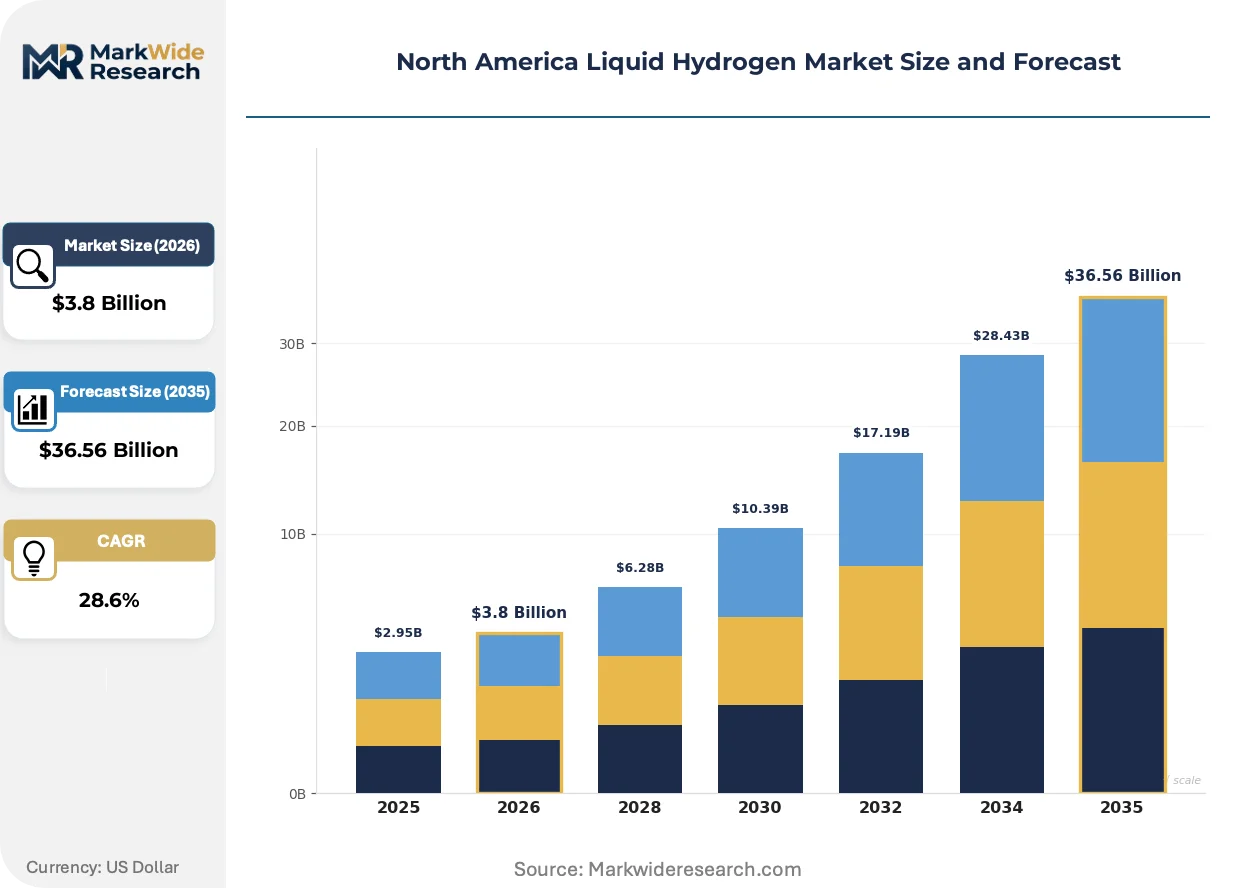
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $36.56 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Aerospace, Automotive, Industrial, Energy Storage Distribution Channel: Bulk Supply, Retail, On-site Production, Special Projects End User: Manufacturing, Defense, Transportation, Research Institutions Technology: Cryogenic, Turboexpanders, Electrolysis, Compression |
| Companies Covered | Linde plc, Air Liquide, Air Products and Chemicals, Inc., Iwatani Corporation, Chart Industries, Plug Power, Chevron Corporation, Kawasaki Heavy Industries, Shell plc, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Liquid Hydrogen Market Trends and Innovations
Modular liquefaction systems and distributed production architectures are compressing the scale threshold for commercially viable hydrogen supply. Technology developers and project sponsors are reconfiguring facility footprints to match regional demand density.
Small-scale hydrogen liquefiers utilizing mixed-refrigerant cycles and magnetic bearing turboexpanders are miniaturizing. Regional fueling station operators in California and Texas are deploying sub-ten-ton-per-day units to serve early heavy-duty fleet corridors without waiting for centralized Gulf Coast supply. This distributed architecture is compressing capital deployment timelines from five-year megaproject cycles to eighteen-month station buildouts.
Canada's Clean Fuel Regulations and the U.S. Treasury 45V guidance are tightening carbon intensity accounting methodologies. Project developers must now secure renewable energy attribute certificates and document hourly matching to claim maximum credit tiers. The refining and ammonia sectors across Alberta, Texas, and Louisiana are responding by restructuring power purchase agreements and advancing electrolyzer project timelines.
Fleet operators are consolidating procurement around total-cost-of-ownership contracts rather than per-kilogram fuel pricing. Heavy-duty trucking companies in California and Texas are negotiating bundled vehicle-maintenance-fuel agreements with infrastructure providers. This shift is most visible in the Ports of Los Angeles and Long Beach, where drayage fleet electrification mandates are accelerating hydrogen fuel cell truck deployment with performance-guaranteed supply contracts.
North America Liquid Hydrogen Market Segmentation
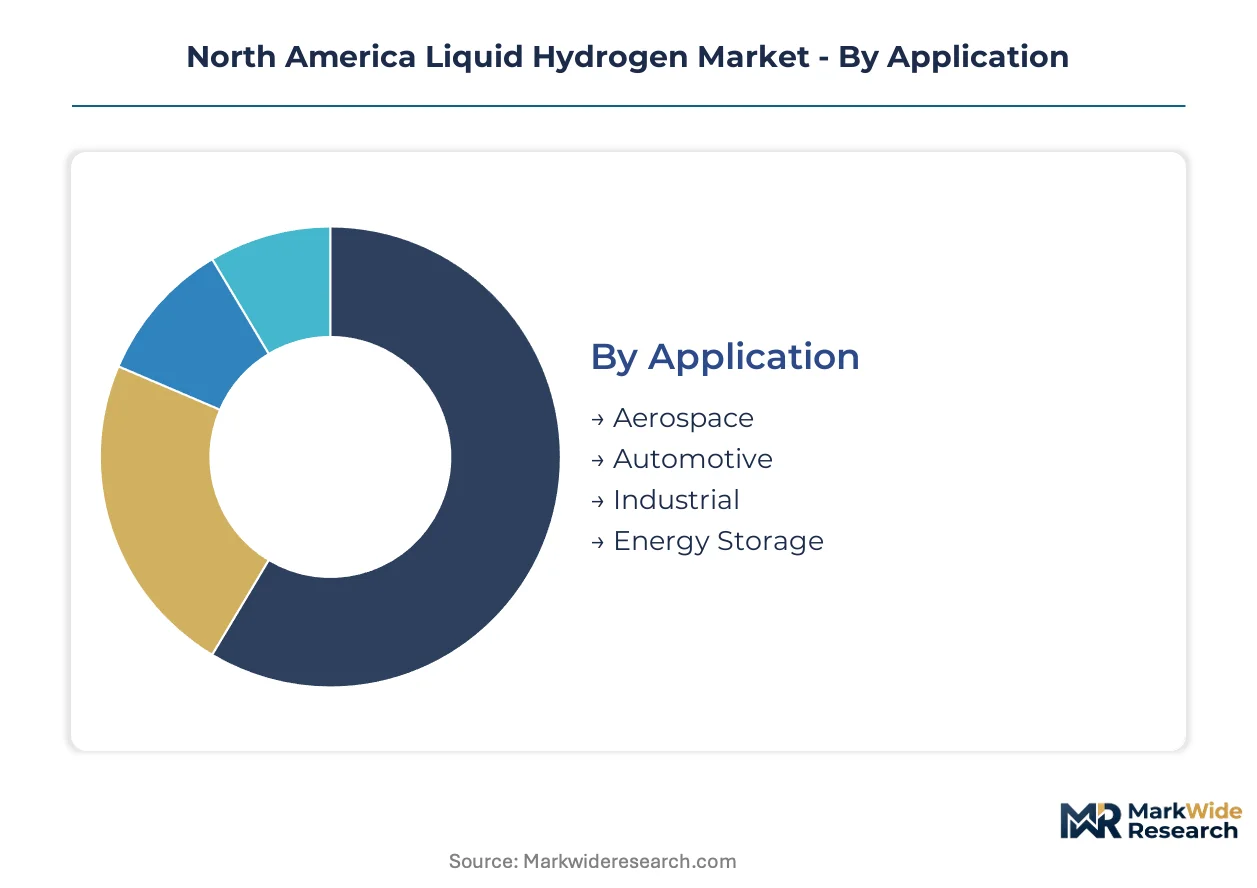
Liquid hydrogen flows through distinct procurement channels shaped by volume scale, purity specifications, and delivery reliability requirements. Each segment category reveals where value concentrates and how infrastructure investments align with buyer priorities.
Application:
Aerospace offtake moves through dedicated bulk supply contracts with long-term scheduling, while automotive demand splinters across retail station networks and fleet direct agreements.
- Aerospace:NASA and commercial launch operators consume high-purity liquid hydrogen under rigid temperature and pressure specifications. Demand clusters at Cape Canaveral, Vandenberg Space Force Base, and emerging commercial spaceports in Texas where dedicated cryogenic logistics chains serve vertical integration requirements.
- Automotive:Heavy-duty fuel cell truck fleets in California and Texas corridors drive procurement through guaranteed supply contracts with infrastructure providers. OEMs negotiate total-cost-of-ownership agreements bundling vehicle, maintenance, and hydrogen delivery to de-risk fleet conversion decisions.
- Industrial:Petrochemical and refining customers source through legacy industrial gas contracts with take-or-pay structures.
- Energy Storage:Utility procurement for grid-scale installations is expanding most quickly in Texas and California renewable curtailment zones.
Aerospace dominates installed base. Energy Storage is where expansion concentrates.
Distribution Channel:
Channel selection tracks volume thresholds and capital deployment timelines, with bulk supply commanding infrastructure investment and on-site production capturing margin in remote locations.
- Bulk Supply:Centralized Gulf Coast liquefaction facilities distribute via cryogenic tanker truck and rail to regional terminals. Air Products and Linde operate dedicated fleets under DOT 49 CFR Part 173 compliance, with route optimization software minimizing boil-off losses during multi-day transits.
- On-site Production:Electrolyzer-liquefaction co-location at Texas industrial parks eliminates intermediate transport and captures IRA stackable credits. Developers target 10-50 ton per day modular systems with eighteen-month deployment cycles versus five-year megaproject timelines.
- Retail:California and Texas fueling stations serve early heavy-duty fleet corridors with sub-ten-ton-per-day liquefiers.
- Special Projects:Defense and research contracts demand custom purity certifications and security-cleared logistics.
Bulk Supply anchors current throughput. On-site Production is climbing the fastest as modular systems compress scale economics.
End User:
Procurement authority fragments across operational buyers seeking supply security and strategic buyers securing long-term carbon reduction pathways.
- Transportation:Fleet operators in California drayage and Texas long-haul corridors negotiate performance-guaranteed fuel contracts with infrastructure providers. Ports of Los Angeles and Long Beach mandates are accelerating hydrogen fuel cell truck deployment with bundled vehicle-maintenance-fuel agreements.
- Manufacturing:Petrochemical and ammonia producers across Texas and Louisiana evaluate low-carbon hydrogen switches under legacy contract renegotiation pressure. Gulf Coast hydrogen hub development is restructuring offtake commitments toward 45V credit-compliant supply.
- Defense:Military applications require hardened supply chains with surge capacity and cybersecurity certifications.
- Research Institutions:National laboratories and universities source through federal procurement vehicles with small-lot flexibility requirements.
Manufacturing holds the largest contract volume. Transportation is gaining share fastest as fleet commitments multiply.
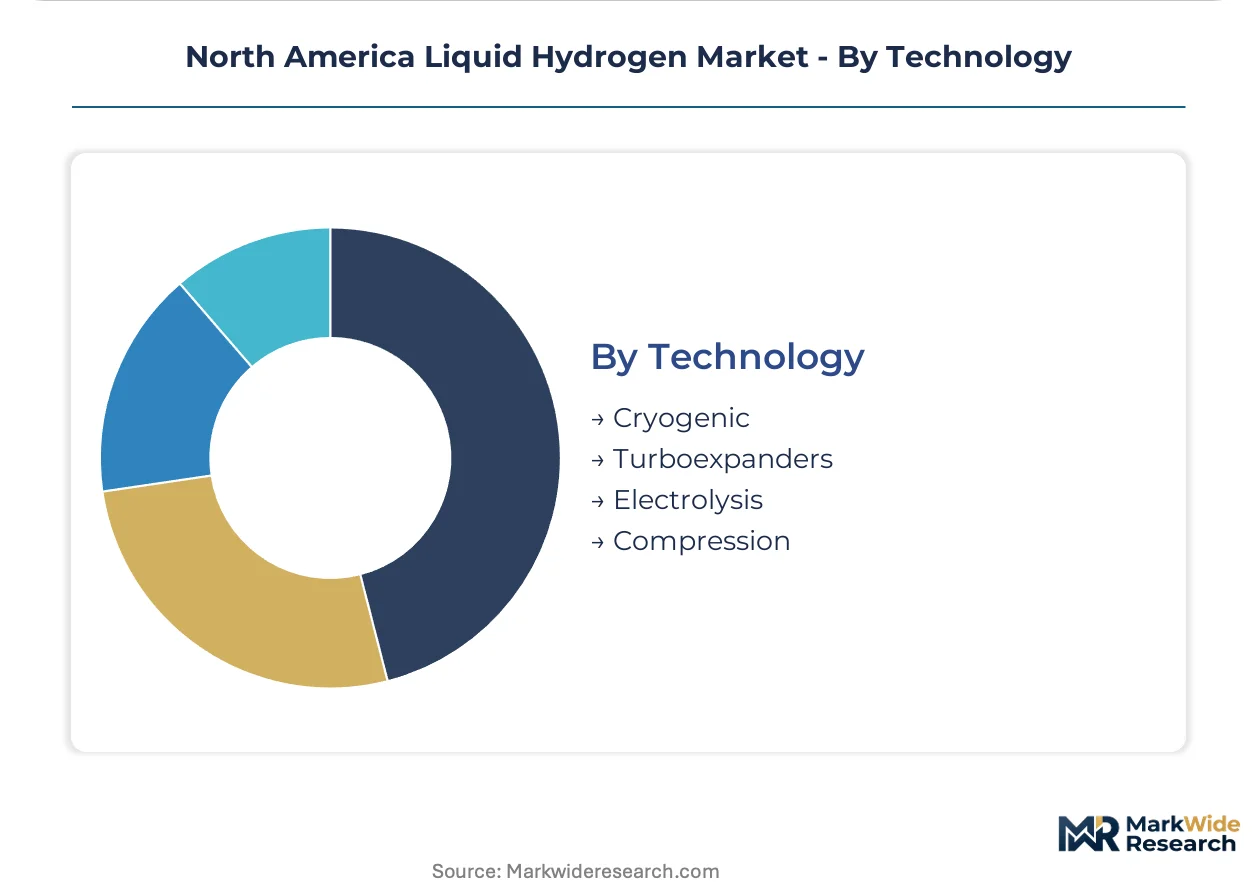
Technology:
Technology selection determines capital intensity, energy efficiency, and operational flexibility, with cryogenic systems dominating large-scale deployment and electrolysis capturing policy support.
- Cryogenic:Multi-stage Claude and Brayton cycle liquefaction achieves minus 253 degrees Celsius with 70.8 kilograms per cubic meter density for efficient transport. Gulf Coast megaprojects deploy 100-plus ton per day trains with vacuum-insulated storage and specialized loading arms.
- Turboexpanders:German and Japanese suppliers control large-scale rotating equipment for hydrogen service, creating procurement bottlenecks. Magnetic bearing variants in small-scale systems reduce maintenance intervals and enable distributed deployment.
- Electrolysis:PEM and alkaline systems integrate with renewable power purchase agreements for IRA credit eligibility.
- Compression:Reciprocating and diaphragm compressors handle intermediate pressure staging before final liquefaction.
Cryogenic systems command installed capacity. Turboexpanders sustain premium margins due to supplier concentration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Heavy-duty fleet operators and aerospace launch providers concentrate demand across distinct sub-regional corridors, with Gulf Coast hydrogen hub development and California zero-emission mandates driving infrastructure deployment timelines.
Texas
Petrochemical hydrogen pipelines and salt cavern storage facilities attract liquefaction megaprojects to the Gulf Coast corridor. IRA 45V tax credit implementation through Treasury Department guidance determines project return thresholds for developers. Houston and Beaumont industrial zones host Air Products and Linde distribution terminals serving regional refining and emerging fuel cell truck corridors.
California
Ports of Los Angeles and Long Beach drayage electrification mandates accelerate hydrogen fuel cell truck deployment with performance-guaranteed supply contracts. California Air Resources Board regulations enforce fleet emission reductions that diesel alternatives cannot satisfy. Central Valley renewable curtailment zones open utility procurement for grid-scale hydrogen storage installations.
Louisiana
Existing ammonia and methanol production facilities create anchor offtake for low-carbon hydrogen switching under legacy contract renegotiation. EPA permitting frameworks for industrial carbon capture influence project siting decisions along the Mississippi River corridor. Baton Rouge and Lake Charles chemical complexes integrate with Gulf Coast hydrogen hub development timelines.
Alberta
Bitumen upgrading and natural gas processing operations evaluate hydrogen blending for carbon intensity reduction under federal Clean Fuel Regulations. Alberta Energy Regulator frameworks govern carbon capture and storage co-location with blue hydrogen production. Edmonton and Calgary industrial corridors advance electrolyzer-liquefaction integration for export positioning.
British Columbia
Abundant hydroelectric capacity supports green hydrogen production cost structures for Asia-Pacific export markets. British Columbia Ministry of Energy and Mines permitting timelines determine project sequencing for port-adjacent liquefaction. Vancouver and Prince Rupert terminals compete for positioning within Pacific hydrogen trade routes.
North America Liquid Hydrogen Market Competitive Landscape
Player mix skews toward integrated industrial gas conglomerates with captive liquefaction technology and established cryogenic distribution networks. Market structure concentrates around three to five dominant operators controlling Gulf Coast production capacity and coastal terminal access. Strategic archetypes include industrial gas incumbents leveraging existing hydrogen infrastructure, energy majors diversifying into low-carbon fuels, and specialized equipment fabricators capturing margins on liquefaction plant components. Competitive moves center on megaproject development partnerships and electrolyzer-liquefaction co-location to capture stackable IRA credits.
Within the industrial gas tier, Air Products and Chemicals, Inc., Linde plc, and Air Liquide occupy positions defined by Gulf Coast production dominance and multi-decade hydrogen supply relationships with petrochemical customers. These entities exemplify the integrated archetype combining captive liquefaction capacity with dedicated cryogenic logistics fleets. Chart Industries represents specialized equipment concentration, with rotating machinery and vacuum insulation systems commanding premium positioning in plant engineering procurement.
| Leading Market Players |
|---|
| Linde plc |
| Air Liquide |
| Air Products and Chemicals, Inc. |
| Iwatani Corporation |
| Chart Industries |
| Plug Power |
| Chevron Corporation |
| Kawasaki Heavy Industries |
| Shell plc |
| Others |
Pricing and Supply Chain Analysis
Electrolyzer-liquefaction co-location on the Texas Gulf Coast is displacing compressed gas delivery for heavy-duty fleet operators while compressing delivered cost structures and redrawing procurement geography toward IRA credit-eligible supply zones.
Pricing Analysis
Cost-plus contracts with natural gas indexation dominate industrial offtake agreements, while fleet operators negotiate total-cost-of-ownership bundles de-risking hydrogen fuel cell conversion. Price differentiation separates aerospace purity grades from industrial specifications, with certification tier and volume scale as primary levers. Pricing pressure stems from cryogenic energy penalties consuming 30-40 percent of hydrogen's energy content, compressing margins against on-site electrolysis alternatives. Petrochemical buyers exhibit highest price sensitivity due to legacy industrial gas contract structures, while aerospace launch operators accept premiums for supply security guarantees.
Supply Chain Analysis
Inventory lead times for turboexpander rotating equipment extend 18-24 months due to German and Japanese supplier concentration, constraining North American liquefaction project schedules. Supply concentrates in the United States Gulf Coast and Alberta, with raw material dependencies on nickel-based alloys, specialized cryogenic insulation, and high-purity hydrogen feedstock. Single-source vulnerability in magnetic bearing turboexpanders creates procurement bottlenecks for distributed liquefaction deployments. Distribution runs through dedicated cryogenic tanker fleets under DOT 49 CFR Part 173 compliance, with regional terminal networks serving heavy-duty corridors in California and Texas.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Compressed hydrogen and battery-electric alternatives threaten liquid hydrogen's long-haul trucking capture, forcing incumbents to defend through co-location economics and credit-stacked supply security.
For Market Incumbents: Shield market position by accelerating electrolyzer-liquefaction integration on the Texas Gulf Coast to capture stackable IRA credits before Treasury guidance finalizes. Deepen backward integration into salt cavern storage and dedicated cryogenic logistics fleets to lock in offtake commitments from refining and ammonia customers facing legacy contract renegotiation pressure. For New Entrants and Emerging Players: Lead with modular sub-ten-ton-per-day liquefaction systems targeting California drayage fleet corridors underserved by centralized Gulf Coast supply. The Ports of Los Angeles and Long Beach electrification mandates create the most penetrable entry point, with performance-guaranteed fuel contracts as the decisive go-to-market angle against incumbent industrial gas structures. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed industrial gas specialists holding Gulf Coast hydrogen hub positioning but lacking green hydrogen certification capabilities. Long-term viability hinges on 45V credit eligibility and hourly renewable matching documentation, with Treasury Department final guidance release as the critical inflection signal for portfolio rebalancing toward credit-compliant developers.| Strategic Initiative | Industry Significance |
|---|---|
| Electrolyzer-Liquefaction Co-location | Captures IRA stackable credits while eliminating intermediate transport costs for Gulf Coast projects. |
| Salt Cavern Storage Development | Provides seasonal buffering capacity essential for grid-scale hydrogen storage procurement in Texas. |
| Turboexpander Supply Agreement | Secures rotating equipment allocation from German and Japanese suppliers amid 18-24 month lead times. |
| Total-Cost-of-Ownership Contracting | Bundles vehicle, maintenance, and fuel delivery to de-risk fleet conversion decisions in California corridors. |
| Clean Fuel Regulations Compliance | Positions Alberta and British Columbia supply for Canadian refining offtake premiums under federal mandates. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with liquefaction plant engineers, heavy-duty fleet procurement directors, hydrogen hub project developers, and industrial gas supply contract managers; and secondary validation through EIA hydrogen production databases, Treasury Department IRA guidance documents, DOT hazardous materials regulations, and FERC infrastructure filings. Bottom-up capacity installation tracking and top-down demand segmentation triangulated volume estimates across application categories.
Forecasts spanning the projection horizon applied multi-dimensional segmentation across aerospace, automotive, industrial, and energy storage applications, with distribution channel splits between bulk supply, on-site production, retail, and special projects. CAGRs derived from capacity buildout timelines, policy implementation schedules, and fleet electrification mandate compliance deadlines. Key inputs included Treasury 45V credit tier eligibility modeling and DOT cryogenic transport regulatory friction coefficients.
Underlying assumptions cover Treasury guidance finalization on additionality and prevailing wage requirements, with deviation risk concentrated in turboexpander procurement bottlenecks and OSHA process safety management compliance timelines. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydrogen Energy
Liquid Organic Hydrogen Carrier (LOHC) Market
Hydrogen Energy
Hydrogen Purification Technologies Market
Hydrogen Energy
Hydrogen Storage Technology Market
Hydrogen Energy
Asia Pacific Liquid Hydrogen Market
Hydrogen Energy
Hydrogen Tanks Market
Hydrogen Energy
Hydrogen Refueling Protocol and Dispenser Performance Test Systems Market
Hydrogen Energy
Blue Hydrogen Market
Hydrogen Energy
Hydrogen Purification Market
Hydrogen Energy
United States Hydrogen Generation Market
Hydrogen Energy
Hydrogen Market
Hydrogen Energy
Liquid Hydrogen Market
Hydrogen Energy
70MPa High Pressure Hydrogen Storage Cylinders Market
Hydrogen Energy
Europe Hydrogen Generation Market
Hydrogen Energy
Hydrogen Ejector Market
Hydrogen Energy
Electrolyzer Market
Hydrogen Energy
On-Site Hydrogen Generator Market