
 Hydrogen Production Electrolyser Market | 2026-2036
Hydrogen Production Electrolyser Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogen Production Electrolyser Market Insights
The EU Carbon Border Adjustment Mechanism is consolidating import competitiveness around electrolyser-based hydrogen for European steel and chemical buyers. Nel Hydrogen anchors Nordic project development through integrated stack manufacturing and filling station deployment. Siemens Energy leverages its energy-sector installed base to bundle grid-balancing electrolysers with renewable power purchase agreements. ITM Power competes on megawatt-scale PEM modularity designed for rapid deployment at industrial harbors.
A hydrogen production electrolyser electrochemically splits water into hydrogen and oxygen using direct current, with alkaline units operating at 1.6-2.0 volts per cell and PEM systems achieving current densities above 2.0 amperes per square centimeter at differential pressures up to 30 bar. PEM electrolyser adoption accelerates where variable renewable integration demands rapid response ramp rates below one second. Solid oxide electrolysers occupy a nascent but thermodynamically efficient niche at temperatures near 800 degrees Celsius where industrial waste heat is available. Alkaline technology sustains cost leadership in large-scale baseload ammonia and refining applications where purity requirements stay below 99.9 percent.
EMA and REACH frameworks in Europe mandate material traceability for catalyst metals and fluorinated membrane chemistries, shaping supplier qualification and recycling obligations. EPA renewable fuel standards and IRA production tax credits in the United States redirect capital toward domestic electrolyser manufacturing and green hydrogen hubs. China's GB standards and dual carbon goals enforce efficiency benchmarks and localization requirements that filter market access for imported stack assemblies. Stakeholders must monitor evolving certification regimes for hydrogen purity and carbon intensity that will determine offtake eligibility across jurisdictions.
Market Dynamics
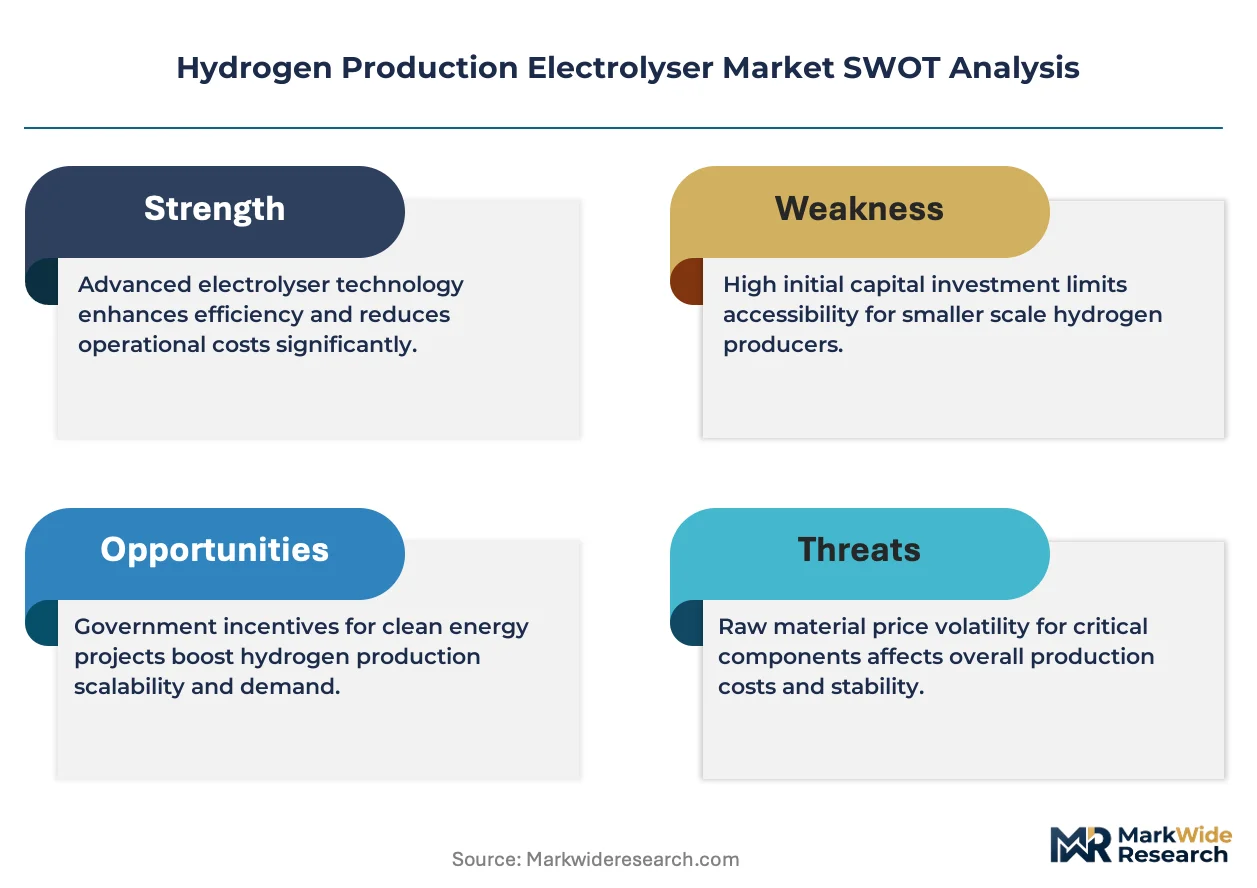
PEM stack architectures with sub-0.3 mg per square centimeter iridium loadings are compressing alkaline cost advantages in high-purity hydrogen segments, forcing incumbent manufacturers to accelerate catalyst efficiency programs or cede margin in premium applications.
Growth Catalysts
- EU Carbon Border Adjustment Mechanism:European steel and chemical buyers now face embedded carbon tariffs on imports, redirecting procurement toward electrolyser-based hydrogen with verifiable low-carbon intensity. German steelmakers have initiated long-term offtake agreements to secure compliance-grade supply.
- Industrial cluster convergence:Coastal zones in China, Norway, and Australia combine stranded renewable assets with concentrated ammonia, refining, and maritime fuel demand, creating self-reinforcing project ecosystems that de-risk capital deployment.
- PEM ramp-rate performance:Sub-second response times to variable renewable input enable electrolyser operators to capture price arbitrage in wholesale electricity markets, improving project economics beyond static LCOH calculations.
Market Restraints
- Iridium supply concentration:Over eighty percent of primary iridium extraction occurs in South African platinum-group metal mines, creating single-point vulnerability for PEM catalyst supply chains and exposing stack manufacturers to geopolitical and labor disruption risks.
- Alkaline purity ceiling:Baseline alkaline systems struggle to deliver hydrogen above 99.9 percent purity without auxiliary purification, limiting addressable market share in semiconductor and fuel-cell vehicle applications where contamination thresholds are stringent.
- Grid interconnection queues:Multi-year transmission access delays in jurisdictions with renewable curtailment prevent electrolyser projects from reaching operational status despite secured equipment and offtake contracts.
Strategic Opportunities
- Industrial waste heat integration:Solid oxide electrolyser technology operating near 800 degrees Celsius can substitute purchased electricity with recovered thermal energy from cement, glass, and steel production, opening efficiency gains unavailable to liquid-electrolyte systems.
- US domestic manufacturing incentives:IRA production tax credits and domestic content bonuses create favorable project economics for electrolyser assembly facilities serving Gulf Coast hydrogen hub networks.
- Maritime fuel bunkering:Ammonia and methanol synthesis from electrolytic hydrogen is expanding into port infrastructure, with Singapore, Rotterdam, and Shanghai developing dedicated loading and storage facilities for deep-sea vessel refueling.
Industry Challenges
- Membrane fluoropolymer processing expertise:Perfluorinated sulfonic acid membrane casting and quality assurance requires specialized chemical engineering talent concentrated in a handful of supplier organizations, constraining stack manufacturing scale-up.
- Certification timeline compression:Emerging hydrogen purity and carbon-intensity certification regimes across the EU, Japan, and South Korea impose overlapping compliance requirements that extend project development cycles and increase documentation burden.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogen Production Electrolyser Market |
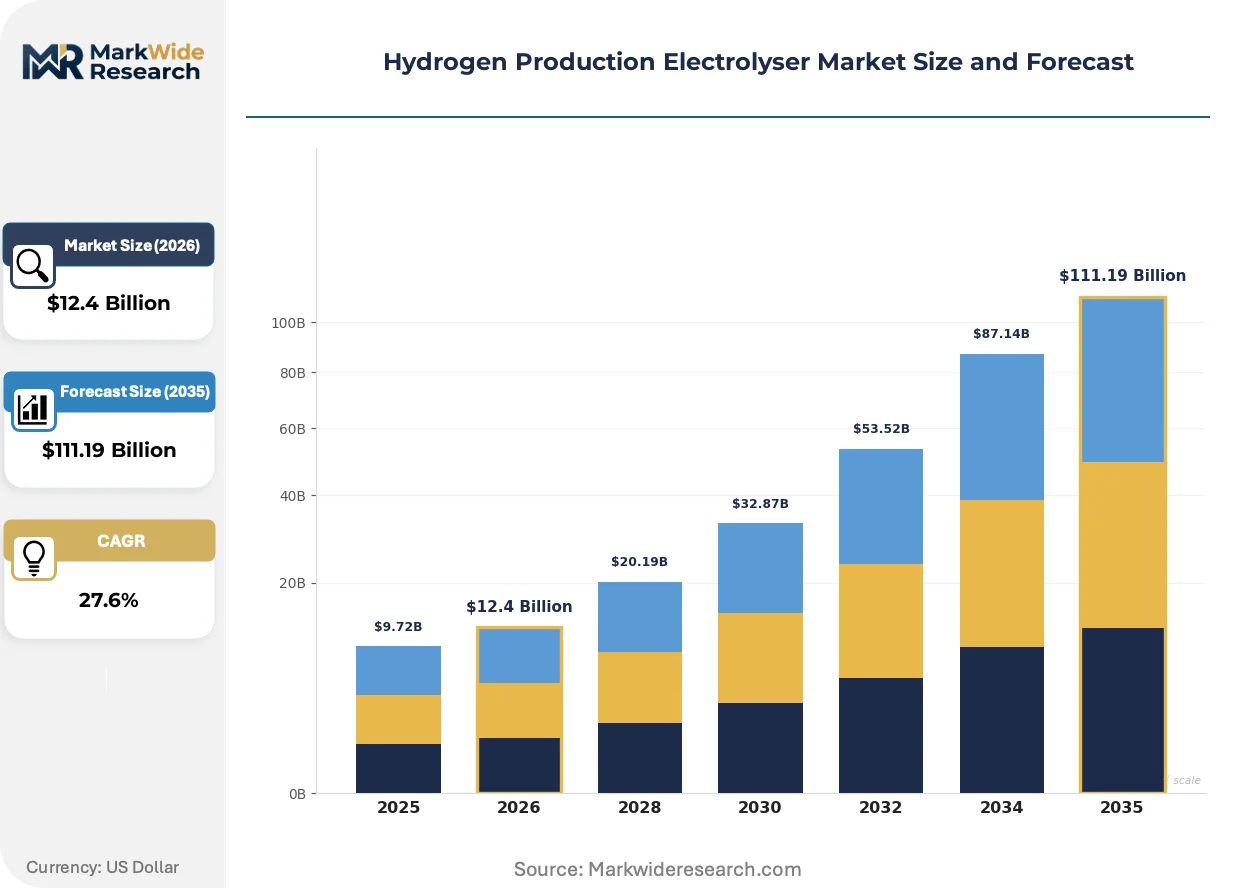
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $111.19 Billion |
| CAGR (2026 – 2036) | 27.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Alkaline Electrolyser, PEM Electrolyser, Solid Oxide Electrolyser, Others Technology: Electrochemical, Thermochemical, Photochemical, Biochemical Application: Energy Storage, Industrial Hydrogen, Fuel Cell Vehicles, Metal Processing End User: Power Generation, Chemical Manufacturing, Steel Production, Aerospace |
| Companies Covered | Nel Hydrogen, ITM Power, Plug Power, Siemens Energy, thyssenkrupp nucera, John Cockerill, McPhy Energy, LONGi, Cummins Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogen Production Electrolyser Market Trends and Innovations
Electrolyser system architectures are converging with power electronics and digital controls to enable autonomous operation in high-renewable-penetration grids, compressing the traditional separation between generation asset management and hydrogen production scheduling.
Anion exchange membrane technology is expanding into the cost-sensitive middle market between alkaline and PEM systems, offering intermediate purity without precious metal catalysts. Chemical process industries in Southeast Asia are piloting AEM units for captive ammonia production where capital constraints exclude PEM procurement. This technology is expanding into applications previously reserved for refurbished alkaline equipment, compressing second-hand equipment residual values.
REACH and F-Gas Regulation amendments in Europe now mandate full material traceability for fluorinated membrane chemistries and catalyst metals, forcing stack manufacturers to requalify suppliers and establish recycling partnerships. Industrial buyers in the Netherlands and Belgium have delayed project final investment decisions pending compliance verification. The certification burden falls most heavily on imported stack assemblies from jurisdictions without equivalent disclosure frameworks.
Steel producers are consolidating hydrogen procurement through direct equity participation in electrolyser projects rather than arm's-length offtake contracts. ArcelorMittal, Nippon Steel, and POSCO have each announced captive or joint-venture electrolyser developments tied to specific blast furnace conversion timelines. This vertical integration pattern is most visible in Germany and Japan where carbon border exposure is immediate and domestic equipment manufacturing capacity is limited.
Hydrogen Production Electrolyser Market Segmentation
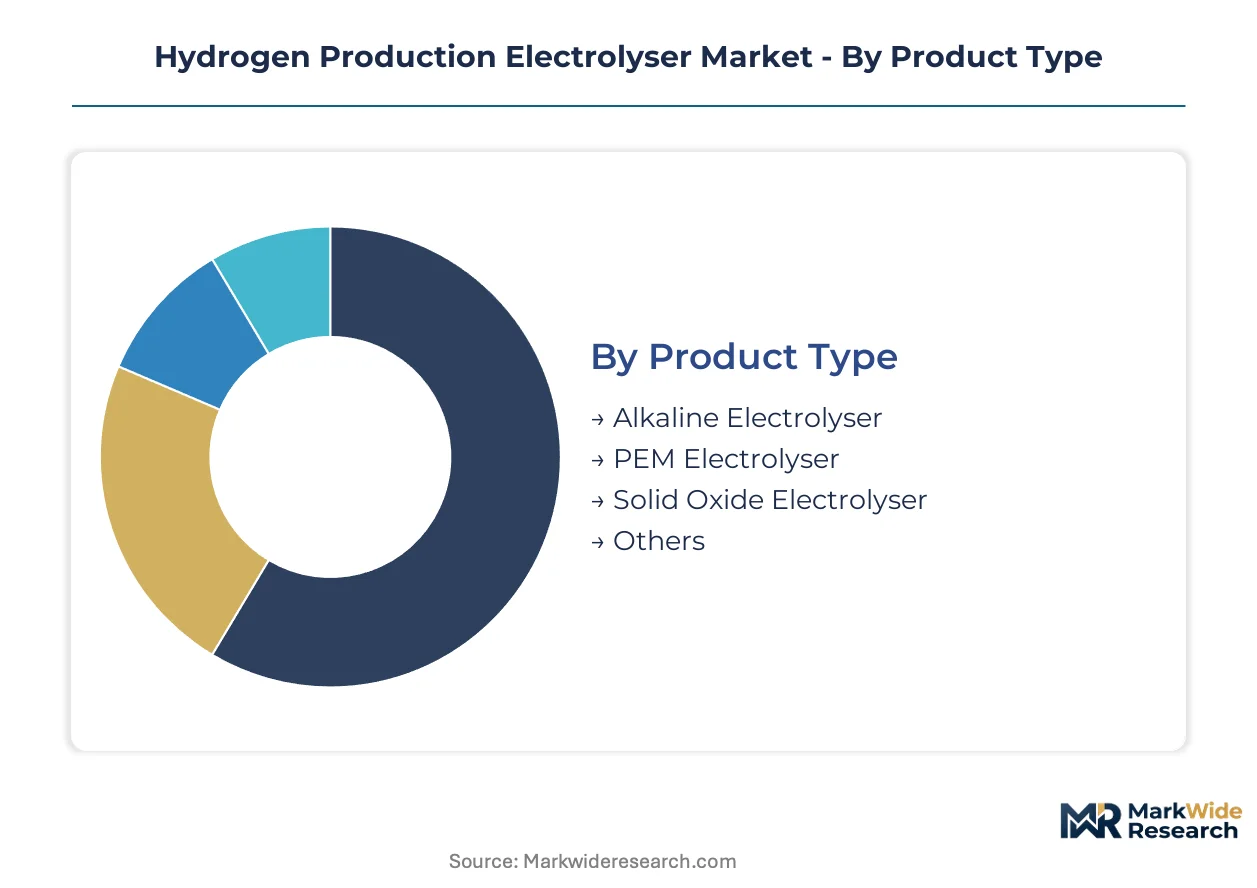
Electrolyser procurement decisions hinge on certification compatibility with end-use purity standards and carbon-intensity thresholds. Segmentation reveals where capital concentrates across technology readiness levels and regulatory compliance burdens.
Product Type:
Certification requirements diverge sharply across stack architectures, with PEM systems facing REACH membrane traceability mandates and alkaline units navigating simpler pressure-vessel approvals.
- PEM Electrolyser:Proton-exchange membrane stacks operate at differential pressures up to 30 bar with current densities above 2.0 amperes per square centimeter. Demand concentrates in German and Japanese steel decarbonization projects where sub-second renewable ramp rates prove essential for grid arbitrage.
- Alkaline Electrolyser:Liquid-potassium-hydroxide systems sustain cost leadership in large-scale ammonia and refining applications. Baseline units dominate Chinese coastal industrial clusters where purity requirements remain below 99.9 percent and capital constraints favor proven equipment.
- Solid Oxide Electrolyser:High-temperature ceramic cells near 800 degrees Celsius target cement and glass waste heat integration.
- Others:Emerging anion exchange membrane units occupy the cost-sensitive middle market without precious metal catalysts.
Leading the category by volume: Alkaline Electrolyser. Growing fastest: PEM Electrolyser.
Technology:
Cost tiers separate commercial-scale deployment from pilot-phase alternatives, with electrochemical systems commanding premium pricing against thermochemical and biochemical alternatives.
- Electrochemical:Direct current water splitting dominates installed capacity across alkaline, PEM, and solid oxide architectures. Norwegian and Australian project developers prioritize this pathway for its compatibility with existing balance-of-plant engineering standards and established safety certification frameworks.
- Thermochemical:High-temperature chemical cycles using solar or nuclear heat remain pre-commercial. Research consortia in Japan and France pilot sulfur-iodine and hybrid sulfur processes for baseload hydrogen without electrical input.
- Photochemical:Direct solar-to-hydrogen conversion via semiconductor photoelectrodes occupies laboratory demonstration. Australian universities and national laboratories lead published research output.
- Biochemical:Microbial and enzymatic hydrogen production from biomass streams serves niche captive applications. Southeast Asian palm oil processors pilot dark fermentation for refinery fuel gas substitution.
Margin concentration sits with Electrochemical. Steepest expansion trajectory: Thermochemical pilot programs.
Application:
Customer type determines volume scale and contract structure, with industrial offtakers committing to decade-long supply agreements against shorter-duration mobility and storage deployments.
- Industrial Hydrogen:Ammonia synthesis, petroleum refining, and methanol production absorb the majority of electrolyser capacity. Rotterdam and Singapore port authorities are developing dedicated bunkering infrastructure for maritime fuel derived from electrolytic hydrogen.
- Energy Storage:Power-to-gas systems convert curtailed renewable electricity into storable hydrogen for seasonal discharge. German transmission system operators procure PEM units for grid balancing services under FERC-style capacity mechanisms.
- Fuel Cell Vehicles:Heavy-duty trucking and bus fleets drive demand for high-purity hydrogen at 99.97 percent. California and South Korea deploy integrated electrolyser-fueling station networks.
- Metal Processing:Direct reduction of iron ore using hydrogen replaces coke in blast furnace conversions. ArcelorMittal and POSCO have announced captive electrolyser developments tied to specific facility retrofits.
Contract value concentrates in Industrial Hydrogen. Fastest volume gains: Metal Processing.
End User:
Supply concentration aligns with geographic clustering of heavy industry, with chemical and steel producers consolidating procurement through direct project equity rather than arm's-length contracts.
- Chemical Manufacturing:Ammonia and methanol producers represent the most mature demand segment with established purity specifications and pipeline delivery infrastructure. BASF and Yara International anchor project development in Antwerp and Norway.
- Steel Production:Carbon border exposure in Germany and Japan accelerates direct reduction investments. Thyssenkrupp and Nippon Steel have initiated long-term offtake agreements for compliance-grade hydrogen supply.
- Power Generation:Gas turbine blending and dedicated hydrogen-fired plants create seasonal demand peaks. Utility procurement favors alkaline systems for baseload ammonia cracking.
- Aerospace:Sustainable aviation fuel synthesis from electrolytic hydrogen remains nascent. Airbus and Rolls-Royce consortiums pilot power-to-liquid kerosene for narrow-body compatibility.
Procurement volume leads with Chemical Manufacturing. Share expansion: Steel Production.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rotterdam anchors the densest concentration of electrolyser project development, with port authorities constructing dedicated ammonia bunkering terminals to serve North Sea shipping corridors.
Germany
Steel decarbonization drives procurement urgency, with Thyssenkrupp and Salzgitter AG committing to hydrogen-based direct reduction timelines. The EU Carbon Border Adjustment Mechanism tightens compliance windows for import-exposed producers. Industrial clusters in the Ruhr and coastal Lower Saxony host the majority of announced electrolyser deployments tied to blast furnace conversions.
China
Coastal ammonia and refining demand absorbs alkaline electrolyser capacity at scale. GB efficiency benchmarks and dual carbon goals enforce localization requirements that filter imported stack assemblies. The Yangtze River Delta and Shandong Peninsula concentrate manufacturing and project development where state-backed offtake guarantees de-risk capital deployment.
United States
Gulf Coast hydrogen hub networks attract electrolyser assembly investment under IRA production tax credits and domestic content bonuses. EPA renewable fuel standards redirect refinery demand toward low-carbon hydrogen pathways. Texas and Louisiana industrial corridors combine curtailed renewable access with established pipeline infrastructure for ammonia and methanol synthesis.
Norway
Stranded hydroelectric assets power coastal electrolyser installations serving European ammonia export markets. Nel Hydrogen anchors integrated project development through domestic stack manufacturing and filling station deployment. The Vestland region concentrates equipment production and maritime fuel pilot programs for deep-sea vessel refueling.
Australia
Solar and wind curtailment creates feedstock cost advantages for export-oriented hydrogen and ammonia projects. National laboratories pilot photochemical and thermochemical pathways alongside commercial electrochemical deployment. The Pilbara and Gladstone industrial zones host the largest announced electrolyser capacities targeting Asian offtake markets.
Hydrogen Production Electrolyser Market Competitive Landscape
Premium-margin players sit above commodity-margin players across catalyst efficiency and membrane traceability dimensions. The vendor base stratifies between integrated energy conglomerates with power-sector installed bases and specialized electrolyser pure-plays focused on stack modularity. Three archetypes dominate: Nordic integrated developers, German industrial conglomerates with chemical process expertise, and Chinese scale manufacturers leveraging domestic supply chains. Competitive moves concentrate on backward integration into iridium recycling partnerships and geographic expansion into Gulf Coast hydrogen hub networks.
Among Nordic integrated developers, Nel Hydrogen exemplifies the project-development-plus-manufacturing archetype. German industrial conglomerates anchor the premium-tier vector, with thyssenkrupp nucera occupying a position tied to steel-sector decarbonization timelines. Chinese scale manufacturers include LONGi, which sits within the cost-leadership tier serving baseline purity applications. These three represent distinct strategic postures: captive supply chain control, end-use vertical integration, and manufacturing scale respectively.
| Leading Market Players |
|---|
| Nel Hydrogen |
| ITM Power |
| Plug Power |
| Siemens Energy |
| thyssenkrupp nucera |
| John Cockerill |
| McPhy Energy |
| LONGi |
| Cummins Inc. |
| Others |
Pricing and Supply Chain Analysis
Sovereign-backed producers in China and Norway anchor electrolyser stack manufacturing, translating state-guaranteed offtake into pricing discipline that resists margin erosion despite iridium cost volatility. Their captive access to stranded renewable assets and domestic catalyst recycling partnerships insulate project economics from supply shocks that pressure privately financed competitors.
Pricing Analysis
Value-based pricing anchored to hydrogen purity certification and carbon-intensity verification dominates contract structures, with PEM systems commanding premiums for sub-second ramp rates that enable wholesale electricity arbitrage. Price differentiation separates REACH-compliant membrane traceability tiers from baseline alkaline units serving ammonia synthesis. Cost compression in the alkaline segment intensifies as Chinese manufacturers scale domestic stack assembly. Chemical buyers in coastal industrial clusters exhibit highest price sensitivity, while semiconductor and fuel-cell vehicle offtakers absorb premiums for 99.97 percent purity guarantees.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Shanghai coordinate hub-and-spoke patterns for membrane and catalyst delivery to project sites. Manufacturing concentrates in China, Germany, and Norway, with iridium sourcing tethered to South African platinum-group metal extraction. Perfluorinated sulfonic acid membrane casting and quality assurance rest on specialized chemical engineering talent concentrated in a handful of supplier organizations. Single-source vulnerability for iridium exposes stack manufacturers to geopolitical disruption. Distribution runs through integrated project developers bundling stack manufacturing with filling station deployment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Carbon Border Adjustment Mechanism transforms electrolyser procurement into a cost-of-compliance story, erecting a regulatory moat around REACH-certified membrane traceability that filters out non-compliant imported stack assemblies.
For Market Incumbents: Acquire iridium recycling partnerships and membrane casting expertise to defend against anion exchange membrane entrants targeting the cost-sensitive middle market. Secure backward integration into catalyst recovery operations in South Africa. Expand capacity in Gulf Coast hydrogen hub corridors under IRA domestic content bonuses before tariff exposure hardens. For New Entrants and Emerging Players: Enter via solid oxide electrolyser waste heat integration partnerships with cement and glass producers in Southeast Asia, where industrial cluster convergence creates captive demand without precious metal dependencies. Target captive ammonia production for palm oil processors facing capital constraints. Lead with efficiency gains from recovered thermal energy rather than purity specifications. For Investors and Strategic Acquirers: Distressed-cycle entries favor Nordic integrated developers with stranded hydroelectric assets and established filling station networks in Norway. Five-to-ten year viability hinges on certification regime convergence across EU, Japan, and South Korea. Watch for project final investment decision delays in the Netherlands and Belgium as REACH and F-Gas Regulation amendments force supplier requalification.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Catalyst Recycling | Secures iridium supply chains against South African labor disruption risks for PEM manufacturers. |
| Membrane Traceability Certification Investment | Unlocks EU Carbon Border Adjustment Mechanism compliance for German steel decarbonization offtake. |
| Waste Heat Integration Partnership | Opens cement and glass sector demand for solid oxide electrolyser efficiency gains near 800 degrees Celsius. |
| Coastal Industrial Cluster Co-location | Combines stranded renewable access with concentrated ammonia demand in China's Yangtze River Delta. |
| Domestic Content Assembly Expansion | Captures IRA production tax credits for Gulf Coast hydrogen hub network equipment supply. |
Research Methodology
Independent corroboration across electrolyser project developers, utility planning officers, and EPC contractors underwrites the qualitative findings, validated against EIA project databases, IEA hydrogen reports, and FERC interconnection filings. Primary fieldwork with stack manufacturing engineers, procurement leads at steel and chemical offtakers, and membrane supplier technical directors combined with customs trade data and SEC equipment manufacturer disclosures. Bottom-up electrolyser deployment tallies triangulate against top-down hydrogen demand projections from national decarbonization roadmaps.
Rate-of-change decomposition across the projection horizon segments volume and value by stack architecture, purity tier, end-use application, and regional regulatory cluster. Electrochemical system CAGRs derive from capacity announcement tracking, final investment decision timelines, and offtake contract duration analysis. Modeled inputs include renewable curtailment rates, grid interconnection queue lengths, and carbon border tariff phase-in schedules without year-specific calibration.
Forecast precision tightens around the base case; tail outcomes carry wider variance under iridium supply disruption or membrane fluoropolymer processing bottleneck scenarios. Outputs reflect documented assumptions around certification timeline compression and localization requirement enforcement. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydrogen Energy
Water Electrolysis Green Hydrogen Production Market
Hydrogen Energy
Hydrogen Composite Tanks Market
Hydrogen Energy
Hydrogen Energy Electrolyzer Market
Hydrogen Energy
Hydrogen for Mobility Market
Hydrogen Energy
Electrolyzer Market
Hydrogen Energy
US Hydrogen Fueling Station Market
Hydrogen Energy
High-Pressure Hydrogen Tanks Market
Hydrogen Energy
Hydrogen Station Market
Hydrogen Energy
Green Hydrogen Energy Storage System Market
Hydrogen Energy
Hydrogen Purifiers Market
Hydrogen Energy
North America Liquid Hydrogen Market
Hydrogen Energy
On-Site Hydrogen Generator Market
Hydrogen Energy
Partial Oxidation Blue Hydrogen Market
Hydrogen Energy
Hydrogen Tanks Market
Hydrogen Energy
Green Energy Hydrogen Production System Market
Hydrogen Energy
Europe Hydrogen Generation Market