
 Green Energy Hydrogen Production System Market | 2026-2036
Green Energy Hydrogen Production System Market Size, Share, and Industry Trends Forecast 2026-2036
Green Energy Hydrogen Production System Market Insights
Project finance channels for green hydrogen infrastructure is tilting toward offtake-backed development models. Siemens Energy leverages its electrolyzer manufacturing scale to anchor European supply chains. Nel ASA competes through vertical integration into stack production and system assembly. ITM Power specializes in PEM technology leadership for utility-scale installations.
Green energy hydrogen production systems integrate renewable electricity with water electrolysis, typically operating at pressures between 30 and 80 bar and efficiencies spanning 60 to 80 percent depending on cell technology. These systems serve industrial decarbonization, transport fueling, and grid-scale energy storage applications. Electrolysis technology dominates installed capacity while fuel cells application segments capture premium margins through aerospace and maritime offtake contracts. Biomass gasification occupies a niche position where waste feedstock availability supports distributed production economics.
EU Green Deal hydrogen strategy and F-Gas Regulation shape equipment standards and import certification requirements across European deployment zones. EPA renewable fuel pathways and IRA production tax credits steer capital allocation toward electrolyzer projects in United States industrial corridors. Stakeholders must track regulatory parity between imported and domestically produced hydrogen to assess offtake contract viability.
Market Dynamics
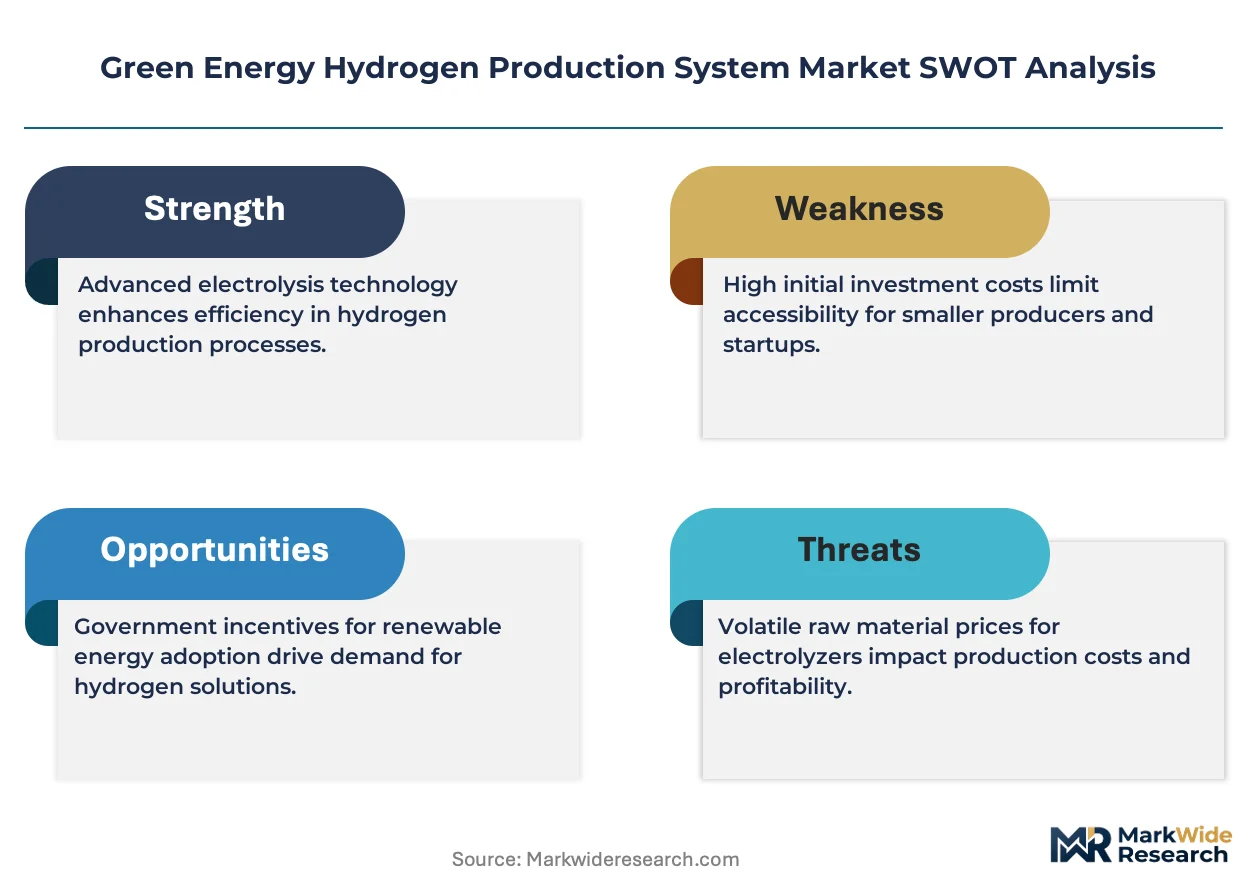
PEM electrolysis technology is compressing alkaline system margins as transport and industrial offtakers prioritize rapid response and compact footprint over capital efficiency. This technology transition concentrates manufacturing investment in electrolyzer stack production capacity.
Growth Catalysts
- EU Green Deal renewable hydrogen mandates:Germany's heavy industry clusters face binding decarbonization timelines that accelerate electrolyzer deployment in steel and chemical corridors.
- China's state-backed hydrogen corridor investments:Gigawatt-scale manufacturing commitments anchor demand for domestically produced electrolyzer systems and compress import dependency.
- PEM stack cost reductions:Platinum-group metal loading efficiency gains and membrane thickness optimization cut stack costs per kilowatt, improving project IRRs for transport fueling applications.
Market Restraints
- Grid electricity price volatility:Renewable power purchase agreement renegotiation clauses expose electrolyzer operators to input cost swings that erode green hydrogen cost parity with gray hydrogen.
- Iridium supply concentration:South African and Russian mining dominance for PEM catalyst materials creates geopolitical concentration risk for stack manufacturers.
- Alkaline system stranded asset risk:Existing installed base in chlor-alkali and heavy industry faces technical obsolescence as PEM systems capture transport-linked premium offtake contracts.
Strategic Opportunities
- India's PLI scheme for electrolyzer manufacturing:Production-linked incentives attract domestic assembly investments to serve Middle East and Southeast Asian export markets.
- Maritime fuel cell propulsion:Ammonia cracking and direct hydrogen bunkering create vessel-scale demand for high-pressure electrolyzer systems at port clusters.
- US IRA production tax credits:Section 45V credit duration and stack domestic content requirements steer capital toward US-based manufacturing and offtake contracting.
Industry Challenges
- Electrolyzer stack technician scarcity:Membrane electrode assembly calibration and catalyst coating expertise concentrates in European and East Asian supplier engineering teams.
- Certification timeline compression:EU F-Gas Regulation and EPA renewable fuel pathway approvals require parallel safety and environmental compliance documentation that extends project development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Green Energy Hydrogen Production System Market |
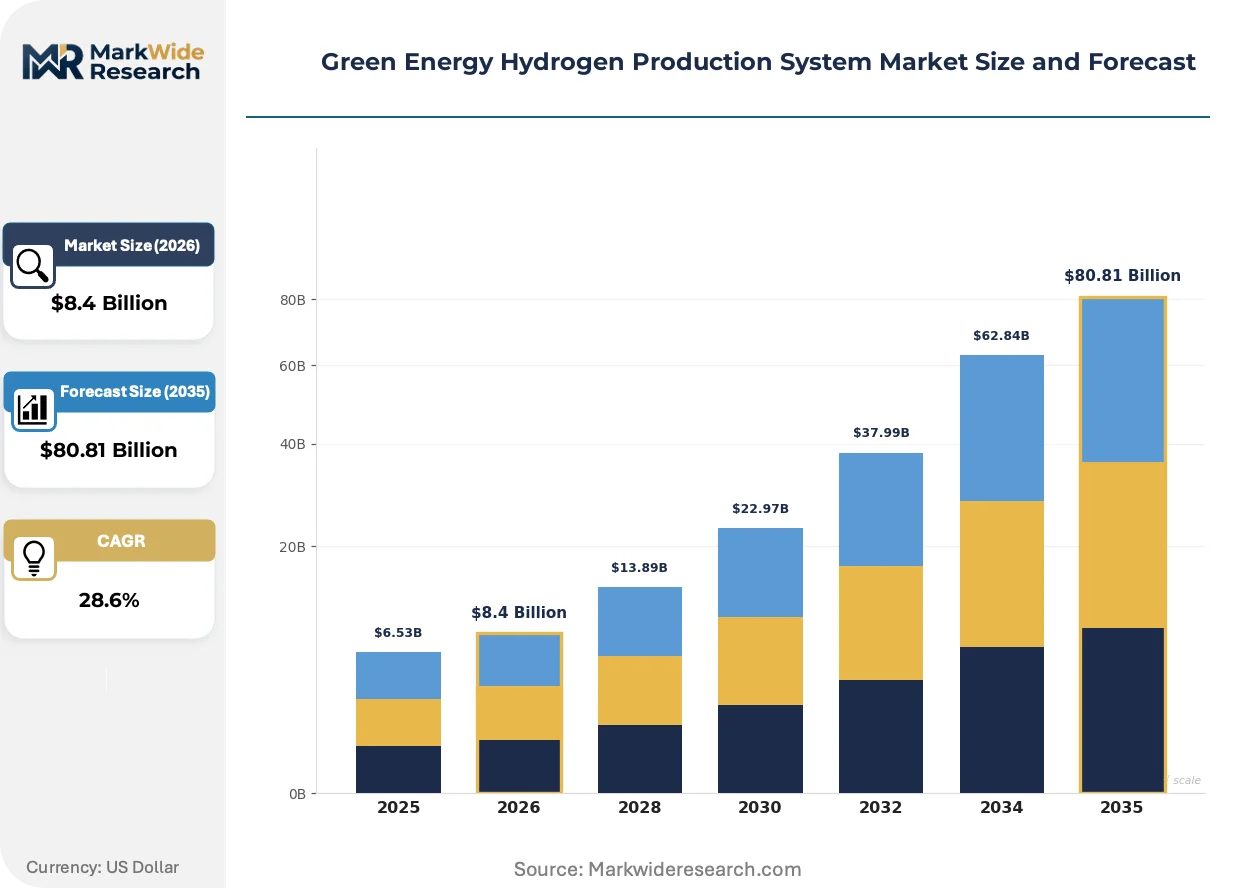
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $80.81 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Electrolysis, Steam Methane Reforming, Biomass Gasification, Photoelectrochemical End User: Industrial, Transportation, Power Generation, Residential Installation: On-Premises, Off-Site, Mobile Units, Renewable Sources Application: Fuel Cells, Chemical Feedstock, Energy Storage, Heating Solutions |
| Companies Covered | Siemens Energy, Air Liquide, Air Products and Chemicals, Nel ASA, Plug Power, ITM Power, Linde, ENGIE, Uniper, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Green Energy Hydrogen Production System Market Trends and Innovations
Electrolyzer system architecture is fragmenting into modular, containerized units that slash installation timelines and enable distributed production economics. This shift is compressing the traditional centralized plant model.
Solid oxide electrolysis cell technology operates at 700-800°C, enabling direct steam feedstock integration with industrial waste heat sources. Steel and ammonia producers in Germany and Japan are piloting hybrid SOEC-PEM configurations. High-temperature operation is rendering obsolete the electrical heating loads that burden conventional low-temperature systems.
The EU F-Gas Regulation tightens fluorinated gas containment standards for electrolyzer cooling systems and hydrogen purification units. Equipment vendors must redesign thermal management architectures to comply with phasedown schedules. European transport fueling projects face accelerated compliance timelines that compress supplier qualification windows.
Industrial offtakers are unbundling electrolyzer supply contracts from long-term maintenance agreements, treating stack replacement as a separate procurement category. This disintermediation pressures OEM service revenue models and opens third-party stack refurbishment markets. German chemical clusters and California refinery conversions exhibit this pattern most visibly.
Green Energy Hydrogen Production System Market Segmentation
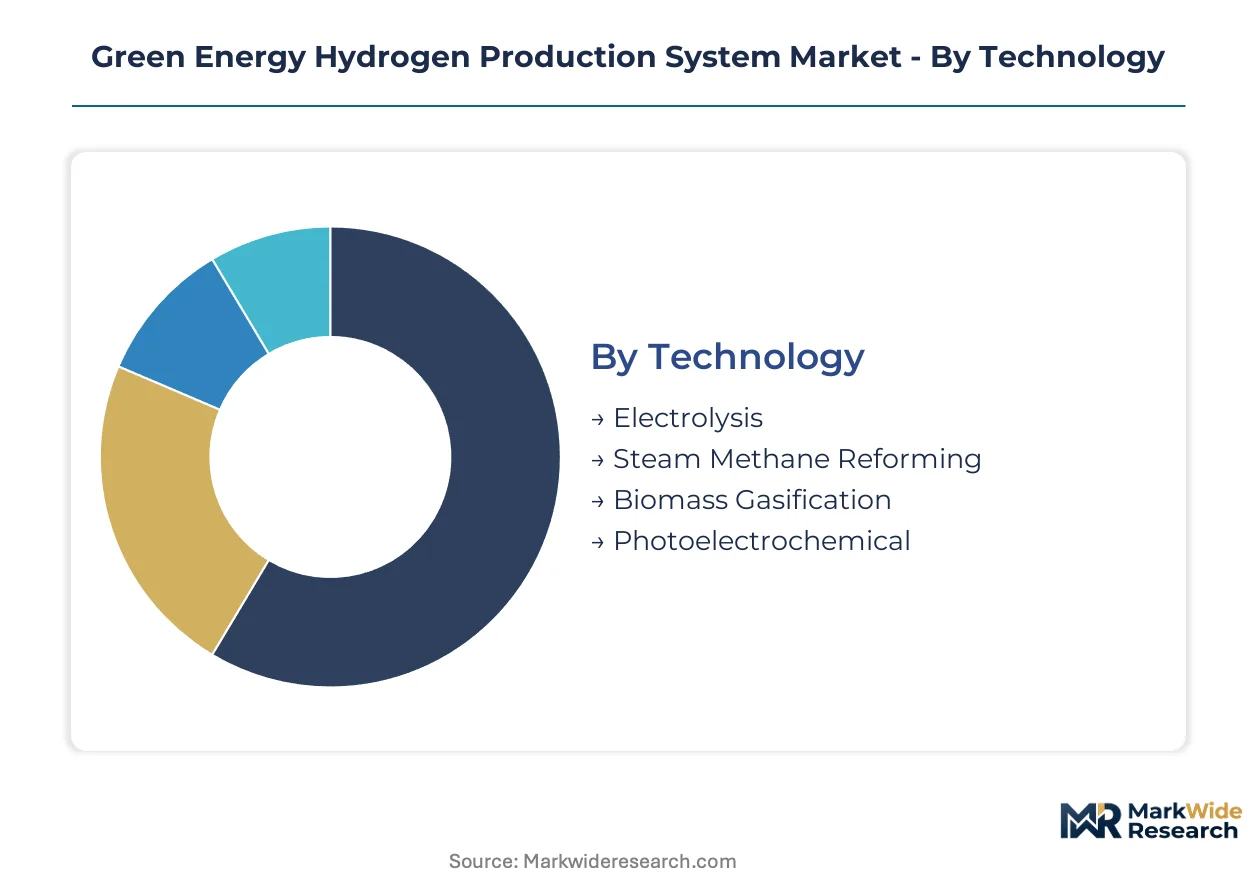
Technology choice dictates stack replacement schedules and membrane electrode assembly refurbishment intensity across the green hydrogen production system market. Service revenue concentration varies sharply by segment, with some categories requiring continuous catalyst recoating while others operate with minimal intervention.
Technology:
After-sales service intensity separates electrolysis from competing pathways, with stack degradation curves driving multi-year maintenance contracts and refurbishment revenue pools.
- Electrolysis:Water splitting via alkaline or PEM cells operates at 60-80% efficiency with stack lifespans of 50,000-80,000 hours. Germany's steel corridors and China's hydrogen valleys anchor demand for megawatt-scale systems with intensive membrane replacement schedules.
- Steam Methane Reforming:Natural gas reforming with carbon capture retrofits serves existing industrial hydrogen users seeking incremental decarbonization. Gulf Coast refinery clusters in the United States and Rotterdam's chemical harbors deploy these systems where grid electricity costs disadvantage electrolysis.
- Biomass Gasification:Waste-to-hydrogen conversion via high-temperature pyrolysis suits distributed production near forestry and agricultural residue sources. Nordic district heating networks pilot these units for seasonal hydrogen injection.
- Photoelectrochemical:Direct solar-to-hydrogen conversion eliminates separate renewable power purchase agreements through integrated semiconductor-liquid junctions. Japanese research consortia and Australian desert demonstration sites test durability against photocorrosion degradation.
By volume, electrolysis leads. By growth pace, photoelectrochemical is climbing the fastest.
End User:
Capital deployment scale and offtake contract duration vary dramatically across customer categories, with industrial users committing to decade-long supply agreements while residential segments remain nascent.
- Industrial:Ammonia synthesis, steel direct reduction, and methanol production consume hydrogen at multi-tonne-per-day scale. Germany's Ruhr industrial cluster and China's Ningxia coal-chemical corridor anchor electrolyzer deployments with 20-year power purchase agreements.
- Transportation:Heavy-duty fuel cell trucks, maritime ammonia bunkering, and aviation synthetic fuel offtake create demand for high-pressure, high-purity hydrogen. California's port drayage corridors and Rotterdam's shipping lanes lead deployment.
- Power Generation:Grid-scale storage and gas turbine blending applications utilize hydrogen for seasonal electricity arbitrage. Texas and South Australia integrate electrolyzers with wind and solar farms for dispatchable renewable output.
- Residential:Combined heat and power fuel cells and heating system retrofits serve single-family and multi-unit buildings. Japan's ENE-FARM program and South Korean apartment complexes pilot distributed electrolyzer-fed networks.
Industrial offtake dominates absolute consumption. Transportation contracts are gaining share fastest.
Installation:
Site configuration determines balance-of-plant complexity, with mobile and remote installations commanding premium pricing for containerized integration and autonomous operation capabilities.
- On-Premises:Dedicated electrolyzer installations at industrial facilities enable direct pipeline connection to hydrogen consumers. German chemical parks and Saudi ammonia plants favor this model for supply security.
- Off-Site:Centralized production hubs with pipeline or tube-trailer distribution serve dispersed offtakers. Netherlands' port clusters and Spain's solar-hydrogen valleys export to northwest European industrial users.
- Mobile Units:Containerized, transportable electrolyzer systems enable temporary deployment for construction sites, mining operations, and emergency response. Australian remote mining camps and Canadian oil sands operations lease these for diesel displacement.
- Renewable Sources:Co-located solar, wind, or hydroelectric integration eliminates grid interconnection costs and curtailment exposure. Morocco's wind-hydrogen complexes and Iceland's geothermal-powered plants exemplify this architecture.
Off-site installations handle the largest throughput volumes. Mobile units are expanding most quickly.
Application:
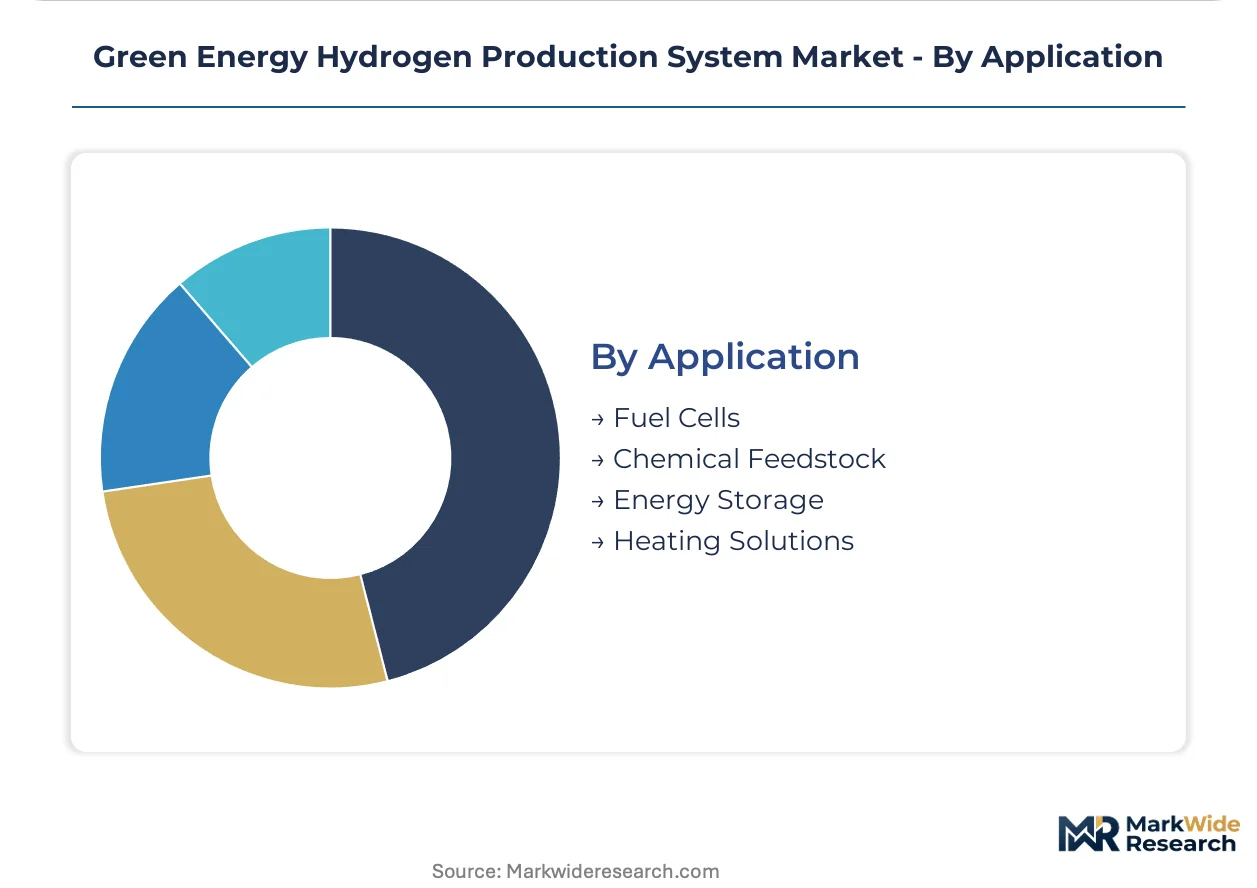
Purity specifications and pressure requirements fragment the application landscape, with fuel cells demanding 99.97% purity while heating solutions tolerate lower grades.
- Fuel Cells:Proton exchange membrane and solid oxide fuel cells require ultra-high purity hydrogen with carbon monoxide below 0.2 ppm. South Korean automotive manufacturing and California transit agencies drive quality certification standards.
- Chemical Feedstock:Ammonia, methanol, and synthetic fuel synthesis consume hydrogen at massive scale with moderate purity requirements. US Gulf Coast fertilizer producers and Middle East petrochemical complexes anchor this segment.
- Energy Storage:Power-to-gas and power-to-liquid systems store surplus renewable electricity for seasonal discharge. German salt cavern storage and Danish liquid organic hydrogen carrier projects lead integration.
- Heating Solutions:Natural gas grid blending and dedicated hydrogen boilers utilize lower-grade hydrogen for residential and commercial thermal loads. UK pilot programs and Dutch district heating networks test 20% hydrogen injection.
Chemical feedstock absorbs the greatest volume. Fuel cell applications are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany commands pricing power through EU Green Deal hydrogen subsidies while China compresses electrolyzer costs via state-backed manufacturing scale. This asymmetry fragments procurement strategies across industrial corridors.
Germany
Ruhr steel clusters and chemical parks in North Rhine-Westphalia anchor electrolyzer demand for direct iron reduction and ammonia synthesis. The EU F-Gas Regulation mandates fluorinated gas containment standards that tighten equipment certification timelines. Hamburg's port infrastructure hosts PEM electrolyzer deployments for maritime ammonia bunkering trials.
China
Ningxia coal-chemical corridors and Inner Mongolia wind-hydrogen complexes drive gigawatt-scale electrolyzer procurement. National dual carbon goals enforce renewable hydrogen quotas for heavy industry decarbonization. Zhangjiakou's hydrogen valley hosts state-backed manufacturing commitments that reduce import dependency for stack components.
United States
Texas wind-solar hybrid sites and California port drayage corridors concentrate electrolyzer deployments for grid storage and transport fueling. EPA renewable fuel pathways and IRA Section 45V production tax credits steer capital toward domestic manufacturing. Gulf Coast refinery clusters in Louisiana pursue ammonia exports using high-pressure electrolyzer systems.
India
Gujarat's chemical parks and Maharashtra's industrial corridors pilot electrolyzer installations for fertilizer and steel decarbonization. The PLI scheme for electrolyzer manufacturing attracts domestic assembly investments to serve Middle East export markets. Tamil Nadu's renewable energy zones host gigawatt-scale green hydrogen hub proposals.
Japan
Kansai industrial zones and Chubu manufacturing belts import electrolyzer systems for ammonia co-firing and semiconductor-grade hydrogen. METI hydrogen roadmaps mandate cost reduction targets that accelerate technology partnerships. Kyushu's renewable energy islands test offshore wind-to-hydrogen integration for export markets.
Green Energy Hydrogen Production System Market Competitive Landscape
Industrial conglomerates and specialized electrolyzer fabricators split the market along technology and geography vectors. Siemens Energy and Air Liquide anchor consolidated positions through integrated project development capabilities. Three archetypes dominate: diversified energy majors with balance-sheet scale, pure-play electrolyzer specialists with stack manufacturing depth, and industrial gas incumbents with distribution infrastructure. Competitive moves concentrate on manufacturing capacity expansion and strategic partnerships for offtake contracting.
Among European-based industrial groups, Siemens Energy, Air Liquide, and Linde occupy positions spanning electrolyzer supply through to hydrogen distribution infrastructure. Nel ASA and ITM Power exemplify the specialist archetype with focused stack production capabilities. Plug Power represents North American positioning in fuel cell-integrated hydrogen systems. These five entities anchor competitive dynamics without exhaustively mapping the vendor landscape.
| Leading Market Players |
|---|
| Siemens Energy |
| Air Liquide |
| Air Products and Chemicals |
| Nel ASA |
| Plug Power |
| ITM Power |
| Linde |
| ENGIE |
| Uniper |
| Others |
Pricing and Supply Chain Analysis
Electrolyzer overcapacity in China compresses stack pricing globally while forcing European manufacturers toward configured-to-order premium positioning. This utilization divergence rewards state-backed gigawatt-scale producers with volume economics while squeezing mid-tier suppliers into niche customization segments.
Pricing Analysis
The customization-premium spread separates standard alkaline systems from configured PEM configurations with integrated purification and compression. Project-based long-term offtake contracts dominate industrial procurement, with price differentiation hinging on stack efficiency certification and after-sales service bundling. Cost compression in standard alkaline tiers intensifies as Chinese state-backed manufacturing scales, while transport fueling applications show least price sensitivity due to regulatory compliance premiums.
Supply Chain Analysis
Upstream feedstock concentration for platinum-group metals centers on South African mining operations and Russian palladium extraction, creating catalyst cost volatility that ripples through stack manufacturing. Iridium and titanium dependencies draw from concentrated geological sources, with single-source vulnerability for membrane electrode assembly coatings. Distribution runs through integrated project developers and EPC contractors serving industrial corridor deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Technology fragmentation across alkaline, PEM, and solid oxide architectures creates specialist niches as industrial offtakers unbundle stack supply from maintenance contracts.
For Market Incumbents: Build captive iridium sourcing moats through offtake agreements with South African mining consortia. Siemens Energy and Air Liquide should deepen backward integration into membrane electrode assembly production to defend against Chinese stack cost compression. Securing EPA renewable fuel pathway pre-certification for integrated system architectures blocks entrant qualification timelines. For New Entrants and Emerging Players: Establish a beachhead in India's PLI-subsidized electrolyzer assembly segment serving Middle East export markets. Maritime ammonia bunkering infrastructure at Rotterdam and Singapore ports offers penetrable demand with limited incumbent service presence. Target containerized mobile unit leasing for Australian mining camps with diesel displacement mandates. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among stack refurbishment specialists with membrane electrode assembly recoating capabilities. Long-term viability across the analysis window favors acquisition targets with iridium loading efficiency patents and SOEC-PEM hybrid pilot credentials. Watch F-Gas Regulation compliance timeline acceleration as inflection signal for European vendor consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Stack Manufacturing Capacity Expansion | Siemens Energy's gigawatt-scale commitments anchor European supply security under EU Green Deal mandates. |
| Backward Integration into Catalyst Coating | Nel ASA's membrane electrode assembly in-house production captures margin from iridium supply volatility. |
| Long-term Offtake Contracting | Industrial clusters in Germany's Ruhr region lock in 20-year hydrogen supply agreements with project developers. |
| Technology Licensing for SOEC Hybrids | Japanese steel producers pilot waste heat integration reducing electrical load for ammonia synthesis feedstock. |
| Green Certification Program Alignment | EPA renewable fuel pathway approvals determine IRA Section 45V credit eligibility for US Gulf Coast projects. |
Research Methodology
Operator-level perspectives from electrolyzer procurement managers at German chemical parks, EPC contractors in Middle East hydrogen hubs, and stack engineering leads at PEM specialists anchored the qualitative base. Secondary validation drew from EU hydrogen strategy implementation reports, EPA renewable fuel pathway dockets, and customs data tracking electrolyzer component trade flows. Bottom-up installation forecasts triangulated against top-down policy target aggregations.
Scenario-bracketing around IRA credit duration assumptions and EU F-Gas Regulation phase-in timelines bounded the projection horizon. Segmentation modeling spanned technology choice, end-use application, and regional regulatory framework clusters. CAGRs derived from electrolyzer deployment pipelines and industrial offtake contract visibility, with stack cost learning curves and iridium price sensitivity as key inputs.
Sensitivities concentrate around South African mining disruptions for iridium supply and EU renewable hydrogen mandate enforcement timing. Cross-checking against IEA hydrogen project tracking databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydrogen Energy
Europe Clean Hydrogen Market
Hydrogen Energy
Hydrogen Energy Electrolyzer Market
Hydrogen Energy
Alkaline Water Electrolysis Market
Hydrogen Energy
Hydrogen for Mobility Market
Hydrogen Energy
PEM Water Electrolytic Hydrogen Production System Market
Hydrogen Energy
Asia-Pacific Clean Hydrogen Market
Hydrogen Energy
US Hydrogen Fueling Station Market
Hydrogen Energy
Liquid Hydrogen Market
Hydrogen Energy
Merchant Hydrogen Market
Hydrogen Energy
70MPa High Pressure Hydrogen Storage Cylinders Market
Hydrogen Energy
Hydrogen Composite Tanks Market
Hydrogen Energy
Hydrogen Powered Engine Market
Hydrogen Energy
Electrolyzer Market
Hydrogen Energy
Hydrogen Recovery Market
Hydrogen Energy
Hydrogen Station Market
Hydrogen Energy
35MPa High Pressure Hydrogen Storage Cylinders Market