
 Green Hydrogen Energy Storage System Market | 2026-2036
Green Hydrogen Energy Storage System Market Size, Share, and Industry Trends Forecast 2026-2036
Green Hydrogen Energy Storage System Market Insights
Proton exchange membrane scaling is reconfiguring system architectures toward modular, distributed storage nodes. Siemens Energy leverages its turbine integration expertise to anchor utility-scale projects across European hydrogen corridors. Nel ASA sustains manufacturing scale in electrolyzer stack production, while Plug Power specializes in end-to-end hydrogen fuel cell systems for material handling and mobility.
A green hydrogen energy storage system converts surplus renewable electricity into hydrogen via electrolysis, compresses or liquefies the gas for containment, and reconverts it through fuel cells or combustion for dispatchable power, typically operating at pressures of 350–700 bar or cryogenic temperatures below minus 253 degrees Celsius. Electrolyzers command the largest capital allocation in new project budgets, with alkaline electrolysis occupying the mature cost-efficient tier and proton exchange membrane units capturing premium deployments requiring rapid response. Hydrogen storage tanks represent a concentrated margin pool as composite pressure vessel manufacturing remains supply-constrained.
The EU Green Deal and Germany's national hydrogen strategy mandate renewable-origin certification for hydrogen consumed in steel and chemical processes, directly conditioning market access and offtake pricing. The EPA in the United States and Japan's METI both enforce greenhouse gas intensity thresholds for clean hydrogen tax credits and import eligibility. Stakeholders must track how certification rules evolve across jurisdictions to avoid stranded asset risk in cross-border hydrogen trade.
Market Dynamics
Proton exchange membrane electrolyzer scaling is compressing project timelines from years to months, forcing alkaline system vendors to defend cost positions while utilities reconfigure procurement specifications around response speed rather than capital efficiency alone.
Growth Catalysts
- EU Green Deal renewable hydrogen quotas:Steel and chemical producers in Germany's Ruhr cluster must now source certified green hydrogen for feedstock, creating binding offtake commitments that de-risk storage infrastructure investments.
- Grid balancing procurement by utilities:Transmission operators across Spain, France, and Germany are contracting hydrogen storage for seasonal arbitrage, treating electrolyzer-integrated systems as dispatchable assets rather than experimental pilots.
- Spain's renewable hydrogen valleys:Concentrated solar and wind resource zones in Aragon and Andalusia are attracting co-located electrolyzer and storage deployments that exploit zero-curtailment electricity pricing.
Market Restraints
- Composite pressure vessel supply concentration:Type IV carbon-fiber tank manufacturing remains captive to a handful of specialized producers, creating 18-24 month delivery backlogs for 700-bar containment systems.
- Platinum and iridium input volatility:PEM electrolyzer stack production depends on iridium catalyst loading that has experienced price swings exceeding 400 percent, destabilizing project economics at the feasibility stage.
- Cryogenic liquefaction energy penalty:Hydrogen liquefaction below minus 253 degrees Celsius consumes 30-40 percent of stored energy content, compressing round-trip efficiency and limiting applications to long-duration seasonal storage.
Strategic Opportunities
- Industrial feedstock substitution in German chemicals:BASF and Evonik are piloting ammonia and methanol production from green hydrogen, creating demand for 100+ MWh-scale storage buffers that smooth electrolyzer output variability.
- Japan's METI clean hydrogen import eligibility rules:Certification schemes that recognize EU-origin hydrogen open arbitrage pathways for European producers to supply Japanese power utilities under long-term offtake structures.
- Modular distributed storage nodes:Containerized electrolyzer-tank-fuel cell units are enabling port operators and data centers to bypass transmission interconnection queues, capturing stranded renewable generation at the source.
Industry Challenges
- Electrolyzer-fuel cell integration engineering:System integrators face thermal management and pressure-balancing complexity when coupling alkaline electrolyzers with PEM fuel cells, requiring bespoke control architectures that extend commissioning timelines.
- Certification timeline fragmentation:Divergent hydrogen purity standards between Germany's DVGW, France's AFNOR, and Spain's UNE create retesting burdens for equipment vendors seeking multi-country project eligibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Green Hydrogen Energy Storage System Market |
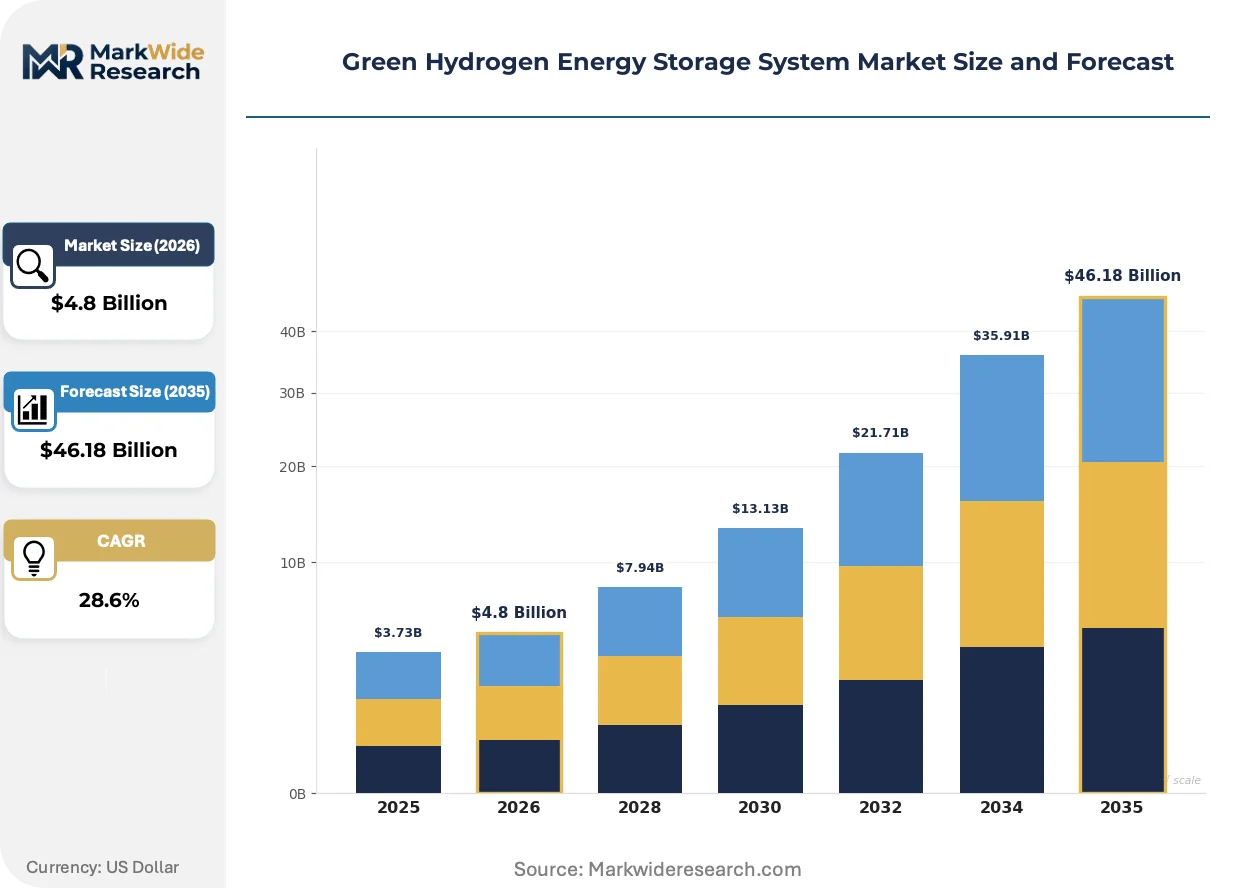
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $46.18 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electrolyzers, Fuel Cells, Hydrogen Storage Tanks, Compression Systems End User: Industrial, Transportation, Utilities, Commercial Technology: Proton Exchange Membrane, Alkaline Electrolysis, Solid Oxide Electrolysis, Photoelectrochemical Application: Power Generation, Transportation Fuels, Grid Stabilization, Backup Power |
| Companies Covered | Air Liquide, Linde, Air Products and Chemicals, Nel ASA, ITM Power, Siemens Energy, ENGIE, Plug Power, Chart Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Green Hydrogen Energy Storage System Market Trends and Innovations
Digital twins and predictive maintenance algorithms are penetrating hydrogen storage operations, compressing unplanned downtime while enabling remote optimization of pressure cycling and boil-off management across distributed asset fleets.
Solid oxide electrolyzer technology is digitizing operational data streams from high-temperature ceramic stacks, enabling steel producers in Sweden and the Netherlands to integrate hydrogen production directly with blast furnace off-gas heat recovery. Equipment vendors are deploying sensor arrays that predict cell degradation 2,000 hours before failure, allowing scheduled replacement rather than emergency shutdowns. This predictive capability is compressing insurance premiums and financing costs for first-of-a-kind installations.
The EPA's greenhouse gas intensity thresholds for clean hydrogen tax credits are forcing project developers to document full lifecycle emissions from electricity sourcing through compression, creating audit trails that favor grid-connected electrolyzers with 24/7 renewable matching over simple annual averaging. Developers are responding by securing dedicated solar and wind power purchase agreements with hourly tracking, reshaping procurement structures in Texas and California project pipelines.
Steelmakers are unbundling hydrogen supply contracts from equipment procurement, preferring tolling arrangements where storage system owners retain operational risk and earn availability-based payments rather than capital recovery through hydrogen offtake. This model is visible in ArcelorMittal's Belgian and German pilot projects, where external operators manage buffer storage while the steelmaker pays only for delivered molecules meeting purity specifications.
Green Hydrogen Energy Storage System Market Segmentation
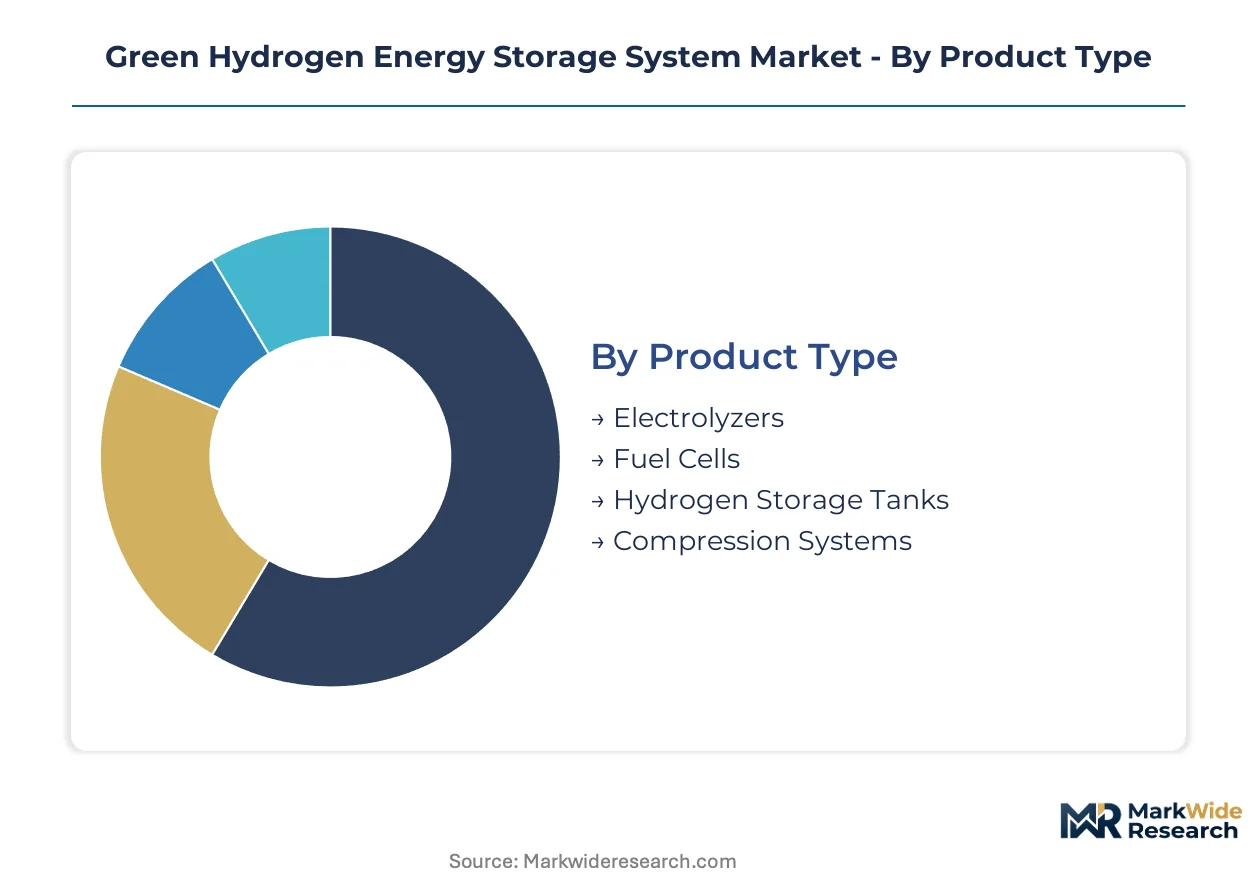
Segmentation in the green hydrogen energy storage system market reveals distinct procurement patterns across electrolyzer technologies, storage hardware, and end-use applications. Each category carries different capital intensity profiles and regulatory compliance burdens that reshape vendor positioning.
Product Type:
Mature compression hardware sits alongside emerging electrolyzer platforms in a cost tier that separates commodity balance-of-plant from proprietary stack technology.
- Electrolyzers:These units convert surplus renewable electricity into hydrogen through water splitting, commanding the largest capital allocation in new project budgets. Demand concentrates in Germany's Ruhr industrial cluster where steel and chemical producers face binding renewable hydrogen quotas under the EU Green Deal.
- Hydrogen Storage Tanks:Type IV carbon-fiber composite vessels contain compressed gas at 350–700 bar pressures or cryogenic liquid below minus 253 degrees Celsius. Spain's renewable hydrogen valleys in Aragon and Andalusia are driving procurement for co-located buffer storage that exploits zero-curtailment electricity pricing.
- Fuel Cells:Reconversion devices transform stored hydrogen back into dispatchable electricity through electrochemical reaction.
- Compression Systems:Mechanical packages pressurize gaseous hydrogen for efficient containment and transport.
Electrolyzers handle the majority of throughput; hydrogen storage tanks are expanding most quickly on share as composite manufacturing scales.
End User:
Application concentration varies sharply by customer type, with industrial offtakers driving volume and utilities reshaping procurement specifications around response speed.
- Industrial:Steelmakers and chemical producers consume hydrogen as feedstock for ammonia, methanol, and direct reduction iron processes. BASF and Evonik in Germany are piloting production lines that require 100+ MWh-scale storage buffers to smooth electrolyzer output variability.
- Utilities:Transmission operators contract hydrogen storage for seasonal arbitrage and grid balancing, treating electrolyzer-integrated systems as dispatchable assets rather than experimental pilots across Spain, France, and Germany.
- Transportation:Fleet operators and port authorities procure hydrogen for heavy-duty fuel cell vehicles and maritime applications.
- Commercial:Data centers and distributed energy users deploy containerized units for backup power and stranded renewable capture.
Industrial offtakers anchor current volume; utilities are climbing the fastest as procurement shifts from pilot to operational contracting.
Technology:
The technology mix spans mature alkaline systems defending cost positions against premium PEM platforms and emerging solid oxide configurations.
- Proton Exchange Membrane:These electrolyzers operate at lower temperatures with rapid response capabilities suited to variable renewable input. PEM scaling is compressing project timelines from years to months, though iridium catalyst price volatility exceeding 400 percent destabilizes project economics.
- Alkaline Electrolysis:Mature water-alkali systems use liquid electrolyte and nickel-based electrodes for cost-efficient bulk hydrogen production. Vendors are defending positions against PEM incursions as utilities reconfigure specifications around capital efficiency.
- Solid Oxide Electrolysis:High-temperature ceramic stacks integrate with industrial heat recovery for enhanced efficiency.
- Photoelectrochemical:Direct solar-to-hydrogen conversion technologies remain at demonstration scale.
Alkaline electrolysis retains the installed base; proton exchange membrane is gaining share fastest on new project awards.
Application:
Use case segmentation tracks how hydrogen value propositions differ across power sector, mobility, and industrial feedstock substitution.
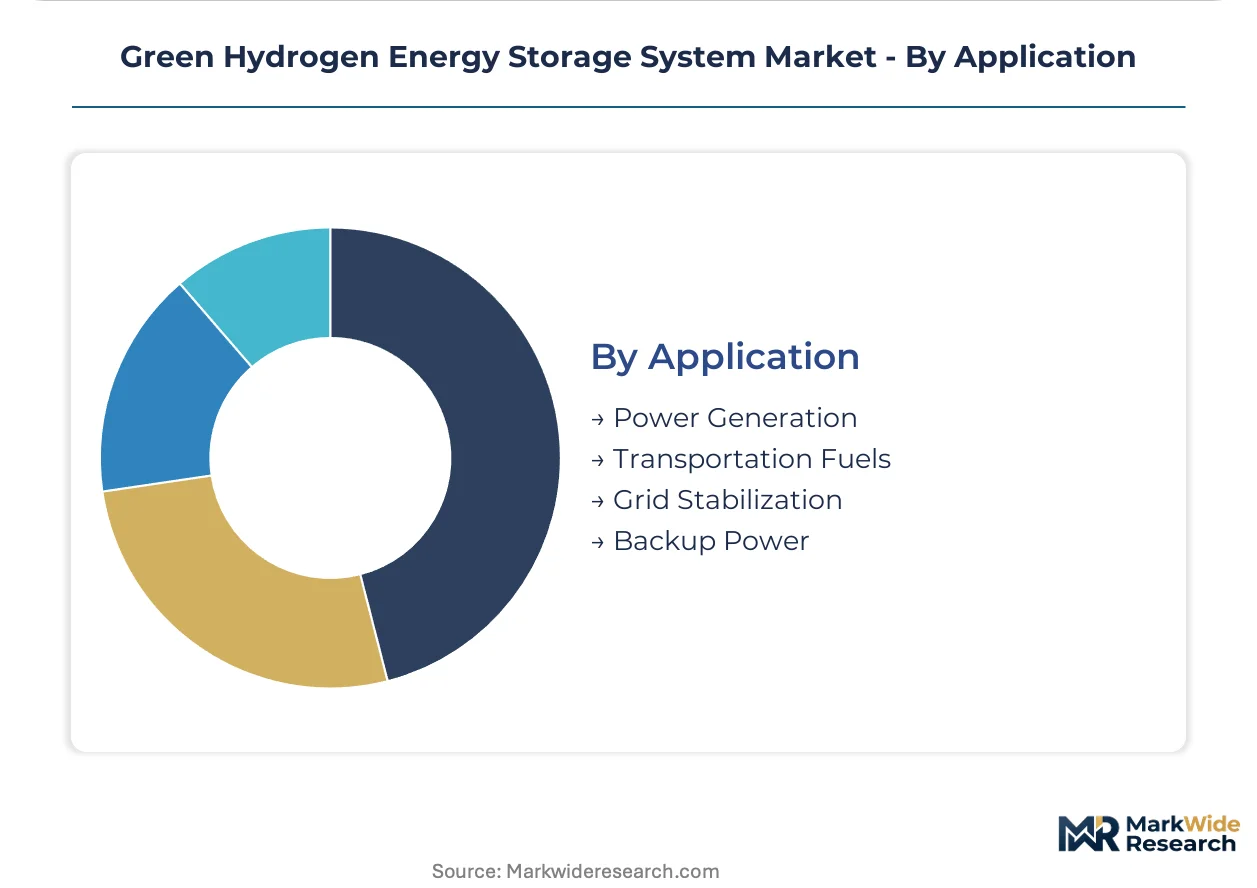
- Power Generation:Reconverted hydrogen feeds gas turbines and fuel cells for dispatchable renewable electricity. ArcelorMittal's Belgian and German pilot projects demonstrate tolling arrangements where external operators manage buffer storage while steelmakers pay for delivered molecules.
- Grid Stabilization:Long-duration storage absorbs seasonal renewable surpluses and provides frequency regulation. Japan's METI clean hydrogen import eligibility rules open arbitrage pathways for European producers to supply Japanese power utilities.
- Transportation Fuels:Hydrogen serves as fuel for heavy-duty road freight, rail, and maritime propulsion.
- Backup Power:Fuel cell systems provide resilience for critical infrastructure and off-grid applications.
Power generation commands current investment; grid stabilization shows the steepest expansion trajectory as seasonal storage economics improve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial offtakers in Germany's Ruhr cluster and utility procurement teams in Spain's renewable hydrogen valleys represent the dominant buyer archetypes shaping regional deployment patterns. Each geography conditions market access through distinct certification regimes and infrastructure investment cycles.
Germany
Steel and chemical producers in the Ruhr industrial cluster face binding renewable hydrogen quotas under the EU Green Deal and Germany's national hydrogen strategy. The Federal Network Agency (Bundesnetzagentur) regulates grid connection priorities for electrolyzer-integrated storage systems. BASF and Evonik in Ludwigshafen are piloting 100+ MWh-scale storage buffers to smooth electrolyzer output variability for ammonia production.
Spain
Concentrated solar and wind resource zones in Aragon and Andalusia attract co-located electrolyzer and storage deployments exploiting zero-curtailment electricity pricing. The Spanish national hydrogen strategy mandates renewable-origin certification through UNE standards. The Andalusian Green Hydrogen Valley project anchors utility-scale procurement for seasonal arbitrage contracts.
United States
Project developers in Texas and California reshape procurement structures around hourly renewable matching to satisfy EPA greenhouse gas intensity thresholds for clean hydrogen tax credits. The Inflation Reduction Act production tax credits condition eligibility on documented lifecycle emissions. ArcelorMittal's Texas Gulf Coast pilot demonstrates tolling arrangements where external operators manage buffer storage.
Japan
METI clean hydrogen import eligibility rules open arbitrage pathways for European producers to supply Japanese power utilities under long-term offtake structures. The Ministry of Economy, Trade and Industry enforces greenhouse gas intensity thresholds for import eligibility. Kobe and Yokohama port operators deploy containerized electrolyzer-tank-fuel cell units to bypass transmission interconnection queues.
France
Hydrogen valleys in Auvergne-Rhône-Alpes and Hauts-de-France concentrate demand from steel decarbonization and chemical feedstock substitution. AFNOR certification standards create retesting burdens for equipment vendors seeking multi-country project eligibility. ENGIE and industrial partners in Fos-sur-Mer pilot port-based storage systems for maritime fuel applications.
Green Hydrogen Energy Storage System Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a market structure that concentrates capital allocation in electrolyzer manufacturing while fragmenting across storage hardware. Integrated industrial gas conglomerates leverage existing hydrogen infrastructure and customer relationships against pure-play electrolyzer vendors scaling manufacturing capacity. Three archetypes dominate: turbine-integrated system architects, electrolyzer stack manufacturers, and end-to-end fuel cell specialists. Competitive moves center on strategic partnerships for project development and backward integration into catalyst and membrane supply chains.
Among European integrated industrial gas providers, Air Liquide and Linde occupy positions that exemplify channel control through existing hydrogen distribution networks and carbon capture expertise. Nel ASA represents the manufacturing-scale archetype for electrolyzer stack production. These three anchors illustrate how geographic origin and corporate structure map to strategic positioning: Paris-based Air Liquide S.A. and Dublin-incorporated Linde plc leverage global reach, while Norwegian Nel ASA concentrates on specialized equipment fabrication.
| Leading Market Players |
|---|
| Air Liquide |
| Linde |
| Air Products and Chemicals |
| Nel ASA |
| ITM Power |
| Siemens Energy |
| ENGIE |
| Plug Power |
| Chart Industries |
| Others |
Pricing and Supply Chain Analysis
Electrolyzer manufacturing overcapacity in China is compressing stack prices while tightening margins for European vendors, forcing procurement teams to renegotiate contract structures and suppliers to extend payment terms to preserve offtake relationships.
Pricing Analysis
Cost-plus contracts with iridium and nickel indexation dominate electrolyzer procurement, with PEM systems commanding premiums over alkaline units due to rapid-response specifications. Price differentiation hinges on certification tier under EU Green Deal origin rules and volume scale, with industrial offtakers in Germany's Ruhr cluster showing lowest sensitivity. Pricing pressure intensifies as Chinese manufacturers flood European markets with subsidized alkaline stacks, eroding margins for incumbent Western vendors while utilities exploit buyer leverage.
Supply Chain Analysis
Supplier-financing facilities now extend payment terms to 24 months for composite pressure vessel procurement, easing capital burdens for project developers. Manufacturing concentrates in Germany, China, and Japan for electrolyzer stacks; Type IV carbon-fiber tanks draw from Japanese and South Korean fiber producers. Supply chain risk centers on single-source iridium catalyst supply from South African refiners. Distribution runs through EPC-led turnkey contracting for utility-scale deployments and direct OEM sales for modular units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Green hydrogen energy storage represents a high-growth disruption as PEM electrolyzer scaling collapses project delivery timelines and EU renewable hydrogen quotas mandate industrial feedstock substitution.
For Market Incumbents: Harden manufacturing positions by securing captive iridium supply through offtake agreements with South African refiners, and accelerate backward integration into membrane production to neutralize Chinese cost advantages. Defend against modular containerized entrants by embedding long-term service contracts into electrolyzer sales.
For New Entrants and Emerging Players: Japan's port hydrogen infrastructure offers underpenetrated white space where METI import eligibility rules favor certified European supply. Target data center backup power segments with skid-mounted electrolyzer-tank-fuel cell units, bypassing utility interconnection queues through behind-the-meter deployment.
For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across containerized distributed storage nodes as manufacturing scales compress unit costs. Five-to-ten-year viability favors equipment-as-a-service operators over pure hardware vendors. Watch for iridium price stabilization as the signal that project economics have reached investable thresholds.
| Strategic Initiative | Industry Significance |
|---|---|
| Electrolyzer Manufacturing Scale-Up | Nel ASA and Siemens Energy expansion in Norway and Germany locks in supply for EU hydrogen corridor projects. |
| Backward Integration into Catalyst Supply | Captive iridium sourcing neutralizes price volatility exceeding 400 percent that destabilizes PEM project economics. |
| Green Certification Program | EU Green Deal origin certification under TÜV or DVGW standards conditions market access for industrial offtakers. |
| Long-term Supply Agreement | ArcelorMittal tolling arrangements transfer operational risk to storage owners while securing steel decarbonization feedstock. |
| Joint Venture for Hydrogen Valley Development | Spain's Andalusian and Aragon clusters aggregate solar and wind resources with co-located electrolyzer and buffer storage. |
Research Methodology
Initial hypotheses were tested against primary input from utility planning officers, electrolyzer procurement leads at chemical producers, EPC contractors, and grid operators, and refined through secondary validation against EIA project databases, IEA hydrogen reports, FERC interconnection filings, and EU hydrogen corridor development trackers. Bottom-up electrolyzer shipment data triangulated against top-down national hydrogen strategy capacity targets.
Demand-supply-balance framing anchored the forecast framework across the analysis window, modeling electrolyzer technology, storage hardware type, end-use application, and regional regulatory cluster as segmentation dimensions. CAGRs derived from electrolyzer manufacturing capacity expansion curves and industrial offtake contract visibility. Key inputs included iridium price trajectories, composite vessel manufacturing lead times, and EU Green Deal certification timeline assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-subsidized manufacturers or breakthrough solid oxide electrolyzer commercialization would shift outcomes. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydrogen Energy
Hydrogen ICE Ignition System Platforms Market
Hydrogen Energy
Hydrogen Station Market
Hydrogen Energy
Hydrogen Purification Technologies Market
Hydrogen Energy
Hydrogen Refueling Protocol and Dispenser Performance Test Systems Market
Hydrogen Energy
USA Hydrogen Electrolyzer Market
Hydrogen Energy
Hydrogen Storage Technology Market
Hydrogen Energy
Green Hydrogen Storage Technology Market
Hydrogen Energy
Alkaline Water Electrolysis Market
Hydrogen Energy
Black Hydrogen Market
Hydrogen Energy
Electrolyzer Market
Hydrogen Energy
Asia Pacific Liquid Hydrogen Market
Hydrogen Energy
Global Hydrogen Electrolyzers Market
Hydrogen Energy
High-Pressure Hydrogen Tanks Market
Hydrogen Energy
35MPa High Pressure Hydrogen Storage Cylinders Market
Hydrogen Energy
US Hydrogen Fueling Station Market
Hydrogen Energy
Hydrogen Market