
 Hydrogen Station Market | 2026-2036
Hydrogen Station Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogen Station Market Insights
The hydrogen station landscape is recalibrating around a widening gap between premium electrolysis-based hubs and commodity reforming stations serving transitional demand. Air Liquide leverages its cryogenic expertise to dominate high-purity hydrogen logistics across European port networks. Linde sustains cost leadership in steam methane reforming installations through captive natural gas supply agreements. Nel Hydrogen anchors its position in Nordic markets with modular PEM electrolyzer packages designed for rapid deployment.
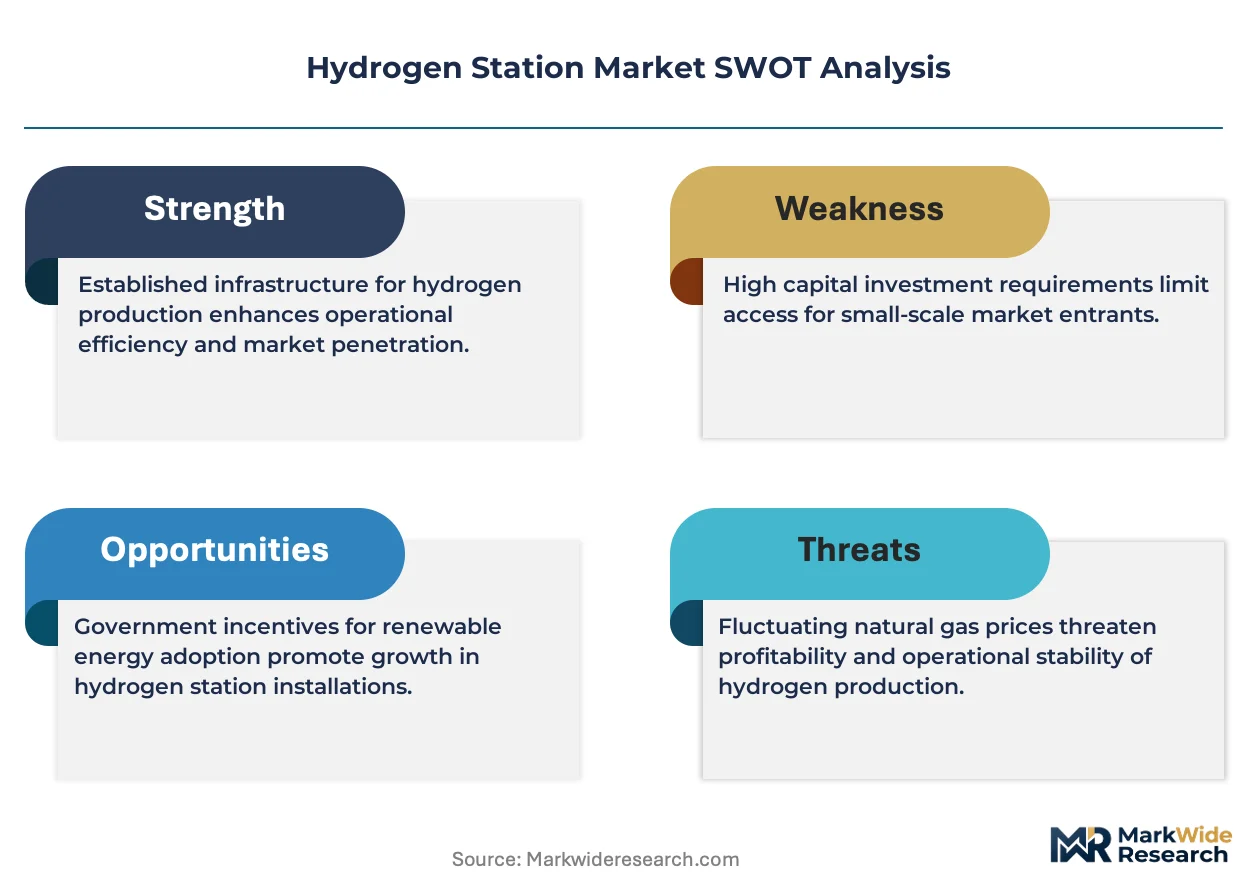
A hydrogen station constitutes an integrated facility that produces, compresses, stores, and dispenses hydrogen fuel at pressures of 350 bar or 700 bar for vehicle refueling, with electrolysis systems splitting water via proton exchange membranes to generate zero-emission hydrogen on location. Compression stations and storage systems currently absorb the majority of capital expenditure as operators prioritize buffer capacity over dispenser throughput. Electrolysis technology is capturing margin pools from government-backed green hydrogen certification schemes while steam methane reforming retains volume leadership in markets without carbon border adjustments.
The EU Green Deal and F-Gas Regulation shape equipment standards across European deployments, while Japan's METI hydrogen roadmap mandates specific safety protocols for urban station siting. The US IRA production tax credits are redirecting developer capital toward electrolysis projects with domestic content requirements. Stakeholders must track how carbon intensity certification rules redefine which station technologies qualify for public procurement contracts.
Market Dynamics
Electrolysis technology is pulling capital away from steam methane reforming as carbon intensity certification rules harden across public procurement corridors. The EU Green Deal and US IRA production tax credits are bifurcating station economics between green hydrogen hubs and transitional gray hydrogen stopgaps.
Growth Catalysts
- EU Green Deal carbon border adjustments:Logistics operators in Rotterdam and Hamburg are pre-committing to electrolysis-based refueling to secure fleet certification under tightening emission thresholds.
- Heavy-duty trucking corridor development:California's port-to-highway hydrogen networks are anchoring infrastructure deployment along I-710 and I-5 freight routes.
- PEM electrolyzer modularity:Nordic developers are deploying containerized systems that compress deployment timelines for remote industrial clusters.
Market Restraints
- Platinum group metal supply concentration:PEM electrolyzer membrane production depends on South African and Russian palladium supply chains vulnerable to export disruptions.
- Grid interconnection queues:Electrolysis projects in Germany face 18-24 month utility connection delays that extend project payback periods.
- Steam methane reforming lock-in:Existing natural gas infrastructure in Texas and Louisiana creates path dependency that slows green hydrogen conversion.
Strategic Opportunities
- Japan's METI urban siting protocols:Safety standard harmonization is opening residential-adjacent station locations previously excluded by buffer zone requirements.
- Maritime bunkering corridors:Port authorities in Singapore and Rotterdam are tendering hydrogen liquefaction and dispensing infrastructure for short-sea shipping.
- Off-grid renewable coupling:Iberian solar-wind hybrid sites are pairing electrolysis with dedicated renewable offtake to bypass grid congestion.
Industry Challenges
- High-pressure vessel certification timelines:700 bar storage systems require ASME and TPED dual certification cycles that extend commissioning by 8-12 months.
- Cryogenic handling skill scarcity:Liquid hydrogen logistics demand technicians trained in sub-20 Kelvin operations, a qualification pool concentrated in aerospace and LNG sectors.
- Legacy CNG station retrofit complexity:Existing compressed natural gas infrastructure requires complete compressor and dispenser replacement rather than component upgrade.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogen Station Market |
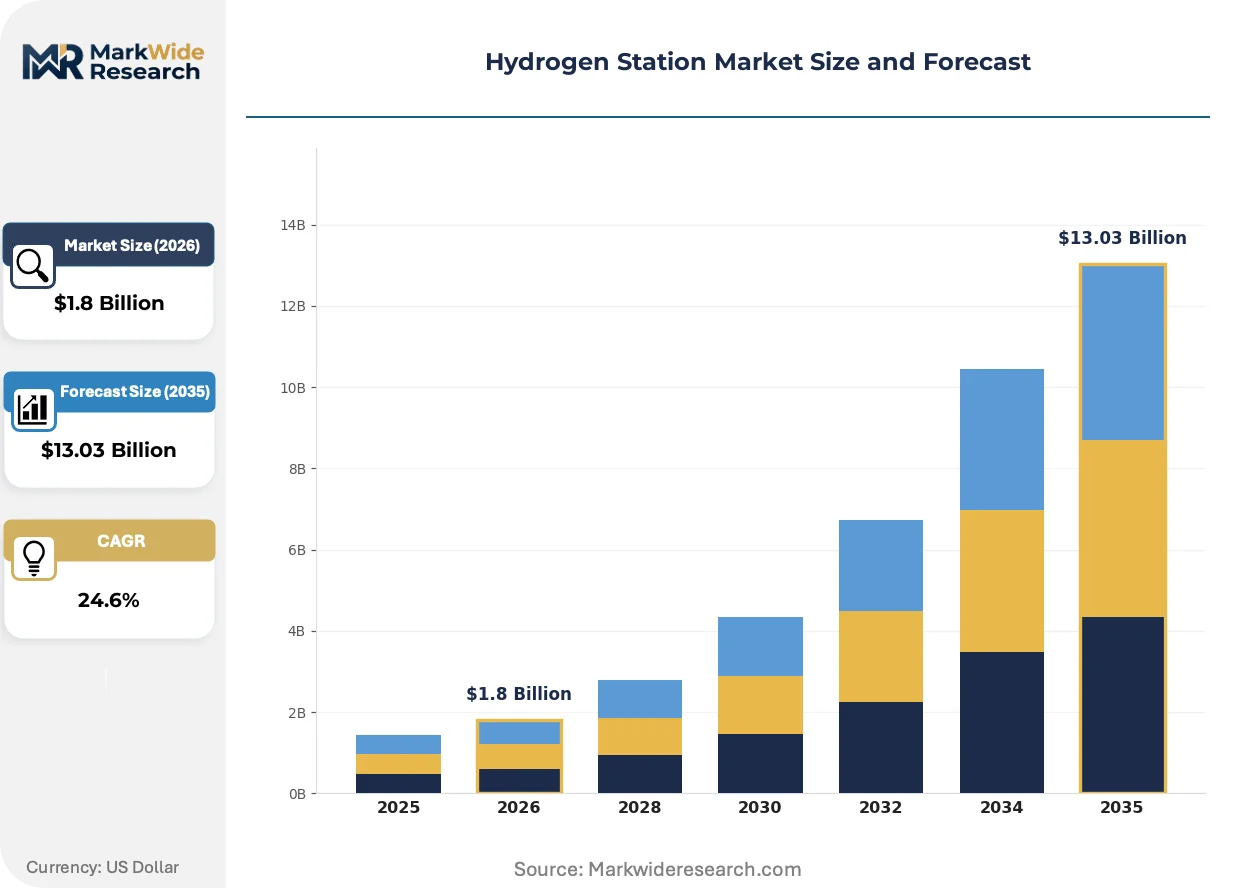
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $13.03 Billion |
| CAGR (2026 – 2036) | 24.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Compression Stations, Storage Systems, Dispensers, Fuel Cell Systems Technology: Electrolysis, Steam Methane Reforming, Biomass Gasification, Pyrolysis End User: Industrial Users, Transportation Fleet Operators, Retail Stations, Government Projects Installation: Onsite, Offsite, Mobile, Permanent |
| Companies Covered | Air Liquide, Linde, Air Products and Chemicals, Nel Hydrogen, ITM Power, Plug Power, Cummins, China Petrochemical Corporation, FuelCell Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogen Station Market Trends and Innovations
Station architecture is fragmenting between centralized production hubs and distributed electrolysis nodes. Technology trajectories are diverging around purity grades, pressure ratings, and renewable coupling strategies.
Modular PEM electrolyzer systems are decentralizing hydrogen production by enabling on-site generation at fleet depots and industrial parks. Municipal bus operators in Denmark and the Netherlands are adopting 1-5 MW containerized units that eliminate liquid hydrogen delivery logistics. This distributed model is compressing the addressable radius of centralized reforming plants and shifting margin capture toward electricity procurement and O&M services.
The EU F-Gas Regulation is phasing down hydrofluorocarbon use in station cooling systems, forcing equipment suppliers to adopt CO2 or ammonia-based refrigeration cycles. Industrial gas specialists are redesigning heat exchanger architectures to maintain dispensing rates under tighter thermal constraints. Cold-climate installations in Scandinavia are most affected, with operators pre-ordering compliant equipment two years ahead of mandate deadlines.
Fleet operators are consolidating procurement around long-term hydrogen supply agreements that bundle station access, fuel pricing, and maintenance into single contracts. Third-party logistics providers in California are displacing spot-market purchasing that dominated early pilot programs. This contract concentration is most visible among drayage operators at the Ports of Long Beach and Los Angeles, where fuel cost predictability outweighs spot-price flexibility.
Hydrogen Station Market Segmentation
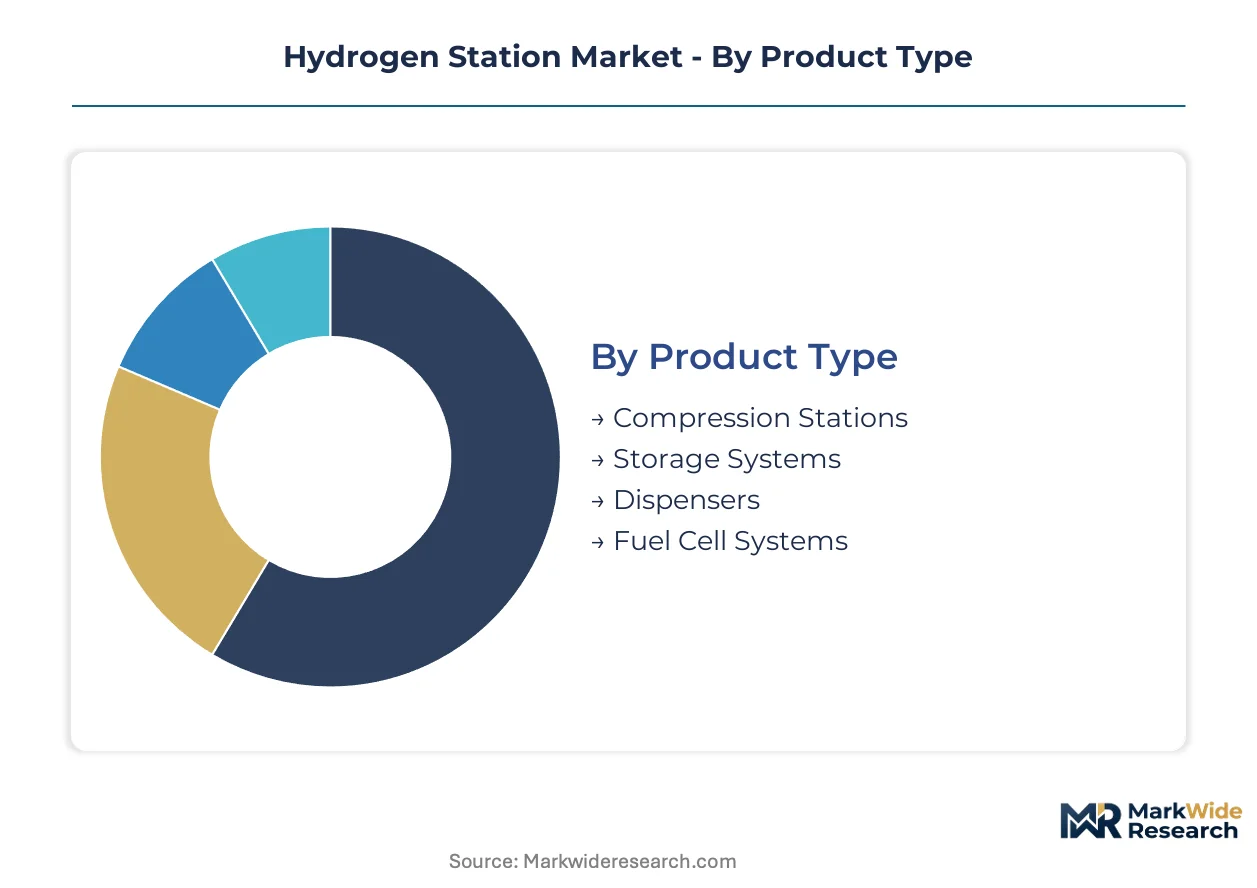
Hydrogen station segmentation reveals how capital allocation splits between production technology choices and infrastructure deployment models. Equipment specifications and siting strategies diverge sharply across fleet depots, retail corridors, and industrial clusters.
Product Type:
Upgrade cycles for compression and storage equipment are accelerating as 700 bar dispensing becomes standard for heavy-duty trucking applications.
- Compression Stations:Multi-stage compressors boost hydrogen to 350 bar or 700 bar for vehicle refueling, with diaphragm and ionic liquid technologies displacing reciprocating designs in California freight corridors. Port operators in Rotterdam and Long Beach are pre-ordering 700 bar systems to accommodate next-generation fuel cell trucks.
- Storage Systems:High-pressure vessels and cryogenic tanks buffer supply against demand spikes, absorbing the largest share of capital expenditure in greenfield installations. German utility-scale projects are specifying ASME-certified Type IV composite cylinders to compress commissioning timelines.
- Dispensers:Nozzle and metering assemblies interface directly with vehicles, requiring SAE J2601 protocol compliance for fueling rate optimization.
- Fuel Cell Systems:On-site power generation units convert stored hydrogen to electricity for station operations, gaining traction in off-grid Iberian deployments.
Compression stations sit at the top of the volume ranking, with storage systems climbing the fastest as operators prioritize buffer capacity over dispenser throughput.
Technology:
Cost tiers separate premium electrolysis installations from commodity reforming alternatives, with carbon intensity certification rules widening the economic gap.
- Electrolysis:Proton exchange membrane and alkaline systems split water using electricity, generating zero-emission hydrogen when paired with renewable power. Nordic developers are deploying containerized PEM packages at Danish bus depots to bypass liquid hydrogen logistics entirely.
- Steam Methane Reforming:Natural gas feedstock conversion with carbon capture retrofits dominates transitional markets lacking border adjustments. Linde maintains cost leadership through captive supply agreements in Texas and Louisiana.
- Biomass Gasification:Organic feedstock conversion produces hydrogen with lower lifecycle emissions than fossil alternatives.
- Pyrolysis:Thermal decomposition of hydrocarbons yields hydrogen and solid carbon, attracting pilot investment from waste-to-energy operators.
Steam methane reforming holds the largest installed base, though electrolysis is expanding most quickly as EU Green Deal incentives redirect developer capital.
End User:
Customer type determines contract structure, with fleet operators consolidating procurement around bundled supply agreements while retail stations remain fragmented.
- Industrial Users:Steel, ammonia, and refining operations consume hydrogen at scale, often co-locating production with offtake. Rotterdam port authorities are tendering dedicated infrastructure for chemical cluster decarbonization.
- Transportation Fleet Operators:Heavy-duty trucking and municipal bus operators anchor corridor development along California's I-5 and Germany's Rhine-Alpine freight routes. Drayage operators at Los Angeles and Long Beach ports are displacing spot-market purchasing with long-term hydrogen supply contracts.
- Retail Stations:Public access facilities serve light-duty vehicles and early adopters, facing utilization challenges in markets without fleet density.
- Government Projects:Demonstration and research installations validate safety protocols and operational standards, with Japan's METI urban siting protocols enabling residential-adjacent locations.
Transportation fleet operators command the steepest expansion trajectory, while industrial users represent the largest committed volume.
Installation:
Deployment models fragment between permanent infrastructure and mobile alternatives, with supply concentration favoring established construction corridors.
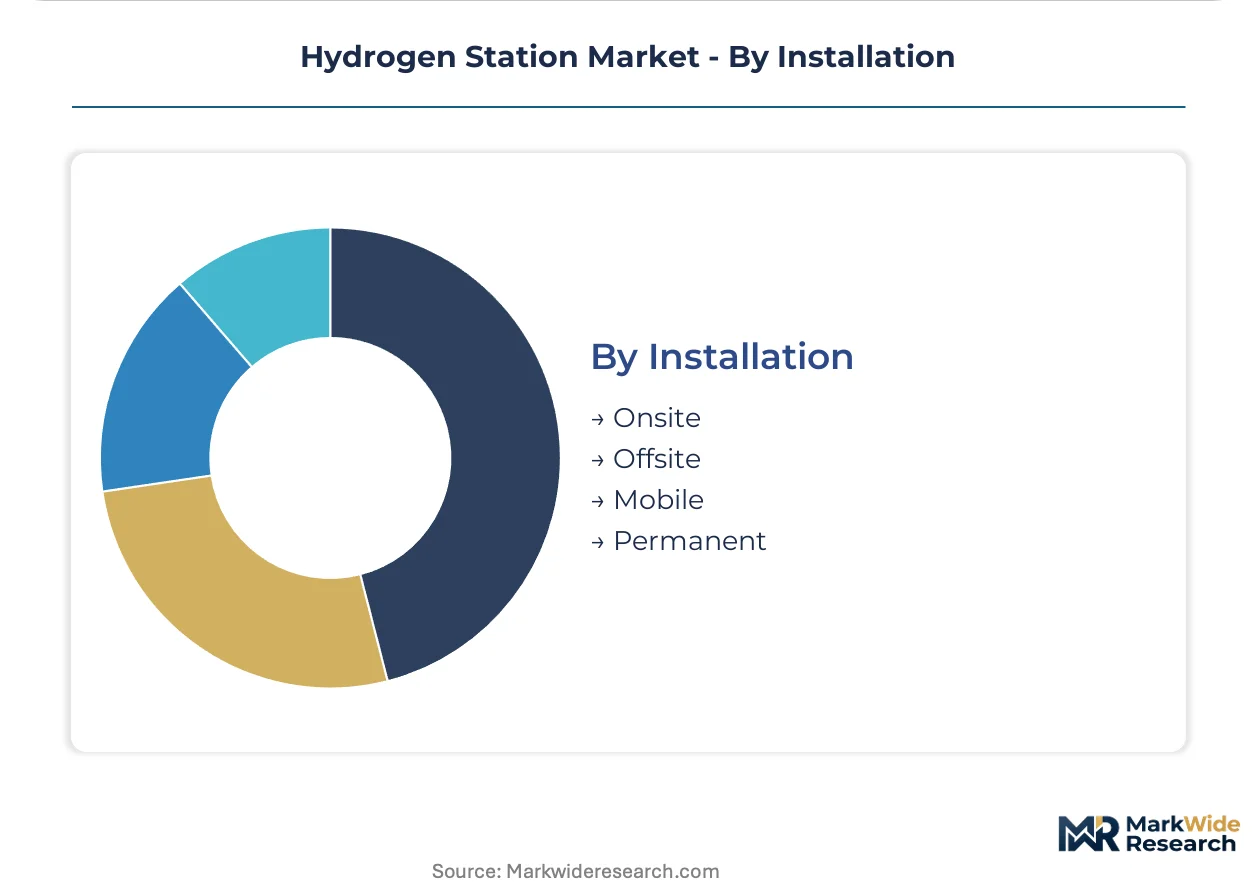
- Onsite:Production and dispensing co-located at fleet depots or industrial facilities eliminate distribution logistics. PEM electrolyzer modularity is compressing deployment timelines for remote clusters.
- Offsite:Centralized production with tube trailer or pipeline delivery serves dispersed demand points, dominating early market development.
- Mobile:Trailer-mounted refueling units provide temporary coverage for construction sites and event logistics.
- Permanent:Fixed infrastructure with 20-year asset lifecycles requires grid interconnection and municipal permitting.
Permanent installations anchor the volume ranking, with onsite configurations gaining share fastest as electrolyzer costs decline.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Cryogenic technicians and high-pressure vessel specialists concentrate in Germany, Japan, and California, anchoring the technical workforce for advanced hydrogen infrastructure deployment. Their expertise shapes where electrolysis hubs and 700 bar dispensing networks materialize first.
United States
Heavy-duty trucking fleets along California's I-5 and I-710 corridors are pre-committing to hydrogen refueling as the state's clean fuel standards tighten emission thresholds for logistics operators. The IRA production tax credits redirect developer capital toward electrolysis projects with domestic content requirements. Drayage operators at the Ports of Long Beach and Los Angeles are consolidating procurement around long-term hydrogen supply agreements.
Germany
Rhine-Alpine freight operators face 18-24 month grid interconnection queues that extend electrolysis project payback periods despite strong fleet demand. The EU Green Deal carbon border adjustments are bifurcating station economics between green hydrogen hubs and transitional gray hydrogen stopgaps. Hamburg port authorities are tendering dedicated infrastructure for chemical cluster decarbonization.
Japan
METI hydrogen roadmap mandates specific safety protocols that are opening residential-adjacent station locations previously excluded by buffer zone requirements. Kanto industrial belt port-to-highway networks anchor early infrastructure deployment for short-sea shipping corridors. Municipal bus operators in Tokyo and Yokohama are adopting containerized electrolyzer units.
Netherlands
Rotterdam port authorities are tendering hydrogen liquefaction and dispensing infrastructure as logistics operators pre-commit to electrolysis-based refueling for fleet certification. The EU F-Gas Regulation phases down hydrofluorocarbon use in station cooling systems, forcing equipment redesigns. North Sea wind coupling is enabling off-grid renewable electrolysis to bypass grid congestion.
China
State-owned energy conglomerates leverage captive natural gas supply agreements to sustain cost leadership in steam methane reforming installations. Yangtze River Delta industrial clusters are deploying centralized production with tube trailer delivery to dispersed demand points. Dual carbon goals are redirecting pilot investment toward electrolysis in coastal hydrogen corridors.
Hydrogen Station Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the hydrogen station value chain, with industrial gas conglomerates wielding cryogenic logistics scale against modular equipment specialists. The vendor base splits between consolidated electrolyzer packagers and fragmented component suppliers. Three archetypes dominate: integrated industrial gas providers with captive hydrogen networks, modular PEM system designers with rapid-deployment capabilities, and state-backed energy majors with reforming infrastructure lock-in. Competitive moves center on strategic partnerships for renewable power offtake and geographic expansion along freight corridor clusters.
Within the integrated industrial gas tier, Air Liquide and Linde occupy positions shaped by decades of cryogenic handling expertise and captive supply infrastructure. Nel Hydrogen exemplifies the modular specialist archetype with containerized deployment capabilities. These three anchors illustrate how technical heritage and asset configuration determine margin capture across green hydrogen certification schemes and transitional gray hydrogen markets.
| Leading Market Players |
|---|
| Air Liquide |
| Linde |
| Air Products and Chemicals |
| Nel Hydrogen |
| ITM Power |
| Plug Power |
| Cummins |
| China Petrochemical Corporation |
| FuelCell Energy |
| Others |
Pricing and Supply Chain Analysis
Captive electrolyzer manufacturing in Germany and Japan anchors both supply security and pricing power for integrated hydrogen station developers, compressing margin capture for operators dependent on imported PEM stacks or reforming equipment. This vertical integration choice separates premium green hydrogen hubs from commodity gray hydrogen stopgaps as carbon intensity certification rules harden procurement standards.
Pricing Analysis
Bundled long-term supply agreements dominate California freight corridors while unbundled spot purchasing persists in fragmented retail markets. Price differentiation rests on green hydrogen certification tier and volume commitment scale, with fleet operators securing fixed-rate contracts and retail stations facing variable hydrogen delivery costs. Cost compression in electrolyzer manufacturing is intensifying because Chinese and Korean equipment suppliers are scaling alkaline system production. Municipal bus operators exhibit highest price sensitivity due to constrained public procurement budgets, while industrial chemical clusters show lowest sensitivity given pass-through mechanisms in ammonia and refining economics.
Supply Chain Analysis
Dual-sourcing requirements for platinum group metals are forcing PEM electrolyzer manufacturers to qualify both South African and Russian palladium suppliers despite export disruption risks. Component production concentrates in Germany, Japan, and South Korea for high-pressure vessels and cryogenic handling systems. Raw material dependencies include iridium-coated titanium electrodes, carbon fiber composite cylinders, and specialized refrigeration gases. Single-source vulnerability in iridium mining creates supply chain risk given concentration in South African and Zimbabwean extraction. Distribution runs through industrial gas specialists with captive hydrogen networks rather than independent logistics providers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where developers can exploit the gap between US IRA domestic content requirements and EU Green Deal carbon border adjustments to optimize equipment sourcing and certification pathways.
For Market Incumbents: Anchor cryogenic logistics scale against modular specialist encroachment by expanding 700 bar dispensing networks along California I-5 and Germany Rhine-Alpine corridors. Deepen backward integration into PEM electrolyzer membrane production to reduce platinum group metal exposure. Prioritize certification investment under EU Green Deal frameworks to lock in public procurement eligibility as carbon intensity thresholds tighten. For New Entrants and Emerging Players: Digital-channel fleet management platforms offer the lowest-friction entry path for hydrogen procurement aggregation services targeting fragmented drayage operators at secondary ports. White-space targets include Iberian solar-wind hybrid sites for off-grid electrolysis and Japan residential-adjacent stations enabled by METI safety protocol harmonization. Pursue containerized PEM system deployment for remote industrial clusters as the most penetrable application segment. For Investors and Strategic Acquirers: Roll-up economics work for regional hydrogen station operators with captive fleet contracts because contract concentration creates predictable offtake volumes that support debt financing. Long-term viability hinges on electrolyzer cost curves and renewable power purchase agreement availability. Watch EU carbon border adjustment implementation timing as the critical inflection signal for green hydrogen hub investment returns.| Strategic Initiative | Industry Significance |
|---|---|
| Electrolyzer Manufacturing Scale-Up | Alkaline and PEM capacity expansion in Germany and China compresses equipment costs for greenfield developers. |
| Backward Integration into PGM Supply | Captive palladium and iridium sourcing agreements reduce membrane production disruption exposure for PEM specialists. |
| Long-Term Hydrogen Supply Agreements | Fleet operators at California ports are consolidating procurement around bundled fuel-station-maintenance contracts. |
| Green Certification Program Enrollment | EU Green Deal carbon intensity tiers determine public procurement eligibility for Rotterdam and Hamburg infrastructure tenders. |
| Joint Venture for Maritime Bunkering | Singapore and Rotterdam port authorities are partnering on liquefaction and dispensing infrastructure for short-sea shipping. |
Research Methodology
Coverage spans the United States, Germany, Japan, the Netherlands, and China, with primary inputs from each market cluster combining interviews with hydrogen station developers, fleet procurement managers, industrial gas supply specialists, and electrolyzer manufacturing engineers alongside secondary validation. Primary research drew from utility interconnection officers, port authority infrastructure planners, and PEM stack R&D directors. Secondary sources included EIA hydrogen production databases, EU F-Gas Regulation implementation filings, METI roadmap documentation, and SEC disclosures from listed industrial gas conglomerates. Bottom-up project pipeline analysis triangulated against top-down market sizing from equipment shipment records.
Granularity-level modeling deployed capacity-by-technology splits for electrolysis versus reforming installations, pressure-rating segmentation for 350 bar versus 700 bar dispensing systems, and end-use disaggregation across fleet depots, industrial clusters, and retail corridors. CAGRs were derived from installed base expansion trajectories and fleet pre-commitment timelines across the projection horizon. Forecast inputs incorporated grid interconnection queue durations, platinum group metal price volatility assumptions, and renewable power purchase agreement availability curves.
Policy implementation delays, platinum group metal supply disruptions, and electrolyzer manufacturing cost trajectory deviations are the dominant revision risks for hydrogen station deployment forecasts. Deviation in EU carbon border adjustment enforcement timing would shift the outlook materially for green hydrogen hub economics versus transitional gray hydrogen alternatives.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydrogen Energy
Hydrogen Energy Storage Market
Hydrogen Energy
Hydrogen for Mobility Market
Hydrogen Energy
Hydrogen Purification Technologies Market
Hydrogen Energy
Hydrogen Storage Technology Market
Hydrogen Energy
Hydrogen Recovery Market
Hydrogen Energy
Europe Hydrogen Generation Market
Hydrogen Energy
Global Hydrogen Electrolyzers Market
Hydrogen Energy
US Hydrogen Fueling Station Market
Hydrogen Energy
Hydrogen Powered Engine Market
Hydrogen Energy
Green Hydrogen Dispensing Equipment Market
Hydrogen Energy
70MPa High Pressure Hydrogen Storage Cylinders Market
Hydrogen Energy
Gray Hydrogen Market
Hydrogen Energy
On-Site Hydrogen Generator Market
Hydrogen Energy
Green Hydrogen Energy Storage System Market
Hydrogen Energy
Hydrogen Ejector Market
Hydrogen Energy
35MPa High Pressure Hydrogen Storage Cylinders Market