
 United Kingdom Geothermal Energy Market | 2026-2036
United Kingdom Geothermal Energy Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Geothermal Energy Market Analytics
The UK's net-zero commitment and the Green Heat Network Fund is decoupling geothermal deployment from purely subsidy-dependent models. Geothermal Engineering Ltd leverages its expertise in deep drilling projects in Cornwall to anchor early-stage commercial viability. Eden Geothermal Ltd sustains development of the United Downs project, demonstrating enhanced geothermal viability in granite formations. Engie SA competes through its district heating operational scale, positioning geothermal within integrated low-carbon heat portfolios.
United Kingdom geothermal energy harnesses subsurface heat through hydrothermal reservoirs, hot dry rock, or enhanced geothermal systems, typically extracting thermal energy at temperatures ranging from 30°C for direct-use applications to over 150°C for electricity generation, with ground-source heat pumps dominating residential and light-commercial deployment. Direct heating solutions occupy the largest installed base due to mature ground-source heat pump technology and building retrofit mandates, while electricity generation from deep geothermal differentiates through baseload renewable output and higher capital intensity. Enhanced geothermal systems represent the fastest-growing technology segment as hydraulic stimulation advances unlock productivity in otherwise impermeable crystalline basement rocks.
The Department for Energy Security and Net Zero shapes project economics through the Green Heat Network Fund and Contract for Difference mechanisms, while Ofgem regulates network access tariffs and connection standards for geothermal heat feeding district systems. The Environment Agency governs abstraction licensing and reinjection protocols, directly determining drilling permit timelines and operational compliance burdens. Stakeholders must monitor the evolution of subsurface rights frameworks and the allocation of future carbon price support between geothermal and competing low-carbon heat technologies.
Market Dynamics
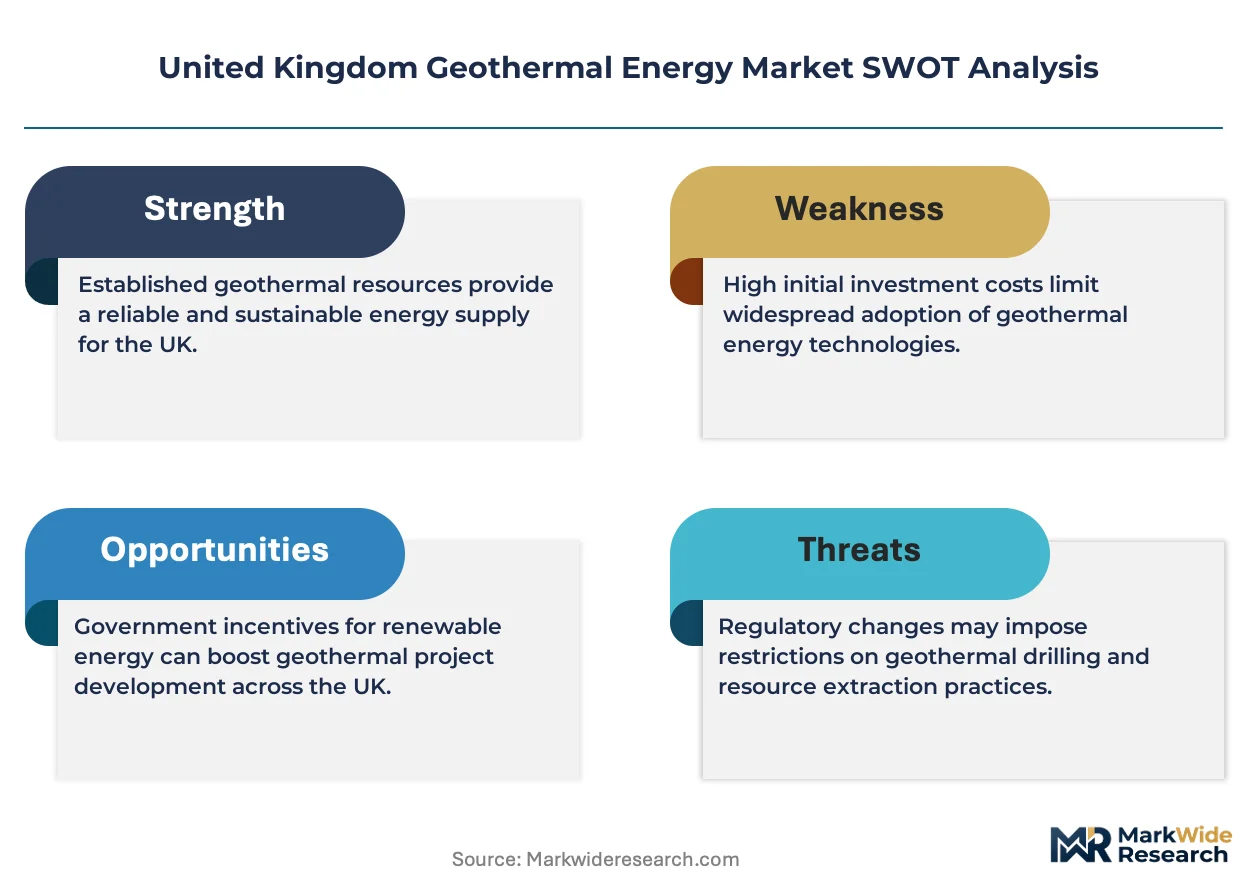
The Green Heat Network Fund is redirecting capital flows from gas-fired district heating toward deep geothermal boreholes, while Cornwall's granite formations attract drilling investment that validates enhanced geothermal systems at commercial scale.
Growth Catalysts
- Green Heat Network Fund:The UK's capital grant mechanism de-risks district heating infrastructure, enabling geothermal feed-in at scale without full merchant exposure.
- Cornwall's granite intrusions:Hot dry rock formations at 5km depth offer temperatures exceeding 180°C, supporting electricity generation viability absent in sedimentary basins.
- Ground-source heat pumps:Building retrofit mandates under the Future Homes Standard are accelerating shallow geothermal deployment in residential construction.
Market Restraints
- Steel casing costs:Deep geothermal drilling requires corrosion-resistant alloys that fluctuate with commodity markets, compressing project IRRs during price spikes.
- Environment Agency permitting:Abstraction licensing and reinjection protocols extend pre-construction timelines by 18-24 months, freezing capital deployment.
- Air-source heat pumps:Lower upfront costs and simpler installation are capturing retrofit demand that geothermal heat pumps could serve.
Strategic Opportunities
- West Midlands sedimentary basins:Permo-Triassic sandstone aquifers offer moderate-temperature resources ideal for direct-use district heating with lower drilling risk.
- Boiler Upgrade Scheme extension:Future iterations could include deep geothermal eligibility, opening residential-scale ground arrays to subsidy support.
- Heat network zoning:The Department for Energy Security and Net Zero's designation of heat network priority areas is unifying geothermal developers with municipal planning authorities.
Industry Challenges
- Deep drilling expertise:The UK retains limited specialist crews capable of directional drilling in crystalline basement rock, constraining project throughput.
- Grid connection queuing:Ofgem's connection application backlog delays electricity export from geothermal generators, eroding revenue certainty.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Geothermal Energy Market |
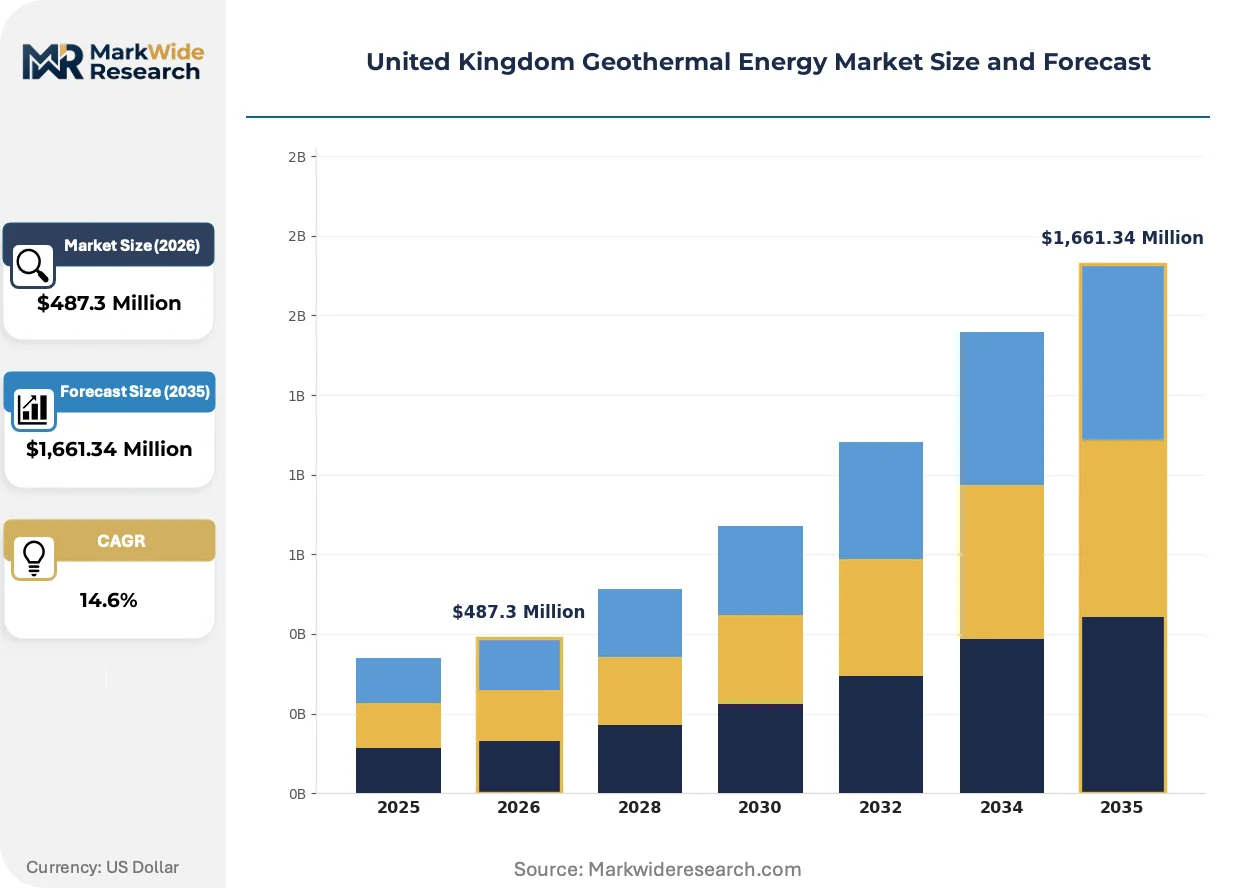
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,661.34 Million |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Direct Heating, Electricity Generation, Ground Source, Enhanced Geothermal Installation Method: Drilling, Surface Loop, Borehole, Well Injection Energy Source: Hydrothermal, Geopressured, Hot Dry Rock, Enhanced Reservoirs End User: District Heating, Industrial Applications, Residential Heating, Aquaculture |
| Companies Covered | Geothermal Engineering Ltd, Eden Geothermal Ltd, Go Geothermal Ltd, GT Energy, Engie SA, GI Energy, Gateshead Energy Company, Octopus Energy, Exergy International, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Geothermal Energy Market Evolving Landscape
Technology convergence between hydraulic stimulation methods and closed-loop systems is expanding viable resource bases beyond traditional hydrothermal reservoirs. Regulatory pressure on gas heating is accelerating alternative thermal infrastructure deployment.
Closed-loop geothermal systems are unifying surface heat exchange with deep borehole arrays, eliminating reservoir permeability requirements. Housing associations in Scotland's Central Belt are piloting these systems for social housing retrofits. The technology is unifying project development timelines by removing hydrogeological uncertainty from resource assessment.
The Environment Agency's abstraction licensing reform is tightening reinjection standards for geothermal operators. Developers must now demonstrate zero net fluid loss to secure permits, increasing monitoring infrastructure costs. Scotland's regulatory divergence from England on water resource classification is creating compliance fragmentation for cross-border projects.
Heat-as-a-service contracts are displacing capital-intensive equipment purchases for commercial building owners. Energy service companies in England's university sector are offering geothermal heating on fixed-price agreements. The model concentrates in the education vertical where long-term occupancy certainty supports 20-year contract structures.
United Kingdom Geothermal Energy Market Segmentation
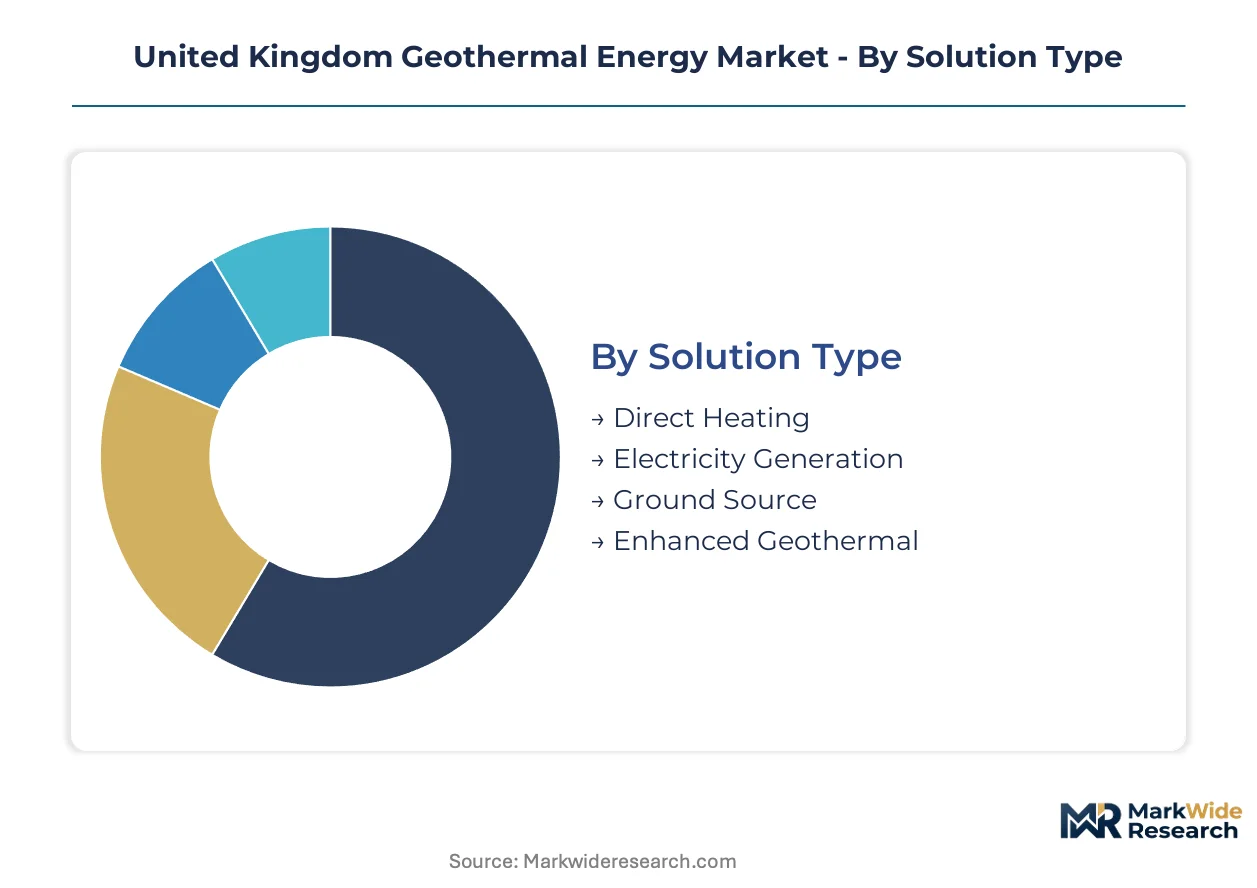
Segmentation in the United Kingdom geothermal energy market reveals distinct capital intensity profiles and regulatory exposure across deployment modes. Each category maps to specific subsurface conditions, drilling expertise requirements, and end-use thermal demands that shape project economics and stakeholder strategies.
Solution Type:
Supply concentration clusters around technologies with proven deployment track records and accessible subsidy mechanisms, while emerging systems face financing gaps despite superior resource potential.
- Direct Heating:Systems extract thermal energy at 30-90°C for space heating and industrial process heat through hydrothermal reservoirs or ground-source loops. Demand concentrates in England's sedimentary basins where the Green Heat Network Fund de-risks district heating infrastructure in Cornwall and the West Midlands. Regulatory clarity on abstraction licensing favors this segment's shorter development timelines.
- Electricity Generation:Deep geothermal plants harness temperatures exceeding 150°C from granite intrusions and hot dry rock formations to drive binary or flash cycle turbines. Deployment focuses on Cornwall's United Downs project where subsurface temperatures at 5km depth validate commercial power production. Grid connection queuing at Ofgem erodes revenue certainty for independent generators.
- Ground Source:Shallow vertical or horizontal loop systems transfer subsurface heat to residential and light-commercial buildings via heat pump technology. The Future Homes Standard mandates low-carbon heating in new construction, accelerating borehole array installations across England's housing developments.
- Enhanced Geothermal:Hydraulic stimulation creates artificial permeability in crystalline basement rocks to enable fluid circulation and heat extraction. Granite formations in Cornwall offer the UK's most viable enhanced geothermal resource base, though limited specialist drilling crews constrain project throughput.
Today's leader: Direct Heating. Tomorrow's challenger: Enhanced Geothermal.
Installation Method:
Cost tier differentiation separates capital-intensive deep drilling from shallow surface installations, with mid-depth boreholes capturing retrofit demand through balanced risk-return profiles.
- Drilling:Deep directional drilling in crystalline rock requires corrosion-resistant steel casings and specialist crews with granite formation expertise. Commodity price volatility in alloy markets compresses project IRRs during steel cost spikes.
- Surface Loop:Horizontal pipe networks at 1-2m depth serve residential plots with sufficient land area, offering lower upfront costs than vertical alternatives. Scotland's Central Belt housing associations pilot closed-loop surface systems for social housing retrofits.
- Borehole:Vertical arrays at 100-200m depth maximize heat exchange efficiency in constrained urban sites, dominating commercial building deployments. The Boiler Upgrade Scheme eligibility for shallow ground arrays drives adoption in England's new construction sector.
- Well Injection:Reinjection of cooled geothermal fluids maintains reservoir pressure and enables sustainable extraction rates. The Environment Agency's tightened zero net fluid loss standards increase monitoring infrastructure costs for permit compliance.
Drilling commands the highest capital commitment. Borehole arrays scale fastest.
Energy Source:
Maturity curves separate established hydrothermal production from experimental enhanced reservoir techniques, with resource accessibility determining viable geography within the UK.
- Hydrothermal:Naturally occurring hot water aquifers in Permo-Triassic sandstone formations provide moderate-temperature resources for direct-use applications. The West Midlands sedimentary basins offer lower drilling risk than crystalline targets, attracting district heating developers.
- Geopressured:Deep sedimentary formations with elevated fluid pressure and dissolved methane content offer combined thermal and hydrocarbon energy potential. No commercial geopressured projects operate in the UK, though North Sea basin geology suggests untapped resource potential.
- Hot Dry Rock:Impermeable crystalline formations at 3-5km depth require hydraulic stimulation to create artificial reservoirs. Cornwall's granite intrusions anchor the UK's only hot dry rock development pipeline, with temperatures exceeding 180°C at commercial drilling depths.
- Enhanced Reservoirs:Engineered permeability through hydraulic fracturing or chemical stimulation expands viable resource bases beyond naturally permeable zones. Technology convergence with closed-loop systems is eliminating hydrogeological uncertainty from resource assessment.
Hydrothermal dominates current output. Enhanced Reservoirs show steepest expansion trajectory.
End User:
Customer type fragmentation reflects divergent thermal load profiles, contract structures, and regulatory exposure across municipal, industrial, and residential demand pools.
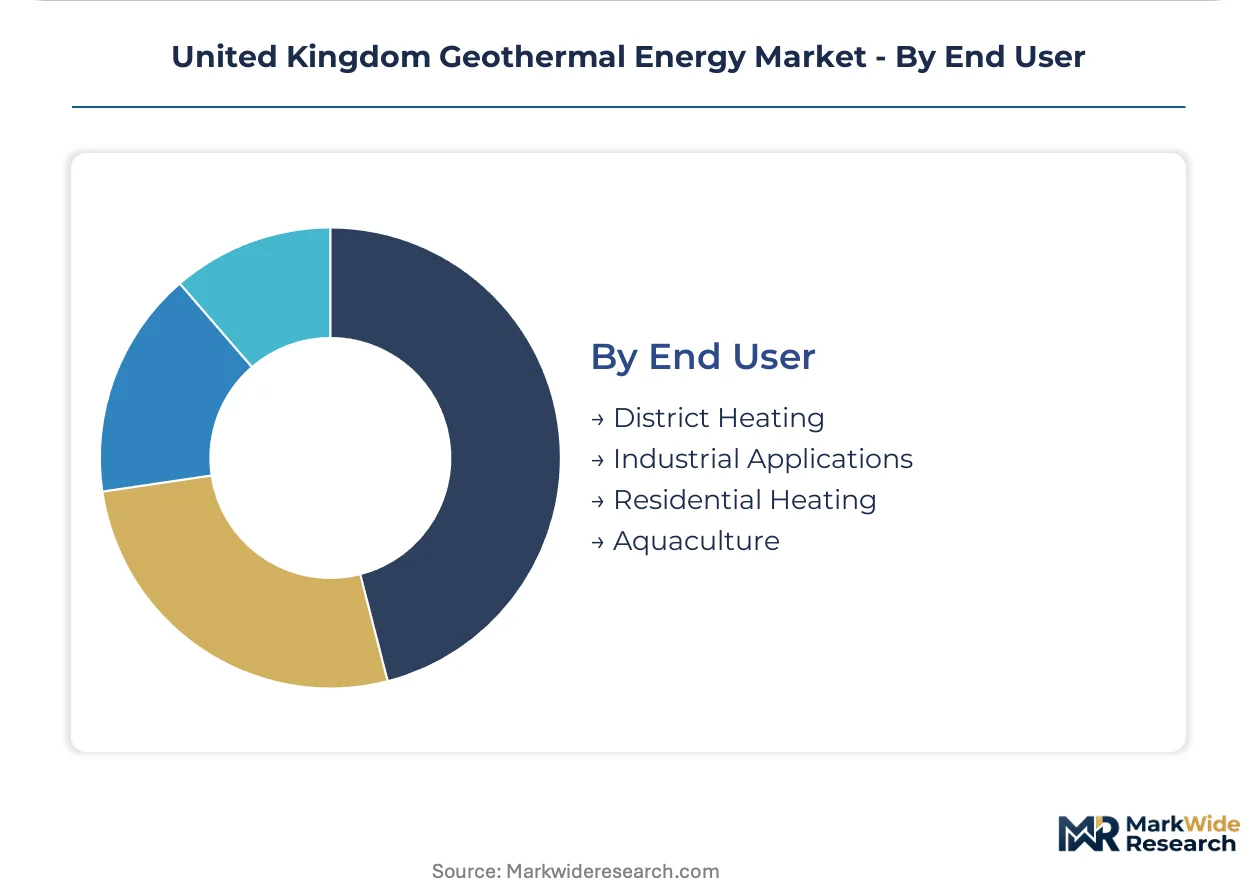
- District Heating:Centralized geothermal plants feed pipe networks serving multiple buildings through heat-as-a-service contracts. Energy service companies in England's university sector offer fixed-price 20-year agreements, leveraging long-term occupancy certainty.
- Industrial Applications:Process heat demand from food processing, paper manufacturing, and chemical production matches moderate-temperature geothermal output. The Department for Energy Security and Net Zero's heat network zoning unifies geothermal developers with municipal planning authorities in industrial corridors.
- Residential Heating:Individual ground-source heat pump installations serve single-family homes and small multi-unit buildings. Building retrofit mandates under the Future Homes Standard accelerate shallow geothermal deployment, though air-source heat pumps capture cost-sensitive demand.
- Aquaculture:Controlled-temperature water supplies optimize fish farming productivity in recirculating systems. Scottish salmon farms explore geothermal heating to reduce energy costs and carbon exposure in coastal production facilities.
District Heating aggregates the largest committed capital. Industrial Applications offer highest load factors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United Kingdom pioneered deep geothermal research at the Rosemanowes quarry in Cornwall during the 1970s, establishing foundational expertise in hot dry rock extraction that informs today's commercial project pipeline.
Cornwall and Southwest England
Granite intrusions at United Downs and Eden Project sites host the UK's highest subsurface temperatures exceeding 180°C at 5km depth. The Green Heat Network Fund channels capital toward district heating networks in Redruth and St Austell. Geothermal Engineering Ltd anchors commercial viability through deep drilling expertise validated at the United Downs demonstration plant.
West Midlands
Permo-Triassic sandstone aquifers beneath Birmingham and Coventry offer moderate-temperature resources ideal for direct-use applications with lower drilling risk than crystalline targets. The Department for Energy Security and Net Zero's heat network zoning unifies developers with municipal planning authorities across the Birmingham metropolitan corridor. GT Energy advances projects targeting university and hospital thermal loads in the region.
Scotland's Central Belt
Sedimentary basins stretching from Glasgow to Edinburgh present hydrothermal potential for district heating integration with existing municipal infrastructure. Housing associations pilot closed-loop geothermal systems for social housing retrofits in Glasgow's East End. The Scottish government's regulatory divergence on water resource classification creates distinct compliance frameworks from England.
North East England
Abandoned coal mine workings beneath Gateshead and Newcastle offer flooded shaft geothermal potential with minimal drilling requirements. Gateshead Energy Company leverages mine water heat recovery for municipal district heating networks. The Boiler Upgrade Scheme accelerates shallow ground-source deployment across Tyneside residential developments.
London and Southeast England
Chalk aquifers beneath the capital provide low-temperature resources suited to ground-source heat pump networks in dense urban construction. The Future Homes Standard mandates low-carbon heating in new Greater London Authority developments. GI Energy and Octopus Energy position shallow geothermal within integrated residential energy service portfolios across suburban housing stock.
United Kingdom Geothermal Energy Market Competitive Landscape
Premium-margin players sit above commodity-margin players across project development depth and regulatory navigation capability. The vendor base clusters around three strategic tiers: deep drilling specialists commanding technical premiums, district heating operators capturing scale economies, and energy service companies bundling geothermal within broader low-carbon portfolios. Consolidation pressure concentrates among shallow ground-source installers facing air-source heat pump competition. Dominant competitive moves include strategic partnerships with municipal authorities for heat network concessions and technology licensing agreements transferring hydraulic stimulation expertise.
Among UK-registered developers, Geothermal Engineering Ltd and Eden Geothermal Ltd occupy positions within the deep drilling specialist tier, representing archetypes of granite-formation expertise and project demonstration capability respectively. Engie SA exemplifies the integrated energy service company model, anchoring geothermal within multi-technology low-carbon heat portfolios. These three entities represent distinct strategic postures: technical specialization, project development focus, and operational scale integration.
| Leading Market Players |
|---|
| Geothermal Engineering Ltd |
| Eden Geothermal Ltd |
| Go Geothermal Ltd |
| GT Energy |
| Engie SA |
| GI Energy |
| Gateshead Energy Company |
| Octopus Energy |
| Exergy International |
| Others |
Value Network & Pricing Analysis
Deep drilling premium-commodity bifurcation separates projects employing corrosion-resistant alloy casings for granite formations from shallow borehole arrays using standard steel. This divergence manifests in capital intensity spreads that compress project IRRs when commodity markets spike, while supply chain configurations concentrate specialist crew availability and equipment fabrication capacity around the North Sea oil services cluster.
Pricing Analysis
Project-based long-term offtake structures dominate, with pricing stratifying across premium engineering-grade specifications, standard commercial arrays, and economy residential heat pump installations. Price differentiation hinges on drilling depth certification and vertical integration of heat network operations. Cost compression in shallow ground-source segments is intensifying because air-source heat pumps capture retrofit demand. Residential buyers exhibit highest price sensitivity, while district heating authorities with Green Heat Network Fund backing absorb premium drilling costs.
Supply Chain Analysis
Equipment refurbishment and remanufacturing flows from decommissioned North Sea oil platforms feed specialist drilling rig availability for deep geothermal projects. Supply concentrates in Norway, the Netherlands, and the United Kingdom for directional drilling technology. Raw material dependencies center on corrosion-resistant steel alloys, high-pressure cementing systems, and downhole temperature sensors. Single-source vulnerability sits with specialist crews capable of granite formation drilling. Distribution runs through EPC contractors and heat network developers serving municipal authority procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom geothermal energy market functions as a regulatory compounder where the Green Heat Network Fund's capital grant mechanism de-risks infrastructure deployment and anchors demand visibility independent of merchant energy prices.
For Market Incumbents: Deploy heat network concession leverage to secure 20-year offtake agreements with municipal authorities before competitor entry. Deepen backward integration into specialist drilling crew training to offset crew scarcity constraining project throughput. Air-source heat pump substitution threatens shallow geothermal market share and demands defensive bundling with district heating operations. For New Entrants and Emerging Players: Closed-loop geothermal systems eliminating hydrogeological uncertainty offer the most penetrable wedge for technology-first market entry. Target Scotland's Central Belt social housing retrofit programs where regulatory divergence creates compliance fragmentation incumbents navigate poorly. Partner with housing associations on heat-as-a-service contracts to bypass capital-intensive equipment purchase barriers. For Investors and Strategic Acquirers: Asymmetric upside sits with deep drilling specialists possessing granite formation expertise and validated project pipelines. Long-term viability framing centers on baseload renewable output securing premium grid access terms against intermittent alternatives. Monitor Environment Agency abstraction licensing reform timelines as inflection indicator for permit velocity and capital deployment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Deep Drilling Capacity Expansion | Validates commercial EGS viability in Cornwall's granite intrusions where United Downs anchors resource proof. |
| Heat Network Concession Partnership | Secures 20-year revenue visibility with municipal authorities under Green Heat Network Fund eligibility. |
| Closed-Loop Technology Licensing | Eliminates hydrogeological uncertainty from resource assessment and accelerates project development timelines. |
| Specialist Crew Training Investment | Addresses bottleneck constraining enhanced geothermal project throughput in crystalline basement formations. |
| Scotland Regulatory Arbitrage Positioning | Captures water resource classification divergence creating compliance fragmentation for cross-border developers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with geothermal project developers, district heating network operators, drilling contractors, and Environment Agency permitting officers with secondary validation against Ofgem regulatory filings, Department for Energy Security and Net Zero policy documents, and geological survey data. Bottom-up project pipeline enumeration and top-down heat demand modeling provided cross-verification.
Comparable-period anchoring linked forward projections to historical deployment trajectories across the analysis window. Segmentation dimensions modeled encompass solution type, installation depth tier, energy source category, and end-user vertical. CAGRs derived from installed capacity build-out curves and capital expenditure flows. Forecast inputs incorporated Green Heat Network Fund allocation trajectories and abstraction licensing reform implementation pace.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to steel commodity volatility and grid connection queuing resolution at Ofgem. Practitioners should monitor specialist crew training program announcements and heat network zoning designations for early signals of supply capacity expansion and demand concentration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Geothermal Energy
US Geothermal Heat Pump Market
Geothermal Energy
Denmark Geothermal Energy Market
Geothermal Energy
Global Geothermal Heat Pumps Market
Geothermal Energy
Geothermal Power Market
Geothermal Energy
Indonesia Geothermal Energy Market
Geothermal Energy
Enhanced Geothermal System Market
Geothermal Energy
Asia-Pacific Geothermal Energy Market
Geothermal Energy
Geothermal Power Generation Market
Geothermal Energy
Hungary Geothermal Energy Market
Geothermal Energy
Philippines Geothermal Energy Market
Geothermal Energy
Netherlands Geothermal Energy Market
Geothermal Energy
Geothermal Power Infrastructure and Components Market
Geothermal Energy
Geothermal Power Infrastructure Market
Geothermal Energy
Geothermal Energy Market
Geothermal Energy
Sweden Geothermal Energy Market