
 Asia Pacific Liquid Hydrogen Market | 2026-2036
Asia Pacific Liquid Hydrogen Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Liquid Hydrogen Market Outlook
ISO 19880-1 certification for gaseous and liquid hydrogen fueling stations is reorganizing competitive access across the Asia Pacific liquid hydrogen landscape. Linde plc leverages its cryogenic engineering heritage to sustain liquefaction capacity leadership in Australia and South Korea. Iwatani Corporation anchors domestic supply chains through integrated production and distribution networks spanning Japan's key industrial ports. Kawasaki Heavy Industries, Ltd. differentiates via proprietary cargo containment systems for maritime liquid hydrogen transport.
Liquid hydrogen denotes hydrogen cooled to minus 253 degrees Celsius, achieving a density of 70.8 kilograms per cubic meter for efficient long-distance energy transport and high-purity industrial use. Bulk liquid hydrogen dominates current revenue pools due to scale economics at export-oriented liquefaction terminals, while cryogenic liquid hydrogen commands premium positioning in aerospace and satellite launch applications where boil-off rates below two percent define operational viability. Electrolysis technology segments are attracting disproportionate capital allocation as renewable-powered projects in Australia and Chile-linked offtake structures reshape cost trajectories.
METI in Japan, the Korean Agency for Technology and Standards, and Australia's National Hydrogen Strategy collectively establish product purity benchmarks, safety protocols, and cross-border certification reciprocity that determine market participation eligibility. These frameworks mandate specific storage pressure thresholds and leak detection standards that filter out non-compliant infrastructure developers. Stakeholders must track evolving bilateral hydrogen trade agreements and domestic subsidy qualification criteria to secure offtake visibility and project finance access.
Market Dynamics
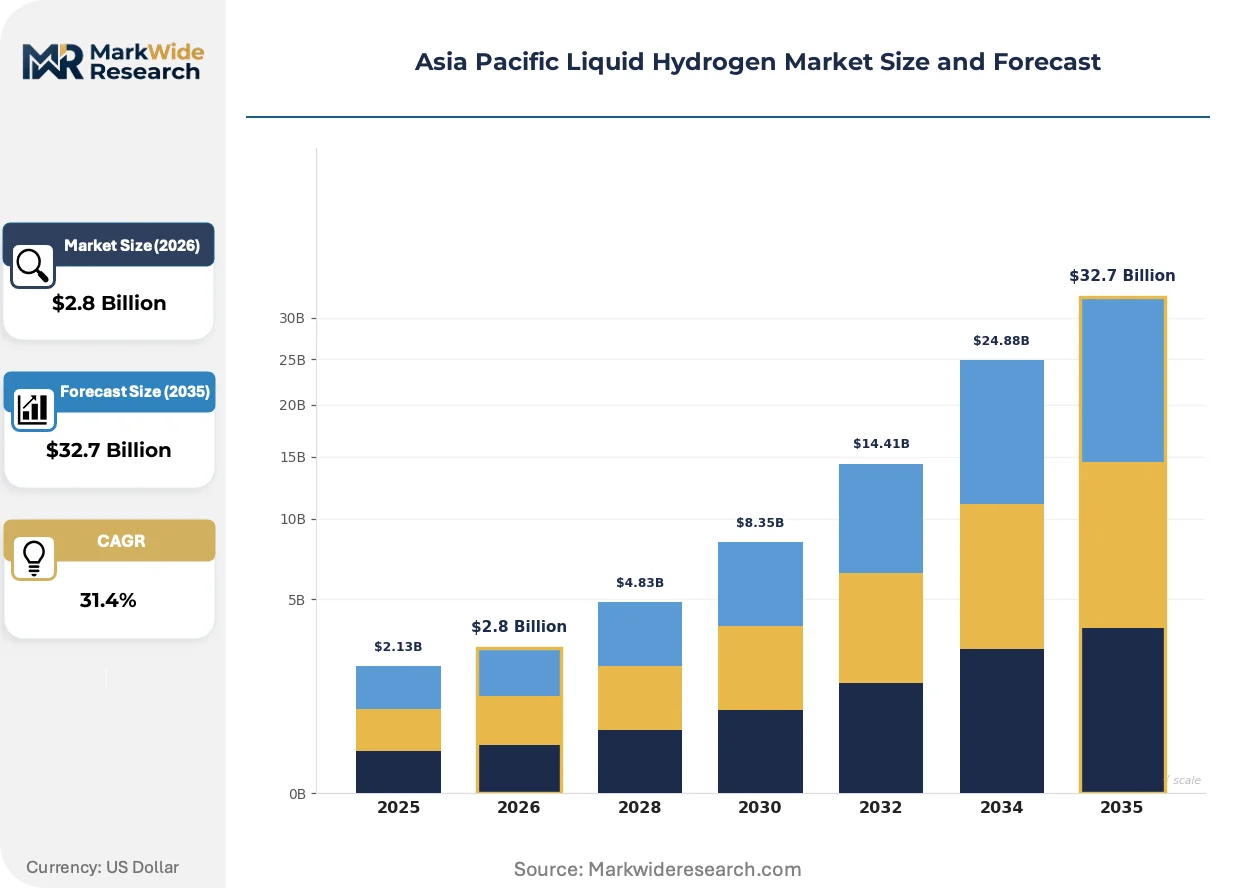
Japan's METI hydrogen roadmap and South Korea's Hydrogen Economy Policy are redirecting capital flows toward liquefaction infrastructure, compressing project development timelines and reshaping competitive entry barriers across the Asia Pacific liquid hydrogen landscape.
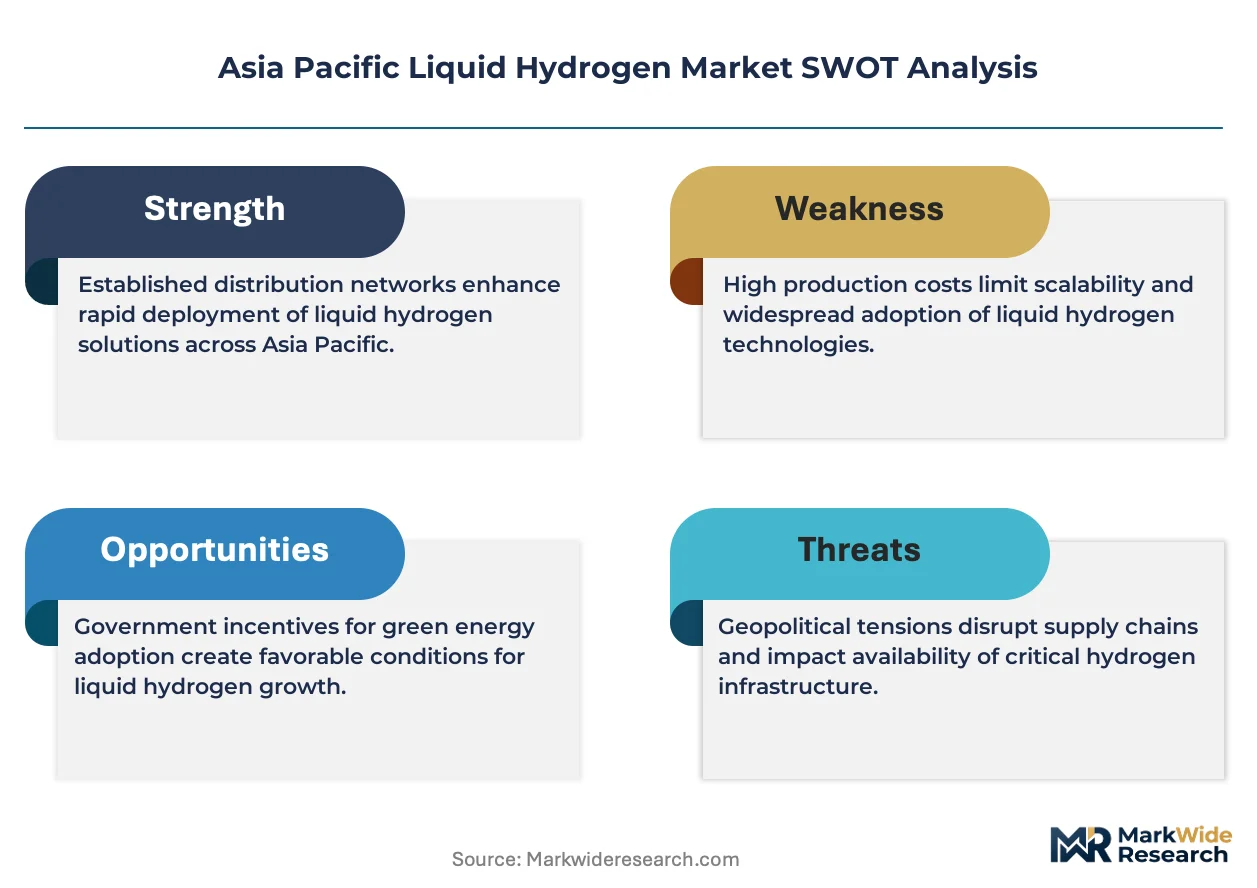
Growth Catalysts
- Aerospace propulsion demand:Satellite launch operators and hypersonic vehicle developers are accelerating offtake agreements for cryogenic liquid hydrogen with boil-off rates below two percent.
- Australia's National Hydrogen Strategy:Export-oriented liquefaction terminals are securing bilateral trade frameworks with Japan and South Korea, anchoring regional supply chain formation.
- Electrolysis capital allocation:Renewable-powered projects in Australia are compressing production cost trajectories and attracting Chile-linked offtake structures.
Market Restraints
- Cryogenic storage cost structure:Minus 253 degrees Celsius liquefaction consumes 30-40 percent of hydrogen energy content, constraining project economics at smaller scales.
- Supply concentration risk:Liquefaction capacity clusters in Japan, South Korea, and eastern Australia, exposing buyers to geographic disruption vulnerabilities.
- ISO 19880-1 certification friction:Fueling station compliance timelines extend 18-24 months, filtering out infrastructure developers lacking cryogenic engineering heritage.
Strategic Opportunities
- Maritime transport containment:Proprietary cargo systems for liquid hydrogen shipping are opening new export corridors from Australian production hubs to Japanese industrial ports.
- South Korea's Hydrogen Economy Policy:Domestic subsidy qualification criteria are creating first-mover advantages for integrated production and distribution networks.
- Industrial feedstock pivot:Steel and chemical producers in Japan are retrofitting blast furnaces and ammonia synthesis loops for liquid hydrogen direct reduction.
Industry Challenges
- Cryogenic engineering talent scarcity:Specialized expertise in minus 253 degrees Celsius system design and boil-off management is concentrating among legacy industrial gas specialists.
- Cross-border certification reciprocity:Divergent safety protocols between Japan's METI, South Korea's KATS, and Australia's safety regulators are complicating equipment standardization.
- Legacy infrastructure integration:Existing gaseous hydrogen pipelines and storage caverns require costly retrofitting for liquid hydrogen compatibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Liquid Hydrogen Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $32.7 Billion |
| CAGR (2026 – 2036) | 31.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bulk Liquid Hydrogen, Liquid Hydrogen Cylinder, Liquid Hydrogen Tanker, Cryogenic Liquid Hydrogen End User: Aerospace, Industrial Applications, Fuel Cell Vehicles, Energy Providers Technology: Electrolysis, Steam Methane Reforming, Gasification, Hybrid Processes Application: Power Generation, Transportation, Chemical Manufacturing, Refrigeration |
| Companies Covered | Air Liquide S.A, Linde plc, Air Products and Chemicals Inc., Iwatani Corporation, Ballard Power Systems, Taiyo Nippon Sanso Holding Corporation, Messer Group GmbH, Kawasaki Heavy Industries, Ltd., Mitsubishi Heavy Industries, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Liquid Hydrogen Market Strategic Shifts
Technology convergence and regulatory harmonization are compressing development cycles across the Asia Pacific liquid hydrogen value chain, with particular acceleration in maritime transport and aerospace applications.
Cryogenic pump technology is miniaturizing. These systems enable precise liquid hydrogen transfer at minus 253 degrees Celsius for satellite refueling operations. Aerospace ground support equipment manufacturers are adopting compact units to reduce pad turnaround times. The technology is miniaturizing containment footprints, allowing launch operators to site fueling infrastructure closer to payload integration facilities.
METI's hydrogen roadmap mandates specific storage pressure thresholds and leak detection standards that exceed prior industrial gas protocols. Japanese industrial ports are retrofitting existing LNG terminals with cryogenic-compatible materials and monitoring systems. Australia's National Hydrogen Strategy is aligning with these benchmarks to secure bilateral certification reciprocity, compressing equipment approval timelines for cross-border projects.
Steel producers are consolidating procurement through long-term offtake agreements rather than spot market purchases. Japanese blast furnace operators are signing 10-15 year supply contracts directly with liquefaction project developers, bypassing traditional industrial gas distributors. South Korean chemical conglomerates are replicating this model for ammonia synthesis feedstock, concentrating buyer power among a handful of integrated energy majors.
Asia Pacific Liquid Hydrogen Market Segmentation
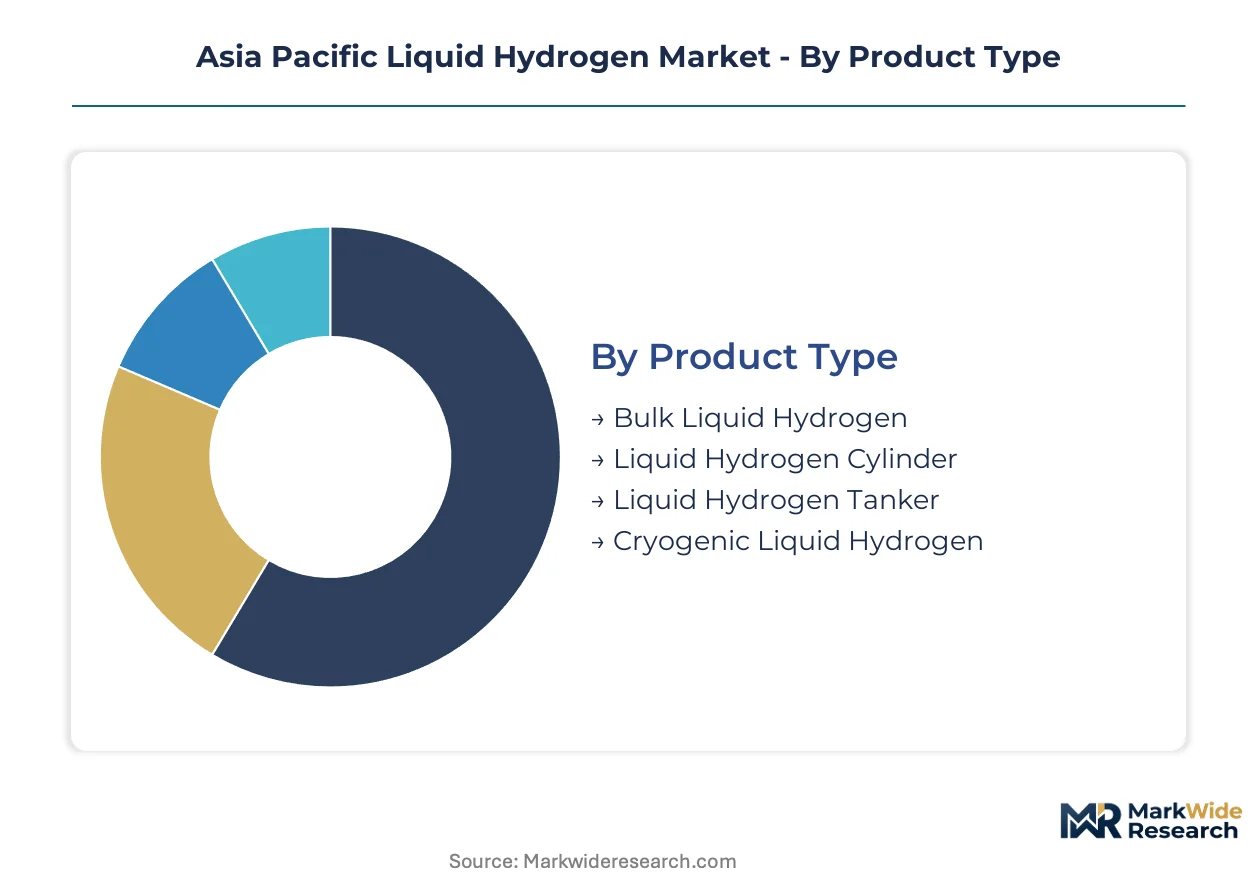
Segmentation in the Asia Pacific liquid hydrogen market reveals how regulatory frameworks and infrastructure maturity concentrate value capture across product formats and end-use applications. Distinct certification requirements from Japan's METI, South Korea's KATS, and Australia's safety regulators fragment competitive access by segment.
Product Type:
Japan's METI mandates ISO 19880-1 compliance thresholds that vary sharply by container scale, filtering market participation across storage and transport formats.
- Bulk Liquid Hydrogen:Large-scale storage at minus 253 degrees Celsius serves export-oriented liquefaction terminals in Australia and industrial ports in Japan. Demand concentrates at Queensland and Western Australia production hubs where bilateral trade frameworks with Japanese buyers anchor offtake visibility.
- Cryogenic Liquid Hydrogen:Ultra-low boil-off formulations achieve sub-two-percent loss rates for aerospace propulsion and satellite launch applications. South Korean launch operators and Japanese space agencies drive procurement for ground support equipment requiring compact containment footprints near payload integration facilities.
- Liquid Hydrogen Cylinder:Intermediate-scale containers serve distributed fueling stations and industrial feedstock delivery across Japanese manufacturing clusters.
- Liquid Hydrogen Tanker:Maritime cargo systems enable intercontinental transport from Australian production hubs to Japanese industrial ports under emerging bilateral certification reciprocity agreements.
Bulk liquid hydrogen handles the majority of throughput; cryogenic liquid hydrogen is the fastest mover on share.
End User:
Customer procurement patterns diverge sharply between long-term contract consolidation and spot market exposure.
- Industrial Applications:Steel and chemical producers in Japan's blast furnace corridors and South Korean ammonia synthesis facilities are signing direct 10-15 year offtake agreements with liquefaction developers, bypassing traditional industrial gas distributors.
- Aerospace:Satellite launch operators require cryogenic liquid hydrogen with precise boil-off specifications for propulsion systems and ground support equipment, with procurement concentrated among government-backed space agencies and commercial launch providers.
- Fuel Cell Vehicles:Japanese and South Korean automotive OEMs drive demand for ISO 19880-1 certified fueling infrastructure, though station deployment timelines extend 18-24 months due to cryogenic engineering certification requirements.
- Energy Providers:Utility-scale power generation projects in Australia and grid-balancing applications in Japan represent emerging offtake channels with volume concentration among integrated energy majors.
Industrial applications command the dominant procurement volume; aerospace is climbing the fastest on contract value per kilogram.
Technology:
Capital allocation intensity separates renewable-powered pathways from fossil-linked production methods.
- Electrolysis:Renewable-powered projects in Australia leverage solar and wind resource availability to compress production cost trajectories, with Chile-linked offtake structures attracting disproportionate investment flows.
- Steam Methane Reforming:Established production methods dominate current supply in Japan and South Korea, though carbon intensity constraints under national hydrogen roadmaps are redirecting capital toward lower-emission alternatives.
- Gasification:Coal and biomass gasification pathways retain relevance in specific Australian and South Korean industrial corridors with carbon capture integration requirements.
- Hybrid Processes:Combined electrolysis and reforming configurations are emerging at pilot scale to optimize capacity factor and cost structure across variable renewable output profiles.
Steam methane reforming retains the installed base; electrolysis is gaining share fastest on new project announcements.
Application:
End-use economics vary by energy density requirements and purity specifications that determine technology selection.
- Transportation:Maritime shipping and fuel cell vehicle fueling drive demand for high-purity liquid hydrogen with stringent boil-off constraints, with Australian-Japanese export corridors opening new volume channels.
- Chemical Manufacturing:Ammonia synthesis and refinery hydrogenation loops in South Korea and Japan require continuous supply reliability, favoring long-term contract structures over spot procurement.
- Power Generation:Grid-scale storage and peaking applications in Australia leverage liquid hydrogen's energy density for seasonal renewable balancing, though round-trip efficiency constraints limit current deployment scale.
- Refrigeration:Cryogenic cooling applications in semiconductor manufacturing and scientific research represent niche demand with premium pricing tolerance for ultra-high purity specifications.
Transportation absorbs the largest forward investment; chemical manufacturing maintains the steadiest contract profile.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Procurement from Japanese steelmakers and South Korean chemical conglomerates dominates contract volumes, while Australian export terminals anchor supply-side investment. METI, KATS, and Australia's National Hydrogen Strategy collectively determine certification reciprocity and project finance access across the region.
Japan
Blast furnace operators in Chiba and Kobe are retrofitting direct reduction systems for liquid hydrogen feedstock. METI mandates ISO 19880-1 compliance thresholds that exceed prior industrial gas protocols. The Keihin industrial corridor hosts liquefaction terminals retrofitting existing LNG infrastructure with cryogenic-compatible materials.
South Korea
Naju and Ulsan chemical clusters drive ammonia synthesis feedstock demand through 10-15 year offtake agreements. KATS establishes storage pressure thresholds and leak detection standards that filter non-compliant equipment vendors. The Busan-Ulsan corridor concentrates aerospace ground support equipment procurement for satellite launch operations.
Australia
Queensland and Western Australia production hubs leverage solar and wind resources to compress electrolysis cost trajectories. The National Hydrogen Strategy aligns with Japanese benchmarks to secure bilateral certification reciprocity. Gladstone and Kwinana industrial zones anchor export-oriented liquefaction terminal development.
China
Yangtze River Delta hydrogen equipment fabricators supply cryogenic pump systems to regional liquefaction projects. MIIT and GB standards govern pressure vessel certification for liquid hydrogen storage. The Pearl River Delta hosts pilot-scale maritime containment system testing for intercontinental transport corridors.
Asia Pacific Liquid Hydrogen Market Competitive Environment
Player mix skews toward integrated industrial gas majors with cryogenic engineering heritage, compressing entry for specialized entrants. Tier-one positions concentrate among liquefaction capacity owners and maritime containment system developers. Strategic moves center on bilateral offtake anchoring and certification reciprocity alignment across Japanese, South Korean, and Australian regulatory frameworks.
Within the industrial gas archetype, Air Liquide S.A., Linde plc, and Iwatani Corporation occupy positions reflecting geographic anchoring and integrated supply chain control. Air Liquide S.A. exemplifies European-headquartered capacity leadership in cryogenic systems. Linde plc represents Anglo-German heritage in large-scale liquefaction engineering. Iwatani Corporation anchors Japanese domestic distribution networks spanning key industrial ports. These three entities collectively illustrate how regulatory compliance capability and bilateral trade framework access determine competitive positioning.
| Leading Market Players |
|---|
| Air Liquide S.A |
| Linde plc |
| Air Products and Chemicals Inc. |
| Iwatani Corporation |
| Ballard Power Systems |
| Taiyo Nippon Sanso Holding Corporation |
| Messer Group GmbH |
| Kawasaki Heavy Industries, Ltd. |
| Mitsubishi Heavy Industries |
| Others |
Value Chain & Pricing Dynamics
Eighteen-to-twenty-four-month ISO 19880-1 certification timelines concentrate pricing power among cryogenic engineering specialists with established METI and KATS compliance track records, while compressing margins for infrastructure developers lacking bilateral trade framework access across Japanese and South Korean industrial corridors.
Pricing Analysis
Cost-plus contracts indexed to renewable electricity tariffs and electrolyzer capacity factors dominate procurement between Australian liquefaction developers and Japanese steelmaker consortiums. Pricing stratifies across aerospace-grade cryogenic formulations, industrial bulk supply, and maritime transport containment tiers. Cost compression in electrolysis pathways is intensifying because solar and wind resource availability in Queensland and Western Australia anchors production economics. Fuel cell vehicle fueling station operators exhibit highest price sensitivity due to extended certification timelines, while satellite launch agencies tolerate premium positioning for sub-two-percent boil-off specifications.
Supply Chain Analysis
Australia, Japan, and South Korea anchor liquefaction capacity and cryogenic containment manufacturing across the Asia Pacific liquid hydrogen landscape. Australian production hubs draw from solar and wind generation assets, Japanese industrial ports rest on retrofit LNG terminal infrastructure, and South Korean chemical clusters hinge on ammonia synthesis feedstock integration. Single-source vulnerability concentrates in cryogenic pump systems and specialized cargo containment materials sourced from Yangtze River Delta fabricators. Distribution runs through bilateral offtake agreements linking Queensland production terminals to Keihin and Busan-Ulsan industrial corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia Pacific liquid hydrogen market represents a high-growth disruption propelled by METI hydrogen roadmap mandates and South Korean Hydrogen Economy Policy subsidies compressing project development timelines.
For Market Incumbents: Shield liquefaction capacity leadership by securing backward integration into Australian renewable generation assets and accelerating KATS certification reciprocity alignment before emerging electrolysis specialists capture bilateral offtake channels. Cryogenic engineering talent scarcity among legacy industrial gas majors creates defensive moats, but electrolyzer OEMs with Chile-linked project finance access threaten margin compression in export-oriented supply chains.
For New Entrants and Emerging Players: ISO 19880-1 fast-track partnerships with Japanese industrial port authorities open white-space entry for cryogenic fueling station developers lacking legacy METI compliance histories. Australia's National Hydrogen Strategy subsidy qualification criteria create penetrable entry points for integrated production-distribution networks serving Gladstone and Kwinana export terminals. Target direct procurement relationships with South Korean ammonia synthesis facilities bypassing established industrial gas distributor intermediation.
For Investors and Strategic Acquirers: Carve-out targets emerge from conglomerate industrial divisions holding cryogenic containment patents but lacking integrated liquefaction capacity or bilateral trade framework access. Long-term viability centers on electrolysis cost trajectory convergence with steam methane reforming benchmarks across the analysis window. Watch for METI-KATS-Australian certification reciprocity announcements as inflection indicators for cross-border equipment standardization and project finance liquidity.
| Strategic Initiative | Industry Significance |
|---|---|
| Electrolysis Capacity Buildout | Queensland solar-wind hybrid projects compress production economics for Japanese offtake. |
| Backward Integration into Renewable Generation | Captive solar and wind assets anchor electrolyzer capacity factors and cost visibility. |
| Long-term Supply Agreement | Chiba and Kobe steelmakers bypass spot markets through 10-15 year direct procurement contracts. |
| Technology Licensing | Proprietary cargo containment systems from Kawasaki Heavy Industries enable maritime export corridors. |
| Joint Venture | Australian-Japanese liquefaction terminal partnerships secure bilateral certification reciprocity alignment. |
Study Parameters
Operator-level perspectives from liquefaction project developers, cryogenic engineering specialists, METI policy officers, KATS certification auditors, and Australian hydrogen hub coordinators anchored the qualitative base for this study. Primary field engagement combined structured interviews with secondary validation across SEC filings from industrial gas majors, Australian National Hydrogen Strategy progress reports, KATS technical standards documentation, and METI hydrogen roadmap implementation updates. Bottom-up capacity and offtake modeling triangulated against top-down regional demand projections from steel, chemical, and aerospace end-use sectors.
Sensitivity analysis tested electrolyzer cost decline trajectories, renewable capacity factor assumptions, and bilateral trade framework implementation timelines across the projection horizon. Segmentation dimensions modeled include product format, end-use application, production technology pathway, and regional regulatory cluster. CAGRs derived from installed base evolution and new project announcement pipelines, with electrolysis capital allocation intensity and cryogenic storage cost structures serving as key forecast inputs.
Decision-makers should treat outputs as directional under sustained METI-KATS-Australian policy alignment and electrolyzer cost compression assumptions; material deviation in certification reciprocity timelines or renewable generation buildout rates would warrant model refresh. Recalibration cycles align with material shifts in national hydrogen roadmap implementation schedules and bilateral trade agreement finalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydrogen Energy
Water Electrolysis Green Hydrogen Production Market
Hydrogen Energy
Europe Hydrogen Generation Market
Hydrogen Energy
Clean Hydrogen Market
Hydrogen Energy
Hydrogen Gas Generator Market
Hydrogen Energy
Hydrogen Refueling Protocol and Dispenser Performance Test Systems Market
Hydrogen Energy
Electrolyzer Market
Hydrogen Energy
Green Hydrogen Storage Technology Market
Hydrogen Energy
Green Energy Hydrogen Production System Market
Hydrogen Energy
Brown Hydrogen Market
Hydrogen Energy
Green Hydrogen Market
Hydrogen Energy
On-Site Hydrogen Generator Market
Hydrogen Energy
Alkaline Water Electrolysis Market
Hydrogen Energy
Hydrogen Ejector Market
Hydrogen Energy
Asia-Pacific Clean Hydrogen Market
Hydrogen Energy
Hydrogen Purification Technologies Market
Hydrogen Energy
Hydrogen Energy Storage Market