
 Hydrogen Energy Electrolyzer Market | 2026-2036
Hydrogen Energy Electrolyzer Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogen Energy Electrolyzer Market Insights
Platinum is expanding its role in proton exchange membrane stacks as iridium supply constraints force stack redesigns across the industry. Nel ASA leverages its integrated manufacturing footprint in Norway to control stack production from catalyst coating to system assembly. Siemens Energy anchors its position through large-scale alkaline and PEM platforms serving European industrial clusters. thyssenkrupp nucera specializes in high-capacity alkaline systems for chemical and steel sector offtakers.
Hydrogen energy electrolyzers are electrochemical devices that split water into hydrogen and oxygen using direct current electricity, with stack power densities ranging from 1.5 to 6.0 kW per liter depending on technology class. Their primary commercial purpose is to produce low-carbon or renewable hydrogen for industrial feedstock, energy storage, and transport fuel applications. Alkaline technology dominates installed base economics through lower capital cost per kilowatt, while PEM systems command premium positioning in variable renewable integration and compact deployment scenarios. Utility-scale capacity configurations are attracting the fastest-growing order pipeline as developers pair gigawatt-class projects with offshore wind and solar farms.
The EU Green Deal and delegated acts under the Renewable Energy Directive establish product-level criteria for renewable hydrogen certification, directly conditioning market access for European deployments. In the United States, the Department of Energy and IRS administer production tax credits under the Inflation Reduction Act that reshape project finance structures for domestic electrolyzer installations. China's MIIT and National Development and Reform Commission coordinate dual carbon goals with provincial hydrogen demonstration zones that concentrate demand creation. Stakeholders must monitor regulatory granularity around additionality requirements and carbon intensity thresholds, as these definitions will determine which technology configurations and power sourcing strategies qualify for preferential treatment across jurisdictions.
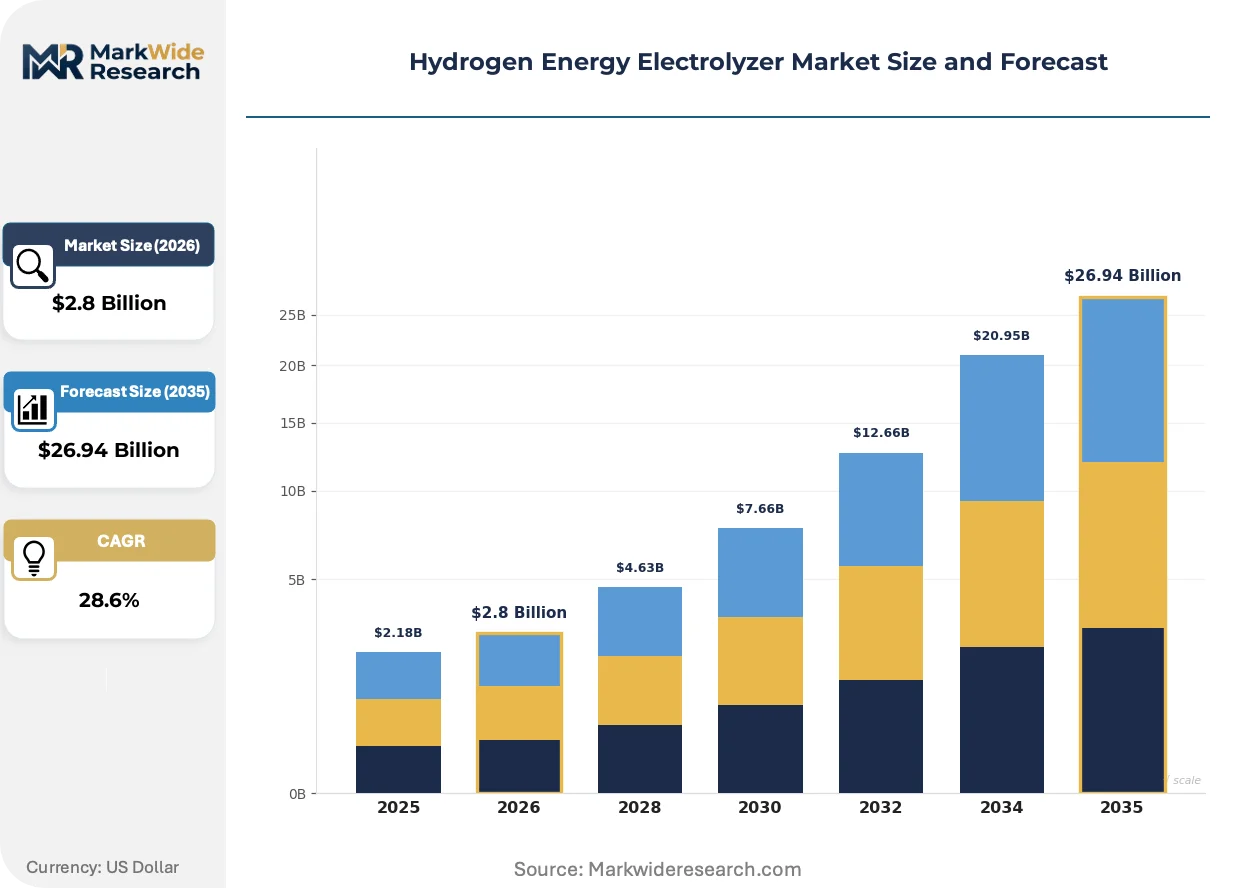
Market Dynamics
The EU Green Deal's delegated acts under the Renewable Energy Directive are forcing electrolyzer manufacturers to reconfigure power sourcing strategies to meet renewable hydrogen certification thresholds. This regulatory pressure is compressing project development timelines while reshaping technology selection criteria across European industrial clusters.
Growth Catalysts
- Alkaline Technology Economics:Lower capital cost per kilowatt positions alkaline systems as the default choice for utility-scale ammonia and steel sector offtakers seeking baseload hydrogen supply.
- Inflation Reduction Act Production Tax Credits:The US Department of Energy and IRS administration of IRA credits restructures project finance for domestic electrolyzer installations, accelerating gigawatt-class deployment pipelines.
- China's Provincial Demonstration Zones:MIIT and NDRC coordination of dual carbon goals concentrates demand creation in designated hydrogen hubs, concentrating manufacturing scale and offtake certainty.
Market Restraints
- Iridium Supply Concentration:South African and Russian mining dominance creates iridium procurement risk that forces PEM stack redesigns toward platinum-heavy catalyst configurations.
- Renewable Power Intermittency:Variable wind and solar output imposes capacity factor penalties on electrolyzer economics, requiring oversized renewable generation assets or grid backup contracts.
- Grid Connection Queues:Transmission interconnection delays in Germany and the United States extend project commissioning timelines by 18-36 months beyond equipment delivery schedules.
Strategic Opportunities
- Saudi Arabia's NEOM Gigaproject:The kingdom's renewable hydrogen export hub creates concentrated demand for high-capacity alkaline systems integrated with dedicated solar and wind generation.
- Offshore Wind Pairing:North Sea offshore wind farms in Denmark and the Netherlands offer direct power contracts that bypass grid congestion and satisfy additionality requirements for green hydrogen certification.
- Steel Sector Decarbonization Mandates:EU Carbon Border Adjustment Mechanism phase-in creates contractual pull for electrolyzer-derived hydrogen in blast furnace replacement projects across German and Polish industrial clusters.
Industry Challenges
- Electrolyzer Stack Assembly Skill Gap:Precision membrane electrode assembly and catalyst coating operations require specialized technicians that outstrip current vocational training pipeline output in Norway and Germany.
- Multi-Megawatt System Integration Complexity:Utility-scale installations demand coordination between power electronics, gas handling, and thermal management subsystems that strains EPC contractor experience.
- Certification Timeline Uncertainty:Pending final EU delegated act specifications on carbon intensity thresholds delay final investment decisions as developers await qualifying criteria clarity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogen Energy Electrolyzer Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $26.94 Billion |
| CAGR (2026 – 2036) | 28.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: PEM, Alkaline, Solid Oxide, Anion Exchange Membrane End User: Industrial, Transportation, Power Generation, Residential Deployment: Onshore, Mobile, Distributed, Centralized Capacity: Small Scale, Medium Scale, Large Scale, Utility Scale |
| Companies Covered | Nel ASA, Plug Power Inc., ITM Power plc, Siemens Energy, thyssenkrupp nucera, Cummins Inc., McPhy Energy, LONGi, John Cockerill, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogen Energy Electrolyzer Market Trends and Innovations
Electrolyzer technology trajectories are converging on modular, high-pressure systems that compress balance-of-plant costs while expanding deployment flexibility across industrial and energy storage applications.
Solid oxide electrolyzer technology is unifying high-temperature steam input with waste heat recovery from adjacent industrial processes. Chemical sector offtakers in the Netherlands and Germany are piloting integrated configurations that source steam from ethylene cracker operations. This convergence is unifying thermal and electrical efficiency optimization into single-system design specifications that reshape competitive bidding criteria for large-scale tenders.
REACH regulation amendments on fluorinated polymer restrictions are compelling membrane manufacturers to accelerate perfluorinated compound phase-out timelines. Industrial chemical producers face reformulation deadlines that compress R&D investment cycles for alternative proton exchange materials. European PEM stack suppliers are responding with accelerated validation programs for hydrocarbon-based membrane alternatives that trade ionic conductivity for regulatory compliance certainty.
Long-term hydrogen purchase agreements are displacing spot market exposure as the dominant procurement mechanism for industrial offtakers. Ammonia and steel producers in Germany and China are negotiating 10-15 year take-or-pay contracts that transfer volume risk to project developers in exchange for price predictability. This contractual evolution is most visible in North Sea offshore wind corridors where developers anchor project finance on contracted offtake coverage ratios.
Hydrogen Energy Electrolyzer Market Segmentation
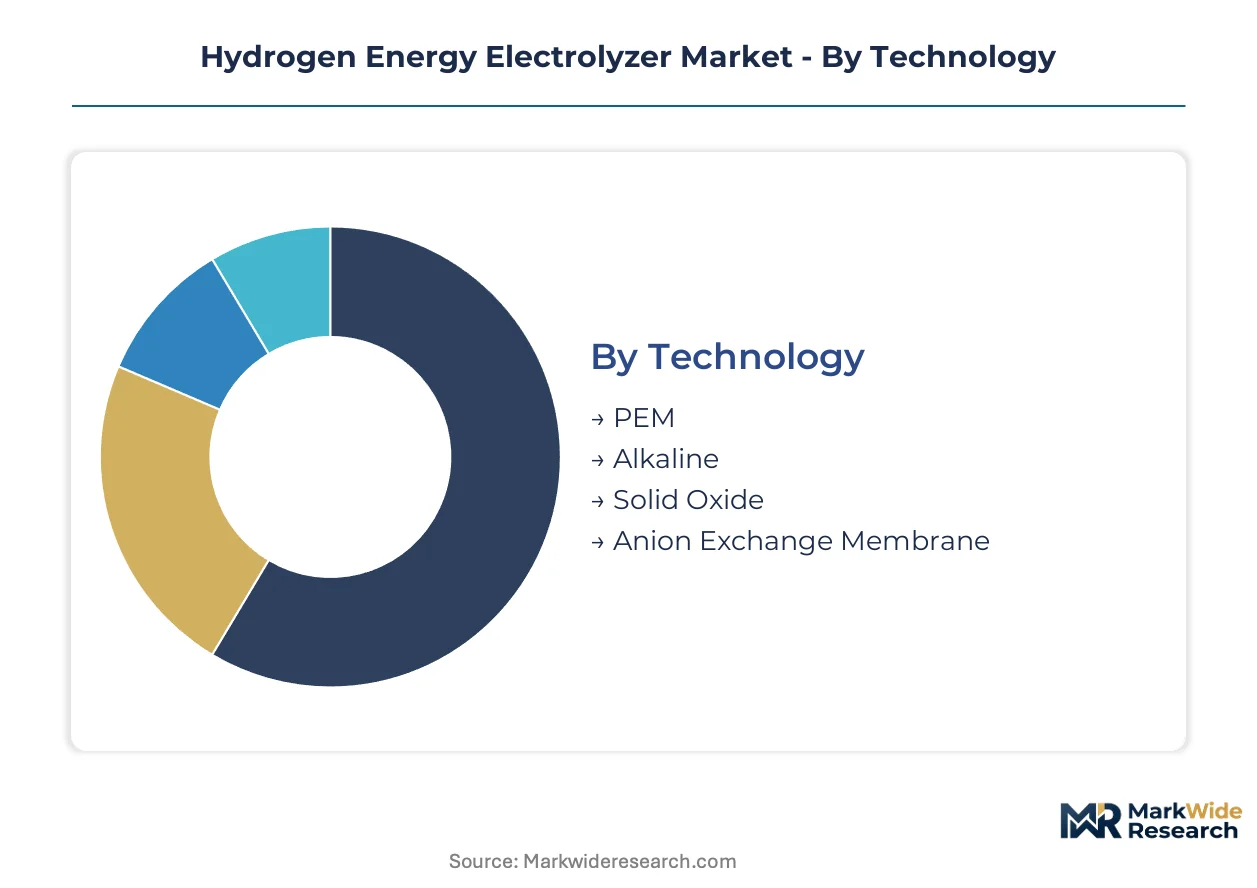
Electrolyzer segmentation reveals how technology choices, deployment configurations, and capacity scales align with distinct commercial use cases and financing structures. Understanding these divisions exposes where capital is concentrating and which system architectures are gaining procurement traction.
Technology:
Supply concentration in catalyst materials and membrane manufacturing is fragmenting competitive positions across electrolyzer technology classes.
- PEM:Proton exchange membrane stacks utilize platinum-group catalysts and fluorinated polymer membranes to achieve rapid response to variable renewable input. Nel ASA and Siemens Energy dominate European PEM supply for German industrial clusters seeking grid-balancing hydrogen production.
- Alkaline:Liquid potassium hydroxide electrolyte systems operate with nickel-based electrodes at lower capital intensity per kilowatt. China's MIIT-coordinated demonstration zones and Saudi Arabia's NEOM project are absorbing the majority of high-capacity alkaline manufacturing output.
- Solid Oxide:High-temperature ceramic electrolyte cells achieve superior efficiency when paired with industrial waste heat sources. Netherlands chemical sector pilots integrate these units with ethylene cracker operations.
- Anion Exchange Membrane:Emerging alkaline-compatible architecture eliminates fluorinated components while preserving membrane electrode assembly manufacturing compatibility. Developers target REACH-compliant supply chains for European deployment.
Alkaline systems absorb the bulk of installed capacity; solid oxide is expanding most quickly in integrated industrial applications.
End User:
Cost tier differentiation separates premium certified hydrogen from commodity-grade supply based on carbon intensity verification requirements.
- Industrial:Ammonia and steel producers constitute the dominant procurement segment, with German and Polish blast furnace replacement projects driving contracted offtake volumes under EU Carbon Border Adjustment Mechanism phase-in schedules.
- Transportation:Heavy-duty fuel cell vehicle fleets and aviation synthetic fuel projects require high-pressure hydrogen delivery. California and South Korean mobility hubs are establishing dedicated electrolyzer supply chains.
- Power Generation:Grid-scale storage and power-to-gas facilities utilize electrolyzers for seasonal energy shifting. Danish offshore wind corridors pair direct power contracts with hydrogen storage injection.
- Residential:Micro-scale systems for heating and vehicle refueling remain nascent, concentrated in Japanese demonstration programs under METI hydrogen town initiatives.
Industrial offtake commands the dominant revenue share; transportation applications are climbing the fastest as fuel cell truck and aviation commitments materialize.
Deployment:
Volume concentration in utility-scale projects is reshaping deployment architecture preferences toward centralized configurations with dedicated generation assets.
- Onshore:Fixed installations at industrial sites or renewable generation locations constitute the standard deployment model. German steel clusters and Chinese provincial hydrogen zones anchor this segment's order pipeline.
- Mobile:Containerized or trailer-mounted systems serve temporary industrial demand and remote construction sites. Mining operations in Australia and Canada deploy these for off-grid equipment refueling.
- Distributed:Small-scale units co-located with retail hydrogen dispensing target transportation corridors. California's highway network and German autobahn corridors host these configurations.
- Centralized:Gigawatt-class facilities with dedicated renewable generation and pipeline or maritime export infrastructure. Saudi Arabia's NEOM and planned North Sea hubs exemplify this architecture.
Onshore deployment retains the largest installed base; centralized configurations are gaining share fastest as export-oriented projects advance to final investment decision.
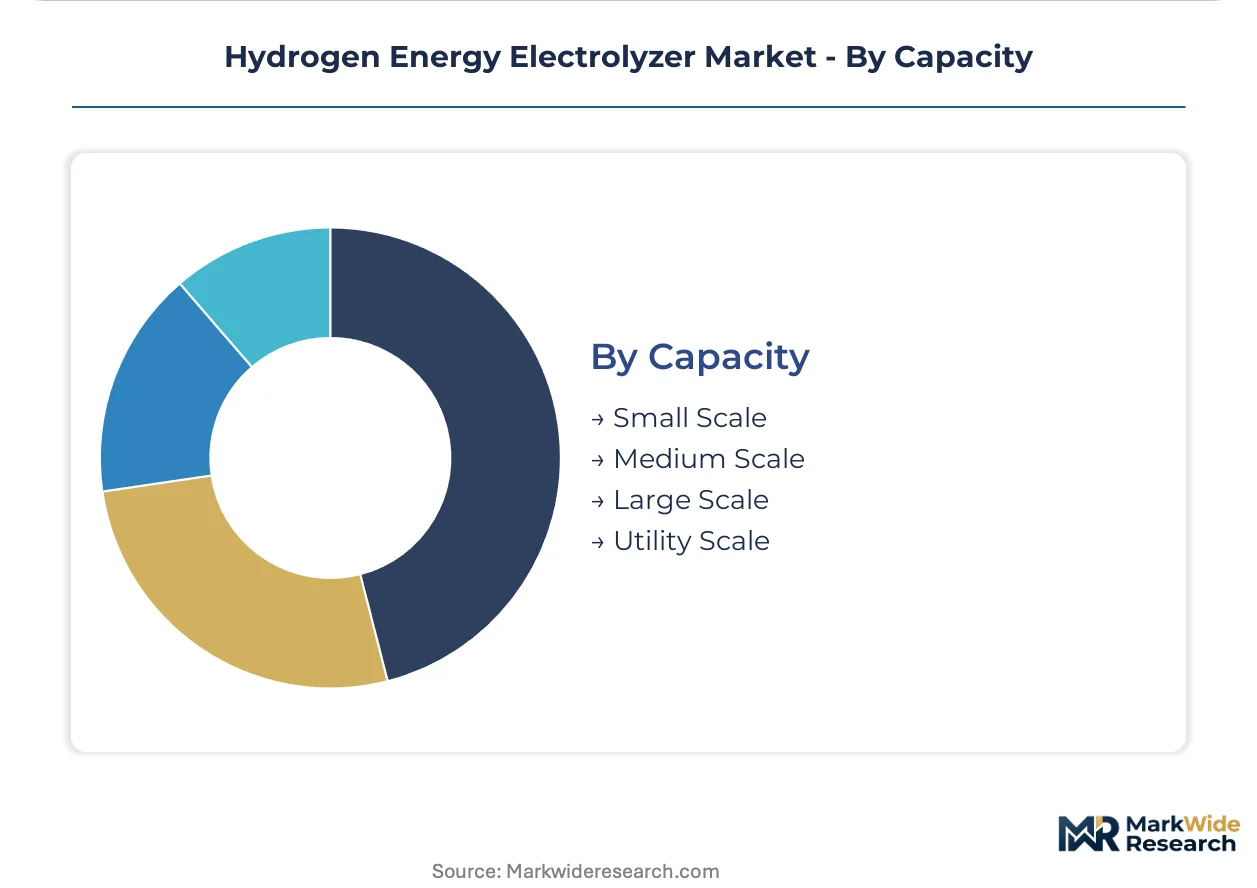
Capacity:
Customer type stratification separates project developers serving single offtakers from multi-contractor hub operators managing shared infrastructure.
- Small Scale:Systems below 10 MW serve pilot programs, research facilities, and distributed mobility applications. University and national laboratory procurement in the United States and Germany sustains this segment.
- Medium Scale:10-100 MW installations target single industrial offtakers with dedicated renewable power purchase agreements. German chemical sector projects and Chinese demonstration zone deployments concentrate here.
- Large Scale:100-500 MW systems serve integrated industrial complexes or regional hydrogen hub anchor tenants. thyssenkrupp nucera and Siemens Energy compete for European steel and ammonia sector tenders in this range.
- Utility Scale:Configurations exceeding 500 MW pair with gigawatt-class renewable generation for export or multi-sector supply. Saudi NEOM, Australian renewable export projects, and planned North Sea corridors define this segment.
Medium scale absorbs the dominant share of current manufacturing output; utility scale is expanding most rapidly as project finance structures mature for gigawatt-class developments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German steel clusters and Chinese provincial hydrogen zones absorb the dominant share of electrolyzer procurement, while Saudi Arabia's NEOM project and U.S. Gulf Coast developments reshape manufacturing capacity location decisions.
Germany
Ruhr Valley steel decarbonization and North Sea offshore wind pairing drive electrolyzer demand. The EU Green Deal's delegated acts under the Renewable Energy Directive mandate renewable hydrogen certification thresholds. Hamburg and Bremen industrial clusters host thyssenkrupp nucera and Siemens Energy assembly operations serving blast furnace replacement projects.
China
Provincial demonstration zones in Inner Mongolia and Xinjiang concentrate alkaline system deployment for ammonia and methanol feedstock. MIIT and NDRC coordination of dual carbon goals channels manufacturing subsidies toward designated hydrogen hubs. Ningxia and Shandong provinces anchor gigawatt-scale manufacturing footprints for domestic and export supply.
United States
Texas and Louisiana Gulf Coast petrochemical complexes seek electrolyzer-derived hydrogen for refinery and ammonia applications. The Department of Energy and IRS administer Inflation Reduction Act production tax credits that restructure project finance for domestic installations. Houston and Corpus Christi industrial corridors attract developer final investment decisions for integrated renewable hydrogen facilities.
Saudi Arabia
NEOM gigaproject renewable hydrogen export ambitions create concentrated demand for high-capacity alkaline systems. The kingdom's sovereign wealth fund and ACWA Power coordinate dedicated solar and wind generation pairing. Tabuk Province hosts the world's largest integrated green hydrogen facility under construction.
Netherlands
Port of Rotterdam chemical sector demand and North Sea offshore wind direct power contracts reshape deployment economics. ECHA REACH regulation amendments on fluorinated polymer restrictions compel membrane manufacturer reformulation timelines. Eemshaven and Maasvlakte industrial zones pilot solid oxide electrolyzer integration with ethylene cracker waste heat recovery.
Hydrogen Energy Electrolyzer Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers race to capture utility-scale order pipelines. The vendor base separates into integrated industrial conglomerates with captive energy expertise, pure-play electrolyzer specialists controlling stack manufacturing depth, and diversified power equipment suppliers leveraging electrical system integration capabilities. Strategic archetypes include alkaline-focused scale players, PEM-oriented premium technology providers, and emerging solid oxide high-temperature specialists. Geographic expansion and technology licensing represent the dominant competitive moves as firms seek regulatory-compliant manufacturing footprints across EU, U.S., and Middle Eastern jurisdictions.
Among European-based integrated suppliers, Nel ASA and Siemens Energy occupy positions spanning stack production through system assembly, while thyssenkrupp nucera anchors the high-capacity alkaline segment for chemical and steel sector offtakers. Chinese manufacturers including LONGi exemplify the scale-driven archetype targeting provincial demonstration zone procurement. U.S.-listed Plug Power Inc. and Cummins Inc. represent diversified industrial players extending power equipment portfolios into electrolyzer integration. These named entities serve as reference points for understanding how competitive positioning fragments across technology classes and geographic regulatory environments.
| Leading Market Players |
|---|
| Nel ASA |
| Plug Power Inc. |
| ITM Power plc |
| Siemens Energy |
| thyssenkrupp nucera |
| Cummins Inc. |
| McPhy Energy |
| LONGi |
| John Cockerill |
| Others |
Pricing and Supply Chain Analysis
PEM stack redesigns toward platinum-heavy catalyst configurations are simultaneously compressing manufacturing costs and redrawing procurement geography as iridium supply concentration forces alternative sourcing strategies across European and North American assembly operations.
Pricing Analysis
High-volume alkaline contracts trade margin for market share while PEM systems retain premium positioning through certification-grade hydrogen output. Three-tier pricing structure across certified renewable, grid-connected, and industrial-grade supply separates EU Green Deal-compliant installations from standard configurations. Cost compression in utility-scale tenders is intensifying as Chinese manufacturers absorb provincial demonstration zone procurement. Ammonia and steel sector offtakers exhibit highest price sensitivity; mobility and export-oriented projects show lowest.
Supply Chain Analysis
Specialized membrane electrode assembly technicians in Norway and Germany remain outstripped by vocational training pipeline output, constraining stack production scaling. Manufacturing concentrates in China, Germany, and Norway for system assembly, with South Africa and Russia anchoring platinum-group metal extraction. Electrolyzer production draws from fluorinated polymer membranes, nickel-based electrodes, and high-purity titanium components. Single-source vulnerability in iridium procurement forces reformulation timelines. Distribution runs through EPC contractors serving industrial cluster developments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is consolidating around manufacturers with captive stack production capabilities as iridium supply disruption eliminates pure-play assemblers without catalyst coating depth.
For Market Incumbents: Anticipate margin compression from Chinese alkaline imports by deepening backward integration into membrane manufacturing and securing long-term platinum supply agreements with South African mining consortiums. Prioritize REACH-compliant fluoropolymer alternatives ahead of ECHA reformulation deadlines to defend European market access against emerging anion exchange membrane specialists. For New Entrants and Emerging Players: The Inflation Reduction Act in the United States opens a window for domestic PEM assembly operations serving Texas and Louisiana Gulf Coast petrochemical demand. Target solid oxide integration with ethylene cracker waste heat recovery in Netherlands chemical corridors. Pursue technology licensing partnerships with established stack manufacturers rather than greenfield production investment. For Investors and Strategic Acquirers: Re-rating potential sits with alkaline-focused scale players given Saudi NEOM and Australian export project final investment decisions accelerating through the analysis window. Favor manufacturers with demonstrated utility-scale EPC execution and contracted offtake coverage ratios above hub threshold levels. Monitor EU delegated act carbon intensity threshold finalization as inflection indicator for European deployment qualification.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Catalyst Coating | Nel ASA's Norwegian manufacturing footprint controls membrane electrode assembly quality and insulates against iridium supply disruption. |
| Utility-Scale Capacity Buildout | thyssenkrupp nucera's high-capacity alkaline systems capture German steel sector decarbonization mandates under EU Carbon Border Adjustment Mechanism phase-in. |
| Green Certification Program | EU Green Deal delegated acts establish product-level renewable hydrogen criteria conditioning market access for European deployments. |
| Technology Licensing Agreement | Siemens Energy's PEM platform licensing expands manufacturing footprint across U.S. and Middle Eastern regulatory jurisdictions. |
| Long-term Supply Agreement | 10-15 year take-or-pay contracts with ammonia producers transfer volume risk and anchor project finance for gigawatt-class developments. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this electrolyzer market analysis. Primary interviews with EPC contractors, utility planning officers, and chemical sector procurement leads combined with hydrogen hub development databases and IEA technology roadmaps. Bottom-up manufacturing capacity tallies triangulated against top-down renewable hydrogen demand projections from national hydrogen strategies.
Data-stream reconciliation across technology class, deployment scale, and end-use industry segmentation generated volume and value outputs over the projection horizon. CAGRs derived from electrolyzer system cost curves, renewable power purchase agreement pricing trends, and industrial offtake contract tenor evolution. Modeled inputs included IRA production tax credit qualification thresholds and EU additionality requirement implementation timelines.
Caveats apply where iridium supply disruption, delegated act carbon intensity threshold revisions, or grid interconnection queue delays could materially shift the outlook. Forecasts reflect assumptions around renewable power cost trajectories and industrial decarbonization mandate enforcement schedules. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydrogen Energy
Hydrogen for Mobility Market
Hydrogen Energy
Hydrogen Generation Market
Hydrogen Energy
Photovoltaic Hydrogen Production Market
Hydrogen Energy
Hydrogen Liquefaction Unit Market
Hydrogen Energy
Gray Hydrogen Market
Hydrogen Energy
Hydrogen-Cooled Turbine Generator Market
Hydrogen Energy
Hydrogen Recovery Market
Hydrogen Energy
Hydrogen Tanks Market
Hydrogen Energy
Clean Hydrogen Market
Hydrogen Energy
US Hydrogen Fueling Station Market
Hydrogen Energy
Water Electrolysis Green Hydrogen Production Market
Hydrogen Energy
Hydrogen ICE Ignition System Platforms Market
Hydrogen Energy
Hydrogen Composite Tanks Market
Hydrogen Energy
PEM Water Electrolytic Hydrogen Production System Market
Hydrogen Energy
Green Hydrogen Dispensing Equipment Market
Hydrogen Energy
North America Liquid Hydrogen Market