
 Hydrogen Storage Technology Market | 2026-2036
Hydrogen Storage Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogen Storage Technology Market Insights
Germany's hydrogen corridor build-out is tilting European storage demand toward high-pressure and liquid systems. Linde leverages its cryogenic infrastructure across the Rhine-Ruhr industrial belt. Air Liquide anchors large-scale liquid hydrogen supply chains in Northern Europe. Chart Industries competes on modular tank fabrication for distributed refueling stations.
Hydrogen storage technology encompasses physical and material-based systems engineered to contain hydrogen at densities enabling practical transport and end-use, typically requiring pressures exceeding 350 bar for compressed gas or temperatures below minus 253 degrees Celsius for liquid states. Compressed gas and liquid storage categories currently lead installed capacity, while metal hydrides command premium margins in portable and stationary applications where volumetric efficiency outweighs capital cost sensitivity. Fuel cell vehicles and energy storage systems represent the fastest-growing application clusters, with industrial use remaining the volume anchor due to ammonia and refining demand.
The EU F-Gas Regulation and CE marking frameworks govern equipment certification across member states, while Germany's KBA enforces transport safety standards for onboard vehicle tanks. The US Department of Energy and Japan's METI coordinate hydrogen hub funding that directly shapes procurement scale and technology selection criteria. Stakeholders must track evolving interoperability standards between storage systems and refueling infrastructure before committing to platform-specific designs.
Market Dynamics
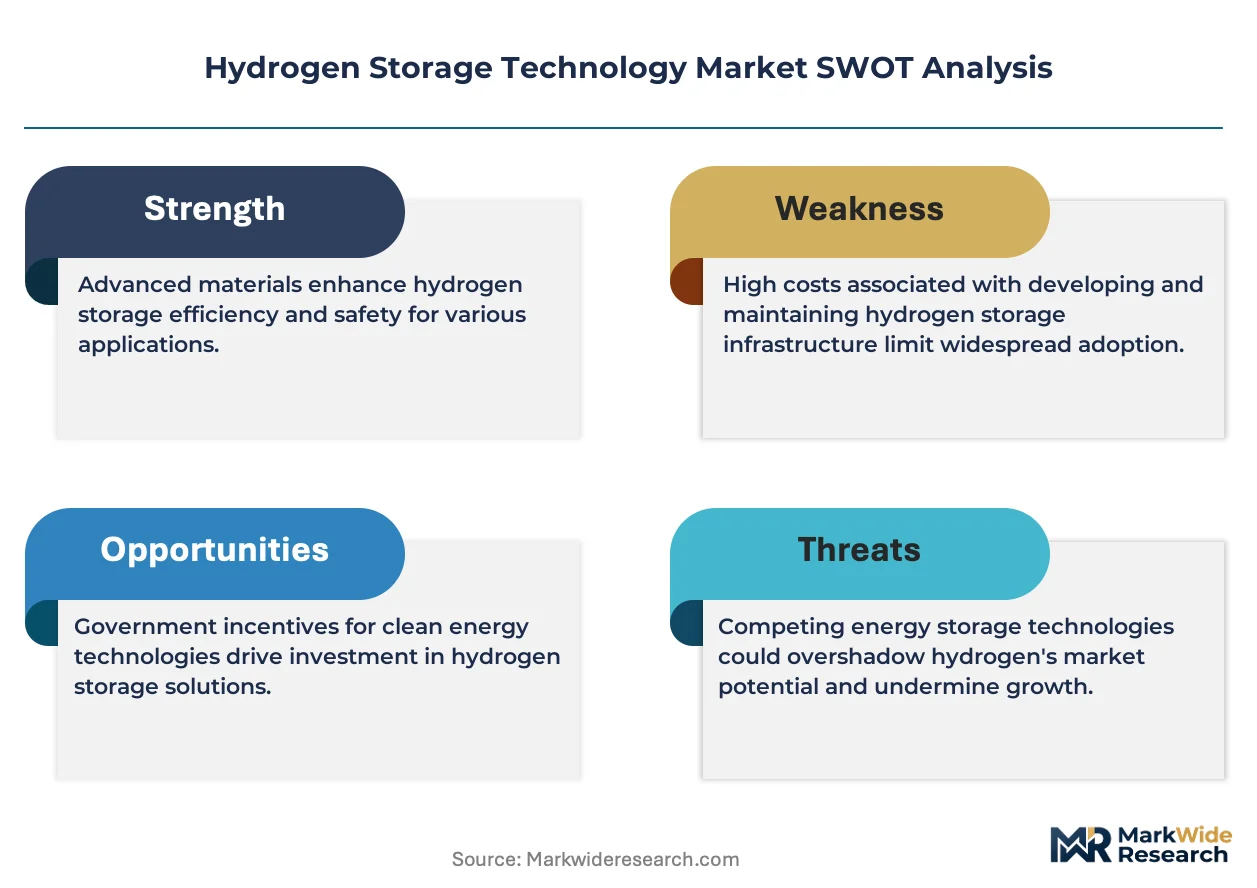
Industrial decarbonization mandates in Germany's steel and ammonia clusters are compressing project timelines for hydrogen storage infrastructure, forcing technology selection toward liquid and high-pressure systems that can integrate with existing pipeline networks.
Growth Catalysts
- EU Hydrogen Strategy:Binding infrastructure targets under REPowerEU accelerate storage procurement for import terminals and industrial hubs across member states.
- Fuel cell vehicle fleets:Japan and South Korea are expanding storage contracts for heavy-duty trucking and bus networks, creating demand for high-pressure composite tanks.
- Metal hydride R&D:Stationary applications in residential and backup power systems command premium margins where volumetric density outweighs capital cost sensitivity.
Market Restraints
- Liquefaction energy penalty:Cryogenic storage consumes 30-40% of hydrogen energy content, constraining economics for distributed applications.
- Nickel and rare earth supply:Metal hydride production depends on concentrated mining operations in Indonesia and the Democratic Republic of Congo.
- CE marking complexity:Pressure Equipment Directive compliance creates 12-18 month certification timelines for novel tank designs.
Strategic Opportunities
- Underpenetrated maritime sector:Ammonia-powered shipping in Northern Europe requires novel bulk storage solutions at port refueling hubs.
- US Inflation Reduction Act:Production tax credits for clean hydrogen indirectly subsidize storage infrastructure co-located with production facilities.
- AI-enabled predictive maintenance:Sensor integration with tank monitoring systems reduces inspection downtime for fleet operators.
Industry Challenges
- Cryogenic engineering talent:Specialized welding and insulation expertise for liquid hydrogen systems remains concentrated at a handful of European and Japanese suppliers.
- Interoperability gaps:Refueling nozzle standards differ between SAE protocols in North America and ISO specifications in Europe, complicating cross-border vehicle deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogen Storage Technology Market |
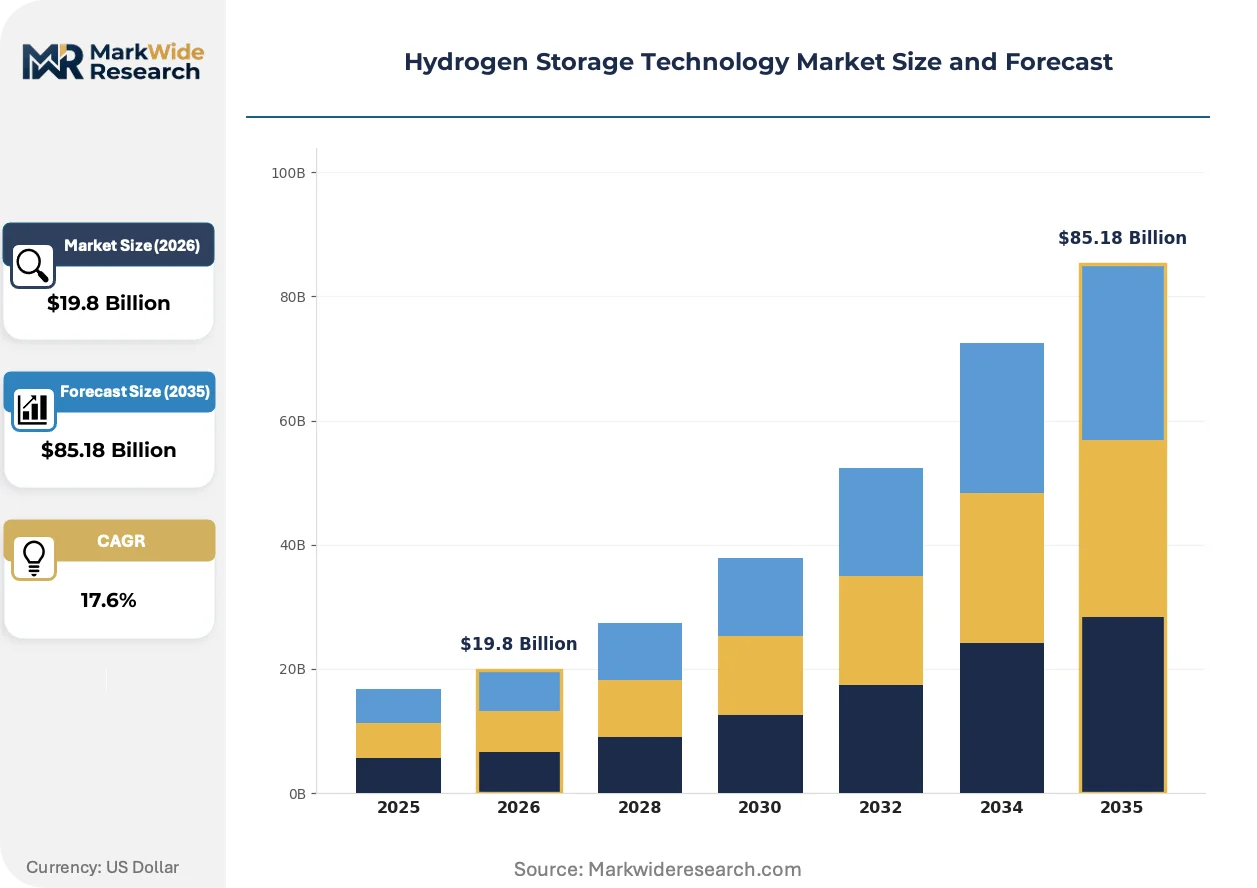
| Market Size in 2026 | $19.8 Billion |
| Market Size in 2035 | $85.18 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Storage Type: Compressed Gas, Liquid Storage, Metal Hydrides, Chemical Hydrides Application: Fuel Cell Vehicles, Energy Storage Systems, Industrial Use, Residential Heating Technology: High-Pressure Tanks, Cryogenic Systems, Adsorption Systems, Integrated Systems End User: Transportation, Power Generation, Industrial Manufacturing, Research Institutions |
| Companies Covered | Linde, Air Liquide, Chart Industries, Luxfer Holdings, Worthington Industries, Hexagon Composites, McPhy Energy, GKN Hydrogen, Hydrogenious Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogen Storage Technology Market Trends and Innovations
Storage technology trajectories are diverging between industrial-scale liquid systems and distributed high-pressure networks, with material science breakthroughs enabling intermediate solutions that challenge traditional cost-performance tradeoffs.
Composite pressure vessels are migrating from 350-bar to 700-bar ratings for heavy-duty fuel cell trucks. Fleet operators in California and Germany specify the higher pressure to extend vehicle range without additional tank volume. This migration from lower-pressure designs is compressing the addressable market for aluminum-lined cylinders in long-haul applications.
Germany's KBA and the EU Pressure Equipment Directive are tightening inspection intervals for onboard vehicle tanks. Manufacturers must now submit fatigue testing data across 15,000 fill cycles rather than 10,000. Japanese suppliers with established 700-bar certification pipelines are capturing early procurement contracts for European bus fleets.
Industrial offtake agreements now specify storage-as-a-service terms rather than capital purchase. Ammonia producers in the Netherlands and steelmakers in Sweden lease tank capacity from Linde and Air Liquide under 10-year contracts with embedded maintenance. This shift transfers operational risk to infrastructure owners while locking in offtake volumes for project finance.
Hydrogen Storage Technology Market Segmentation
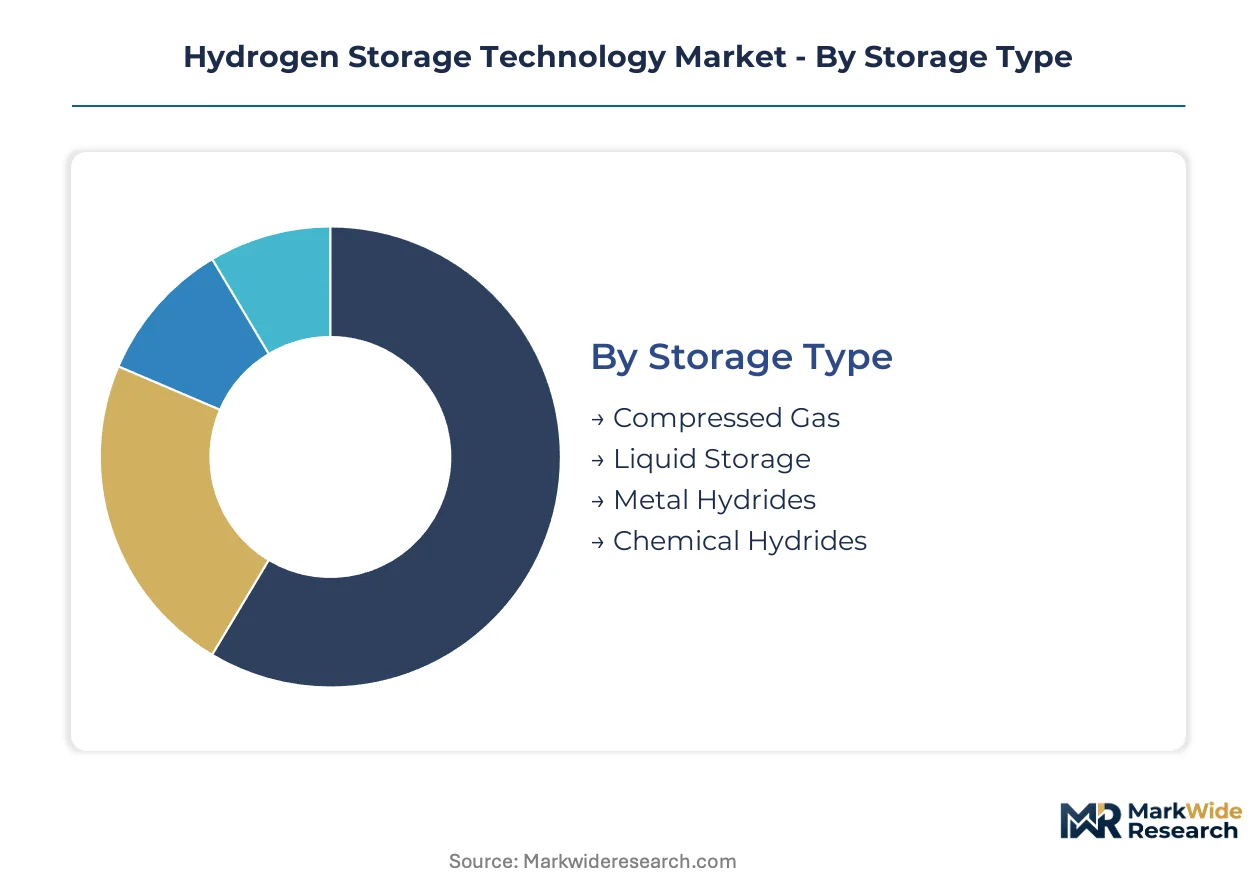
Technology selection in hydrogen storage hinges on pressure-temperature tradeoffs, volumetric density requirements, and integration complexity with downstream applications. Each segment carries distinct service intensity profiles, from cryogenic system maintenance to hydride material regeneration cycles.
Storage Type:
After-sales service intensity varies dramatically across physical containment methods, with cryogenic systems demanding continuous monitoring and hydrides requiring periodic material replacement.
- Liquid Storage:Cryogenic containment at minus 253 degrees Celsius enables the highest volumetric density for long-haul transport and industrial terminals. Demand concentrates at Germany's Rhine-Ruhr ammonia hubs and Japan's import terminals, where liquefaction infrastructure justifies the 30-40% energy penalty through scale economies.
- Compressed Gas:High-pressure vessels operating at 350-700 bar dominate fuel cell vehicle fleets and distributed refueling networks. Fleet operators in California and South Korea specify 700-bar ratings to extend heavy-duty truck range without additional tank volume.
- Metal Hydrides:Solid-state absorption systems command premium pricing in portable and backup power applications where safety outweighs capital cost sensitivity.
- Chemical Hydrides:Liquid organic hydrogen carrier systems enable ambient-temperature transport with catalytic release at point of use.
Liquid storage holds the largest share; momentum sits with compressed gas as 700-bar certification pipelines mature.
Application:
Cost tier stratification separates industrial volume contracts from premium mobile applications where weight and space constraints dominate procurement criteria.
- Industrial Use:Ammonia synthesis and steel decarbonization anchor demand volume, with German steelmakers and Dutch chemical producers contracting storage-as-a-service under 10-year lease structures.
- Fuel Cell Vehicles:Heavy-duty trucking and bus networks in Japan and South Korea drive specifications for lightweight composite tanks with 15,000-cycle fatigue ratings.
- Energy Storage Systems:Grid-scale buffering and renewable integration projects favor large-scale liquid or underground cavern storage.
- Residential Heating:Pilot programs in Northern Europe test metal hydride units for seasonal storage in district heating networks.
Industrial use captures the largest revenue pool; fuel cell vehicles are climbing the fastest as fleet deployment accelerates.
Technology:
Supply concentration in cryogenic engineering talent—particularly specialized welding and insulation expertise—shapes competitive dynamics for liquid system deployment.
- Cryogenic Systems:Vacuum-insulated double-wall tanks with multi-layer insulation demand precision manufacturing concentrated among European and Japanese suppliers. Air Liquide anchors large-scale deployment across Northern European import terminals.
- High-Pressure Tanks:Type III aluminum-lined and Type IV all-composite vessels migrate toward 700-bar ratings as KBA and EU Pressure Equipment Directive standards tighten.
- Adsorption Systems:Carbon-based and MOF materials remain pre-commercial for most applications.
- Integrated Systems:Combined compression-liquefaction-storage units serve distributed production sites.
High-pressure tanks dominate unit volume; cryogenic systems command the highest project values per installation.
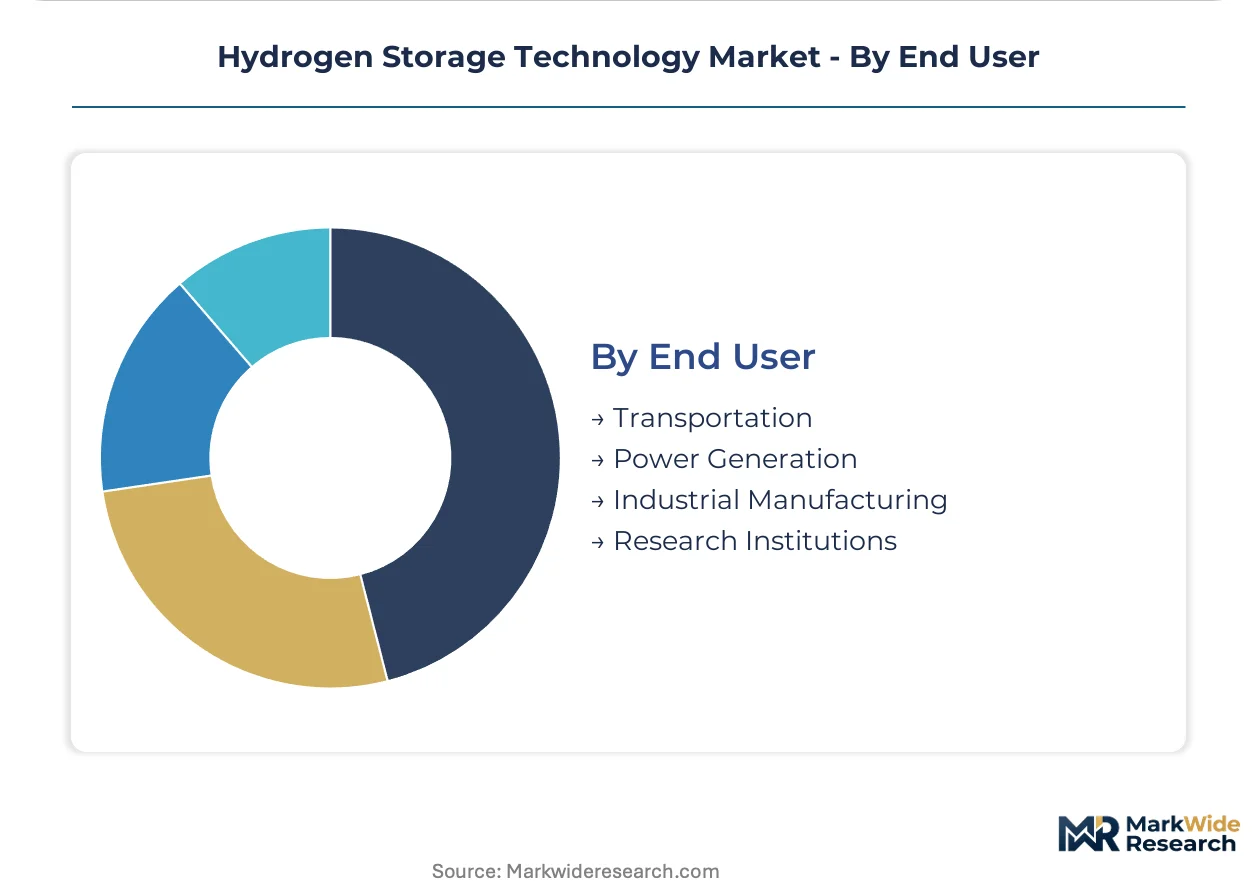
End User:
Customer type determines contract structure, with industrial manufacturers favoring long-term service agreements and transportation operators prioritizing rapid tank exchange and predictive maintenance.
- Transportation:Fuel cell bus and truck fleets specify standardized tank interfaces to enable cross-operator refueling compatibility. CE marking complexity creates 12-18 month certification timelines for novel designs.
- Industrial Manufacturing:Steel, ammonia, and refining operations drive demand for bulk liquid storage with pipeline integration.
- Power Generation:Utility-scale hydrogen peaking plants and gas turbine blending projects require high-volume, fast-cycling storage.
- Research Institutions:National laboratories and university consortia test novel materials and system architectures.
Industrial manufacturing holds the largest share; transportation is gaining share fastest as fleet procurement scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan consumes hydrogen storage technology through fuel cell vehicle fleets and import terminals, while Germany drives demand through industrial decarbonization clusters, and the United States splits procurement between California mobility projects and Gulf Coast ammonia hubs.
Germany
Rhine-Ruhr steel decarbonization and Hamburg ammonia import terminals anchor storage demand. KBA enforces 15,000-cycle fatigue ratings for onboard vehicle tanks under tightened transport safety standards. North Rhine-Westphalia hosts Linde's cryogenic infrastructure serving BASF and ThyssenKrupp hydrogen offtake contracts.
Japan
Fuel cell bus fleets in Tokyo and Osaka prefectures specify 700-bar composite tanks for extended range. METI coordinates hydrogen hub funding that shapes procurement scale for heavy-duty trucking networks. Kanto region import terminals deploy liquid storage systems for power generation and industrial feedstock supply.
United States
California Air Resources Board mandates drive fleet procurement for 700-bar tank systems in long-haul trucking. IRA production tax credits subsidize storage infrastructure co-located with Gulf Coast clean hydrogen facilities. Texas and Louisiana ammonia producers contract bulk liquid storage with pipeline integration to refining complexes.
South Korea
Ulsan and Busan metropolitan areas expand fuel cell bus and truck deployment requiring high-pressure tank certification. Ministry of Trade, Industry and Energy funds hydrogen station build-out with standardized tank interfaces. Gyeonggi Province industrial parks test metal hydride systems for stationary backup power applications.
Netherlands
Rotterdam port ammonia bunkering infrastructure demands novel bulk storage solutions for maritime refueling. EU F-Gas Regulation governs pressure equipment certification for import terminal installations. Chemelot industrial cluster in Limburg contracts storage-as-a-service for green ammonia export production.
Hydrogen Storage Technology Market Competitive Landscape
Capability concentration sits with cryogenic engineering specialists; scale advantage sits with diversified industrial gas incumbents. The market structures around three tiers: integrated gas majors with liquefaction infrastructure, composite vessel fabricators serving mobility applications, and solid-state material developers targeting niche stationary deployments. Dominant competitive moves include strategic partnerships for hub development and technology licensing for 700-bar certification pipelines.
Within the industrial gas tier, Linde and Air Liquide occupy positions as anchors of large-scale liquid hydrogen supply chains across Northern European import terminals. Chart Industries exemplifies the specialized fabricator archetype, competing on modular tank systems for distributed refueling networks. Hexagon Composites represents the composite pressure vessel segment focused on mobility applications.
| Leading Market Players |
|---|
| Linde |
| Air Liquide |
| Chart Industries |
| Luxfer Holdings |
| Worthington Industries |
| Hexagon Composites |
| McPhy Energy |
| GKN Hydrogen |
| Hydrogenious Technologies |
| Others |
Pricing and Supply Chain Analysis
Rhine-Ruhr corridor freight costs compress margins for liquid hydrogen tank deliveries from Northern European fabricators to German industrial clusters, concentrating pricing power with cryogenic engineering specialists while forcing downstream buyers into long-term offtake structures that lock in volume commitments against spot market volatility.
Pricing Analysis
Long-term offtake contracts dominate procurement for industrial-scale liquid storage, with ammonia producers and steelmakers leasing capacity under 10-year agreements that embed maintenance and certification costs. Price differentiation stems from CE marking tier and volume scale, with 700-bar composite tanks commanding premiums over 350-bar aluminum-lined alternatives. Cost compression in compressed gas systems intensifies as fleet operators standardize on higher-pressure ratings. Transportation operators exhibit highest price sensitivity due to thin fleet margins, while industrial manufacturers accept premium pricing for guaranteed supply security.
Supply Chain Analysis
High-purity nickel feedstock for metal hydride production concentrates in Indonesian mining operations and Democratic Republic of Congo rare earth processing. Composite pressure vessel manufacturing draws from Japanese carbon fiber suppliers and German resin formulators. Single-source vulnerability runs through cryogenic insulation material providers concentrated in Europe and Japan. Distribution runs through Linde and Air Liquide hub-and-spoke networks serving Rhine-Ruhr and Northern European import terminals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hydrogen storage technology sits in early-cycle expansion as EU REPowerEU infrastructure mandates accelerate procurement timelines for import terminals and industrial decarbonization hubs.
For Market Incumbents: Insulate cryogenic engineering talent pools through captive training programs and exclusive supplier agreements with specialized welding contractors. Deepen backward integration into carbon fiber preform manufacturing to offset Japanese supplier pricing leverage. Lock in 15,000-cycle certification pipelines ahead of KBA and EU Pressure Equipment Directive enforcement timelines.
For New Entrants and Emerging Players: Maritime ammonia bunkering infrastructure at Rotterdam and Hamburg ports represents the most penetrable entry point for novel bulk storage solutions, with port authorities soliciting non-incumbent bids for 2025-2026 terminal build-outs. Metal hydride residential heating pilots in Northern European district networks offer second-mover positioning behind established industrial gas suppliers. Lead with predictive maintenance software bundles to differentiate against hardware-centric incumbents.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors cryogenic system fabricators with demonstrated 700-bar certification pipelines and existing relationships with KBA or METI regulators. Long-term viability hinges on exposure to industrial offtake rather than mobility applications given fleet deployment uncertainty. Monitor EU Hydrogen Strategy funding disbursement velocity as inflection indicator for storage procurement acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout | Linde's cryogenic infrastructure expansion across Rhine-Ruhr secures BASF and ThyssenKrupp offtake contracts. |
| Backward Integration | Air Liquide's captive liquefaction capacity insulates margins from third-party hydrogen supply volatility. |
| Technology Licensing | Japanese 700-bar certification pipelines license to European fabricators under KBA compliance timelines. |
| Long-term Supply Agreement | Dutch ammonia producers contract storage-as-a-service with embedded maintenance under 10-year structures. |
| Joint Venture | Chart Industries partners with port authorities on modular tank systems for distributed refueling networks. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EIA hydrogen hub disclosures, EU REPowerEU funding databases, and METI procurement announcements. Primary interviews engaged cryogenic system engineers, fleet procurement managers at fuel cell vehicle operators, and industrial gas contract specialists. Secondary validation drew from KBA transport safety filings, EU Pressure Equipment Directive guidance documents, and SEC 10-K disclosures from listed industrial gas majors. Bottom-up project pipeline aggregation triangulates against top-down infrastructure spending forecasts.
Forecast inputs include hydrogen demand trajectories from ammonia synthesis and steel decarbonization clusters, fuel cell vehicle fleet deployment schedules, and regulatory funding allocation velocities across the analysis window. Segmentation models disaggregate by storage type, application tier, pressure rating, and regional regulatory framework. CAGRs derive from installed capacity build-out curves and unit economics evolution for liquid versus compressed gas systems. Cryogenic engineering labor availability and nickel supply constraints feed as boundary conditions.
Practitioners should monitor EU Hydrogen Strategy disbursement delays, KBA certification timeline extensions, and nickel export restriction announcements from Indonesian regulators for early signals of forecast revision. Cross-checking against IEA hydrogen project tracking databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydrogen Energy
Hydrogen-Cooled Turbine Generator Market
Hydrogen Energy
Green Hydrogen Storage Technology Market
Hydrogen Energy
Asia Pacific Liquid Hydrogen Market
Hydrogen Energy
Europe Hydrogen Generation Market
Hydrogen Energy
Hydrogen Production Electrolyser Market
Hydrogen Energy
Global Hydrogen Electrolyzers Market
Hydrogen Energy
Hydrogen Station Market
Hydrogen Energy
Brown Hydrogen Market
Hydrogen Energy
Hydrogen Powered Engine Market
Hydrogen Energy
Clean Hydrogen Market
Hydrogen Energy
Asia-Pacific Clean Hydrogen Market
Hydrogen Energy
Alkaline Water Electrolysis Market
Hydrogen Energy
North America Liquid Hydrogen Market
Hydrogen Energy
Hydrogen Purification Units Market
Hydrogen Energy
Hydrogen Liquefaction Unit Market
Hydrogen Energy
35MPa High Pressure Hydrogen Storage Cylinders Market