
 United States Hydrogen Generation Market | 2026-2036
United States Hydrogen Generation Market Size, Share, and Industry Trends Forecast 2026-2036
United States Hydrogen Generation Market Analytics
Capital-intensity divergence between electrolyzer manufacturers and fossil-based producers is reorganizing competitive hierarchy in domestic hydrogen supply. Plug Power Inc. leverages vertical integration into electrolyzer stack manufacturing to control cost curves. Linde Plc sustains geographic dominance through its Gulf Coast hydrogen pipeline network. Air Products and Chemicals Inc. anchors its position via large-scale steam methane reforming assets serving ammonia and refining customers.
United States hydrogen generation encompasses the production of hydrogen gas through thermal, electrochemical, or biological processes, with purity grades ranging from industrial (95-99%) to fuel-cell (99.97%+) specifications, primarily serving decarbonization mandates in transport, chemicals, and heavy industry. Steam methane reforming currently dominates output volumes due to established infrastructure and lower unit costs, while electrolysis represents the fastest-expanding technology segment as renewable power purchase agreements reshape production economics. Green hydrogen, produced via electrolysis powered by zero-carbon electricity, commands premium positioning in offtake contracts from transportation and power generation end users seeking Scope 3 emissions reductions.
The Department of Energy's Hydrogen and Fuel Cell Technologies Office coordinates national laboratory research funding, while EPA tailpipe standards and IRA tax credits directly shape demand velocity for clean hydrogen alternatives. OSHA process safety management rules govern reforming facility operations, influencing capital deployment timelines for brownfield expansions versus greenfield electrolyzer projects. Stakeholders must monitor state-level renewable portfolio standards and regional clean hydrogen hub selections to anticipate offtake concentration and infrastructure buildout sequencing.
Market Dynamics
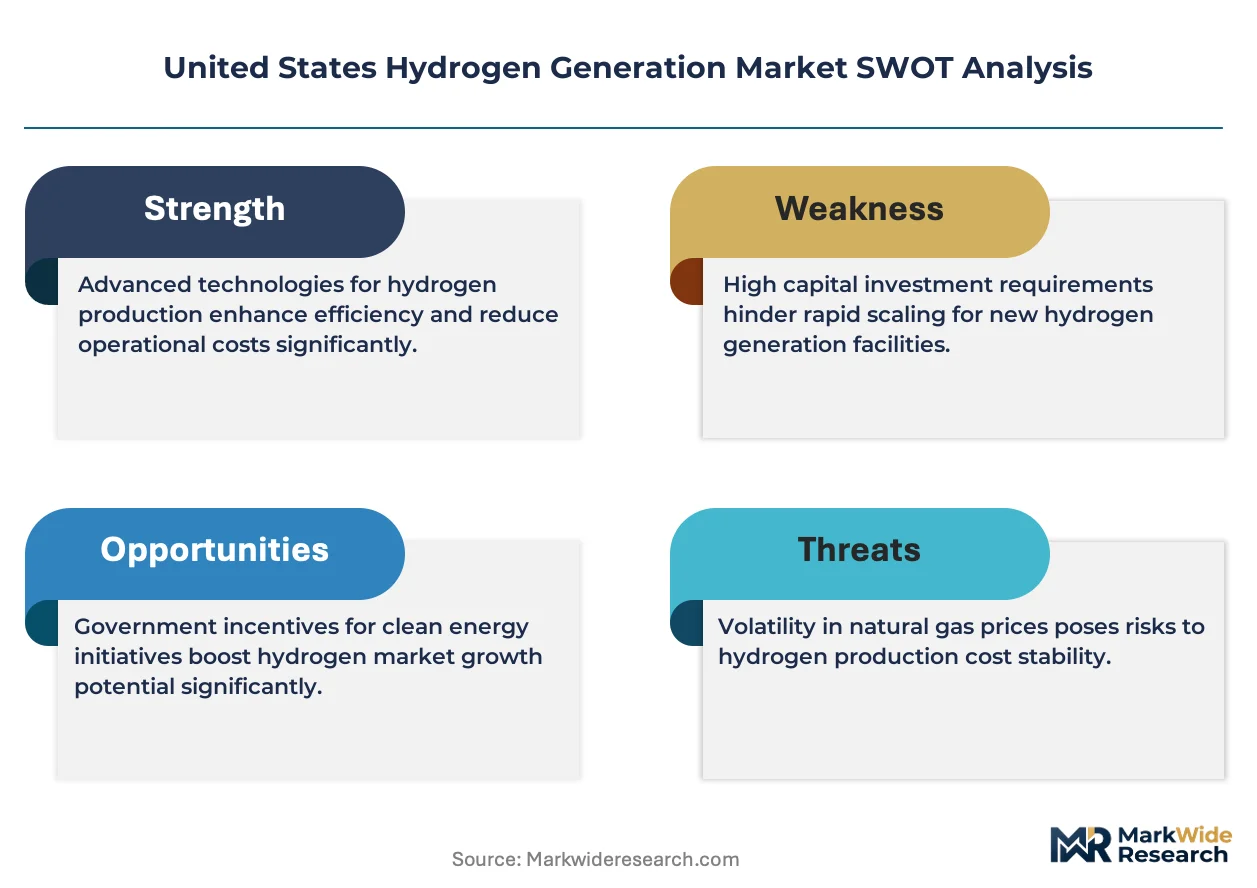
The Inflation Reduction Act's hydrogen production tax credits are compressing project payback periods and rerouting capital toward electrolyzer deployments over steam methane reforming expansions. This policy lever is accelerating technology substitution timelines that infrastructure inertia had previously delayed.
Growth Catalysts
- Clean Hydrogen Production Tax Credits:The IRA's tiered credit structure rewards projects achieving lifecycle carbon intensity below specified thresholds, pulling capital toward renewable-powered electrolysis in Texas and California.
- Heavy-Duty Fleet Electrification Mandates:California's Advanced Clean Trucks regulation and EPA tailpipe standards are creating guaranteed offtake volumes for fuel-cell truck operators seeking zero-emission compliance pathways.
- Gulf Coast Hydrogen Pipeline Network:Existing infrastructure concentration along the Texas-Louisiana corridor enables rapid scaling of blue hydrogen production with carbon capture integration.
Market Restraints
- Electrolyzer Stack Cost Structure:Proton exchange membrane systems require iridium and platinum group metal catalysts subject to supply concentration in South African and Russian mining operations.
- Renewable Power Purchase Agreement Volatility:Intermittency in wind and solar output forces electrolyzer operators to either oversize generation assets or accept reduced capacity utilization rates.
- Fossil-Based Hydrogen Price Anchoring:Steam methane reforming with unabated emissions maintains a production cost floor that compresses green hydrogen pricing power in industrial ammonia and refining offtake.
Strategic Opportunities
- Regional Clean Hydrogen Hub Designations:The Department of Energy's hub selection process is concentrating federal funding across seven geographic clusters, with Gulf Coast and Midwest networks positioned for ammonia export integration.
- Steel Sector Decarbonization Contracts:Electric arc furnace operators in the Ohio River Valley are piloting hydrogen direct reduction processes, creating new demand verticals beyond transport and chemicals.
- Power-to-X Fuel Synthesis Convergence:Integration of electrolysis with Fischer-Tropsch synthesis and methanol production is enabling e-fuel output for aviation offtake from California and Washington state projects.
Industry Challenges
- Electrolyzer Manufacturing Skill Shortages:Specialized welding and membrane coating expertise required for stack assembly remains concentrated in European and Japanese supplier workforces, constraining domestic production scaling.
- OSHA Process Safety Management Compliance:Reforming facility expansions face extended permitting timelines under 29 CFR 1910.119 requirements for highly hazardous chemicals, disadvantaging brownfield projects against greenfield electrolyzer sites with simpler safety profiles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Hydrogen Generation Market |
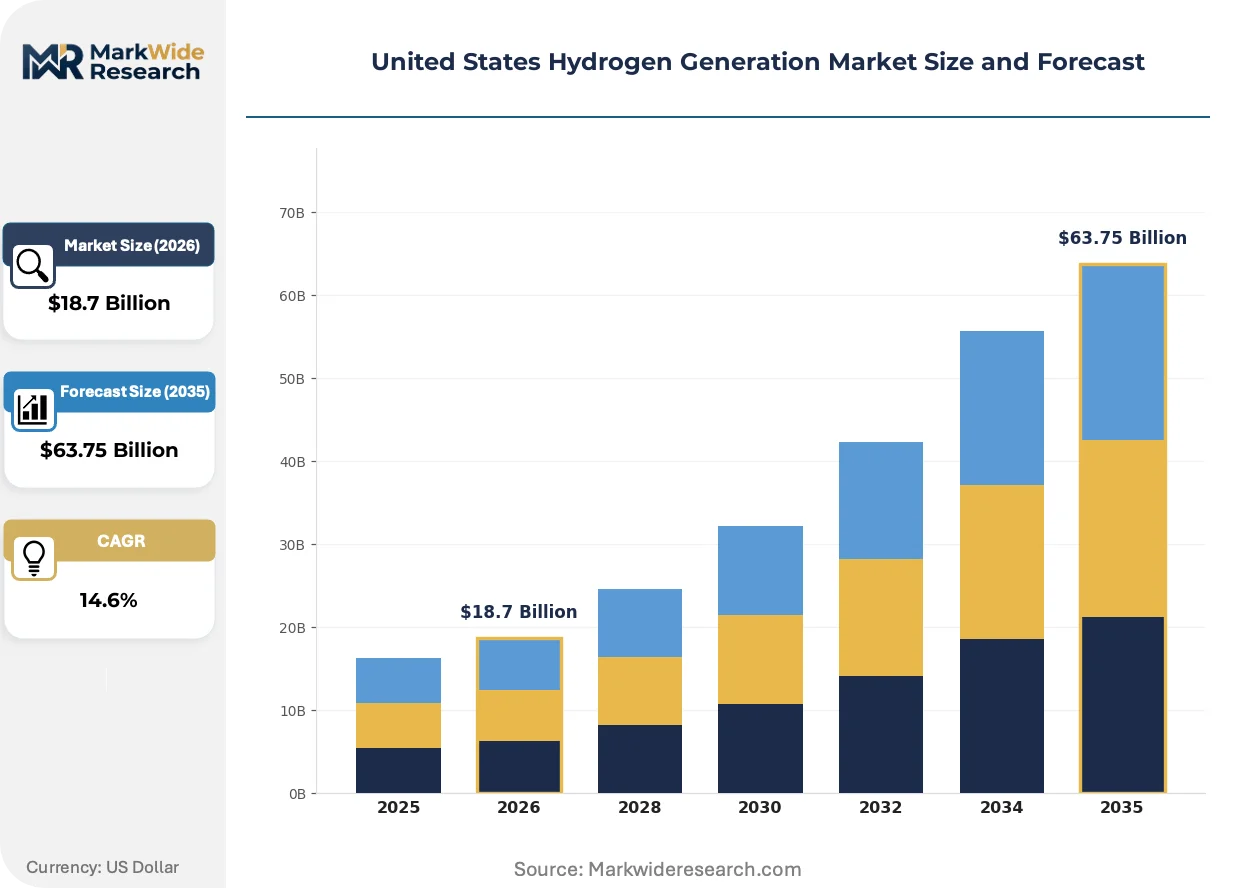
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $63.75 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Electrolysis, Steam Methane Reforming, Biomass Gasification, Coal Gasification End User: Transportation, Industrial, Power Generation, Chemical Manufacturing Production Method: Grey Hydrogen, Green Hydrogen, Blue Hydrogen, Turquoise Hydrogen Application: Fuel Cells, Ammonia Production, Oil Refining, Metal Processing |
| Companies Covered | Plug Power Inc., NextEra Energy, Linde Plc, AES Corporation, Messer, Air Liquide SA, Cummins Inc., Bloom Energy, Air Products and Chemicals Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Hydrogen Generation Market Evolving Landscape
Technology substitution is compressing equipment procurement cycles as developers weigh electrolyzer platform commitments against evolving efficiency benchmarks. The competitive landscape is reorganizing around stack manufacturing capabilities and renewable energy access rather than conventional feedstock logistics.
Solid oxide electrolyzer technology is fragmenting the incumbent alkaline and PEM technology duopoly by offering higher conversion efficiencies at elevated operating temperatures. Industrial developers in the Pacific Northwest are piloting these systems for integration with geothermal and industrial waste heat sources. The technology is fragmenting vendor selection criteria toward heat integration potential rather than pure electricity consumption metrics.
EPA's updated greenhouse gas permitting requirements under the Clean Air Act are forcing reforming facility operators to document carbon capture readiness or face construction moratoria. This regulatory pressure is diverting maintenance capital toward emissions monitoring instrumentation and away from pure throughput expansion. Gulf Coast operators are responding by accelerating carbon capture and sequestration partnership negotiations to preserve operating permits.
Long-term offtake contracting is displacing spot market transactions as the dominant procurement mode for industrial hydrogen buyers. Ammonia producers and refiners are locking in fifteen to twenty-year supply agreements to secure IRA credit pass-through and hedge against renewable power price volatility. This shift is most visible in Texas, where electrolyzer developers require contracted revenue streams to reach final investment decisions on greenfield projects.
United States Hydrogen Generation Market Segmentation
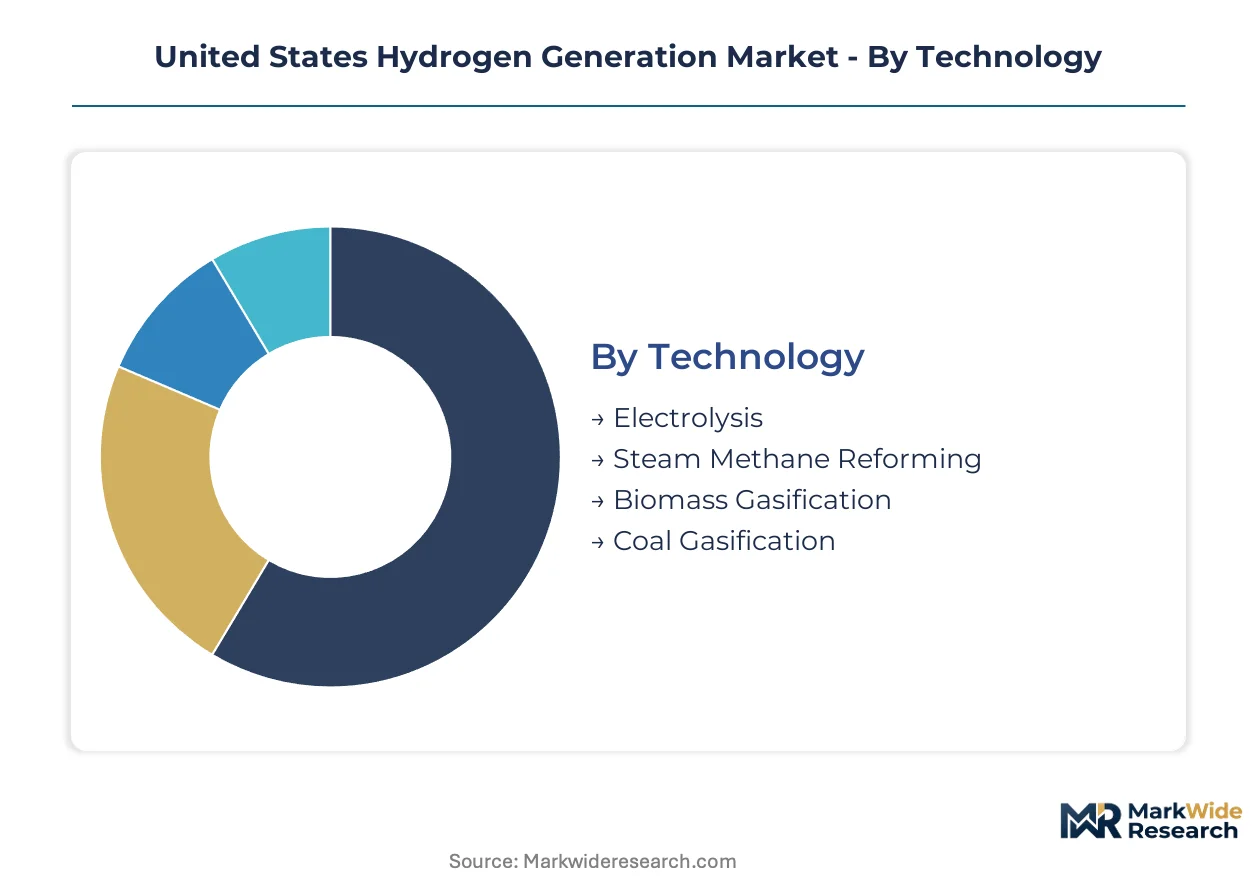
Technology pathways and carbon intensity grades define competitive positioning in domestic hydrogen supply. Each segmentation dimension reveals distinct margin architectures shaped by policy incentives and offtake contract structures.
Technology:
Margin pools concentrate in electrolyzer stack manufacturing and integrated project development rather than commodity equipment supply.
- Electrolysis:Proton exchange membrane and alkaline systems split water using electric current, with stack efficiency determining lifecycle production costs. Texas and California developers are securing renewable power purchase agreements to qualify for IRA production tax credits, though iridium catalyst supply concentration in South African mining operations constrains capacity scaling.
- Steam Methane Reforming:Natural gas feedstock reacts with steam over nickel catalyst beds to produce hydrogen and carbon dioxide, leveraging existing Gulf Coast pipeline infrastructure. The technology maintains cost advantages in ammonia and refining offtake where carbon intensity thresholds remain unenforced, though EPA permitting requirements are forcing carbon capture readiness documentation.
- Biomass Gasification:Organic feedstock thermal conversion yields syngas for hydrogen extraction, with California agricultural waste streams providing regional feedstock access.
- Coal Gasification:High-temperature coal reaction with oxygen and steam produces hydrogen, concentrated in legacy industrial clusters with limited new capital deployment.
The dominant share belongs to Steam Methane Reforming, while Electrolysis is closing the gap fastest.
End User:
Demand concentration tracks state-level decarbonization mandates and fleet electrification timelines.
- Transportation:Heavy-duty trucking fleets in California deploy fuel-cell vehicles to comply with Advanced Clean Trucks regulations, creating guaranteed offtake volumes for hydrogen suppliers. Station network buildout along I-10 and I-5 corridors is accelerating consumption growth.
- Industrial:Steel direct reduction and cement process heat applications in the Ohio River Valley and Great Lakes regions are piloting hydrogen substitution for metallurgical coal and natural gas.
- Power Generation:Gas turbine co-firing and long-duration storage applications in Texas ERCOT territory absorb intermittent renewable output through electrolyzer-to-power cycles.
- Chemical Manufacturing:Ammonia and methanol producers on the Gulf Coast represent baseline demand with established supply contracts and pipeline delivery infrastructure.
Industrial offtake commands volume leadership, though Transportation is expanding most quickly.
Production Method:
Carbon intensity certification tiers determine tax credit eligibility and export market access.
- Grey Hydrogen:Unabated steam methane reforming without carbon capture serves price-sensitive ammonia and refining customers in Louisiana and Texas.
- Green Hydrogen:Renewable-powered electrolysis achieves lifecycle emissions below specified thresholds, qualifying for maximum IRA credit tiers and European import certification.
- Blue Hydrogen:Reforming with carbon capture and sequestration leverages Gulf Coast saline formation geology for permanent CO2 storage, bridging cost and carbon performance.
- Turquoise Hydrogen:Methane pyrolysis produces hydrogen and solid carbon, with pilot projects evaluating reactor scaling and carbon product offtake economics.
Grey Hydrogen retains installed base dominance, while Green Hydrogen is gaining share fastest.
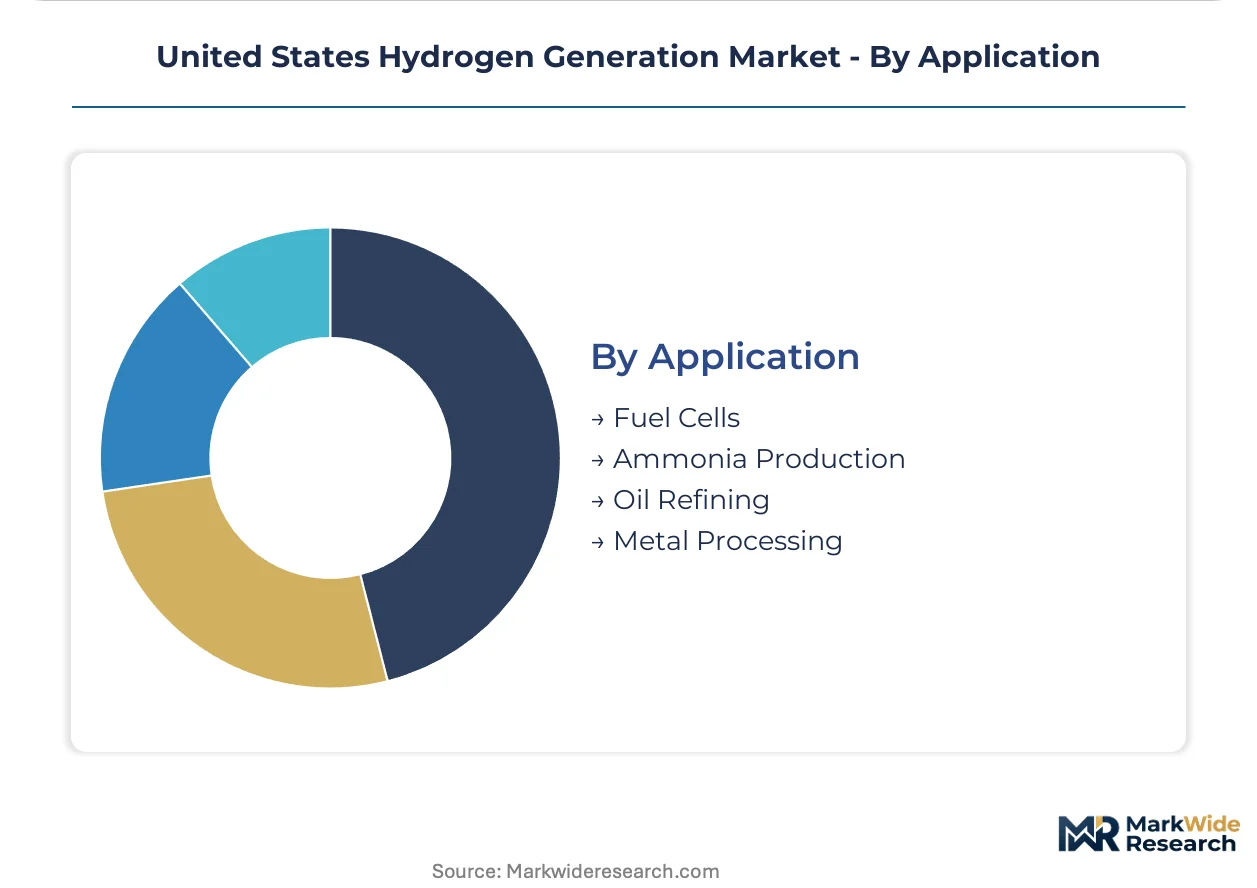
Application:
Product purity specifications and delivery modalities segment margin structures.
- Fuel Cells:Transportation and stationary power applications demand 99.97%+ purity with ultra-low contaminant thresholds for proton exchange membrane stack protection.
- Ammonia Production:Haber-Bosch synthesis requires consistent hydrogen-nitrogen ratio control, with Gulf Coast producers representing concentrated demand.
- Oil Refining:Hydrocracking and desulfurization units consume industrial-grade hydrogen at scale, with California refineries facing renewable content mandates.
- Metal Processing:Direct reduction iron applications in the Midwest are testing hydrogen substitution rates against metallurgical coal benchmarks.
Ammonia Production holds the largest demand position, though Fuel Cells show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas commands pricing power through Gulf Coast pipeline infrastructure density, while California's renewable-powered electrolysis projects extract premiums via IRA credit stacking and carbon intensity certification advantages.
Texas Gulf Coast
Heavy-duty trucking corridors along I-10 and I-45 absorb fuel-cell hydrogen volumes from Houston-area production clusters. EPA tailpipe standards and Texas Commission on Environmental Quality permitting frameworks accelerate carbon capture readiness documentation for reforming facilities. The Houston Ship Channel industrial complex hosts concentrated ammonia and refining offtake with established hydrogen pipeline delivery networks.
California
Advanced Clean Trucks regulations mandate zero-emission fleet conversions by 2036, guaranteeing hydrogen demand from drayage and long-haul operators. California Air Resources Board low-carbon fuel standard credits stack with IRA production tax credits for renewable-powered electrolysis projects. The Central Valley and Port of Long Beach anchor production clusters where solar and wind power purchase agreements reshape project economics.
Pacific Northwest
Columbia River hydropower access enables sub-dollar electricity rates for electrolyzer operations in Washington and Oregon. Bonneville Power Administration transmission agreements and state renewable portfolio standards direct capital toward greenfield electrolyzer deployments. The Portland-Vancouver metro area pilots solid oxide electrolyzer integration with geothermal waste heat from regional industrial facilities.
Ohio River Valley
Steel direct reduction pilot programs in Kentucky and West Virginia test hydrogen substitution for metallurgical coal in electric arc furnace feedstock. Department of Energy regional clean hydrogen hub funding targets Appalachian geological formations for carbon sequestration. The Pittsburgh-Cleveland corridor concentrates industrial process heat demand from cement and glass manufacturers evaluating hydrogen fuel switching.
Midwest Industrial Corridor
Ammonia and methanol producers in Illinois and Iowa seek hydrogen supply contracts to decarbonize fertilizer and biofuel output. Iowa Utilities Board renewable energy interconnection rules and Midwest ISO grid access shape electrolyzer siting decisions. The Des Moines-Chicago logistics corridor positions production assets for agricultural chemical offtake and emerging sustainable aviation fuel synthesis.
United States Hydrogen Generation Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with electrolyzer stack specialists commanding premium positioning against incumbent gas processors with legacy infrastructure advantages. The market structure organizes around three tiers: integrated project developers controlling renewable energy access, industrial gas incumbents leveraging pipeline networks, and pure-play electrolyzer manufacturers racing down cost curves. Dominant competitive moves include strategic partnerships securing offtake volumes and capacity expansion announcements timed to IRA credit guidance releases.
Within the integrated developer tier, Plug Power Inc. and NextEra Energy exemplify capital deployment strategies combining renewable generation assets with captive hydrogen production. Linde Plc and Air Products and Chemicals Inc. anchor the industrial gas incumbent position through Gulf Coast pipeline network control and established reforming facility operations. Cummins Inc. occupies a technology-supplier niche, representing the power systems manufacturer's pivot toward fuel-cell and electrolyzer component markets.
| Leading Market Players |
|---|
| Plug Power Inc. |
| NextEra Energy |
| Linde Plc |
| AES Corporation |
| Messer |
| Air Liquide SA |
| Cummins Inc. |
| Bloom Energy |
| Air Products and Chemicals Inc. |
| Others |
Value Network & Pricing Analysis
Electrolyzer gigafactory scale economies are compressing unit production costs while simultaneously concentrating supply among three domestic stack manufacturers, creating price floors that legacy steam methane reforming operations struggle to match under IRA credit-stacked competition. Capacity utilization rates above 85 percent at Texas and California production clusters enable aggressive offtake contracting that locks in fifteen-year revenue streams and marginalizes higher-cost grey hydrogen suppliers.
Pricing Analysis
The configured-to-order premium spread separates green hydrogen production under bespoke renewable power purchase agreements from standardized grey hydrogen delivered through Gulf Coast pipeline networks. Long-term offtake contracting dominates procurement structures, with price differentiation driven by carbon intensity certification tiers under IRA guidelines and volume scale commitments from ammonia producers. Cost compression in electrolyzer manufacturing is intensifying because Chinese stack imports and domestic capacity expansions are flooding the equipment market. Industrial ammonia and refining offtake remains most price-sensitive, while fuel-cell fleet operators accept premiums for Scope 3 compliance.
Supply Chain Analysis
South Africa and Russia anchor iridium and platinum group metal catalyst production for proton exchange membrane electrolyzer stacks, creating geopolitical concentration in critical input supply. Domestic manufacturing draws from nickel catalyst beds for reforming operations, specialized membrane coatings from European and Japanese suppliers, and carbon fiber pressure vessels for hydrogen storage. Single-source vulnerability in South African mining operations threatens electrolyzer scaling timelines. Distribution runs through Gulf Coast pipeline networks for industrial offtake and compressed tube trailer delivery for fuel-cell station networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States hydrogen generation market is approaching a platform-economics inflection where electrolyzer stack interoperability standards and shared renewable energy access protocols will determine winner-take-most dynamics. The Department of Energy's regional clean hydrogen hub selections are accelerating ecosystem consolidation around seven geographic clusters with shared infrastructure and standardized offtake contracting.
For Market Incumbents: Secure carbon capture readiness documentation for Gulf Coast reforming facilities before EPA permitting deadlines harden construction moratoria. Anchor pipeline network control through capacity additions in the Houston Ship Channel corridor and invest in electrolyzer stack manufacturing partnerships to hedge against technology substitution. The threat of green hydrogen cost parity under IRA credits demands defensive positioning in both legacy infrastructure and emerging electrolyzer supply chains. For New Entrants and Emerging Players: IRA production tax credit pre-certification offers the fastest path to bankable offtake contracts and project finance access. Target steel direct reduction pilot programs in the Ohio River Valley and sustainable aviation fuel synthesis in the Midwest where incumbent supply contracts remain unconsolidated. A go-to-market angle anchored to geothermal-waste heat integration for solid oxide electrolyzer deployments differentiates against generic renewable-powered alkaline systems. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated project developers with captive renewable generation and fifteen-year offtake contracts. Long-term viability over the next decade favors electrolyzer stack specialists with backward integration into membrane coating and catalyst application capabilities. The signal to watch is final investment decision velocity on greenfield electrolyzer projects in Texas ERCOT territory, where interconnection queue positions indicate capital commitment confidence.| Strategic Initiative | Industry Significance |
|---|---|
| Electrolyzer Gigafactory Capacity Buildout | Domestic stack manufacturing reduces iridium supply chain exposure and captures IRA domestic content bonuses. |
| Carbon Capture and Sequestration Partnership | Gulf Coast saline formation geology enables blue hydrogen production with permanent CO2 storage for ammonia export markets. |
| Renewable Power Purchase Agreement | ERCOT and CAISO grid access with solar-wind hybrid contracts secures sub-dollar electricity rates for green hydrogen qualification. |
| Regional Clean Hydrogen Hub Consortium | Department of Energy funding clusters concentrate federal investment and standardize offtake contracting across seven geographic networks. |
| Long-term Industrial Offtake Contract | Fifteen-year supply agreements with ammonia producers and refiners hedge renewable power price volatility and enable project finance. |
Research Methodology
Initial hypotheses were tested against primary input from electrolyzer project developers, utility planning officers, industrial gas procurement leads, and EPA regulatory affairs specialists and refined through secondary validation against EIA hydrogen production databases, FERC interconnection filings, Department of Energy funding announcements, and SEC 10-K disclosures from listed industrial gas producers. Bottom-up capacity buildout modeling was triangulated against top-down demand projections from ammonia, refining, and transportation offtake segments.
Variance decomposition across technology pathways, carbon intensity certification tiers, and regional regulatory frameworks shaped the analytical approach over the projection horizon. Segmentation dimensions modeled include production method, end-use industry, application purity specifications, and state-level policy incentive structures. CAGRs were derived from electrolyzer deployment pipelines, renewable energy interconnection queues, and fleet electrification mandate compliance timelines. IRA credit guidance releases and regional clean hydrogen hub selection announcements provided critical inflection inputs.
Decision-makers should treat outputs as directional under assumptions of sustained IRA credit authorization and electrolyzer cost decline curves; material deviation in federal policy continuity or catalyst supply disruption would warrant model refresh. Recalibration cycles align with material shifts in Department of Energy funding announcements, EPA permitting rulemakings, and final investment decisions on gigafactory-scale electrolyzer manufacturing facilities.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydrogen Energy
Blue Hydrogen Market
Hydrogen Energy
Green Hydrogen Market
Hydrogen Energy
US Hydrogen Fueling Station Market
Hydrogen Energy
Hydrogen Powered Engine Market
Hydrogen Energy
Alkaline Water Electrolysis Market
Hydrogen Energy
Black Hydrogen Market
Hydrogen Energy
70MPa High Pressure Hydrogen Storage Cylinders Market
Hydrogen Energy
On-Site Hydrogen Generator Market
Hydrogen Energy
Hydrogen Recovery Market
Hydrogen Energy
Hydrogen Market
Hydrogen Energy
Hydrogen Liquefaction Unit Market
Hydrogen Energy
Solar Hydrogen Panel Market
Hydrogen Energy
Green Energy Hydrogen Production System Market
Hydrogen Energy
Hydrogen Generation Market
Hydrogen Energy
35MPa High Pressure Hydrogen Storage Cylinders Market
Hydrogen Energy
Green Hydrogen Dispensing Equipment Market