
 35MPa High Pressure Hydrogen Storage Cylinders Market | 2026-2036
35MPa High Pressure Hydrogen Storage Cylinders Market Size, Share, and Industry Trends Forecast 2026-2036
35MPa High Pressure Hydrogen Storage Cylinders Market Insights
Carbon fiber wrapping over aluminum liners is tilting manufacturing economics toward lighter, higher-cycle designs. Hexagon Composites leverages its automated filament winding lines to dominate Type III and Type IV output. Luxfer Gas Cylinders anchors European supply through backward integration into aluminum liner extrusion. Faber Industrie specializes in high-volume steel-to-composite transition programs for Italian transport operators.
35MPa high pressure hydrogen storage cylinders are pressure vessels engineered to contain compressed hydrogen gas at 35 megapascals, typically constructed from aluminum or steel liners overwrapped with carbon fiber or glass fiber composites to achieve strength-to-weight ratios critical for mobile applications. Their primary purpose centers on onboard fuel storage for fuel cell electric vehicles and modular refueling infrastructure. Composite cylinders command premium positioning in fuel cell vehicle applications where weight reduction directly extends driving range. Aluminum lined cylinders retain cost advantages in stationary storage and backup power systems where mass matters less. Hydrogen refueling stations favor modular storage systems that scale throughput without footprint expansion.
ISO 11119-2 governs composite cylinder design and testing, while the EU F-Gas Regulation and REACH constrain material selection for liners and resins. Japan's METI hydrogen safety standards and South Korea's KGS certification create divergent compliance paths that fragment cross-border product platforms. China's GB/T 35544 and NMPA-equivalent pressure equipment rules impose localized testing regimes. Stakeholders must monitor evolving certification reciprocity between Asian and European frameworks to avoid stranded engineering investments.
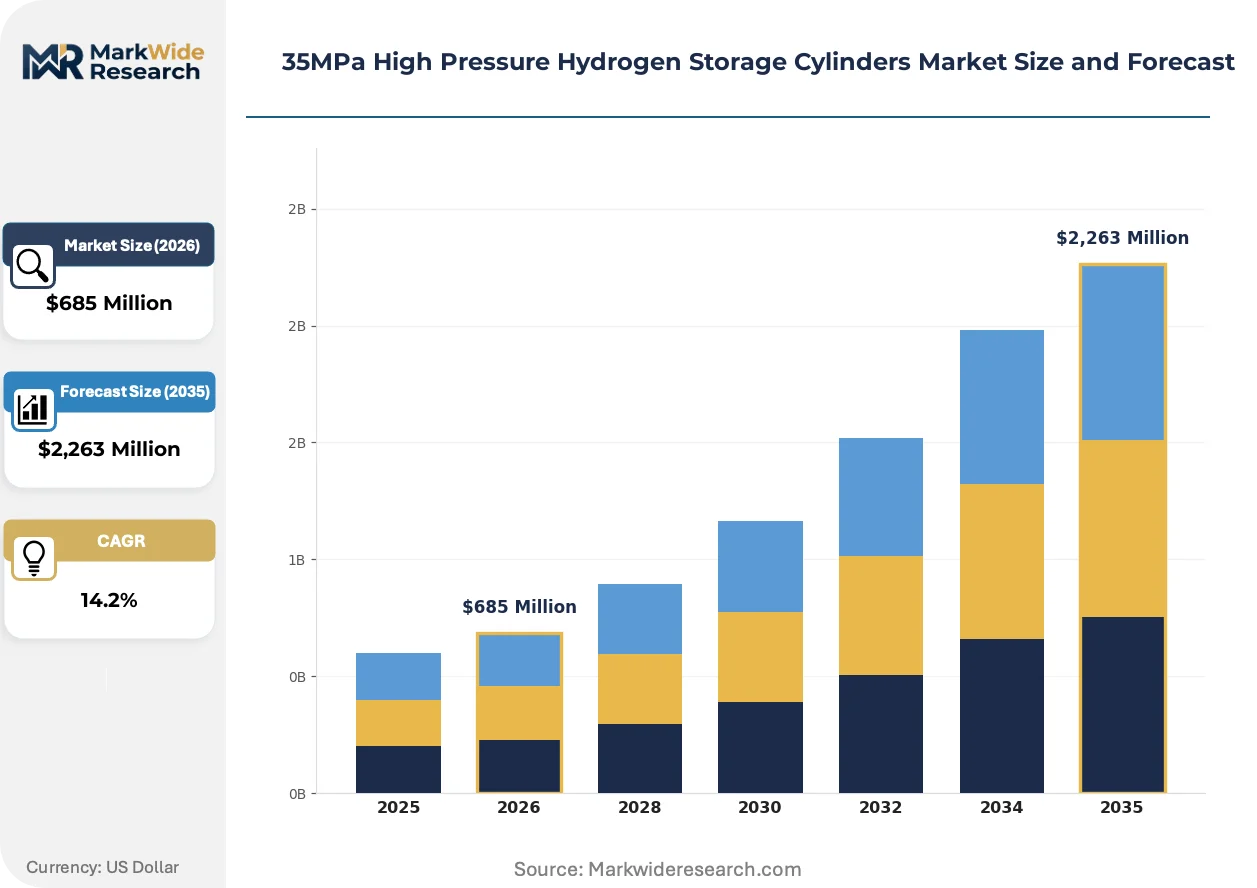
Market Dynamics
Carbon fiber cost deflation and automated filament winding advances are compressing the manufacturing cost gap between Type III aluminum-lined and Type IV all-composite cylinders, redirecting capital toward lighter designs.
Growth Catalysts
- EU F-Gas Regulation phase-down:Restrictions on high-global-warming-potential industrial gases accelerate hydrogen adoption as a process heat alternative in German and Dutch chemical corridors.
- Fuel cell bus fleet procurement:Municipal transit authorities in Japan and South Korea specify 35MPa onboard storage for route-standardized refueling infrastructure.
- Carbon fiber tow supply expansion:Toray Industries and SGL Carbon have added aerospace-surplus capacity to industrial grades, easing raw material constraints for cylinder manufacturers.
Market Restraints
- High-purity hydrogen supply concentration:Steam methane reforming with carbon capture clusters in Texas and Louisiana create geographic dependency for fuel cell vehicle rollout.
- Recertification cost burden:ISO 11119-2 hydrostatic retesting every five years imposes lifecycle cost penalties that compressed natural gas cylinders avoid.
- Stationary storage substitution:Liquid hydrogen and metal hydride systems capture warehouse and backup power applications where weight is immaterial.
Strategic Opportunities
- Indian heavy-duty trucking corridor:NHAI hydrogen highway pilots along Delhi-Mumbai Expressway create first-mover positioning for 35MPa modular tube trailer systems.
- EU Hydrogen Bank auction mechanism:Contract-for-difference subsidies for renewable hydrogen production de-risk downstream storage infrastructure investment.
- Digital twin integration:Real-time pressure cycling monitoring combined with predictive maintenance algorithms enables cylinder-as-a-service business models.
Industry Challenges
- Composite repair technician scarcity:Specialized carbon fiber damage assessment and overlay certification programs lag fleet deployment timelines.
- Cross-border certification reciprocity gaps:Japan's METI hydrogen safety standards and South Korea's KGS codes lack mutual recognition, forcing redundant testing for regional suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 35MPa High Pressure Hydrogen Storage Cylinders Market |
| Market Size in 2026 | $685 Million |
| Market Size in 2035 | $2,263 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Composite Cylinders, Aluminum Lined Cylinders, Steel Cylinders, Carbon Fiber Reinforced Cylinders, Fiber Wrapped Cylinders Application: Fuel Cell Vehicles, Industrial Gas Storage, Portable Power Devices, Backup Power Systems, Hydrogen Refueling Stations End User: OEM Manufacturers, Energy Storage Companies, Portable Device Makers, Emergency Power Providers, Refueling Equipment Suppliers Deployment Type: Onboard Storage, Stationary Storage, Mobile Storage Units, Transportable Containers, Modular Storage Systems |
| Companies Covered | Luxfer Gas Cylinders, Hexagon Composites, Faber Industrie, NPROXX, GFI, Rotarex, Cavagna Group, Parker Hannifin, Swagelok, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
35MPa High Pressure Hydrogen Storage Cylinders Market Trends and Innovations
Manufacturing automation and materials science advances are compressing production cycle times while extending cylinder fatigue life, reshaping procurement economics for fleet operators and refueling infrastructure developers.
Filament winding robotics with in-situ thermoplastic resin injection is rendering obsolete manual layup processes for Type IV linerless cylinders. Hexagon Composites and Toyota Motors have adopted these lines for fuel cell vehicle production scales. The shift collapses labor cost differentials between European and Asian manufacturing bases.
REACH Annex XVII restrictions on bisphenol-A in epoxy resin formulations are forcing reformulation of cylinder matrix systems. German cylinder manufacturers face eighteen-month requalification timelines for alternative resin chemistries. The regulatory pressure concentrates procurement among suppliers with pre-validated material stacks.
Fleet operators now specify total-cost-of-ownership contracts bundling cylinder procurement, recertification, and end-of-life recycling. Municipal bus authorities in Japan and South Korea have shifted from capital purchase to per-kilometer leasing. The model transfers fatigue risk to manufacturers and accelerates Type IV adoption where residual value uncertainty previously stalled investment.
35MPa High Pressure Hydrogen Storage Cylinders Market Segmentation
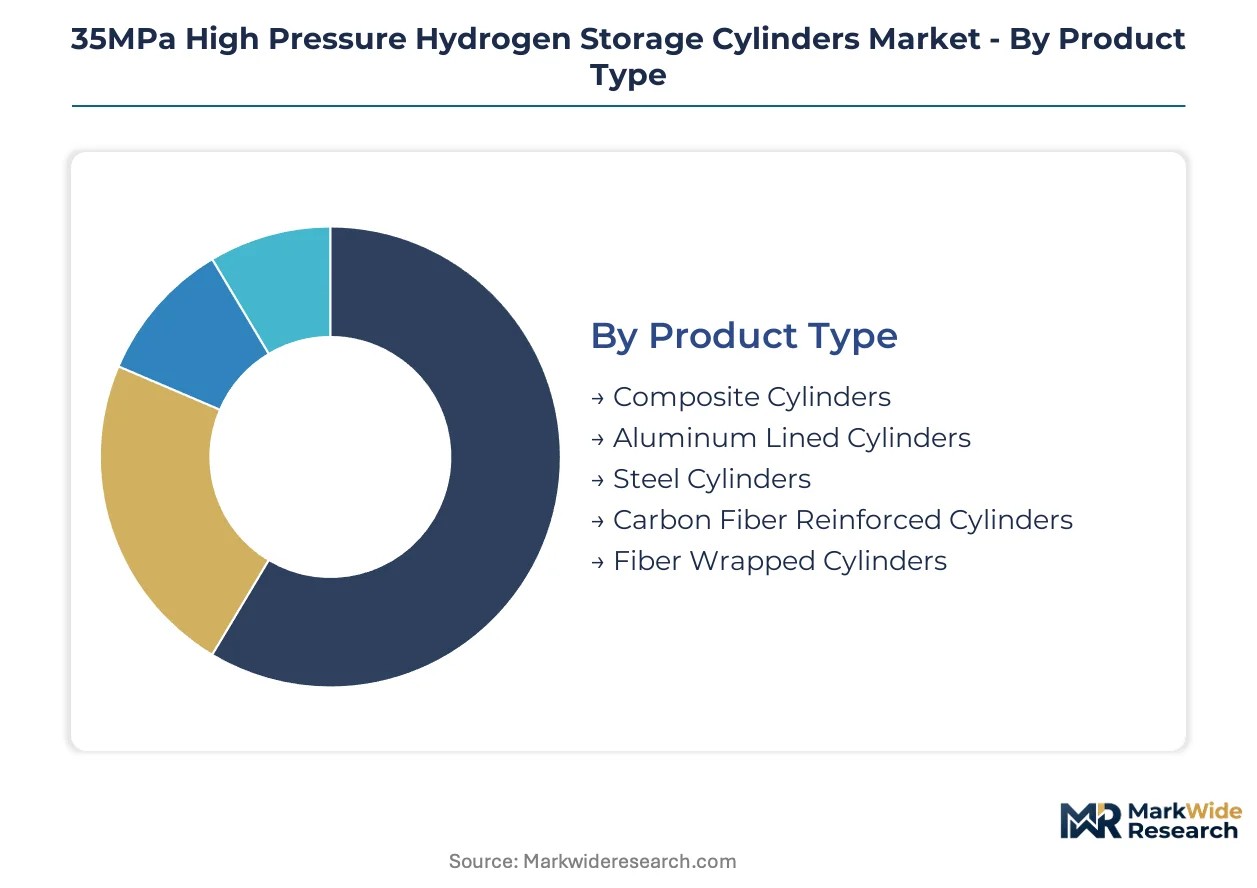
Technology-material combinations in 35MPa hydrogen storage cylinders create divergent performance-cost tradeoffs that reshape procurement across mobility and stationary applications. Segmentation reveals where carbon fiber premiumization commands pricing power versus where aluminum and steel retain cost-driven volume.
Product Type:
The use-case spectrum spans ultralight fuel cell vehicle integration to bulk industrial containment, with liner material and fiber architecture determining weight-cycle economics.
- Composite Cylinders:All-carbon-fiber Type IV construction eliminates metallic liners entirely, achieving weight reductions critical for extending fuel cell vehicle range. Japanese and South Korean bus fleets specify these for standardized 35MPa infrastructure.
- Aluminum Lined Cylinders:Type III hybrid designs wrap aluminum liners with carbon fiber overwrap, balancing fatigue resistance with moderate weight penalties. These dominate Chinese industrial hydrogen corridors where cost sensitivity exceeds mass constraints.
- Steel Cylinders:Type I all-metal construction persists in legacy industrial gas storage and backup power installations. German chemical operators specify these for stationary buffer storage where weight is irrelevant.
- Carbon Fiber Reinforced Cylinders:Specialized high-tow fiber architectures optimize burst strength-to-weight ratios for aerospace-derived automotive programs.
- Fiber Wrapped Cylinders:Glass fiber variants serve cost-constrained portable power and emergency backup segments with reduced cycle life requirements.
Established volume favors aluminum lined designs; emerging adoption favors all-composite Type IV construction.
Application:
Cost tier stratification separates premium mobility applications from economy stationary storage, with refueling infrastructure occupying a mid-tier equipment investment band.
- Fuel Cell Vehicles:Onboard 35MPa storage dictates cylinder specifications for passenger cars, buses, and commercial trucks. South Korean municipal transit authorities procure standardized tank systems to enable route-optimized refueling networks.
- Industrial Gas Storage:Bulk hydrogen containment for chemical process feedstock and steel decarbonization favors heavier, lower-cost cylinder configurations. Dutch and German chemical corridor operators prioritize capital efficiency over transportability.
- Portable Power Devices:Compact 35MPa cylinders enable fuel cell generators for remote construction and outdoor events. Japanese equipment manufacturers integrate these into modular power rental fleets.
- Backup Power Systems:Stationary installations at data centers and telecommunications facilities require long-duration hydrogen storage with minimal maintenance cycles.
- Hydrogen Refueling Stations:Buffer and cascade storage systems require high-cycle fatigue resistance to manage daily compression and dispensing operations.
Mobility applications absorb premium pricing for weight reduction; stationary applications prioritize capital efficiency and cycle economics.
End User:
Customer type concentration determines procurement modality, with OEMs demanding design integration support and energy storage companies negotiating volume supply agreements.
- OEM Manufacturers:Toyota Motors and Hyundai integrate 35MPa cylinders into fuel cell vehicle platforms during assembly, requiring crash-tested, vehicle-certified tank systems with full traceability documentation.
- Energy Storage Companies:Industrial hydrogen suppliers in China's Shandong and Jiangsu provinces procure tube trailer systems for bulk transport and site storage.
- Portable Device Makers:Fuel cell generator manufacturers specify compact cylinders with rapid-connect interfaces for consumer and commercial equipment.
- Emergency Power Providers:Data center operators and telecommunications utilities negotiate service contracts bundling cylinder supply with recertification and replacement logistics.
- Refueling Equipment Suppliers:Station builders source cascade storage banks and buffer tanks with harmonized pressure ratings to match dispenser throughput specifications.
Automotive OEMs drive technology roadmaps; industrial energy storage companies anchor production volume planning.
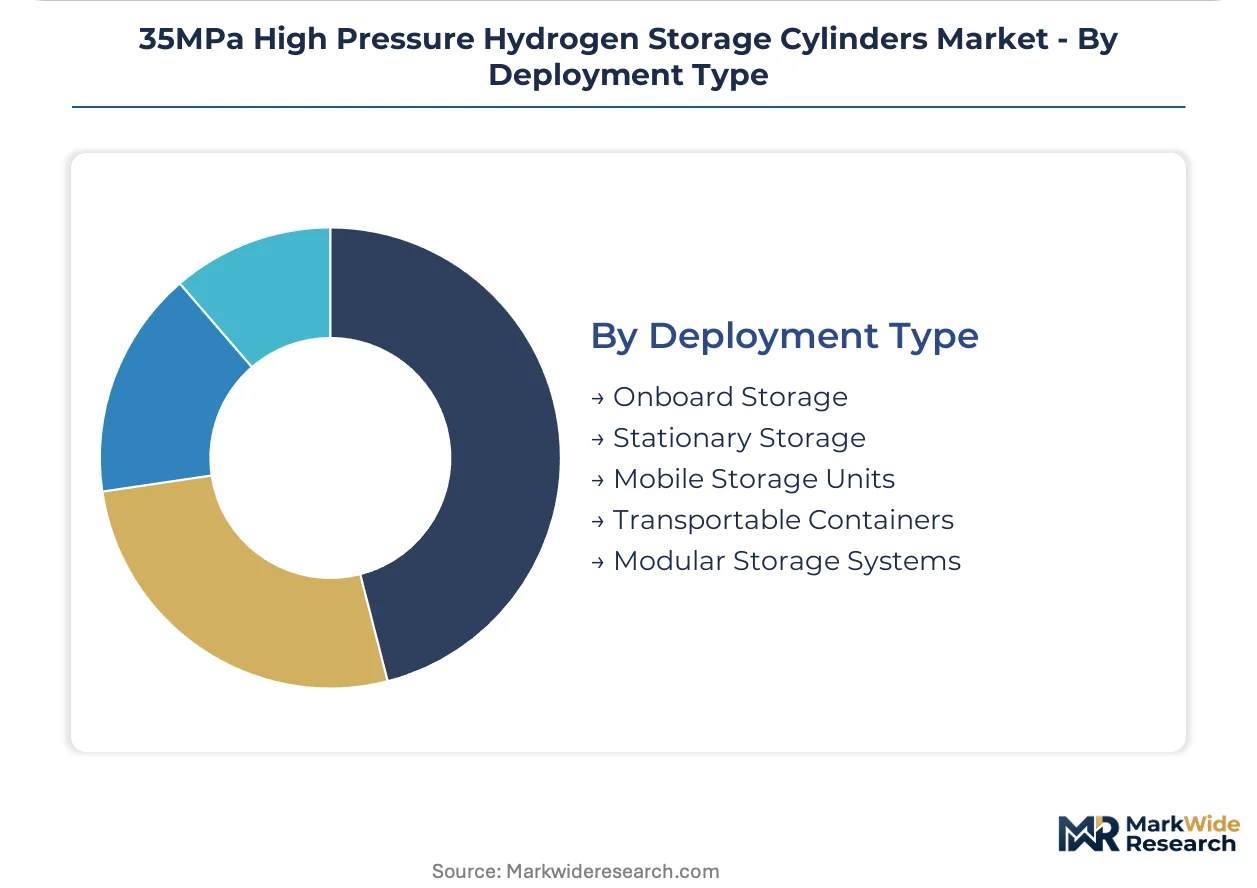
Deployment Type:
Geography of installation constrains cylinder specification, with onboard applications demanding extreme weight optimization and stationary sites tolerating heavier, lower-cost alternatives.
- Onboard Storage:Vehicle-integrated 35MPa tanks must survive crash, fire, and gunfire testing per UN ECE R134 and regional homologation. South Korean KGS certification adds localized impact testing requirements.
- Stationary Storage:Fixed installations at production facilities and consumption sites prioritize capacity per square meter and minimal foundation requirements.
- Mobile Storage Units:Tube trailers and portable cascade systems enable hydrogen distribution without pipeline infrastructure. Indian NHAI hydrogen highway pilots specify these for Delhi-Mumbai Expressway corridors.
- Transportable Containers:Intermodal cylinder systems support multimodal hydrogen logistics across road, rail, and limited maritime routes.
- Modular Storage Systems:Scalable bank configurations allow refueling stations to expand throughput without footprint expansion or major civil works.
Fixed stationary installations retain the largest installed base; modular and mobile configurations are expanding most quickly with infrastructure buildout.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese cylinder manufacturers supply tube trailer systems to industrial hydrogen corridors in Germany and the Netherlands, while Japanese and South Korean producers dominate onboard storage integration for fuel cell vehicle OEMs.
China
Shandong and Jiangsu provinces anchor industrial hydrogen demand for steel decarbonization and chemical feedstock applications. NMPA-equivalent pressure equipment rules under GB/T 35544 impose localized testing regimes that favor domestic suppliers. The Yangtze River Delta cluster concentrates Type III aluminum-lined cylinder production for cost-sensitive bulk transport.
Japan
METI hydrogen safety standards drive certification requirements for fuel cell bus fleet procurement by municipal transit authorities. The Kanto region around Tokyo hosts integrated cylinder-to-vehicle supply chains serving Toyota Motors production scales. Kawasaki and Nagoya industrial zones specialize in high-cycle fatigue designs for standardized 35MPa refueling infrastructure.
Germany
The EU F-Gas Regulation phase-down accelerates hydrogen adoption as process heat alternative in chemical corridors along the Rhine and Ruhr. REACH Annex XVII constraints on epoxy resin formulations force eighteen-month requalification timelines for cylinder matrix systems. Bavaria-based manufacturers leverage backward integration into aluminum liner extrusion for European supply security.
South Korea
KGS certification adds localized impact testing requirements beyond UN ECE R134 for onboard vehicle integration. The Seoul Capital Area concentrates demand from Hyundai fuel cell vehicle platforms requiring crash-tested, vehicle-certified tank systems. Busan-Ulsan industrial zones support modular refueling station deployment along coastal hydrogen highway pilots.
India
NHAI hydrogen highway pilots along the Delhi-Mumbai Expressway create first-mover positioning for 35MPa modular tube trailer systems. BIS standards development for high-pressure hydrogen equipment lags fleet deployment timelines, creating regulatory uncertainty. Maharashtra and Gujarat industrial clusters attract investment for mobile storage units serving heavy-duty trucking corridors.
35MPa High Pressure Hydrogen Storage Cylinders Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three discernible tiers. Consolidation pressure concentrates among automated filament winding specialists and aluminum liner extrusion integrators. Three archetypes dominate: composite-overwrap technology leaders, metallic liner backward integrators, and regional steel-to-composite transition specialists. Capacity expansion and strategic partnerships represent the dominant competitive moves, with manufacturers securing carbon fiber tow supply through long-term offtake agreements.
Among European-anchored suppliers, Luxfer Gas Cylinders exemplifies the metallic liner integration archetype, while Hexagon Composites occupies a position representing automated filament winding scale. Faber Industrie sits within the regional transition specialist tier, serving Italian transport operator requirements. These three entities collectively illustrate the geographic and technological segmentation defining competitive positioning.
| Leading Market Players |
|---|
| Luxfer Gas Cylinders |
| Hexagon Composites |
| Faber Industrie |
| NPROXX |
| GFI |
| Rotarex |
| Cavagna Group |
| Parker Hannifin |
| Swagelok |
| Others |
Pricing and Supply Chain Analysis
Carbon fiber tow supply concentration in Japan and South Korea determines both the premium spread for Type IV cylinders and the geographic clustering of automated filament winding capacity. This single-source dependency for aerospace-grade fiber feeds directly into pricing tier stratification and shapes where manufacturers locate backward integration investments.
Pricing Analysis
The Type III-to-Type IV technology-generation pricing gap narrows as automated filament winding compresses labor cost differentials. Three-tier pricing structure across premium, standard, and economy levels separates vehicle-certified Type IV systems from industrial-grade Type III configurations and legacy steel cylinders. Price differentiation hinges on ISO 11119-2 certification tier and carbon fiber tow grade. Cost compression in Type IV manufacturing is intensifying because Toray Industries and SGL Carbon have expanded aerospace-surplus capacity into industrial grades. Fleet operators show least price sensitivity for onboard fuel cell vehicle integration, while Chinese industrial hydrogen corridor buyers anchor the economy tier.
Supply Chain Analysis
Contract manufacturing concentration for aluminum liner extrusion rests with Bavaria-based specialists and Shandong province producers. Geographic supply concentrates in China, Germany, and Japan for liner production, with carbon fiber overwrap capacity clustering in Japan and South Korea. Raw material dependencies draw from Toray Industries tow supply, epoxy resin formulations constrained by REACH Annex XVII, and aerospace-grade pre-preg inventories. Single-source vulnerability runs through Japanese carbon fiber suppliers holding 70% of qualified aerospace-industrial crossover grades. Distribution runs through OEM direct procurement for vehicle integration and industrial gas equipment distributors for stationary applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
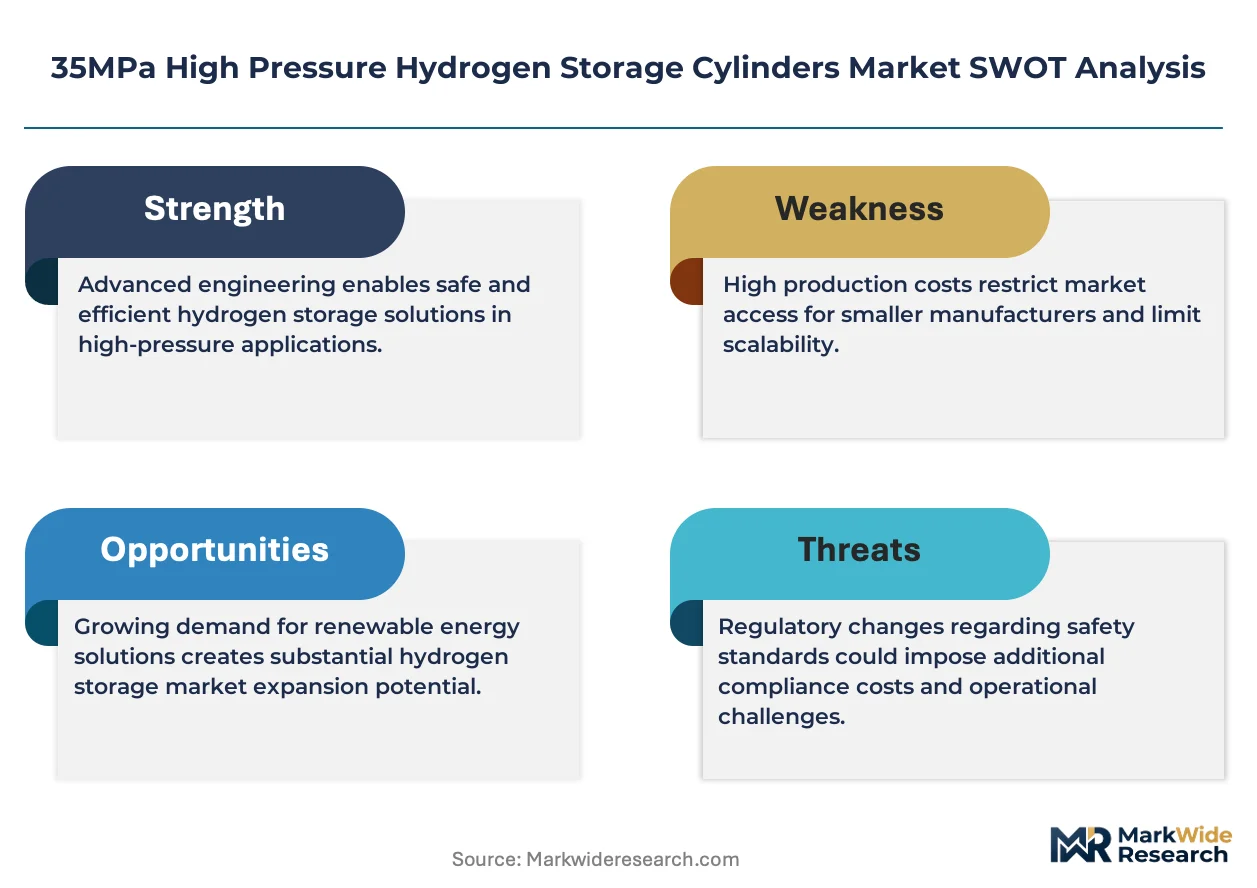
The 35MPa cylinder market sits at an inflection where EU F-Gas Regulation phase-down accelerates hydrogen adoption faster than certification reciprocity frameworks can harmonize. This regulatory-technological misalignment creates asymmetric opportunity windows across stakeholder positions.
For Market Incumbents: Build certification moats by securing dual METI-KGS qualification before reciprocal recognition agreements finalize. Deepen backward integration into aluminum liner extrusion to defend margin position against Chinese cost leaders entering European chemical corridors. Threat substitution from liquid hydrogen and metal hydride systems in stationary applications demands accelerated Type IV fatigue-life extension programs. For New Entrants and Emerging Players: Build out modular tube trailer assembly capacity targeting Indian NHAI hydrogen highway pilots along the Delhi-Mumbai Expressway corridor. White-space concentration sits with BIS standards development lagging fleet deployment timelines, creating first-mover positioning before regulatory clarity solidifies. Go-to-market angle: per-kilometer leasing models transferring fatigue risk from municipal bus authorities to cylinder-as-a-service providers. For Investors and Strategic Acquirers: EU Hydrogen Bank auction mechanism reshapes the acquisition landscape by de-risking downstream storage infrastructure investment through contract-for-difference subsidies. Long-term viability frames around 5-10 year hydrogen corridor buildout timelines with cylinder replacement cycles embedded. Target acquisition archetype: automated filament winding specialists with pre-validated REACH-compliant resin stacks. Signal to watch: reciprocity agreements between METI and KGS certification bodies eliminating redundant testing costs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Liner Extrusion | Luxfer Gas Cylinders anchors European supply security against import dependency. |
| Automated Filament Winding Scale-Up | Hexagon Composites collapses labor cost differentials between European and Asian manufacturing bases. |
| Dual Certification Investment (METI-KGS) | Eliminates redundant testing costs for suppliers serving Japanese and South Korean bus fleets simultaneously. |
| Carbon Fiber Tow Long-Term Offtake Agreements | Secures aerospace-surplus capacity from Toray Industries and SGL Carbon before industrial grade constraints tighten. |
| Digital Twin Integration for Predictive Maintenance | Enables cylinder-as-a-service business models transferring fatigue risk from fleet operators to manufacturers. |
Research Methodology
A spread of perspectives from cylinder manufacturing engineers, fuel cell vehicle platform directors, industrial hydrogen procurement leads, and refueling station EPC contractors converged on the working assumptions. Primary interviews with METI certification specialists and KGS testing laboratory directors validated compliance pathway fragmentation. Secondary sources combined UN ECE R134 homologation databases, EU Hydrogen Bank auction documentation, GB/T 35544 standards filings, and carbon fiber trade flow customs records. Bottom-up cylinder unit economics triangulated against top-down hydrogen corridor investment forecasts.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with fleet deployment timelines cross-referenced against carbon fiber tow capacity expansion announcements. Segmentation dimensions modeled include liner material architecture, deployment type mobility, end-user procurement modality, and regional regulatory cluster. CAGRs derived from installed base replacement cycles and new infrastructure buildout phasing. Industry-specific forecast inputs incorporated EU F-Gas Regulation phase-down schedules and Indian NHAI hydrogen highway pilot progressions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese state-backed cylinder manufacturers into European chemical corridor supply would shift outcomes beyond modeled ranges. Assumptions reflect current certification reciprocity gaps and carbon fiber supply allocation priorities. Quarterly review of METI-KGS mutual recognition negotiations and EU Hydrogen Bank auction subscription rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydrogen Energy
Hydrogen Composite Tanks Market
Hydrogen Energy
USA Hydrogen Electrolyzer Market
Hydrogen Energy
Hydrogen Storage Tank Market
Hydrogen Energy
Alkaline Water Electrolysis Market
Hydrogen Energy
Hydrogen Production Electrolyser Market
Hydrogen Energy
Brown Hydrogen Market
Hydrogen Energy
Hydrogen Gas Generator Market
Hydrogen Energy
Hydrogen Storage Technology Market
Hydrogen Energy
Hydrogen Recovery Market
Hydrogen Energy
Hydrogen Generation Market
Hydrogen Energy
70MPa High Pressure Hydrogen Storage Cylinders Market
Hydrogen Energy
Blue Hydrogen Market
Hydrogen Energy
Liquid Organic Hydrogen Carrier (LOHC) Market
Hydrogen Energy
Solar Hydrogen Panel Market
Hydrogen Energy
Hydrogen Tanks Market
Hydrogen Energy
Gray Hydrogen Market