
 Europe Clean Hydrogen Market | 2026-2036
Europe Clean Hydrogen Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Clean Hydrogen Market Insights
Project finance structures with long-term offtake guarantees is narrowing the field of viable developers to those with balance-sheet depth or sovereign-backed credit support. Linde PLC leverages its existing industrial gas infrastructure to anchor large-scale electrolyzer deployments near German chemical parks. Nel ASA specializes in PEM electrolyzer manufacturing and competes on modular system architectures that reduce installation lead times. ThyssenKrupp Nucera dominates alkaline electrolysis engineering and sustains its position through deep integration with chlor-alkali process expertise.
Europe clean hydrogen refers to hydrogen produced with greenhouse gas emissions below defined thresholds, typically via water electrolysis powered by renewable electricity or through reforming with carbon capture, yielding purity grades from 99.9% to 99.999% depending on end-use requirements. Its primary purpose is to displace unabated fossil hydrogen in ammonia synthesis, steel reduction, and synthetic fuel production while serving as a seasonal electricity storage vector. Electrolysis technology leads capacity announcements but reforming with carbon capture still occupies the lowest-cost position for near-term industrial supply. Compressed hydrogen delivery mode currently controls the logistics landscape, though liquid hydrogen infrastructure is gaining investment for maritime export corridors.
The EU Green Deal, F-Gas Regulation, and delegated acts under the Renewable Energy Directive collectively shape what qualifies as renewable hydrogen of origin, directly determining subsidy eligibility and import acceptance at European borders. ECHA chemical safety frameworks and national permitting regimes in Germany, France, and the Netherlands further constrain project timelines and equipment standards. Stakeholders must monitor the finalization of certification methodologies and cross-border pipeline tariff structures before committing capital to long-duration assets.
Market Dynamics
Refinery decarbonization mandates in the Netherlands are compressing project timelines and forcing developers to secure pipeline-ready molecules before electrolyzer capacity comes online. This demand pull is restructuring capital allocation across the value chain.
Growth Catalysts
- EU Hydrogen Bank:The facility's auction mechanism is de-risking first-of-a-kind projects by providing fixed premium payments for certified renewable hydrogen output.
- Steel sector electrification:Direct reduction facilities in Germany's industrial clusters are signing decade-long offtake agreements for green hydrogen feedstock.
- Alkaline electrolysis scale-up:Engineering advances are driving capital cost reductions for gigawatt-class installations serving ammonia synthesis.
Market Restraints
- Renewable electricity cost volatility:Power purchase agreement pricing uncertainty undermines project finance assumptions for electrolyzer operators.
- Electrolyzer supply concentration:Stack manufacturing capacity remains concentrated among a limited set of European and Asian equipment vendors.
- Pipeline certification delays:Delegated acts under the Renewable Energy Directive have not finalized methodology for cross-border hydrogen origin verification.
Strategic Opportunities
- Maritime fuel corridors:Rotterdam and Hamburg port authorities are developing liquid hydrogen bunkering infrastructure for deep-sea shipping routes.
- French nuclear-powered electrolysis:Low-carbon electricity from existing reactor fleets offers a compliance pathway under draft EU taxonomy criteria.
- Carbon capture integration:Reforming with carbon capture and storage is capturing industrial demand in regions with depleted North Sea reservoirs.
Industry Challenges
- Electrolyzer technician scarcity:Specialized commissioning and maintenance skills for PEM and alkaline systems outpace vocational training output.
- Grid connection queuing:Transmission system operator approval timelines for multi-hundred megawatt renewable connections extend project schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Clean Hydrogen Market |
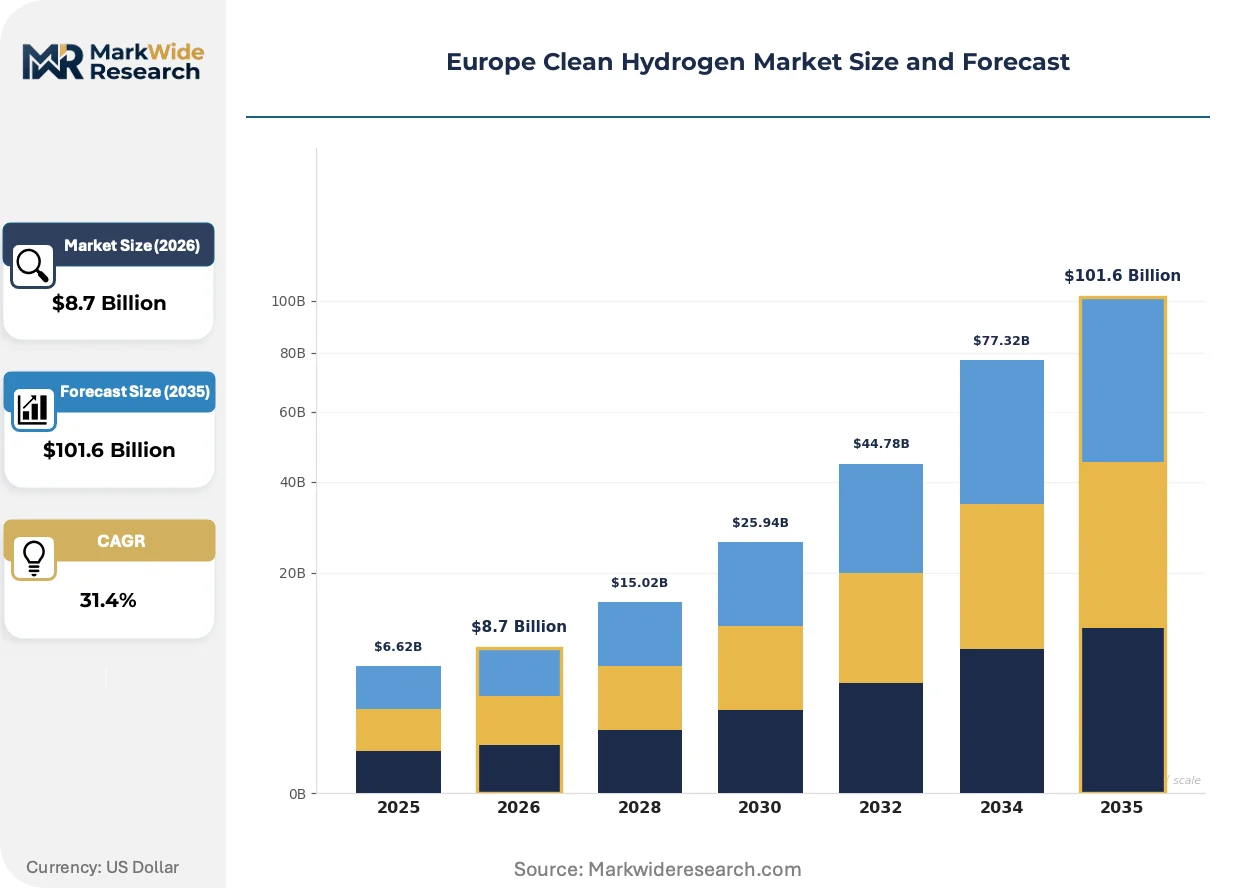
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $101.6 Billion |
| CAGR (2026 – 2036) | 31.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Transportation, Power Generation, Industrial Processes, Heating Technology: Electrolysis, Reforming, Gasification, Pyrolysis End User: Manufacturing, Transportation Fleet, Energy Sector, Utilities Delivery Mode: Compressed Hydrogen, Liquid Hydrogen, H2 Blending, On-site Generation |
| Companies Covered | Linde PLC, Air Liquide, Air Products, Nel ASA, Engie SA, Uniper SE, ThyssenKrupp Nucera, ITM Power, McPhy Energy, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Clean Hydrogen Market Trends and Innovations
Technology maturation and regulatory precision are converging to separate bankable projects from speculative capacity announcements. Developers now face pressure to demonstrate certified offtake before securing construction financing.
Solid oxide electrolysis is rendering obsolete the efficiency ceiling that constrained alkaline and PEM systems to sub-70% conversion rates. Steel producers in Sweden's Boden corridor are piloting high-temperature units for direct integration with blast furnace off-gas heat recovery. The technology is rendering obsolete the need for separate steam generation infrastructure in industrial hydrogen supply.
The EU F-Gas Regulation is tightening containment and reporting requirements for fluorinated gases used in electrolyzer cooling systems. Equipment vendors must redesign thermal management architectures or face import restrictions on completed systems. German chemical parks are accelerating specifications that exclude high-global-warming-potential refrigerants from new build tenders.
Buyers are consolidating procurement through hydrogen purchase agreements that bundle molecule supply with transport and storage services. Industrial offtakers in the Netherlands are bypassing merchant market exposure by contracting directly with integrated project developers. This pattern concentrates contract volume among balance-sheet-backed suppliers with captive renewable generation assets.
Europe Clean Hydrogen Market Segmentation
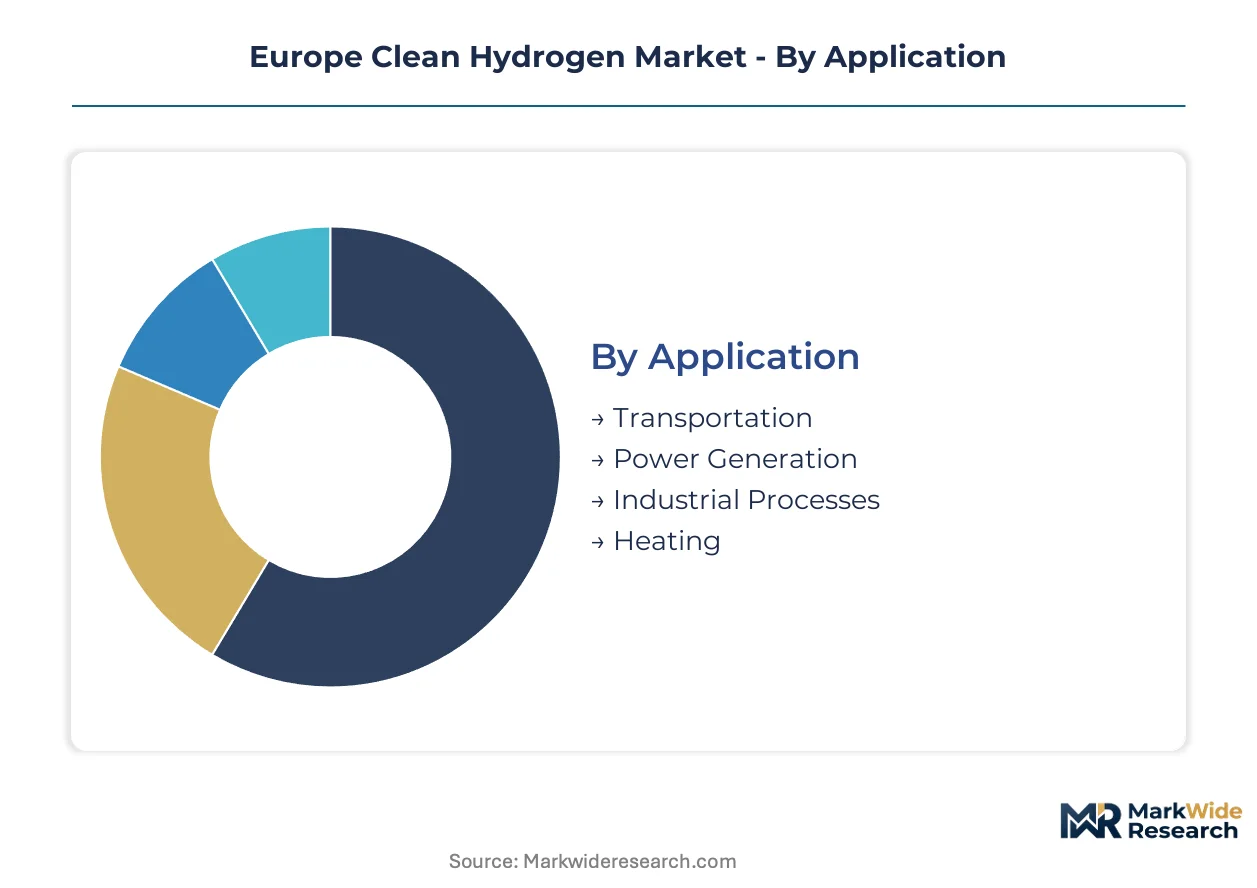
Segmentation in the Europe clean hydrogen market reveals how capital allocation and project timelines diverge across use cases and infrastructure choices. Each category carries distinct risk-return profiles that determine which developers secure financing and which technologies scale first.
Application:
Cycle times vary dramatically across applications, with industrial processes requiring decade-long asset commitments while transportation pilots turn over in 2-3 year phases.
- Industrial Processes:Ammonia synthesis, steel direct reduction, and refinery hydrocracking consume the largest molecule volumes. German chemical parks along the Rhine and Dutch refinery clusters are contracting for pipeline-ready supply before electrolyzer capacity ramps.
- Transportation:Fuel cell buses and heavy-duty trucking fleets operate on shorter procurement cycles. Hamburg and Rotterdam port authorities are piloting liquid hydrogen bunkering for maritime corridors.
- Power Generation:Grid-scale storage and gas turbine blending trials serve seasonal electricity balancing needs.
- Heating:District heating pilots and industrial furnace conversions remain early-stage with limited commercial offtake.
Industrial processes dominate installed base. Transportation is where expansion concentrates.
Technology:
Cost tiers separate mature alkaline systems from emerging alternatives, with capital intensity and efficiency trade-offs driving developer selection.
- Electrolysis:Alkaline systems serve gigawatt-scale installations with lowest capital cost per megawatt. PEM units offer modular deployment for distributed supply near German industrial clusters.
- Reforming:Steam methane reforming with carbon capture occupies the near-term cost floor. North Sea depleted reservoirs enable permanent CO2 storage for Dutch and Norwegian production hubs.
- Gasification:Biomass and waste feedstock pathways remain pre-commercial with limited project finance availability.
- Pyrolysis:Thermal decomposition of methane yields carbon black co-product but requires high-temperature reactor engineering advances.
Electrolysis commands capital deployment momentum. Reforming with carbon capture retains the lowest production cost position.
End User:
Customer type determines contract structure, with utilities seeking long-term supply security and manufacturing prioritizing price certainty.
- Manufacturing:Steel producers and chemical operators sign 10-15 year offtake agreements. ThyssenKrupp's Duisburg facility anchors demand for direct reduction feedstock.
- Energy Sector:Power utilities and gas network operators procure for blending and seasonal storage applications.
- Transportation Fleet:Bus operators and trucking consortiums purchase through fueling station networks with shorter contract horizons.
- Utilities:Grid operators and distribution companies focus on pipeline injection and storage facility utilization.
Manufacturing anchors contracted volume. Energy sector procurement is climbing the fastest.
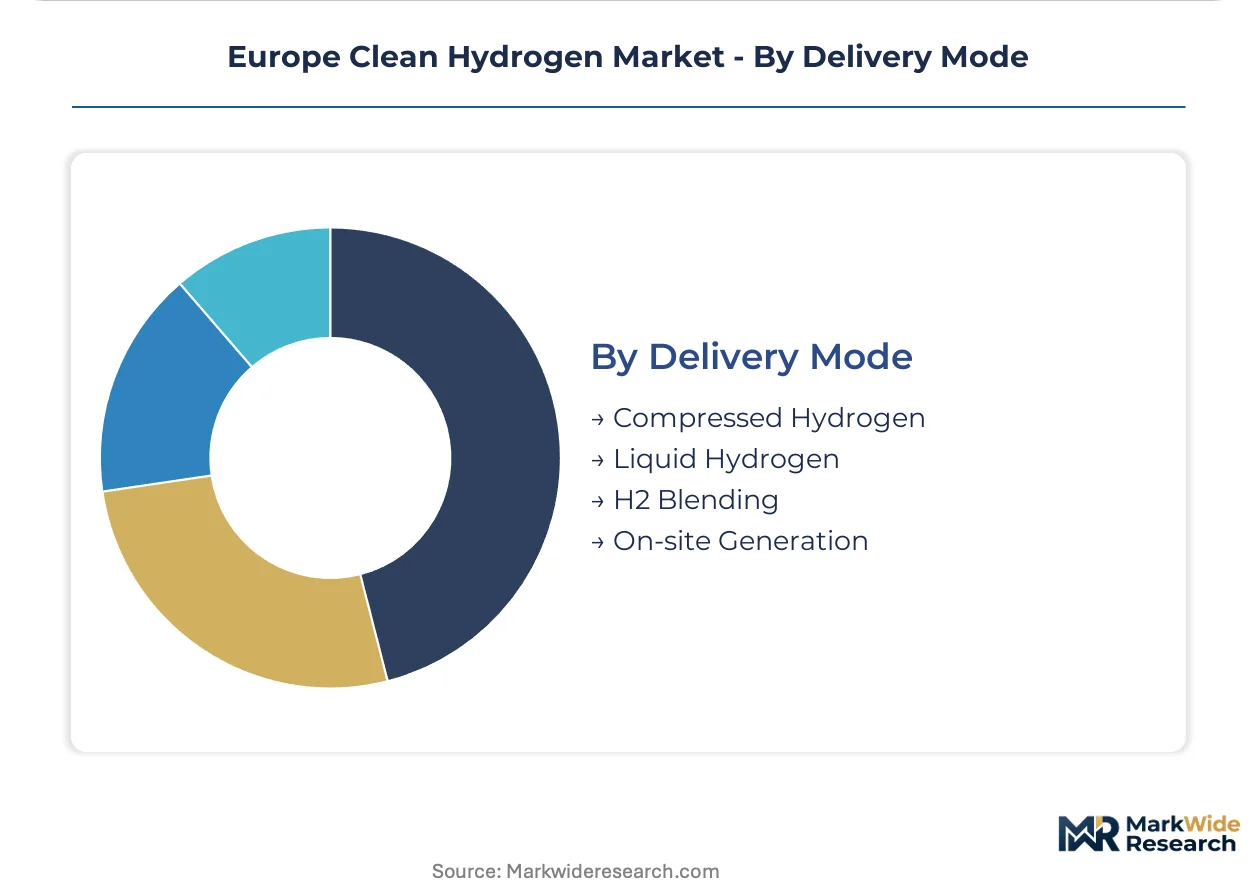
Delivery Mode:
Supply concentration shapes infrastructure investment, with compressed gas dominating near-term logistics and liquid hydrogen requiring specialized terminal development.
- Compressed Hydrogen:Tube trailer and pipeline networks serve industrial clusters within 200-kilometer radii. Germany's SoutH2 pipeline corridor connects production to offtake.
- Liquid Hydrogen:Cryogenic tanker and bunkering infrastructure enables maritime export and long-distance supply. Rotterdam's Maasvlakte terminal is expanding liquefaction capacity.
- H2 Blending:Natural gas network injection at 2-20% concentrations leverages existing pipeline assets.
- On-site Generation:Electrolyzer installations at point-of-use eliminate transport costs for remote industrial facilities.
Compressed hydrogen dominates installed logistics. Liquid hydrogen is where infrastructure investment concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Hydrogen Bank's auction mechanism is redirecting capital toward certified production pathways across member states. Industrial clusters in Germany, the Netherlands, and France are concentrating demand for pipeline-ready molecules ahead of electrolyzer capacity ramps.
Germany
Steel direct reduction facilities in Duisburg and chemical parks along the Rhine anchor molecule demand. The national hydrogen strategy accelerates pipeline corridor development connecting production to offtake. Hamburg's port authority pilots liquid hydrogen bunkering infrastructure for maritime export routes.
Netherlands
Refinery decarbonization mandates in Rotterdam and Amsterdam compress project timelines for pipeline-ready supply. The EU Renewable Energy Directive's delegated acts determine subsidy eligibility for imported molecules. The Maasvlakte terminal expands liquefaction capacity to serve North Sea shipping corridors.
France
Low-carbon electrolysis powered by existing nuclear fleets offers compliance pathways under draft EU taxonomy criteria. ECHA chemical safety frameworks constrain equipment standards and permitting timelines. The Normandy industrial cluster concentrates reforming with carbon capture projects targeting depleted reservoir storage.
Spain
Solar-powered electrolyzer installations in Andalusia and Extremadura leverage high-capacity-factor renewable resources. National hydrogen roadmaps align with EU Green Deal targets for renewable hydrogen of origin certification. Zaragoza's logistics corridor positions for compressed hydrogen delivery to French industrial markets.
Sweden
Steel producers in the Boden corridor pilot solid oxide electrolysis with direct blast furnace off-gas heat recovery. The Nordic energy market integration enables cross-border renewable electricity sourcing for electrolyzer operations. SSAB's fossil-free steel initiative anchors decade-long offtake commitments for green hydrogen feedstock.
Europe Clean Hydrogen Market Competitive Landscape
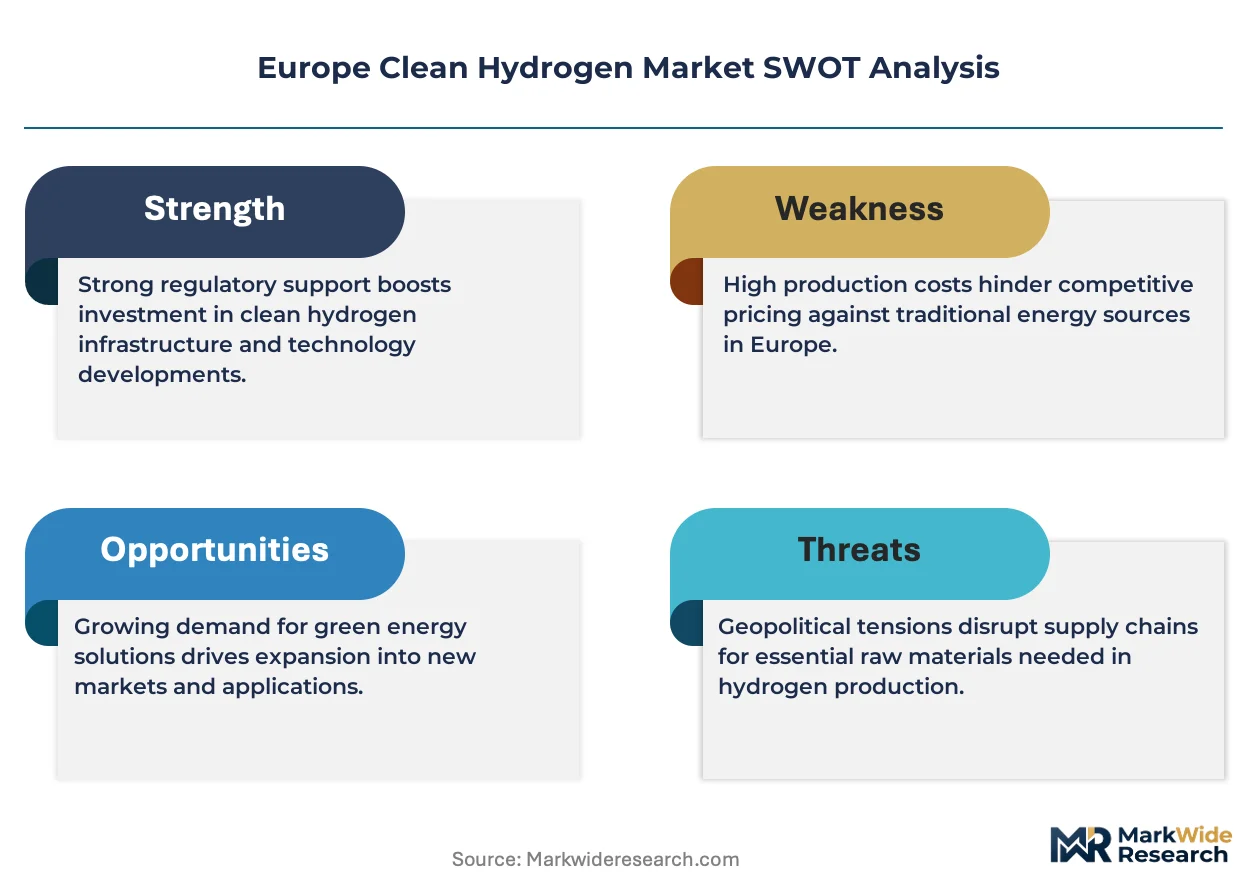
Channel-controlling players compete with product-specialist players for contract volume in a market restructuring around balance-sheet depth. Industrial gas incumbents leverage existing pipeline and storage infrastructure to anchor large-scale electrolyzer deployments. Equipment manufacturers compete on modular system architectures versus gigawatt-scale engineering integration. Dominant competitive moves include strategic partnerships for captive renewable generation and vertical integration into offtake contracting.
Within the industrial gas incumbent tier, Linde PLC and Air Liquide occupy positions shaped by existing infrastructure control. Among specialized electrolyzer manufacturers, Nel ASA and ITM Power exemplify the equipment-specialist archetype competing on technology differentiation. ThyssenKrupp Nucera represents the engineering-integrated model anchored in process industry expertise.
| Leading Market Players |
|---|
| Linde PLC |
| Air Liquide |
| Air Products |
| Nel ASA |
| Engie SA |
| Uniper SE |
| ThyssenKrupp Nucera |
| ITM Power |
| McPhy Energy |
| Others |
Pricing and Supply Chain Analysis
Stack manufacturing concentration in Norway and Germany feeds directly into margin capture by electrolyzer system integrators rather than component suppliers. Renewable electricity contract structures determine whether project developers retain pricing power or pass through cost volatility to industrial offtakers.
Pricing Analysis
Certification level under the EU Renewable Energy Directive's delegated acts creates the primary spread between bankable and speculative supply. Contract-based long-term offtake agreements dominate, with pricing stratifying across premium certified renewable, standard low-carbon, and economy grey hydrogen tiers. Cost compression in alkaline electrolyzer stacks is intensifying because Chinese equipment vendors are expanding European distribution. Steel producers and ammonia synthesizers exhibit lowest price sensitivity; trucking fleet operators show highest.
Supply Chain Analysis
Export control regimes targeting high-pressure electrolyzer membranes and specialized iridium catalyst coatings limit technology flows from European vendors to Asian manufacturing partners. Supply concentrates in Germany, Norway, and China for stack assembly, with platinum group metal sourcing drawing from South Africa and Russia. Single-source vulnerability sits with iridium supply for PEM anode coatings. Distribution runs through integrated project developers with captive renewable generation and pipeline infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU Hydrogen Bank's auction mechanism represents a regulatory inflection that separates bankable projects from speculative capacity announcements, concentrating returns among developers with balance-sheet depth.
For Market Incumbents: Harden positions by securing exclusive pipeline corridor access along the Rhine and SoutH2 routes before electrolyzer capacity saturates industrial clusters. Deepen backward integration into offshore wind development to lock in renewable electricity supply. Invest in EU taxonomy-compliant certification infrastructure to defend margin position against emerging reforming-with-carbon-capture competitors. For New Entrants and Emerging Players: Build out modular PEM electrolyzer deployments for distributed supply to mid-sized chemical operators bypassing pipeline queue delays. Target Spanish solar-powered production hubs where land and irradiance costs enable competitive molecule pricing. Pursue joint development agreements with port authorities seeking liquid hydrogen bunkering infrastructure as the go-to-market angle. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed electrolyzer manufacturers lacking integrated offtake contracting capabilities. Five-to-ten year viability hinges on securing decade-long purchase agreements with steel direct reduction facilities. Watch for finalization of cross-border hydrogen origin verification methodology as the signal indicating which project pipelines will access EU Hydrogen Bank premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Hydrogen Purchase Agreement | ThyssenKrupp's Duisburg facility anchors 10-15 year offtake commitments that de-risk project finance. |
| Backward Integration into Renewable Generation | Developers with captive offshore wind assets eliminate power purchase agreement pricing uncertainty. |
| Pipeline Corridor Development | Germany's SoutH2 route connects electrolyzer production to Rotterdam and Hamburg industrial clusters. |
| EU Taxonomy Certification Investment | Compliance with delegated acts under the Renewable Energy Directive determines subsidy eligibility. |
| Liquid Hydrogen Terminal Expansion | Rotterdam's Maasvlakte facility enables maritime export corridors for North Sea shipping routes. |
Research Methodology
Initial hypotheses were tested against primary input from electrolyzer project developers, utility planning officers, EPC contractors, and industrial offtake procurement leads and refined through secondary validation. Bottom-up capacity announcements were cross-referenced with top-down policy target trajectories from EU Green Deal implementation documents and IEA hydrogen project databases. Customs data on electrolyzer stack imports and FERC-style regulatory filings on grid interconnection queues provided supply-side triangulation.
Demand-supply balance modeling across the projection horizon incorporated technology segmentation by alkaline, PEM, and solid oxide systems alongside delivery mode differentiation between compressed pipeline and liquid hydrogen logistics. CAGRs were derived from project finance commitment timelines and electrolyzer manufacturing capacity expansion announcements. Modeled inputs included renewable electricity curtailment rates and steel sector direct reduction facility conversion schedules.
Stress conditions across renewable power price volatility, electrolyzer stack delivery delays, and pipeline certification timeline slippage were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions on subsidy auction participation rates and industrial offtake contract execution. Material shifts in EU delegated act finalization or North Sea carbon storage licensing would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydrogen Energy
Liquid Hydrogen Market
Hydrogen Energy
Solar Hydrogen Panel Market
Hydrogen Energy
Green Energy Hydrogen Production System Market
Hydrogen Energy
India Hydrogen Market
Hydrogen Energy
On-Site Hydrogen Generator Market
Hydrogen Energy
United States Hydrogen Generation Market
Hydrogen Energy
Black Hydrogen Market
Hydrogen Energy
Clean Hydrogen Market
Hydrogen Energy
Hydrogen Energy Electrolyzer Market
Hydrogen Energy
Asia Pacific Liquid Hydrogen Market
Hydrogen Energy
Hydrogen Purification Market
Hydrogen Energy
High-Pressure Hydrogen Tanks Market
Hydrogen Energy
Hydrogen Market
Hydrogen Energy
Hydrogen Production Electrolyser Market
Hydrogen Energy
Hydrogen Composite Tanks Market
Hydrogen Energy
Hydrogen Energy Storage Market