
 US Hydrogen Fueling Station Market | 2026-2036
US Hydrogen Fueling Station Market Size, Share, and Industry Trends Forecast 2026-2036
US Hydrogen Fueling Station Market Insights
Composite pressure vessels is shifting toward Type IV carbon-fiber-wrapped tanks in US hydrogen fueling station builds, cutting weight and extending cycle life versus metal alternatives. Air Products and Chemicals leverages its Gulf Coast hydrogen pipeline network to anchor supply security for station developers. Nel Hydrogen specializes in containerized electrolyzer systems that slash installation timelines. FirstElement Fuel dominates California's I-5 corridor with the highest station count of any private operator in the state.
A hydrogen fueling station compresses, stores, and dispenses gaseous or liquid hydrogen at pressures reaching 700 bar for passenger vehicles or 350 bar for heavy-duty transport, incorporating pre-cooling systems to manage thermal spikes during rapid fills. The primary commercial purpose is enabling zero-emission mobility for fuel cell electric vehicles where battery-electric architectures face weight or range constraints. Highway installations currently lead capital deployment as long-haul trucking electrification demands corridor coverage, while electrolyzer-based fueling technology represents the fastest-growing segment as renewable hydrogen mandates harden. Small-scale urban stations remain margin-constrained due to real estate costs and utilization rates below commercial thresholds.
The Department of Transportation's National Electric Vehicle Infrastructure program standards now incorporate hydrogen corridor planning, while OSHA's 29 CFR 1910.103 hydrogen handling rules govern worker safety protocols and station design. EPA greenhouse gas standards for heavy-duty vehicles indirectly pressure fleet operators toward hydrogen adoption by tightening diesel compliance costs. State energy offices must weigh infrastructure subsidy allocation between battery-electric and hydrogen pathways as congressional funding windows narrow.
Market Dynamics
The Inflation Reduction Act's hydrogen production tax credits are compressing project timelines and redirecting capital flows toward electrolyzer-based station architectures, fundamentally altering developer economics across California's freight corridors.
Growth Catalysts
- Advanced Clean Trucks regulation:California Air Resources Board mandates force escalating zero-emission heavy-duty vehicle sales, creating guaranteed demand anchors for corridor hydrogen infrastructure.
- Containerized electrolyzer systems:Modular fabrication slashing installation timelines is accelerating deployment velocity and reducing site-specific engineering costs.
- Texas and Louisiana:Concentrated Gulf Coast hydrogen pipeline networks provide pre-built feedstock access that de-risks supply security for station developers.
Market Restraints
- Carbon fiber supply concentration:Type IV pressure vessel manufacturing depends on limited North American carbon fiber capacity, creating input bottlenecks for station builds.
- OSHA 29 CFR 1910.103:Stringent hydrogen handling protocols extend permitting timelines and inflate safety system capital requirements.
- Battery-electric substitution:Falling lithium-ion costs and expanding DC fast-charging networks capture light-duty and short-haul segments that might otherwise adopt fuel cells.
Strategic Opportunities
- Texas Triangle freight hubs:Underpenetrated corridors connecting Houston, Dallas-Fort Worth, and San Antonio offer first-mover positioning ahead of federal hydrogen hub designations.
- Renewable hydrogen mandates:State-level clean fuel standards in Oregon and Washington create regulatory pull for electrolyzer-based stations with documented renewable sourcing.
- On-site electrolyzer + solar pairing:Technology convergence enables behind-the-meter production that bypasses pipeline dependency and captures investment tax credits.
Industry Challenges
- Hydrogen-specific technician certification:Compressed gas systems maintenance and cryogenic handling require specialized training pipelines that community colleges have not yet scaled.
- Interconnection queue delays:Electrolyzer-based stations face 18-36 month utility interconnection timelines that misalign with fleet operator vehicle delivery schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Hydrogen Fueling Station Market |
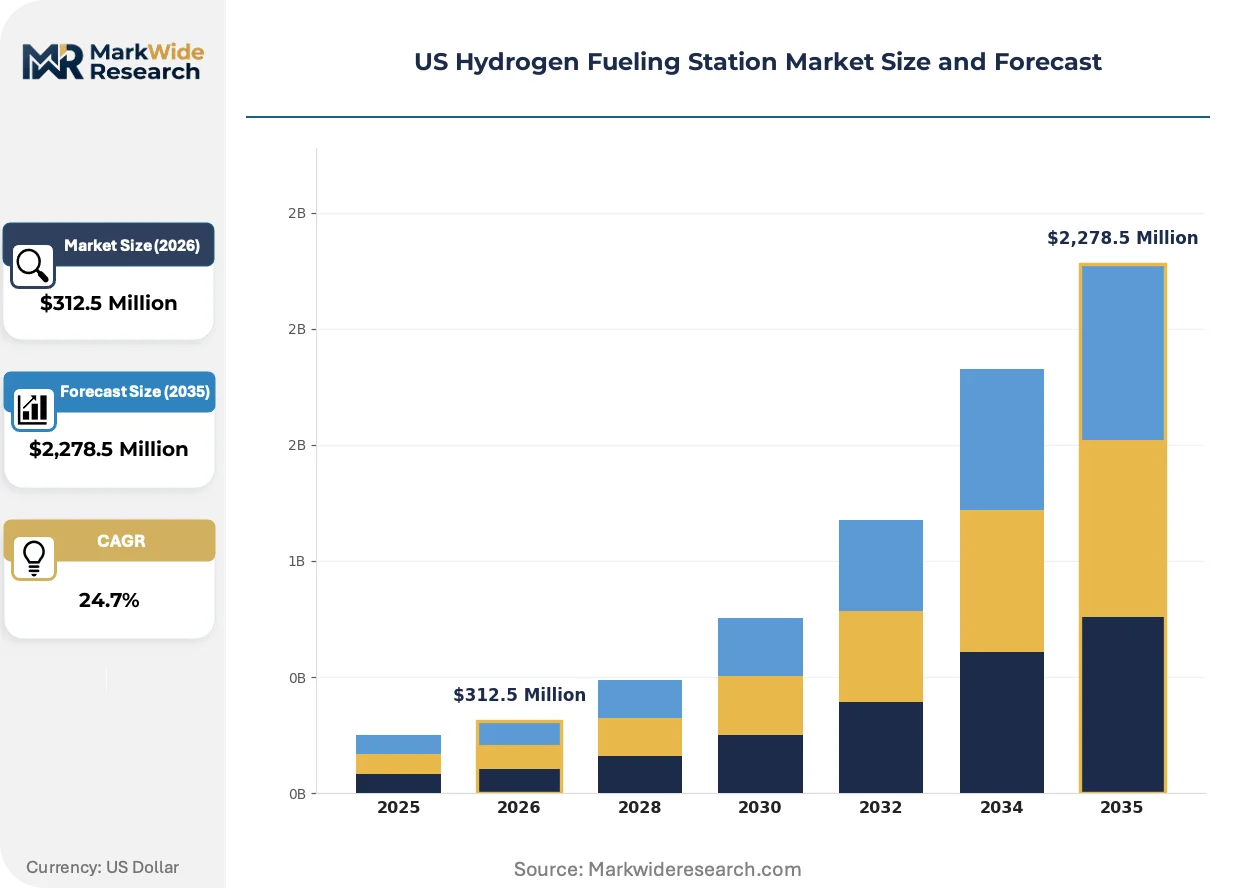
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $2,278.5 Million |
| CAGR (2026 – 2036) | 24.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Installation Type: Urban, Suburban, Highway, Commercial, Public Facilities Station Capacity: Small Scale, Medium Scale, Large Scale, Ultra Large Scale Fueling Technology: Electrolyzer-Based, Compressed Gas, Liquid Hydrogen, Onsite Production End User: Fuel Cell Vehicles, Public Transit, Fleet Vehicles, Industrial Equipment |
| Companies Covered | Air Liquide, Air Products and Chemicals, Linde, Nel Hydrogen, Plug Power, Cummins, Chart Industries, FirstElement Fuel, H2 Energy Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Hydrogen Fueling Station Market Trends and Innovations
Station architecture is pivoting from centralized pipeline dependency toward distributed on-site generation, with implications for equipment sourcing, real estate requirements, and operator business models.
Containerized proton exchange membrane electrolyzers are decentralizing hydrogen supply by enabling modular, skid-mounted production at fueling sites. Fleet operators with captive demand are adopting these systems to lock in fuel costs and qualify for production tax credits. This shift is compressing the addressable market for pipeline-dependent station developers while expanding the vendor base for electrolyzer OEMs.
EPA greenhouse gas standards for heavy-duty vehicles are tightening compliance costs for diesel fleets, indirectly accelerating hydrogen infrastructure investment. The regulatory pressure concentrates on long-haul trucking segments where battery weight penalties erode payload economics. California's freight corridors are responding with accelerated station permitting and consolidated procurement consortia.
Acquisition patterns among fleet operators are consolidating around multi-year hydrogen supply agreements with take-or-pay structures. Traditional spot-fueling arrangements are yielding to contracted volumes that underpin project finance for station developers. This behavioral shift is most visible among drayage and regional haul operators in the Ports of Los Angeles and Long Beach ecosystem.
US Hydrogen Fueling Station Market Segmentation
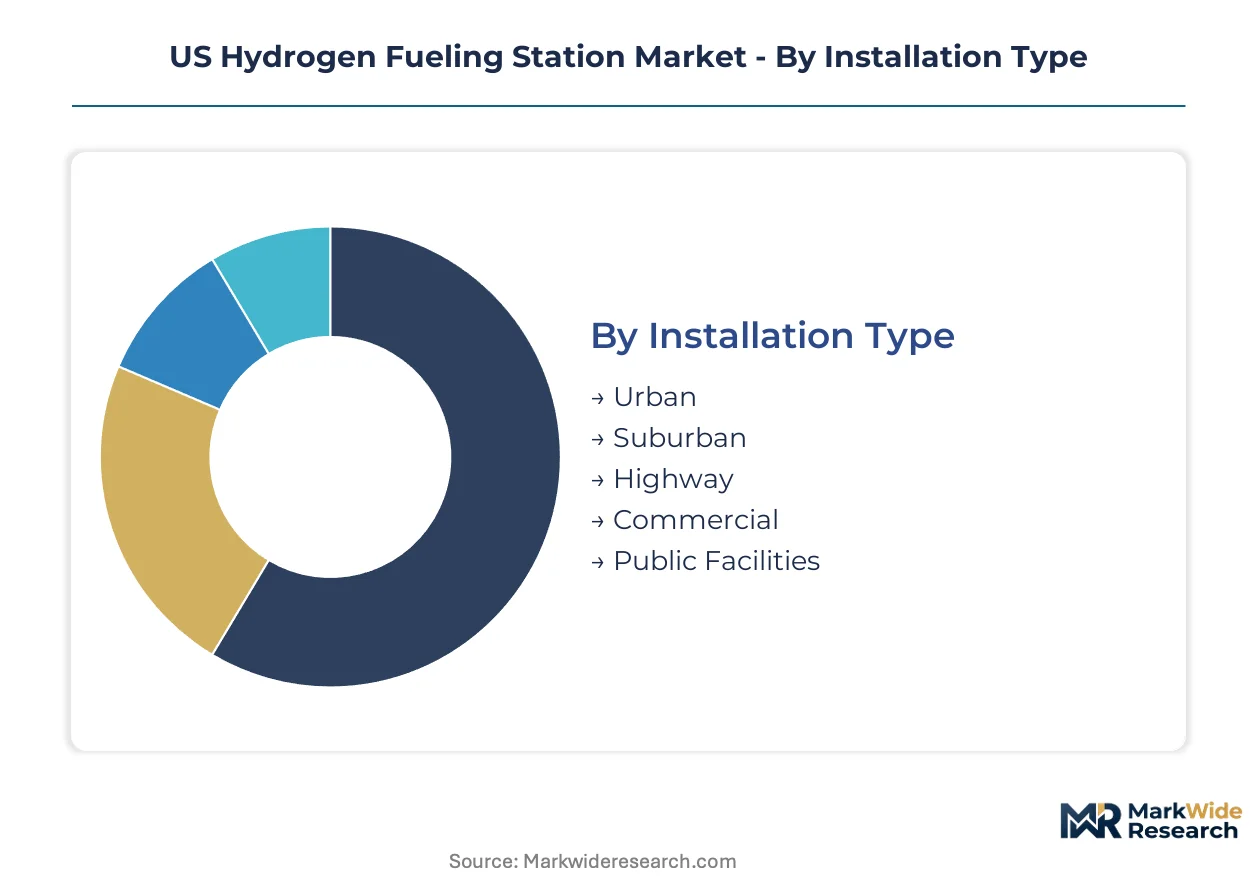
Segmentation reveals how capital allocation diverges between corridor-scale highway builds and constrained urban sites. Each dimension exposes distinct equipment specifications, permitting pathways, and utilization economics that shape developer returns.
Installation Type:
Standalone highway installations anchor fleet operator demand, while embedded urban systems face real estate and throughput constraints that compress margins.
- Highway:These corridor installations compress hydrogen to 700 bar for passenger vehicles and 350 bar for heavy-duty trucks across multiple dispensing positions. California's I-5 freight corridor concentrates the preponderance of current deployments as the California Air Resources Board enforces escalating zero-emission truck sales mandates.
- Urban:Embedded within dense metropolitan fabric, these stations face land scarcity and below-threshold utilization rates that challenge commercial viability. Real estate costs in Los Angeles and San Francisco metropolitan areas consume disproportionate capital allocations relative to throughput potential.
- Suburban:Peripheral locations balance land availability with commuter corridor access, typically serving mixed passenger and light commercial demand.
- Commercial:Captive installations serving single-fleet operations with dedicated throughput agreements and simplified permitting pathways.
- Public Facilities:Government-owned sites prioritizing visibility and accessibility over utilization optimization, often subsidized through state energy office programs.
Volume placements concentrate in Highway; the faster expansion belongs to Commercial.
Station Capacity:
Capital intensity scales non-linearly with throughput design, creating tiered entry barriers that separate municipal pilots from private corridor infrastructure.
- Large Scale:Configured for 1,000+ kg daily throughput with multiple compression trains and redundant storage arrays. Texas Triangle freight corridors between Houston, Dallas-Fort Worth, and San Antonio attract this format as fleet operators consolidate procurement.
- Medium Scale:Daily capacity of 200-500 kg serves regional haul and drayage operations with modular expansion pathways. These systems dominate California's port ecosystem where the Ports of Los Angeles and Long Beach drive hydrogen adoption.
- Small Scale:Sub-200 kg installations for demonstration projects and captive fleet pilots with limited commercial ambition.
- Ultra Large Scale:Hub configurations exceeding 2,000 kg daily with integrated liquefaction or pipeline interconnection, requiring consolidated offtake agreements to underwrite capital deployment.
Large Scale captures dominant capital flows; Ultra Large Scale posts the steepest expansion trajectory as hub-and-spoke architectures mature.
Fueling Technology:
Technology selection determines feedstock security, carbon intensity accounting, and eligibility for production tax credits under the Inflation Reduction Act.
- Electrolyzer-Based:Proton exchange membrane systems enable modular, behind-the-meter hydrogen production with documented renewable sourcing. Oregon and Washington state-level clean fuel standards create regulatory pull for this architecture.
- Onsite Production:Integrated electrolyzer or reformer systems eliminate logistics costs and capture investment tax credits through solar pairing.
- Compressed Gas:Pipeline or tube-trailer delivery of gaseous hydrogen at 350-700 bar dispensing pressure, leveraging existing Gulf Coast hydrogen pipeline networks.
- Liquid Hydrogen:Cryogenic storage and vaporization systems for high-throughput applications with established liquefaction infrastructure.
Compressed Gas retains volume leadership; Electrolyzer-Based gains share fastest as renewable hydrogen mandates harden.
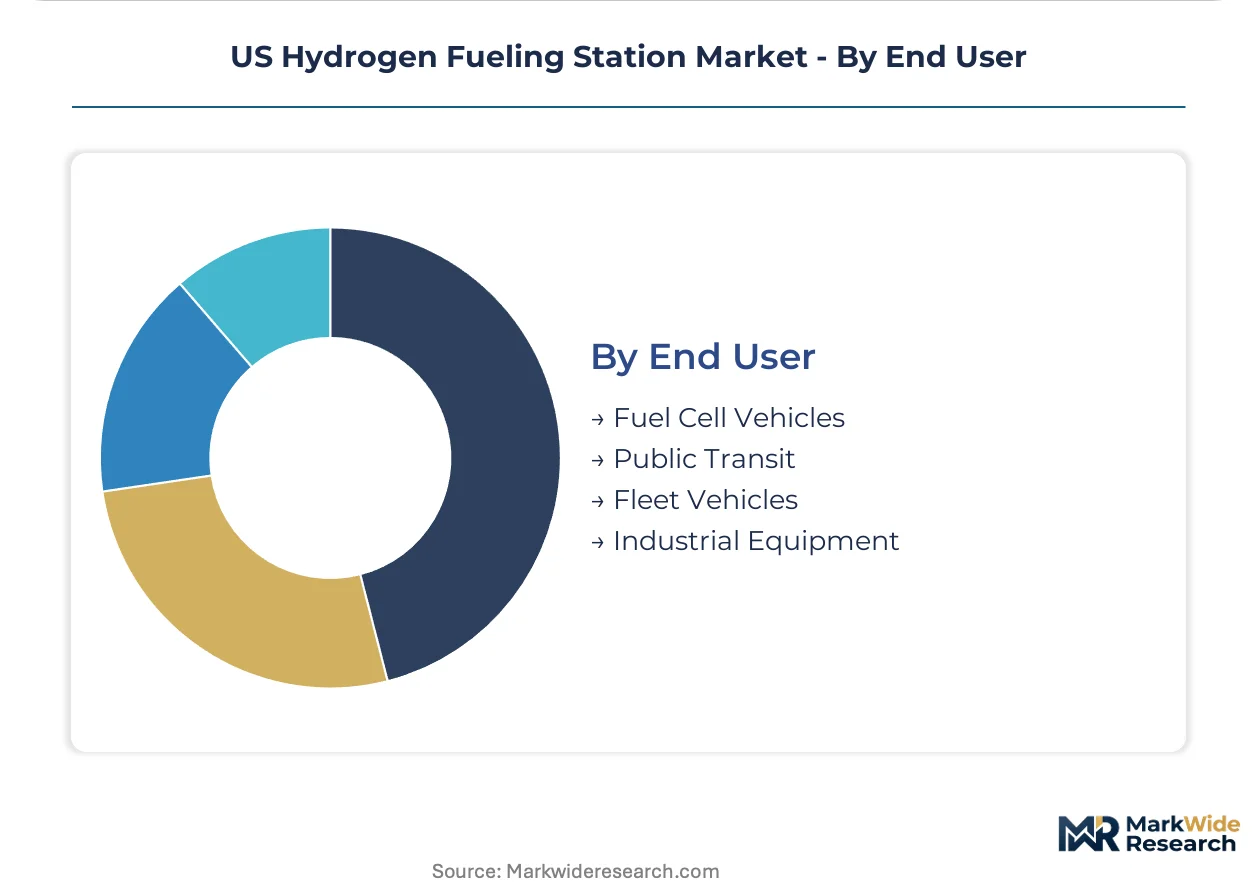
End User:
Demand concentration varies sharply by payload requirements, duty cycles, and regulatory exposure across vehicle categories.
- Fleet Vehicles:Heavy-duty trucks and regional haul operators with predictable route structures and centralized refueling requirements. EPA greenhouse gas standards for heavy-duty vehicles tighten diesel compliance costs, redirecting capital toward hydrogen-compatible fleet refresh cycles.
- Fuel Cell Vehicles:Passenger cars and light trucks with dispersed demand patterns that strain station utilization economics outside corridor concentrations.
- Public Transit:Municipal bus operators with captive depot fueling and simplified infrastructure requirements.
- Industrial Equipment:Forklifts, port handling equipment, and stationary power applications with localized demand anchors.
Fleet Vehicles anchor throughput commitments; Public Transit shows the most rapid deployment velocity as municipal zero-emission mandates accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
California concentrates over 80% of US hydrogen fueling station deployments as the California Air Resources Board enforces zero-emission mandates through the Advanced Clean Trucks regulation. Fleet operators anchor demand along freight corridors connecting major port complexes to inland distribution hubs.
California
The California Air Resources Board's Advanced Clean Trucks regulation mandates escalating zero-emission heavy-duty vehicle sales through 2035. The Ports of Los Angeles and Long Beach drive hydrogen adoption through drayage electrification requirements and consolidated procurement consortia. FirstElement Fuel dominates the I-5 corridor with the highest station count of any private operator in the state.
Texas
The Texas Triangle connecting Houston, Dallas-Fort Worth, and San Antonio attracts large-scale station investments as fleet operators consolidate procurement around Gulf Coast hydrogen pipeline access. The state's energy office weighs infrastructure subsidy allocation between battery-electric and hydrogen pathways as federal funding windows narrow. Houston anchors pre-built feedstock security for station developers leveraging Air Products and Chemicals' pipeline network.
Pacific Northwest
Oregon and Washington state-level clean fuel standards create regulatory pull for electrolyzer-based stations with documented renewable sourcing. Containerized proton exchange membrane systems enable modular, behind-the-meter hydrogen production that qualifies for production tax credits. Seattle-Tacoma port complexes are responding with accelerated station permitting for drayage operators.
Southwest
Arizona and New Mexico position for first-mover advantage ahead of federal hydrogen hub designations targeting interstate freight corridors. The region's solar irradiance supports on-site electrolyzer pairing that captures investment tax credits through behind-the-meter production. Phoenix anchors emerging demand from regional haul operators seeking corridor coverage between California and Texas markets.
Mid-Atlantic
The Northeast Corridor from Washington DC through Philadelphia to New York Metro faces interconnection queue delays of 18-36 months that misalign electrolyzer-based station timelines with fleet operator vehicle delivery schedules. State energy offices in New Jersey and New York evaluate hydrogen corridor planning under Department of Transportation National Electric Vehicle Infrastructure program standards. Port Newark-Elizabeth drives pilot deployments for terminal tractor electrification.
US Hydrogen Fueling Station Market Competitive Landscape
Strategic partnerships dominate the current landscape as equipment suppliers anchor supply security for station developers and fleet operators lock in multi-year hydrogen supply agreements. The vendor base concentrates around three tiers: integrated industrial gas majors with pipeline networks, modular electrolyzer specialists with containerized systems, and regional fueling operators with corridor-specific real estate positions. Two strategic archetypes define competitive positioning: pipeline-dependent developers leveraging pre-built feedstock access and distributed generation advocates capturing production tax credits through on-site electrolysis. Competitive moves center on capacity expansion along freight corridors and vertical integration into captive hydrogen production.
Within the industrial gas major tier, Air Products and Chemicals, Air Liquide, and Linde occupy positions anchored by Gulf Coast hydrogen pipeline infrastructure and liquefaction capabilities. These companies exemplify the pipeline-dependent archetype that de-risks supply security for station developers. Nel Hydrogen and Plug Power represent the modular electrolyzer specialist tier, with containerized systems that slash installation timelines and enable distributed generation architectures qualifying for Inflation Reduction Act production tax credits.
| Leading Market Players |
|---|
| Air Liquide |
| Air Products and Chemicals |
| Linde |
| Nel Hydrogen |
| Plug Power |
| Cummins |
| Chart Industries |
| FirstElement Fuel |
| H2 Energy Group |
| Others |
Pricing and Supply Chain Analysis
Carbon fiber composite index movements cascade through hydrogen fueling station equipment tiers, compressing margins on Type IV pressure vessels while amplifying cost premiums for domestic-fabricated alternatives under Buy America compliance thresholds.
Pricing Analysis
Volume throughput separates margin tiers across the station landscape. Large-scale corridor installations command contract-based long-term offtake structures with take-or-pay provisions that insulate developers from spot-price volatility, while small-scale urban sites face commodity-exposed tube-trailer delivery costs that erode returns. Price differentiation rests on certification grade—OSHA 29 CFR 1910.103 compliance systems carry 15-25% capital premiums—and volume scale, with fleet operators securing preferential rates through consolidated procurement consortia. Cost compression in medium-scale installations is intensifying because electrolyzer OEMs are modularizing proton exchange membrane systems to capture Inflation Reduction Act production tax credits. Public transit agencies exhibit the highest price sensitivity due to municipal budget constraints, whereas captive commercial fleet operators demonstrate the lowest sensitivity given payload economics that favor hydrogen over battery-electric alternatives.
Supply Chain Analysis
Domestic-content mandates under the Inflation Reduction Act are reshaping sourcing patterns for electrolyzer stacks and pressure vessel fabrication, pressuring developers to certify North American assembly thresholds. Manufacturing concentration centers on Japan, South Korea, and Germany for high-grade carbon fiber precursor, while China dominates rare earth processing for electrolyzer catalysts. Raw material dependencies include carbon fiber tow, titanium-lined polymer liners, and iridium-based catalyst coatings. Single-source vulnerability in carbon fiber supply creates exposure to aerospace sector demand spikes that divert capacity from hydrogen applications. Distribution runs through specialized cryogenic logistics providers and tube-trailer operators with hazardous materials certifications, limiting downstream channel alternatives for remote corridor deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
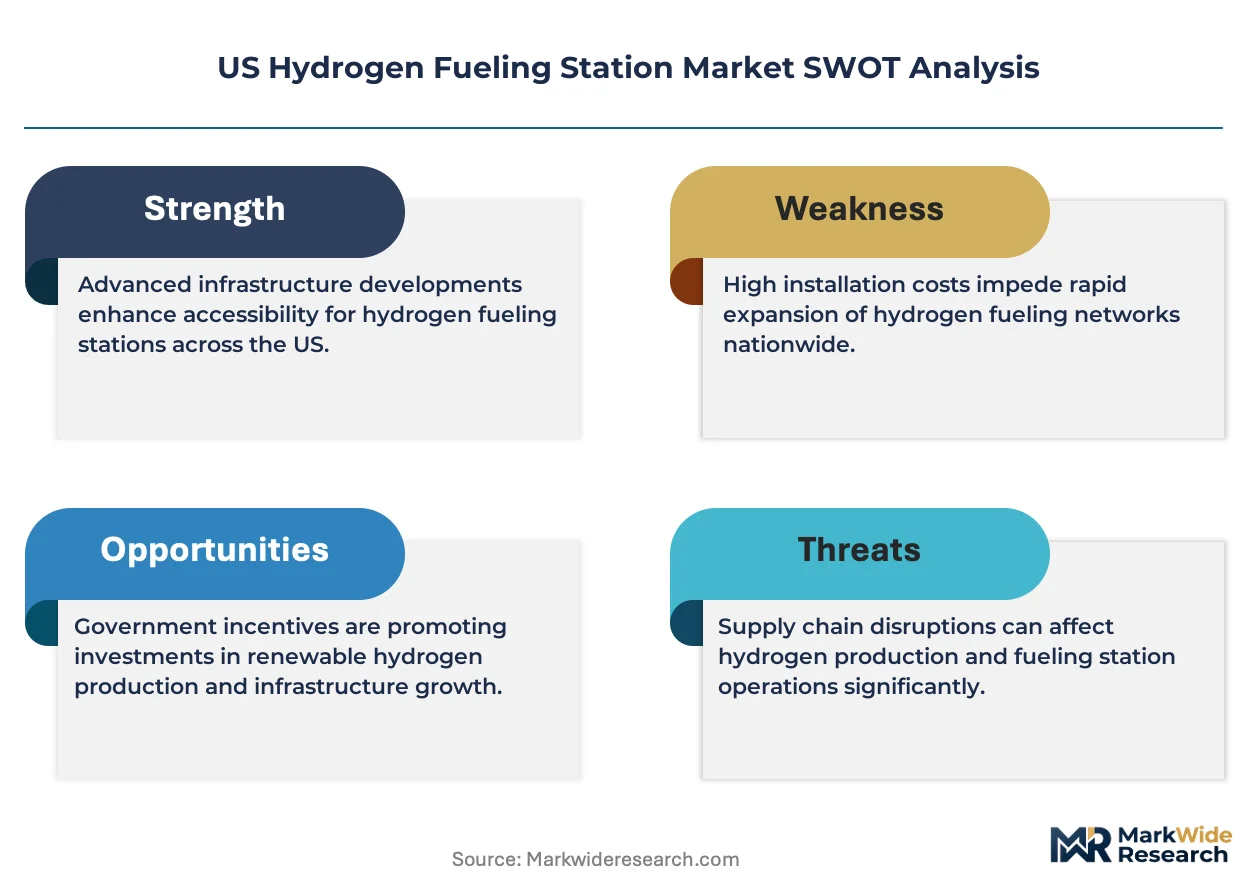
The US hydrogen fueling station market is becoming a vertical-integration race as developers pursue captive electrolyzer production to capture production tax credits and lock in feedstock cost predictability against pipeline tariff volatility.
For Market Incumbents: Deepen backward integration into electrolyzer manufacturing or secure exclusive offtake from Gulf Coast hydrogen pipeline networks to defend against modular electrolyzer specialists displacing pipeline-dependent architectures. Air Products and Chemicals' pipeline network advantage faces erosion from containerized proton exchange membrane systems that slash installation timelines; incumbents should consolidate corridor real estate positions in the Texas Triangle before federal hydrogen hub designations accelerate. Certification investment in OSHA 29 CFR 1910.103 compliance systems preserves premium positioning against safety-capital-constrained entrants. For New Entrants and Emerging Players: Fleet operators with captive demand represent the most penetrable entry channel, particularly drayage and regional haul operators in the Ports of Los Angeles and Long Beach ecosystem seeking to decouple from volatile diesel compliance costs. The Texas Triangle connecting Houston, Dallas-Fort Worth, and San Antonio offers white-space positioning ahead of incumbent corridor saturation. A go-to-market angle pairing containerized electrolyzer systems with solar photovoltaic arrays enables behind-the-meter production that qualifies for investment tax credits while bypassing interconnection queue delays. For Investors and Strategic Acquirers: Distressed-cycle entries favor electrolyzer OEMs with modular product architectures in the Pacific Northwest, where Oregon and Washington clean fuel standards create regulatory pull for renewable hydrogen documentation. Long-term viability over the next decade hinges on demonstrated ability to secure utility interconnection agreements ahead of fleet operator vehicle delivery schedules. The signal to watch is consolidation patterns among fleet operators around multi-year hydrogen supply agreements with take-or-pay structures, which underpin project finance capacity for station developers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Electrolyzer Manufacturing | Captive production secures Inflation Reduction Act tax credits and insulates against feedstock price volatility. |
| Corridor Real Estate Consolidation | Texas Triangle positioning ahead of federal hydrogen hub designations locks in first-mover freight corridor access. |
| Containerized System Modularization | Skid-mounted proton exchange membrane electrolyzers compress installation timelines from months to weeks. |
| Multi-Year Supply Agreement Structuring | Take-or-pay contracts with fleet operators underpin project finance for large-scale station deployments. |
| Solar-Electrolyzer Pairing Deployment | Behind-the-meter production captures investment tax credits and bypasses utility interconnection queue delays. |
Research Methodology
Multi-period observation of station deployment permits, electrolyzer installation timelines, and fleet operator procurement patterns anchored the trend analysis, supplemented by interviews with hydrogen fueling station developers, electrolyzer OEM technical directors, fleet operator sustainability officers, and California Air Resources Board regulatory staff. Secondary validation drew from Department of Energy hydrogen program databases, FERC interconnection queue filings, EPA heavy-duty vehicle greenhouse gas standard dockets, and state energy office infrastructure subsidy disclosures. Bottom-up triangulation across equipment shipment records and top-down reconciliation against capital deployment announcements ensured cross-verification of market sizing.
Segment-weighting approaches modeled installation type, station capacity tier, fueling technology architecture, and end-user category across the projection horizon, with each dimension assigned elasticity coefficients derived from historical deployment velocity and regulatory mandate schedules. CAGRs were computed from fitted growth curves calibrated to fleet operator vehicle delivery timelines and infrastructure subsidy program windows. Industry-specific forecast inputs included California Air Resources Board Advanced Clean Trucks regulation compliance trajectories and Inflation Reduction Act hydrogen production tax credit uptake assumptions.
Caveats apply where utility interconnection queue delays, carbon fiber supply bottlenecks, or battery-electric technology cost curves could materially shift the outlook for electrolyzer-based station economics. Forecasts reflect assumptions about regulatory continuity and production tax credit availability that remain exposed to congressional appropriation cycles. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Hydrogen Energy
PEM Water Electrolytic Hydrogen Production System Market
Hydrogen Energy
North America Liquid Hydrogen Market
Hydrogen Energy
Hydrogen ICE Ignition System Platforms Market
Hydrogen Energy
Hydrogen-Cooled Turbine Generator Market
Hydrogen Energy
Hydrogen Energy Electrolyzer Market
Hydrogen Energy
Europe Hydrogen Generation Market
Hydrogen Energy
Hydrogen Liquefaction Unit Market
Hydrogen Energy
Hydrogen Market
Hydrogen Energy
Global Hydrogen Electrolyzers Market
Hydrogen Energy
Hydrogen Generator Market
Hydrogen Energy
USA Hydrogen Electrolyzer Market
Hydrogen Energy
India Hydrogen Market
Hydrogen Energy
Liquid Hydrogen Market
Hydrogen Energy
Green Energy Hydrogen Production System Market
Hydrogen Energy
Hydrogen Gas Generator Market
Hydrogen Energy
Green Hydrogen Dispensing Equipment Market