
 Edible Packaging Market | 2026-2036
Edible Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Edible Packaging Market Intelligence
The European Union's Single-Use Plastics Directive is consolidating the market by creating a clear commercial advantage for non-plastic alternatives. Notpla leverages its proprietary seaweed-based technology to target beverage and sauce applications. MonoSol specializes in water-soluble polymer films for food ingredients and detergents. Meanwhile, Xampla differentiates with its plant protein-based materials, which are fully biodegradable without leaving microplastics.
Edible packaging comprises materials, typically derived from natural polymers, that are safe for human consumption and designed to be eaten with the product. These materials, such as polysaccharide-based films or protein coatings, function as a primary barrier to moisture, oxygen, or microbial contamination, extending shelf life. Polysaccharides, including starches and alginates, represent the dominant material type due to their film-forming properties and cost-effectiveness. Within applications, food preservation remains the largest segment, while nutrient delivery in capsules is an area of high-margin innovation for nutraceutical manufacturers.
Market access requires compliance with food contact material regulations set by bodies like the US FDA and the European Food Safety Authority (EFSA). These agencies scrutinize the safety of ingredients and production processes to ensure consumer protection. Stakeholder success will depend on navigating the complex food-grade certification process while scaling production to compete with conventional packaging on cost.
Market Dynamics
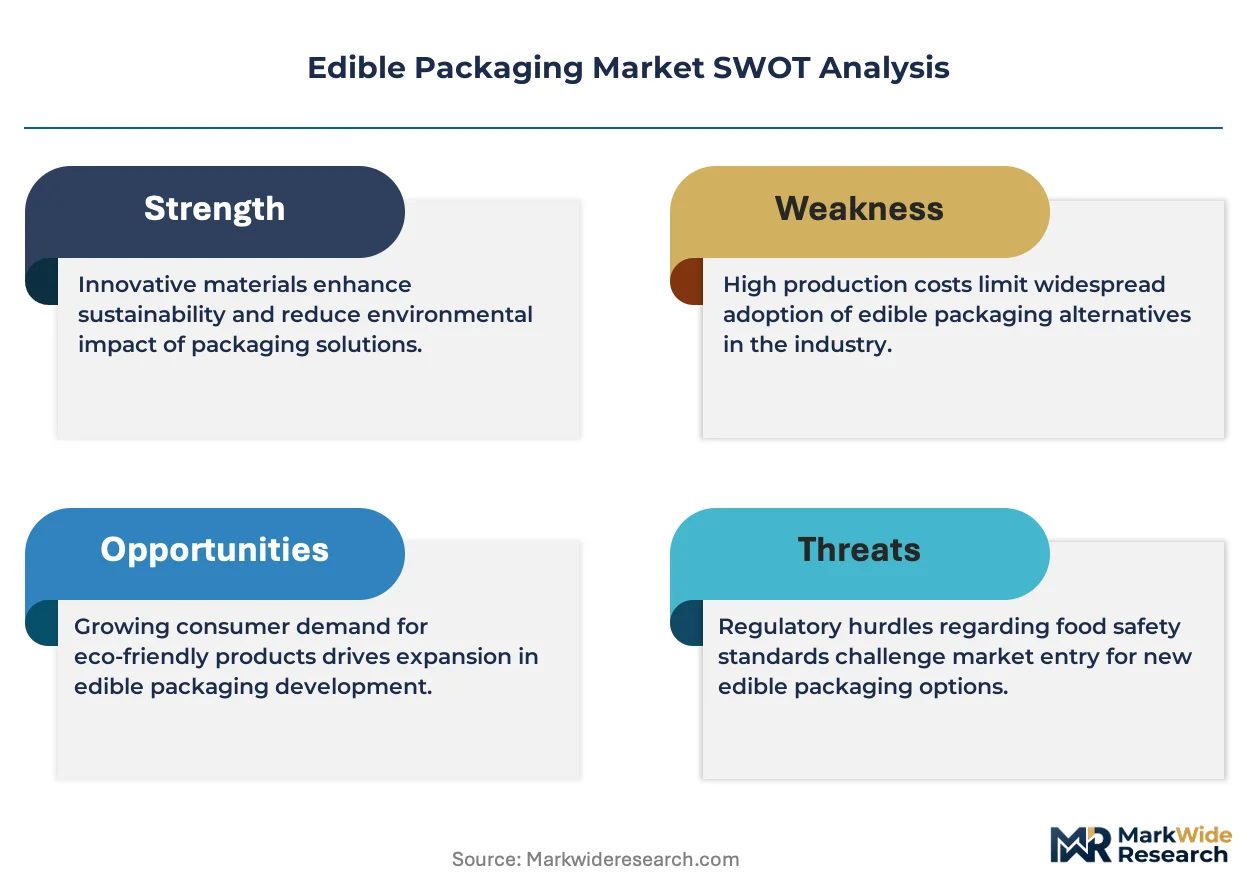
The central force shaping the edible packaging market is the regulatory clampdown on single-use plastics, particularly in the food and beverage sector. This pressure, exemplified by directives in Europe, is compelling brand owners to actively seek and pilot commercially viable, biodegradable alternatives.
Growth Catalysts
- Regulatory Mandates:The European Union's Single-Use Plastics Directive is creating a non-negotiable deadline for phasing out certain plastic items, directly benefiting edible alternatives in quick-service restaurants and for beverage applications.
- Food Service Sector Demand:Quick-service restaurant and food service chains in the United States are adopting edible packaging for single-serving condiments, sauces, and beverages to meet corporate sustainability goals and appeal to environmentally conscious consumers.
- Material Innovation:Advances in polysaccharide film-forming technology, particularly using starches and alginates, are improving barrier properties and reducing production costs, making these materials more competitive against conventional packaging.
Market Restraints
- Cost Disparity:The production cost for most edible packaging materials, especially protein-based formulations, remains significantly higher than that of petroleum-derived plastics, limiting adoption to premium or niche applications.
- Technical Performance Gaps:Edible films often exhibit lower mechanical strength and inferior moisture barrier properties compared to multi-layer plastic films, restricting their use for products requiring a long shelf life.
- Complex Certification Pathways:Navigating the stringent food contact material regulations set by bodies like the US FDA and EFSA is a time-consuming and expensive process that can act as a significant barrier to entry for new suppliers.
Strategic Opportunities
- Nutraceutical Delivery Systems:Developing high-margin, edible capsules and films for delivering precise doses of vitamins, supplements, and active pharmaceutical ingredients represents a significant opportunity in the nutraceuticals market.
- Asia-Pacific Market Entry:Countries like Japan and South Korea, with strong consumer demand for innovative food products and increasing government focus on plastic waste reduction, offer untapped growth potential for edible packaging solutions.
- Functional Ingredient Integration:Incorporating active compounds such as antioxidants, antimicrobials, or flavors directly into the edible film can create value-added packaging that improves food quality and extends shelf life.
Industry Challenges
- Manufacturing Scalability:Achieving cost-competitive production requires significant capital investment in specialized equipment and facilities, a major hurdle for startups and smaller enterprises attempting to compete with established packaging giants.
- Integration with Existing Infrastructure:Adapting existing high-speed food and beverage filling and sealing lines, which are designed for robust plastic or glass, to handle more delicate edible materials is a major technical and operational challenge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Edible Packaging Market |
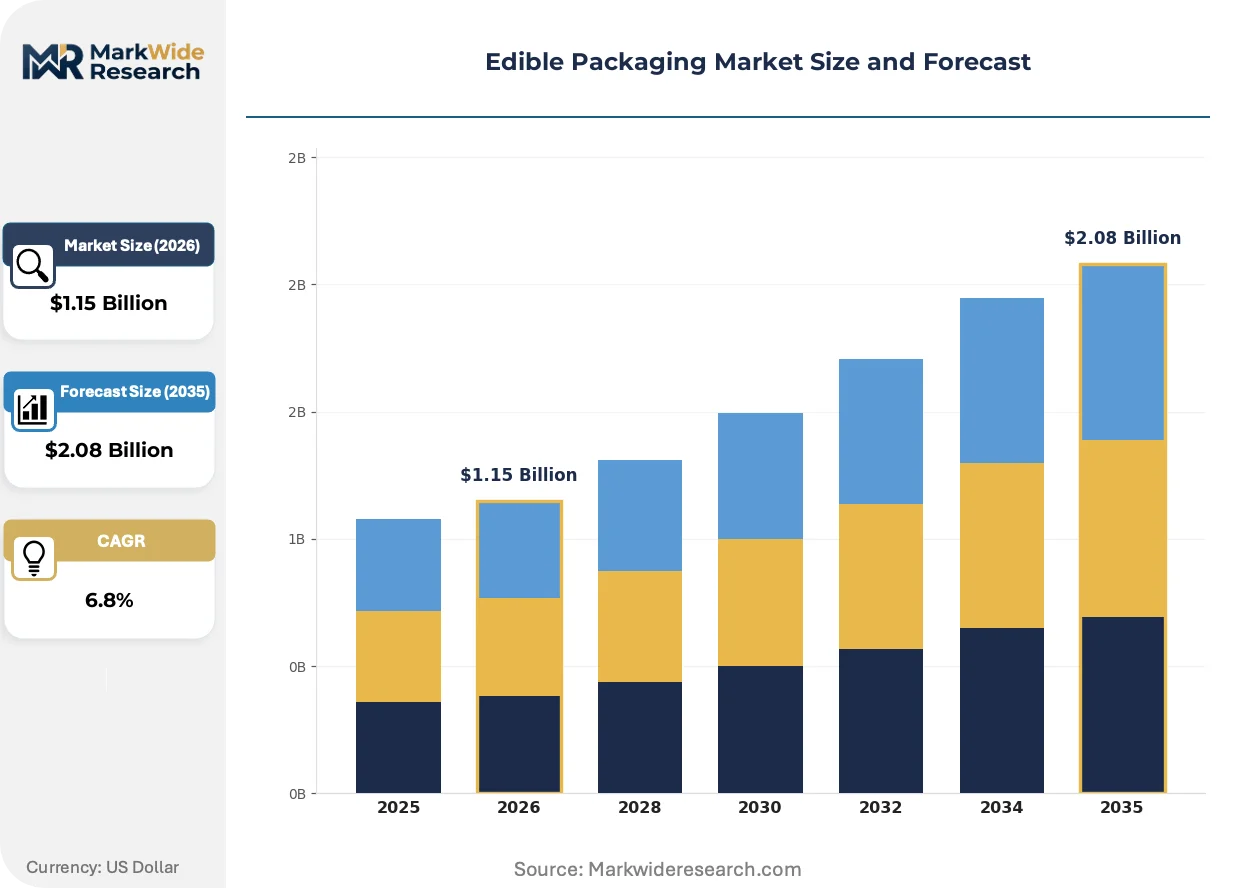
| Market Size in 2026 | $1.15 Billion |
| Market Size in 2035 | $2.08 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Polysaccharides, Proteins, Lipids, Composite Blends, Natural Fibers Form: Films, Coatings, Capsules, Sheets, Pouches Application: Food Preservation, Flavor Enhancement, Portion Control, Nutrient Delivery, Fresh Produce Packaging End User: Food Processors, Confectionery Makers, Beverage Producers, Nutraceutical Manufacturers, Culinary Services |
| Companies Covered | Notpla, Xampla, Amtrex, Devro, MonoSol, Evoware, EdiblePro, Lactips, Biome Bioplastics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Edible Packaging Market Strategic Shifts & Innovations
Material science advancements are the primary engine of change, with development focused on enhancing the functional properties of edible films to move them from niche applications to mainstream use. This innovation is responding directly to both regulatory pressures and shifting consumer preferences for sustainability.
Plant protein-based materials offer a fully biodegradable alternative that leaves no microplastics. Premium food brands are adopting these films to bolster their environmental credentials and product narrative. This development in material science is converging with active packaging technology, enabling the incorporation of natural antimicrobials directly into the film to enhance preservation beyond simple barrier functions.
The US FDA’s Food Contact Notification program is formalizing the approval process for new materials. This regulation creates a more rigorous, data-intensive pathway to market, favoring companies with substantial R&D and toxicological testing capabilities. Ingredient suppliers and film converters are most affected, as they must now prepare extensive safety dossiers prior to commercialization.
A clear behavioral shift is visible as brands move away from bulk procurement of commodity plastics. Instead, they are placing smaller, more frequent orders for specialized edible packaging, often for limited-edition products or premium lines. This change disrupts traditional high-volume distribution, favoring agile suppliers who can support customized, just-in-time production runs, a pattern most evident in the North American craft beverage sector.
Edible Packaging Market Segmentation
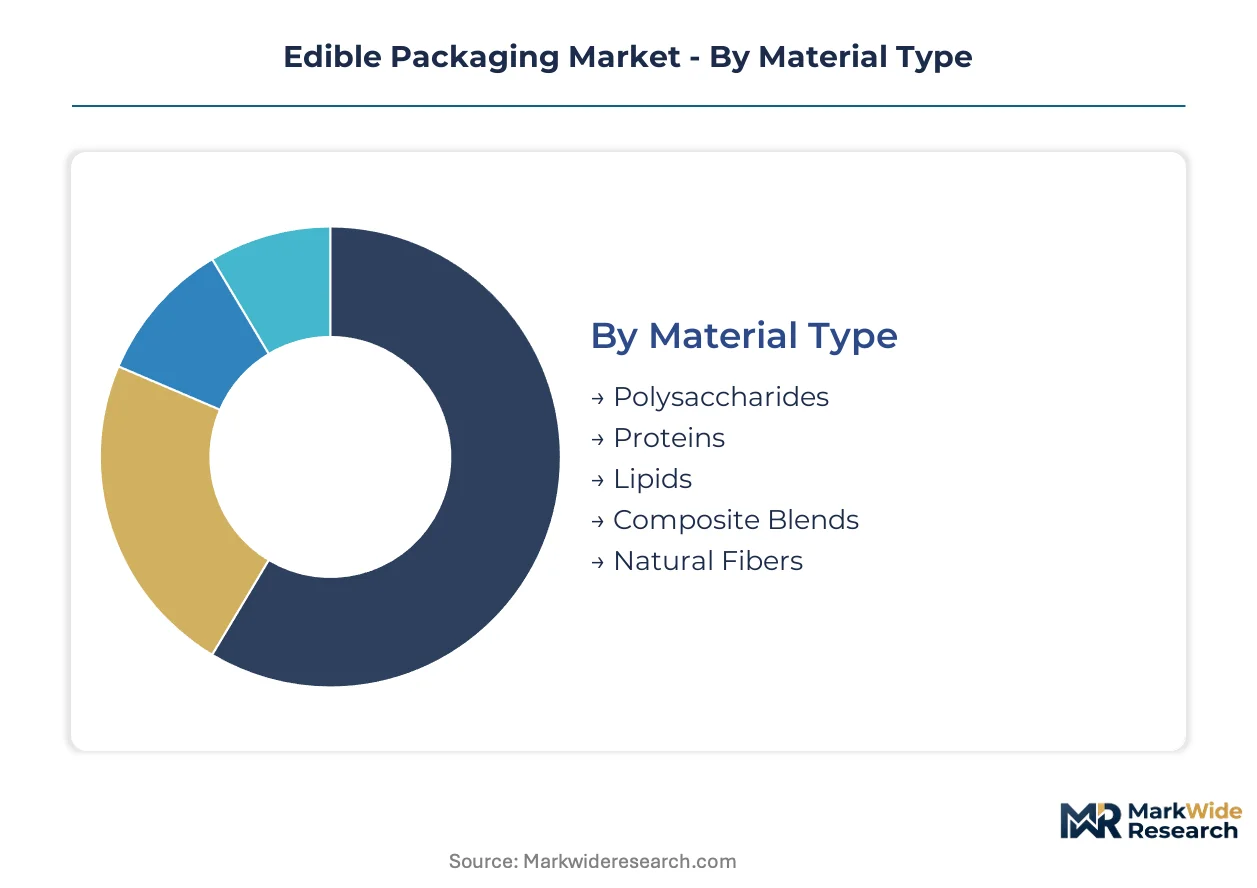
The edible packaging market is inherently diverse, driven by varied material science, functional requirements, and end-user demands. Understanding these distinct segments provides crucial insight into where innovation is concentrated and where commercial opportunities are most pronounced. Each segment reflects unique technical challenges and regulatory pathways for market entry.
Material Type:
The selection of raw materials dictates the functional properties and biodegradability profile of edible packaging solutions.
- Polysaccharides:These natural polymers, including starches and alginates, form flexible films and coatings, providing effective moisture and oxygen barriers. Demand concentrates in the beverage and quick-service restaurant sectors, driven by their cost-effectiveness and film-forming properties.
- Proteins:Derived from plant sources like pea or corn, protein-based materials offer superior mechanical strength and oxygen barrier properties, fully biodegrading without microplastics. Premium food brands adopt these for their environmental credentials and enhanced product narratives.
- Lipids:Fats and waxes create hydrophobic barriers, primarily used as thin coatings to reduce moisture loss and improve gloss on fresh produce.
- Composite Blends:Combinations of different material types leverage synergistic properties, such as enhanced strength or improved barrier functions, for specialized applications.
- Natural Fibers:Cellulose or other plant fibers provide structural integrity and opacity, often integrated into more complex edible matrices.
Polysaccharides leads on scale; Proteins leads on momentum.
Form:
The physical configuration of edible packaging directly influences its application and integration into existing production lines.
- Films:Thin, flexible layers provide a primary barrier against external contaminants, widely used for wrapping and protecting individual food items. Beverage producers are increasingly piloting these for single-serve portions.
- Coatings:Applied directly to food surfaces, these layers extend shelf life by reducing moisture transfer and microbial growth. Fresh produce packaging heavily relies on these protective applications.
- Capsules:Small, enclosed forms deliver precise doses of ingredients or active compounds, particularly relevant for nutraceuticals and flavor enhancements.
- Sheets:Thicker, more rigid forms offer structural support, often used for separating or containing multiple food components.
- Pouches:Flexible, self-contained units hold liquids or semi-solid products, requiring advanced sealing technologies for commercial viability.
Films represent the largest volume; Capsules are expanding most quickly.
Application:
Edible packaging serves various critical functions, from extending product viability to enhancing consumer experience.
- Food Preservation:This application focuses on extending the shelf life of perishable goods by creating barriers against oxygen, moisture, and microbial contamination. Food processors utilize these solutions to reduce waste and maintain product quality.
- Nutrient Delivery:High-margin innovation involves encapsulating vitamins, supplements, or active pharmaceutical ingredients within edible forms for precise dosing. Nutraceutical manufacturers are driving advancements in this specialized area.
- Flavor Enhancement:Edible films or coatings can incorporate flavor compounds that release upon consumption, improving the sensory experience of a product.
- Portion Control:Individual edible wrappers or containers help manage serving sizes, particularly useful in the confectionery and culinary services sectors.
- Fresh Produce Packaging:Direct coatings on fruits and vegetables reduce spoilage and respiration rates, maintaining freshness from farm to consumer.
Food Preservation commands the broadest usage; Nutrient Delivery shows the steepest expansion trajectory.
End User:
Different industry sectors adopt edible packaging based on their specific product needs, sustainability goals, and consumer engagement strategies.
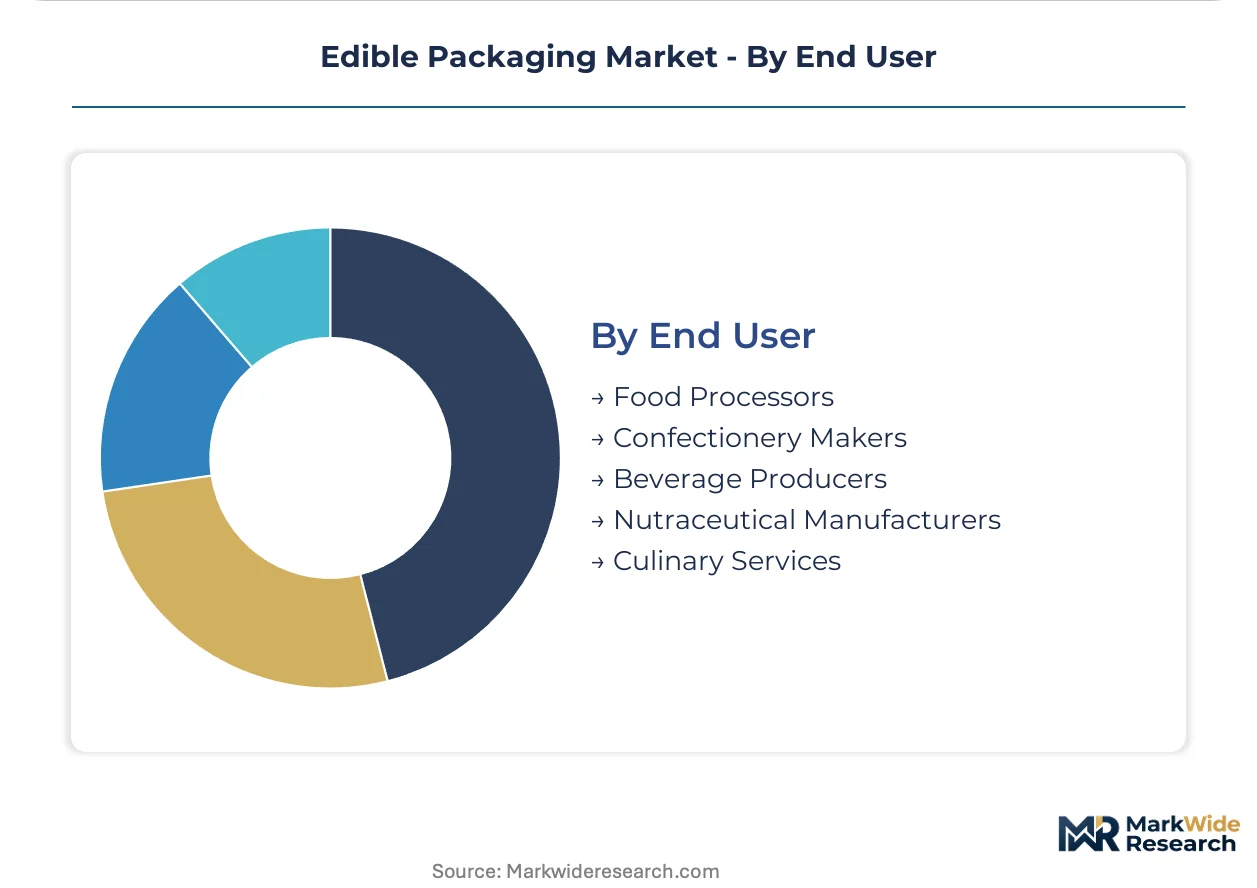
- Beverage Producers:These companies adopt edible packaging for single-serving drink capsules or water pods, driven by regulatory pressure on single-use plastics. The European Union's Single-Use Plastics Directive directly benefits this segment.
- Nutraceutical Manufacturers:This segment leverages edible capsules and films for precise, convenient delivery of vitamins, supplements, and functional ingredients. High-margin products in this sector absorb the premium cost of advanced edible materials.
- Food Processors:Large-scale operations integrate edible coatings and films to extend the shelf life of processed foods, reducing spoilage during distribution.
- Confectionery Makers:Candy and dessert producers use edible wrappers and decorations to enhance novelty and reduce packaging waste.
- Culinary Services:Quick-service restaurants and catering companies utilize edible packaging for condiments, sauces, and small food items to meet sustainability targets and consumer preferences.
Food Processors drive significant volume; Beverage Producers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Research and development hubs across key global economies anchor the Edible Packaging Market's geographic distribution. These centers attract skilled scientists and engineers, driving material science advancements. Regulatory pressures and consumer sustainability preferences further shape regional demand for innovative packaging solutions.
United States
Quick-service restaurants and the food service sector drive significant demand for edible packaging, seeking sustainable alternatives for single-serving condiments and beverages. The US FDA's Food Contact Notification program provides a formal pathway for new material approvals, influencing market entry. California's vibrant food tech ecosystem, particularly in the San Francisco Bay Area, concentrates innovation in plant-based edible film development.
Germany
Strong consumer demand for sustainable packaging and robust circular economy initiatives propel the adoption of edible solutions in Germany. The EU Single-Use Plastics Directive creates a clear commercial advantage for non-plastic alternatives, benefiting local producers. Bavaria's extensive food processing industry acts as a testing ground for integrating edible coatings and films into existing production lines.
Japan
A culture of innovative food products and a strong focus on waste reduction initiatives stimulate the market for edible packaging in Japan. Regulations from METI (Ministry of Economy, Trade and Industry) encourage sustainable material development and recycling. Tokyo's advanced materials research institutions and food manufacturers collaborate on developing high-performance edible films for diverse applications.
India
Urbanization and rising consumer awareness regarding plastic waste are generating new demand for edible packaging, particularly in the food and beverage sectors. The FSSAI (Food Safety and Standards Authority of India) sets guidelines for food contact materials, ensuring product safety and compliance. Maharashtra's large food manufacturing sector, especially around Mumbai and Pune, explores edible coatings for fresh produce and processed foods.
South Korea
The demand for convenient food products and government initiatives to reduce plastic waste are accelerating the adoption of edible packaging solutions. The Ministry of Environment's policies on plastics management push industries towards biodegradable alternatives. Seoul's dynamic food and beverage innovation centers are actively piloting edible films and capsules for new product launches.
Edible Packaging Market Key Industry Players
The competitive structure tilts toward a tiered ecosystem, where specialized material science firms coexist with larger, established packaging solution providers. This market exhibits a blend of niche innovators focusing on specific material properties and broader players seeking to integrate these into comprehensive offerings. Strategic archetypes include technology developers, raw material suppliers, and application-focused integrators. Dominant competitive moves center on technology licensing agreements and strategic partnerships to scale novel solutions rapidly, alongside targeted mergers and acquisitions for capability expansion.
Specialists in advanced material science, Notpla and Xampla, exemplify the innovation-driven segment, leveraging proprietary technologies for sustainable alternatives that address specific environmental concerns like microplastics. Notpla focuses on seaweed-based solutions for beverage and sauce applications, while Xampla differentiates with plant protein-based materials. MonoSol occupies a position as a key provider of water-soluble polymer films, serving diverse applications including food ingredients and detergents, demonstrating versatility in material application. These entities anchor the market's technological evolution, pushing the boundaries of functional edible materials across various end-use sectors.
| Leading Market Players |
|---|
| Notpla |
| Xampla |
| Amtrex |
| Devro |
| MonoSol |
| Evoware |
| EdiblePro |
| Lactips |
| Biome Bioplastics |
| Others |
Cost & Logistics Intelligence
Raw material costs for edible packaging are heavily influenced by agricultural commodity prices, particularly for starches and proteins, which then cascade through processing and film conversion to impact end-product pricing for beverage producers and quick-service restaurants.
Pricing Analysis
The bundled versus unbundled service split defines pricing for edible packaging solutions. Pricing stratifies across premium, standard, and economy tiers, with differentiation driven by material quality grade and required food-grade certification levels, such as those from the US FDA or EFSA. Pricing pressure stems from the cost disparity with conventional plastics, particularly for high-volume applications. Quick-service restaurants represent the most price-sensitive buyers, while nutraceutical manufacturers are less sensitive due to high-margin product lines.
Supply Chain Analysis
Dual-sourcing requirements frequently apply to edible packaging materials, particularly for specialized films, as buyers seek to mitigate risk and ensure supply continuity. Geographic supply concentrates in regions with strong agricultural bases like the United States for plant proteins and Asia for starches, alongside specialized chemical processing in Europe. Raw material dependencies include polysaccharides, plant proteins, and film-forming agents. Commodity price volatility for key inputs represents a structural supply chain risk. Distribution runs through specialized packaging distributors and direct sales channels to large food and beverage manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The edible packaging market is evolving into a late-cycle quality story, driven by consumer demand for premium, microplastic-free solutions and enhanced functional properties.
For Market Incumbents: Deepen R&D investment into advanced barrier technologies for films to overcome existing technical performance gaps against multi-layer plastics. Pursue strategic partnerships with large food and beverage brands to integrate edible materials into mainstream product lines, countering the threat of new regulatory mandates on conventional packaging. Invest in specialized manufacturing scalability to reduce unit costs and compete more effectively. Secure long-term supply contracts for key polysaccharide and protein raw materials.
For New Entrants and Emerging Players: Direct-to-consumer digital channels offer new entrants a pathway to market niche applications, bypassing established distribution networks. Target the nutraceuticals segment with high-margin, innovative capsule and film solutions for nutrient delivery, as this area exhibits higher price tolerance. Focus on plant protein-based materials that offer superior environmental credentials and fully biodegrade without microplastics. Emphasize compliance with local food contact material regulations as a key go-to-market angle.
For Investors and Strategic Acquirers: Consolidation pressure builds where manufacturing scalability remains a significant barrier to entry for smaller players. Target vertically integrated specialists with proprietary material science and established food-grade certifications, particularly those with strong intellectual property in polysaccharide or protein film technologies. Look for companies with demonstrable success in integrating their solutions into existing food production infrastructure. A key signal to watch is the increasing number of commercial pilot programs by major beverage producers, indicating market readiness.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Advanced Barrier Technology | Enhances competitive advantage by matching or exceeding conventional plastic performance for food preservation. |
| Secure Long-Term Raw Material Contracts | Mitigates commodity price volatility and ensures stable supply for large-scale production. |
| Attain Global Food-Grade Certifications | Unlocks market access across major economies like the US and EU, facilitating international expansion. |
| Develop Bespoke Application Solutions | Addresses specific functional requirements for high-value segments such as nutraceuticals and premium beverages. |
| Scale Up Manufacturing Capabilities | Reduces per-unit production costs, making edible packaging more competitive against traditional alternatives. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region's market participants. Primary research included in-depth interviews with R&D directors, procurement leads, regulatory specialists, and brand managers across the food, beverage, and packaging industries. Secondary data validation drew from regulatory filings with the US FDA and EFSA, trade association reports, and company financial disclosures. Bottom-up and top-down triangulation ensured data accuracy and comprehensive market understanding.
Rate-of-change decomposition analyzes market evolution by material type, form, application, and end-user segments, alongside the impact of barrier properties. The analytical framework projects market growth across the analysis window, deriving compound annual growth rates from historical trends and anticipated shifts. Key forecast inputs include regulatory timelines for single-use plastics and material science breakthroughs in film performance.
The model assumes a particular technology adoption path; alternative pathways for protein-based materials would alter the outlook. Forecasts reflect assumptions regarding regulatory enforcement and consumer demand for sustainable solutions. Deviation in raw material price stability or major policy changes would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Vegan Casing Market
Alternative Food Sources
Artificial Meat Market
Alternative Food Sources
Corn-Based Protein Market
Alternative Food Sources
Algal Protein Market
Alternative Food Sources
Teff Products Market
Alternative Food Sources
North America Meat Substitutes Market
Alternative Food Sources
Europe Upcycled Food Products Market
Alternative Food Sources
Sugar Alternative Market
Alternative Food Sources
Flaxseed Based Egg Replacement Market
Alternative Food Sources
Egg Replacers Market
Alternative Food Sources
Upcycled Food Products Market
Alternative Food Sources
Asia-Pacific Meal Replacement Products Market
Alternative Food Sources
Flour Substitutes Market
Alternative Food Sources
Gluten Replacer Market
Alternative Food Sources
Insect Protein Market
Alternative Food Sources
Vegan Ham Market