
 Teff Products Market | 2026-2036
Teff Products Market Size, Share, and Industry Trends Forecast 2026-2036
Teff Products Market Analytics
Organic certification under EU Regulation 2018/848 is collapsing the supplier base for European teff flour distribution, as Ethiopian smallholders struggle with conversion costs and documentation. Maskal Teff leverages direct grower relationships in the highlands to sustain its organic pipeline. Bob's Red Mill anchors North American retail visibility through established gluten-free aisle placement. Lovegrass Ethiopia differentiates via single-origin traceability and vertical control from farm to export.
Teff products encompass processed and whole-grain outputs from Eragrostis tef, a C4 grass species native to the Ethiopian highlands whose seeds range 0.8–1.0 mm in diameter with protein content typically exceeding 10% and a favorable essential amino acid profile including lysine. The grain's functional properties suit injera fermentation, gluten-free baking, and malted beverage applications where its water-binding capacity and subtle nutty flavor deliver textural and sensory performance. Flour currently leads product-type revenue due to established bakery substitution demand, while gluten-free products as an end-use segment captures the fastest structural expansion as clean-label formulations displace rice and corn alternatives. Nutritional supplements represent a concentrated margin pool where encapsulated teff protein and fiber extracts command premium positioning in sports nutrition and clinical dietetic channels.
FDA gluten-free labeling rules under 21 CFR 101.91 shape US market access by mandating sub-20 ppm gluten thresholds that teff naturally satisfies, while Ethiopia's national quality and standards authority enforces export grading protocols for moisture content and foreign matter that determine lot acceptance at EU ports. BIS import clearance requirements for India classify teff under food safety surveillance categories that extend clearance timelines for new suppliers. Stakeholders must monitor how evolving novel food classifications in target jurisdictions reshape registration burdens relative to commodity grain pathways.
Market Dynamics
The Teff Products Market pivots on EU Regulation 2018/848 organic certification requirements, which are systematically filtering Ethiopian smallholder suppliers out of European distribution channels while concentrating sourcing among vertically integrated highland operators capable of absorbing compliance documentation burdens.
Growth Catalysts
- FDA Gluten-Free Labeling:The 21 CFR 101.91 sub-20 ppm threshold mandate opens US retail shelf access for teff flour as a naturally compliant celiac-safe substitute, accelerating bakery formulation switches from rice and corn bases.
- German Health Food Retail:Dedicated ancient-grain section builds by dm-drogerie markt and Alnatura are creating structured demand pull for teff injera mixes and whole grain packages in Central European urban centers.
- Clean-Label Momentum:Sports nutrition brands are incorporating encapsulated teff protein isolates into pre-workout formulations, displacing whey and soy concentrates in premium positioning channels.
Market Restraints
- Highland Supply Concentration:Over 90% of export-grade teff originates from Ethiopia's central highlands, exposing buyers to localized drought risk and political logistics disruption without geographic diversification buffers.
- EU Novel Food Authorization:Non-traditional grain import pathways require EFSA safety dossiers that extend clearance timelines 18-24 months for new Ethiopian suppliers, constraining market entry velocity.
- Quinoa Price Competition:Established Andean quinoa supply chains offer comparable protein profiles at 15-20% lower landed costs in North American retail, pressuring teff volume expansion in budget gluten-free segments.
Strategic Opportunities
- Indian BIS Clearance:First-mover suppliers navigating India's extended food safety surveillance timelines for novel grains can establish captive supply relationships ahead of domestic gluten-free bakery scaling.
- Malted Beverage Applications:Teff's enzymatic amylase activity suits craft brewing and functional beverage fermentation, opening white space beyond traditional injera and bakery end-uses.
- Single-Origin Traceability:Blockchain-enabled farm-to-package verification commands 25-40% retail price premiums in Japanese and South Korean health food channels where provenance transparency drives purchase decisions.
Industry Challenges
- Organic Conversion Documentation:Ethiopian smallholders face prohibitive costs for EU 2018/848 certification record-keeping, forcing distributors to consolidate sourcing among a shrinking pool of compliant highland cooperatives.
- Moisture Content Standardization:Ethiopia's national quality authority grading protocols for export lots create rejection risk at Rotterdam and Hamburg ports when pre-shipment testing discrepancies emerge.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Teff Products Market |
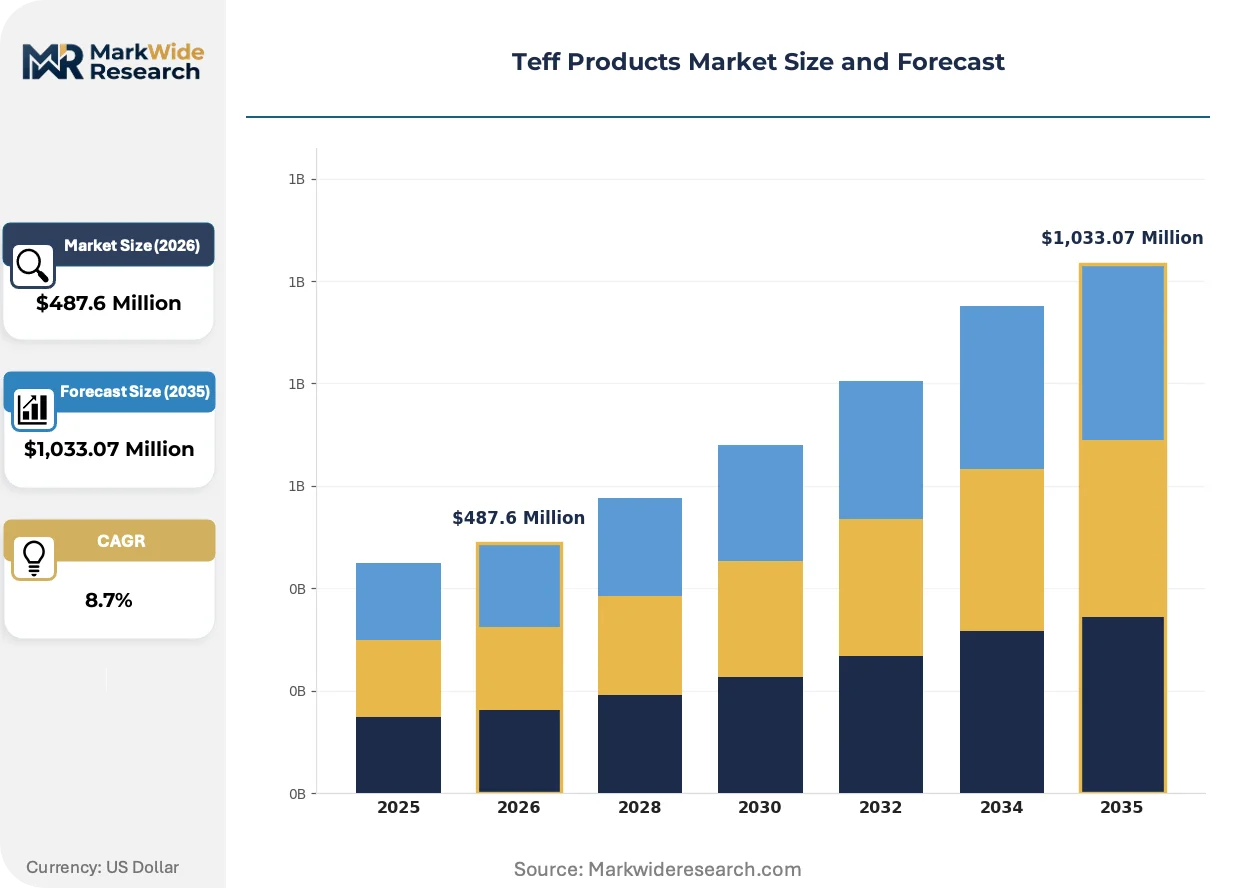
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $1,033.07 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flour, Grain, Seeds, Snacks End Use: Baking, Brewing, Gluten-Free Products, Nutritional Supplements Distribution Channel: Online Stores, Supermarkets, Health Food Stores, Specialty Shops Packaging Type: Bags, Boxes, Tins, Bulk |
| Companies Covered | Tena Teff, Bob’s Red Mill, Maskal Teff, Outside The Breadbox, Anthony’s Goods, Lovegrass Ethiopia, Grainful, Tobia Teff, Berhan Grains, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Teff Products Market Evolving Landscape
Processing technology advances and regulatory pathway clarifications are compressing teff's transition from ethnic specialty to mainstream gluten-free commodity, with fermentation science and clean-label extraction methods driving product format diversification.
Enzymatic debittering of teff bran is supplanting traditional water-washing methods in protein isolate production, enabling higher yield recovery and reduced wastewater discharge. Scandinavian plant-protein specialists are adopting this bioprocessing route at pilot scale. The shift is compressing capital requirements for entry-level teff fractionation facilities while raising barriers for legacy wet-milling operations dependent on volume throughput.
REACH registration requirements for novel food contact substances are reshaping packaging specifications for teff flour exports into the European Economic Area, with ECHA compliance timelines extending 12-18 months for biodegradable film alternatives. German importers are responding by consolidating shipments through established logistics partners with pre-cleared polymer certifications, marginalizing smaller distributors lacking regulatory affairs capacity.
Direct-to-baker procurement contracts are fragmenting traditional commodity broker dominance in North American teff distribution, with artisan gluten-free bakeries in Portland and Austin establishing multi-year grower commitments. This channel shift concentrates volume among relationship-based suppliers while compressing spot-market liquidity and price transparency for transactional buyers.
Teff Products Market Segmentation
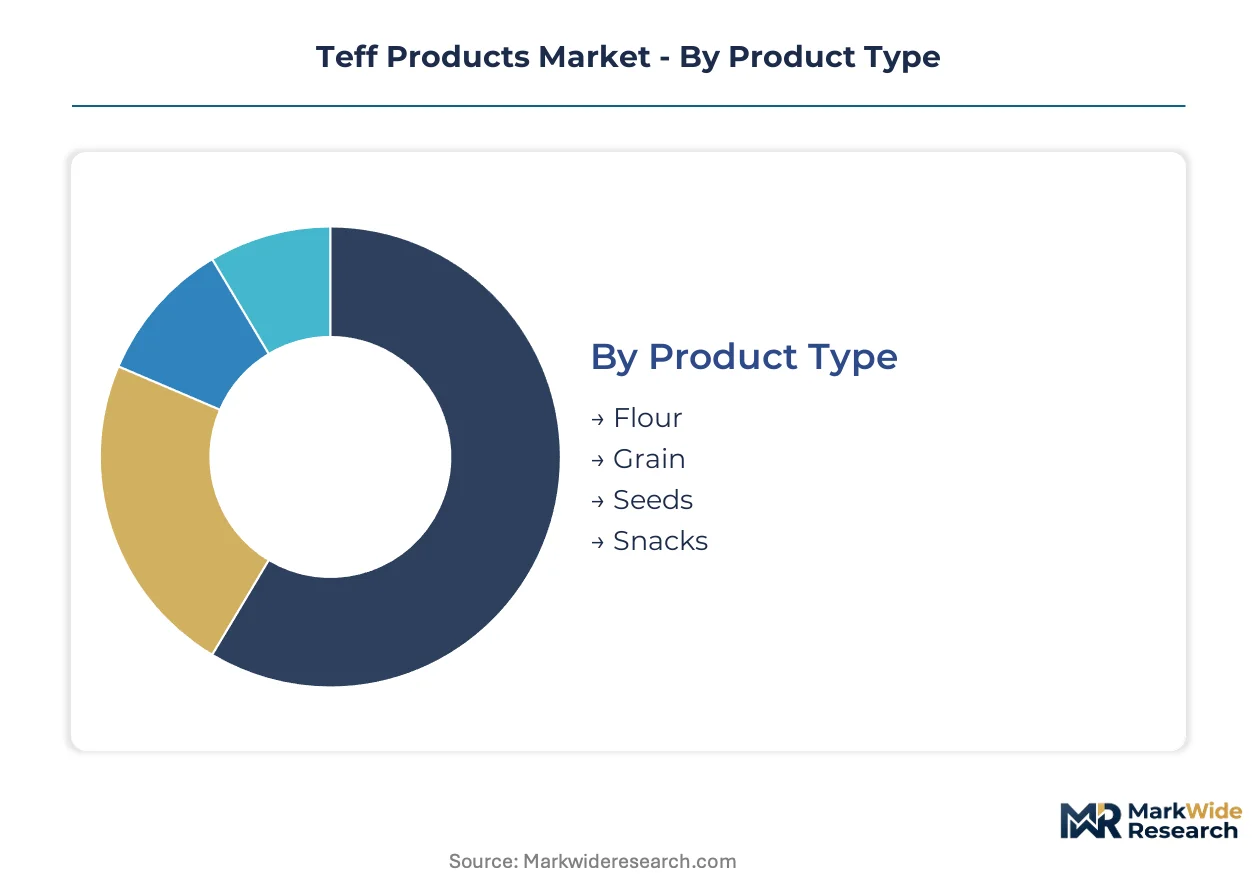
Teff product segmentation reveals how value migrates across processing stages and channel tiers. Margin concentration varies sharply between commodity grain flows and finished consumer formats, with certification requirements and shelf placement determining profitability thresholds.
Product Type:
Flour commands premium positioning in European gluten-free bakery supply chains, while whole grain retains volume concentration in Ethiopian diaspora channels.
- Flour:Stone-milled and roller-milled variants with protein content exceeding 10% serve injera fermentation and gluten-free baking applications. German health food retail chains are building dedicated ancient-grain sections that prioritize teff flour SKUs over competing ancient grains.
- Grain:Whole teff seeds in 0.8–1.0 mm diameter grades supply direct cooking and home milling demand. Ethiopian export grading protocols for moisture content and foreign matter determine lot acceptance at Rotterdam and Hamburg ports, concentrating supply among vertically integrated highland operators.
- Seeds:Certified propagation stock for contract farming programs in Idaho and Nevada.
- Snacks:Puffed and extruded formats targeting convenience channels in Japanese health food markets.
Flour holds installed capacity. Grain is rotating up the share rankings.
End Use:
Application diversity determines pricing power, with clinical and sports nutrition channels extracting multiples over commodity foodservice volumes.
- Gluten-Free Products:FDA 21 CFR 101.91 sub-20 ppm compliance opens US retail shelf access for celiac-safe formulations. Clean-label momentum is displacing rice and corn alternatives in premium bakery positioning.
- Nutritional Supplements:Encapsulated teff protein and fiber extracts command premium positioning in sports nutrition channels. Scandinavian plant-protein specialists are adopting enzymatic debittering methods at pilot scale.
- Baking:Artisan gluten-free bakeries in Portland and Austin are establishing multi-year grower commitments.
- Brewing:Teff's enzymatic amylase activity suits craft fermentation applications.
Nutritional Supplements extract the highest margin per kilogram. Gluten-Free Products are climbing the fastest.
Distribution Channel:
Channel selection dictates working capital intensity and traceability investment requirements.
- Health Food Stores:Dedicated ancient-grain section builds by dm-drogerie markt and Alnatura create structured demand pull for teff injera mixes in Central European urban centers.
- Supermarkets:Mainstream gluten-free aisle placement requires scale and certification documentation that filters out Ethiopian smallholders.
- Online Stores:Direct-to-consumer formats enabling single-origin traceability premiums in Japanese and South Korean markets.
- Specialty Shops:Ethnic grocery channels serving Ethiopian diaspora demand in Washington DC and London.
Health Food Stores concentrate margin extraction. Online Stores are expanding most quickly.
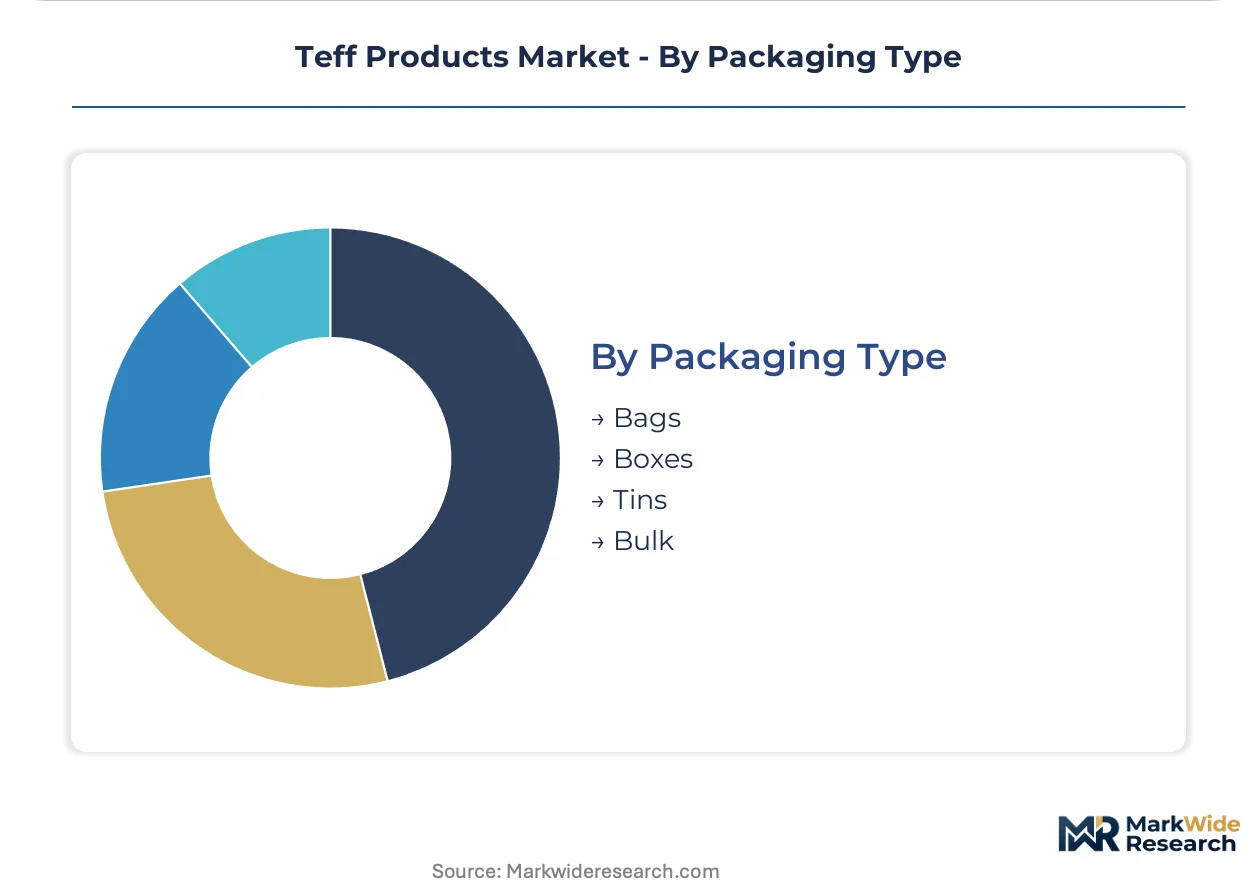
Packaging Type:
Packaging specifications are reshaping under REACH registration requirements for novel food contact substances.
- Bags:Biodegradable film alternatives face ECHA compliance timelines extending 12-18 months, consolidating shipments through German logistics partners with pre-cleared polymer certifications.
- Bulk:Direct-to-baker procurement contracts fragment traditional commodity broker dominance in North American distribution.
- Boxes:Retail-ready formats for supermarket gluten-free aisles.
- Tins:Premium positioning for gift and specialty channels.
Bulk holds installed capacity. Bags is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EU Regulation 2018/848 organic certification requirements are filtering Ethiopian smallholder suppliers out of European distribution channels while FDA gluten-free labeling rules under 21 CFR 101.91 open US retail shelf access for teff flour. This regulatory divergence is concentrating sourcing among vertically integrated highland operators capable of absorbing compliance documentation burdens.
Germany
dm-drogerie markt and Alnatura are building dedicated ancient-grain sections that create structured demand pull for teff injera mixes and whole grain packages in urban centers. EFSA novel food authorization requirements for non-traditional grains streamline import pathways for Ethiopian-origin teff. Berlin and Hamburg serve as the primary distribution hubs where pre-cleared polymer certifications consolidate shipments through established logistics partners.
United States
Artisan gluten-free bakeries in Portland and Austin are establishing multi-year grower commitments that fragment traditional commodity broker dominance. FDA 21 CFR 101.91 sub-20 ppm gluten thresholds mandate celiac-safe formulations that teff naturally satisfies. The Pacific Northwest and Texas Hill Country clusters concentrate direct-to-baker procurement contracts that compress spot-market liquidity.
Ethiopia
The central highlands supply over 90% of export-grade teff, exposing buyers to localized drought risk without geographic diversification buffers. The national quality and standards authority enforces export grading protocols for moisture content and foreign matter that determine lot acceptance at EU ports. Addis Ababa anchors vertically integrated operations where Maskal Teff leverages direct grower relationships to sustain organic pipelines.
India
BIS import clearance requirements classify teff under food safety surveillance categories that extend clearance timelines for new suppliers. First-mover suppliers navigating these extended timelines can establish captive supply relationships ahead of domestic gluten-free bakery scaling. Mumbai and Delhi-NCR serve as the primary entry points where regulatory affairs capacity determines market access velocity.
Japan
Blockchain-enabled farm-to-package verification commands 25-40% retail price premiums in health food channels where provenance transparency drives purchase decisions. METI standards for novel food contact substances reshape packaging specifications for teff flour imports. Tokyo and Osaka concentrate specialty retail demand for single-origin traceability in premium positioning channels.
Teff Products Market Competitive Landscape
Player mix skews toward specialty grain distributors and vertically integrated Ethiopian exporters, with limited participation from diversified multinational food conglomerates. The structure remains fragmented across regional supply bases, with no dominant volume leader capturing significant share. Two strategic archetypes define competitive positioning: direct-source operators controlling highland grower relationships, and North American retail-facing brands anchoring gluten-free aisle placement. Capacity expansion and certification documentation investments represent the dominant competitive moves as suppliers absorb EU 2018/848 compliance burdens.
Among Ethiopian-origin specialists, Maskal Teff and Lovegrass Ethiopia occupy positions exemplifying the direct-source archetype through highland grower network control. Bob's Red Mill anchors North American retail visibility through established gluten-free aisle placement, representing the retail-facing tier. These three companies illustrate how geographic origin and channel strategy stratify competitive positioning across the value chain.
| Leading Market Players |
|---|
| Tena Teff |
| Bob's Red Mill |
| Maskal Teff |
| Outside The Breadbox |
| Anthony's Goods |
| Lovegrass Ethiopia |
| Grainful |
| Tobia Teff |
| Berhan Grains |
| Others |
Value Network & Pricing Analysis
Teff's displacement of rice and corn bases in gluten-free formulations simultaneously redraws procurement geography toward Ethiopia's central highlands and compresses margin structures for distributors lacking direct grower relationships. This substitution dynamic concentrates pricing power among vertically integrated operators while fragmenting spot-market liquidity for transactional buyers.
Pricing Analysis
EU 2018/848 organic certification level creates the primary spread between premium and commodity tiers, with compliant flour commanding substantial premiums over conventional grades in German health food retail. Contract-based long-term offtake dominates volume flows as artisan bakeries in Portland and Austin lock in multi-year grower commitments. Cost compression in standard-grade segments is intensifying because quinoa supply chains offer comparable protein profiles at lower landed costs. Budget gluten-free manufacturers exhibit highest price sensitivity, while sports nutrition brands purchasing encapsulated protein isolates demonstrate lowest elasticity.
Supply Chain Analysis
Container availability constraints on the Djibouti-Rotterdam trade lane extend lead times and elevate working capital requirements for European distributors. Over 90% of export-grade supply draws from Ethiopia's central highlands, with emerging propagation programs in Idaho and Nevada diversifying seed stock. Raw material dependencies center on highland rainfall patterns, certified organic inputs, and pre-cleared polymer packaging certifications. Single-source vulnerability from localized drought exposure represents the dominant structural risk. Distribution runs through vertically integrated Ethiopian exporters and North American specialty grain distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Teff products occupy an early-cycle expansion phase as FDA gluten-free labeling and EU novel food authorization streamline regulatory pathways for mainstream adoption. Clean-label bakery substitution provides the underlying penetration tailwind.
For Market Incumbents: Shield organic certification pipelines by deepening direct grower relationships in Ethiopia's highlands before EU 2018/848 documentation requirements further collapse the supplier base. Absorb compliance costs through scale economies that transactional competitors cannot replicate. Reinforce channel control through pre-cleared polymer logistics partnerships in Germany.
For New Entrants and Emerging Players: Blockchain-enabled traceability services represent a service-layer gap where incumbents under-serve Japanese and South Korean premium channels. Target malted beverage applications as the most penetrable white-space segment beyond traditional injera and bakery end-uses. Pursue direct-to-baker procurement contracts in Austin and Portland as the primary go-to-market angle.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed specialty grain distributors lacking Ethiopian direct-source capabilities. Five-to-ten year viability hinges on backward integration into highland grower networks. Monitor EFSA novel food authorization timelines as the critical inflection signal for supply-constrained pricing power.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Highland Grower Networks | EU 2018/848 compliance costs filter smallholders, concentrating sourcing among integrated operators. |
| Blockchain-Enabled Farm-to-Package Traceability | Japanese health food channels command 25-40% retail premiums for provenance transparency. |
| Enzymatic Debittering Technology Adoption | Scandinavian plant-protein specialists compress capital requirements for teff fractionation facilities. |
| Direct-to-Baker Procurement Contracts | Portland and Austin artisan bakeries fragment traditional commodity broker dominance in North America. |
| Malted Beverage Application Development | Teff's enzymatic amylase activity opens white space beyond injera and bakery end-uses. |
Research Methodology
A standing panel of organic certification specialists, Ethiopian highland cooperative managers, German health food retail buyers, and FDA regulatory affairs consultants provided ongoing calibration across the study period. Primary interviews with these stakeholders combined with secondary validation from EFSA novel food dossiers, Ethiopia's national quality authority export grading protocols, and US customs import records. Bottom-up volume modeling and top-down value triangulation anchored the analytical framework.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. Segmentation dimensions modeled include product type, end-use application, distribution channel tier, and geographic regulatory cluster. CAGRs were derived from trend extrapolation calibrated to documented substitution rates in gluten-free bakery formulations. Forecast inputs incorporated EU organic conversion timelines and FDA labeling compliance thresholds.
Forecasts assume regulatory continuity in EU 2018/848 organic certification and FDA 21 CFR 101.91 gluten-free labeling regimes; material policy shifts would require re-modeling. Highland drought frequency, novel food authorization delays, and quinoa price volatility represent specific risk factors that could revise trajectory. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Vegan Casing Market
Alternative Food Sources
Global Alternative Protein Market
Alternative Food Sources
Plant-Based Compound Feed Market
Alternative Food Sources
Asia-Pacific Fat Replacers Market
Alternative Food Sources
Asia-Pacific Algae Protein Market
Alternative Food Sources
Egg Substitutes Market
Alternative Food Sources
Low Carbs Vegan Food Market
Alternative Food Sources
Africa Potato Protein Market
Alternative Food Sources
Sugar Alternative Market
Alternative Food Sources
Meat Analogue Market
Alternative Food Sources
Konjac Market
Alternative Food Sources
Vegan Ham Market
Alternative Food Sources
Plant-Based Squalene Market
Alternative Food Sources
Flour Substitutes Market
Alternative Food Sources
Algae Products Market
Alternative Food Sources
Africa Fat Replacers Market