
 Coral Calcium Supplements Market | 2026-2036
Coral Calcium Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Coral Calcium Supplements Market Analytics
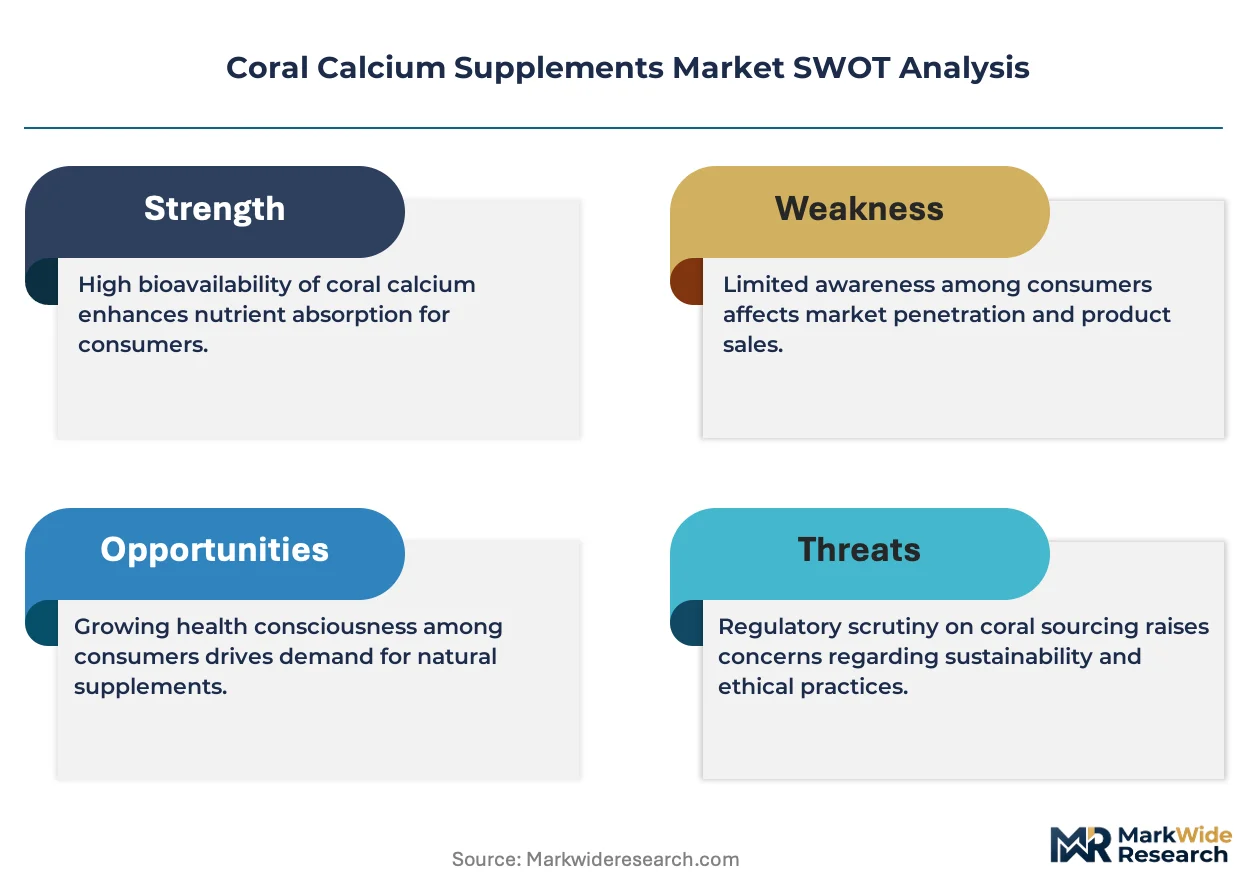
USP verification and NSF International certification is bifurcating the competitive landscape into qualified suppliers and fringe operators. NOW Foods leverages its vertically integrated manufacturing network to sustain cost discipline across capsule and powder lines. GNC anchors its position through controlled shelf access in corporate retail channels, while Marine Bio differentiates via Okinawa-sourced marine coral extraction credentials.
Coral calcium supplements derive from fossilized above-sea or marine coral deposits, delivering calcium carbonate with trace magnesium and over seventy mineral co-factors at typical elemental calcium concentrations of 35-38% by weight. Manufacturers grind and micronize raw coral skeleton before encapsulation or tableting for bone density and pH balance applications. Capsule formats dominate current volume owing to dosing precision and portability, though liquid formulations capture above-average margins among senior and pediatric-adjacent buyers. Online retail channels represent the fastest-expanding distribution vector, disintermediating traditional health store gatekeepers.
FDA oversees Current Good Manufacturing Practice enforcement for domestic production facilities, while the Federal Trade Commission polices structure-function advertising claims that lack substantiation. The Dietary Supplement Health and Education Act creates a pre-market notification framework distinct from pharmaceutical pathways, lowering entry barriers but elevating liability exposure for unsubstantiated health assertions. Stakeholders must monitor evolving enforcement priorities between purity testing mandates and permissible marketing language to avoid compliance-driven inventory seizures or consent decrees.
Market Dynamics
The coral calcium supplements market is being fundamentally restructured by the FDA's Current Good Manufacturing Practice enforcement, which is bifurcating manufacturers into certified operators capable of third-party verification and uncertified fringe suppliers facing inventory seizure risk.
Growth Catalysts
- Aging Demographics:Senior consumers seeking bone density maintenance represent the fastest-expanding end-user cohort, creating sustained pull for encapsulated and liquid formulations.
- DSHEA Framework:The Dietary Supplement Health and Education Act's pre-market notification pathway lowers entry barriers compared to pharmaceutical routes, accelerating new product introductions.
- Micronization Technology:Advanced grinding processes producing 35-38% elemental calcium concentrations improve bioavailability claims and support premium positioning.
Market Restraints
- Okinawa Supply Concentration:Marine coral extraction credentials cluster around Japanese island deposits, creating geographic single-source vulnerability for differentiated positioning.
- Calcium Carbonate Substitution:Synthetic and plant-derived calcium alternatives at lower price points threaten volume retention in cost-sensitive buyer segments.
- FTC Advertising Scrutiny:The Federal Trade Commission's structure-function claim policing elevates liability exposure for unsubstantiated pH balance and bone health assertions.
Strategic Opportunities
- Pediatric-Adjacent Formulations:Liquid coral calcium products capture above-average margins among parents seeking trace mineral supplementation for children.
- Online Channel Disintermediation:Direct-to-consumer platforms bypass traditional health store gatekeepers, reducing shelf-access dependency and expanding addressable geography.
- NSF International Certification:Third-party quality verification creates pricing power separation between qualified suppliers and uncertified competitors.
Industry Challenges
- Purity Testing Capex:Heavy metal and contaminant screening infrastructure demands capital investment that strains mid-tier manufacturers.
- Labeling Compliance Timelines:FDA substantiation requirements for structure-function claims extend product launch cycles and increase legal review costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coral Calcium Supplements Market |
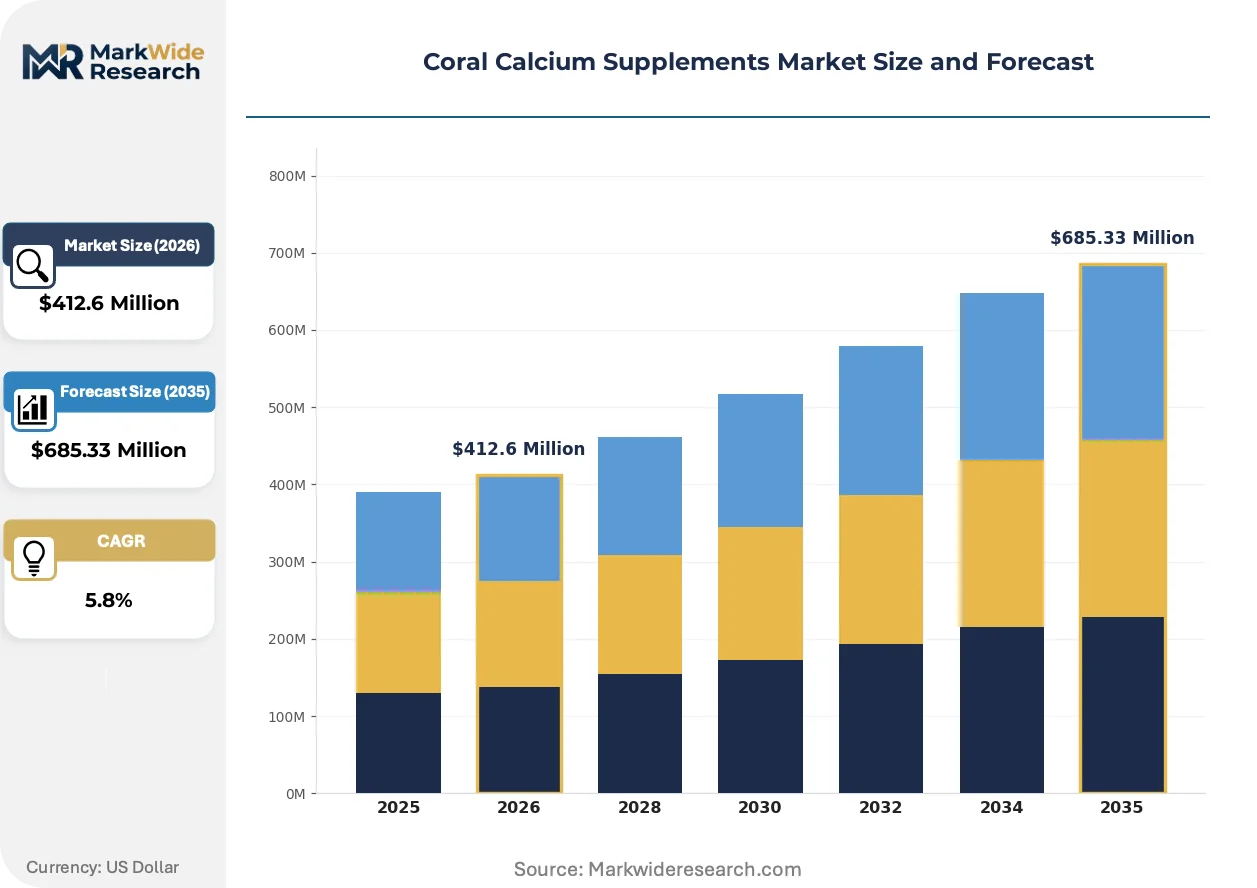
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $685.33 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Capsules, Powder, Liquid, Chewable End User: Adults, Seniors, Athletes, Vegetarians Distribution Channel: Online Retail, Health Stores, Pharmacies, Supermarkets Formulation: Organic, Fortified, Standard, Natural |
| Companies Covered | Nature’s Way, Daily Manufacturing, GNC, Marine Bio, Wonder Laboratories, Coral LLC, Nature’s Sunshine, Natural Biology, NOW Foods, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coral Calcium Supplements Market Evolving Landscape
Formulation science and distribution architecture are actively compressing traditional competitive moats in coral calcium supplements. Three developments merit particular attention.
Micronization equipment is miniaturizing production footprints while maintaining 35-38% elemental calcium output. Regional contract manufacturers in Florida and Arizona are adopting these systems to serve private-label brands without building captive extraction facilities. This technology is miniaturizing the minimum viable scale for quality production, eroding the volume advantages of established integrated players.
REACH registration requirements for imported marine-derived materials are tightening traceability documentation for European-bound shipments. German and Dutch distributors now demand chain-of-custody certification from Okinawa-sourced suppliers. The compliance burden falls heaviest on small importers lacking dedicated regulatory affairs staff, consolidating procurement relationships toward larger verified traders.
Senior buyers are migrating from quarterly health store purchases to subscription-based replenishment through specialized supplement platforms. This behavioral shift disintermediates GNC and independent retailers that historically controlled shelf placement and brand visibility. The United States exhibits the most pronounced channel rotation, where Medicare-eligible consumers demonstrate highest comfort with automated delivery models.
Coral Calcium Supplements Market Segmentation
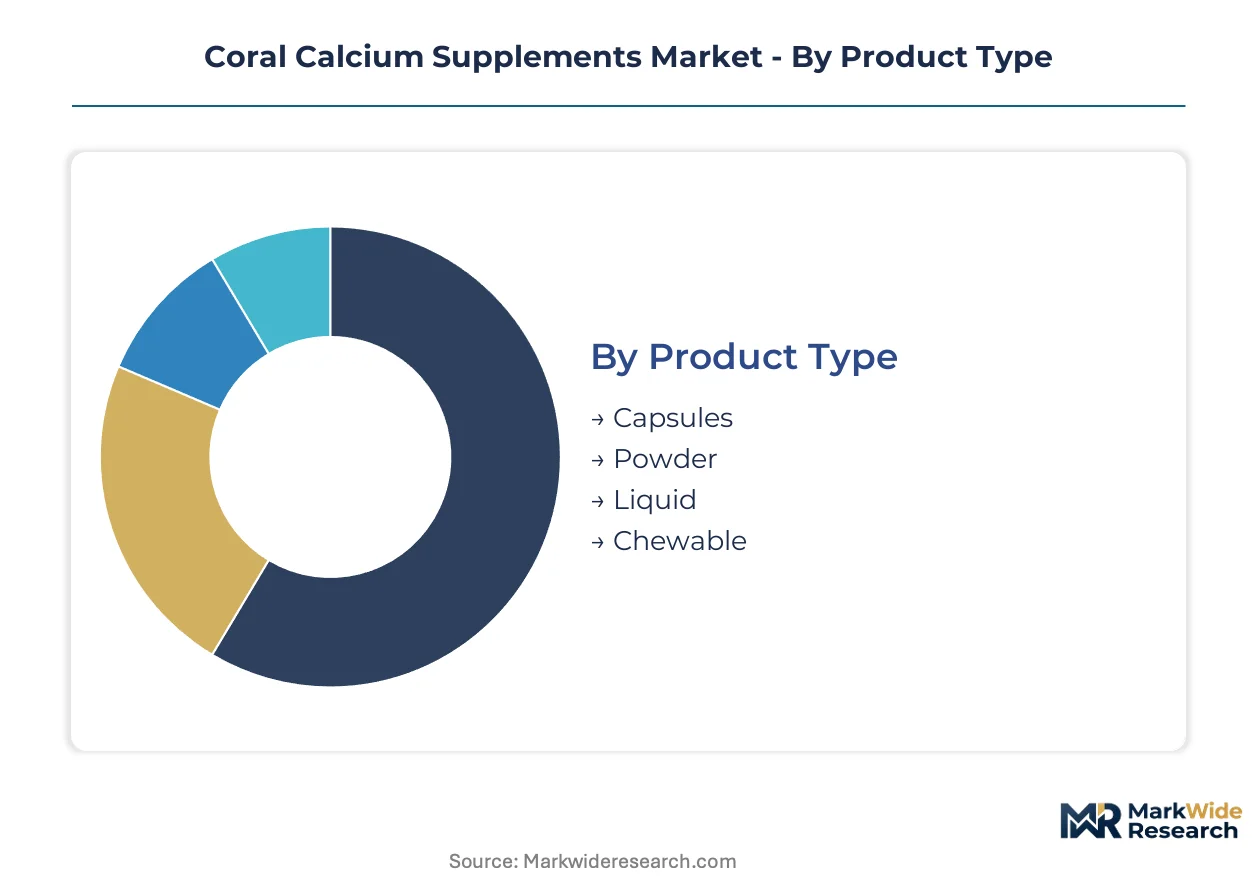
Segmentation in coral calcium supplements reveals where synthetic calcium carbonate and plant-derived alternatives exert maximum pressure. Manufacturers must align formulation investments with the specific substitution vulnerabilities of each product type and end-user cohort.
Product Type:
Capsule and powder formats face the most intense substitution threat from lower-cost calcium carbonate tablets, while liquid formulations maintain defensive moats through pediatric and senior dosing advantages.
- Capsules:Gelatin or vegetable cellulose shells containing 35-38% elemental calcium from micronized coral skeleton. Dosing precision and portability sustain demand among working-age adults in the United States despite price undercutting by synthetic alternatives.
- Liquid:Suspended coral calcium with flavor masking for children and seniors with swallowing difficulties. Parents seeking trace mineral supplementation for children drive above-average margins in this segment.
- Powder:Bulk micronized coral for beverage integration and custom dosing flexibility. Cost-conscious buyers in health store channels favor this format for value-per-serving calculations.
- Chewable:Flavored compressed tablets with reduced elemental calcium density per unit. Limited differentiation from conventional calcium chews constrains premium positioning.
Capsules retain volume leadership; liquid holds the steepest expansion curve.
End User:
Cost tier stratification separates clinically motivated seniors from price-sensitive vegetarians seeking mineral completeness without animal-derived ingredients.
- Seniors:Medicare-eligible consumers prioritizing bone density maintenance with physician-adjacent purchase behavior. Subscription-based replenishment through specialized supplement platforms is displacing quarterly health store visits.
- Adults:Working-age buyers balancing pH balance marketing claims with budget constraints. FTC scrutiny of unsubstantiated structure-function claims elevates liability for brands targeting this cohort.
- Athletes:Trace mineral seekers emphasizing electrolyte recovery and bone stress protection. Niche positioning limits volume scale despite premium pricing tolerance.
- Vegetarians:Mineral-deficiency-avoidance buyers comparing coral-derived against algae-based calcium alternatives. Plant-derived substitute availability constrains willingness-to-pay premiums.
Seniors command the highest per-capita spend; vegetarians face the steepest churn risk to non-coral alternatives.
Distribution Channel:
Geography of buyer comfort with automated replenishment determines channel momentum, with Medicare-eligible populations in the United States leading channel migration.
- Online Retail:Direct-to-consumer platforms with subscription mechanics and third-party verification badges. Disintermediation of health store gatekeepers expands addressable geography beyond traditional retail footprints.
- Health Stores:GNC and independent retailers historically controlling shelf placement and brand visibility. Senior buyer migration to automated delivery models compresses foot traffic dependency.
- Pharmacies:White-coat endorsement environments with pharmacist recommendation leverage. DSHEA framework compliance requirements extend product launch cycles for pharmacy-bound SKUs.
- Supermarkets:Mass-market accessibility with limited staff consultation and price-driven selection. Synthetic calcium carbonate dominance in this channel crowds out coral premium positioning.
Online retail is gaining share fastest; supermarkets remain the most substitution-exposed channel.
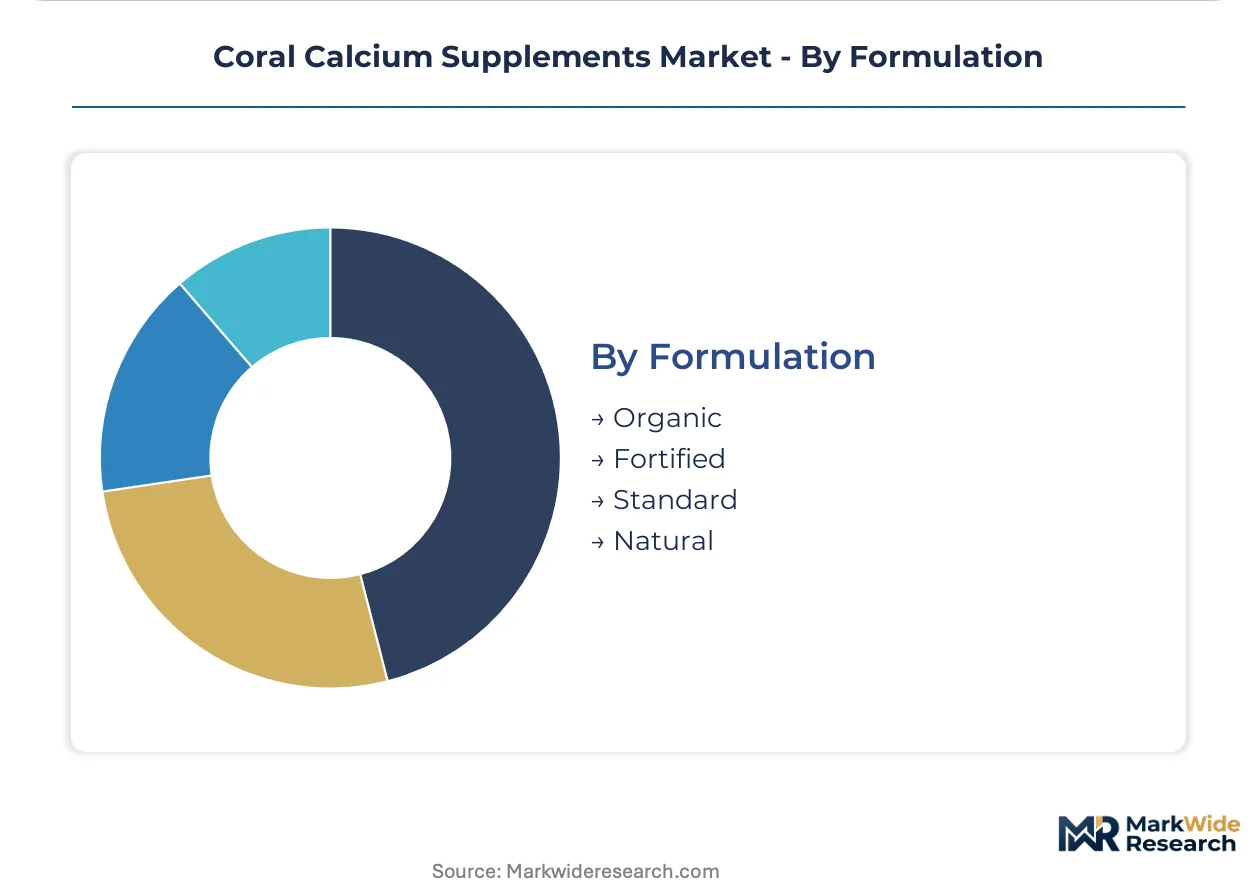
Formulation:
Supply concentration of Okinawa-sourced marine coral credentials bifurcates formulation tiers into verified-origin premium and undifferentiated standard offerings.
- Natural:Unfortified coral calcium with native trace mineral matrix including magnesium and over seventy co-factors. Okinawa extraction credentials support pricing power separation from uncertified competitors.
- Fortified:Coral base with added vitamin D3, K2, or magnesium oxide for enhanced bioavailability claims. Pediatric-adjacent liquid products in this sub-category capture above-average margins.
- Organic:Above-sea fossilized coral deposits certified to organic agricultural input standards. REACH registration requirements for European-bound shipments tighten traceability documentation burdens.
- Standard:Commodity-grade coral calcium without third-party verification or geographic sourcing claims. NSF International certification absence constrains pharmacy and professional channel access.
Natural formulation commands the sourcing premium; fortified is climbing the fastest as manufacturers respond to bioavailability marketing demands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Senior consumers seeking bone density maintenance concentrate demand pull in the United States, where Medicare-eligible populations drive subscription-based replenishment behaviors. Japan and Okinawa supply chains anchor marine coral extraction credentials, while European REACH compliance reshapes import documentation burdens.
United States
Medicare-eligible seniors in Florida and Arizona generate concentrated demand for encapsulated and liquid formulations. The FDA's Current Good Manufacturing Practice enforcement bifurcates domestic manufacturers into certified operators and uncertified fringe suppliers. NOW Foods leverages vertically integrated manufacturing networks from Illinois production facilities to sustain cost discipline.
Japan
Okinawa-sourced marine coral deposits supply extraction credentials that command pricing premiums in professional and pharmacy channels. METI oversight of dietary supplement manufacturing standards elevates documentation requirements for above-sea fossilized coral processors. Marine Bio anchors its competitive positioning through controlled access to Japanese island extraction sites.
Germany
REACH registration requirements for imported marine-derived materials tighten traceability documentation for coral calcium bound for European distribution. EFSA guidance on mineral supplement health claims constrains permissible marketing language for pH balance assertions. German distributors in Hamburg and Frankfurt now demand chain-of-custody certification from Okinawa-sourced suppliers.
Canada
Health Canada and the Natural and Non-prescription Health Products Directorate regulate site licensing for imported coral calcium formulations. Aging demographics in Ontario and British Columbia sustain demand for bone health supplements among seniors seeking alternatives to synthetic calcium carbonate. Vancouver-based importers face elevated compliance timelines for structure-function claim substantiation.
Australia
The Therapeutic Goods Administration classifies coral calcium supplements according to permitted indications and compositional standards. Senior populations in New South Wales and Victoria demonstrate migration toward online subscription platforms for trace mineral replenishment. Sydney distributors consolidate procurement relationships toward larger verified traders capable of sustained regulatory affairs staffing.
Coral Calcium Supplements Market Competitive Landscape
Player mix skews toward vertically integrated manufacturers and specialty marine extractors, with limited presence of diversified pharmaceutical conglomerates. The vendor base separates into three strategic archetypes: Okinawa-credentialed premium-positioned suppliers, cost-disciplined domestic manufacturers with captive micronization capacity, and private-label contract producers serving online direct-to-consumer brands. Competitive moves concentrate on NSF International certification acquisition and geographic expansion of third-party verification credentials.
Within the premium-credentialed tier, Marine Bio and Coral LLC exemplify positioning anchored to Japanese marine extraction provenance. NOW Foods occupies a scale-driven position among domestic manufacturers with backward integration into capsule and powder production. GNC sits within the controlled-access retail archetype, leveraging corporate channel shelf placement against disintermediation pressures from subscription platforms.
| Leading Market Players |
|---|
| Nature's Way |
| Daily Manufacturing |
| GNC |
| Marine Bio |
| Wonder Laboratories |
| Coral LLC |
| Nature's Sunshine |
| Natural Biology |
| NOW Foods |
| Others |
Value Network & Pricing Analysis
Sixty-to-ninety-day Okinawa-to-North America lead times concentrate pricing power among credentialed importers with established FDA import alert clearances, while spot-buyers face inventory volatility that erodes margin predictability across capsule and liquid formulation tiers.
Pricing Analysis
Cost-plus contracts with marine coral feedstock indexation dominate procurement between Okinawa extractors and North American encapsulators, creating three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on NSF International certification status and Okinawa chain-of-custody documentation, with uncertified standard-grade product facing the steepest compression. Cost compression in the economy tier is intensifying because synthetic calcium carbonate alternatives capture price-sensitive vegetarian and adult segments. Medicare-eligible seniors demonstrate lowest price sensitivity, prioritizing verified-origin natural formulations over per-serving cost calculations.
Supply Chain Analysis
Inbound logistics costs from Naha Port congestion and trans-Pacific container availability constraints elevate landed costs for Okinawa-sourced marine coral extract, particularly during Q3 typhoon season disruptions. Supply concentrates in Japan, with secondary processing nodes in the United States and contract manufacturing emerging in Florida and Arizona. Raw material dependencies include fossilized above-sea coral deposits, micronized calcium carbonate intermediates, and gelatin or vegetable cellulose encapsulation materials. Single-source vulnerability around Japanese marine extraction credentials threatens continuity for premium-positioned brands. Distribution runs through direct-to-consumer subscription platforms, disintermediating traditional health store and pharmacy gatekeepers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-stage cyclical recovery driven by Medicare-eligible demographic expansion and subscription-platform channel maturation, with pricing power consolidating toward verified-origin suppliers capable of sustained regulatory compliance investment.
For Market Incumbents: Consolidate procurement relationships toward Okinawa extraction sites with documented METI oversight and captive micronization capacity in Arizona or Florida production nodes. Threat from synthetic calcium carbonate substitution demands defensive certification acquisition, particularly NSF International verification and USP testing protocols that create pharmacy channel access moats. Capacity addition in domestic contract manufacturing preserves margin structure against import logistics volatility. For New Entrants and Emerging Players: Lead with pediatric-adjacent liquid formulations in online direct-to-consumer channels, where above-average margins and lower certification barriers enable rapid scale. The most penetrable white-space sits among parents seeking trace mineral supplementation for children, underserved by incumbent capsule-centric portfolios. Go-to-market execution should emphasize subscription mechanics with automated replenishment and third-party verification badge placement. For Investors and Strategic Acquirers: Long-term, this sits as a demographic-tethered defensive play because Medicare enrollment curves and bone health awareness sustain demand inelasticity through economic cycles. Acquisition target archetype: mid-tier encapsulators with dormant Okinawa sourcing relationships and underutilized NSF certification infrastructure. Signal to watch is FTC enforcement intensity around structure-function claim substantiation, which would accelerate consolidation toward legally resourced incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| NSF International Certification Acquisition | Third-party verification unlocks pharmacy channel access and pricing power separation from uncertified competitors. |
| Okinawa Supply Agreement Expansion | Marine coral extraction credentials from Japanese island deposits defend premium positioning against synthetic substitution. |
| Direct-to-Consumer Platform Launch | Subscription mechanics disintermediate GNC and health store gatekeepers while expanding geographic addressability. |
| Micronization Technology Investment | Advanced grinding equipment maintains 35-38% elemental calcium output with reduced production footprint. |
| Pediatric-Adjacent Formulation Development | Liquid coral calcium with flavor masking captures above-average margins among parents seeking trace mineral supplementation. |
Research Methodology
A standing panel of supplement brand managers, FDA regulatory affairs consultants, health store category buyers, and direct-to-consumer platform operators provided ongoing calibration across primary interview cycles. Secondary validation drew from FDA warning letter databases, FTC enforcement action records, NSF International certification registries, and customs import data for coral-derived calcium carbonate. Bottom-up demand modeling from end-user segmentation triangulated against top-down value chain analysis from extraction through retail.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled segmentation across product type, end-user cohort, distribution channel, and formulation tier, with geographic regulatory clusters as an industry-specific dimension. CAGRs were derived from trend extrapolation adjusted for enforcement intensity and channel migration patterns. Forecast inputs included Medicare enrollment projections, micronization technology diffusion curves, and REACH registration compliance timelines.
Forecasts assume regulatory continuity in FDA DSHEA enforcement and EFSA mineral supplement guidance regimes; material policy shifts would require re-modeling. Specific risk factors include FTC structure-function claim policing intensification, Okinawa supply disruption from marine ecosystem protection measures, and synthetic calcium carbonate price erosion. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Asia Pacific Nutraceuticals Market
Nutritional Supplements
Global Egg Protein Powder Market
Nutritional Supplements
Older Adults Health Supplements Market
Nutritional Supplements
Coq10 Gummies Market
Nutritional Supplements
Europe Feed Prebiotics Market
Nutritional Supplements
Bee Pollen Supplements Market
Nutritional Supplements
Vegan Vitamins and Supplements Market
Nutritional Supplements
Global Nootropics Brain Supplements Market
Nutritional Supplements
Diet Shakes Market
Nutritional Supplements
Policosanol Market
Nutritional Supplements
South America Nutricosmetics Market
Nutritional Supplements
Mediterranean Citrus Nutricosmetic Complex Market
Nutritional Supplements
Nutrition Therapy Market
Nutritional Supplements
Calcium Supplements Market
Nutritional Supplements
Latin America Herbal Supplements Market
Nutritional Supplements
Canada Nutraceuticals Market