
 GCC Edible Meat Market | 2026-2036
GCC Edible Meat Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Edible Meat Market Foresight
Saudi Arabia's poultry capacity build-out is tilting regional supply dynamics toward greater self-sufficiency. JBS S.A. leverages its Brazilian feedlot network to secure consistent container volumes into Jeddah and Dammam. Almarai Company dominates integrated dairy and poultry operations across the Kingdom, while Tanmiah Food Company extends its hatchery-to-retail model with expanded slaughterhouse capacity near Riyadh.
GCC edible meat comprises animal-derived protein products processed under halal certification protocols requiring specific slaughter methods, species eligibility, and post-slaughter inspection. These products serve commercial food service operations and retail households requiring compliance with Islamic dietary law. Fresh meat and processed meat categories anchor volume, with halal meat commanding premium positioning due to certification rigor and religious mandate across Gulf states. Poultry leads animal source volumes given shorter production cycles and lower feed conversion ratios suited to regional climate constraints.
Saudi Food and Drug Authority and UAE's Ministry of Climate Change and Environment enforce import licensing, cold-chain documentation, and halal slaughter certification for market access. These frameworks elevate compliance costs for non-regional suppliers while privileging GCC-based processors with established audit relationships. Stakeholders must monitor evolving local content requirements and subsidy shifts that could redirect procurement from imports toward domestic production investments.
Market Dynamics
Halal certification rigor enforced by Saudi Food and Drug Authority and UAE's Ministry of Climate Change and Environment is restructuring procurement relationships, privileging processors with established audit capacity while elevating compliance costs for new entrants.
Growth Catalysts
- Tourism Infrastructure Expansion:Hotel chains and resort operators across the Gulf are scaling protein procurement volumes to match rising hospitality capacity, particularly in Dubai and Abu Dhabi corridors.
- SFDA Cold-Chain Mandates:Tighter import compliance rules for refrigerated meat shipments are consolidating demand toward certified logistics providers with end-to-end temperature documentation.
- Poultry Production Economics:Shorter production cycles and superior feed conversion ratios under regional climate constraints position poultry as the dominant animal protein source.
Market Restraints
- Feed Input Volatility:Regional dependence on imported soybean and corn exposes margins to commodity price swings and currency fluctuation against supplier currencies.
- Import Concentration Risk:Brazilian feedlot networks supply dominant container volumes into Jeddah and Dammam, creating single-source vulnerability for red meat categories.
- Halal Slaughter Technical Limitation:Manual certification requirements constrain line speeds and automation potential compared to conventional processing jurisdictions.
Strategic Opportunities
- Kuwait and Bahrain Underpenetration:Smaller GCC states with nascent domestic processing infrastructure present first-mover advantages for integrated slaughterhouse-to-retail operators.
- Domestic Production Incentives:Saudi subsidy shifts and local content requirements are redirecting capital toward hatchery and feedlot investments within the Kingdom.
- E-Commerce Cold-Chain Innovation:Direct-to-consumer frozen meat platforms leveraging last-mile refrigerated logistics are capturing household segments outside traditional retail.
Industry Challenges
- Veterinary Certification Talent Scarcity:Shortage of qualified halal inspectors and food safety auditors is extending facility approval timelines and constraining capacity expansion.
- Slaughterhouse Capex Intensity:Automated stun-free processing equipment and dedicated halal lines require substantial capital outlays with extended payback periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Edible Meat Market |
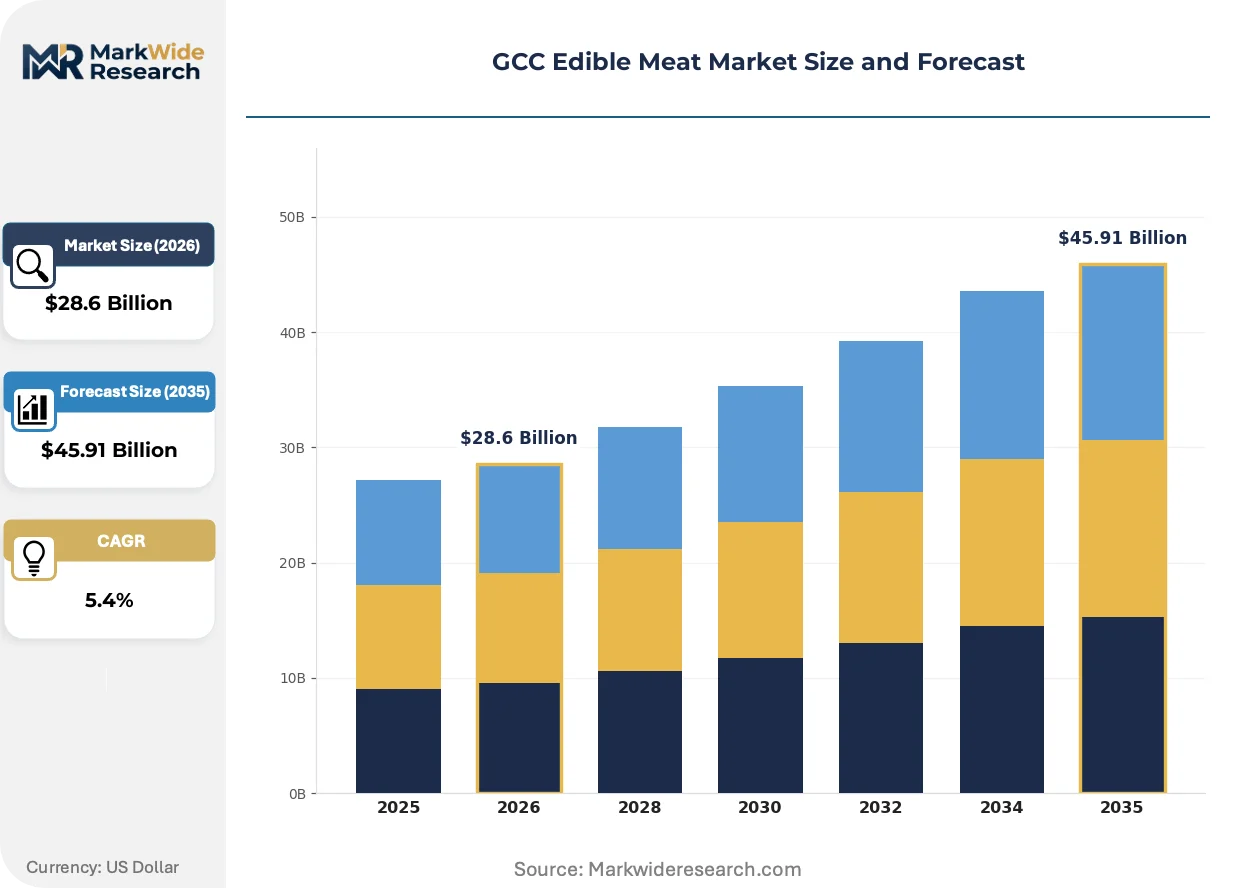
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $45.91 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fresh Meat, Frozen Meat, Processed Meat, Meat Cuts, Halal Meat Animal Source: Beef, Lamb, Poultry, Camel, Goat Distribution Channel: Supermarkets, Hypermarkets, Butcher Shops, Online Retailers, Food Service End User: Households, Hospitality Sector, Catering Services, Institutional Buyers |
| Companies Covered | JBS S.A., Sunbulah Group, Ghitha Holding PJSC, Siniora Food Industries Company, Tanmiah Food Company, Al Islami Foods, Almarai Company, Al Ain Farms, BRF S.A., Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Edible Meat Market Shifts & Advancements
Blockchain traceability and automated compliance documentation are compressing certification timelines while procurement consolidation among hospitality groups is reshaping supplier relationship structures.
Blockchain-enabled halal certification platforms are digitizing supply chain documentation from slaughterhouse to retail shelf. Major hotel procurement departments and government catering contracts now mandate electronic traceability records. This technology is digitizing audit workflows, reducing manual inspection bottlenecks while compressing supplier onboarding cycles from months to weeks.
SFDA's tightened cold-chain compliance protocols are mandating real-time temperature logging for all imported meat shipments. Logistics providers must now maintain continuous data records across maritime, port, and inland distribution segments. Red meat importers face the steepest adjustment costs, with many restructuring supplier contracts to transfer documentation liability upstream.
Consolidated hospitality procurement is displacing fragmented spot-market purchasing across Gulf hotel chains. Volume commitments now span multi-year frameworks with penalty clauses for supply interruption. This pattern concentrates most visibly in the UAE, where international resort operators have centralized protein sourcing decisions at regional headquarters level.
GCC Edible Meat Market Segmentation
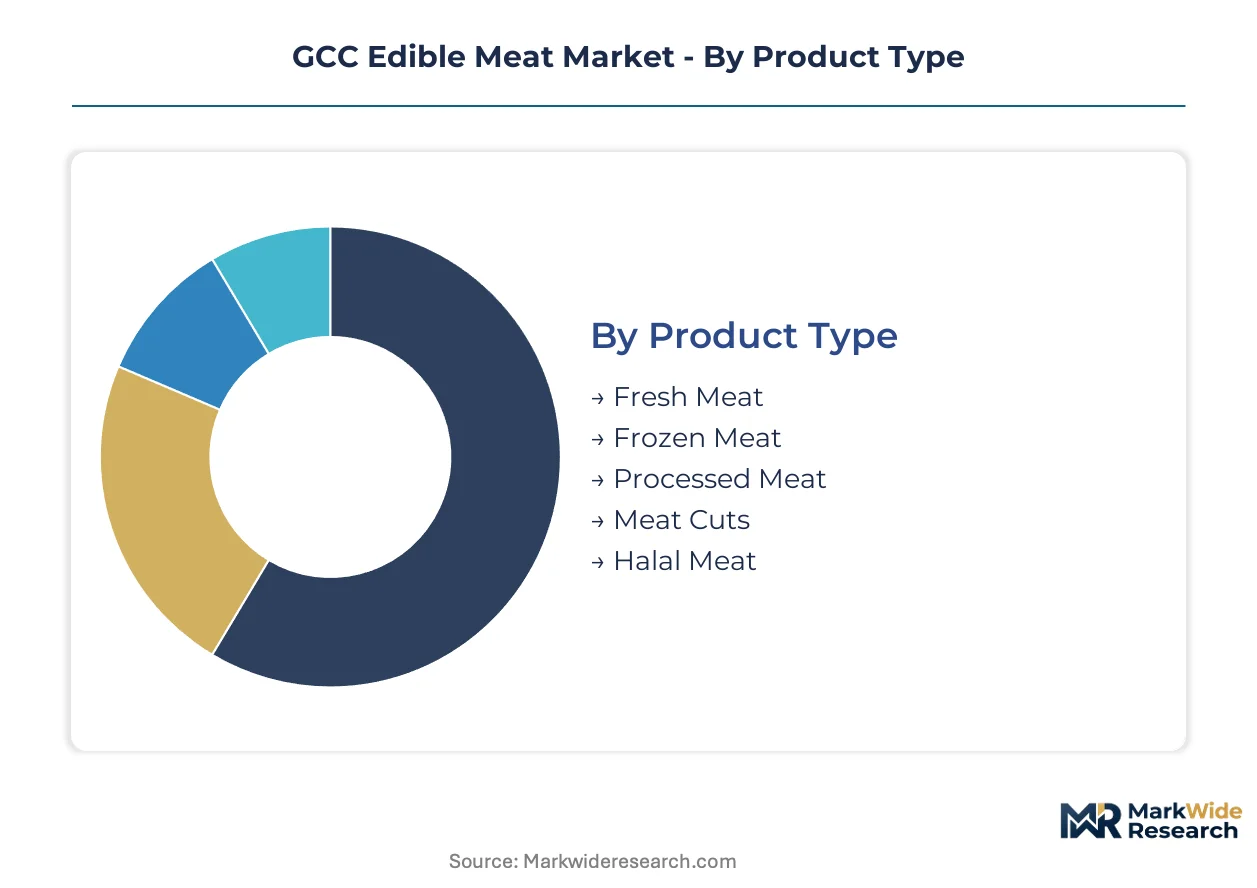
Segmentation reveals how procurement cycles, certification requirements, and temperature sensitivity create divergent margin profiles across the GCC edible meat value chain. Understanding these structural differences enables targeted capacity investments and channel-specific compliance strategies.
Product Type:
Inventory velocity varies dramatically across this category, with fresh meat turning in days while frozen and processed categories extend shelf life from weeks to months.
- Fresh Meat:Unfrozen carcass and primal cuts requiring continuous cold-chain maintenance from slaughterhouse to retail display. Dubai's hotel corridor generates concentrated demand for chilled premium grades with same-day delivery windows.
- Frozen Meat:Blast-frozen at minus 18 degrees Celsius enabling maritime import from Brazilian feedlot networks. Jeddah and Dammam port infrastructure prioritizes containerized frozen volumes given extended storage tolerance.
- Processed Meat:Value-added products including sausages, cured cuts, and ready-to-cook preparations. Manufacturing concentrates in Saudi Arabia's industrial zones near Riyadh.
- Meat Cuts:Portion-controlled specifications for food service and retail tray packs. Kuwait's hospitality sector drives demand for standardized portion weights.
- Halal Meat:Certification-mandated slaughter and processing under SFDA and MOHAP supervision. Religious compliance elevates pricing premiums across all temperature categories.
Fresh meat dominates installed base. Frozen meat is where expansion concentrates.
Animal Source:
Feed conversion efficiency and climate adaptability create stark production economics differences across species.
- Poultry:Six-week grow-out cycles and superior feed conversion ratios under regional heat stress. Tanmiah Food Company and Almarai operate integrated hatchery-to-slaughter networks across Saudi Arabia.
- Beef:Grain-fed and grass-fed categories with Brazilian imports supplying dominant container volumes. JBS S.A. leverages feedlot scale for consistent halal-certified shipments.
- Lamb:Seasonal demand spikes during Ramadan and Hajj pilgrimage periods. Australian and New Zealand exports maintain strong positioning in UAE retail.
- Camel:Traditional protein source with concentrated consumption in Saudi Arabia's central and eastern regions. Local breeding programs receive subsidy support.
- Goat:Niche category serving specific ethnic and regional preferences. Smaller scale imports from South Asia and East Africa.
Poultry commands volume leadership. Beef is climbing the fastest in absolute tonnage.
Distribution Channel:
Customer touchpoint economics range from high-frequency small-basket retail to contracted institutional volumes with penalty clauses for supply interruption.
- Supermarkets:Chilled cabinet retail with halal certification prominently displayed. Carrefour and Lulu Hypermarket chains dominate SKU breadth across UAE and Saudi Arabia.
- Hypermarkets:Bulk-format retail with dedicated butcher counters and custom cutting services. Weekend traffic drives volume concentration in Riyadh and Jeddah.
- Butcher Shops:Traditional neighborhood outlets with live-animal sourcing relationships. Manual certification processes constrain line speeds compared to industrial scale.
- Online Retailers:Direct-to-consumer frozen delivery platforms with last-mile refrigerated logistics. Noon and Talabat expand protein categories in Dubai and Abu Dhabi.
- Food Service:Contracted supply to hotels, restaurants, and catering operations with multi-year framework agreements. UAE hospitality procurement consolidation reshapes supplier relationships.
Food service captures margin premiums. Online retail is gaining share fastest.
End User:
Purchase frequency and certification documentation requirements vary from daily household replenishment to quarterly institutional tenders with audit stipulations.
- Hospitality Sector:International hotel chains and resort operators with centralized procurement at regional headquarters level. Dubai and Abu Dhabi corridors scale protein volumes to match tourism capacity expansion.
- Households:Retail-dependent consumption with preference for fresh chilled cuts in premium segments and frozen value packs in mass market.
- Catering Services:Event-driven and contract food service with batch preparation requirements. Government and corporate contracts mandate electronic traceability records.
- Institutional Buyers:Military, hospital, and educational facility procurement with extended tender cycles and strict halal audit protocols.
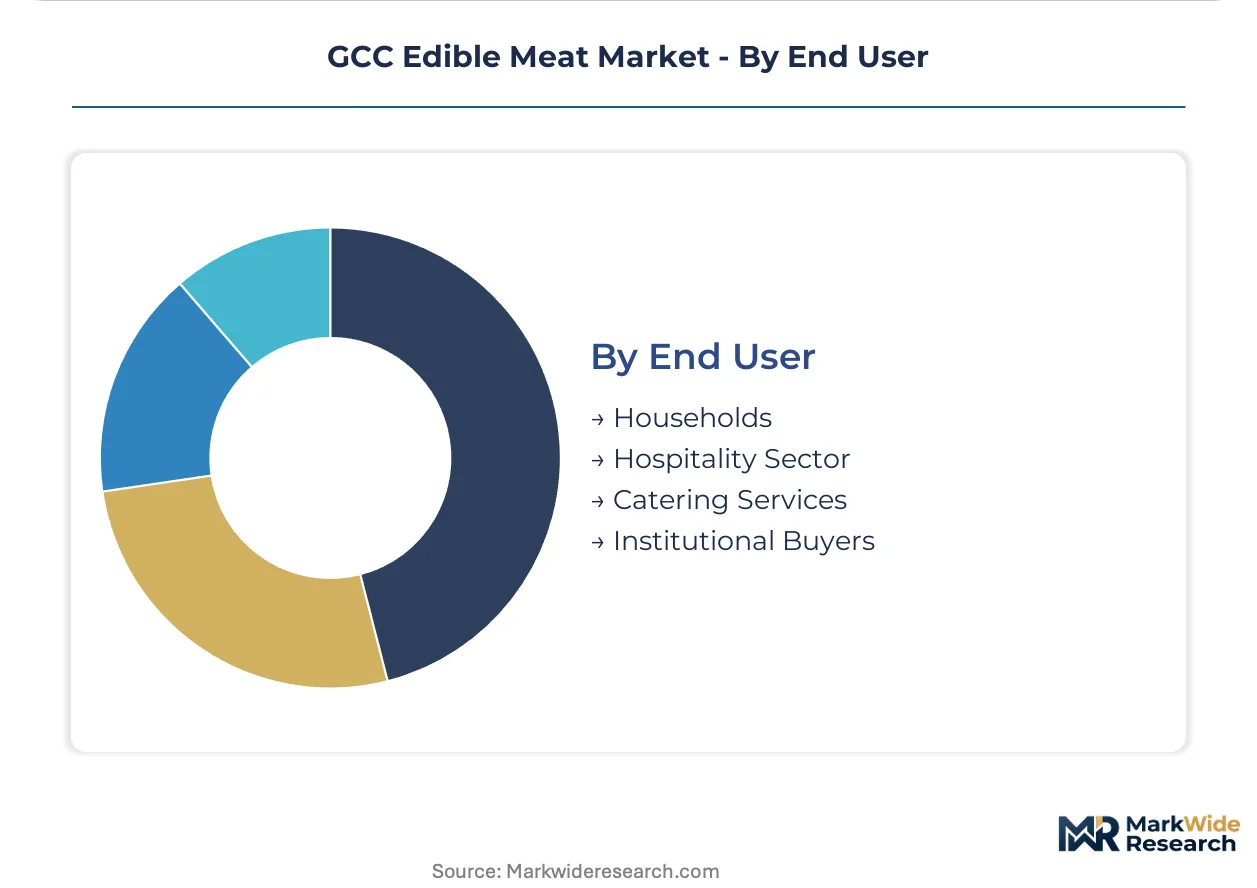
Households dominate installed base. Hospitality sector is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jeddah Islamic Port and King Abdulaziz Port in Dammam anchor the GCC's refrigerated import infrastructure, handling containerized frozen meat volumes from Brazilian feedlot networks. These maritime gateways connect to cold-chain corridors serving Riyadh, Dubai, and Abu Dhabi hospitality clusters.
Saudi Arabia
Riyadh's expanding hotel inventory and NEOM tourism development drive protein procurement scaling. SFDA mandates real-time temperature logging for all imported meat shipments, consolidating demand toward certified logistics providers. Tanmiah Food Company operates integrated hatchery-to-slaughter networks near Riyadh, capturing domestic production incentives.
United Arab Emirates
Dubai's hospitality corridor and Abu Dhabi's resort developments concentrate food service demand for premium chilled cuts. MOHAP enforces halal slaughter certification and electronic traceability records for government catering contracts. Jebel Ali Port's reefer container infrastructure prioritizes Brazilian beef imports for redistribution across Gulf states.
Kuwait
Nascent domestic processing infrastructure creates first-mover opportunities for integrated slaughterhouse operators. The country's national food safety regulator maintains strict import licensing for refrigerated meat shipments. Kuwait City's hospitality sector relies on spot-market purchasing with limited multi-year procurement frameworks.
Qatar
Hamad Port's cold-chain expansion supports hospitality procurement for FIFA-legacy tourism infrastructure. The national food safety authority aligns halal certification protocols with Saudi and UAE standards. Doha's hotel procurement departments increasingly mandate electronic traceability records from suppliers.
Bahrain
Underpenetrated retail and food service channels present expansion vectors for direct-to-consumer frozen meat platforms. The national food control directorate enforces import documentation for refrigerated shipments. Manama's traditional butcher shops dominate household purchasing despite hypermarket format growth.
GCC Edible Meat Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in feedstock and certification services. The vendor base organizes around three archetypes: Brazilian feedlot-scale exporters with consistent container volumes, Saudi integrated poultry processors with hatchery-to-retail control, and UAE-based trading houses managing import logistics. Competitive moves concentrate on backward integration into captive hatchery capacity and multi-year hospitality procurement frameworks with penalty clauses.
Among Brazilian-origin exporters, JBS S.A. anchors the feedlot-scale archetype with consistent halal-certified shipments. Saudi-based integrated operators include Almarai Company and Tanmiah Food Company, representing the domestic production pivot. These three exemplify the structural divergence between import-dependent and self-sufficiency-oriented competitive strategies across the GCC protein supply base.
| Leading Market Players |
|---|
| JBS S.A. |
| Sunbulah Group |
| Ghitha Holding PJSC |
| Siniora Food Industries Company |
| Tanmiah Food Company |
| Al Islami Foods |
| Almarai Company |
| Al Ain Farms |
| BRF S.A. |
| Others |
Supply & Pricing Matrix
Brazilian feedlot concentration upstream anchors margin capture at Jeddah and Dammam port terminals, with JBS S.A. container volumes dictating red meat pricing benchmarks across Gulf hospitality procurement desks.
Pricing Analysis
SFDA halal certification mandates dictate the pricing tier structure across fresh, frozen, and processed categories. Three-tier pricing structure across premium chilled cuts, standard frozen imports, and economy value packs separates hospitality-grade specifications from retail mass market. Pricing pressure stems from feed input volatility in Brazilian reais and Saudi subsidy shifts toward domestic poultry. Food service buyers demonstrate lowest price sensitivity given penalty clauses for supply interruption, while household segments concentrate demand around promotional frozen volumes.
Supply Chain Analysis
JBS S.A., Almarai Company, and Tanmiah Food Company hold dominant processing and import capacity across the GCC protein network. Geographic supply concentration centers on Brazil for beef feedlot exports, Saudi Arabia for integrated poultry operations, and Australia for seasonal lamb shipments. Raw material dependencies rest on imported soybean and corn feedstock, refrigerated container fleets, and halal-certified slaughter equipment. Single-source vulnerability runs through Brazilian red meat corridors. Distribution runs through Jeddah Islamic Port and King Abdulaziz Port connecting to Riyadh and UAE hospitality clusters.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Blockchain-enabled halal traceability platforms are creating platform-economics inflection, with interoperability mandates from Saudi and UAE regulators forcing supplier ecosystem consolidation around digitized certification workflows.
For Market Incumbents: Entrench multi-year hospitality procurement frameworks with electronic traceability integration to lock out spot-market competitors. SFDA cold-chain documentation requirements create compliance moats that privilege established audit relationships. Backward integration into captive hatchery capacity secures margin pools threatened by Brazilian feedlot price volatility.
For New Entrants and Emerging Players: Build out direct-to-consumer frozen meat platforms targeting Bahrain and Kuwait household segments outside traditional retail dominance. Underpenetrated domestic processing infrastructure in smaller GCC states offers first-mover slaughterhouse-to-retail positioning. Last-mile refrigerated logistics partnerships with regional delivery apps provide go-to-market velocity without legacy retail slotting costs.
For Investors and Strategic Acquirers: Capital is best deployed toward integrated poultry operators with hatchery-to-slaughter control and established SFDA audit relationships across the analysis window. Acquisition targets should demonstrate electronic traceability platform deployment and multi-year hospitality contract backlog. Quarterly review of Saudi subsidy allocation shifts and Brazilian real exchange rate movement is advised to detect margin inflection.
| Strategic Initiative | Industry Significance |
|---|---|
| Blockchain Traceability Platform Deployment | SFDA and MOHAP mandates compress supplier onboarding from months to weeks for certified operators. |
| Backward Integration into Hatchery Capacity | Tanmiah Food Company model captures domestic production incentives and reduces feed cost exposure. |
| Multi-Year Hospitality Procurement Framework | UAE resort operator consolidation creates volume commitments with penalty clauses for supply interruption. |
| Cold-Chain Logistics Certification Investment | Real-time temperature logging compliance consolidates demand toward certified maritime and inland providers. |
| E-Commerce Direct-to-Consumer Launch | Noon and Talabat expansion into frozen protein captures household segments outside traditional retail channels. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of SFDA regulatory filings, MOHAP import licensing databases, and GCC customs trade records. Primary interviews engaged halal certification auditors, hospitality procurement directors, cold-chain logistics operators, and poultry processing executives. Secondary validation drew from Saudi Food and Drug Authority compliance bulletins, UAE Ministry of Climate Change and Environment import protocols, and Brazilian agricultural export statistics. Bottom-up volume modeling triangulated against top-down macroeconomic consumption projections.
Forecast inputs span animal source segmentation across poultry, beef, and lamb categories; temperature state differentiation between fresh, frozen, and processed; and distribution channel splits across food service, retail, and online platforms. CAGRs were derived from trend extrapolation adjusted for regulatory intervention timing and subsidy policy shifts. Feed conversion ratio improvements and halal inspector training pipeline constraints informed supply-side elasticity assumptions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Brazilian feedlot exporters or Saudi domestic production subsidizers would shift outcomes. Quarterly review of SFDA certification backlog duration and Jeddah port reefer container dwell times is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Brazil Meat Products Market
Meat Products
France Meat Products Market
Meat Products
Fresh Organic Chicken Market
Meat Products
Global Canned Meat Market
Meat Products
Middle East Red Meat Market
Meat Products
Organic Lamb Market
Meat Products
Brisket Market
Meat Products
Meat Tenderizer Market
Meat Products
Global Edible Meat Market
Meat Products
Saudi Arabia Goat Meat and Cheese Market
Meat Products
Vegan Meatball Market
Meat Products
Edible Offal Market
Meat Products
United States Bacon Market
Meat Products
Meat Flavors Market
Meat Products
Qatar Poultry Meat Market
Meat Products
Low Fat Sausage Market