
 Asia-Pacific Meal Replacement Products Market | 2026-2036
Asia-Pacific Meal Replacement Products Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Meal Replacement Products Market Outlook
Precision fermentation and enzymatic protein processing is narrowing the cost gap between plant-based and dairy-derived formulations across the Asia-Pacific region. Abbott Laboratories leverages its clinical nutrition heritage to anchor hospital and pharmacy channels with medical-grade shakes. Glanbia PLC competes through backward integration into whey and plant protein sourcing, sustaining margin control across volatile raw material cycles. Danone SA specializes in fermented protein matrices, differentiating its ready-to-drink portfolio from commodity shake competitors.
Asia-Pacific meal replacement products encompass formulated food systems delivering complete macro- and micronutrient profiles in controlled caloric doses, typically manufactured via spray-drying, cold-pressed bar formation, or aseptic liquid filling with protein contents ranging from 15g to 40g per serving. These products serve commercial purposes spanning weight management protocols, athletic recovery regimens, and convenience nutrition for time-constrained consumers. Ready-to-drink formats command premium shelf positioning in Japanese convenience retail, while powder segments dominate Australian online subscription channels through bulk purchasing economics. Vegan dietary preference offerings accelerate fastest in South Korean and Indian metros, though keto-positioned lines retain higher per-unit margins across premium health store networks.
China's SAMR enforces GB standard compliance for nutritional fortification claims, while Australia's FSANZ mandates rigorous substantiation for weight management and sports performance assertions. Japan's Consumer Affairs Agency tightens functional food labeling under Foods with Function Claims protocols, restricting unverified metabolic benefit statements. India's FSSAI progressively aligns with Codex Alimentarius protein quality metrics, reshaping import eligibility for multinational powder suppliers. Stakeholders must monitor evolving protein source sustainability mandates and digital health claim enforcement to calibrate regional portfolio priorities.
Market Dynamics
Precision fermentation and enzymatic protein processing are compressing cost structures across Asia-Pacific formulation facilities, forcing incumbent manufacturers to recalibrate sourcing strategies or surrender margin to biotechnology-enabled entrants.
Growth Catalysts
- Japan's Foods with Function Claims framework:Permits substantiated metabolic benefit statements on ready-to-drink packaging, accelerating premium positioning for fermented protein matrices in Tokyo-Osaka convenience retail corridors.
- Urban work-hour compression:Professionals across Shanghai, Sydney, and Seoul compress meal windows below 20 minutes, concentrating demand for shelf-stable liquid formats in metropolitan transit hubs.
- Precision fermentation scale-up:Singapore and Australian biotech clusters achieve cost parity with whey isolate for mycoprotein and microbial biomass, enabling clean-label vegan lines at dairy-competitive price points.
Market Restraints
- Whey protein concentrate volatility:Oceania dairy commodity auctions transmit price swings directly into powder formulation costs, squeezing mid-tier brands without captive milk processing contracts.
- China SAMR GB standard compliance:Nutritional fortification claim substantiation requires 12-18 month clinical dossier preparation, creating regulatory moats that delay multinational portfolio launches.
- Soy protein digestibility limitations:PDCAAS scoring gaps versus dairy isolate restrict medical nutrition positioning, confining plant-based entrants to wellness rather than clinical channels.
Strategic Opportunities
- India's tier-two urban corridors:Pune, Hyderabad, and Ahmedabad exhibit protein deficiency awareness without saturated competition, offering first-mover subscription economics for localized flavor development.
- South Korean MFDS functional food pathway:Streamlined approval for blood glucose management claims creates regulatory arbitrage for diabetic-targeted meal replacement lines versus stricter Australian TGA requirements.
- Direct-to-hospital procurement channels:Post-acute care facilities in Japan and Australia seek enteral nutrition alternatives, opening institutional volumes for medical-grade shake formulations with reimbursement coding.
Industry Challenges
- Cross-border e-commerce labeling fragmentation:Platform-specific compliance for Tmall Global, Rakuten, and Shopee requires parallel packaging runs, inflating working capital intensity for regional SKU proliferation.
- Flavor chemist scarcity:Formulation expertise bridging traditional Asian taste profiles with Western protein bases concentrates in Singapore and Melbourne, creating recruitment bottlenecks for expansion into Southeast Asian markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Meal Replacement Products Market |
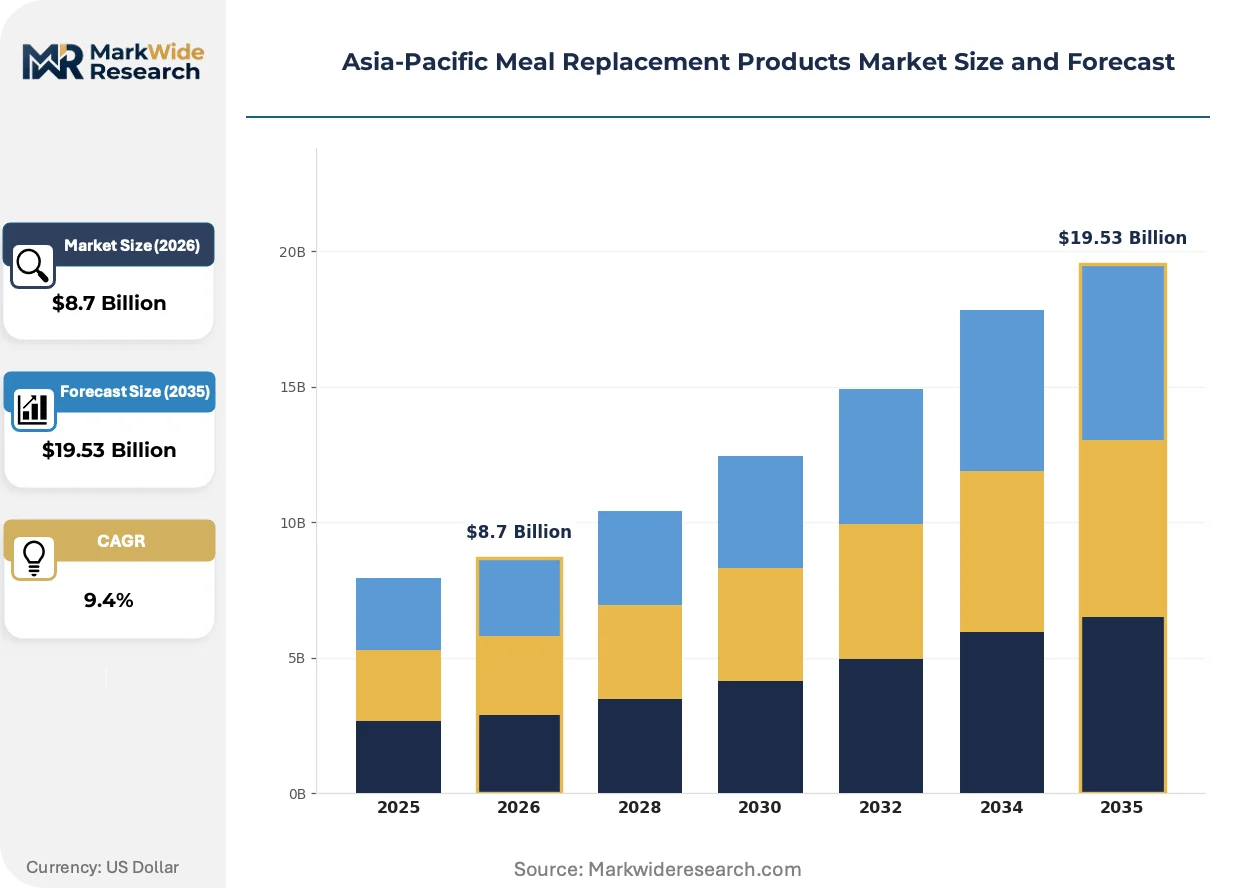
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bars, Shakes, Powders, Ready-to-Drink Dietary Preference: Vegan, Keto, Gluten-Free, Low-Calorie Distribution Channel: Supermarkets, Online Retail, Health Stores, Pharmacies End User: Athletes, Fitness Enthusiasts, Busy Professionals, Weight Watchers |
| Companies Covered | Abbott Laboratories, Formulite Pty Ltd, Glanbia PLC, Danone SA, Bulk Nutrients, Nestlé SA, Herbalife Nutrition, Sun Pharmaceutical Industries Limited, Amway Corp., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Meal Replacement Products Market Strategic Shifts
Digital commerce infrastructure and biotechnology maturation are converging to compress product development cycles and redistribute channel power away from traditional pharmacy and mass retail gatekeepers across Asia-Pacific markets.
Smart packaging embedded with NFC tags is digitizing supply chain transparency and consumer engagement simultaneously. Japanese and Australian premium brands deploy blockchain-traceable protein sourcing data accessible via smartphone tap, converting packaging into retention tools. This capability is digitizing loyalty program economics by collapsing the cost of personalized nutrition coaching previously delivered through separate app ecosystems.
China's SAMR enforcement of GB 28050 nutrition labeling revisions tightens permissible variance between declared and actual micronutrient content. Manufacturers must retest batch stability across accelerated shelf-life protocols, elevating quality assurance headcount. Powder segments targeting weight management claims face disproportionate scrutiny, driving reformulation toward conservative fortification levels that sacrifice differentiation.
Subscription commerce is displacing traditional replenishment purchasing in Australian and South Korean metropolitan markets. Direct-to-consumer platforms capture recurring revenue through algorithmic flavor rotation and portion customization, extracting lifetime value exceeding conventional retail transactions. This model concentrates most intensely among dual-income households in Sydney and Seoul where pantry space constraints favor just-in-time delivery over bulk powder storage.
Asia-Pacific Meal Replacement Products Market Segmentation
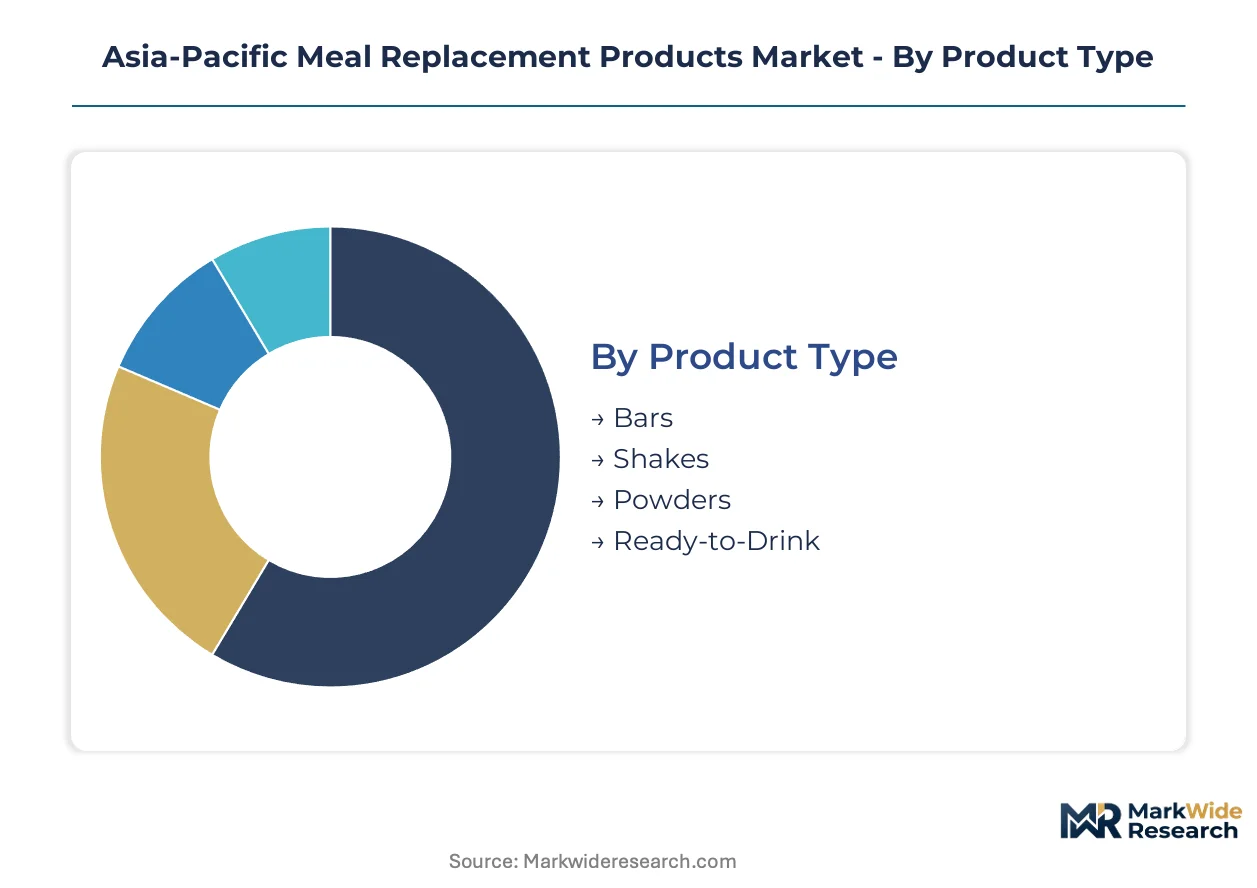
Asia-Pacific meal replacement markets fragment across four intersecting dimensions that determine formulation priorities, channel economics, and regulatory exposure. Product format selection dictates manufacturing capital intensity, while dietary positioning calibrates margin structure against addressable population share.
Product Type:
Mature formats dominate shelf space in established metropolitan markets, while emerging liquid technologies capture premium positioning in transit-oriented consumption corridors.
- Ready-to-Drink:Aseptically filled liquid formulations with 15-40g protein per serving, stabilized through UHT processing and cold-chain distribution. Demand concentrates in Tokyo, Shanghai, and Sydney CBD convenience networks where sub-20 minute meal windows compress consumption occasions. Japanese 7-Eleven and Lawson chains allocate refrigerated premium facings to fermented protein matrices with substantiated metabolic claims under Foods with Function Claims protocols.
- Powders:Spray-dried or agglomerated blends requiring reconstitution, offering bulk purchasing economics and extended shelf stability. Australian subscription platforms and South Korean e-commerce aggregators concentrate recurring revenue through algorithmic flavor rotation and portion customization. Powder segments face disproportionate SAMR scrutiny under GB 28050 labeling revisions, driving conservative fortification levels.
- Shakes:Pre-portioned single-serve sachets or bottled mixes targeting gym-adjacent consumption and travel portability.
- Bars:Cold-pressed or extruded solid formats with binding systems stabilizing macro-nutrient density across temperature variations.
Powders handle the majority of throughput; Ready-to-Drink is expanding most quickly on share as urban work-hour compression intensifies.
Dietary Preference:
Cost tier stratification separates clinical-grade positioning from wellness-oriented mass market entries, with premium tiers commanding 3-4x unit economics.
- Keto:High-fat, ultra-low-carbohydrate formulations with 70-75% caloric contribution from lipids, targeting metabolic state maintenance. Premium health store networks across Melbourne, Singapore, and Seoul allocate dedicated shelf sections, sustaining per-unit margins above standard protein lines despite smaller addressable populations.
- Vegan:Plant-protein matrices utilizing pea, rice, or precision-fermented mycoprotein isolates. Singapore and Australian biotech clusters achieve cost parity with dairy isolate, enabling clean-label positioning at competitive price points. South Korean and Indian metros show steepest adoption curves as sustainability consciousness intersects with lactose intolerance prevalence.
- Gluten-Free:Formulations eliminating wheat, barley, and rye derivatives for celiac and sensitivity populations.
- Low-Calorie:Portion-controlled systems below 200 kcal per serving, targeting deficit-phase weight management protocols.
Keto lines sustain margin leadership; Vegan offerings are gaining share fastest as precision fermentation scales.
Distribution Channel:
Channel selection determines working capital intensity, with direct-to-consumer models compressing inventory cycles versus retail gatekeeper dependence.
- Online Retail:Subscription platforms and marketplace aggregators capturing recurring revenue through algorithmic replenishment. Sydney and Seoul dual-income households drive just-in-time delivery economics, displacing bulk pantry storage. Cross-border e-commerce fragmentation across Tmall Global, Rakuten, and Shopee requires parallel packaging compliance, inflating SKU proliferation costs.
- Supermarkets:Mass retail placement demanding slotting fees and promotional calendar conformity, concentrating volume in China's tier-one cities and Australian metropolitan corridors.
- Health Stores:Specialty retail with trained staff consultation, anchoring premium positioning for keto and clinical-grade lines.
- Pharmacies:Hospital and community pharmacy channels requiring reimbursement coding and medical-grade manufacturing certifications.
Supermarkets move the largest absolute volume; Online Retail shows the steepest expansion trajectory as subscription commerce matures.
End User:
Customer type segmentation aligns formulation specifications with physiological demands and consumption occasion constraints.
- Busy Professionals:Time-constrained urban workers across Shanghai, Tokyo, and Sydney compressing meal windows below 20 minutes. This segment drives ready-to-drink format premiumization and transit-hub placement economics.
- Athletes:Performance-oriented consumers requiring 25-40g protein per serving with rapid absorption kinetics and electrolyte fortification.
- Fitness Enthusiasts:Recreational exercisers seeking convenient macro-nutrient control without competitive-grade specifications.
- Weight Watchers:Calorie-deficit seekers utilizing portion-controlled systems for body composition management protocols.
Busy Professionals generate the highest per-capita spend; Athletes are climbing fastest on volume contribution as sports nutrition mainstreams.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Australia exports whey protein concentrate and milk solids to Southeast Asian formulation facilities, while China manufactures finished powders and ready-to-drink formats for domestic consumption and regional re-export into Vietnam and Thailand.
China
Tier-one cities Shanghai, Beijing, and Shenzhen concentrate demand from time-pressed professionals compressing meal windows below 20 minutes. SAMR enforces GB 28050 nutrition labeling revisions that tighten permissible variance between declared and actual micronutrient content. Yangtze River Delta biotech clusters advance precision fermentation scale-up for mycoprotein production at cost parity with dairy isolate.
Japan
Tokyo-Osaka convenience retail corridors allocate premium refrigerated facings to fermented protein matrices with substantiated metabolic claims. The Consumer Affairs Agency administers Foods with Function Claims protocols that permit verified benefit statements on packaging. Kanto region formulation facilities specialize in aseptic liquid filling technologies for UHT-stabilized ready-to-drink formats.
Australia
Sydney and Melbourne dual-income households drive subscription commerce economics through algorithmic flavor rotation and just-in-time delivery. FSANZ mandates rigorous substantiation for weight management and sports performance assertions on product labels. Victoria-based powder manufacturers leverage backward integration into Oceania dairy commodity auctions to manage whey protein concentrate cost volatility.
South Korea
Seoul Capital Area professionals adopt vegan dietary preference offerings at the steepest regional adoption curve as sustainability consciousness intersects with lactose intolerance prevalence. MFDS operates a streamlined functional food approval pathway for blood glucose management claims. Busan-Ulsan industrial corridors house flavor chemist expertise bridging traditional Korean taste profiles with Western protein bases.
India
Pune, Hyderabad, and Ahmedabad tier-two urban corridors exhibit protein deficiency awareness without saturated competition from incumbent brands. FSSAI progressively aligns with Codex Alimentarius protein quality metrics, reshaping import eligibility for multinational powder suppliers. Maharashtra-based contract manufacturers develop localized flavor profiles for subscription-based powder delivery targeting first-mover economics.
Asia-Pacific Meal Replacement Products Market Competitive Environment
Channel-controlling players compete with product-specialist players across pharmacy, convenience retail, and direct-to-consumer subscription platforms. The market structure tiered across clinical nutrition heritage brands, biotechnology-enabled clean-label entrants, and mass-market commodity powder suppliers. Three strategic archetypes dominate: hospital-channel anchors leveraging reimbursement coding, fermentation-technology differentiators, and subscription-commerce native brands. Competitive moves concentrate on backward integration into protein sourcing and geographic licensing partnerships for regulatory market access.
Within the clinical nutrition tier, Abbott Laboratories and Glanbia PLC exemplify divergent sourcing strategies for margin control. Abbott leverages its heritage position to anchor hospital and pharmacy channels with medical-grade shake formulations. Glanbia competes through upstream control over whey and plant protein supply chains. Danone SA occupies a differentiated position specializing in fermented protein matrices. Among Asia-Pacific regional specialists, Formulite Pty Ltd and Bulk Nutrients represent subscription-commerce native architectures targeting Australian metropolitan markets with algorithmic replenishment models.
| Leading Market Players |
|---|
| Abbott Laboratories |
| Formulite Pty Ltd |
| Glanbia PLC |
| Danone SA |
| Bulk Nutrients |
| Nestlé SA |
| Herbalife Nutrition |
| Sun Pharmaceutical Industries Limited |
| Amway Corp. |
| Others |
Value Chain & Pricing Dynamics
Yangtze River Delta biotech clusters anchor regional mycoprotein capacity, transmitting cost advantages downstream to formulation facilities that command pricing power in vegan-ready-to-drink segments. This geographic concentration tightens margin structures for mid-tier brands lacking captive fermentation contracts or backward integration into precision protein sourcing.
Pricing Analysis
Oceania dairy commodity auctions index whey protein concentrate contracts, transmitting price volatility directly into powder formulation costs. Three-tier pricing structure across premium, standard, and economy levels separates medical-grade shakes with reimbursement coding from mass-market subscription powders and convenience retail commodity lines. Pricing pressure stems from precision fermentation scale-up achieving cost parity with dairy isolate, compressing premiums on plant-based positioning. Price-sensitive fitness enthusiasts in Australian subscription channels drive volume, while hospital procurement managers show lowest sensitivity due to reimbursement pass-through mechanics.
Supply Chain Analysis
Contract manufacturing concentrates among Victoria-based powder processors, Kanto region aseptic liquid filling facilities, and Maharashtra flavor development houses. Raw material dependencies rest on Oceania whey auctions, Singapore mycoprotein fermentation output, and Indian pea protein isolate streams. Single-source vulnerability runs through precision fermentation capacity concentrated in Singapore-Australian biotech corridors. Distribution runs through direct-to-consumer subscription platforms, pharmacy networks with reimbursement coding, and convenience retail chains with refrigerated premium facings.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory entrenchment constructs durable defensive moats in this market, as SAMR GB standard compliance timelines and Foods with Function Claims substantiation requirements delay challenger brand entry by 12-18 months.
For Market Incumbents: Pre-empt biotechnology-enabled entrants by securing exclusive precision fermentation offtake agreements with Singapore-Australian clusters before cost parity erodes dairy-protein margin premiums. Anchor hospital and pharmacy channels with medical-grade shake formulations carrying reimbursement coding to lock out commodity competitors from clinical nutrition positioning.
For New Entrants and Emerging Players: Pursue India's tier-two urban corridors—Pune, Hyderabad, Ahmedabad—where protein deficiency awareness runs high without incumbent brand saturation. Localized flavor development targeting traditional taste profiles offers the most penetrable entry vector, with subscription-based direct-to-consumer platforms providing working capital-efficient scale economics.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors fermentation-technology differentiators with clean-label vegan lines at dairy-competitive price points. Long-term viability hinges on backward integration into protein sourcing and regulatory market access partnerships. Watch SAMR enforcement intensity on GB 28050 labeling revisions as the inflection signal for compliance-cost barriers shifting competitive dynamics.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Singapore-Australian biotech clusters achieve mycoprotein cost parity with whey isolate, enabling clean-label vegan positioning. |
| Regulatory Market Access Partnership | Geographic licensing with local contract manufacturers accelerates SAMR GB standard compliance without 12-18 month dossier preparation. |
| Direct-to-Consumer Subscription Launch | Algorithmic flavor rotation and just-in-time delivery capture lifetime value exceeding conventional retail transactions in Sydney-Seoul corridors. |
| Hospital Channel Reimbursement Strategy | Medical-grade shake formulations with enteral nutrition coding secure institutional volumes in Japanese and Australian post-acute care facilities. |
| Backward Integration into Protein Sourcing | Captive supply of whey concentrate or mycoprotein isolates insulates margin control from Oceania dairy auction volatility. |
Study Parameters
Initial hypotheses were tested against primary input from brand managers at multinational nutrition companies, regulatory affairs leads navigating SAMR and FSANZ frameworks, hospital procurement managers overseeing enteral nutrition contracts, and flavor chemists bridging Asian taste profiles with Western protein bases, then refined through secondary validation against customs records, FSANZ substantiation databases, Foods with Function Claims registries, and Nielsen retail audit data. Bottom-up demand modeling across metropolitan consumer segments was triangulated with top-down supply-side capacity assessments from biotech cluster disclosures.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, with segmentation dimensions spanning product format, dietary preference, distribution channel, and end-user archetype. CAGRs were derived from fitted growth curves calibrated to protein source substitution elasticities and urban work-hour compression indices. Forecast inputs incorporated precision fermentation cost decline trajectories and regulatory enforcement intensity scoring for nutrition labeling compliance.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending indices or dairy commodity auction clearing prices would shift the trajectory of premium-format adoption and plant-protein substitution rates. Quarterly review of SAMR enforcement actions, Oceania GlobalDairyTrade auction results, and MFDS functional food approval volumes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
United States Hemp Protein Market
Alternative Food Sources
North America Insect Protein Market
Alternative Food Sources
North America Meat Substitutes Market
Alternative Food Sources
Insect Protein Market
Alternative Food Sources
Paleo Food Market
Alternative Food Sources
Dunaliella Salina Market
Alternative Food Sources
Spirulina Beverages Market
Alternative Food Sources
South American Algae Protein Market
Alternative Food Sources
Middle East and Africa Edible Insects Market
Alternative Food Sources
Plant-Based Squalene Market
Alternative Food Sources
Egg Substitutes Market
Alternative Food Sources
Algal Protein Market
Alternative Food Sources
Bagasse Disposable Cutlery Market
Alternative Food Sources
Feather Meal Market
Alternative Food Sources
Mycoprotein Products Market
Alternative Food Sources
North America Algae Protein Market