
 North America Fruits & Vegetables Market | 2026-2036
North America Fruits & Vegetables Market Size, Share, and Industry Trends Forecast 2026-2036
North America Fruits & Vegetables Market Analytics
Premium organic produce pricing is decoupling from conventional commodity tiers as certification costs and cold-chain investments widen the gap. Dole Food Company leverages its integrated plantation-to-port infrastructure across Central America and the U.S. Southeast to sustain year-round berry availability. Fresh Del Monte Produce anchors its North American position through controlled-atmosphere shipping technology that extends tropical fruit shelf life. Grimmway Farms dominates organic carrot and vegetable juice feedstock supply through its vertically integrated operations in California's Imperial Valley.
North America fruits and vegetables encompass fresh, minimally processed, and value-added plant products sold through retail, foodservice, and industrial channels, requiring maintenance at 0-4°C for quality retention and compliance with microbial load standards. The category serves nutritional intake, ingredient sourcing for processing, and export trade balance objectives. Leafy greens and berries command the strongest margin pools due to perishability-driven supply constraints and year-round greenhouse production investments. The processing industry segment is expanding fastest as ready-to-eat salads and fresh-cut fruit kits penetrate convenience-oriented retail and foodservice accounts. Plastic containers and clamshells retain dominance in packaging despite sustainability pressures, though cardboard box adoption is accelerating in direct-to-restaurant wholesale channels.
The U.S. FDA enforces Produce Safety Rule standards under FSMA that mandate agricultural water testing and worker hygiene protocols, directly raising compliance costs for small growers while advantaging scaled operators. Mexico's SENASICA and the USDA's AMS coordinate cross-border phytosanitary inspections that shape seasonal import windows and tariff-rate quota administration. Canada's CFIA and the Safe Food for Canadians Regulations impose parallel traceability requirements that suppliers must satisfy for access to integrated North American retail networks. Stakeholders must monitor how evolving climate disclosure rules and scope-three emissions accounting reshape sourcing priorities across the value chain.
Market Dynamics
California's Central Valley and Mexico's Sinaloa corridor anchor continental supply chains, concentrating procurement leverage among scaled operators while FSMA compliance costs squeeze marginal growers out of retail channels.
Growth Catalysts
- FSMA Produce Safety Rule:Federal agricultural water testing mandates favor integrated operators with in-house laboratory capacity over fragmented smallholders.
- Controlled-atmosphere shipping:Tropical fruit importers deploy modified atmospheric containers that extend shelf life and reduce retail shrinkage penalties.
- Foodservice pre-cut demand:Restaurant chains and institutional buyers expand procurement of value-added produce kits, concentrating volume with processors possessing HACCP-certified facilities.
Market Restraints
- Input cost volatility:Fertilizer and agricultural labor costs fluctuate with energy markets, compressing margins for non-vertically integrated growers.
- Geographic concentration risk:California drought cycles and Sinaloa irrigation constraints expose continental supply to single-region climate shocks.
- Substitution pressure:Frozen and shelf-stable fruit alternatives capture price-sensitive retail segments during fresh produce inflation spikes.
Strategic Opportunities
- Canadian greenhouse expansion:Ontario and British Columbia protected agriculture investments enable year-round leafy green supply to offset California seasonal gaps.
- USDA Organic certification tailwind:Federal cost-share programs reduce certification barriers for mid-scale operators targeting premium retail placement.
- Direct-to-restaurant platforms:Digital wholesale marketplaces bypass traditional produce distributors, capturing margin from foodservice accounts seeking traceability documentation.
Industry Challenges
- Cold-chain capex intensity:Zero-emission refrigeration retrofits and electric vehicle fleet conversion demand capital deployment that strains regional distributors.
- Traceability system integration:Blockchain and ERP platform adoption creates data interoperability friction between legacy farm management systems and retailer compliance portals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Fruits & Vegetables Market |
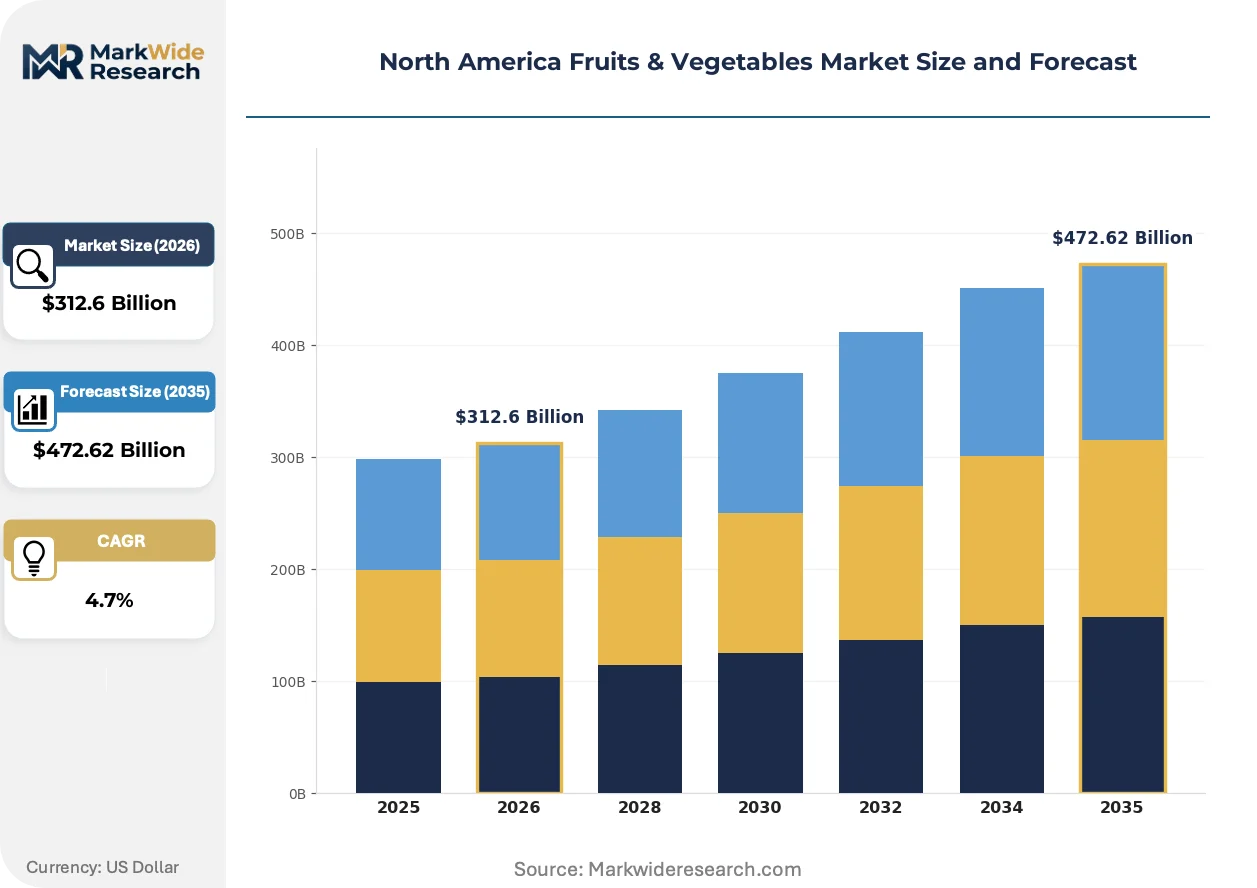
| Market Size in 2026 | $312.6 Billion |
| Market Size in 2035 | $472.62 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Berries, Leafy Greens, Root Vegetables, Citrus Fruits Distribution Channel: Supermarkets, Farmers Markets, Online Retail, Wholesalers Packaging Type: Plastic Containers, Cardboard Boxes, Bulk Bags, Clamshells End User: Food Services, Retail Consumers, Processing Industry, Exporters |
| Companies Covered | Dole Food Company, Inc., Fresh Del Monte Produce, Inc., Chiquita Brands International, Inc., Sysco Corp., Tanimura & Antle Fresh Foods Inc., Taylor Farms, Grimmway Farms, Driscoll’s Inc., Sunkist Growers, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Fruits & Vegetables Market Evolving Landscape
Technology convergence and regulatory disclosure mandates are compressing traditional sourcing timelines while reshaping how buyers verify provenance and sustainability claims across the value chain.
Blockchain-enabled traceability platforms are unifying farm-level data capture with retailer compliance dashboards. Major supermarket chains now require lot-level provenance documentation from berry and leafy green suppliers. This unification is compressing audit cycles from quarterly to real-time while raising IT infrastructure requirements for mid-tier growers.
The FDA's Food Safety Modernization Act generates recurring compliance expenditure for agricultural water monitoring and worker hygiene documentation. Small-scale operators face disproportionate cost burdens relative to revenue, accelerating consolidation toward integrated plantation networks. California and Arizona growers respond by pooling testing resources through cooperative associations.
Corporate sustainability procurement criteria now prioritize scope-three emissions disclosure from fruit and vegetable suppliers. Large foodservice distributors demand carbon accounting documentation that smaller Mexican importers struggle to provide. This behavioral shift concentrates contract awards with operators possessing dedicated sustainability staff and third-party verification partnerships.
North America Fruits & Vegetables Market Segmentation
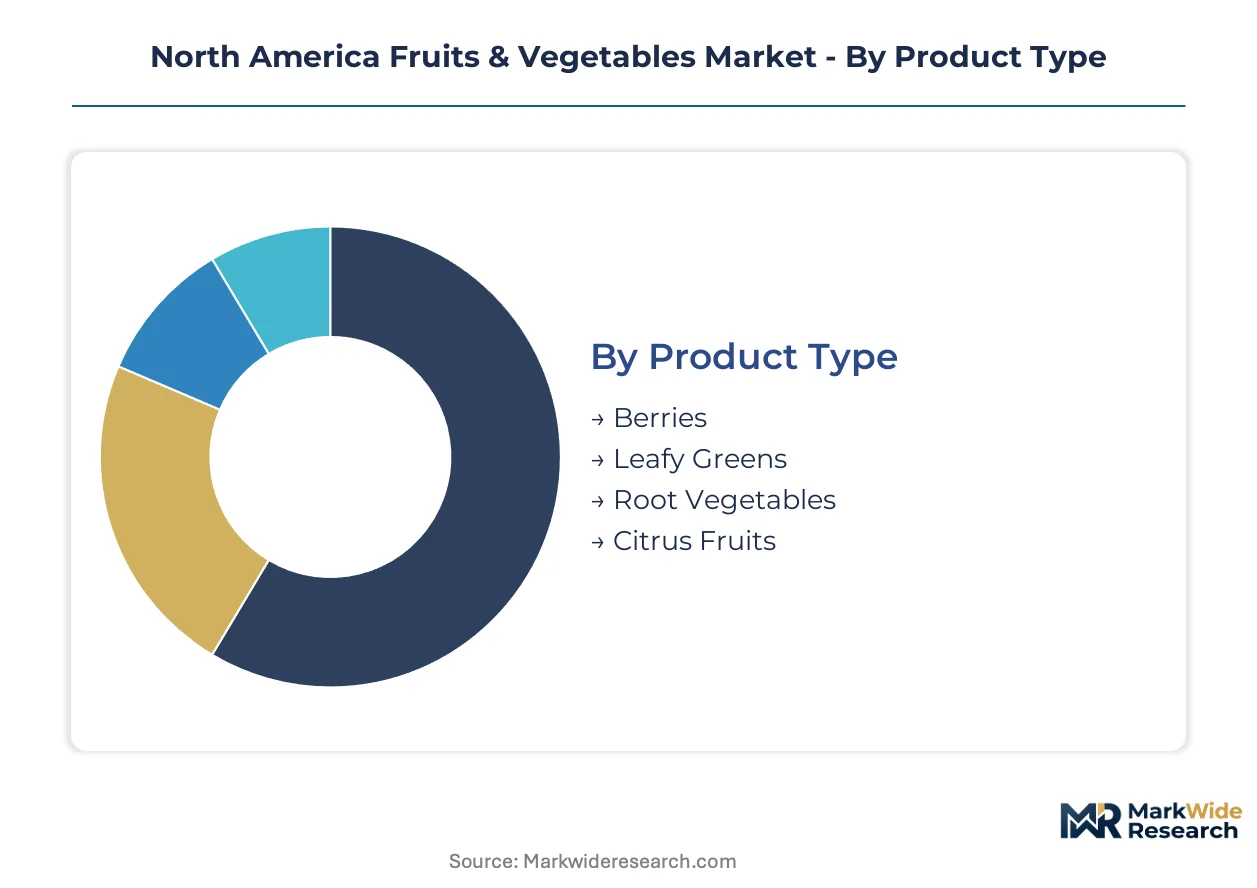
Segmentation in North American produce markets reveals where capital deployment and regulatory compliance costs concentrate. Procurement patterns diverge sharply between fresh retail channels and industrial processing volumes, with cold-chain infrastructure requirements acting as the primary sorting mechanism.
Product Type:
Capital intensity varies dramatically across fresh produce categories, with perishability rates and greenhouse infrastructure requirements determining upfront investment thresholds.
- Berries:Controlled-environment agriculture dominates supply, with hydroponic strawberry operations requiring $15-25 per square foot in infrastructure. California's Salinas Valley and Mexico's Baja California peninsula anchor year-round supply through coordinated harvest windows. Demand concentrates in retail pre-packaged formats where shrinkage penalties reward shelf-life extension investments.
- Leafy Greens:Triple-washed processing lines and HACCP-certified facilities represent the dominant cost structure. Arizona's Yuma desert and California's Central Valley rotate seasonal production to maintain continuous supply to foodservice distributors. FSMA agricultural water testing mandates favor operators with in-house laboratory capacity.
- Root Vegetables:Field-grown crops with lower per-unit handling costs and extended storage compatibility.
- Citrus Fruits:Tree-crop economics with multi-year establishment periods and freeze-risk exposure in Texas and Florida growing regions.
Most installed capacity flows through Berries. Expansion is steepest in Leafy Greens.
Distribution Channel:
Channel selection determines traceability documentation requirements and margin capture potential, with direct-to-buyer platforms disrupting traditional wholesale intermediation.
- Supermarkets:Corporate sustainability scorecards and blockchain-enabled provenance tracking dominate procurement specifications. Chains operating across Canada, the United States, and Mexico demand harmonized food safety documentation that smaller growers struggle to provide. Private-label pre-cut salad programs concentrate volume with processors possessing multi-region supply networks.
- Online Retail:Last-mile cold-chain reliability and subscription fulfillment infrastructure define competitive viability. Toronto, Vancouver, Los Angeles, and New York City metro areas show the densest penetration of direct-to-consumer produce delivery platforms. Customer acquisition costs and packaging waste reduction pressures shape unit economics.
- Farmers Markets:Limited scale with seasonal availability and minimal regulatory oversight relative to retail channels.
- Wholesalers:Traditional intermediary role concentrated in terminal market facilities with declining share in traceability-sensitive categories.
Supermarkets retain the largest throughput volume. Online Retail is gaining share fastest in premium organic segments.
Packaging Type:
Packaging selection reflects tension between shelf-life performance, sustainability credentials, and food safety compliance across retail and foodservice endpoints.
- Plastic Containers:Modified atmosphere engineering extends berry and grape shelf life through permeability-controlled films. California's packaging converters supply clamshell formats optimized for automated filling lines at Central Valley processing facilities. Retailer plastic reduction commitments are compressing growth trajectories despite functional advantages.
- Clamshells:Structural rigidity protects soft fruit through distribution while enabling retail display efficiency. Mexican exporters to the United States increasingly adopt clamshells to reduce damage rates during cross-border transit. Recycled content mandates in California and Canada are reshaping material sourcing.
- Cardboard Boxes:Accelerating adoption in direct-to-restaurant wholesale channels seeking sustainability differentiation.
- Bulk Bags:Dominant in foodservice and processing inputs where downstream handling occurs in controlled environments.
Plastic Containers and Clamshells together handle the majority of retail-facing volume. Cardboard Boxes are climbing the fastest as sustainability procurement criteria harden.
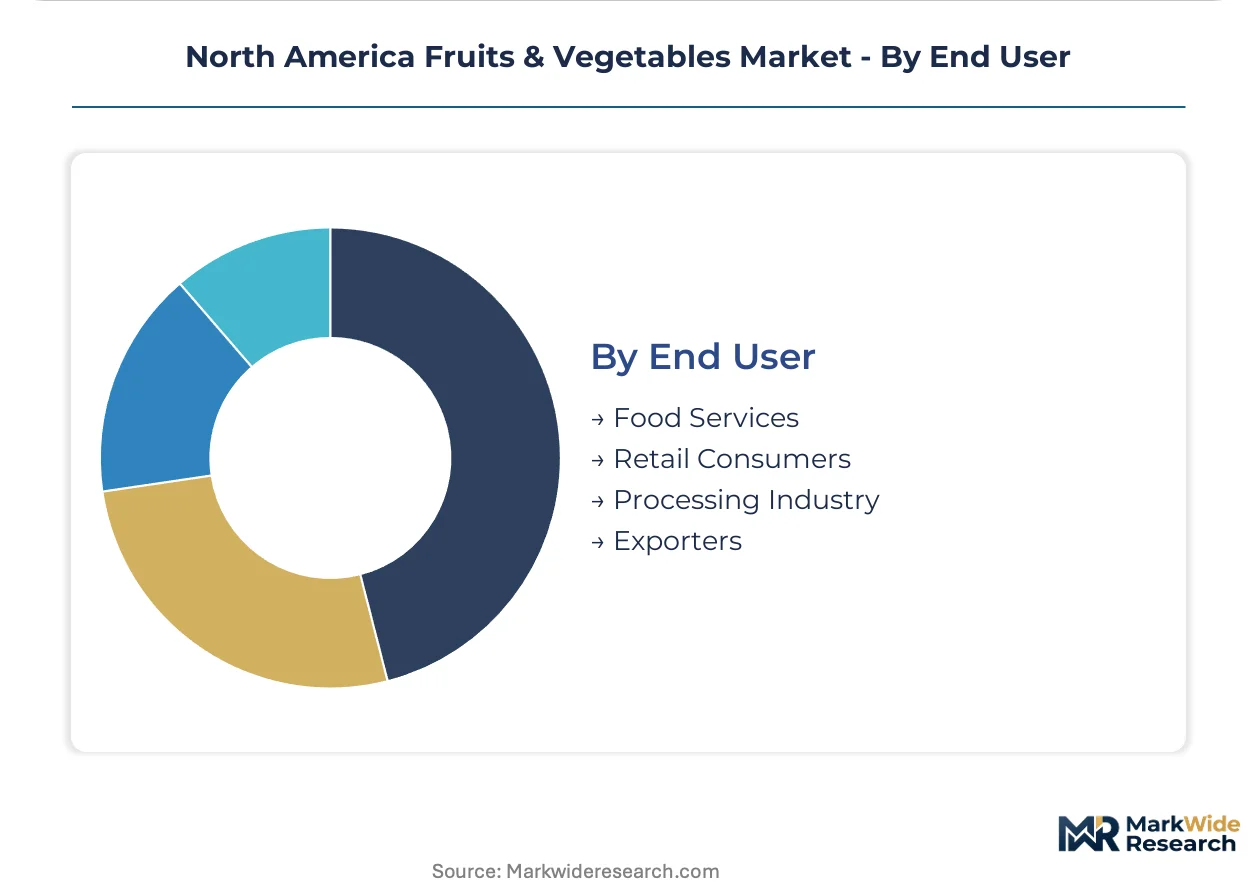
End User:
End-user segmentation separates traceability-intensive retail and export channels from volume-driven processing applications with differing specification tolerances.
- Food Services:Pre-cut and value-added specifications dominate procurement, with HACCP certification mandatory for supply to institutional accounts. Restaurant chains operating across multiple states and provinces demand consistent sizing and microbial load documentation. Labor cost pressures in commercial kitchens are accelerating ready-to-use produce adoption.
- Processing Industry:Juice, smoothie, and frozen concentrate operations purchase on brix and color specifications with tolerance for cosmetic defects rejected by fresh retail. California's Central Valley hosts the densest concentration of vegetable juice feedstock processors. Contract pricing structures reduce exposure to spot market volatility.
- Retail Consumers:Direct purchase behavior shaped by convenience formats and organic certification premiums.
- Exporters:Phytosanitary compliance and cold-chain integrity requirements for Asian and European destination markets.
Food Services commands the largest procurement volume. Processing Industry shows the steepest expansion trajectory as beverage and convenience food manufacturers secure captive supply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Migrant agricultural labor pools anchor production capacity across the continent's growing regions, with seasonal worker flows from Mexico's interior sustaining harvest operations in California, Arizona, and the Pacific Northwest.
United States
Foodservice pre-cut demand and retail organic premiums drive procurement volume. The FDA's Produce Safety Rule mandates agricultural water testing and worker hygiene protocols that favor scaled operators with in-house laboratory capacity. California's Central Valley hosts the densest concentration of berry processors and vegetable juice feedstock operations, with Salinas Valley leafy green production rotating seasonally with Arizona's Yuma desert.
Canada
Greenhouse-protected agriculture expansion in Ontario and British Columbia enables year-round leafy green supply to offset California seasonal gaps. The CFIA and Safe Food for Canadians Regulations impose traceability requirements that suppliers must satisfy for access to integrated North American retail networks. Toronto and Vancouver metro areas show the densest penetration of direct-to-consumer produce delivery platforms.
Mexico
Cross-border export volume to U.S. retail and foodservice channels concentrates procurement leverage among Sinaloa corridor operators. SENASICA coordinates with USDA's AMS on phytosanitary inspections that shape seasonal import windows and tariff-rate quota administration. Baja California peninsula berry operations coordinate harvest windows with California's Salinas Valley to maintain continuous supply.
Florida
Citrus and tropical fruit production serves processing juice concentrate and fresh retail channels with freeze-risk exposure during winter months. State agricultural water management districts regulate irrigation withdrawals that constrain expansion in phosphate-rich growing regions. The Indian River district maintains specialized grapefruit and orange cultivar concentration for domestic juice blending operations.
North America Fruits & Vegetables Market Competitive Landscape
Top-tier vendors anchor integrated plantation-to-port infrastructure, while mid-scale cooperatives and regional distributors compete on traceability documentation and direct-to-restaurant platform access. The market structures around three distinct tiers: multinational integrated operators with captive supply networks, specialized organic and greenhouse producers with certification premiums, and regional distributors with terminal market presence. Consolidation pressures favor scaled operators capable of absorbing FSMA compliance costs and cold-chain capital intensity. Dominant competitive moves include backward integration into controlled-environment agriculture and strategic partnerships with foodservice distributors seeking HACCP-certified supply.
Within the integrated multinational tier, Dole Food Company and Fresh Del Monte Produce exemplify operators with plantation-to-port infrastructure spanning Central America and U.S. Southeast distribution networks. Grimmway Farms occupies a specialized position in organic root vegetable and processing feedstock supply through vertically integrated Imperial Valley operations. These three entities represent the archetype spectrum from tropical fruit import logistics to domestic organic field production.
| Leading Market Players |
|---|
| Dole Food Company, Inc. |
| Fresh Del Monte Produce, Inc. |
| Chiquita Brands International, Inc. |
| Sysco Corp. |
| Tanimura & Antle Fresh Foods Inc. |
| Taylor Farms |
| Grimmway Farms |
| Driscoll's Inc. |
| Sunkist Growers, Inc. |
| Others |
Value Network & Pricing Analysis
Controlled-atmosphere shipping adoption simultaneously compresses per-unit logistics costs and consolidates procurement leverage among operators with capital to deploy modified atmospheric containers across the California-Mexico corridor. This technology shift widens the margin capture gap between integrated importers and fragmented smallholders unable to finance cold-chain upgrades.
Pricing Analysis
Fresh produce pricing separates value-added processing from raw commodity tiers. Three-tier pricing structure across organic premium, conventional retail, and foodservice bulk levels reflects certification costs and cold-chain investment differentials. Pricing pressure stems from fertilizer and agricultural labor cost volatility tied to energy markets. Foodservice buyers exhibit highest price sensitivity due to thin restaurant margins, while organic retail consumers show lowest sensitivity.
Supply Chain Analysis
Single-source vulnerability sits with California's Central Valley and Mexico's Sinaloa corridor anchoring continental berry and leafy green supply. The production base draws from phosphate fertilizers, agricultural water rights, and seasonal migrant labor pools. Tariff-rate quota administration and cross-border phytosanitary inspections create structural risk at the US-Mexico frontier. Distribution runs through integrated plantation-to-port networks serving retail and foodservice channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America fruits and vegetables market functions as a regulatory compounder where FDA Produce Safety Rule compliance costs accelerate consolidation toward scaled operators with in-house laboratory capacity.
For Market Incumbents: To counter margin compression from input cost volatility, Dole Food Company and Fresh Del Monte Produce should deepen backward integration into controlled-environment agriculture in Mexico's Baja California peninsula. Certification investment in USDA Organic and blockchain-enabled traceability platforms secures premium retail placement against emerging greenhouse competitors. For New Entrants and Emerging Players: Enter via direct-to-restaurant digital platforms bypassing traditional produce distributors in Toronto and Vancouver metro areas where traceability documentation commands buyer loyalty. White-space targets include HACCP-certified pre-cut salad supply to mid-sized restaurant chains and greenhouse-grown leafy greens for Canadian retail offsetting California seasonal gaps. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale cooperatives pooling FSMA compliance costs through California and Arizona testing associations. Long-term viability favors acquisition targets with captive water rights in Imperial Valley or Sinaloa corridor irrigation districts. Watch SENASICA-USDA AMS coordination friction as inflection indicator for cross-border supply disruption risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Controlled-Environment Agriculture | Year-round berry supply from Baja California peninsula operations reduces seasonal import dependence. |
| Blockchain Traceability Platform Deployment | Lot-level provenance documentation satisfies Walmart and Kroger compliance dashboards for leafy greens. |
| HACCP-Certified Pre-Cut Processing Expansion | Ready-to-eat salad kits capture foodservice volume from labor-cost-pressured commercial kitchens. |
| Canadian Greenhouse Protected Agriculture Buildout | Ontario and British Columbia facilities offset California drought risk for North American retail networks. |
| Direct-to-Restaurant Digital Marketplace Launch | Bypassing Sysco and US Foods captures margin from traceability-seeking institutional buyers. |
Research Methodology
Coverage spans the United States, Canada, and Mexico, with primary inputs from each national market combining executive interviews with berry and leafy green processors, foodservice procurement directors, and agricultural cooperative managers. Secondary validation drew from FDA Produce Safety Rule guidance documents, USDA AMS market reports, SENASICA phytosanitary bulletins, and CFIA Safe Food for Canadians Regulations. Bottom-up volume estimates triangulated against top-down trade flow analysis.
Rate-of-change decomposition across the analysis window segmented growth by product type, distribution channel, packaging format, and end-user application. CAGRs derived from modeled supply constraints including California water allocation cycles, Sinaloa irrigation infrastructure capacity, and greenhouse expansion timelines in Ontario and British Columbia. Forecast inputs incorporated labor cost trajectories and cold-chain capital deployment patterns.
Inputs from FDA, USDA AMS, and SENASICA regulatory filings were available through the study window; gaps in real-time agricultural water testing cost data from smallholder cooperatives introduce uncertainty bands around compliance-driven consolidation speed. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fruits and Vegetables
Fruit and Vegetable Pieces and Powders Market
Fruits and Vegetables
Butterfly Pea Flowers Market
Fruits and Vegetables
Peach Extract Market
Fruits and Vegetables
Canned Fruits and Vegetables Market
Fruits and Vegetables
Ackee Market
Fruits and Vegetables
Olive Market
Fruits and Vegetables
Dried Berries Market
Fruits and Vegetables
Rosehip Market
Fruits and Vegetables
Global Maqui Berries Market
Fruits and Vegetables
Europe Olive Market
Fruits and Vegetables
Brown Shimeji Mushroom Market
Fruits and Vegetables
Avocado Puree Market
Fruits and Vegetables
South America Lime Market
Fruits and Vegetables
Middle East and Africa Freeze-Dried Fruits and Vegetables Market
Fruits and Vegetables
Spain Tropical Fruits Market
Fruits and Vegetables
Yellow Oyster Mushroom Market